
 Cedarwood Oil Market | 2026-2036
Cedarwood Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Cedarwood Oil Market Outlook
REACH is rebalancing the cost-of-entry calculus for cedarwood oil suppliers seeking European market access, as registration dossiers for botanical substances now require expanded toxicological data. Texarome Inc. leverages its Texas-based steam distillation infrastructure to serve domestic fragrance houses with certified organic grades. Symrise AG anchors its competitive position through backward integration into Atlas cedar sourcing in Morocco. Givaudan SA differentiates via biotechnology-derived cedarwood alternatives that reduce wild-harvest dependence.
Cedarwood oil is a volatile essential oil obtained from the wood of Cedrus and Juniperus species, typically containing cedrol, alpha-cedrene, and thujopsene as principal sesquiterpene constituents, with steam distillation yielding pale yellow to amber liquids at specific gravities between 0.940 and 0.960. The oil functions primarily as a fixative and base note in fine fragrance compounding, as well as an active ingredient in dermatological preparations for its astringent and antiseptic properties. Steam distillation dominates extraction output volumes due to capital efficiency and scalability, though microwave-assisted extraction is gaining traction among boutique producers targeting heat-sensitive terpene preservation. Cosmetics and aromatherapy end uses command premium pricing, while pharmaceutical-grade specifications remain a narrow but high-margin niche constrained by pharmacopeial compliance costs.
The EPA regulates cedarwood oil as a biochemical pesticide active ingredient under FIFRA, requiring minimum risk exemption documentation for insect repellent applications. FDA oversight of cosmetic ingredient safety through the Voluntary Cosmetic Registration Program creates additional compliance layers for personal care suppliers. India's BIS essential oil standards and China's GB/T aromatic oil specifications further fragment quality benchmarks for export-oriented distillers. Stakeholders must monitor evolving biocidal product regulations in the European Union, where cedarwood oil's classification under the Biocidal Products Regulation will determine access for household cleaning applications.
Market Dynamics
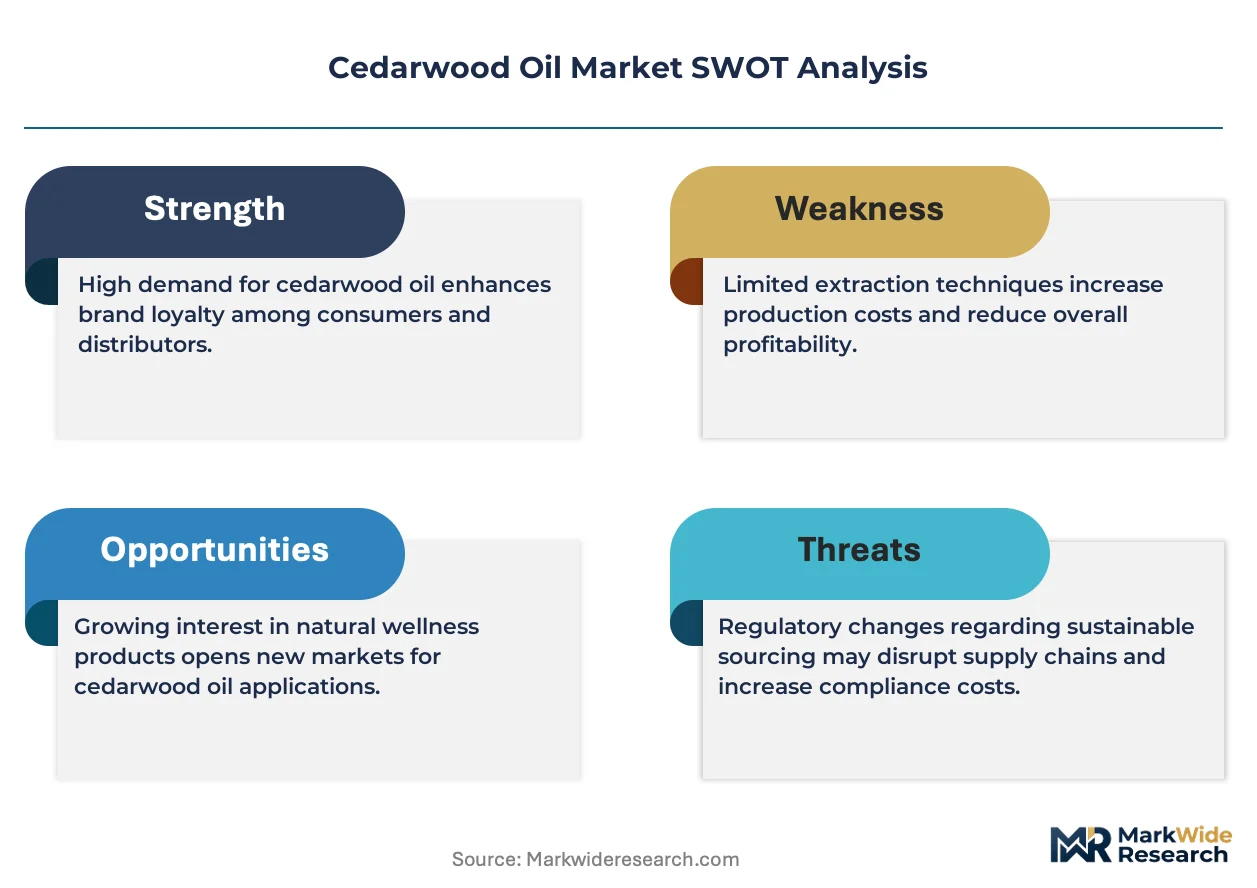
REACH registration requirements for botanical extracts into the European Union are rebalancing supplier economics, as expanded toxicological dossiers raise compliance costs and compress margins for smaller distillers serving fragrance houses.
Growth Catalysts
- Personal Care Formulation Demand:Natural fragrance portfolios in France and Germany are expanding cedarwood oil procurement as clean-label positioning displaces synthetic alternatives in premium cosmetics.
- Sustainable Forestry Certification:Harvesting integration with certification programs in the United States Pacific Northwest is unlocking preferential supply contracts with environmentally credentialed buyers.
- Biocidal Product Regulation:Cedarwood oil's pending classification under the EU Biocidal Products Regulation is creating regulatory clarity for household cleaning applications previously constrained by uncertain compliance pathways.
Market Restraints
- Wild-Harvest Dependence:Atlas cedar sourcing concentration in Morocco creates supply vulnerability from climate variability and land-use competition with agriculture.
- Pharmacopeial Compliance Costs:Pharmaceutical-grade specifications require investment in GMP infrastructure that narrows participation to capitalized producers.
- Synthetic Substitution:Biotechnology-derived cedarwood alternatives from major fragrance houses reduce price premiums for botanical extracts in mass-market applications.
Strategic Opportunities
- Microwave-Assisted Extraction:Boutique producers adopting this technology capture heat-sensitive terpene segments underserved by conventional steam distillation.
- EPA Minimum Risk Exemption:Biochemical pesticide registration for insect repellent applications opens household product channels with reduced regulatory burden versus conventional actives.
- Aromatherapy Channel Expansion:Direct-to-consumer wellness platforms in North America and Western Europe are bypassing traditional fragrance compounder intermediaries.
Industry Challenges
- Documentation Standard Fragmentation:India's BIS essential oil standards, China's GB/T specifications, and FDA Voluntary Cosmetic Registration Program create multi-jurisdictional compliance complexity for export-oriented distillers.
- Steam Distillation Capex Requirements:Capital-efficient scaling demands continuous investment in boiler infrastructure and energy recovery systems to maintain cost parity.
- REACH Dossier Expertise Gap:Toxicological data compilation for botanical substance registration requires specialized regulatory affairs capacity scarce among traditional essential oil suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cedarwood Oil Market |
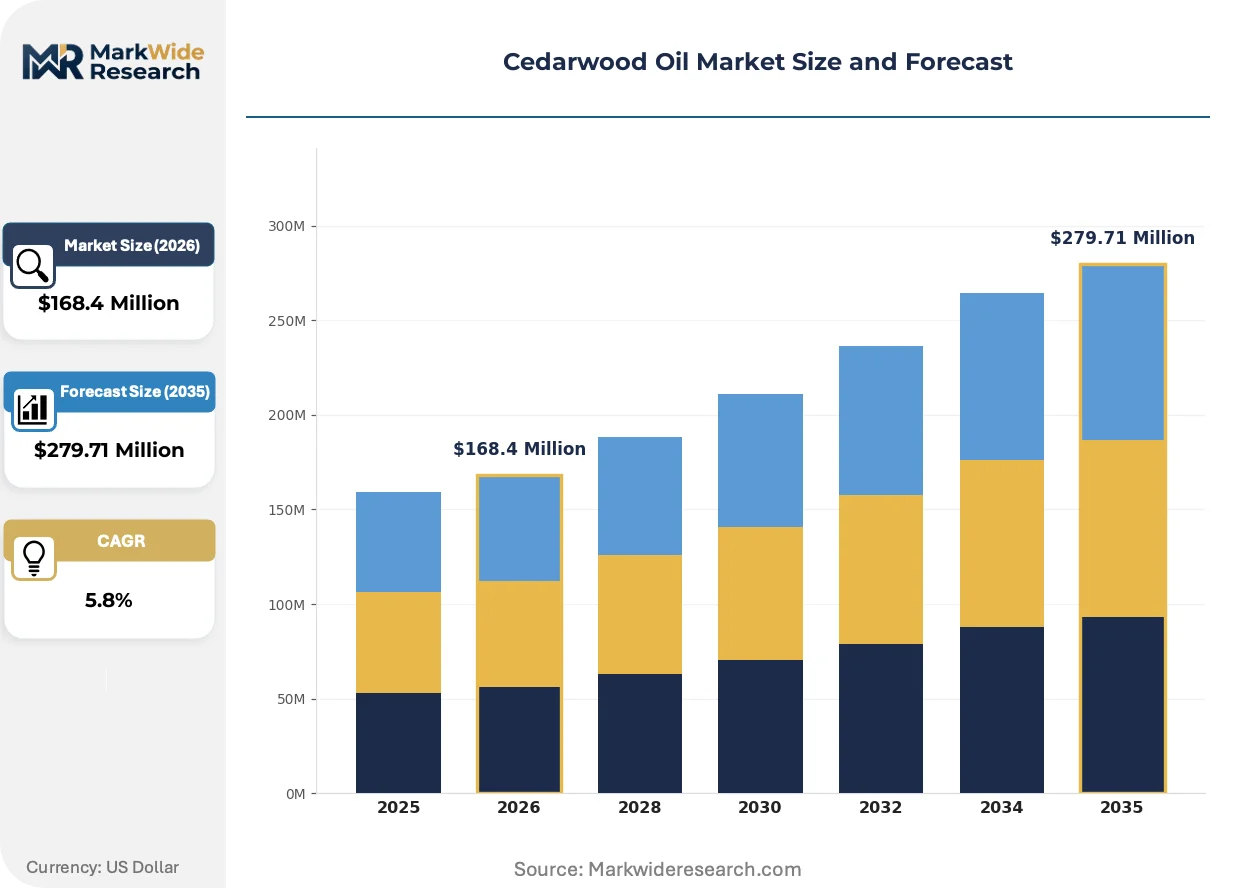
| Market Size in 2026 | $168.4 Million |
| Market Size in 2035 | $279.71 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Extraction Method: Steam Distillation, Cold Pressing, Solvent Extraction, Microwave-Assisted Extraction End Use: Aromatherapy, Cosmetics, Pharmaceuticals, Cleaning Products Packaging Type: Glass Bottles, Plastic Containers, Metal Cans, Bulk Packaging Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Texarome Inc., Foreverest Resources Ltd., Finetech Industry Limited, ORCHID Chemical Supplies Ltd, Grayden Cedar Works, International Flavors & Fragrances Inc., The Essential Oil Company, Symrise AG, Givaudan SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cedarwood Oil Market Strategic Shifts
Extraction technology diversification and regulatory recalibration are compressing traditional supply hierarchies while opening new value-capture points for agile producers.
Microwave-assisted extraction technology is decentralizing terpene recovery operations by enabling smaller-batch processing with reduced thermal degradation. Boutique aromatherapy brands and regional fragrance houses are adopting these systems to differentiate on freshness markers. The capital threshold for competitive extraction is falling, fragmenting production geography beyond traditional steam distillation clusters.
EU REACH dossier requirements for botanical substances are tightening toxicological documentation standards for essential oil imports. Registration costs are concentrating supply relationships around larger distillers with dedicated regulatory affairs capacity. Fragrance compounders in Germany and France are consolidating supplier bases to reduce compliance audit burden.
Certification-driven procurement is reshaping buyer-supplier contracting in personal care. Clean-label positioning now demands chain-of-custody documentation from forest to formulation. Sustainable forestry programs in the United States Pacific Northwest are capturing premium pricing from cosmetics manufacturers seeking deforestation-free supply assurances.
Cedarwood Oil Market Segmentation
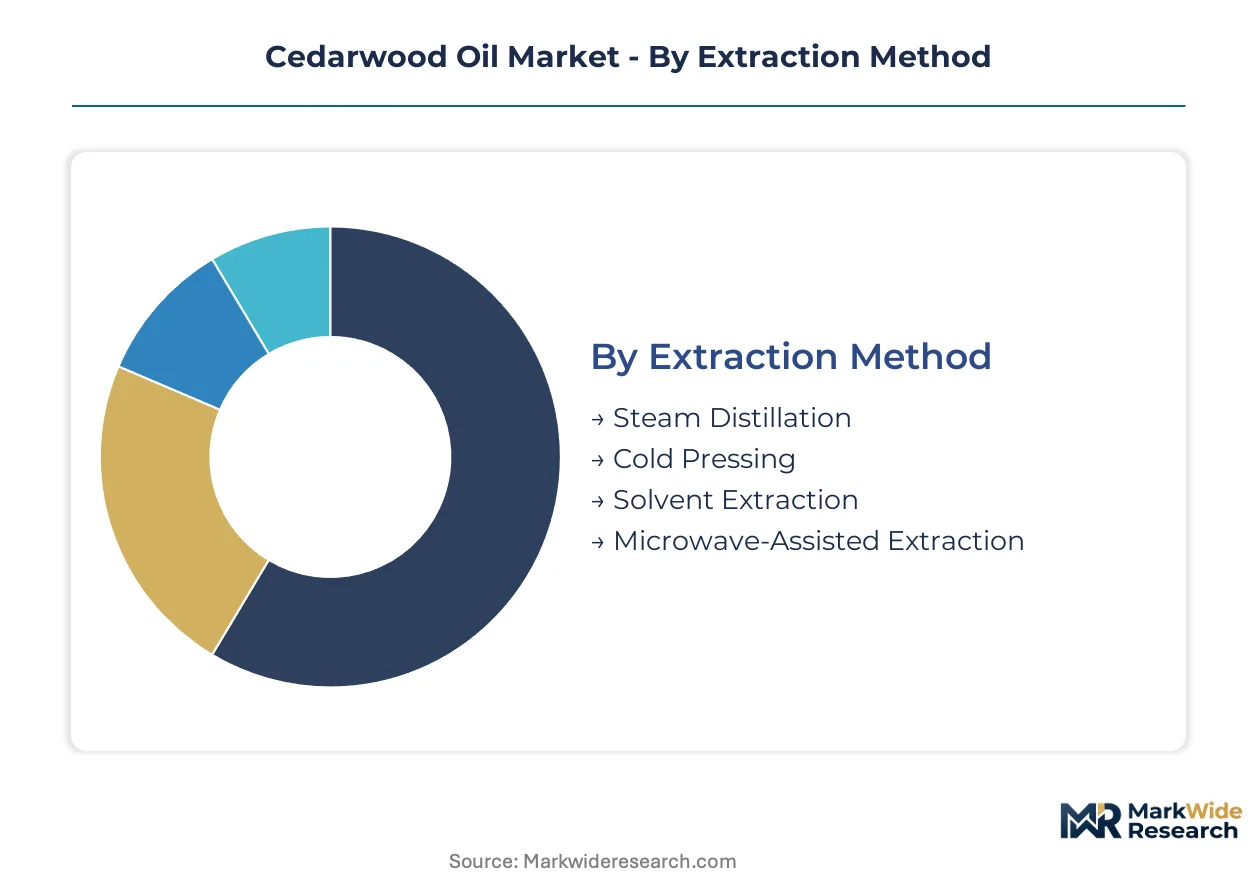
Cedarwood oil segmentation reflects divergent processing economics and end-use specifications that determine margin capture. Distillers must align extraction infrastructure with target applications, as pharmaceutical-grade compliance demands fundamentally different capital deployment than commodity fragrance supply.
Extraction Method:
Customization intensity varies sharply across this category, from standardized industrial steam distillation to boutique microwave systems preserving volatile terpene profiles.
- Steam Distillation:Dominates commercial output through capital-efficient continuous processing of cedarwood chips and sawdust. Fragrance compounders in France and Germany anchor procurement contracts around this method's cost predictability, though energy recovery investments now separate competitive distillers from margin-compressed operators.
- Microwave-Assisted Extraction:Captures premium positioning through reduced thermal degradation of cedrol and alpha-cedrene. Regional aromatherapy brands in the United States Pacific Northwest deploy these systems to supply direct-to-consumer wellness platforms with freshness-differentiated inventory.
- Cold Pressing:Preserves top-note volatility for high-end perfume applications requiring unaltered sesquiterpene complexity.
- Solvent Extraction:Yields absolute extracts for fixative-intensive fine fragrance compounding where alcohol-soluble concentration matters.
Volume leadership: Steam Distillation. Steepest expansion trajectory: Microwave-Assisted Extraction.
End Use:
Application-driven specification tiers separate pharmacopeial-grade investments from commodity fragrance supply, with regulatory compliance costs determining viable participation.
- Cosmetics:Clean-label positioning in French and German personal care formulators is concentrating procurement around certified organic grades with chain-of-custody documentation. REACH registration dossiers for botanical extracts now require expanded toxicological data, consolidating supplier relationships around capitalized distillers with dedicated regulatory affairs capacity.
- Pharmaceuticals:GMP infrastructure requirements and FDA Voluntary Cosmetic Registration Program compliance create narrow, high-margin participation limited to producers with validated quality systems. Pharmacopeial specifications for cedrol content and heavy metal limits constrain sourcing to established Moroccan Atlas cedar processors.
- Aromatherapy:Direct-to-consumer wellness platforms are bypassing traditional fragrance compounder intermediaries, fragmenting demand toward smaller-batch producers.
- Cleaning Products:EPA minimum risk exemption documentation for biochemical pesticide applications opens household channels with reduced regulatory burden versus conventional actives.
Revenue concentration: Cosmetics. Gaining share fastest: Aromatherapy.
Packaging Type:
Volume scale and shelf-life requirements drive format selection, from protective glass for photo-sensitive terpenes to cost-minimized bulk for industrial compounders.
- Bulk Packaging:Serves fragrance houses and cosmetic manufacturers with continuous formulation demand, minimizing per-unit handling costs through drum and tote configurations.
- Glass Bottles:Preserves terpene integrity for premium aromatherapy retail through UV-protective amber and cobalt formulations.
- Plastic Containers:Balances cost and chemical resistance for mid-market cosmetic ingredient distribution.
- Metal Cans:Provides impact resistance for industrial cleaning product manufacturers with high-throughput filling operations.
Dominant by throughput: Bulk Packaging. Premium expansion: Glass Bottles.
Distribution Channel:
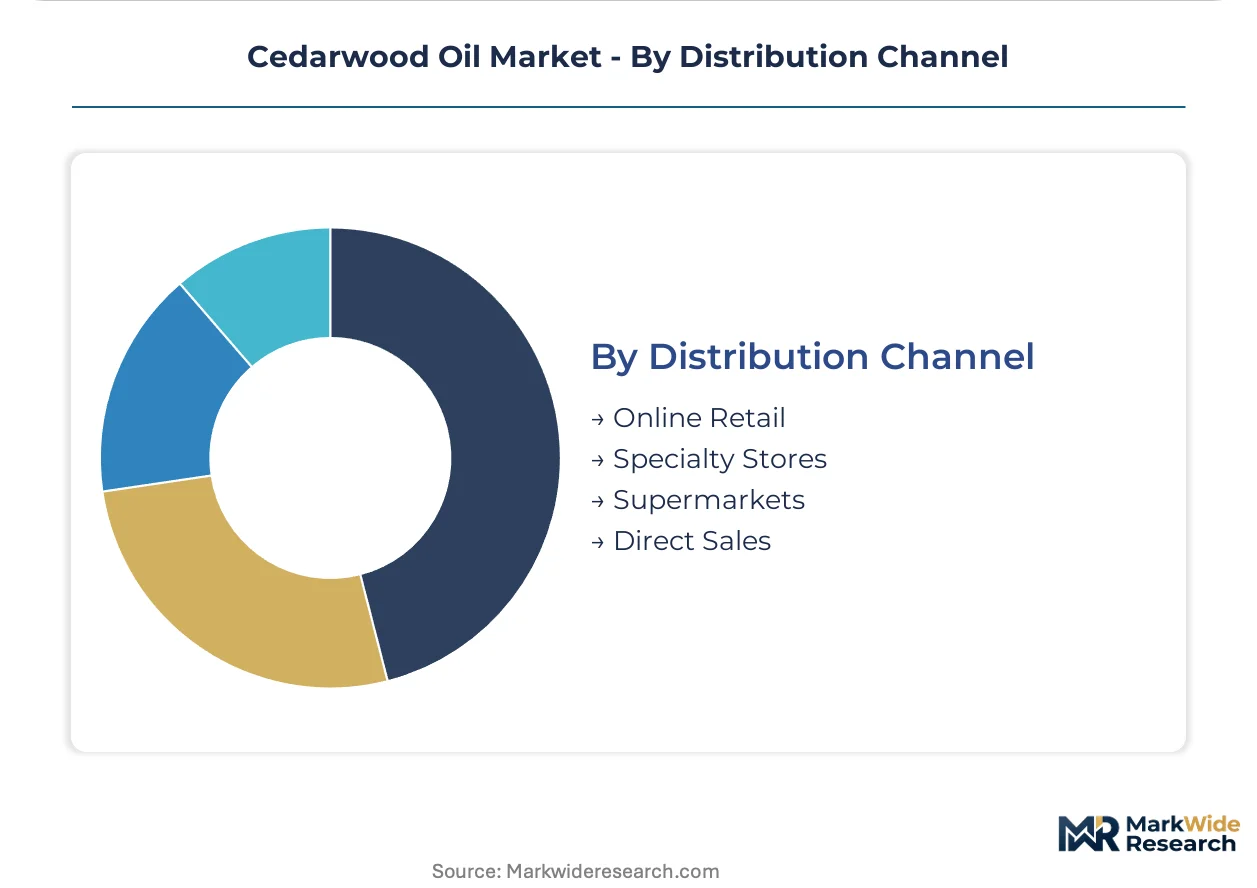
Customer proximity and order fragmentation determine channel economics, with digital platforms disrupting traditional fragrance house intermediation.
- Direct Sales:Long-term supply contracts with Givaudan, Symrise, and regional European compounders provide volume visibility for distillation capacity planning. Texarome leverages Texas-based infrastructure to serve domestic fragrance houses through dedicated account relationships.
- Online Retail:Wellness platforms and boutique aromatherapy brands are capturing end-user demand previously routed through specialty intermediaries, enabling margin retention for small-batch producers.
- Specialty Stores:Curated selection for professional aromatherapists and independent cosmetic formulators seeking certified organic grades.
- Supermarkets:Mass-market reach for standardized household cleaning applications with EPA-registered biocidal positioning.
Highest volume flow: Direct Sales. Channel disruption: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Morocco's free trade zones and preferential tariff arrangements with the European Union have concentrated Atlas cedar processing capacity around Fès-Meknès. This tax-advantaged positioning anchors supply chains serving fragrance compounders in France and Germany.
Morocco
Atlas cedar harvesting in the Middle Atlas mountains supplies distillers serving Givaudan and Symrise with raw material for fixative production. ECHA REACH registration requirements for botanical extracts now mandate expanded toxicological dossiers, raising compliance costs for smaller Moroccan processors. Fès-Meknès hosts the primary concentration of steam distillation infrastructure integrated with cooperative harvesting networks.
United States
Juniperus virginiana harvesting in Texas, Arkansas, and Virginia feeds domestic fragrance houses and EPA-registered biochemical pesticide formulators. The EPA's minimum risk exemption under FIFRA enables insect repellent applications with reduced regulatory burden versus conventional actives. Texarome leverages Texas-based infrastructure to serve compounders through certified organic grades with chain-of-custody documentation.
France
Personal care formulators in Grasse and Paris expand procurement of natural fragrance inputs as clean-label positioning displaces synthetic alternatives. ECHA administers REACH registration for botanical substance imports, consolidating supplier relationships around capitalized distillers with dedicated regulatory affairs capacity. The Grasse fragrance cluster anchors formulation demand for cedarwood oil as a base note and fixative.
Germany
Fragrance compounders in Holzminden and Hamburg drive specification standards for cedarwood oil grades used in premium cosmetics. ECHA's expanded toxicological data requirements for REACH botanical dossiers compress margins for smaller suppliers lacking regulatory expertise. The Holzminden fragrance hub concentrates procurement decision-making for European personal care manufacturers.
India
Cedrus deodara harvesting in Himachal Pradesh and Uttarakhand supplies domestic aromatherapy markets and export-oriented distillers. BIS essential oil standards create quality benchmarks for export shipments to Europe and North America. The Kangra Valley cluster hosts traditional steam distillation operations serving both pharmaceutical-grade and cosmetic ingredient specifications.
Cedarwood Oil Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across extraction and formulation tiers. The supplier base fragments between capital-intensive steam distillation operators and boutique microwave-assisted extraction adopters. Three archetypes dominate: integrated fragrance houses with captive sourcing, independent distillers with certification credentials, and biotechnology platforms offering synthetic alternatives. Consolidation pressure is accelerating through REACH-driven supplier base rationalization and backward integration by major compounders.
Among North American independent distillers, Texarome Inc. exemplifies the certified organic specialist archetype. Givaudan SA and Symrise AG represent the integrated fragrance house tier with upstream control over sourcing. Foreverest Resources Ltd. occupies a position within the Asia-Pacific supply tier serving export markets.
| Leading Market Players |
|---|
| Texarome Inc. |
| Foreverest Resources Ltd. |
| Finetech Industry Limited |
| ORCHID Chemical Supplies Ltd |
| Grayden Cedar Works |
| International Flavors & Fragrances Inc. |
| The Essential Oil Company |
| Symrise AG |
| Givaudan SA |
| Others |
Value Chain & Pricing Dynamics
Steam distillation energy costs cascade through cedarwood oil pricing tiers, with Moroccan Atlas cedar processors passing elevated boiler fuel expenses to European fragrance compounders while Pacific Northwest operators capture margin through hydroelectric-powered extraction.
Pricing Analysis
Short lead-time premiums separate spot buyers from contract offtake arrangements in cedarwood oil procurement. Three-tier pricing structure across certified organic, conventionally distilled, and spot-market grades reflects REACH compliance investment and chain-of-custody documentation depth. Pricing pressure stems from biotechnology-derived alternatives reducing botanical extract premiums in mass-market fragrance applications. Commodity fragrance houses exhibit highest price sensitivity, while pharmaceutical-grade buyers accept substantial premiums for GMP-validated supply security.
Supply Chain Analysis
Refurbishment flows for distillation equipment and solvent recovery systems extend asset life among Moroccan and Indian processors facing capital constraints. Raw material sourcing concentrates in Morocco's Middle Atlas mountains, the United States Pacific Northwest, and India's Himalayan foothills. Supply chains rest on cedar species harvesting permits, steam boiler infrastructure, and EU REACH registration dossiers. Single-source vulnerability from Atlas cedar climate exposure threatens fixative-grade supply continuity. Distribution runs through direct sales contracts with Givaudan and Symrise, supplemented by online wellness platform channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cedarwood oil supply constraints from Moroccan harvesting permit limitations and REACH dossier expertise scarcity prop pricing power toward capitalized distillers with regulatory affairs capacity.
For Market Incumbents: Deploy backward integration into certified forestry operations to secure deforestation-free supply assurances demanded by French and German cosmetics formulators. Expand microwave-assisted extraction capacity in the United States Pacific Northwest to capture heat-sensitive terpene premiums. Biotechnology-derived alternatives from Givaudan and Symrise threaten botanical extract positioning in mass-market applications. For New Entrants and Emerging Players: The premium-to-economy pricing gap in aromatherapy-grade cedarwood oil offers entry opportunity through direct-to-consumer wellness platforms bypassing traditional fragrance house intermediaries. Target EPA minimum risk exemption documentation for insect repellent applications with reduced regulatory burden versus conventional pesticide actives. White-space exists in boutique microwave extraction serving regional organic cosmetic formulators. For Investors and Strategic Acquirers: ECHA REACH registration deadline acceleration for botanical substances is the leading indicator that supplier consolidation will concentrate relationships around capitalized distillers with dedicated regulatory affairs capacity. Acquisition targets should demonstrate validated GMP infrastructure and established Moroccan or Pacific Northwest forestry relationships. Long-term viability hinges on sustainable harvesting certification and biocidal product regulatory clarity.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Dossier Investment | ECHA registration expertise consolidates supplier relationships with French and German fragrance compounders. |
| Microwave Extraction Scale-Up | Heat-sensitive terpene preservation captures premium positioning in aromatherapy and boutique cosmetic channels. |
| Forestry Certification Program | Chain-of-custody documentation unlocks preferential supply contracts with clean-label personal care manufacturers. |
| EPA Biochemical Registration | Minimum risk exemption opens household insect repellent applications with reduced regulatory burden. |
| Direct-to-Consumer Channel Launch | Wellness platform bypass of fragrance compounder intermediaries retains margin for small-batch producers. |
Study Parameters
Multi-period observation of cedarwood oil import volumes, extraction capacity utilization, and REACH registration filings anchored the trend analysis, supplemented by interviews with Moroccan distillation operators, Pacific Northwest forestry managers, French fragrance compounder procurement leads, and German cosmetics formulator R&D directors. Secondary validation drew from ECHA substance registration databases, USDA organic certification records, EPA biochemical pesticide filings, and customs trade data. Bottom-up capacity modeling and top-down demand estimation from personal care formulation trends were triangulated.
Input-output matrices mapped extraction method economics against end-use specification tiers across the projection horizon. Segmentation dimensions modeled include extraction technology, application category, certification grade, and regional supply hub. CAGRs were derived from capacity expansion pipelines and substitution elasticity estimates for biotechnology-derived alternatives. Forecast inputs incorporated sustainable forestry certification adoption curves and biocidal product regulatory pathway clarity.
Inputs from ECHA registration databases and EPA exemption filings were available through the study window; gaps in Moroccan cooperative-level production data introduce uncertainty bands around Atlas cedar supply forecasts. Practitioners should monitor REACH dossier submission timelines and Moroccan land-use permit allocations for early signals of supply constraint intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Europe Aroma Chemicals Market
Flavor and Fragrance Chemicals
United States Aroma Chemicals Market
Flavor and Fragrance Chemicals
North America Aroma Chemicals Market
Flavor and Fragrance Chemicals
Linalool Market
Flavor and Fragrance Chemicals
Ferulic Acid Market
Flavor and Fragrance Chemicals
Gamma Decalactone Market
Flavor and Fragrance Chemicals
Smoke Ingredients Market
Flavor and Fragrance Chemicals
Aromatic Compounds Market
Flavor and Fragrance Chemicals
Sage Essential Oil Market
Flavor and Fragrance Chemicals
Middle East and Africa Deodorants Market
Flavor and Fragrance Chemicals
Pocket Perfume Market
Flavor and Fragrance Chemicals
Tannic Acid Market
Flavor and Fragrance Chemicals
Gel Air Fresheners Market
Flavor and Fragrance Chemicals
Cinnamic Aldehyde Market
Flavor and Fragrance Chemicals
Asia Pacific Essential Oils Market
Flavor and Fragrance Chemicals
Natural Fragrance Ingredients Market