
 Global Hearable Devices Market | 2026-2036
Global Hearable Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hearable Devices Market Analysis
The divergence between premium and commodity tiers is hardening in concrete terms around codec quality, sensor fusion depth, and clinical-grade certification. Apple Inc. leverages its proprietary silicon and ecosystem lock-in to sustain margin capture at the top of the market. Samsung Electronics Co. Ltd. anchors its position through aggressive vertical integration across display, semiconductor, and audio subsystem supply chains. Bose Corporation differentiates via acoustic engineering heritage and active noise cancellation algorithms that command professional audio loyalty.
Hearable devices are wearable audio systems incorporating microelectromechanical microphones, Bluetooth Low Energy chipsets, and inertial measurement units to deliver sound reproduction, biometric monitoring, and spatial computing interfaces for consumer and clinical applications. The product type dimension shows earbuds pulling volume while hearing aids command the steepest pricing premiums due to regulated dispensing channels and personalized fitting requirements. True wireless technology leads unit shipments, yet active noise cancelling modules concentrate value capture in over-ear headphones aimed at enterprise and travel segments.
The FDA software-as-medical-device framework and EU AI Act are reshaping how manufacturers validate heart rate, blood oxygen, and fall detection claims in consumer-oriented hardware. CE marking under the EU Medical Device Regulation imposes clinical evidence thresholds that favor incumbents with regulatory affairs infrastructure over emerging entrants. Stakeholders must monitor whether health-data portability mandates in major economies fragment platform exclusivity or accelerate interoperability investments.
Market Dynamics
The EU AI Act and FDA software-as-medical-device frameworks are bifurcating the hearable devices landscape into consumer-grade and clinical-grade tiers, forcing manufacturers to rebuild validation pipelines around biometric accuracy thresholds.
Growth Catalysts
- FDA software-as-medical-device framework:The pathway accelerates clearance for earbuds with heart rate and blood oxygen monitoring, enabling healthcare providers to deploy remote patient monitoring at scale.
- Telehealth infrastructure buildout:Germany, the United States, and South Korea are expanding reimbursement codes for assistive listening devices used in chronic disease management.
- Bluetooth Low Energy audio:The Auracast broadcast standard is integrating hearing accessibility into public venues, creating pull from institutional buyers for compatible hardware.
Market Restraints
- CE marking under EU MDR:Clinical evidence thresholds for biometric-enabled devices favor incumbents with regulatory affairs infrastructure, raising barriers for emerging entrants.
- MEMS microphone supply concentration:Foundry capacity for microelectromechanical microphones concentrates in East Asian contract manufacturers, exposing brands to single-source risk.
- Lithium-ion cell volatility:True wireless form factors depend on compact battery cells where cobalt and nickel price swings compress hardware margins unpredictably.
Strategic Opportunities
- Underpenetrated hearing aid dispensing:India and Brazil retain high untreated hearing loss prevalence with limited regulated dispensing channels, opening direct-to-consumer pathways for self-fitting devices.
- EU Green Deal circularity mandates:Battery replaceability requirements for small electronics are creating design differentiation for brands engineering modular earbud architectures.
- Spatial computing convergence:Inertial measurement units combined with head-tracking algorithms are integrating augmented reality audio into enterprise training and industrial safety applications.
Industry Challenges
- Biometric algorithm validation:Skin tone and fit variation across user populations complicates FDA and MFDS clearance for photoplethysmography-based vital sign monitoring.
- Legacy audiologist channel conflict:Direct-to-consumer hearing aid brands face resistance from regulated dispensing professionals in the United States and Germany.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hearable Devices Market |
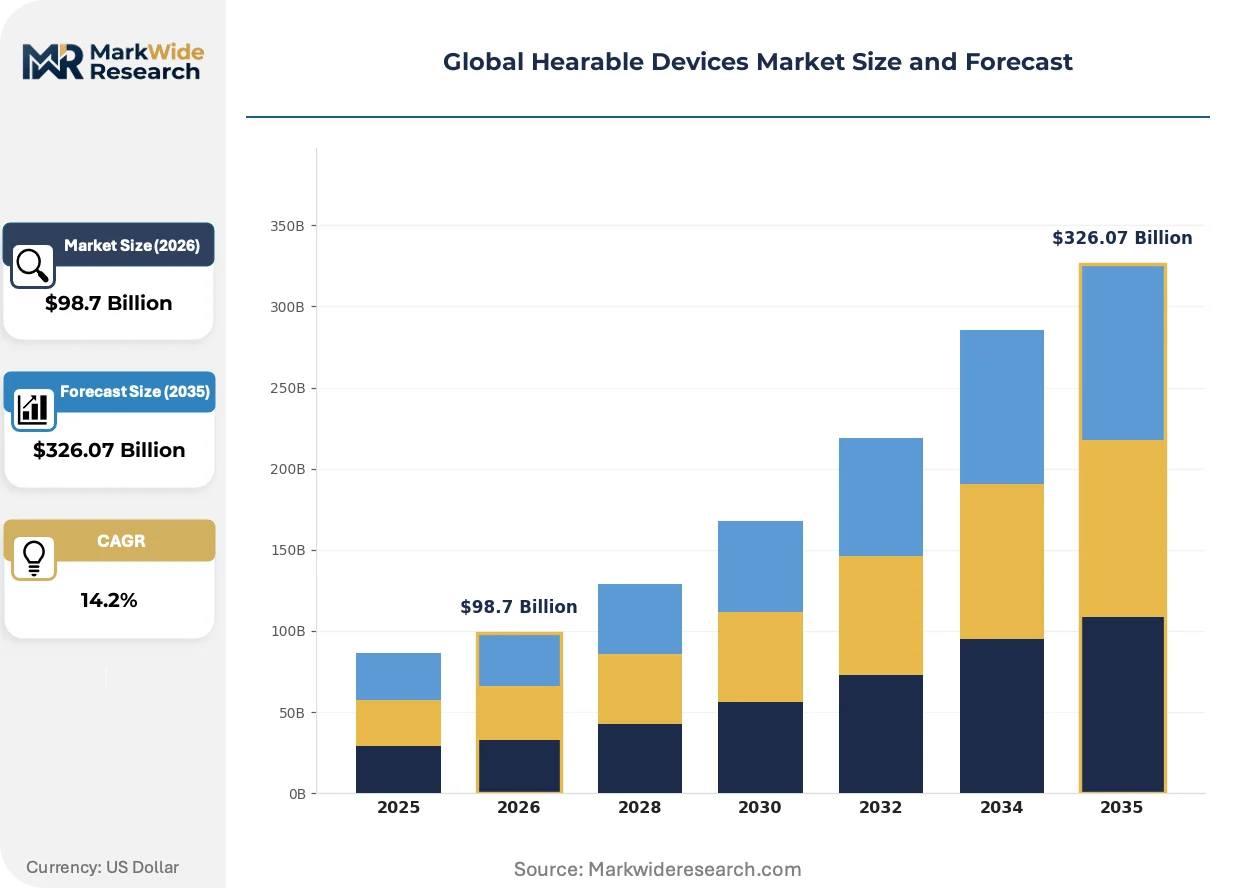
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $326.07 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Earbuds, Headphones, Hearing Aids, Assistive Listening Devices Technology: Bluetooth, True Wireless, Active Noise Cancelling, Voice Assistant End User: Consumer Electronics, Healthcare Professionals, Athletes, Music Enthusiasts Distribution Channel: Online Retail, Specialty Stores, Electronics Outlets, Wholesale |
| Companies Covered | Apple Inc., Samsung Electronics Co. Ltd., Sony Corporation, Bose Corporation, Jabra (GN Store Nord A/S), Skullcandy Inc., Sennheiser Electronic GmbH & Co. KG, LG Electronics, Bragi GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hearable Devices Market Emerging Trajectories
Sensor fusion architectures and regulatory data portability mandates are compressing the boundary between consumer audio and clinical monitoring, forcing hardware platforms to serve dual use cases from identical silicon.
Photoplethysmography and bioimpedance sensors are integrating into true wireless earbuds to enable continuous blood oxygen and stress monitoring. Healthcare systems in Germany and the United States are piloting these devices for post-surgical remote monitoring. The technology is integrating clinical-grade signal processing into consumer price points, collapsing the traditional separation between wellness and medical device categories.
The EU AI Act risk classification system is imposing conformity assessment requirements on biometric-enabled hearables marketed with health claims. Manufacturers must now maintain technical documentation and quality management systems comparable to Class IIa medical devices. Products targeting European clinical applications are responding by segregating firmware builds between consumer and professional variants.
Enterprise procurement of active noise cancelling headphones is unbundling from IT hardware refresh cycles toward subscription models with analytics dashboards. Facility managers in South Korea and the United States are replacing bulk purchases with per-seat service contracts that include usage tracking and replacement logistics. This shift is visible most acutely in contact center and open-plan office deployments where acoustic zoning drives productivity metrics.
Global Hearable Devices Market Segmentation
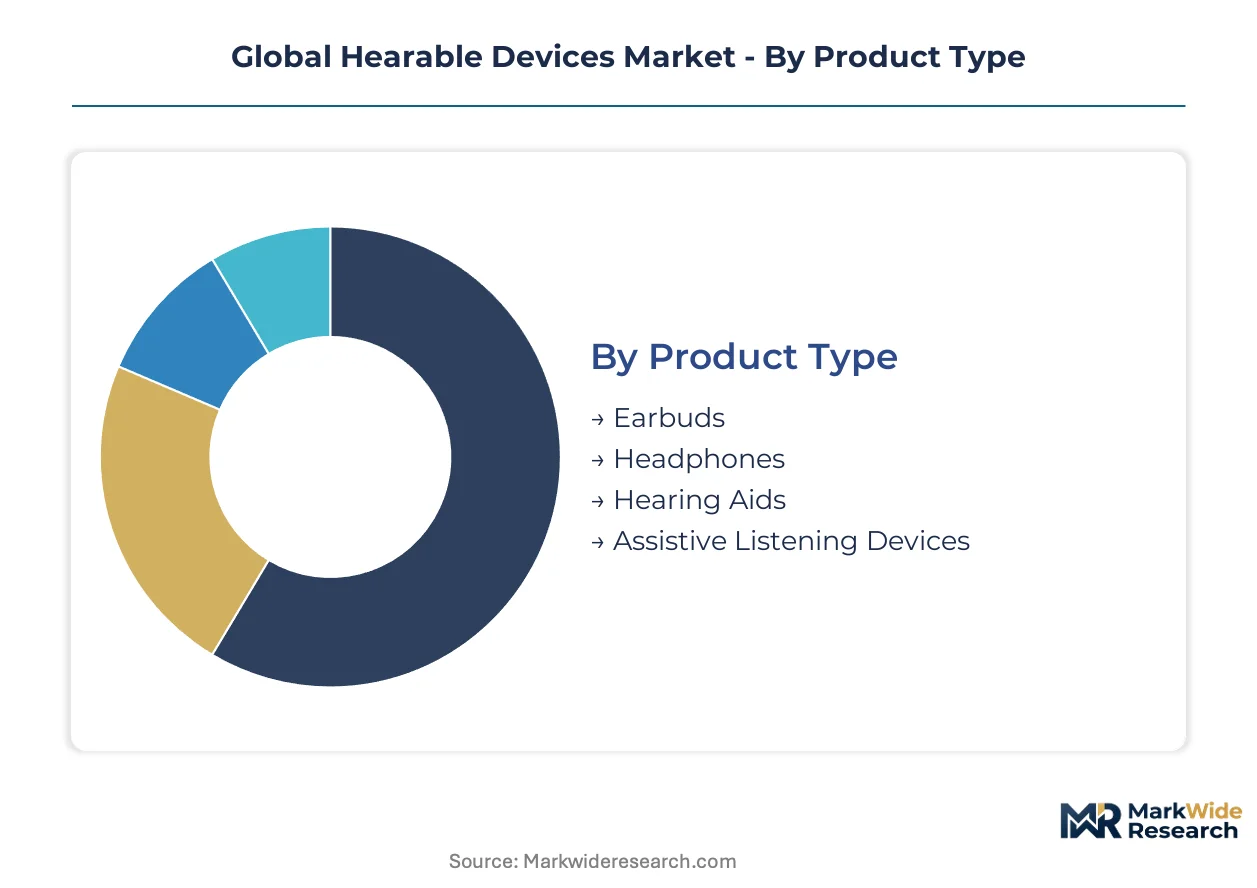
Hearable devices fragment across four structural dimensions where customization depth, regulatory burden, and channel economics create divergent margin profiles. Each category demands distinct validation pipelines, supply chain configurations, and go-to-market architectures.
Product Type:
Customization intensity spans from mass-produced consumer earbuds to individually fitted medical devices requiring clinical calibration and dispensing protocols.
- Earbuds:True wireless form factors integrate MEMS microphones, Bluetooth Low Energy chipsets, and photoplethysmography sensors for biometric monitoring. Demand concentrates in the United States and South Korea where consumer audio ecosystems and telehealth infrastructure create dual-use pull. The FDA software-as-medical-device framework accelerates clearance for heart rate and blood oxygen variants.
- Hearing Aids:Regulated medical devices requiring personalized fitting, audiogram calibration, and dispensing through licensed professionals. Germany and the United States maintain the steepest pricing premiums due to reimbursement codes and clinical evidence thresholds under CE marking and FDA pathways. Untreated hearing loss prevalence in India and Brazil opens direct-to-consumer self-fitting pathways.
- Headphones:Over-ear and on-ear designs emphasizing acoustic engineering and active noise cancellation for enterprise and travel segments.
- Assistive Listening Devices:Institutional hardware for accessibility compliance in public venues and educational facilities.
Leading the category by volume: Earbuds. Expanding most quickly: Hearing Aids.
Technology:
Cost tiers separate proprietary silicon integration from commodity chipset implementations, with premium capture concentrating in algorithm and firmware differentiation.
- True Wireless:Cord-free architectures eliminating physical connectors between left and right channels. Samsung Electronics Co. Ltd. anchors position through aggressive captive supply of semiconductor and audio subsystems. Lithium-ion cell volatility in compact battery form factors compresses hardware margins unpredictably.
- Active Noise Cancelling:Feedforward and feedback microphone arrays combined with inverse waveform generation. Bose Corporation commands professional audio loyalty through acoustic engineering heritage and algorithm performance. Enterprise procurement in South Korea and the United States shifts toward subscription models with analytics dashboards for contact center deployments.
- Bluetooth:Standard wireless protocol for audio transmission and device pairing.
- Voice Assistant:Embedded natural language processing enabling hands-free device control.
Dominating value capture: Active Noise Cancelling. Scaling fastest: True Wireless.
End User:
Application requirements range from lifestyle audio consumption to clinical-grade vital sign monitoring with FDA and EU MDR compliance obligations.
- Healthcare Professionals:Remote patient monitoring deployments leveraging biometric-enabled earbuds for post-surgical recovery and chronic disease management. Germany and the United States expand reimbursement codes for assistive listening devices in telehealth workflows. The EU AI Act imposes conformity assessment requirements comparable to Class IIa medical devices.
- Consumer Electronics:Mass-market audio consumption, fitness tracking, and spatial computing interfaces. Apple Inc. leverages proprietary silicon and ecosystem lock-in to sustain margin capture at the premium tier.
- Athletes:Performance monitoring and biometric feedback during training and competition.
- Music Enthusiasts:High-fidelity reproduction and studio-grade acoustic accuracy.
Generating highest average selling prices: Healthcare Professionals. Broadest volume base: Consumer Electronics.
Distribution Channel:
Customer type determines channel economics, with institutional procurement favoring direct relationships and consumer segments fragmenting across digital and physical touchpoints.
- Online Retail:Direct-to-consumer pathways enabling self-fitting hearing aid penetration in underregulated markets. Direct-to-consumer brands face resistance from audiologist channels in the United States and Germany.
- Specialty Stores:Professional fitting services and acoustic consultation for premium-tier selection.
- Electronics Outlets:Mass-market availability for consumer earbuds and headphones.
- Wholesale:Institutional procurement for enterprise active noise cancelling deployments and assistive listening device bulk purchasing.
Expanding fastest: Online Retail. Maintaining highest conversion for clinical devices: Specialty Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors the global hearable devices supply chain, concentrating MEMS microphone foundries, Bluetooth chipset packaging, and lithium-ion cell assembly within the Pearl River Delta electronics corridor.
United States
FDA software-as-medical-device clearances for biometric-enabled earbuds accelerate healthcare procurement in post-surgical remote monitoring. Reimbursement codes expand under Medicare for assistive listening devices in chronic disease management. The San Francisco Bay Area clusters algorithm developers optimizing photoplethysmography signal processing for diverse skin tone calibration.
Germany
CE marking under EU MDR imposes clinical evidence thresholds that favor incumbent hearing aid manufacturers with established regulatory affairs infrastructure. Telehealth infrastructure buildout in Bavaria and North Rhine-Westphalia integrates assistive listening devices into statutory health insurance reimbursement. Berlin anchors firmware development for EU AI Act compliance in biometric-enabled consumer hardware.
South Korea
MFDS clearance pathways for photoplethysmography-based vital sign monitoring attract enterprise procurement for workplace wellness programs. The Seoul Capital Area concentrates captive semiconductor production for Bluetooth Low Energy audio chipsets. Busan-Ulsan hosts contract manufacturers supplying MEMS microphone components to premium-tier brands.
China
Domestic demand for true wireless earbuds concentrates in the Yangtze River Delta, where Shanghai and Suzhou anchor retail distribution for consumer audio ecosystems. NMPA regulatory harmonization with FDA software-as-medical-device frameworks enables parallel clinical-grade certification for export-oriented manufacturers. Shenzhen's vertical integration into compact battery cell assembly compresses hardware margins through scale economies.
India
Untreated hearing loss prevalence in Maharashtra and Karnataka creates direct-to-consumer pathways for self-fitting devices outside regulated audiologist channels. BIS certification requirements for wireless audio equipment raise compliance costs for import-dependent brands. Bangalore clusters firmware developers adapting biometric algorithms for fit variation across diverse user populations.
Global Hearable Devices Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the hearable devices landscape, with captive foundry ownership separating premium-tier margin capture from commodity hardware assembly. The vendor base concentrates around three strategic archetypes: ecosystem-integrated technology conglomerates, acoustic engineering specialists, and direct-to-consumer audio brands. Consolidation pressures intensify as FDA and EU MDR compliance costs favor incumbents with regulatory affairs infrastructure. Competitive moves center on backward integration into semiconductor design and strategic partnerships for spatial computing audio algorithms.
Within the ecosystem-integrated tier, Apple Inc. and Samsung Electronics Co. Ltd. exemplify divergent approaches to silicon strategy and platform lock-in. Bose Corporation anchors the acoustic engineering specialist archetype through heritage positioning in active noise cancellation. Sony Corporation occupies a hybrid position spanning consumer audio and professional monitoring segments. These three named entities represent the dominant competitive vectors shaping technology licensing and geographic expansion patterns across the analysis window.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics Co. Ltd. |
| Sony Corporation |
| Bose Corporation |
| Jabra (GN Store Nord A/S) |
| Skullcandy Inc. |
| Sennheiser Electronic GmbH & Co. KG |
| LG Electronics |
| Bragi GmbH |
| Others |
Supply Flow & Price Mechanics
The premium-commodity bifurcation between clinical-grade hearing aids and mass-market earbuds manifests in divergent margin architectures and sourcing strategies. Hearing aids command reimbursement-backed premiums through regulated dispensing channels in Germany and the United States, while earbuds compete on cobalt-linked battery costs and MEMS microphone availability from East Asian foundries.
Pricing Analysis
Outcome-based pricing anchors hearing aid procurement through statutory reimbursement codes in Germany and Medicare coverage in the United States. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared biometric devices from wellness-tier consumer hardware. Price differentiation hinges on clinical certification grade and audiologist channel control. Cost compression in true wireless earbuds is intensifying because lithium-ion cobalt and nickel price swings compress hardware margins unpredictably. Enterprise buyers of active noise cancelling headphones exhibit lowest price sensitivity through subscription contracts, while direct-to-consumer earbud purchasers drive volume at thin margins.
Supply Chain Analysis
Freight cost volatility from East Asian contract manufacturers to European and North American assembly plants amplifies working capital pressure for brands without captive semiconductor production. Component sourcing concentrates in China for compact battery cell assembly, South Korea for Bluetooth Low Energy chipsets, and Taiwan for MEMS microphone foundries. Raw material dependencies span lithium-ion cobalt supply, rare earth magnet materials for speaker drivers, and photoresist chemicals for semiconductor fabrication. Single-source vulnerability in MEMS microphone foundry capacity exposes brands to allocation risk during demand spikes. Distribution runs through wholesale channels for enterprise active noise cancelling deployments and online retail for direct-to-consumer hearing aid penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hearable devices market has become a vertical-integration race where captive semiconductor design and regulatory affairs infrastructure separate margin capture from commodity assembly. Players are pursuing backward integration into Bluetooth chipset and sensor fusion silicon to escape foundry dependency.
For Market Incumbents: To counter direct-to-consumer self-fitting brands in underpenetrated hearing aid markets, incumbents should deepen audiologist channel control through exclusive fitting software licensing and accelerate FDA software-as-medical-device clearance for biometric-enabled earbuds to lock enterprise healthcare procurement. For New Entrants and Emerging Players: Begin with direct-to-consumer online retail in India and Brazil where untreated hearing loss prevalence outpaces regulated dispensing capacity. Target self-fitting hearing aid segments with smartphone-based audiogram calibration applications. Pursue EU Green Deal battery replaceability mandates as design differentiation against sealed-architecture incumbents. For Investors and Strategic Acquirers: Re-rating potential sits with acoustic engineering specialists possessing FDA regulatory infrastructure given EU AI Act compliance cost escalation. Long-term viability favors targets with established CE marking pathways and proprietary active noise cancellation algorithms. Watch MFDS clearance timelines for photoplethysmography-based vital sign monitoring as inflection indicator for clinical-grade market access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Design | Captive Bluetooth chipset production insulates Samsung Electronics from foundry allocation risk. |
| FDA Software-as-Medical-Device Submission | Clearance for blood oxygen monitoring unlocks Medicare reimbursement in remote patient monitoring. |
| EU AI Act Compliance Segregation | Separate firmware builds for consumer and professional variants satisfy Class IIa medical device thresholds. |
| Auracast Broadcast Standard Integration | Bluetooth Low Energy audio compatibility pulls institutional procurement from accessibility-mandated venues. |
| Direct-to-Consumer Online Launch | Self-fitting pathways bypass audiologist channel conflict in underregulated emerging markets. |
Methodological Framework
Independent corroboration across hospital procurement databases, GPO contracts, and CMS Medicare reimbursement filings underwrites the qualitative findings. Primary interviews with biomedical engineers, hospital purchasing committee members, regulatory affairs leads at hearing aid manufacturers, and formulary directors at German statutory health insurers combined with secondary validation from FDA 510(k) filings, CE marking databases under EU MDR, and MFDS medical device registrations. Bottom-up unit shipment estimates from contract manufacturers in Shenzhen and Busan-Ulsan triangulate against top-down healthcare expenditure allocations for assistive listening devices.
Comparable-period anchoring to historical reimbursement code expansions and telehealth infrastructure buildouts in Germany, the United States, and South Korea structured the projection horizon. The analytical framework models volume and value across product type, technology tier, end-user application, and distribution channel dimensions, with specific attention to regulated medical device versus consumer electronics pathway divergence. CAGRs derive from regression against Bluetooth Low Energy audio adoption curves and photoplethysmography sensor integration rates. Industry-specific forecast inputs include lithium-ion cell price volatility indices and EU AI Act implementation timelines.
Underlying measurement precision varies by segment; hearing aid pricing through regulated dispensing channels carries tighter precision than direct-to-consumer earbud estimates where promotional discounting obscures net realized prices. Forecasts reflect assumptions regarding reimbursement code stability, foundry capacity expansion, and regulatory harmonization between FDA and NMPA frameworks. Stakeholders should weight assumptions against their own operating context and supply contract structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
US Knife Sharpening Service Market
Consumer Electronics
HiFi Electronics Market
Consumer Electronics
Professional Headset Market
Consumer Electronics
Smartphone Console Market
Consumer Electronics
North America Wireless Anc Headphone Market
Consumer Electronics
Personal Computer Market
Consumer Electronics
Global Digital Watch Market
Consumer Electronics
Portable Laptop Stands Market
Consumer Electronics
India Consumer Electronics Market
Consumer Electronics
Watch Market
Consumer Electronics
Camera Case Market
Consumer Electronics
Global Monitor Headphones (in-Ear Monitors) Market
Consumer Electronics
Learning Remote Controls Market
Consumer Electronics
Used and Refurbished Smartphone Market
Consumer Electronics
Japan Gaming Peripherals Market
Consumer Electronics
Smart Television and Set-Top Box Market