
 Personal Computer Market | 2026-2036
Personal Computer Market Size, Share, and Industry Trends Forecast 2026-2036
Personal Computer Market Analysis
ENERGY STAR 8.0 certification is unwinding competitive access for smaller OEMs unable to fund thermal design validation. Lenovo leverages its in-house motherboard fabrication to control cost curves across enterprise fleets. HP anchors North American institutional contracts through dedicated education channel programs. Dell differentiates via direct-to-business configurators that bypass retail margin stacking.
A personal computer constitutes a programmable digital electronic device built around a central processing unit, system memory, storage subsystem, and I/O architecture, typically specified by thermal design power below 300W for standard form factors and operating system compatibility across x86 or ARM instruction sets, serving commercial data processing, content creation, and interactive communication functions. Laptop configurations command the dominant revenue pool as mobile productivity requirements persist across enterprise and educational deployments, while gaming PC assemblies capture disproportionate margin through discrete GPU integration and liquid cooling subsystems. Chrome OS traction among K-12 institutional buyers in North America and Western Europe is reshaping operating system share dynamics without displacing Windows in knowledge-worker environments.
The US EPA administers ENERGY STAR thresholds that dictate retail access and federal procurement eligibility, while the EU Ecodesign Directive mandates repairability scoring and standby power ceilings that force modular chassis engineering. India's BIS compulsory registration order for IT hardware creates country-specific testing timelines that delay product launches by two to three quarters. Stakeholders must weigh regional certification roadmaps against platform consolidation bets as ARM-based designs challenge x86 hegemony in thin-client and premium mobile segments.
Market Dynamics
Enterprise AI-capable workstation procurement is compressing refresh cycles while India's PLI scheme for IT hardware manufacturing redraws regional supply maps and China's Yangtze River Delta electronics cluster expands high-performance computing assembly capacity.
Growth Catalysts
- AI Workstation Demand:Knowledge-worker environments require discrete GPU integration for generative AI inference, pulling forward enterprise fleet replacements that had stalled during pandemic-era hardware saturation.
- India PLI Scheme:The Production Linked Incentive scheme for IT hardware manufacturing attracts contract manufacturers to establish local assembly lines, reducing import dependency and shortening fulfillment timelines for institutional buyers.
- ENERGY STAR 8.0:The US EPA certification threshold creates procurement eligibility requirements that filter federal and enterprise purchasing toward thermally validated designs, accelerating design standardization.
Market Restraints
- Memory Supply Concentration:DRAM and NAND fabrication concentrates in South Korea and Taiwan, exposing downstream assembly to geopolitical disruption and input cost volatility.
- EU Ecodesign Repairability:The Directive's scoring mandates and standby power ceilings force modular chassis engineering that increases bill-of-materials complexity and extends validation timelines.
- Chrome OS Substitution:K-12 institutional buyers in North America and Western Europe are redirecting volume toward thin-client alternatives that compress average selling prices in education verticals.
Strategic Opportunities
- ARM Architecture Convergence:Thin-client and premium mobile segments are adopting ARM-based designs that challenge x86 thermal envelopes, creating white space for instruction-set diversification.
- Direct-to-Business Configurators:Bypassing retail margin stacking through online fleet customization tools captures enterprise procurement officers seeking volume pricing transparency.
- BIS Registration Timeline Gaps:India's compulsory testing requirements delay product launches by two to three quarters, rewarding early regulatory filing strategies with first-mover positioning.
Industry Challenges
- Thermal Design Validation Talent:ENERGY STAR 8.0 certification requirements exceed smaller OEM engineering capacities, creating capability scarcity in computational fluid dynamics simulation.
- Legacy Fleet Integration:Enterprise IT departments face complexity unifying AI-capable workstations with existing Active Directory and endpoint management infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personal Computer Market |
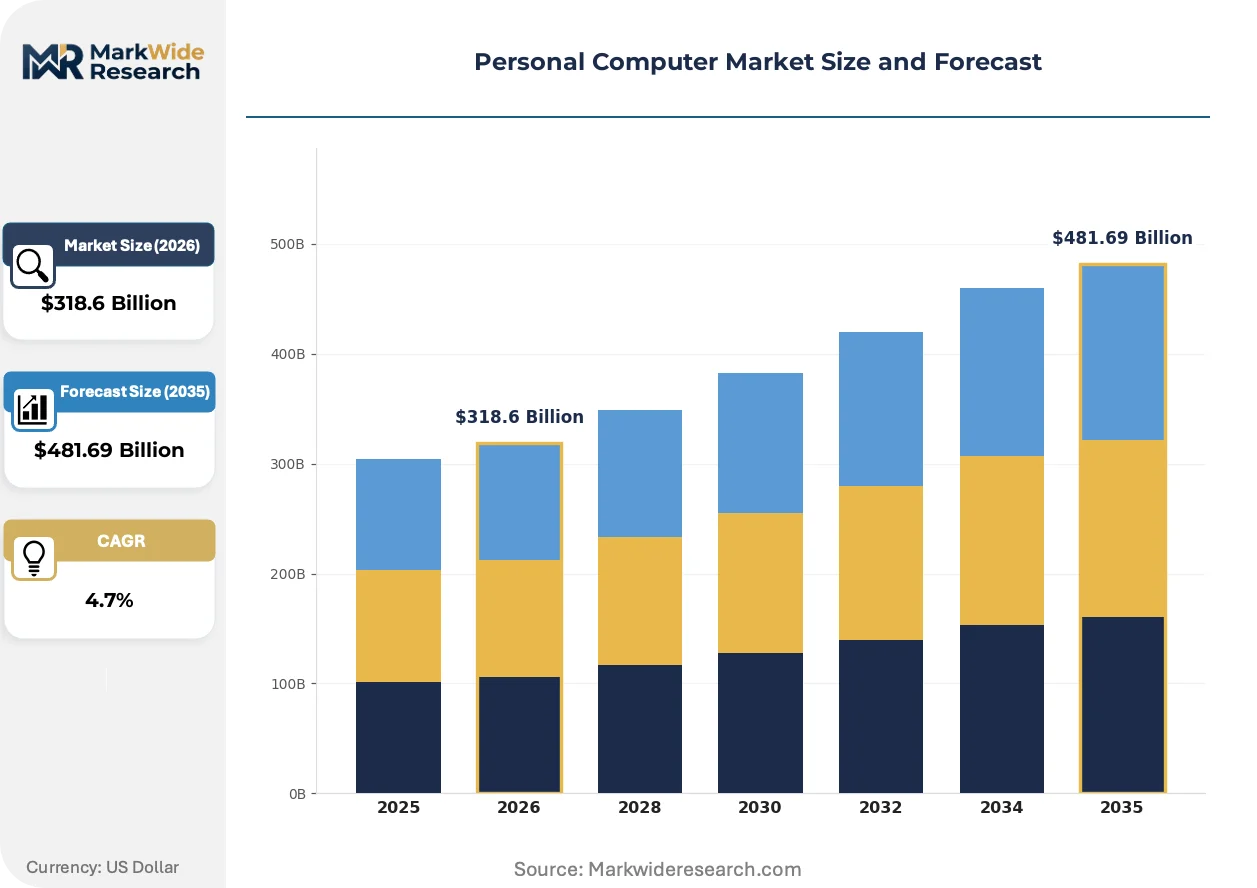
| Market Size in 2026 | $318.6 Billion |
| Market Size in 2035 | $481.69 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop, Laptop, All-in-One, Gaming PC End User: Home Users, Small Businesses, Enterprises, Educational Institutions Form Factor: Convertible, Traditional, Mini PC, Ultrabook Operating System: Windows, macOS, Linux, Chrome OS |
| Companies Covered | Lenovo, HP, Dell, Apple, Asus, Acer, Samsung, Microsoft, Razer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personal Computer Market Emerging Trajectories
Modular motherboard architectures and liquid cooling subsystems are restructuring how performance tiers get engineered, while regulatory repairability mandates and procurement channel shifts are rewriting competitive access rules.
Discrete GPU integration for generative AI inference is decomposing traditional CPU-centric workstation specifications. Enterprise fleet managers are specifying NVIDIA RTX Ada or AMD Radeon Pro configurations at three-year replacement intervals rather than five. This silicon divergence is decomposing the unified platform strategies that previously dominated corporate procurement standardization.
REACH substance restrictions and RoHS compliance deadlines are forcing solder alloy substitutions and halogen-free substrate migrations. The EU Ecodesign Directive's 2027 repairability scoring implementation is compressing design cycles for chassis modularity. Laptop and all-in-one categories face the steepest tooling redesign requirements as screw-accessibility and component labeling rules harden.
Education channel procurement officers are unbundling hardware acquisition from multi-year service contracts. K-12 districts in Texas and California are piloting self-maintained Chromebook fleets with third-party warranty extensions replacing OEM depot service. This disintermediation is most visible in North American institutional verticals where per-device management costs dominate total cost of ownership calculations.
Personal Computer Market Segmentation
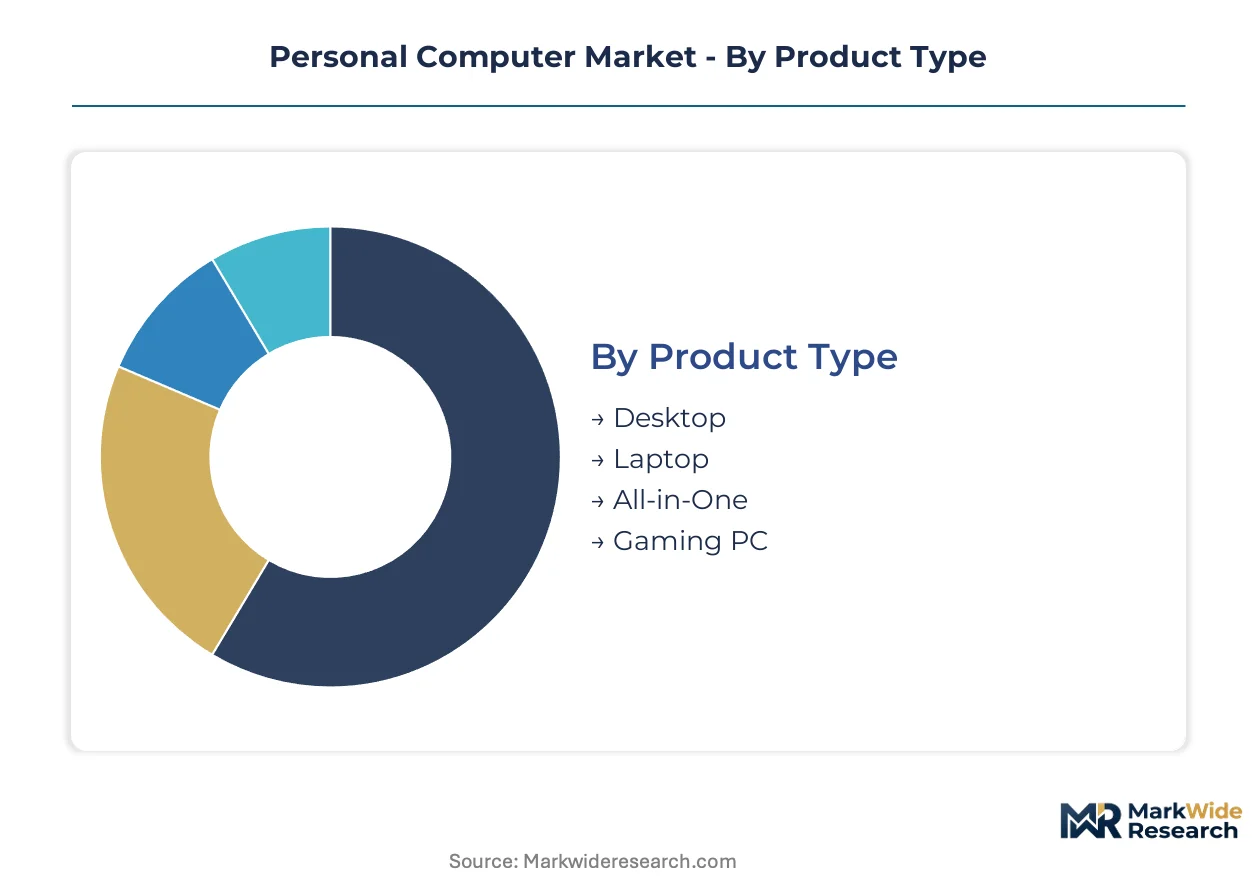
Personal computer segmentation dictates procurement channel access, thermal design priorities, and service attach rates. Enterprise buyers route volume through direct configurators while education verticals flow through specialized distributors with bundled warranty terms.
Product Type:
Channel mix splits sharply: enterprise fleets source laptops through direct OEM portals, gaming systems move through specialty retailers with component upgrade services, and institutional desktops flow via authorized education distributors.
- Laptop:Mobile form factors integrate discrete GPUs for AI inference workloads while maintaining sub-25mm z-heights. Enterprise procurement in the United States concentrates refresh cycles around ENERGY STAR 8.0 eligibility thresholds. This segment dominates revenue concentration across commercial and consumer channels.
- Desktop:Tower configurations accommodate 300W+ thermal design power for workstation-class silicon. Small business demand in India clusters around BIS-registered SKUs with localized keyboard layouts and regional power supplies. Modular chassis designs respond to EU Ecodesign repairability mandates.
- All-in-One:Integrated displays reduce cable complexity for reception desks and nursing stations. Thin panel depths sacrifice discrete GPU options.
- Gaming PC:Liquid cooling subsystems and RGB lighting controllers command premium positioning through specialty retail channels.
Laptop dominates installed base. Gaming PC is where expansion concentrates.
End User:
Cost tier stratification separates premium workstation procurement from thin-client institutional deployments, with margin structures varying threefold across customer types.
- Enterprises:Fleet standardization mandates Active Directory compatibility and three-year replacement intervals with AI-capable GPU specifications. Procurement officers in Germany negotiate volume pricing through framework agreements that lock thermal design parameters. This segment drives discrete GPU attach rates.
- Educational Institutions:K-12 districts in Texas and California pilot self-maintained Chromebook fleets with third-party warranty extensions. Per-device management costs dominate total cost of ownership calculations over acquisition price.
- Home Users:Retail channel purchases prioritize form factor aesthetics and display quality over serviceability.
- Small Businesses:Limited IT staff favor pre-configured bundles with depot service contracts over build-to-order flexibility.
Enterprises anchor volume commitments. Educational Institutions are climbing the fastest.
Form Factor:
Volume distribution skews toward thin-and-light profiles in premium mobile segments while miniaturized desktops capture embedded and digital signage applications.
- Ultrabook:Sub-15mm chassis heights employ carbon fiber unibody construction and soldered memory for structural rigidity. Corporate procurement in Japan specifies METI-aligned standby power thresholds. This segment commands the steepest average selling prices.
- Convertible:360-degree hinge mechanisms enable tablet-mode annotation for field service and healthcare workflows. Stylus integration differentiates education vertical offerings.
- Traditional:Clamshell designs maintain cost positioning through standardized component sourcing and simplified hinge assemblies.
- Mini PC:NUC-format enclosures mount behind displays for kiosk and conference room deployments with VESA compatibility.
Traditional clamshells dominate unit shipments. Ultrabook is where margin expansion concentrates.
Operating System:
Application compatibility requirements and security certification roadmaps determine OS selection, with federal procurement eligibility filtering toward EPA-validated platform combinations.
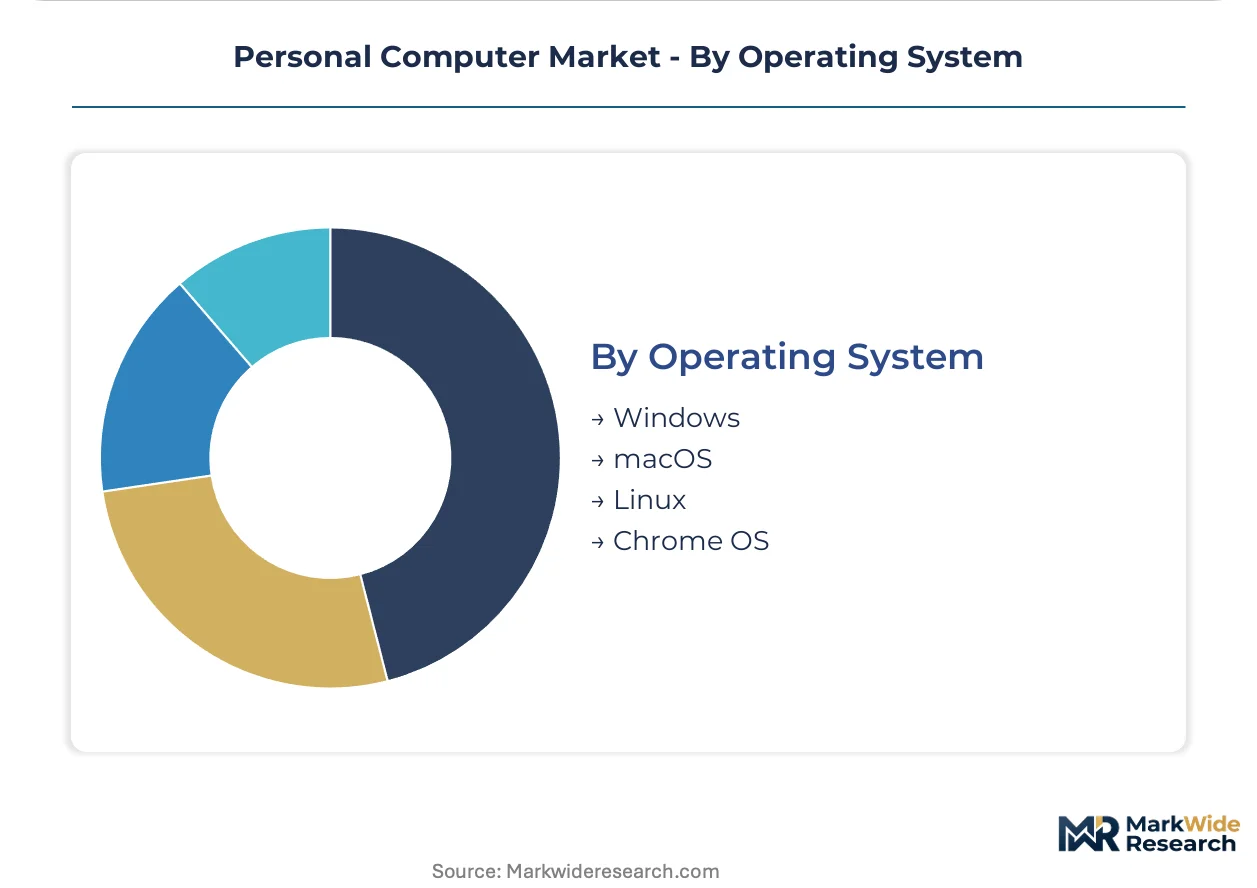
- Windows:Active Directory integration and legacy application compatibility sustain dominance across enterprise and small business deployments. Federal procurement in the United States requires ENERGY STAR 8.0 certification that validates specific Windows image configurations. This segment anchors commercial volume.
- Chrome OS:Cloud-native architecture reduces endpoint management overhead for K-12 institutional buyers. Western European education ministries specify repairability scoring that favors Chromebook modular designs.
- macOS:Creative professional workflows and developer ecosystems sustain positioning in premium price tiers.
- Linux:Open-source licensing eliminates per-seat costs for research computing and server-adjacent workstation deployments.
Windows dominates enterprise installed base. Chrome OS is where education vertical expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement officers in the United States compress refresh cycles around AI-capable workstation specifications. Federal agencies mandate ENERGY STAR 8.0 certification that filters vendor eligibility. India's PLI scheme attracts contract manufacturers to establish local assembly capacity.
United States
Federal procurement mandates ENERGY STAR 8.0 validation for retail access and institutional purchasing eligibility. The EPA administers thermal design thresholds that dictate workstation specifications for knowledge-worker environments. Austin and Raleigh-Durham clusters concentrate enterprise AI workstation deployment for financial services and defense contractors.
Germany
Enterprise fleet managers negotiate framework agreements that lock thermal design parameters across three-year replacement cycles. The EU Ecodesign Directive mandates repairability scoring and standby power ceilings that force modular chassis engineering. Bavaria's industrial automation sector drives workstation demand for CAD and simulation workloads.
China
Yangtze River Delta electronics clusters expand contract manufacturing capacity for high-performance computing assemblies. MIIT oversees GB standards compliance for electromagnetic compatibility and energy efficiency labeling. Shenzhen and Suzhou concentrate motherboard fabrication and GPU integration facilities serving domestic and export markets.
India
BIS compulsory registration orders for IT hardware create country-specific testing timelines that delay product launches by two to three quarters. The PLI scheme for IT hardware manufacturing attracts Foxconn and Dixon Technologies to establish local assembly lines. Tamil Nadu and Karnataka emerge as primary electronics manufacturing clusters with shortened fulfillment timelines for institutional buyers.
Japan
Corporate procurement in Tokyo and Osaka specifies METI-aligned standby power thresholds for ultrabook configurations. METI administers energy efficiency standards that influence premium mobile segment specifications. Chubu region manufacturing maintains precision tooling for carbon fiber unibody chassis production.
Personal Computer Market Vendor Landscape
Player mix skews toward vertically integrated multinational OEMs with captive motherboard fabrication and direct enterprise channel access. Three to five manufacturers capture the majority of commercial volume through framework agreements and federal procurement eligibility. Strategic archetypes separate into full-stack integrators controlling thermal design validation, direct-to-business configurators bypassing retail margin stacking, and education channel specialists bundling warranty terms. Competitive moves concentrate on ENERGY STAR 8.0 certification acceleration and India PLI scheme manufacturing localization.
Among vertically integrated OEMs, Lenovo leverages in-house motherboard fabrication to control cost curves across enterprise fleets. HP anchors North American institutional contracts through dedicated education channel programs. Dell exemplifies the direct-to-business configurator archetype with online fleet customization tools that bypass retail margin stacking.
| Leading Market Players |
|---|
| Lenovo |
| HP |
| Dell |
| Apple |
| Asus |
| Acer |
| Samsung |
| Microsoft |
| Razer |
| Others |
Supply Flow & Price Mechanics
Long-term framework agreements with thermal design parameter lock-ins secure supply access for enterprise fleet procurement while anchoring price visibility across three-year replacement cycles. These contracts tie volume commitments to ENERGY STAR 8.0 certification timelines and BIS registration milestones in India.
Pricing Analysis
Cost-plus contracts indexed to DRAM and NAND spot markets govern component sourcing for downstream assembly. Pricing stratifies across premium workstation, standard enterprise, and economy education tiers based on GPU attach rates and service bundling. Cost compression in K-12 Chromebook segments intensifies as institutional buyers unbundle hardware from multi-year service contracts. Education verticals exhibit the highest price sensitivity, while financial services procurement in the United States shows the least.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication and memory module production for personal computer assembly. Downstream manufacturing draws from Chinese motherboard clusters, Vietnamese chassis stamping, and Mexican final assembly for North American fulfillment. Single-source vulnerability concentrates in high-bandwidth memory supply for AI-capable workstations. Distribution runs through direct OEM portals for enterprise volume and authorized education distributors for institutional procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The personal computer market functions as a defensive-moat environment where ENERGY STAR certification entrenchment and enterprise switching costs protect incumbent positions against new hardware entrants.
For Market Incumbents: Secure ENERGY STAR 8.0 pre-certification for next-generation thermal designs before smaller OEMs can complete computational fluid dynamics validation. Expand captive motherboard fabrication capacity in India to exploit PLI scheme incentives and compress fulfillment timelines for institutional buyers. ARM-based workstation entrants threaten x86 standardization in thin-client segments. For New Entrants and Emerging Players: Anchor in India's BIS registration timeline gaps by filing regulatory documentation two quarters ahead of established competitors. Target education verticals in Western Europe where EU Ecodesign repairability mandates favor modular chassis designs that bypass incumbent tooling investments. Pursue white-label Chromebook assembly partnerships with third-party warranty providers to bypass OEM depot service infrastructure. For Investors and Strategic Acquirers: Thermal design validation boutiques with EPA submission expertise represent the most attractive acquisition archetype for capability gap-filling. Long-term viability hinges on positioning for AI workstation refresh cycles and ARM architecture convergence. Monitor ENERGY STAR 8.0 certification acceleration rates as the inflection signal for competitive access tightening.| Strategic Initiative | Industry Significance |
|---|---|
| ENERGY STAR Pre-Certification Investment | EPA validation locks federal procurement eligibility before competitors complete thermal testing. |
| India PLI Manufacturing Localization | Foxconn and Dixon Technologies assembly lines shorten fulfillment for institutional buyers. |
| Direct-to-Business Configurator Deployment | Online fleet customization bypasses retail margin stacking for enterprise procurement officers. |
| ARM Architecture Platform Development | Thin-client and premium mobile segments challenge x86 hegemony through instruction-set diversification. |
| Education Channel Warranty Unbundling | Third-party service extensions disintermediate OEM depot contracts in K-12 verticals. |
Methodological Framework
A spread of perspectives from enterprise fleet procurement officers, thermal design engineers, education channel distributors, and contract manufacturing executives converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against EPA certification databases, BIS registration filings, and EU Ecodesign Directive implementation timelines. Trade data from customs authorities and SEC disclosures from vertically integrated OEMs anchored bottom-up and top-down triangulation.
Product type, end-user vertical, form factor profile, and operating system architecture served as the core segmentation dimensions modeled across the projection horizon. CAGRs derived from historical replacement cycle compression and AI-capable workstation penetration curves. Forecast inputs incorporated PLI scheme capacity buildout timelines and ENERGY STAR 8.0 adoption trajectories without specifying year-bound milestones.
Material uncertainties — geopolitical disruption to memory supply, regulatory acceleration in repairability mandates, and ARM ecosystem maturity — sit outside the modeled envelope. Forecasts reflect assumptions about enterprise refresh cycle stability and thermal design validation capacity expansion. Recalibration cycles align with material shifts in EPA certification thresholds and India manufacturing localization rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Waterproof Headphones Market
Consumer Electronics
North America Smartphone Accessories Market
Consumer Electronics
Smartphone Console Market
Consumer Electronics
Chromebook Market
Consumer Electronics
Wrist Dive Computer Market
Consumer Electronics
Europe Smart TV Market
Consumer Electronics
North America Refurbished and Used Mobile Phones Market
Consumer Electronics
Smart Phones Market
Consumer Electronics
Global Monitor Headphones (in-Ear Monitors) Market
Consumer Electronics
Pet Cameras Market
Consumer Electronics
Ultraman Peripheral Market
Consumer Electronics
Computing Mouse Market
Consumer Electronics
Stress Ball Market
Consumer Electronics
Kindle E-Reader Accessories Market
Consumer Electronics
Pet Monitoring Camera Market
Consumer Electronics
Instant Camera Market