

HiFi Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
HiFi Electronics Market Insights
A widening capability gap between mass-market assemblers and precision engineering houses is reorganizing competitive tiers in the HiFi electronics space. Sony leverages captive semiconductor fabrication to control amplifier chip supply chains. Sennheiser anchors its position through handcrafted transducer manufacturing in domestic facilities. Bose differentiates via proprietary acoustic modeling software that reduces physical prototyping cycles.
HiFi electronics encompass audio reproduction equipment engineered for minimal signal distortion, typically achieving total harmonic distortion below 0.1% and frequency response flatness within ±2 dB across 20 Hz to 20 kHz, serving both critical listening and professional monitoring applications. Speakers and headphones capture the largest margin pools due to transducer complexity and brand premiumization, while DACs represent the fastest-expanding category as streaming sources proliferate. Vacuum tube technology persists as a niche premium segment, though solid-state designs dominate volume production across home theater and recording studio applications.
FCC emissions standards constrain wireless transmitter designs in US-bound products, while CE marking under the EU Radio Equipment Directive governs Bluetooth and Wi-Fi implementations across European markets. Japan's Ministry of Economy, Trade and Industry (METI) enforces energy efficiency benchmarks that shape amplifier power supply architectures. Stakeholders must weigh analog heritage against digital integration investments as consumer expectations shift toward seamless multi-room connectivity without sacrificing fidelity benchmarks.
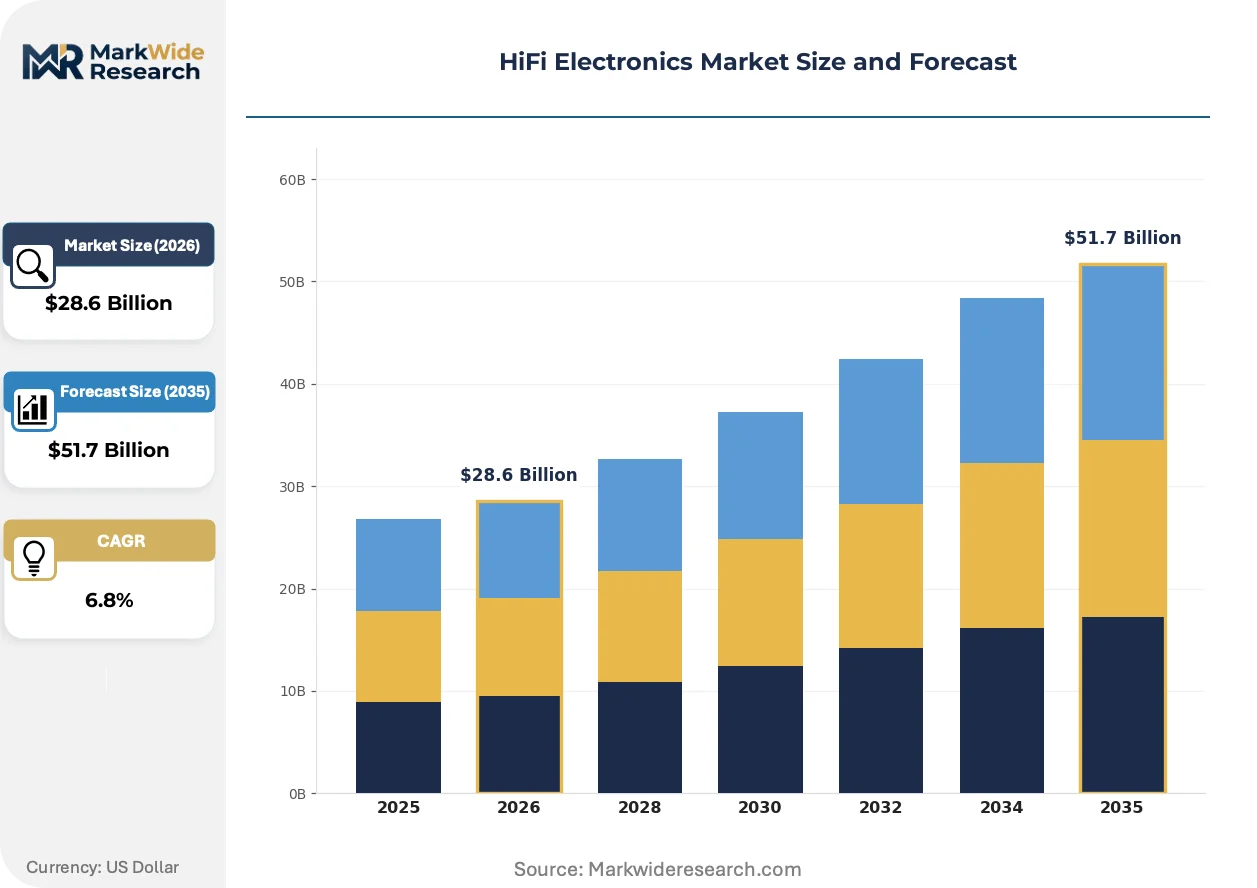
Market Dynamics
Wireless audio protocol maturation is compressing product refresh cycles while fragmenting component sourcing across Bluetooth, Wi-Fi, and proprietary RF stacks. Amplifier manufacturers now engineer for codec agility rather than static wired architectures.
Growth Catalysts
- Japan's METI energy efficiency mandates:Tiered standby power limits force Class-D topology adoption, expanding addressable market for switch-mode amplifier designs in residential installations.
- Audiophile room acoustics:Dedicated listening space construction in high-income households drives demand for matched component systems with calibrated frequency response.
- LDAC and aptX Lossless proliferation:High-bitrate Bluetooth codecs enable wireless transmission of uncompressed 24-bit/96kHz streams, eliminating cable infrastructure as a fidelity bottleneck.
Market Restraints
- Rare earth magnet concentration:Neodymium supply chains cluster in Chinese processing facilities, exposing transducer manufacturers to export quota volatility and forced substitution to ferrite alternatives.
- FCC Part 15 emissions testing:Wireless transmitter certification adds 8-14 week pre-market timelines and $40,000-$80,000 per SKU compliance burden for US-bound products.
- Solid-state displacement of vacuum tubes:Tube rectification and output stages face component obsolescence as Eastern European and Russian manufacturing contracts, compressing vintage-replica supply.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Production-linked incentives for audio equipment assembly attract OEM establishment in Noida and Sri City industrial corridors.
- Immersive audio formats:Dolby Atmos Music and Sony 360 Reality Audio create demand for height-channel speaker configurations and object-based rendering hardware.
- Direct-to-consumer channel maturation:Brand-owned e-commerce bypasses traditional dealer networks, capturing margin and enabling configuration-based customization at scale.
Industry Challenges
- Analog circuit design expertise scarcity:Discrete transistor-level audio engineering talent concentrates in aging workforce cohorts across German and Japanese heritage manufacturers.
- RoHS compliance complexity:Lead-free solder joint reliability in high-thermal-cycling amplifier applications demands accelerated life testing protocols that extend development schedules.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HiFi Electronics Market Trends and Innovations
Codec proliferation and streaming platform integration are redefining what constitutes a complete HiFi system. Physical media playback is decoupling from core electronics architecture.
GaN (gallium nitride) power semiconductors are bifurcating amplifier design trajectories. These wide-bandgap devices enable switching frequencies above 1MHz with sub-1% distortion, allowing compact Class-D architectures to challenge linear amplifier hegemony in premium segments. High-end manufacturers adopt GaN output stages for thermal efficiency in compact chassis, while mass-market assemblers exploit cost-down trajectories to displace legacy silicon MOSFETs entirely.
EU Radio Equipment Directive harmonization under RED 2014/53/EU is consolidating wireless certification requirements across member states. Manufacturers now design for single-notified-body approval valid across 27 jurisdictions, compressing regulatory overhead but mandating stricter RF exposure documentation. Portable and wireless HiFi products face the steepest compliance curve as SAR testing becomes mandatory for body-worn transmission.
Subscription-based hardware access is displacing outright ownership in urban consumer cohorts. Rental and lease-to-own programs for headphone and portable DAC categories target transient professionals in Berlin, Tokyo, and New York. These arrangements bundle insurance and upgrade privileges, capturing lifetime value through recurring revenue rather than single-transaction margins.
HiFi Electronics Market Segmentation
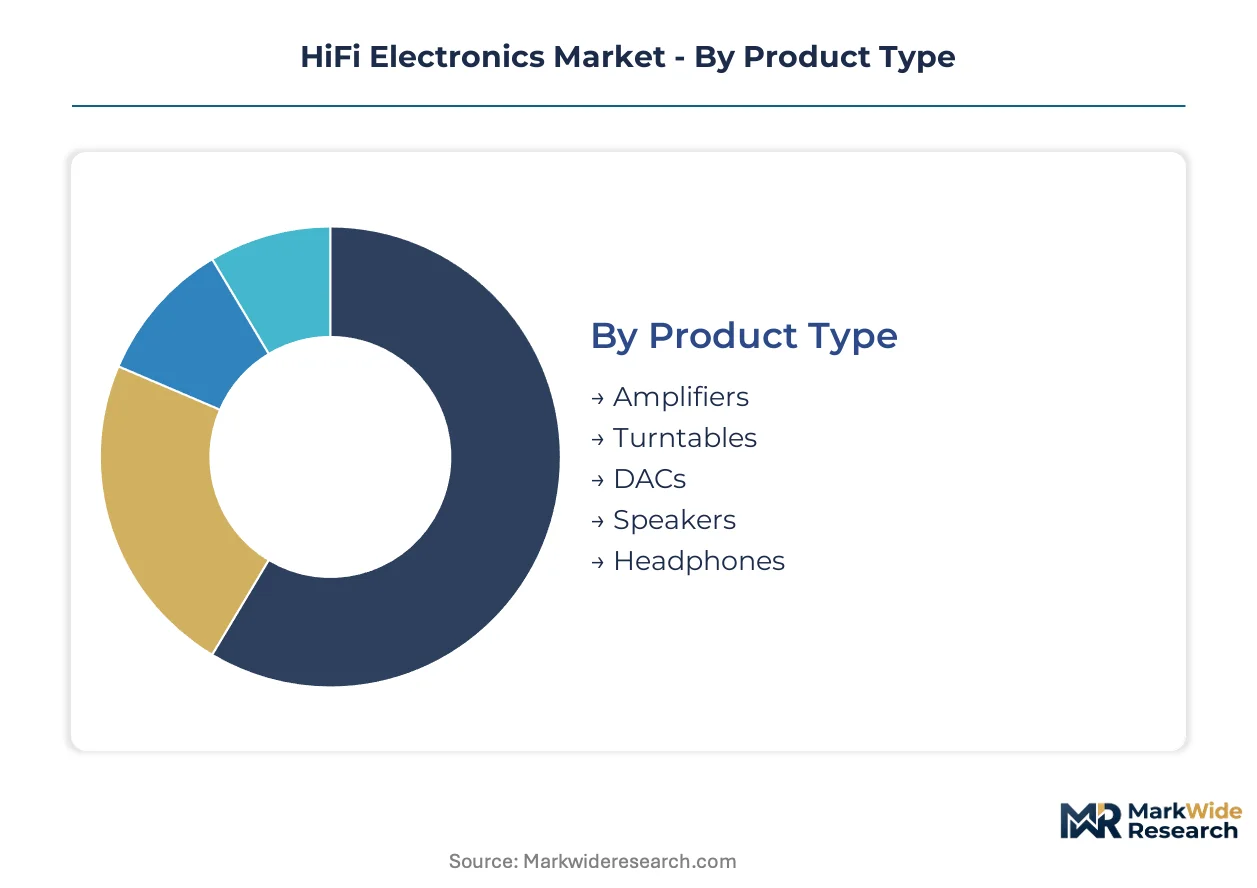
HiFi electronics segmentation reveals divergent sourcing patterns across product categories. Domestic manufacturing clusters in Germany and Japan anchor precision transducer production, while export-dependent assembly lines in Southeast Asia handle volume amplifier and DAC output.
Product Type:
Speakers and headphones concentrate manufacturing in heritage audio clusters across Germany and Japan, while amplifiers and DACs increasingly flow from export-oriented facilities in Malaysia and Vietnam.
- Speakers:Multi-driver configurations with crossover networks demand handcrafted assembly. Demand clusters in high-income residential markets across Germany, Japan, and the United States where dedicated listening room construction accelerates. Transducer complexity sustains margin premiums that mass-market assemblers cannot replicate.
- Headphones:Dynamic and planar magnetic drivers serve both portable and stationary applications. Japan's METI energy efficiency mandates push Class-D amplification integration into wireless models, reshaping power supply architectures for body-worn devices.
- Amplifiers:Solid-state and tube designs span integrated and monoblock configurations.
- DACs:USB and network streamer formats proliferate as streaming platforms displace physical media.
- Turntables:Belt-drive and direct-drive mechanisms persist among analog purists.
Speakers hold the largest share; momentum sits with DACs.
Technology:
Cost tier differentiation separates heritage analog engineering from digital integration investments, with wireless protocols commanding premium R&D allocation.
- Digital:FPGA-based signal processing and delta-sigma modulation dominate DAC and streamer architectures. Professional monitoring applications in recording studios across the United States and United Kingdom drive demand for sub-0.001% jitter specifications.
- Wireless:Wi-Fi and proprietary RF stacks enable multi-room synchronization. LDAC and aptX Lossless codec proliferation in Japanese and South Korean consumer markets eliminates cable infrastructure as a fidelity bottleneck for residential installations.
- Analog:Discrete transistor circuits persist in phono preamplifiers and line stages.
- Bluetooth:Low-energy and classic implementations serve portable categories.
- Vacuum Tube:Thermionic emission devices face component obsolescence as Eastern European manufacturing contracts.
Digital architectures command the greatest volume; wireless implementations are climbing the fastest.
Application:
Volume concentration in residential segments contrasts with margin-rich professional installations where calibration services extend revenue capture.
- Home Theater:Surround and immersive audio configurations integrate with display ecosystems. Demand concentrates in the United States where dedicated media room construction in suburban households drives speaker package sales.
- Audiophile Listening:Two-channel stereo systems prioritize signal purity over feature count. Germany's heritage engineering houses and Japan's precision manufacturers supply matched component systems for calibrated frequency response.
- Commercial Sound:Installed audio for hospitality and retail environments.
- Recording Studios:Nearfield monitors and reference headphones for production workflows.
- Educational Use:Institutional procurement for music programs and broadcast training.
Home Theater captures the greatest unit volume; Audiophile Listening delivers the steepest margin expansion.
End User:
Customer type determines channel strategy, with direct-to-consumer platforms disrupting traditional dealer networks among enthusiast cohorts.
- Audio Enthusiasts:Critical listeners prioritize measurable specifications and upgrade paths. Brand-owned e-commerce platforms in Berlin, Tokyo, and New York enable configuration-based customization that bypasses dealer markups.
- Professional Musicians:Stage and studio applications demand road-worthy construction. FCC Part 15 emissions testing for wireless monitor systems adds 8-14 week pre-market timelines for US-bound products.
- Educational Institutes:Bulk procurement with extended warranty requirements.
- Entertainment Venues:Installed sound systems for performance spaces.
- Corporate Clients:Conference and presentation audio for executive environments.
Audio Enthusiasts represent the largest addressable base; Professional Musicians show the fastest spending growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate the lowest price elasticity, absorbing premiums for handcrafted transducer assemblies and matched component systems. United States consumers split between mass-market wireless adoption and high-end dedicated listening room investments. Emerging manufacturing hubs in India and Vietnam compete primarily on landed cost, compressing margins for entry-level amplifier and DAC assembly.
United States
Dedicated media room construction in suburban households drives speaker package sales for immersive audio configurations. FCC Part 15 emissions testing adds 8-14 week pre-market timelines and $40,000-$80,000 per SKU compliance burden for wireless transmitter certification. Greater Boston and Pacific Northwest clusters anchor precision measurement equipment supply for professional monitoring applications.
Germany
Heritage engineering houses supply matched component systems for calibrated frequency response in critical listening environments. CE marking under the EU Radio Equipment Directive governs Bluetooth and Wi-Fi implementations across European markets. Bavaria and Baden-Württemberg manufacturing clusters concentrate handcrafted multi-driver speaker assembly with crossover network expertise.
Japan
METI energy efficiency mandates enforce tiered standby power limits that force Class-D topology adoption in residential amplifier designs. LDAC codec proliferation enables wireless transmission of uncompressed 24-bit/96kHz streams in domestic consumer markets. Kanto and Kansai industrial corridors host precision transducer manufacturing for planar magnetic and dynamic driver categories.
India
Production-linked incentives under the PLI scheme attract OEM establishment for audio equipment assembly in Noida and Sri City industrial corridors. Central Electricity Authority regulations shape power supply architectures for imported amplifier components. Maharashtra and Karnataka sub-regions concentrate electronics manufacturing services for export-oriented DAC and streamer assembly.
Vietnam
Export-dependent assembly lines handle volume amplifier and DAC output for North American and European brand partners. General functional descriptors for national trade compliance govern import duty structures on semiconductor components. Northern industrial zones around Hanoi and Hai Phong specialize in switch-mode power supply integration for cost-optimized Class-D architectures.
HiFi Electronics Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the HiFi electronics space. Captive semiconductor fabrication and handcrafted transducer manufacturing anchor premium positioning, while export-oriented assembly operations compete on scale economies. Three archetypes dominate: integrated conglomerates with vertical component control, heritage precision houses with domestic manufacturing, and digital-native platforms with direct-to-consumer distribution. Competitive moves concentrate on codec agility investments and multi-room connectivity integration rather than static wired architectures.
Among heritage precision manufacturers, Sennheiser and Yamaha occupy positions defined by domestic facility concentration and discrete engineering expertise. Sony anchors the integrated conglomerate archetype through captive supply chain structures. Bose exemplifies the algorithmic differentiation model with proprietary acoustic modeling capabilities. These three represent divergent strategic paths: transducer craftsmanship, component integration, and software-defined acoustics.
| Leading Market Players |
|---|
| Sony |
| Samsung Electronics |
| Bose |
| LG Electronics |
| Yamaha |
| Panasonic |
| Apple |
| Sonos |
| Sennheiser |
| Others |
Pricing and Supply Chain Analysis
Eighteen-week lead times for GaN power semiconductors from Taiwanese foundries concentrate pricing power among amplifier manufacturers with captive inventory positions, while spot-market purchasers absorb 15-25% cost premiums during allocation periods. This inventory asymmetry separates heritage brands with forward-contracted wafer starts from mass-market assemblers forced into ferrite magnet substitutions when neodymium export quotas tighten.
Pricing Analysis
Calibration services and extended warranty bundles now drive lifetime value, with aftermarket revenue streams expanding faster than hardware unit economics in premium segments. Three-tier pricing structure across premium, standard, and economy levels separates handcrafted transducer assemblies from mass-market Bluetooth implementations. Pricing pressure stems from Southeast Asian contract manufacturers competing on landed cost for entry-level DAC and amplifier assembly. Audio enthusiasts demonstrate the lowest price sensitivity, absorbing premiums for matched component systems, while corporate procurement teams negotiate aggressively on installed audio packages.
Supply Chain Analysis
Strait of Malacca transit routes underpin rare earth magnet flows from Chinese processing facilities to transducer manufacturers in Germany and Japan, exposing supply chains to geopolitical friction. Semiconductor fabrication concentrates in Taiwan, South Korea, and Japan, while neodymium processing clusters in China and vacuum tube manufacturing contracts in Eastern Europe. Single-source vulnerability runs through Chinese rare earth export quotas, forcing substitution to ferrite alternatives in cost-optimized designs. Distribution runs through brand-owned e-commerce platforms and traditional dealer networks, with direct-to-consumer channels capturing margin in enthusiast segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware-as-a-service models and subscription-based upgrade programs represent the fastest-expanding revenue layer, with rental arrangements for headphone and portable DAC categories capturing recurring revenue from transient urban professionals.
For Market Incumbents: Shield heritage margin positions by securing multi-year GaN wafer allocations from Taiwanese foundries before capacity constraints intensify. Deepen backward integration into handcrafted transducer manufacturing to differentiate from digital-native entrants exploiting commoditized Bluetooth module supply. METI energy efficiency mandates favor incumbents with existing Class-D topology expertise.
For New Entrants and Emerging Players: Lead with immersive audio format compatibility as a wedge into home theater installations where Dolby Atmos Music and Sony 360 Reality Audio create demand for height-channel configurations. India's PLI scheme for electronics manufacturing offers the most penetrable geography for cost-optimized amplifier assembly. Direct-to-consumer channel maturation enables configuration-based customization without dealer network investments.
For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate audio divisions lacking streaming platform integration capabilities. Long-term viability favors precision engineering houses with domestic manufacturing footprints and discrete transistor-level expertise. Watch LDAC and aptX Lossless codec penetration rates as inflection indicators for wireless fidelity acceptance.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN Power Semiconductor Integration | Enables compact Class-D architectures with sub-1% distortion challenging linear amplifier dominance. |
| Direct-to-Consumer Channel Expansion | Bypasses dealer markups in Berlin, Tokyo, and New York while enabling mass customization. |
| Immersive Audio Hardware Development | Captures Dolby Atmos Music and Sony 360 Reality Audio demand in dedicated media room construction. |
| India PLI Scheme Manufacturing Establishment | Production-linked incentives attract OEM assembly in Noida and Sri City corridors. |
| Subscription Hardware Access Programs | Rental and lease-to-own arrangements capture lifetime value from transient professional cohorts. |
Research Methodology
Cross-validation between supply chain intelligence from semiconductor distributors and regulatory filings from METI, FCC, and EU notified bodies anchors the qualitative findings. Primary interviews with amplifier design engineers, transducer manufacturing specialists, streaming platform integration leads, and dealer network operators combine with secondary validation from customs records, SEC filings, and energy efficiency certification databases. Bottom-up SKU-level modeling and top-down category spend analysis provide triangulation checks.
Sensitivity analysis around rare earth magnet price volatility and Bluetooth codec adoption curves shapes the analytical framework across the projection horizon. Segmentation dimensions include product type, technology architecture, application context, and end-user archetype, with additional modeling for wireless protocol penetration and Class-D topology share. CAGRs derive from installed base growth, replacement cycle compression, and premium tier mix shifts, with GaN semiconductor cost-down trajectories and METI standby power mandates as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained LDAC codec licensing expansion or stable rare earth export flows would require recalibration. Forecasts reflect assumptions around wireless fidelity acceptance and energy efficiency regulatory trajectories. Practitioners should keep alternative scenarios live as geopolitical conditions in semiconductor and magnet supply chains evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.