
 Smart Television and Set-Top Box Market | 2026-2036
Smart Television and Set-Top Box Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Television and Set-Top Box Market Analytics
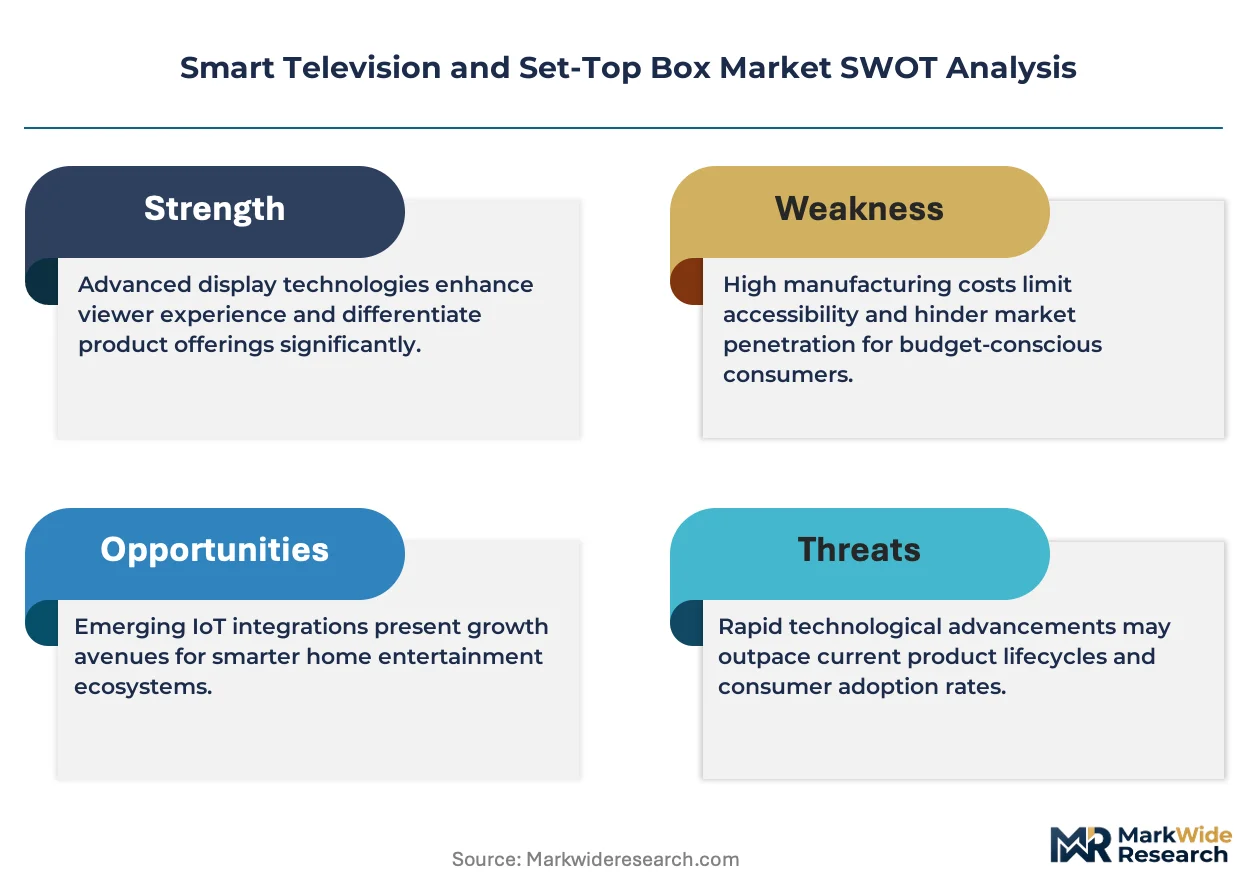
Project finance for display panel fabrication is fragmenting competitive entry barriers across the Smart Television and Set-Top Box landscape. Samsung Electronics leverages captive semiconductor foundry capacity to control component costs across its QLED lineup. TCL Electronics anchors volume production through vertically integrated LCD manufacturing in Shenzhen and Huizhou. Hisense Group competes aggressively on price-performance ratios in emerging markets through localized assembly partnerships.
Smart televisions and set-top boxes encompass networked display terminals and decoding devices that render digital video streams through integrated system-on-chip processors, typically featuring HDMI 2.1 interfaces, Wi-Fi 6 connectivity, and 4K or 8K resolution panels with HDR10+ decoding capability; their commercial purpose centers on delivering subscription and advertising-funded content to residential and commercial viewers. OLED TVs command premium positioning due to manufacturing complexity and material costs, while 4K Ultra HD TVs sustain mainstream volume leadership across price-sensitive segments. Streaming Services technology captures the fastest structural expansion as cord-cutting accelerates and platform-exclusive content deepens subscriber retention.
The US FCC enforces digital broadcast standards and set-top box interoperability rules that shape hardware certification timelines and retail distribution requirements. India's BIS mandates compulsory registration for electronic imports, while the EU Ecodesign Directive imposes standby power limits and material disclosure obligations on devices sold across member states. Stakeholders must monitor evolving interoperability mandates and energy-labeling thresholds that determine market access eligibility without warning.
Market Dynamics
Project finance fragmentation for display panel fabrication is redistributing competitive entry barriers while streaming-first consumption patterns compress replacement cycles for decoding hardware across residential and commercial installations.
Growth Catalysts
- Broadband infrastructure rollout:India's tier-two cities are experiencing rapid fiber-to-the-home deployment, enabling 4K and 8K streaming adoption that necessitates hardware upgrades.
- Ecodesign Directive standby limits:The EU's tightening energy-efficiency thresholds are accelerating replacement of legacy set-top boxes in hospitality and residential sectors across Germany, France, and Italy.
- Interactive guest entertainment systems:Dubai, Singapore, and London hotels are deploying touch-integrated displays that require HDMI 2.1 and Wi-Fi 6 capable terminals.
Market Restraints
- OLED material cost concentration:Premium panel production depends on limited suppliers of organic emitter materials, constraining price elasticity in high-end segments.
- BIS certification timelines:India's compulsory registration scheme for electronic imports creates extended pre-market clearance periods that delay product launches.
- LCD supply geographic concentration:Display module fabrication clusters heavily in specific Chinese manufacturing zones, exposing buyers to concentrated logistics disruption risk.
Strategic Opportunities
- India's underserved tier-three markets:Low penetration of connected televisions in smaller cities offers first-mover positioning as OTT subscription rates accelerate.
- EU circular economy mandates:The Ecodesign Directive's material disclosure obligations favor modular, repairable set-top box designs that reduce total cost of ownership.
- AI-driven content personalization:Convergence of edge computing and system-on-chip neural processing enables localized recommendation engines without cloud dependency.
Industry Challenges
- HDMI 2.1 certification complexity:Variable refresh rate and enhanced audio return channel testing extends hardware validation timelines by 8-12 weeks.
- Legacy hospitality infrastructure integration:Property management system protocols in established Dubai and London hotel properties require custom middleware development for new display terminals.
- 8K content pipeline scarcity:Limited native ultra-high-definition programming compresses consumer willingness to pay panel premiums, forcing manufacturers to justify upgrades through upscaling performance alone.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Television and Set-Top Box Market |
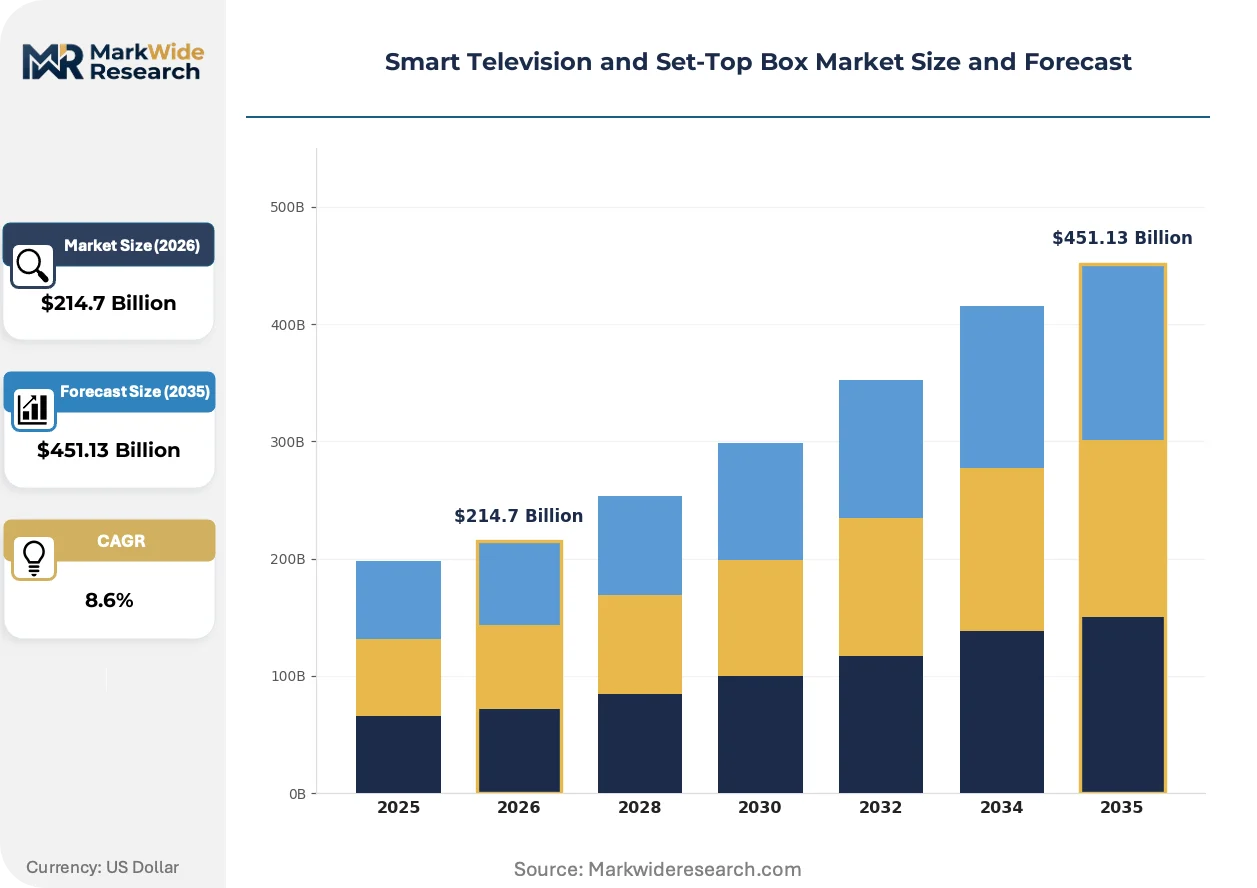
| Market Size in 2026 | $214.7 Billion |
| Market Size in 2035 | $451.13 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart TVs, 4K Ultra HD TVs, OLED TVs, LED TVs Technology: HDMI, Wi-Fi, Bluetooth, Streaming Services End User: Residential, Commercial, Educational, Hospitality Service Type: Installation, Maintenance, Content Subscription, Technical Support |
| Companies Covered | Samsung Electronics, LG Electronics, TCL Electronics, Hisense Group, Sony Group Corporation, Huawei Technologies, Roku, HUMAX, CommScope Holding, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Television and Set-Top Box Market Evolving Landscape
Display technology roadmaps and content delivery architectures are converging around bandwidth-efficient streaming protocols and intelligent processing at the network edge, compressing the functional distinction between decoding hardware and display panels.
MicroLED backlighting arrays are rendering obsolete conventional full-array local dimming systems in premium television segments. Hospitality buyers in Singapore and Dubai are specifying these panels for daylight-viewable lobby installations. The technology is rendering obsolete the contrast-ratio limitations that previously forced venue operators to compromise between brightness and black-level performance.
The EU Ecodesign Directive's 2023 standby power thresholds are forcing set-top box manufacturers to redesign power management architectures. Hardware vendors serving Germany and France must now integrate true zero-watt standby modes that disconnect AC input during idle periods. This regulation is compressing margins on entry-level decoder models while accelerating premium tier segmentation.
Subscription bundling is consolidating consumer purchasing decisions around platform-exclusive content rather than hardware specifications. Retail channels in India and the UK are responding with aggressive financing for television purchases tied to multi-year streaming commitments. This pattern is most visible in India's tier-two cities where broadband penetration and platform competition are simultaneously intensifying.
Smart Television and Set-Top Box Market Segmentation
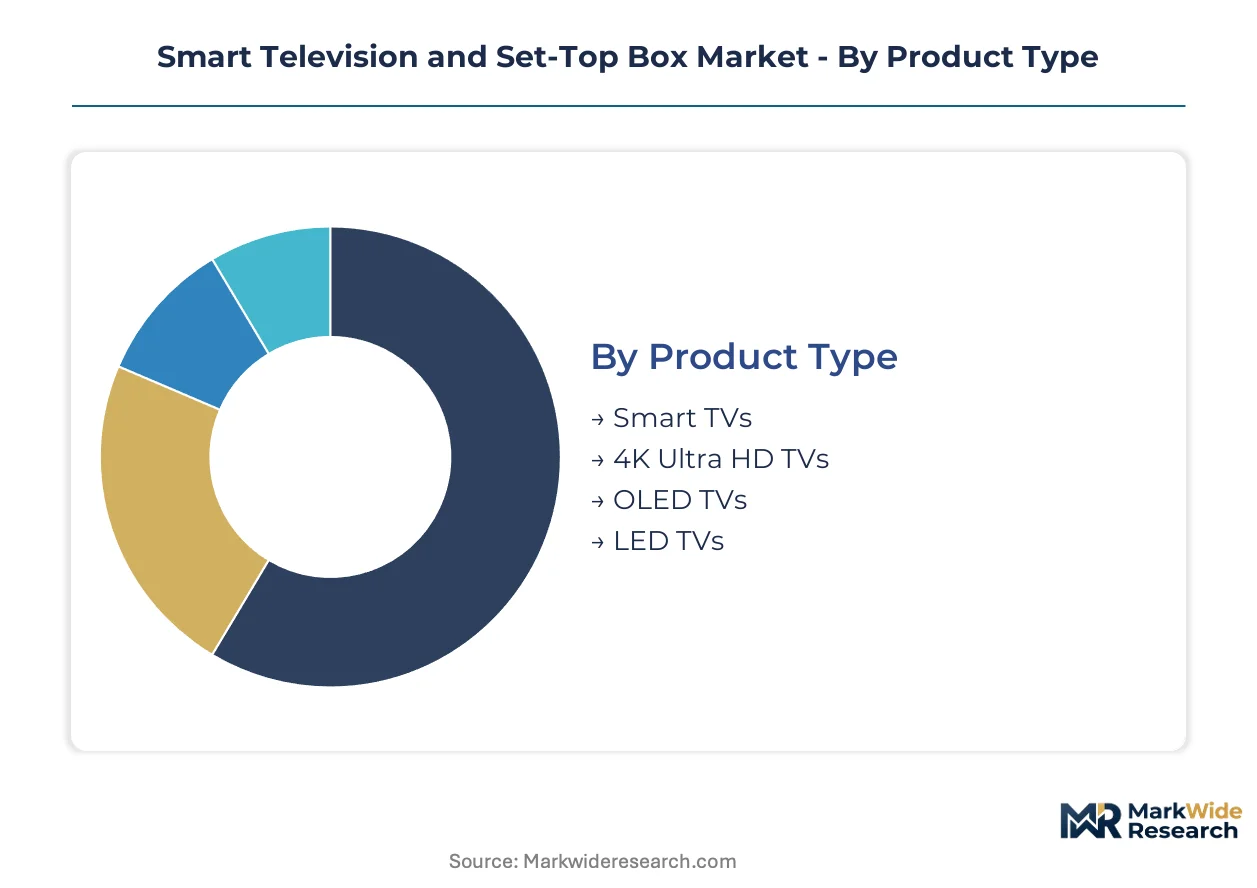
Segmentation in the Smart Television and Set-Top Box Market reveals how hardware specifications, connectivity protocols, and service models align with distinct purchasing logics across residential and commercial buyers. Understanding these divisions exposes where margin pools concentrate and where volume expansion accelerates.
Product Type:
Mature LCD-based categories dominate shipment volumes while emerging display technologies reshape premium positioning and replacement cycles.
- Smart TVs:Networked displays integrate system-on-chip processors with embedded streaming applications, eliminating external decoder requirements. Demand concentrates in India's tier-two cities where broadband penetration and OTT subscription rates are climbing fastest.
- 4K Ultra HD TVs:These panels render 3840x2160 resolution through LCD or QLED backplanes with HDR10+ decoding capability. Hospitality venues in Dubai, Singapore, and London are upgrading display infrastructure to support interactive guest entertainment systems requiring 4K minimum specifications.
- OLED TVs:Self-emissive organic panels deliver infinite contrast ratios without backlight arrays. Manufacturing complexity and material costs constrain price elasticity in high-end residential segments.
- LED TVs:Edge-lit or direct-lit LCD configurations serve entry-level price points through simplified backlight architectures. Volume shipments sustain emerging market penetration where cost sensitivity dominates purchase decisions.
4K Ultra HD TVs retain volume leadership; Smart TVs hold the steepest expansion curve as integrated streaming displaces external set-top boxes.
Technology:
Cost tier differentiation separates essential connectivity from premium bandwidth and processing capabilities that enable advanced features.
- HDMI:The 2.1 specification enables 48Gbps throughput for uncompressed 8K/60Hz or 4K/120Hz signals with variable refresh rate support. Variable refresh rate and enhanced audio return channel testing extends hardware validation timelines by 8-12 weeks.
- Wi-Fi:Wi-Fi 6 and emerging Wi-Fi 6E standards reduce latency for 4K streaming in dense residential environments. India's tier-two cities experiencing rapid fiber-to-the-home deployment drive Wi-Fi 6 capable terminal upgrades.
- Bluetooth:Low-energy protocols connect peripheral audio devices and remote controls without dedicated RF hardware. Peripheral integration requirements are modest across price-sensitive segments.
- Streaming Services:Platform-embedded content delivery architectures compress functional distinction between decoding hardware and display panels. Subscription bundling consolidates consumer purchasing decisions around platform-exclusive content rather than hardware specifications.
HDMI retains interface standard dominance; Streaming Services technology is expanding most quickly as cord-cutting accelerates and platform-exclusive content deepens subscriber retention.
End User:
Application context determines performance thresholds, with hospitality and education imposing specialized integration requirements absent in residential deployments.
- Residential:Individual households prioritize streaming application breadth and voice control integration. India's underserved tier-three markets offer first-mover positioning as OTT subscription rates accelerate.
- Commercial:Corporate deployments emphasize digital signage management platforms and centralized content distribution. Procurement patterns favor volume pricing through enterprise distribution channels.
- Educational:Institutions require interactive whiteboard compatibility and durable chassis designs for high-usage environments. Budget constraints favor standard-definition alternatives in underfunded districts.
- Hospitality:Hotels mandate property management system integration and customized welcome screen branding. Dubai, Singapore, and London properties are deploying touch-integrated displays that require HDMI 2.1 and Wi-Fi 6 capable terminals.
Residential maintains absolute volume dominance; Hospitality commands the steepest technology upgrade trajectory as interactive guest entertainment systems proliferate.
Service Type:
Customer type stratification separates one-time hardware transactions from recurring revenue models that transform lifetime value calculations.
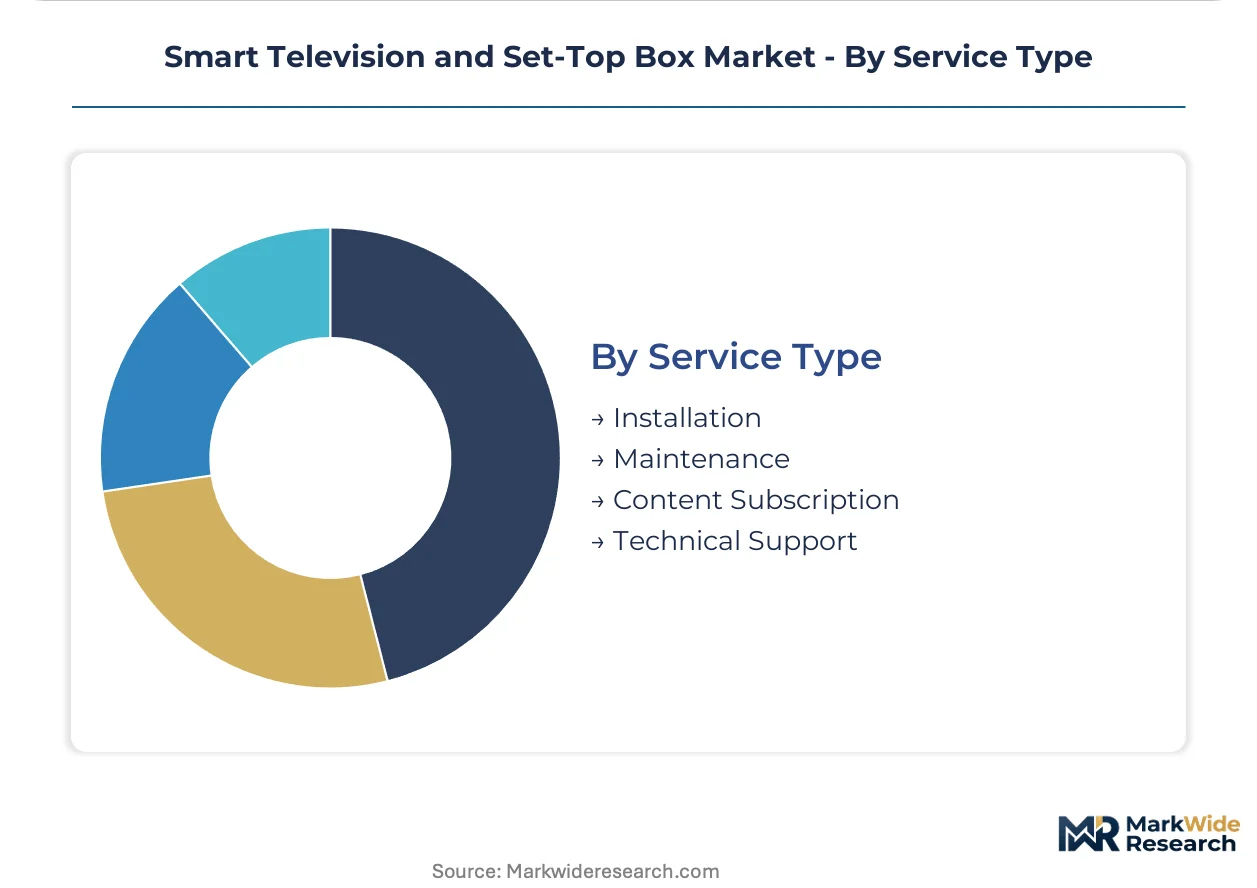
- Installation:Professional mounting, calibration, and network configuration services reduce return rates and support claims. Retail channels in India and the UK are responding with aggressive financing for television purchases tied to multi-year streaming commitments.
- Maintenance:Extended warranty and repair programs address panel degradation and port failure risks. EU circular economy mandates favor modular, repairable designs that reduce total cost of ownership.
- Content Subscription:Recurring platform fees now exceed hardware costs over typical replacement cycles. Bundled streaming commitments are most visible in India's tier-two cities where broadband penetration and platform competition are simultaneously intensifying.
- Technical Support:Remote diagnostics and firmware update assistance sustain device functionality across multi-year ownership periods. Support costs compress margins on entry-level decoder models while accelerating premium tier segmentation.
Content Subscription captures recurring revenue leadership; Installation services are gaining share fastest as display complexity and integration requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany and France where Ecodesign Directive enforcement accelerates premium-tier replacement cycles, while Indian tier-two cities absorb volume shipments at compressed margins as broadband infrastructure expands.
United States
FCC interoperability mandates and cord-cutting momentum drive Wi-Fi 6 and HDMI 2.1 terminal upgrades across residential and hospitality segments. The regulator's set-top box rules shape hardware certification timelines and retail distribution requirements. Texas and California clusters anchor enterprise procurement for commercial digital signage and corporate display deployments.
Germany
Ecodesign Directive standby power limits force zero-watt standby redesigns across entry-level and mid-tier decoder models. The EU regulation compresses margins on legacy hardware while accelerating premium segmentation in hospitality and residential sectors. Bavaria and North Rhine-Westphalia manufacturing zones concentrate modular, repairable set-top box production for circular economy compliance.
India
BIS compulsory registration schemes delay product launches while tier-two cities generate fastest OTT subscription growth and fiber-to-the-home deployment. TRAI broadcast regulations intersect with import certification timelines to reshape competitive entry sequencing. Maharashtra and Karnataka industrial corridors host localized assembly partnerships for price-sensitive volume segments.
China
Vertically integrated LCD fabrication in Shenzhen and Huizhou anchors global display module supply, though concentrated logistics exposure creates disruption vulnerability. MIIT connectivity standards and GB certification frameworks govern domestic terminal specifications. Yangtze River Delta and Pearl River Delta clusters dominate QLED and MicroLED backlighting array production for premium export markets.
United Arab Emirates
Dubai hospitality venues deploy touch-integrated displays with HDMI 2.1 and Wi-Fi 6 specifications for interactive guest entertainment systems. MOHAP device registration and UAE energy efficiency labeling shape import compliance pathways. Dubai and Abu Dhabi property developments concentrate procurement for daylight-viewable lobby installations requiring advanced contrast and brightness performance.
Smart Television and Set-Top Box Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in display panel and semiconductor supply. The vendor base stratifies across captive foundry operators, vertically integrated fabricators, and streaming-native hardware entrants. Three archetypes dominate: semiconductor-integrated platform owners, China-based display manufacturers with backward panel control, and software-anchored streaming device specialists. Competitive moves concentrate on foundry capacity allocation, modular repairability design for EU compliance, and hospitality-specific property management system integration.
Among Korea-based electronics conglomerates, Samsung Electronics and LG Electronics exemplify semiconductor-integrated platform ownership with captive foundry leverage. TCL Electronics anchors the vertically integrated display manufacturing archetype through Shenzhen and Huizhou production bases. Hisense Group occupies a position exemplifying aggressive price-performance competition in emerging markets through localized assembly partnerships. These three company structures represent distinct strategic postures: upstream component control, manufacturing scale concentration, and market-entry flexibility through distributed production.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| TCL Electronics |
| Hisense Group |
| Sony Group Corporation |
| Huawei Technologies |
| Roku |
| HUMAX |
| CommScope Holding |
| Others |
Value Network & Pricing Analysis
Overcapacity in Shenzhen and Huizhou LCD fabrication zones is compressing panel supplier margins while simultaneously enabling aggressive pricing postures across mid-tier smart television segments. This utilization dynamic feeds downstream into set-top box assembler negotiations, where captive foundry operators extract component cost advantages that independent hardware vendors cannot match.
Pricing Analysis
The customization-premium spread between property management system-integrated hospitality displays and standard retail configurations spans significant cost tiers. Pricing stratifies across premium OLED, mainstream QLED, and economy LED tiers, with certification grade for EU Ecodesign compliance and volume scale for India's tier-two city deployments serving as primary differentiation drivers. Cost compression in entry-level decoder models is intensifying because zero-watt standby redesigns absorb engineering resources without commensurate price recovery. Hospitality buyers in Dubai and Singapore exhibit the least price sensitivity due to guest experience mandates, while India's tier-three residential segments demand aggressive economy positioning.
Supply Chain Analysis
Upstream organic emitter materials for OLED panels draw from limited South Korean and Japanese chemical suppliers, constraining price elasticity at the premium tier. Display module fabrication rests on concentrated capacity in China's Shenzhen, Huizhou, and Yangtze River Delta clusters, with system-on-chip processors sourcing from Taiwan and South Korean foundry networks. Single-source vulnerability in specialized HDMI 2.1 controller silicon exposes hardware vendors to allocation prioritization during capacity crunches. Distribution runs through enterprise procurement channels for hospitality and commercial segments, while retail electronics chains and platform-bundled financing dominate residential volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward streaming platform operators and hospitality procurement consortia as volume concentrates among fewer decision-makers with multi-year deployment horizons. This consolidation compresses hardware vendor margins while elevating specification-setting influence.
For Market Incumbents: Pre-empt platform-native hardware displacement by deepening captive foundry allocation for Wi-Fi 6 and HDMI 2.1 system-on-chip integration. Secure modular repairability certification ahead of EU circular economy enforcement to defend hospitality replacement cycles against lower-cost Asian competitors. Vertical integration into display panel fabrication remains essential for margin control. For New Entrants and Emerging Players: India's tier-three cities with accelerating fiber-to-the-home deployment but minimal connected television penetration represent the most penetrable entry point for localized assembly partnerships. Modular set-top box designs targeting EU circular economy compliance offer a secondary white-space avenue as incumbent redesign cycles lag regulatory deadlines. A platform-bundled financing go-to-market angle aligns with OTT subscription growth patterns in underpenetrated Indian markets. For Investors and Strategic Acquirers: Capital is best deployed toward semiconductor-integrated platform owners with captive foundry leverage and established hospitality property management system integration capabilities. Long-term viability hinges on neural processing unit integration for edge-based content personalization, compressing cloud dependency and recurring infrastructure costs. The signal to watch is BIS certification timeline compression in India, which would accelerate competitive entry sequencing and reshape volume allocation.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Capacity Expansion | Samsung Electronics leverages in-house semiconductor production to control QLED component costs against TCL's Shenzhen manufacturing base. |
| EU Circular Economy Compliance Redesign | Modular set-top box architectures with true zero-watt standby modes satisfy Germany's Ecodesign Directive while compressing legacy competitor margins. |
| Hospitality Property Management System Integration | Custom middleware development for Dubai and London hotel protocols secures multi-year display terminal replacement contracts. |
| Platform-Exclusive Content Bundling | Retail financing partnerships in India's tier-two cities align television purchases with multi-year streaming commitments from Disney+ Hotstar and Netflix. |
| MicroLED Backlighting Array Commercialization | Singapore and Dubai lobby installations specify daylight-viewable panels that obsolete conventional full-array local dimming limitations. |
Research Methodology
Cross-validation between primary interviews with display procurement managers at hospitality chains and secondary analysis of FCC certification filings anchors the qualitative findings. The research combined structured conversations with semiconductor foundry planners, OTT platform hardware partnership leads, and retail electronics category buyers against customs import data, BIS registration databases, and EU Ecodesign compliance disclosures. Bottom-up shipment estimates by panel technology and top-down consumer electronics revenue triangulation were reconciled across the analysis window.
Calibration against historical replacement cycle data and broadband infrastructure deployment timelines shaped the projection framework. Segmentation dimensions modeled include display technology tier, connectivity protocol specification, end-use application context, and regional regulatory cluster. CAGRs were derived from installed base turnover analysis and OTT subscription growth correlation. Forecast inputs incorporated fiber-to-the-home penetration curves in India's tier-two cities and Ecodesign Directive enforcement phase-in schedules across Germany, France, and Italy.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending and semiconductor capital expenditure cycles would shift the trajectory. Forecasts reflect underlying assumptions about platform-exclusive content investment continuity and hospitality occupancy recovery patterns. Cross-checking against TRAI broadcast subscriber data and EU energy label registration volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Subwoofer Market
Consumer Electronics
Wrist Dive Computer Market
Consumer Electronics
Apple Accessories Market
Consumer Electronics
Bluetooth Headphones Market
Consumer Electronics
Personal Computer Market
Consumer Electronics
Soft Support Products Market
Consumer Electronics
TV Mirror Market
Consumer Electronics
GCC Soundbar Market
Consumer Electronics
Electric Water Bottle Market
Consumer Electronics
Russia Gaming Gadgets Market
Consumer Electronics
Global Smart Outdoor TV Market
Consumer Electronics
Ultra HD Action Camera Market
Consumer Electronics
Ereader and Enotetaking Devices Market
Consumer Electronics
Global 4K TV Market
Consumer Electronics
Global Polaroid Market
Consumer Electronics
Air Tube Headset Market