
 India Consumer Electronics Market | 2026-2036
India Consumer Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
India Consumer Electronics Market Insights
Rural electrification and digital payment penetration is realigning how Indian households prioritize appliance upgrades over basic durables. Samsung Electronics leverages its manufacturing scale in Noida to anchor supply for northern and western markets. LG Electronics competes through specialized inverter compressor technology in air conditioners and refrigerators. Haier Appliances India sustains channel control via exclusive brand stores in tier-three towns alongside traditional trade.
Consumer electronics encompass electronic devices designed for personal or household use, typically operating on alternating current or rechargeable power with specifications ranging from 5V DC in wearables to 240V AC in large appliances, serving entertainment, communication, home automation, and productivity functions. Smartphones and televisions occupy the largest revenue pools, though wearables represent the fastest-expanding category as fitness tracking integrates with health insurance offerings. Laptops retain structural importance among professionals and students, where margin concentration favors thin-and-light models with extended battery cycles over entry-level configurations.
BIS mandatory registration schemes and the CEA's appliance efficiency labeling program shape product design and import eligibility for all electronics sold in India. The PLI scheme for large-scale electronics manufacturing redirects capital toward domestic assembly of smartphones and components, altering competitive dynamics for foreign versus local brands. Stakeholders must monitor how BIS expands compulsory testing protocols to additional product categories, as this determines which suppliers can maintain market access without costly certification delays.
Market Dynamics
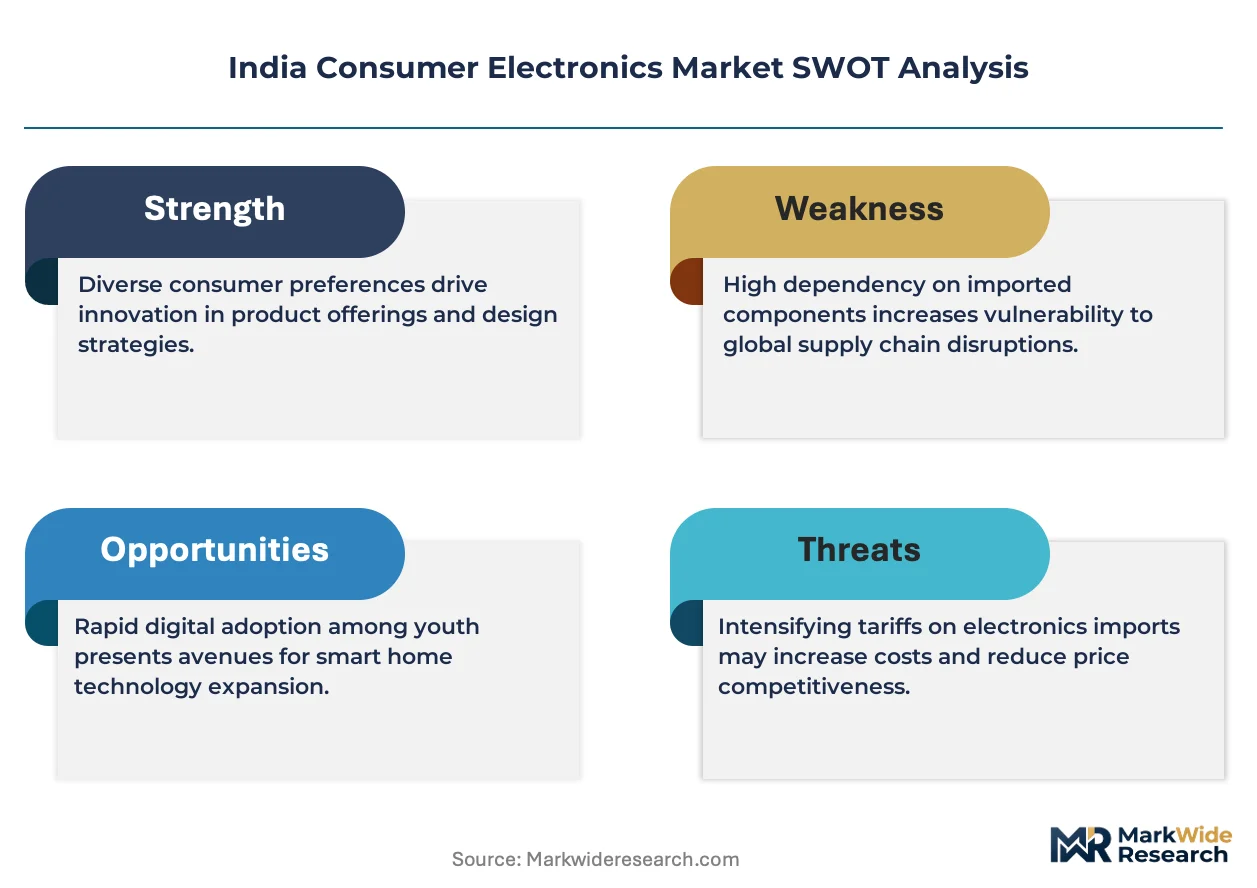
PLI scheme disbursements are redirecting capital toward domestic smartphone assembly, compressing import dependency while BIS certification mandates reshape supplier eligibility across all electronics categories.
Growth Catalysts
- Rural electrification:Grid extension into tier-three towns unlocks first-time appliance ownership, with refrigerator and washing machine penetration climbing fastest in electrified villages.
- CEA efficiency labeling:Mandatory star-rating programs accelerate replacement cycles as households trade older units for certified energy-saving models.
- Digital payment infrastructure:UPI penetration enables EMI financing at point-of-sale, collapsing upfront cost barriers for mid-tier smartphone and television purchases.
Market Restraints
- Semiconductor input volatility:Memory chip and display panel prices fluctuate with Taiwan and South Korea supply conditions, compressing assembler margins unpredictably.
- BIS testing bottlenecks:Compulsory registration scheme backlogs delay product launches by four to eight weeks for unregistered imports.
- Component import concentration:Over seventy percent of finished electronics rely on Chinese PCB and battery cell supplies, exposing assemblers to DGFT tariff adjustments.
Strategic Opportunities
- Tier-two city expansion:Surat, Indore, and Coimbatore exhibit underpenetrated connected appliance demand relative to income growth trajectories.
- Health-insurance wearables convergence:Fitness tracker data integration with private insurer wellness programs creates recurring revenue attachment models.
- Component PLI extension:Scheme expansion into display modules and camera modules incentivizes captive sourcing for smartphone brands.
Industry Challenges
- Embedded systems talent scarcity:Firmware and IoT security engineering capacity lags hardware assembly scale, delaying smart appliance launch timelines.
- Multi-standard certification complexity:Separate BIS, WPC, and BEE approvals for single products fragment compliance resources.
- Legacy distributor credit exposure:Traditional trade partners in tier-three towns carry elevated receivables risk as working capital costs rise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Consumer Electronics Market |
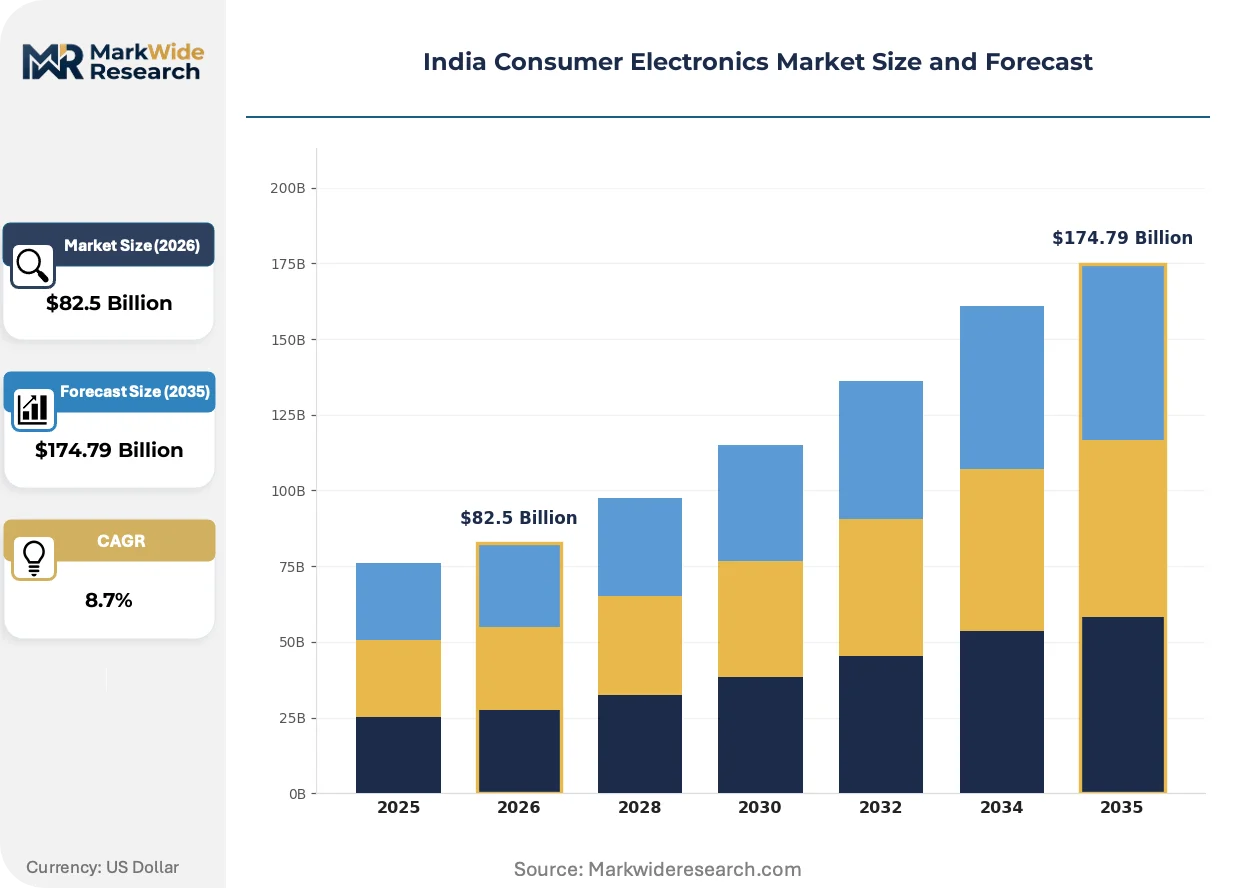
| Market Size in 2026 | $82.5 Billion |
| Market Size in 2035 | $174.79 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphones, Laptops, Televisions, Wearables Brand: Xiaomi, Samsung, Sony, LG Distribution Channel: Online, Offline Retail, Department Stores, E-commerce Customer Segment: Millennials, Families, Students, Professionals |
| Companies Covered | Panasonic Corporation, Haier Appliances India, Samsung Electronics, V-Guard, Toshiba Corporation, LG Electronics, Havells India, Atomberg Technologies, Sony Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Consumer Electronics Market Trends and Innovations
Local value addition requirements and energy efficiency mandates are compressing product development cycles while forcing assemblers to redesign supply footprints around certified component sourcing.
GaN (gallium nitride) charging semiconductors are consolidating across smartphone and laptop adapter portfolios. Premium handset brands have adopted 65W and above fast-charging specifications within eighteen months of commercial availability. This transition is consolidating adapter supply chains around three domestic contract manufacturers with BIS-approved testing facilities.
BIS compulsory registration scheme expansion into wireless audio devices and smart watches tightens import eligibility. Unregistered shipments now face port detention until laboratory testing completes, forcing brands to pre-certify models six months ahead of launch. Wearables and hearables segments are responding by shifting final assembly to Noida and Sri City export zones where in-house testing laboratories accelerate clearance.
Appliance-as-a-service pilots are emerging in Bengaluru and Hyderabad rental markets. Young professionals subscribing to furnished apartments prefer monthly refrigerator and washing machine fees over ownership, with property aggregators bundling hardware into lease agreements. This model compresses brand-direct relationships and elevates after-service reliability as a selection criterion over upfront pricing.
India Consumer Electronics Market Segmentation
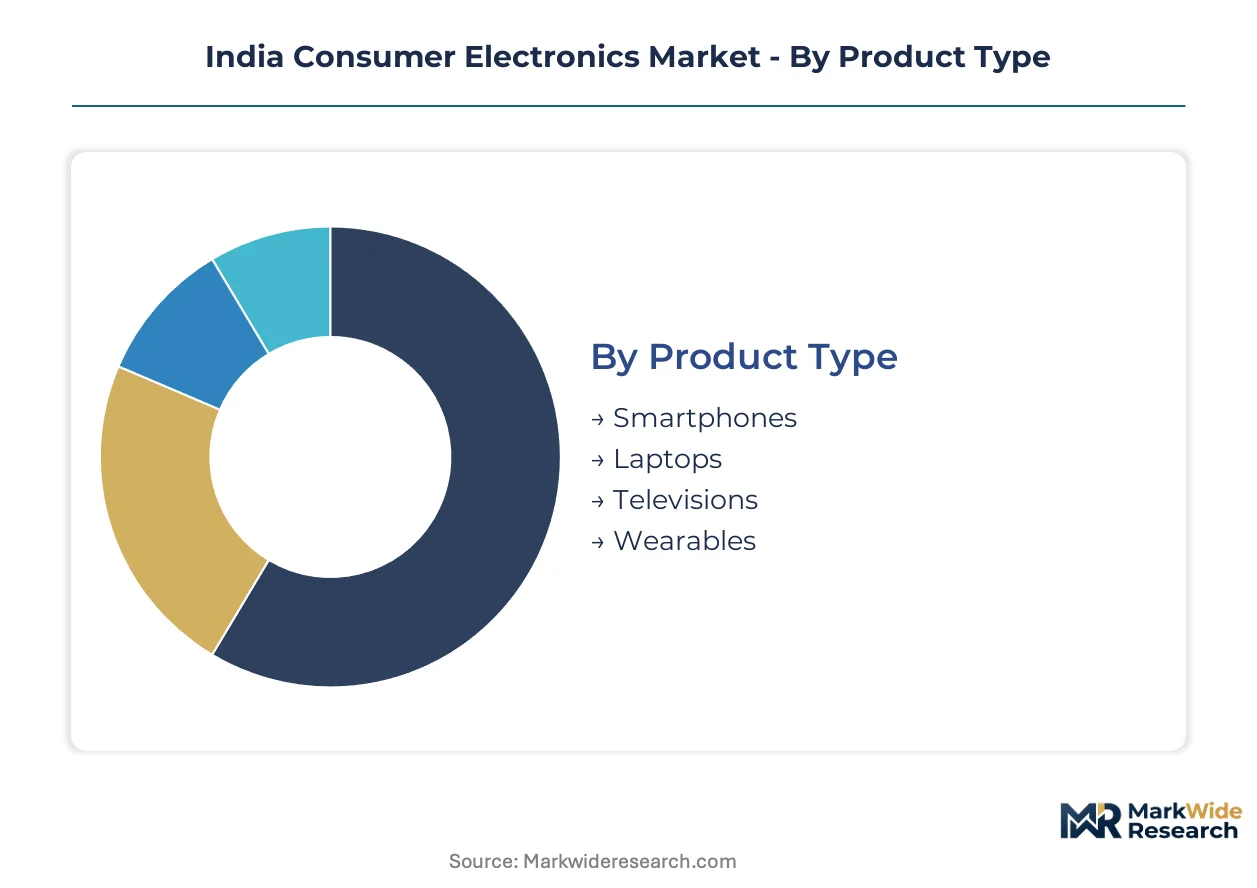
Consumer electronics in India fragment across product architectures, brand positioning, and purchase contexts that determine margin structures and channel economics. Understanding how households self-select into device categories and retail formats clarifies where assembly investment and certification resources generate returns.
Product Type:
Standalone personal devices dominate volume, while embedded home systems anchor replacement cycles and energy compliance exposure.
- Smartphones:Pocket-sized computing platforms with 5G modems and AMOLED displays above 6.5 inches. Maharashtra and Karnataka absorb premium 5G handset volumes as urban income growth supports flagship-tier purchases; BIS compulsory registration for SAR compliance and WPC certification for cellular bands compress launch windows for unregistered imports.
- Televisions:Panel sizes from 32-inch HD to 65-inch 4K UHD with smart OS integration. Tier-two city households in Surat and Indore accelerate connected TV upgrades as fiber broadband penetration enables streaming; CEA star-rating mandates for energy consumption reshape sourcing toward efficient LED backlights.
- Laptops:Clamshell and convertible form factors spanning 11.6-inch education models to 15.6-inch professional workstations.
- Wearables:Wrist-worn fitness trackers and smartwatches with biometric sensors and Bluetooth 5.0 connectivity.
Volume placements concentrate in smartphones; the faster expansion belongs to wearables.
Brand:
Brand positioning stratifies across cost tiers that map to manufacturing origin and certification burden.
- Samsung:Vertically integrated Korean conglomerate with Noida manufacturing campus supplying northern and western India. Domestic assembly insulates against BIS registration delays and DGFT tariff volatility on finished goods.
- Xiaomi:Chinese brand with Sri City and Greater Noida assembly partnerships. Aggressive online-first pricing captures price-sensitive millennials; PLI scheme participation drives component localization for display modules.
- LG:Korean diversified electronics manufacturer with inverter compressor technology leadership in cooling appliances.
- Sony:Japanese premium brand concentrated in audio, imaging, and television segments with limited India assembly footprint.
Domestic assembly concentrates with Samsung and Xiaomi; the steepest expansion trajectory belongs to Xiaomi's online channel penetration.
Distribution Channel:
Channel selection determines working capital intensity and after-service liability allocation.
- Online:Direct-to-consumer platforms and marketplace aggregators with UPI-enabled EMI at checkout. Metro millennials and students in Bengaluru and Hyderabad drive transaction density; return logistics and warranty fulfillment elevate operational complexity versus offline.
- Offline Retail:Exclusive brand stores and multi-brand outlets in tier-three towns. Haier and Samsung deploy dedicated storefronts to control merchandising and service turnaround; credit exposure to traditional distributors rises with working capital costs.
- E-commerce:Pure-play digital marketplaces with warehousing in tax-advantaged zones.
- Department Stores:Large-format retail anchors in Mumbai and Delhi with premium product showcases and extended warranty bundling.
Unit volumes concentrate in offline retail; the fastest share gains belong to online channels.
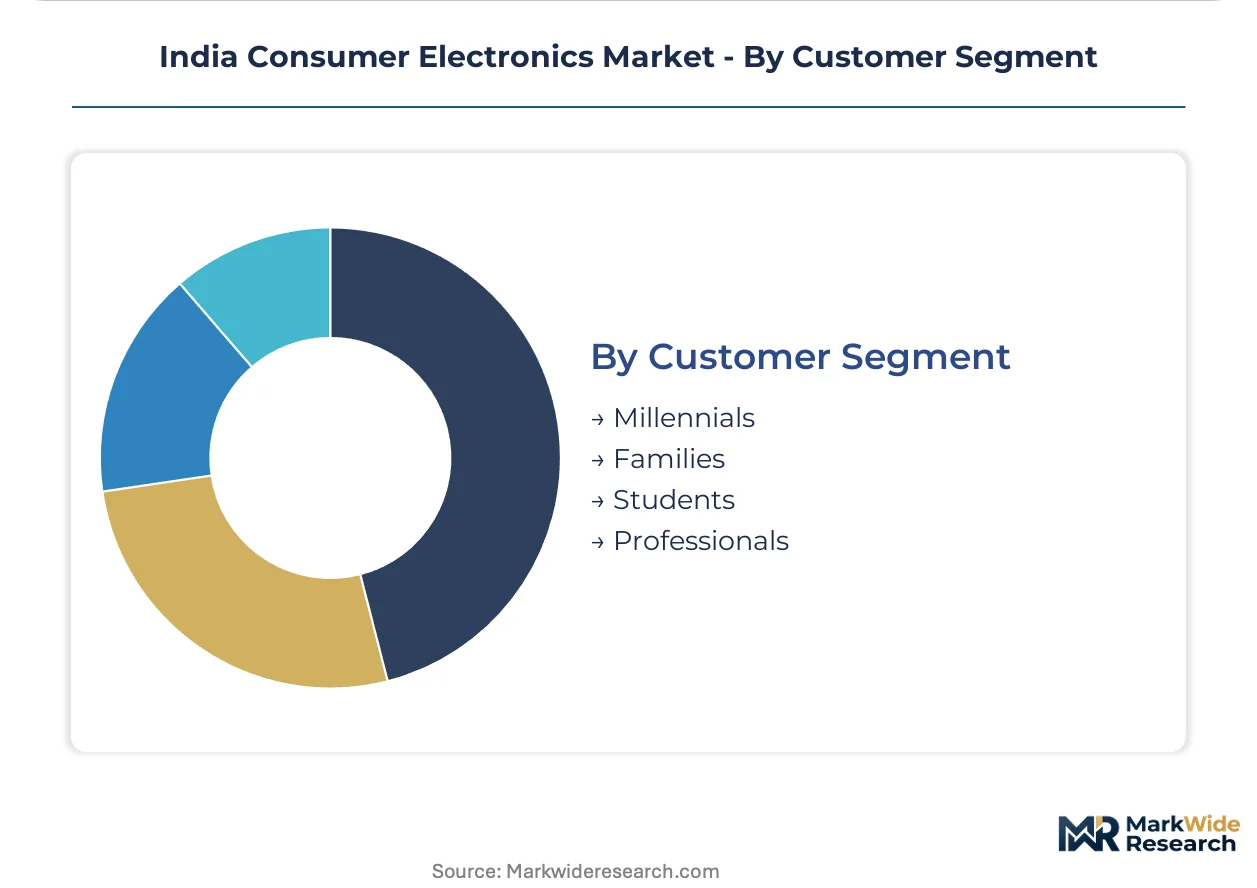
Customer Segment:
Demographic cohorts exhibit divergent upgrade cadences and financing preferences.
- Millennials:Digital-native consumers aged 25-40 prioritizing smartphone camera specifications and streaming-optimized televisions. UPI penetration enables instant purchase decisions; subscription fatigue limits appliance-as-a-service adoption relative to Gen Z.
- Families:Multi-generational households with refrigerator, washing machine, and television replacement cycles tied to festival-season promotions. Energy efficiency star ratings drive trade-in decisions; extended warranty purchases cluster in this segment.
- Students:Price-sensitive cohort concentrated in thin-and-light laptops and entry smartphones for remote learning. Education financing schemes and parental purchase authorization lengthen decision timelines.
- Professionals:Knowledge workers demanding premium ultrabooks, noise-canceling audio, and wearable productivity tools.
Purchase frequency concentrates with millennials; the expanding wallet share belongs to families upgrading connected appliances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PLI scheme incentives and BIS-approved testing infrastructure are concentrating assembly investment in Noida, Sri City, and Bengaluru export zones. These designated manufacturing corridors anchor component sourcing networks and accelerate certification timelines for smartphone and appliance brands.
Maharashtra
Mumbai and Pune metropolitan clusters absorb premium smartphone and television volumes as urban income growth supports flagship-tier purchases. The state's industrial policy extends capital subsidies to electronics manufacturing units in Chakan and Talegaon. Samsung Electronics operates a major distribution hub in Bhiwandi to service western India demand.
Karnataka
Bengaluru's technology workforce drives demand for professional-grade laptops and wearables with productivity integration. The Karnataka Industrial Areas Development Board allocates land parcels for electronics manufacturing in Devanahalli and Hoskote. Atomberg Technologies anchors fan and small appliance assembly in the state to serve southern markets.
Tamil Nadu
Chennai and Coimbatore manufacturing corridors specialize in television panel assembly and refrigerator compressor production. The Tamil Nadu Electronics Manufacturing Policy offers reimbursement of state GST for component suppliers locating in Sri City SEZ. LG Electronics and Haier Appliances India maintain captive sourcing relationships with local contract manufacturers.
Telangana
Hyderabad's startup ecosystem accelerates adoption of smart home devices and connected appliances among young professionals. The Telangana State Industrial Infrastructure Corporation develops electronics manufacturing clusters in Maheshwaram and Raviryal. Xiaomi's assembly partnerships in the region leverage the state's logistics connectivity to eastern and central India.
Gujarat
Surat and Ahmedabad exhibit underpenetrated demand for energy-efficient air conditioners and washing machines relative to income trajectories. The Gujarat Electronics Policy provides power tariff concessions and stamp duty exemptions for manufacturing units in Sanand and Changodar. Panasonic Corporation sources components through Ahmedabad-based distributors for northern India supply.
India Consumer Electronics Market Competitive Landscape
Top-tier vendors anchor domestic assembly scale, while mid-tier specialists compete through inverter technology and channel control in tier-three towns. The vendor base stratifies across Korean conglomerates with captive manufacturing, Chinese brands with online-first pricing, and Indian specialists with regional distribution depth. Three archetypes dominate: vertically integrated assemblers leveraging PLI scheme benefits, technology licensors differentiating through compressor and motor efficiency, and channel-heavy operators deploying exclusive brand stores. Competitive moves concentrate on BIS certification pre-positioning and component localization to compress import dependency.
Among Korean-origin conglomerates, Samsung Electronics and LG Electronics exemplify the integrated assembler archetype through Noida manufacturing scale and inverter technology leadership. Haier Appliances India occupies a position within the channel-control tier, sustaining market access via exclusive brand store networks in tier-three towns alongside traditional trade relationships. These three anchors illustrate how competitive positioning in the India Consumer Electronics Market depends on manufacturing origin, certification readiness, and distribution infrastructure depth rather than pricing alone.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Haier Appliances India |
| Samsung Electronics |
| V-Guard |
| Toshiba Corporation |
| LG Electronics |
| Havells India |
| Atomberg Technologies |
| Sony Corporation |
| Others |
Pricing and Supply Chain Analysis
Firmware engineering talent scarcity in Bengaluru and Hyderabad widens labor-cost differentials between premium smart appliance tiers and entry-level electronics, compressing margin spreads as assemblers compete for embedded systems capability.
Pricing Analysis
Short lead-time premiums dominate smartphone and wearables procurement, with brands paying markups for BIS pre-certified components versus accepting discounts on spot inventory subject to laboratory testing delays. Three-tier pricing structure across premium, standard, and economy levels separates flagship 5G handsets with GaN fast-charging from mid-tier models and entry-level feature phones. Pricing pressure stems from semiconductor input volatility as memory chip and display panel costs fluctuate with Taiwan and South Korea supply conditions. Students and price-sensitive rural first-time buyers exhibit highest price sensitivity; professionals purchasing productivity-integrated ultrabooks show lowest.
Supply Chain Analysis
Dual-sourcing requirements from Xiaomi and Samsung procurement teams mandate qualified suppliers across both Chinese and Vietnamese PCB assembly facilities, reducing single-source concentration risk. Component flows draw from China for battery cells and display modules, Taiwan for semiconductor wafers, and South Korea for memory chips. Raw material dependencies span lithium carbonate for cells, gallium nitride substrates for charging adapters, and rare earth elements for speaker magnets. Tariff exposure through DGFT adjustments on Chinese component imports presents structural supply chain risk. Distribution runs through Noida and Sri City export zone assembly hubs into exclusive brand stores and online marketplace fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as BIS certification backlogs and PLI scheme capital requirements force sub-scale assemblers toward exit or acquisition.
For Market Incumbents: To counter BIS testing bottlenecks that delay unregistered imports by four to eight weeks, Samsung and LG should deepen captive laboratory capacity in Noida and Sri City while accelerating component localization under PLI scheme extensions. Channel control through exclusive brand stores in tier-three towns insulates against credit exposure to traditional distributors as working capital costs rise. For New Entrants and Emerging Players: Appliance-as-a-service subscribers among Bengaluru and Hyderabad young professionals represent an underserved buyer archetype with recurring revenue attachment potential and lower upfront capital barriers. Tier-two city connected appliance demand in Surat, Indore, and Coimbatore offers penetrable white-space with income growth trajectories outpacing current penetration. Go-to-market execution should prioritize property aggregator partnerships bundling hardware into lease agreements over direct retail competition. For Investors and Strategic Acquirers: Re-rating potential sits with domestic contract manufacturers possessing BIS-approved testing facilities given GaN charging semiconductor consolidation and adapter supply chain consolidation around three qualified assemblers. Long-term viability through the forecast window favors operators with backward integration into display modules and camera modules under component PLI extension. The signal to watch is BIS compulsory registration scheme expansion into additional product categories as inflection indicator for certification-dependent margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Component Localization Under PLI Extension | Display module captive sourcing reduces DGFT tariff exposure for smartphone brands. |
| BIS Pre-Certification Laboratory Investment | In-house testing facilities in Noida and Sri City accelerate product launch timelines. |
| Tier-Two City Exclusive Brand Store Expansion | Haier's channel model in Surat and Indore captures underpenetrated connected appliance demand. |
| Health-Insurance Wearables Data Integration | Fitness tracker partnerships with private insurers create recurring revenue attachment models. |
| Appliance-as-a-Service Platform Development | Property aggregator bundling in Bengaluru and Hyderabad elevates after-service reliability as selection criterion. |
Research Methodology
Independent corroboration across primary interviews with electronics manufacturing executives, BIS certification consultants, and tier-two city distributor principals, alongside secondary validation through DGFT trade data, CEA efficiency labeling records, and PLI scheme disbursement disclosures, underwrites the qualitative findings. Bottom-up assembly capacity assessments and top-down consumer expenditure surveys triangulate market sizing across the analysis window.
Comparable-period anchoring to historical smartphone shipment trajectories and appliance replacement cycle data informs the projection horizon. Segmentation dimensions span product architecture, brand positioning tier, distribution channel intensity, and customer demographic cohort. CAGRs derive from trend extrapolation adjusted for regulatory inflection points. Forecast inputs incorporate BIS compulsory registration scheme expansion timelines and semiconductor supply elasticity assumptions.
Revisions become necessary when BIS testing backlogs extend beyond current laboratory capacity constraints or when DGFT tariff adjustments materially alter component import economics. Forecasts reflect documented assumptions regarding PLI scheme continuity and rural electrification penetration rates. A model refresh is warranted upon material change in CEA star-rating mandate enforcement intensity or health-insurance wearables data-sharing regulatory frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Ergonomic Mouse Market
Consumer Electronics
Kid's Wired Earphone and Headphone Market
Consumer Electronics
TV Mirror Market
Consumer Electronics
Apple Accessories Market
Consumer Electronics
Dual Screen Laptops Market
Consumer Electronics
Consumer Electronics Market
Consumer Electronics
Ultra HD Action Camera Market
Consumer Electronics
Global Used Smartphones Market
Consumer Electronics
Europe Cigarette Lighter Market
Consumer Electronics
Gaming Laptop Market
Consumer Electronics
Wet Wipes Market
Consumer Electronics
Soft Support Products Market
Consumer Electronics
Asia-Pacific Professional Audio-Visual Systems Market
Consumer Electronics
Stylus Pen Market
Consumer Electronics
Consumer Electronic Biometrics Market
Consumer Electronics
Used and Refurbished Smartphone Market