
 Japan Gaming Peripherals Market | 2026-2036
Japan Gaming Peripherals Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Gaming Peripherals Market Intelligence
Japan's Radio Law is pivoting the certification burden for wireless gaming peripherals, forcing entrants to absorb pre-market testing costs that favor established players with in-house compliance teams. Logitech G leverages its global regulatory infrastructure to navigate PSE and TELEC approvals with minimal friction. Razer sustains premium positioning through direct-to-consumer channels that bypass traditional retail markups. SteelSeries anchors its Japanese presence through localized esports sponsorships that reinforce brand equity among professional gamers.
Gaming peripherals encompass input and output devices engineered for interactive entertainment, typically featuring sub-1ms polling rates, mechanical switch actuation forces between 45-60g, and driver-level customization via proprietary firmware. Their primary purpose is reducing latency and enhancing tactile precision for competitive and immersive gameplay. Headsets and mechanical keyboards command the deepest margin pools within the product type dimension, while wireless technology is displacing wired alternatives among professional gamers who prioritize desk mobility. Esports athletes represent the fastest-growing user type as Japanese tournament circuits expand prize pools and institutional support.
METI's digital content promotion frameworks intersect with JIS standards for electromagnetic compatibility to shape product development roadmaps and market access protocols for peripheral manufacturers. The Consumer Affairs Agency enforces labeling requirements that affect packaging localization costs for imported brands. Stakeholders must monitor how Japan's evolving esports licensing regime alters procurement patterns among team organizations and training facilities.
Market Dynamics
Wireless technology is restructuring Japan's gaming peripherals competitive landscape, forcing manufacturers to absorb TELEC certification costs while repositioning product portfolios around latency benchmarks that professional esports circuits now mandate.
Growth Catalysts
- Institutional esports recognition:Japan's esports licensing regime is formalizing team procurement standards, creating dedicated hardware budgets for training facilities and tournament organizations.
- METI digital content frameworks:Industrial policy prioritization is channeling subsidy streams toward gaming hardware ecosystems, reducing R&D cost burdens for domestic peripheral developers.
- Mechanical switch innovation:Optical actuation technologies are penetrating the enthusiast segment, with sub-1ms response specifications becoming baseline expectations for competitive gamers in Tokyo and Osaka.
Market Restraints
- Radio Law compliance costs:TELEC and PSE pre-market testing requirements impose fixed cost barriers that favor established players with captive certification infrastructure.
- Specialty retail concentration:Demand clustering in Akihabara and Nipponbashi districts creates geographic dependency, exposing vendors to localized demand shocks and rent inflation.
- Wireless latency floors:Physical transmission constraints limit polling rate improvements beyond 8KHz, capping performance differentiation for premium product tiers.
Strategic Opportunities
- Regional city expansion:Fukuoka and Sapporo gaming café densities are rising faster than Tokyo, creating whitespace for peripheral brands to establish early retail partnerships.
- Cloud gaming integration:Edge computing infrastructure investments are enabling low-latency streaming peripherals that decouple hardware performance from local processing power.
- JIS electromagnetic compatibility harmonization:Standard alignment with international certification schemes is reducing re-engineering costs for export-oriented Japanese manufacturers.
Industry Challenges
- Firmware engineering scarcity:Embedded systems talent capable of optimizing driver-level customization pipelines commands premium compensation, constraining mid-tier vendor R&D scaling.
- Packaging localization complexity:Consumer Affairs Agency labeling mandates require Japanese-language documentation redesigns that extend product launch timelines for import-dependent brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Gaming Peripherals Market |
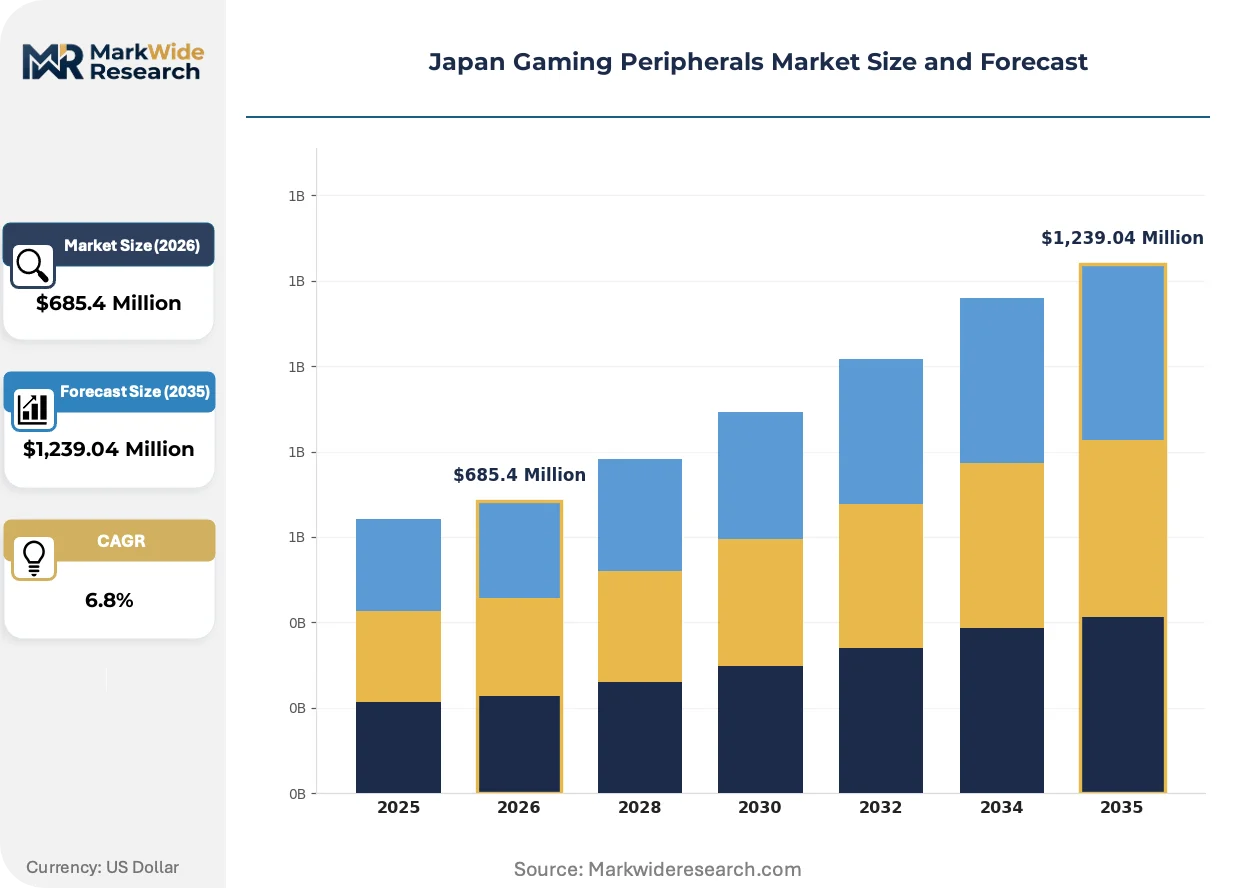
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Keyboards, Mice, Headsets, Controllers Technology: Wired, Wireless, Mechanical, Optical User Type: Casual Gamers, Professional Gamers, Streamers, Esports Athletes Distribution Channel: Online Retail, Specialty Stores, Mass Merchants, Direct Sales |
| Companies Covered | SteelSeries, HyperX, Razer, ROCCAT, Mad Catz, Logitech G, Turtle Beach, Cooler Master, Corsair, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Gaming Peripherals Market Strategic Shifts & Innovations
Three distinct vectors are reconfiguring Japan's gaming peripherals value chain: wireless transmission standards, regulatory compliance automation, and direct-to-consumer channel migration. Each trend is compressing traditional margin structures while opening new competitive terrain.
Optical mechanical switches are expanding into the professional esports segment, replacing traditional contact-based actuation with infrared beam interruption mechanisms. Japanese tournament circuits are adopting these specifications as baseline equipment standards. This technology is expanding into mid-tier consumer keyboards, compressing the price-performance gap between enthusiast and entry-level product categories.
METI's electromagnetic compatibility coordination with JIS standards is streamlining certification pathways for peripheral manufacturers. The policy convergence reduces redundant testing cycles for products targeting both domestic and export markets. Wireless headset manufacturers are responding fastest, re-engineering RF modules to satisfy unified technical specifications rather than maintaining separate regional SKUs.
Esports athletes are consolidating purchase authority within team organizations, shifting procurement from individual retail transactions to institutional volume agreements. Specialty distributors in Akihabara are losing transaction share to manufacturer-direct B2B portals. This concentration is most visible in Tokyo's professional training facilities, where hardware standardization across rosters now dominates equipment selection criteria.
Japan Gaming Peripherals Market Segmentation
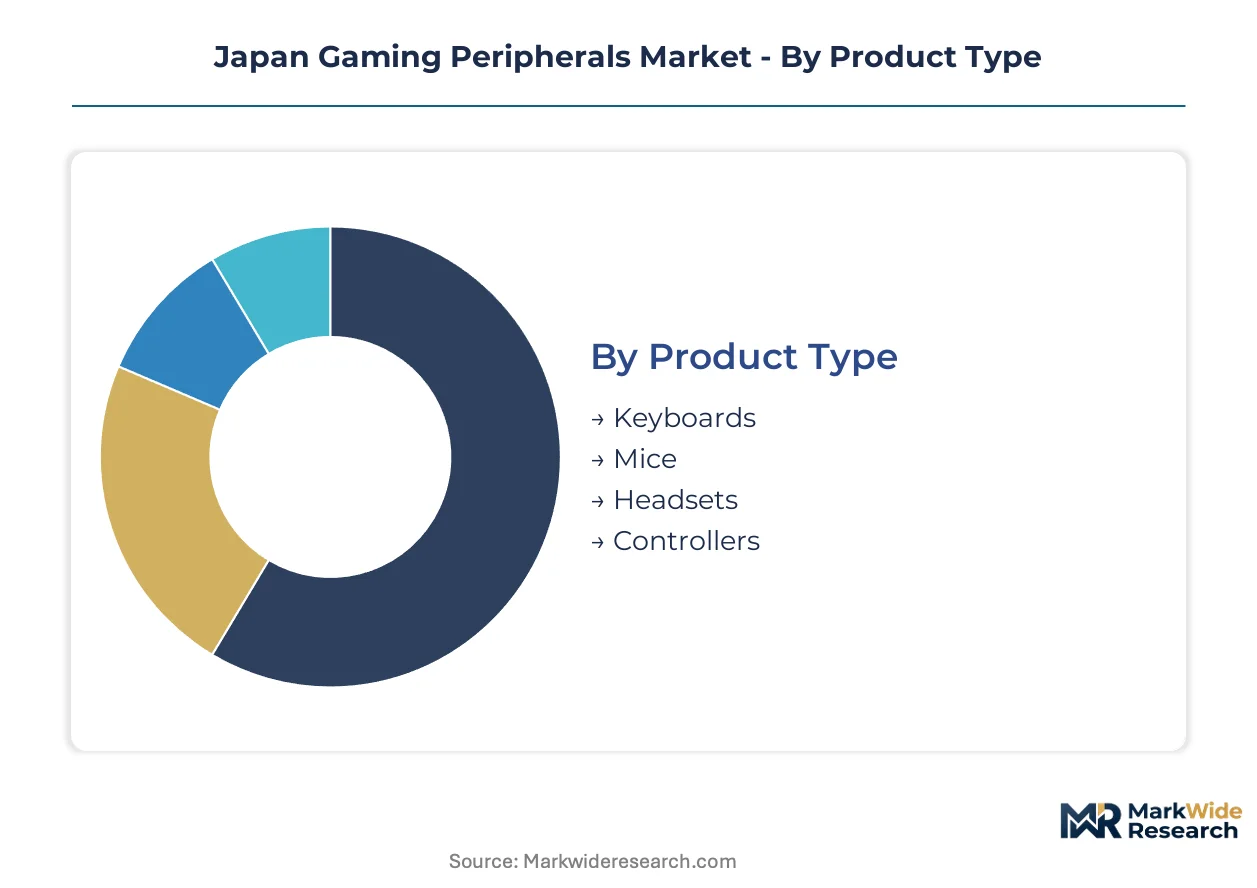
Segmentation in Japan's gaming peripherals market reveals how purchasing authority concentrates among professional users while technology choices diverge across latency-sensitive and mobility-prioritized applications. Understanding these splits enables vendors to align certification investments and channel strategies with actual buyer economics.
Product Type:
Purchase decisions in this category hinge on margin depth and replacement frequency, with peripherals exhibiting fundamentally different lifecycle economics.
- Keyboards:Mechanical and optical switch variants dominate enthusiast procurement, with sub-1ms polling specifications now baseline for Tokyo and Osaka competitive circuits. METI's digital content subsidies reduce R&D burdens for domestic switch manufacturers targeting this segment.
- Headsets:Wireless RF and low-latency Bluetooth configurations capture the deepest margin pools as esports teams standardize audio equipment across training rosters. TELEC certification costs for wireless modules favor established players with captive testing infrastructure.
- Mice:Optical sensor precision and weight reduction drive enthusiast selection criteria.
- Controllers:Console compatibility and haptic feedback specifications anchor purchasing for casual segments.
Headsets lead on scale; keyboards lead on momentum as optical actuation penetrates professional tiers.
Technology:
Cost tier stratification determines adoption sequencing, with premium wireless commanding price multiples over wired alternatives while mechanical maintains enthusiast loyalty.
- Wireless:2.4GHz proprietary protocols and Bluetooth LE implementations displace wired alternatives among professional gamers prioritizing desk mobility. Radio Law compliance costs create fixed barriers that consolidate market share among vendors with in-house TELEC certification teams.
- Mechanical:Contact-based and optical switch variants retain dominance in typing-intensive applications where tactile feedback outweighs raw speed. Japanese tournament circuits are adopting optical mechanical specifications as baseline equipment standards.
- Wired:USB-C and braided cable configurations persist in budget-conscious segments.
- Optical:Infrared beam interruption mechanisms are expanding from enthusiast into mid-tier categories.
Mechanical leads on scale; wireless leads on momentum as latency benchmarks converge with professional requirements.
User Type:
Volume concentration varies dramatically across customer types, with institutional procurement patterns diverging sharply from individual retail transactions.
- Esports Athletes:Team organizations now control hardware procurement through standardized volume agreements, bypassing traditional Akihabara retail channels. Japan's formalizing esports licensing regime is creating dedicated equipment budgets for training facilities and tournament organizations.
- Professional Gamers:Individual competitors with sponsorship arrangements drive premium peripheral adoption through direct-to-consumer manufacturer relationships. These users prioritize sub-1ms latency specifications and driver-level customization via proprietary firmware.
- Casual Gamers:Price-sensitive consumers purchasing through mass merchant and online retail channels.
- Streamers:Content creators balancing aesthetic customization with broadcast-grade audio-visual performance.
Casual gamers lead on scale; esports athletes lead on momentum as institutional recognition formalizes procurement authority.
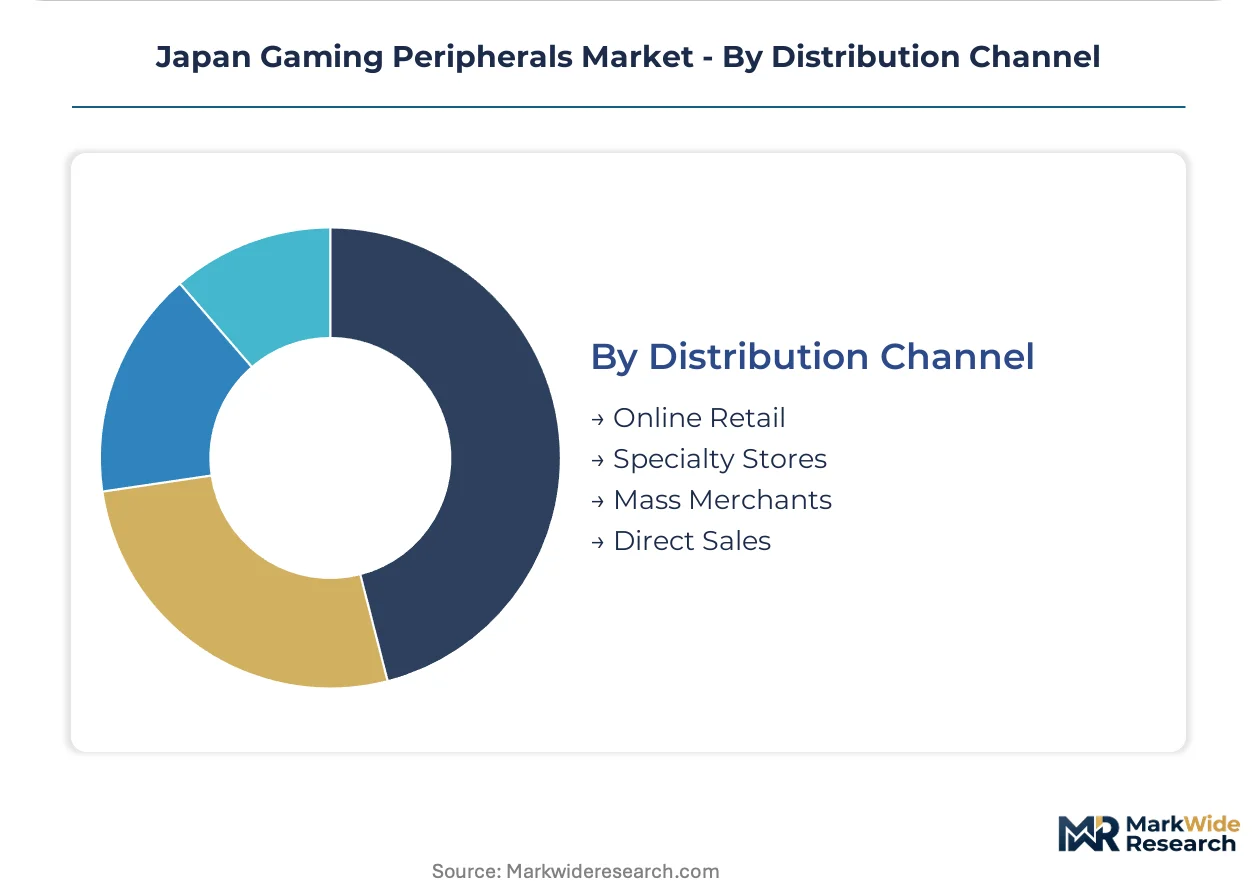
Distribution Channel:
Geographic clustering shapes channel effectiveness, with Tokyo and Osaka specialty retail anchoring premium positioning while direct sales capture institutional volume.
- Specialty Stores:Akihabara and Nipponbashi districts concentrate enthusiast demand and anchor premium brand positioning through hands-on product demonstration. Rent inflation and localized demand shocks expose vendors to geographic dependency risks.
- Direct Sales:Manufacturer B2B portals are displacing traditional distributors as esports teams consolidate procurement through institutional volume agreements. This channel captures the highest margins by eliminating retail markups.
- Online Retail:Amazon Japan and domestic e-commerce platforms serve price-comparison shoppers in secondary cities.
- Mass Merchants:Bic Camera and Yodobashi Camera chains reach casual gamers through bundled promotions.
Specialty stores lead on scale; direct sales leads on momentum as team procurement centralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's embedded systems engineers and firmware developers concentrate in the Greater Tokyo and Osaka metropolitan corridors, anchoring peripheral innovation clusters that feed domestic tournament circuits and export manufacturing.
Kanto/Tokyo
Esports training facilities and professional team headquarters drive concentrated hardware procurement in Akihabara and Shibuya districts. METI's digital content subsidies flow to peripheral developers headquartered in this region. Tokyo's specialty retail channels anchor premium brand positioning through hands-on product demonstration and immediate technical support.
Kansai/Osaka
Nipponbashi's electronics district sustains parallel demand concentration with lower commercial rents than Tokyo. Osaka-based gaming café chains are expanding faster than national averages, creating institutional volume opportunities. Local distributors are consolidating procurement relationships with esports organizations across western Japan.
Chubu/Nagoya
Manufacturing engineering talent from automotive and precision equipment sectors transfers into peripheral production facilities. JIS standards harmonization efforts involve Nagoya-based testing laboratories certifying electromagnetic compatibility. Industrial policy channels R&D tax incentives toward optical switch development programs.
Kyushu
Fukuoka's gaming café density growth outpaces Tokyo on a percentage basis, creating whitespace for early retail partnerships. Regional esports tournaments are formalizing equipment standardization requirements that drive team procurement decisions. Local government economic development offices are recruiting peripheral distributors to establish regional logistics hubs.
Hokkaido
Sapporo's winter tourism economy supports seasonal esports events that create temporary demand spikes for rental and retail peripheral sales. Cold climate conditions influence product durability specifications for regional tournament organizers. Limited specialty retail presence channels demand toward online platforms and direct manufacturer relationships.
Japan Gaming Peripherals Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across Japan's gaming peripherals sector, creating a tiered structure where scale advantages intersect with agility premiums. The vendor base clusters around three strategic archetypes: global peripheral brands with captive certification infrastructure, domestic electronics conglomerates leveraging manufacturing scale, and esports-native specialists built around tournament sponsorship relationships. Competitive dynamics center on M&A activity consolidating distribution networks and strategic partnerships securing exclusive team equipment agreements.
Among global peripheral specialists, Logitech G, Razer, and SteelSeries occupy distinct positioning vectors within the Japanese market. Logitech G represents the diversified technology conglomerate archetype with established regulatory navigation capabilities. Razer exemplifies the esports-native specialist model built around direct-to-consumer channel penetration. SteelSeries anchors the tournament-sponsorship-driven positioning tier through localized professional gaming relationships. Each occupies a definable competitive space without direct functional overlap in procurement channels or user segmentation.
| Leading Market Players |
|---|
| SteelSeries |
| HyperX |
| Razer |
| ROCCAT |
| Mad Catz |
| Logitech G |
| Turtle Beach |
| Cooler Master |
| Corsair |
| Others |
Cost & Logistics Intelligence
Optical mechanical switch adoption is compressing cost curves while concentrating procurement leverage among Japanese esports organizations with volume-standardization authority. TELEC certification requirements for wireless modules simultaneously inflate fixed costs and reward vendors with captive testing infrastructure, reshaping margin distribution across premium and mid-tier product categories.
Pricing Analysis
Bundled team equipment agreements versus unbundled individual retail purchases split pricing power across Japan's gaming peripherals market. Three-tier pricing structure across premium, standard, and economy levels reflects TELEC certification grade and optical switch performance tier as primary differentiation drivers. Cost compression in wireless headsets is intensifying because Radio Law compliance costs disproportionately burden import-dependent brands without localized testing facilities. Casual gamers purchasing through mass merchants exhibit highest price sensitivity, while esports team procurement officers prioritize latency specifications over per-unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Chinese optical sensor foundries and Taiwanese RF module manufacturers supplying Japanese peripheral assemblers. Production draws from China, Taiwan, and South Korea for sensor arrays, switch mechanisms, and wireless transmission components. Tariff exposure on Chinese-sourced optical actuation hardware threatens margin stability for domestic brands without alternative supplier qualifications. Distribution runs through Akihabara and Nipponbashi specialty retail for premium positioning, with direct B2B portals capturing institutional esports team volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's gaming peripherals market functions as a stable compounder, with METI's digital content subsidies and formalizing esports licensing creating predictable institutional demand expansion.
For Market Incumbents: Hedge against firmware engineering talent scarcity by acquiring embedded systems specialists in Greater Tokyo and Osaka corridors. Build backward integration into optical switch manufacturing to reduce dependency on Chinese component suppliers and defend margin position against Radio Law compliance cost inflation. For New Entrants and Emerging Players: The 8,000-15,000 yen price-point gap between premium wireless headsets and economy wired alternatives offers the most penetrable entry corridor. Target Fukuoka and Sapporo gaming café chains before incumbent specialty retail networks establish regional presence, leveraging direct-to-consumer digital marketing to bypass Akihabara rent premiums. For Investors and Strategic Acquirers: Valuations sit cheapest among domestic electronics conglomerates with dormant gaming peripheral divisions and existing JIS certification capabilities. Five-to-ten year viability favors targets with optical mechanical switch IP and established METI subsidy relationships. Watch for esports licensing regime formalization as inflection signal accelerating institutional procurement centralization.| Strategic Initiative | Industry Significance |
|---|---|
| Optical Switch Manufacturing Scale-Up | Captures METI R&D subsidies while reducing Chinese component dependency. |
| TELEC Certification Infrastructure Investment | Creates regulatory moat against import-dependent competitors lacking in-house testing. |
| Direct-to-Consumer B2B Portal Launch | Bypasses Akihabara retail markups and captures esports team procurement centralization. |
| Regional City Distribution Partnership | Establishes first-mover positioning in Fukuoka and Sapporo gaming café expansion zones. |
| Firmware Engineering Talent Acquisition | Secures scarce embedded systems capability for driver-level customization pipelines. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with esports team procurement officers, peripheral distributor account managers, METI digital content policy leads, and gaming café chain operators with secondary validation. Sources included METI subsidy disclosure records, TELEC certification databases, Consumer Affairs Agency labeling guidelines, and JIS electromagnetic compatibility standards documentation. Bottom-up demand modeling from individual user segments triangulated against top-down industrial policy expenditure tracking.
Segment-weighting approaches distributed value and volume across product type, technology configuration, user category, and distribution channel dimensions. CAGRs were derived from polynomial trend fitting against historical certification volume and esports tournament prize pool expansion rates. Forecast inputs incorporated METI digital content framework budget allocations and regional gaming café density trajectories across the projection horizon.
Caveats apply where METI subsidy program revisions, Radio Law certification requirement changes, or optical switch technology disruption could materially shift the outlook. Forecasts reflect assumptions about esports licensing formalization pace and wireless latency benchmark evolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
North America Gaming Accessories Market
Consumer Electronics
Latin America Consumer Electronics Market
Consumer Electronics
Chromebook Market
Consumer Electronics
Advanced Baby Monitors Market
Consumer Electronics
Europe Gaming Headset Market
Consumer Electronics
Mexico Smart TV Market
Consumer Electronics
UAE Consumer Electronics Market
Consumer Electronics
US Refurbished and Used Mobile Phones Market
Consumer Electronics
Baby Monitor Market
Consumer Electronics
India Consumer Electronics Market
Consumer Electronics
True Wireless Stereo Market
Consumer Electronics
Waterproof Bathroom TV Market
Consumer Electronics
Bluetooth Speakers Market
Consumer Electronics
Zipline Kits Market
Consumer Electronics
Noise Cancelling Headphones Market
Consumer Electronics
Gaming Mouse Market