
 Global Healthcare Cloud Based Analytics Market | 2026-2036
Global Healthcare Cloud Based Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Healthcare Cloud Based Analytics Market Foresight
Hospital systems and ambulatory care networks is rebalancing cloud analytics procurement toward platforms that unify electronic health records with real-time operational dashboards. Oracle leverages its Cerner acquisition to anchor clinical data integration pipelines across large health systems. Amazon Web Services competes through specialized health data lakes that sustain low-latency analytics for population health management. Microsoft dominates enterprise trust by extending Azure's compliance certifications to HIPAA and FDA 21 CFR Part 11 workloads.
Healthcare cloud based analytics comprises distributed computing architectures that process structured and unstructured health data through machine learning pipelines, typically requiring sub-second query response times for clinical decision support and petabyte-scale storage for longitudinal patient records. Its primary purpose is converting fragmented health data into actionable intelligence for care coordination, revenue cycle optimization, and predictive risk stratification. Clinical analytics leads solution type deployment as hospitals prioritize real-time patient monitoring and diagnostic decision support, while predictive analytics represents the fastest-expanding margin pool where vendors embed proprietary algorithms into subscription contracts. Hybrid cloud architectures capture growing preference among end users seeking to retain sensitive genomic and imaging data on-premises while bursting computational workloads to public infrastructure.
FDA's software as a medical device framework and HIPAA security rule enforcement by the Office for Civil Rights shape vendor product roadmaps and customer procurement criteria, compelling platform investments in audit trails, encryption standards, and access controls. The EU AI Act and GDPR cross-border data transfer requirements add compliance layers for multinational health systems operating across European and North American jurisdictions. Stakeholders must monitor how regulatory divergence between FDA algorithm validation requirements and EU risk-based AI classifications fragments vendor certification costs and go-to-market strategies.
Market Dynamics
Hospital procurement committees now mandate HIPAA-compliant audit trails and FDA-validated algorithm documentation before cloud analytics contracts exceed $5 million annually, compressing vendor qualification timelines and elevating compliance engineering to a core competitive discipline.
Growth Catalysts
- FDA software as a medical device framework:The guidance creates clear validation pathways for clinical decision support algorithms, reducing regulatory uncertainty for hospital buyers and accelerating procurement cycles for validated platforms.
- Integrated delivery networks:These consolidated health systems demand unified data lakes spanning dozens of hospitals, driving multi-year enterprise contracts that embed analytics into core operational infrastructure.
- Real-time operational dashboards:Perioperative and emergency department managers require sub-second latency for patient flow optimization, pulling cloud infrastructure investment toward edge-computing architectures.
Market Restraints
- Cross-border data transfer restrictions:GDPR Article 44 and Schrems II rulings block EU patient data from standard US cloud regions, forcing redundant infrastructure deployment and doubling compliance costs for multinational deployments.
- Genomic data residency requirements:National biobank regulations in Germany, France, and South Korea mandate on-premises storage for whole-genome sequences, limiting pure public cloud adoption for precision medicine workloads.
- Specialized health informatics talent:The intersection of clinical workflow knowledge, cloud architecture certification, and regulatory documentation expertise concentrates in Boston, San Francisco, and London, inflating implementation costs elsewhere.
Strategic Opportunities
- Brazil's unified health system digitization:ANVISA's accelerating software registration timelines and the Ministry of Health's $2 billion telemedicine expansion create first-mover advantages for Portuguese-language analytics platforms.
- Federated learning architectures:This technique trains algorithms across siloed hospital datasets without centralizing raw patient records, opening revenue models for privacy-preserving multi-site research contracts.
- Medicaid managed care organizations:These payers lack internal analytics capabilities but face state mandates for social determinants reporting, creating channel partnerships for cloud vendors with community health data integration.
Industry Challenges
- Cerner-Millennium to Epic migration cycles:Health systems switching electronic health record platforms face 18-24 month analytics blackout periods as data models rebuild, risking contract churn for cloud vendors.
- Algorithm bias audit protocols:Hospitals now require demographic performance stratification for FDA-cleared decision support tools, demanding documentation pipelines that most vendors have not constructed.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Healthcare Cloud Based Analytics Market |
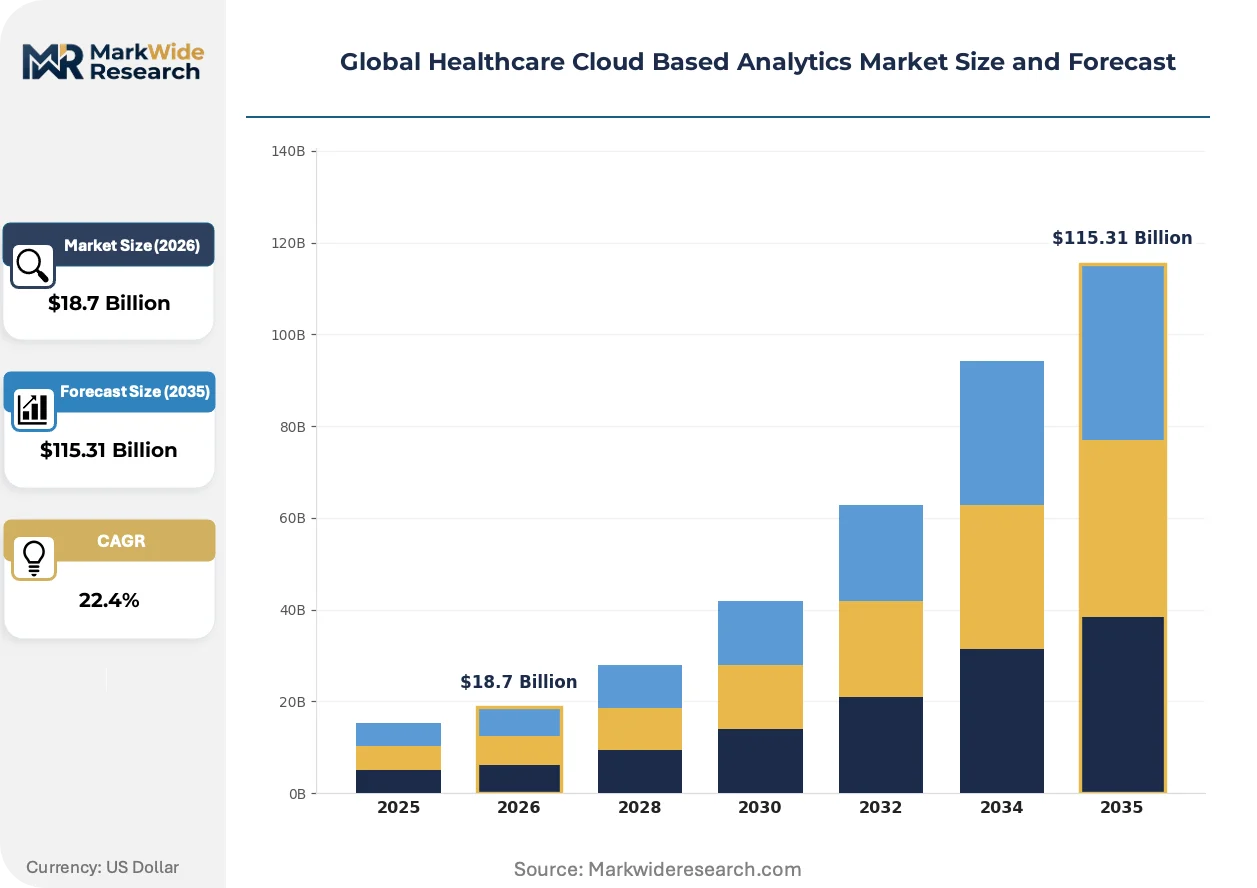
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $115.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Solution Type: Clinical Analytics, Operational Analytics, Financial Analytics, Population Health Analytics, Predictive Analytics End User: Hospitals, Diagnostic Laboratories, Ambulatory Care Centers, Research Institutes, Pharmacies Data Source: Electronic Health Records, Wearable Devices, Imaging Data, Administrative Claims, Genomic Data |
| Companies Covered | Oracle, Optum, Amazon Web Services, IBM, Microsoft, Health Catalyst, SAS Institute, Allscripts, Google Cloud Platform, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Healthcare Cloud Based Analytics Market Shifts & Advancements
Machine learning operations pipelines and synthetic data generation are compressing the gap between research-grade algorithms and production deployment, reshaping how cloud vendors structure subscription pricing and professional services.
Containerized microservices architectures are consolidating previously fragmented analytics modules into unified platforms. Academic medical centers in the United States now demand single-vendor accountability for data ingestion, model training, and visualization layers. This consolidation is compressing margins for point-solution vendors while rewarding full-stack providers with multi-year enterprise agreements.
The EU AI Act's risk-based classification system imposes conformity assessment requirements on clinical decision support tools that influence patient triage. Vendors must maintain technical documentation, human oversight protocols, and post-market monitoring systems for high-risk applications. German university hospitals are responding by centralizing procurement through shared compliance offices that pre-validate vendor submissions.
Subscription-based pricing for algorithm modules is displacing perpetual licensing for on-premises software across Nordic health systems. Denmark's five regional health authorities now coordinate joint tenders for population health analytics, consolidating purchasing power and demanding interoperability guarantees that lock out non-compliant vendors. This procurement concentration is visible most acutely in Sweden and Norway, where county council mergers have halved the number of independent contracting entities since 2020.
Global Healthcare Cloud Based Analytics Market Segmentation
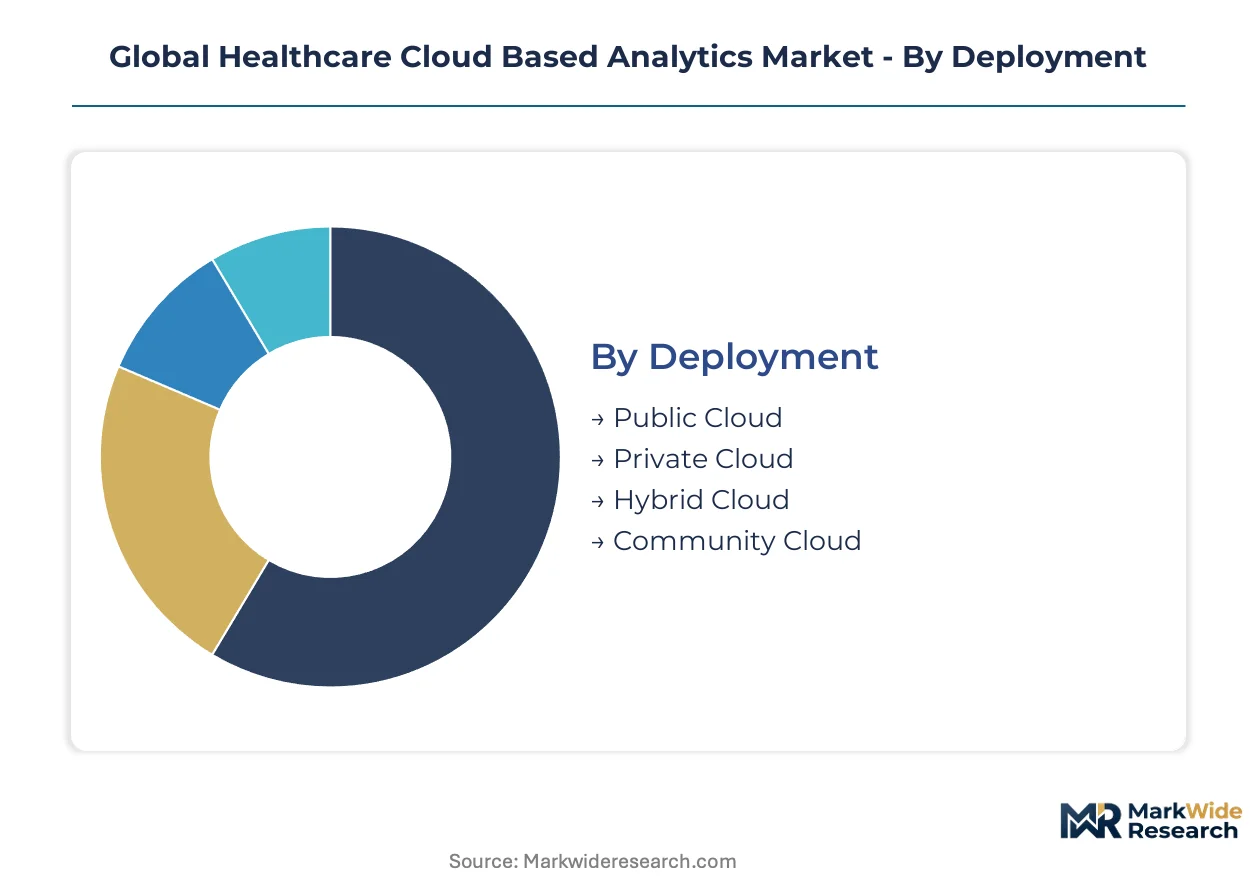
Cloud analytics procurement in healthcare follows distinct technical and organizational fault lines. Deployment architecture choices determine compliance posture and latency requirements, while solution type selection reflects whether buyers prioritize clinical workflows or operational efficiency.
Deployment:
Hospital infrastructure refresh cycles and EHR migration timelines are accelerating cloud architecture decisions, with procurement committees weighing data residency against computational elasticity.
- Public Cloud:Multi-tenant infrastructure delivers on-demand scaling for non-clinical workloads like revenue cycle analytics and supply chain optimization. Demand concentrates among ambulatory networks in the United States seeking to avoid capital expenditure on server hardware.
- Hybrid Cloud:Split architectures retain protected health information on-premises while bursting machine learning training to public infrastructure. Academic medical centers in Germany and the United States favor this model for genomic research pipelines constrained by national biobank regulations.
- Private Cloud:Dedicated single-tenant environments serving health systems with strict data sovereignty requirements or legacy mainframe dependencies.
- Community Cloud:Shared infrastructure among affiliated hospitals within integrated delivery networks, common in Nordic regional health authorities.
Public Cloud sits at the top of the volume ranking, with Hybrid Cloud climbing the fastest.
Solution Type:
Pricing stratification across solution modules reflects implementation complexity and regulatory validation burden rather than raw computational cost.
- Clinical Analytics:Real-time decision support tools processing EHR streams for diagnostic assistance and medication safety alerts. Hospital systems in the United States deploy these for perioperative monitoring and sepsis detection, driven by malpractice risk reduction and quality metrics tied to reimbursement.
- Predictive Analytics:Machine learning models forecasting patient deterioration, readmission probability, and disease progression. Integrated delivery networks in the United States embed proprietary algorithms into multi-year subscription contracts, with FDA software as a medical device validation becoming a procurement prerequisite.
- Operational Analytics:Patient flow optimization and emergency department throughput management tools.
- Financial Analytics:Revenue cycle management and value-based care contract performance monitoring.
- Population Health Analytics:Risk stratification across attributed patient panels for accountable care organizations.
Clinical Analytics commands the largest installed base, while Predictive Analytics expands most quickly as algorithm validation pathways mature.
End User:
Customer scale and technical sophistication create distinct purchasing patterns across provider types, from enterprise procurement committees to departmental credit card transactions.
- Hospitals:Enterprise-scale deployments spanning multiple service lines, with IT governance committees mandating HIPAA-compliant audit trails and FDA documentation for contracts exceeding five million dollars annually.
- Diagnostic Laboratories:High-throughput processing of imaging and pathology data with specialized requirements for DICOM compatibility and AI-assisted diagnostic workflows.
- Ambulatory Care Centers:Federated clinic networks prioritizing interoperability with hospital EHR systems and lightweight deployment models.
- Research Institutes:Federated learning architectures enabling multi-site algorithm training without centralizing raw patient records.
- Pharmacies:Medication adherence analytics and drug interaction screening integrated with dispensing systems.
Hospitals anchor procurement volume, with Research Institutes gaining share fastest through privacy-preserving multi-site contracts.
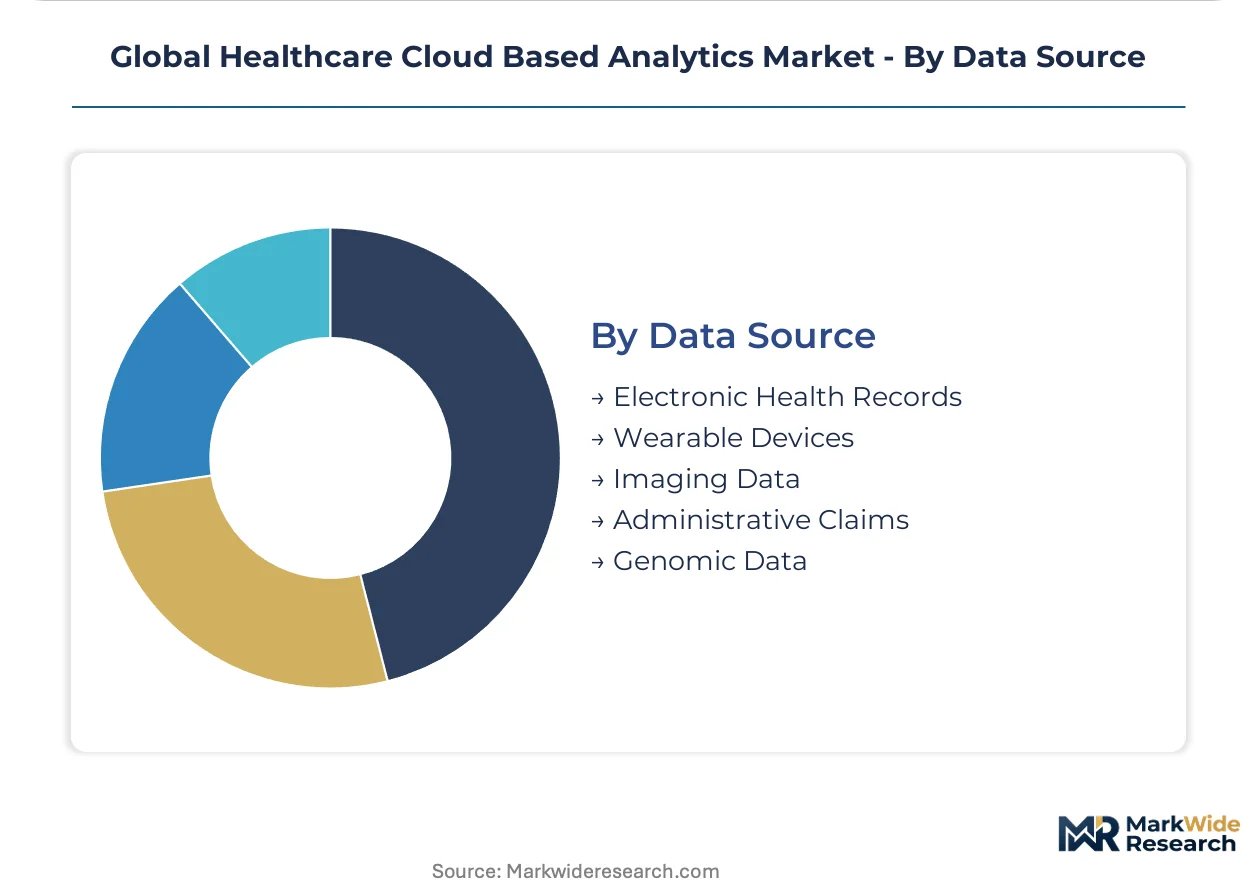
Data Source:
Data ingestion pipelines are consolidating around unified platforms as academic medical centers demand single-vendor accountability across ingestion, model training, and visualization layers.
- Electronic Health Records:Structured clinical documentation, medication orders, and problem lists forming the foundational data layer for most analytics applications. Epic and Cerner data models require specialized normalization pipelines, with migration between these platforms triggering 18-24 month analytics blackout periods.
- Imaging Data:DICOM-formatted radiology, pathology, and cardiology studies requiring petabyte-scale storage and GPU-accelerated processing for AI-assisted interpretation.
- Wearable Devices:Consumer and clinical-grade biosensors generating continuous physiological streams.
- Administrative Claims:Payer-submitted billing data supporting population health risk stratification and contract performance measurement.
- Genomic Data:Whole-genome and exome sequences with national biobank regulations in Germany, France, and South Korea mandating on-premises storage.
Electronic Health Records dominate data volume, with Imaging Data expanding most rapidly as AI diagnostic tools proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping vendor investment flows as compliance cost differentials between the United States and European Union widen. Cloud infrastructure providers now route clinical analytics workloads through jurisdictions with streamlined algorithm validation pathways.
United States
Integrated delivery networks and academic medical centers anchor procurement volume for predictive analytics platforms. FDA software as a medical device guidance creates validation clarity that accelerates hospital contracting cycles. The Boston and San Francisco corridors concentrate specialized health informatics talent, inflating implementation costs for deployments elsewhere.
Germany
University hospitals drive demand for hybrid cloud architectures that retain genomic data on-premises per national biobank regulations. The EU AI Act imposes conformity assessment requirements on clinical decision support tools, prompting centralized procurement through shared compliance offices. Bavarian medical centers lead deployment of federated learning architectures for multi-site research.
United Kingdom
NHS integrated care systems consolidate purchasing power through regional tenders for population health analytics. GDPR cross-border data transfer restrictions block patient data from standard US cloud regions, forcing redundant infrastructure deployment. London-based health tech clusters specialize in synthetic data generation for algorithm development.
Brazil
ANVISA's accelerating software registration timelines and the Ministry of Health's telemedicine expansion create first-mover advantages for Portuguese-language platforms. The unified health system digitization program drives demand for cloud-based operational dashboards. São Paulo anchors vendor establishment strategies for Latin American market entry.
Japan
PMDA guidance on AI-enabled medical devices shapes vendor product roadmaps for clinical decision support. METI initiatives promote data sharing across hospital networks while maintaining strict patient privacy protocols. The Tokyo-Osaka corridor concentrates deployments of real-time perioperative monitoring systems.
Global Healthcare Cloud Based Analytics Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors seek to bridge capability gaps in clinical workflow integration and regulatory documentation. The market structure concentrates around full-stack platform providers that unify data ingestion, model training, and visualization layers, compressing margins for point-solution specialists. Three archetypes define competitive positioning: enterprise cloud hyperscalers extending healthcare-specific compliance certifications, electronic health record incumbents leveraging installed base relationships, and independent analytics vendors differentiating through proprietary algorithm libraries. M&A activity and vertical integration into clinical data pipelines represent the dominant competitive moves.
Among enterprise cloud providers, Oracle, Amazon Web Services, and Microsoft exemplify distinct strategic postures. Oracle occupies a position anchored by its Cerner acquisition and clinical data integration pipelines across large health systems. Amazon Web Services represents the infrastructure-centric archetype, competing through specialized health data lakes that sustain low-latency analytics workloads. Microsoft sits within the enterprise trust tier, extending Azure's compliance certifications to HIPAA and FDA 21 CFR Part 11 workloads for risk-averse hospital procurement committees.
| Leading Market Players |
|---|
| Oracle |
| Optum |
| Amazon Web Services |
| IBM |
| Microsoft |
| Health Catalyst |
| SAS Institute |
| Allscripts |
| Google Cloud Platform |
| Others |
Supply & Pricing Matrix
Hospital procurement committees mandating FDA-validated algorithm documentation and HIPAA-compliant audit trails for contracts exceeding five million dollars annually are forcing cloud vendors to absorb specialized compliance engineering costs, compressing channel margins and elevating subscription pricing for validated platforms.
Pricing Analysis
Direct-to-health-system subscription contracts capture the dominant revenue channel, bypassing traditional distributor markups. Pricing stratifies across FDA-validated premium tiers, HIPAA-enhanced standard tiers, and non-clinical economy tiers for administrative workloads. Cost compression in the economy tier intensifies because ambulatory networks commoditize revenue cycle analytics. Integrated delivery networks exhibit the lowest price sensitivity due to embedded operational dependencies, while standalone diagnostic laboratories negotiate aggressively on per-study imaging analytics.
Supply Chain Analysis
Single-source vulnerability sits with hyperscale cloud infrastructure concentrated in the United States, Germany, and Japan. Compute hardware draws from Taiwan semiconductor foundries, enterprise storage arrays from South Korea, and specialized GPU accelerators from United States fabless designers. Tariff exposure on Chinese-manufactured networking equipment threatens edge-computing deployments for real-time clinical decision support. Distribution runs through direct enterprise sales organizations with embedded clinical workflow consultants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder where regulatory validation requirements create durable moats around incumbent platforms, sustaining recurring revenue visibility across multi-year hospital contracts.
For Market Incumbents: Cement platform stickiness by deepening Cerner and Epic integration pipelines, reducing analytics blackout risk during EHR migration cycles. Prioritize investment in algorithm bias audit documentation to preempt procurement committee scrutiny. Vertical control over federated learning infrastructure offers defensive positioning against privacy-preserving challengers. For New Entrants and Emerging Players: Launch via channel partnerships with Medicaid managed care organizations lacking internal analytics capabilities but facing state social determinants reporting mandates. Brazil's unified health system digitization presents the most penetrable geography for Portuguese-language platforms. Federated learning architectures enable revenue models without centralized data infrastructure. For Investors and Strategic Acquirers: Asymmetric upside sits with independent analytics vendors possessing proprietary algorithm libraries and FDA software as a medical device clearances. The five-to-ten year viability window favors full-stack platforms over point-solution specialists facing margin compression. Watch for EU AI Act conformity assessment bottlenecks as inflection indicators for vendor consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software as Medical Device Submission | Validation pathway clarity accelerates hospital procurement cycles for clinical decision support algorithms. |
| Hospital System Partnership | Integrated delivery network embedment secures multi-year enterprise contracts with switching cost protection. |
| Strategic Partnership | Alliances with EHR incumbents bridge clinical workflow integration gaps for standalone analytics vendors. |
| Geographic Expansion | Portuguese-language platform establishment captures Brazil's unified health system digitization program. |
| Acquisition of Specialist Firm | Federated learning capability purchases enable privacy-preserving multi-site research contract revenue. |
Research Methodology
Multiple input streams — hospital procurement committee interviews, cloud vendor product roadmap assessments, regulatory filing analysis, and GPO contract database review — were reconciled through bottom-up and top-down triangulation. Primary discussions engaged hospital CIOs, biomedical informatics directors, FDA regulatory consultants, and health system purchasing managers. Secondary validation drew from FDA 510(k) clearances, CMS Medicare reimbursement data, hospital procurement databases, and hyperscaler healthcare vertical disclosures.
Historical spending patterns were cross-referenced against expert panel inputs to anchor projection trajectories across the modeling period. Segmentation dimensions modeled encompass deployment architecture, solution type, end-user scale, and data source integration complexity. CAGRs were derived from algorithm validation pathway maturation curves and EHR migration cycle frequencies. Forecast inputs incorporated HIPAA enforcement intensity indices and EU AI Act implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Schrems II data transfer restriction escalations or genomic data residency regulation expansions. Assumptions underlying the analytical framework reflect current FDA guidance stability and integrated delivery network consolidation continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Speech and Voice Analytics Market
Analytics
Datacenter Analytics Market
Analytics
Europe Mobile Analytics Market
Analytics
Big Data Analytics in Automotive Market
Analytics
In-Memory Analytics Tools Market
Analytics
United States Geospatial Analytics Market
Analytics
Asia-Pacific HR Analytics Market
Analytics
Global Big Data Market
Analytics
Geospatial Imagery Analytics Market
Analytics
Europe Location Data Analytics Market
Analytics
Data Visualization Market
Analytics
Asia-Pacific Mobile Analytics Market
Analytics
Spend Analytics Software Market
Analytics
Global Hadoop Big Data Analytics Market
Analytics
Global Telecom Analytics Market
Analytics
App Analytics Tools Market