
 Geospatial Imagery Analytics Market | 2026-2036
Geospatial Imagery Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Geospatial Imagery Analytics Market Analysis
Market Context
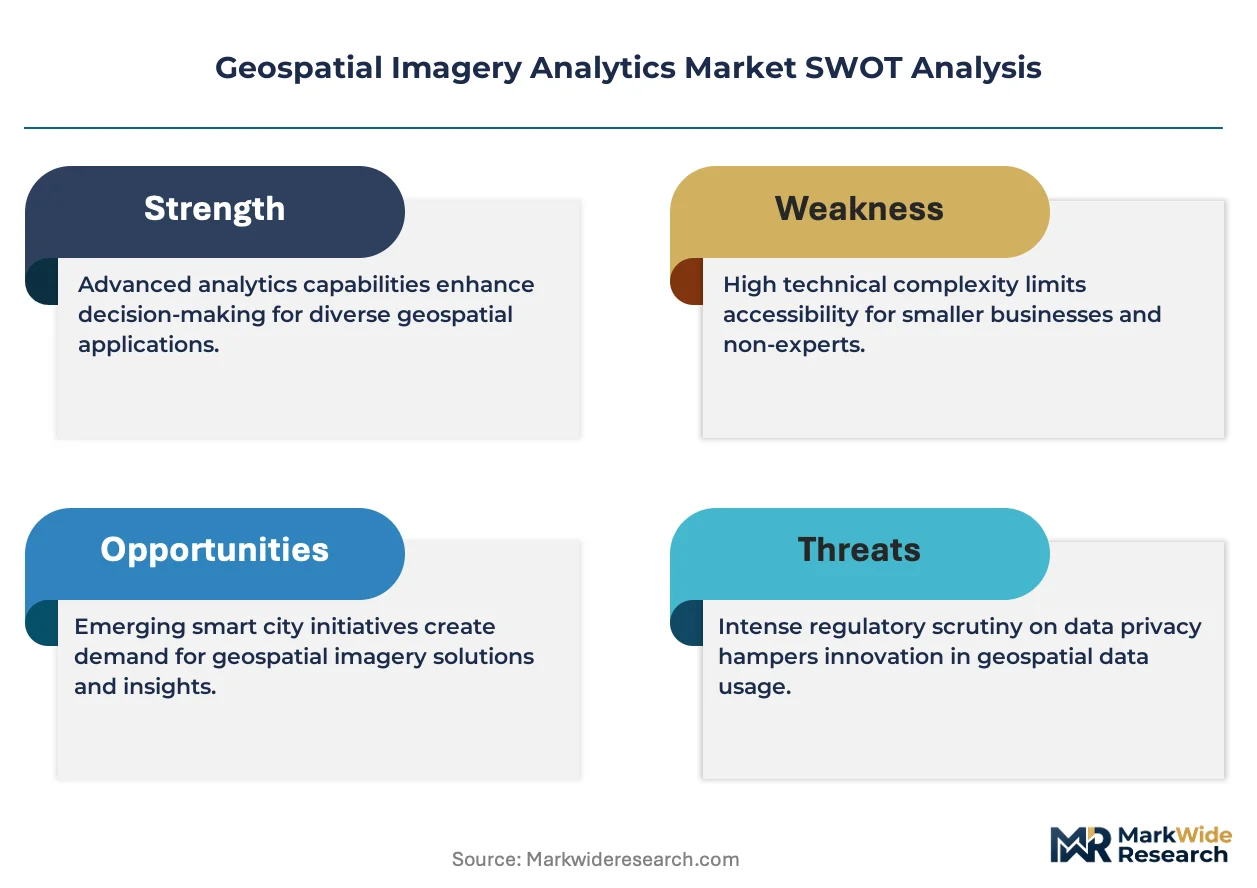
A shortage of geospatial data scientists and remote sensing specialists is redrawing competitive boundaries across the industry. Maxar Technologies sustains its position through captive satellite manufacturing and direct tasking control over high-resolution constellations. Planet Labs dominates daily coverage economics with its Dove and SkySat fleets, while Esri anchors the software layer through ArcGIS platform ubiquity in government and enterprise accounts.
Technical Definition and Segment Structure
Geospatial imagery analytics encompasses the algorithmic extraction of actionable intelligence from raster and point-cloud data captured via satellite, aerial, or unmanned platforms, typically processed through spectral indices, object detection models, and temporal change-detection pipelines to support mapping, monitoring, and predictive applications. Satellite imagery commands the largest revenue pool due to defense contracting scale and persistent orbital revisit capabilities, though LiDAR segments generate premium pricing in precision agriculture and infrastructure inspection where centimeter-level elevation accuracy is non-negotiable. Cloud-based deployment is displacing on-premise installations as hyperscale providers reduce storage and compute friction for petabyte-scale imagery archives.
Regulatory Environment and Outlook
The U.S. Department of Commerce's Bureau of Industry and Security regulates commercial remote sensing licensing, while the EU Copernicus programme mandates free and open data policies that reshape competitive dynamics for European analytics vendors. ISO 19115 metadata standards and the EU AI Act's risk classification for geospatial inference tools are tightening compliance requirements for automated feature extraction products. Stakeholders must monitor evolving export control thresholds for synthetic aperture radar and thermal infrared capabilities, as these dual-use designations determine market access for cross-border analytics services.
Market Dynamics
Defense procurement cycles and cloud infrastructure economics are compressing delivery timelines for geospatial intelligence, forcing analytics providers to rearchitect processing pipelines around hyperscale storage and GPU clusters rather than legacy on-premise workstations.
Growth Catalysts
- Copernicus open data mandates:The EU programme eliminates licensing friction for Sentinel imagery, enabling downstream vendors to build subscription analytics without capital-intensive satellite ownership.
- Hyperspectral sensor miniaturization:Reduced payload mass permits constellation operators to deploy 200+ band instruments for mineral identification and crop stress detection at commodity price points.
- Border surveillance procurement:The US National Geospatial-Intelligence Agency and allied defense ministries sustain multi-year tasking contracts for persistent monitoring of critical infrastructure and maritime chokepoints.
Market Restraints
- Launch capacity concentration:Dependence on SpaceX Falcon 9 and select Chinese Long March variants creates scheduling bottlenecks for constellation replenishment and orbital plane adjustments.
- ITAR-controlled component restrictions:US export regulations on synthetic aperture radar transmitters and cooled infrared focal planes fragment supply chains and delay non-US platform development.
- Cloud egress cost volatility:Petabyte-scale imagery archives face unpredictable retrieval fees from AWS, Azure, and Google Cloud, distorting unit economics for high-frequency analytics services.
Strategic Opportunities
- Indonesia maritime domain awareness:Archipelagic geography and limited coastal radar coverage create demand for satellite-derived vessel tracking and illegal fishing detection.
- EU AI Act compliance tooling:Risk classification requirements for automated geospatial inference create a software layer opportunity for explainable AI and audit trail documentation.
- Drone-to-satellite fusion:Integration of UAV-captured LiDAR with orbital multispectral data enables centimeter-accurate digital twins for utility corridor and rail maintenance applications.
Industry Challenges
- Remote sensing talent scarcity:Universities produce insufficient graduates combining spectral physics, machine learning, and cloud architecture competencies.
- Legacy GIS integration friction:Enterprise ArcGIS deployments resist API-based analytics insertion, forcing vendors to maintain parallel Python and JavaScript connector libraries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Geospatial Imagery Analytics Market |
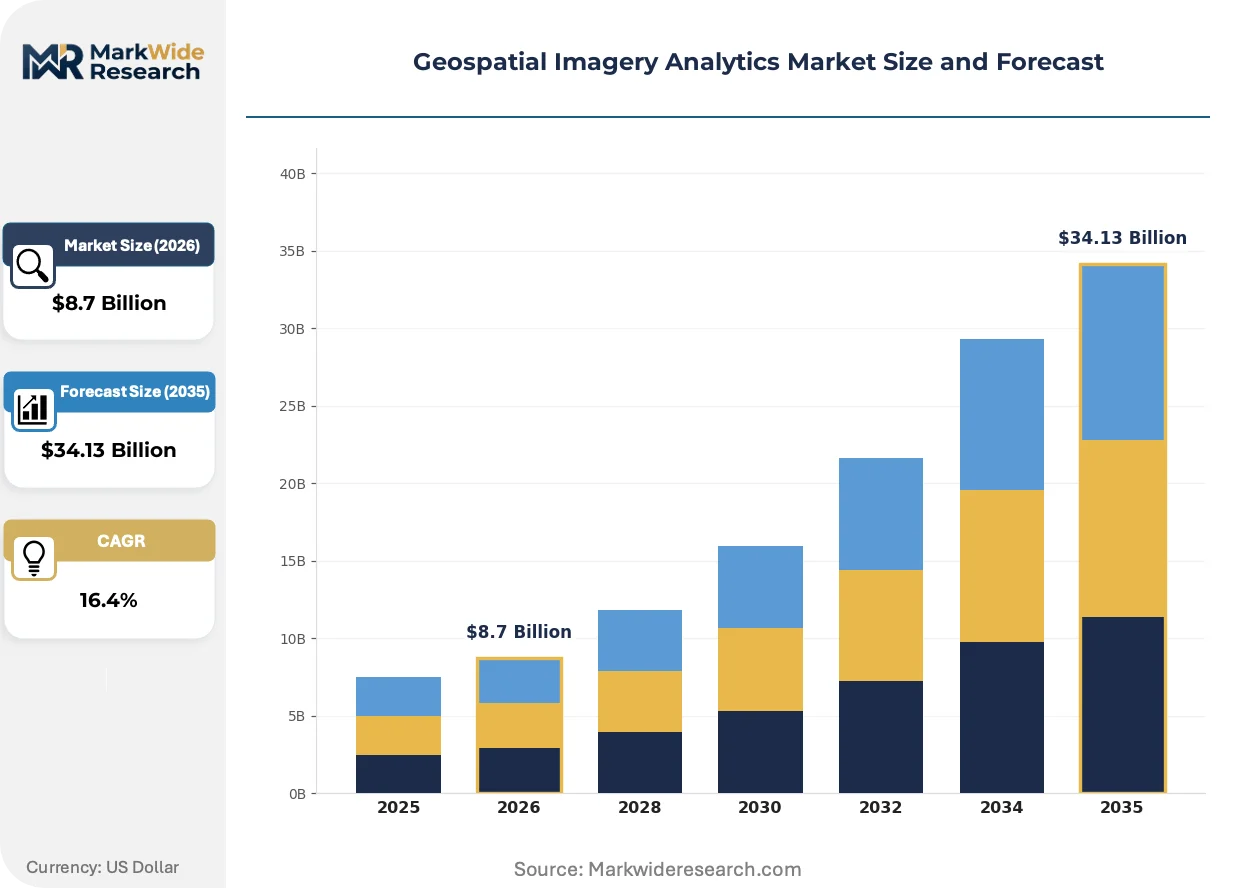
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Urban Planning, Environmental Monitoring, Disaster Management, Agriculture Technology: Satellite Imagery, Aerial Photography, LiDAR, Remote Sensing End User: Government Agencies, Construction Firms, Research Institutions, NGOs Deployment Model: On-Premise, Cloud-Based, Hybrid, SaaS |
| Companies Covered | Hexagon AB, Environmental Systems Research Institute, Inc. (Esri), Maxar Technologies Inc., Spire Global, Inc., BlackSky Technology Inc., Planet Labs PBC, Trimble Inc., MDA Ltd., Airbus Defence and Space SAS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Geospatial Imagery Analytics Market Emerging Trajectories
Federated learning architectures and edge-optimized neural networks are redistributing computational load across satellite, ground station, and client environments, collapsing the traditional centralized processing paradigm.
Foundation models trained on billion-pixel imagery corpora are bifurcating the analytics stack. These self-supervised architectures extract features without task-specific labels, enabling defense agencies and agricultural insurers to deploy custom detectors with minimal training data. The technology is compressing time-to-insight from weeks to hours for change detection and object classification workflows.
The EU AI Act's risk-based classification for geospatial inference tools is tightening compliance requirements for automated feature extraction products. Vendors must now document training data provenance and model drift metrics for high-risk applications including border surveillance and critical infrastructure monitoring. European analytics providers are responding by segregating EU-hosted inference endpoints from global operations to satisfy data residency obligations.
Subscription-based analytics procurement is displacing per-image licensing in enterprise accounts. Agricultural cooperatives and insurance underwriters now demand all-you-can-process contracts tied to acreage or asset counts rather than individual scene purchases. This shift is most visible in the US Corn Belt and Australian wheat belts, where seasonal monitoring requirements favor predictable operational expenditure over capital-intensive archive builds.
Geospatial Imagery Analytics Market Segmentation
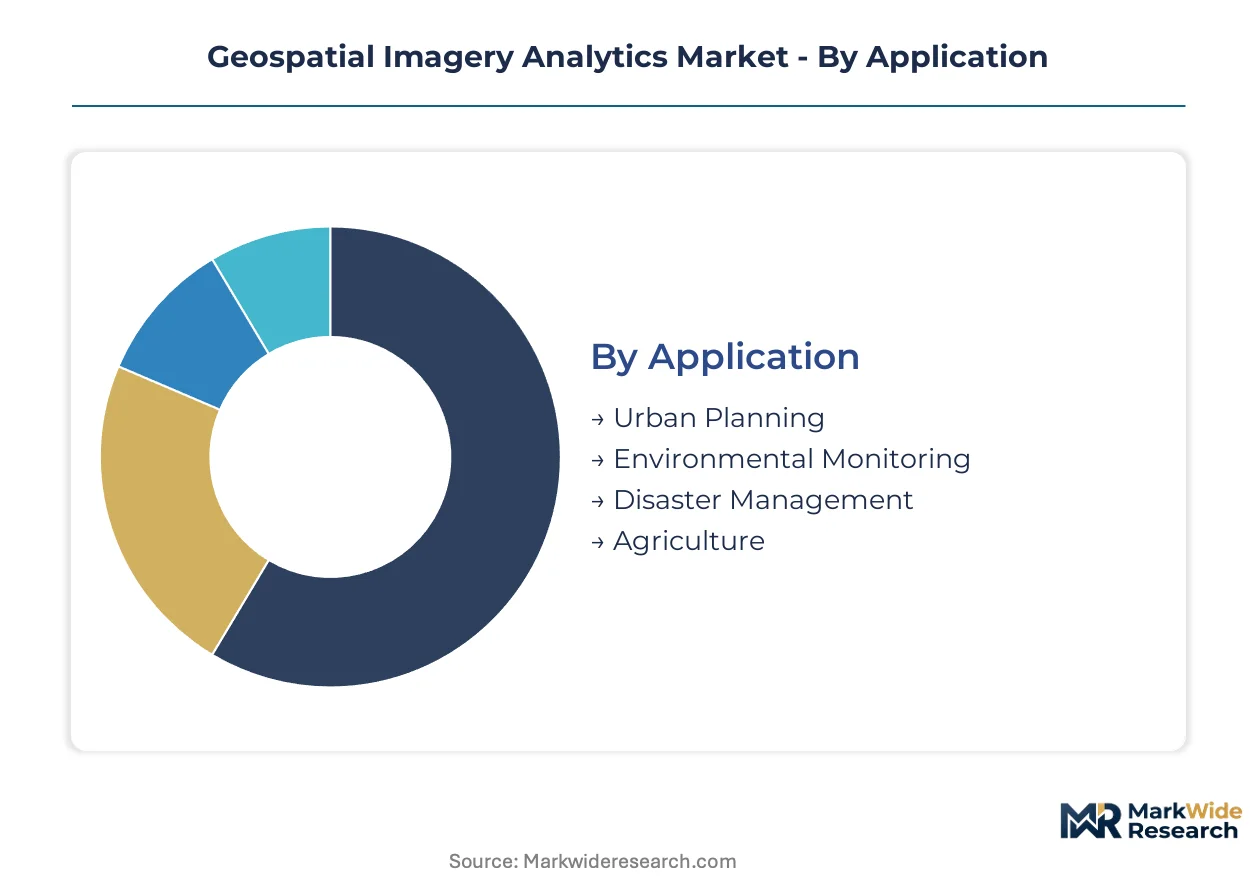
Segmentation in geospatial imagery analytics reveals how regulatory frameworks, procurement patterns, and infrastructure economics allocate value across distinct customer workflows and data sources. Each dimension exposes different competitive barriers and margin structures.
Application:
EU AI Act risk classifications and national security procurement rules create divergent compliance burdens across use cases.
- Urban Planning:Municipal zoning authorities leverage high-resolution orthomosaics for informal settlement mapping and infrastructure density analysis. German cities including Berlin and Munich mandate Copernicus-derived land cover data for statutory development plans, driving standardization around 10-meter resolution baselines.
- Environmental Monitoring:Spectral indices tracking deforestation, water quality, and carbon sequestration dominate subscription analytics procurement. Brazil's INPE and Indonesia's LAPAN operate persistent monitoring systems for Amazon and peatland protection, creating demand for automated change-detection pipelines.
- Disaster Management:FEMA and analogous agencies require rapid post-event damage assessment.
- Agriculture:Crop yield prediction and precision irrigation scheduling concentrate in US Corn Belt and Australian wheat belts.
Established volume favors Urban Planning; emerging adoption favors Environmental Monitoring.
Technology:
Cost tiers separate capital-intensive orbital assets from flexible aerial platforms.
- Satellite Imagery:Defense tasking contracts and persistent revisit capabilities sustain premium pricing for sub-meter optical and synthetic aperture radar data. US National Geospatial-Intelligence Agency multi-year agreements anchor revenue pools, while Copernicus open data policies commoditize 10-meter multispectral baselines.
- LiDAR:Centimeter-level elevation accuracy commands premium pricing in utility corridor mapping and rail maintenance where drone-mounted sensors fuse with orbital data.
- Aerial Photography:Manned aircraft deliver on-demand high-resolution capture for cadastral updates.
- Remote Sensing:Hyperspectral and thermal infrared sensors expand mineral identification and crop stress detection.
Defense procurement concentrates in Satellite Imagery; infrastructure digitization expands LiDAR fastest.
End User:
Customer type determines contracting mechanisms and data residency requirements.
- Government Agencies:Sovereign tasking priorities and classified processing environments dominate defense and intelligence procurement. US, UK, and Australian defense ministries sustain multi-year satellite access agreements with direct constellation control provisions.
- Construction Firms:Engineering-grade topographic surveys and progress monitoring drive drone-to-satellite fusion adoption.
- Research Institutions:Academic access programs lower licensing friction for climate and biodiversity studies.
- NGOs:Humanitarian applications prioritize open data streams and transparent methodology.
Contract value concentrates in Government Agencies; subscription flexibility climbs fastest in Construction Firms.
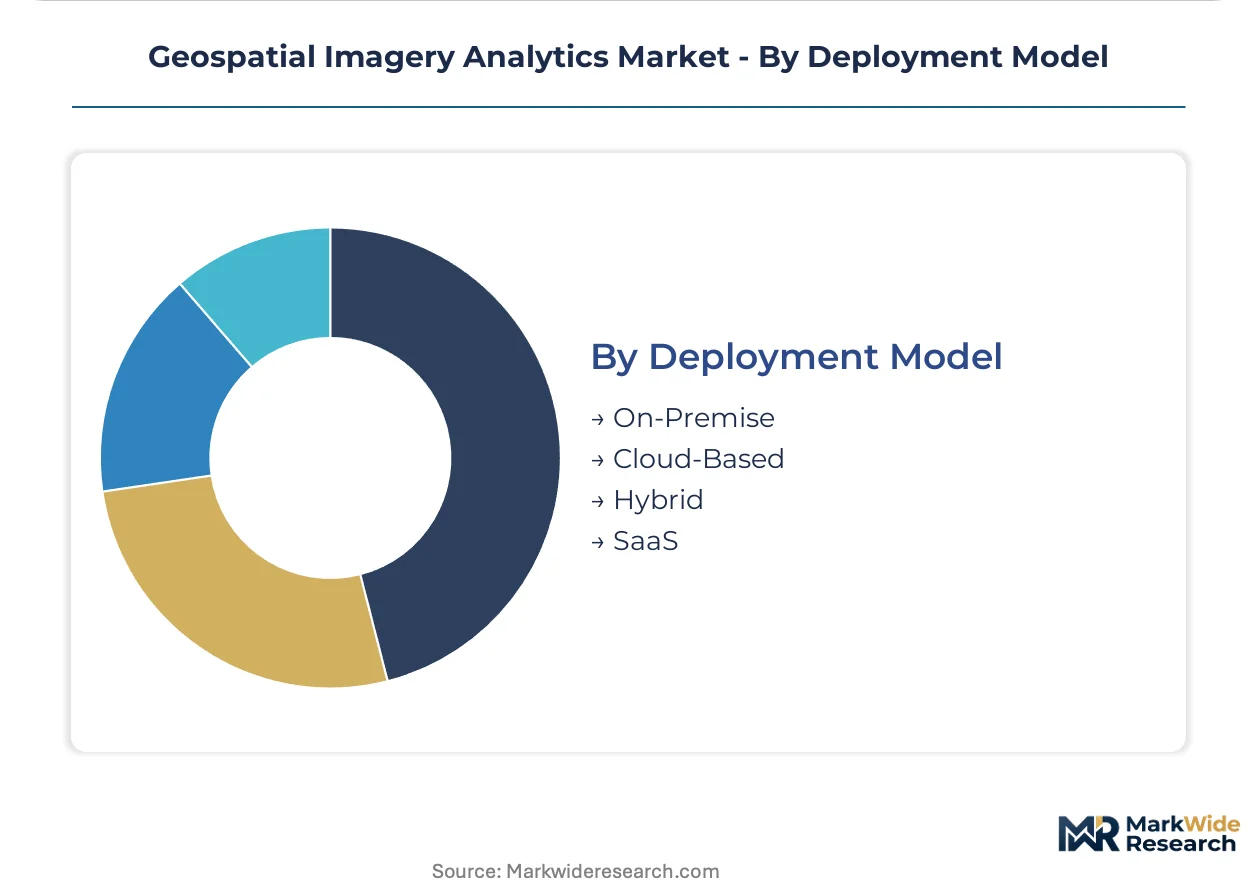
Deployment Model:
Maturity curves separate legacy on-premise installations from cloud-native architectures.
- Cloud-Based:Hyperscale storage and GPU clusters reduce petabyte-scale archive friction, enabling high-frequency analytics without capital infrastructure. AWS, Azure, and Google Cloud egress cost volatility distorts unit economics for retrieval-intensive workflows.
- SaaS:Per-acreage and per-asset subscription contracts displace per-image licensing in agricultural and insurance verticals.
- On-Premise:Classified environments and air-gapped networks persist in defense and intelligence.
- Hybrid:Sensitive inference at edge with non-sensitive processing in cloud balances latency and compliance.
Legacy footprint favors On-Premise; new procurement shifts fastest to Cloud-Based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US National Geospatial-Intelligence Agency anchors procurement volume through multi-year satellite tasking contracts, while the EU Space Programme and Copernicus regulations reshape competitive access across European markets.
United States
Defense and intelligence agencies sustain the largest contract volumes for imagery analytics services, with border surveillance and maritime chokepoint monitoring driving persistent demand. The Department of Commerce's Bureau of Industry and Security regulates commercial remote sensing licensing through export control thresholds. Washington DC and Northern Virginia host concentrated vendor ecosystems serving federal procurement channels.
Germany
Municipal zoning authorities in Berlin and Munich mandate Copernicus-derived land cover data for statutory development plans, standardizing 10-meter resolution baselines across urban planning workflows. The EU AI Act's risk classification for geospatial inference tools tightens compliance for automated feature extraction products. Bavaria and Baden-Württemberg anchor industrial clusters for precision agriculture analytics.
United Kingdom
The UK defense ministry sustains multi-year satellite access agreements with direct constellation control provisions for sovereign tasking priorities. GDPR and post-Brexit data residency requirements fragment cloud deployment architectures for cross-border analytics services. London and the Southeast concentrate financial services demand for property risk assessment and infrastructure monitoring.
Indonesia
Archipelagic geography and limited coastal radar coverage create demand for satellite-derived vessel tracking and illegal fishing detection across maritime domain awareness applications. LAPAN operates persistent monitoring systems for peatland protection through automated change-detection pipelines. Java and Sumatra concentrate domestic analytics adoption for agricultural yield prediction.
Australia
Agricultural cooperatives in the wheat belt demand all-you-can-process subscription contracts tied to acreage rather than individual scene purchases, favoring predictable operational expenditure models. The country's national space agency coordinates downstream access to international satellite constellations. New South Wales and Victoria anchor precision agriculture and infrastructure inspection markets.
Geospatial Imagery Analytics Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with satellite constellation operators and software platform providers occupying distinct competitive territories. The market structure consolidates around defense contracting relationships and hyperscale cloud partnerships rather than pure technology differentiation. Three archetypes dominate: captive satellite manufacturers with direct tasking control, daily coverage specialists with commodity sensor economics, and software incumbents with enterprise GIS ubiquity. Competitive moves center on hyperscale cloud infrastructure integration and subscription-based pricing model displacement of per-image licensing.
Among North American constellation operators, Maxar Technologies Inc. and Planet Labs PBC occupy positions exemplifying divergent strategic vectors—captive manufacturing with direct orbital control versus distributed smallsat economics at scale. European platform presence includes Hexagon AB and Airbus Defence and Space SAS, representing defense-anchored and dual-use commercial archetypes respectively. Trimble Inc. and Environmental Systems Research Institute, Inc. (Esri) sit within the software and precision instrumentation tier, with Esri anchoring enterprise GIS ubiquity that resists API-based analytics insertion.
| Leading Market Players |
|---|
| Hexagon AB |
| Environmental Systems Research Institute, Inc. (Esri) |
| Maxar Technologies Inc. |
| Spire Global, Inc. |
| BlackSky Technology Inc. |
| Planet Labs PBC |
| Trimble Inc. |
| MDA Ltd. |
| Airbus Defence and Space SAS |
| Others |
Supply Flow & Price Mechanics
ITAR-controlled component restrictions gate both supply qualification and price differentiation simultaneously in the geospatial imagery analytics market, fragmenting supply chains for synthetic aperture radar transmitters and cooled infrared focal planes while creating tiered pricing structures that separate US-licensed providers from restricted-access competitors.
Pricing Analysis
US-European price spreads widen for high-resolution tasking contracts as ITAR restrictions inflate procurement costs for non-US buyers. Three-tier pricing structure across premium, standard, and economy levels separates defense-grade sub-meter optical imagery from Copernicus-derived 10-meter baselines and drone-captured cadastral updates. Price differentiation rests on spectral resolution and direct orbital control privileges. Cost compression in commodity multispectral segments is intensifying because hyperspectral sensor miniaturization floods capacity. Agricultural cooperatives in the Australian wheat belt exhibit highest price sensitivity, while US National Geospatial-Intelligence Agency tasking contracts demonstrate lowest sensitivity.
Supply Chain Analysis
Strategic stockpiling of launch slots dominates inventory strategy as constellation operators hedge against SpaceX Falcon 9 scheduling bottlenecks. Manufacturing concentrates in the United States, Germany, and China for satellite platforms, with France and Italy anchoring optical payload assembly. Raw material dependencies include gallium arsenide substrates for infrared sensors, specialized aluminum-lithium alloys for bus structures, and radiation-hardened semiconductors for on-board processing. Single-source vulnerability runs through SpaceX launch capacity concentration. Distribution runs through hyperscale cloud providers AWS, Azure, and Google Cloud for downstream analytics delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's risk-based classification for geospatial inference tools creates a high-growth disruption window, mandating explainable AI documentation that fragments vendor compliance architectures and opens white-space for specialized tooling providers.
For Market Incumbents: Secure defense contracting relationships through direct constellation control provisions and sovereign tasking prioritization. Invest in EU-hosted inference endpoints to satisfy data residency obligations under GDPR and the EU AI Act. Vertical integration into hyperspectral sensor manufacturing reduces payload cost exposure. Threat substitution emerges from foundation models that compress time-to-insight without task-specific training data. For New Entrants and Emerging Players: Differentiate on EU AI Act compliance tooling, building audit trail documentation and model drift monitoring for high-risk geospatial inference applications. Target Indonesia's maritime domain awareness segment, where archipelagic geography and limited coastal radar coverage create unmet demand for vessel tracking analytics. Go-to-market angle: drone-to-satellite fusion partnerships with utility corridor operators seeking centimeter-accurate digital twins. For Investors and Strategic Acquirers: Carve-out targets emerge from defense conglomerates spinning non-core geospatial analytics units amid budget reallocation pressures. Long-term viability over the coming decade hinges on subscription-based pricing model displacement of per-image licensing. Target mid-cap specialists with established Copernicus data pipelines and agricultural insurance vertical relationships. Signal to watch: hyperspectral constellation launch cadence crossing thresholds that commoditize mineral identification services.| Strategic Initiative | Industry Significance |
|---|---|
| Hyperspectral Constellation Deployment | 200+ band instruments from Planet Labs and others enable mineral identification at commodity price points. |
| EU AI Act Compliance Platform Launch | Explainable AI tooling from European vendors satisfies risk classification requirements for border surveillance applications. |
| Drone-to-Satellite Data Fusion Partnership | Trimble and Esri integrations combine UAV LiDAR with orbital multispectral for utility corridor digital twins. |
| Defense Tasking Contract Expansion | US National Geospatial-Intelligence Agency multi-year agreements anchor revenue pools for Maxar and BlackSky. |
| Copernicus Downstream Analytics Buildout | Open data mandates eliminate licensing friction for Sentinel-derived subscription services across European markets. |
Methodological Framework
Desk research of satellite operator regulatory filings, defense procurement databases, and hyperscale cloud capex disclosures preceded structured interviews with constellation operations directors, geospatial data scientists, defense procurement officers, and agricultural insurance underwriters. Primary intelligence combined with secondary validation from Copernicus programme documentation, US Bureau of Industry and Security licensing records, and EU Space Programme implementation reports. Bottom-up segment sizing triangulated against top-down market boundary analysis.
Variance-decomposition across technology, application, end user, and deployment model dimensions structured the analytical framework over the projection horizon. Modeled segmentation tracked satellite imagery versus LiDAR versus aerial photography sourcing, government versus construction versus research institutional demand, and cloud-based versus on-premise versus hybrid deployment architectures. CAGRs derived from cohort growth rate reconciliation across input data streams. Industry-specific forecast inputs included launch manifest schedules and ITAR regulatory threshold adjustments.
The analysis sits within stated boundaries; outcomes outside sustained defense budget authorization and Copernicus open data policy continuity would require recalibration. Forecasts reflect assumptions regarding hyperspectral sensor miniaturization trajectories and cloud egress cost stabilization. Specific risk factors that could revise projections include export control expansion to additional spectral bands and launch capacity disruptions from geopolitical tensions. Revision becomes warranted when EU AI Act enforcement intensity crosses thresholds that fragment vendor operational architectures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Europe Operational Intelligence Market
Analytics
Brazil Big Data Analytics Market
Analytics
Voice Analytics Market
Analytics
Brazil Geospatial Analytics Market
Analytics
Embedded Analytics Software Market
Analytics
RAN Analytics and Monitoring Market
Analytics
Location Analytics Market
Analytics
Content Intelligence Market
Analytics
Data Analytics Outsourcing Market
Analytics
Crowd Analytics Market
Analytics
ASEAN Geospatial Analytics Market
Analytics
Service Analytics Market
Analytics
Big Data Analytics in Semiconductor and Electronics Market
Analytics
Global AI Video Analytics Market
Analytics
Predictive and Prescriptive Analytics Market
Analytics
Global Wi-Fi Analytics Market