
 Global Big Data Market | 2026-2036
Global Big Data Market Size, Share, and Industry Trends Forecast 2026-2036
Global Big Data Market Analysis
Healthcare providers is redrawing demand patterns in the Global Big Data Market, displacing retail businesses as the fastest-expanding buyer archetype. Microsoft Corporation leverages its Azure cloud infrastructure to dominate enterprise data lake deployments. IBM Corporation anchors its position through specialized Watson Health analytics for clinical decision support. Amazon Web Services competes aggressively on storage economics, undercutting rivals in high-velocity streaming workloads.
Big data encompasses the capture, storage, processing, and analysis of datasets exceeding traditional database management capacities, typically characterized by high velocity, variety, and volume requiring distributed computing architectures like Hadoop or Spark. Its primary commercial purpose centers on extracting predictive patterns from unstructured and structured information flows to automate operational decisions. Public cloud deployment leads in revenue contribution as enterprises abandon capital-intensive on-premises infrastructure, while data analytics tools command the deepest margin pools due to recurring subscription pricing and specialized talent requirements. Customer analytics applications show the steepest growth trajectory as consumer-facing industries prioritize real-time personalization engines.
The EU AI Act, GDPR, and HIPAA frameworks collectively shape product standards by mandating explainability in automated decision systems and restricting cross-border data transfers. The SEC's emerging climate disclosure rules are forcing financial institutions to reconstruct data pipelines for emissions tracking and audit trails. Stakeholders must monitor the divergence between European algorithmic accountability mandates and United States sectoral privacy fragmentation when architecting multinational deployment strategies.
Market Dynamics
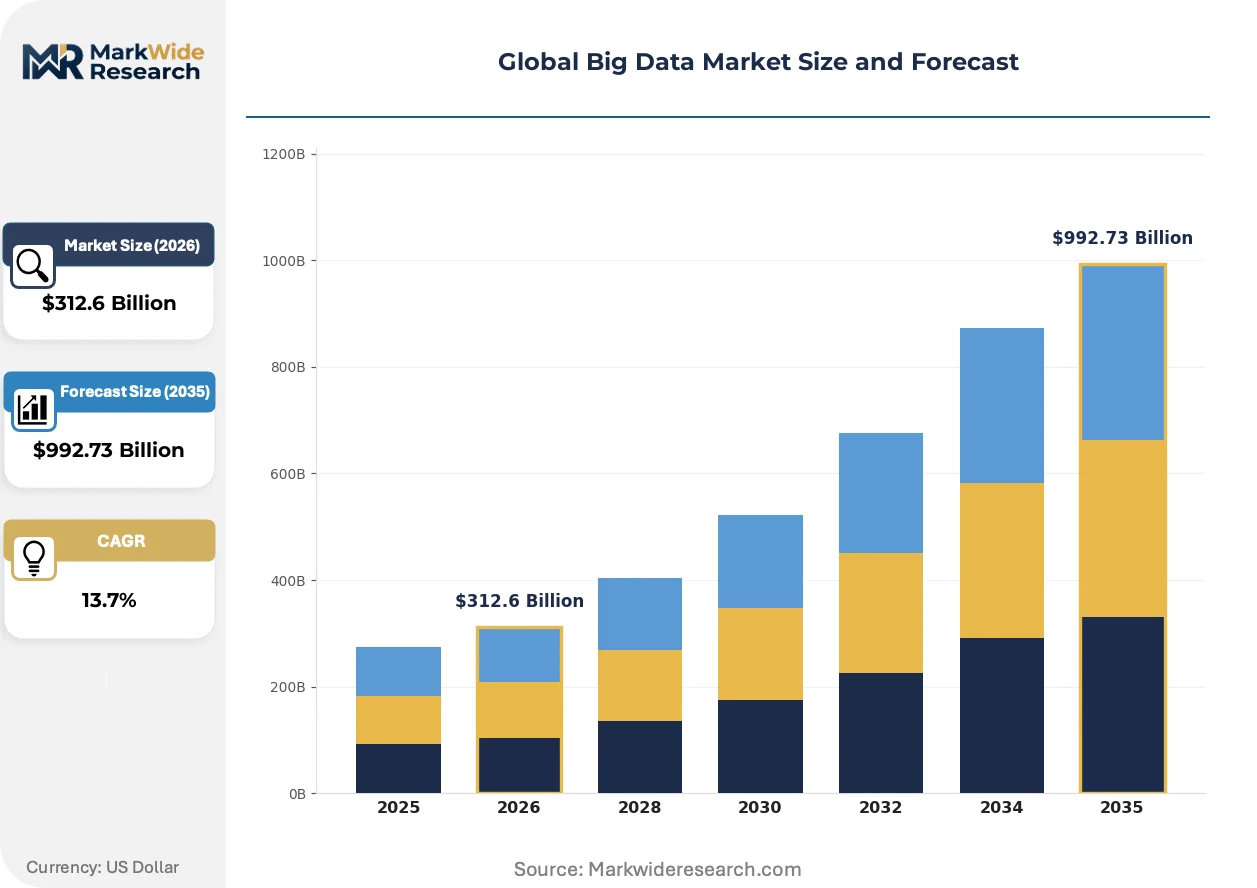
Healthcare providers are redrawing demand patterns in the Global Big Data Market, displacing retail businesses as the fastest-expanding buyer archetype. Cloud-native data architectures are compressing deployment cycles while regulatory mandates from the EU AI Act and HIPAA force explainability into automated clinical decision systems.
Growth Catalysts
- EU AI Act Compliance:Mandatory explainability requirements for automated decision systems are accelerating procurement of interpretable analytics platforms across European healthcare networks.
- Patient Analytics Platforms:Healthcare providers are deploying real-time clinical data lakes to reduce readmission rates and optimize resource allocation across emergency departments.
- United States Cloud Migration:Enterprise abandonment of capital-intensive on-premises infrastructure is concentrating demand in cloud-native data architectures.
Market Restraints
- Cross-Border Data Transfers:GDPR restrictions on international data flows are fragmenting multinational deployment strategies and increasing compliance overhead.
- Specialized Talent Scarcity:Distributed computing expertise in Spark and Hadoop architectures commands premium compensation, inflating operational costs for analytics implementations.
- Algorithmic Accountability:Divergent mandates between European explainability requirements and United States sectoral privacy fragmentation create product standardization friction.
Strategic Opportunities
- Climate Disclosure Mandates:SEC emerging rules on emissions tracking are forcing financial institutions to reconstruct data pipelines, creating demand for specialized audit-trail analytics.
- Real-Time Personalization Engines:Consumer-facing industries in India and Brazil are adopting customer analytics applications to compete with mature-market personalization standards.
- Edge Computing Convergence:Integration of streaming analytics with IoT sensor networks is opening deployment models for manufacturing quality control and predictive maintenance.
Industry Challenges
- Legacy System Integration:Mainframe data architectures in established financial services require costly middleware layers to feed modern analytics pipelines.
- Certification Timeline Compression:HIPAA and GDPR compliance validation cycles are extending product launch schedules for clinical analytics vendors.
- Skill Gap in Federated Learning:Privacy-preserving machine learning techniques remain undersupplied in the talent market despite rising demand from multi-party data collaborations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Big Data Market |
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $992.73 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Solution: Storage Solutions, Data Analytics Tools, Visualization Software, Processing Frameworks End User: Healthcare Providers, Financial Institutions, Government Agencies, Retail Businesses Application: Customer Analytics, Fraud Detection, Predictive Maintenance, Risk Management |
| Companies Covered | Microsoft Corporation, IBM Corporation, Google LLC, Oracle Corporation, SAP SE, Salesforce.com, Inc., Amazon Web Services, Teradata Corporation, Databricks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Big Data Market Emerging Trajectories
Data processing architectures are compressing from centralized warehouses toward distributed edge nodes. This structural migration is reshaping competitive positioning around latency performance and federated governance capabilities.
Apache Spark streaming engines are miniaturizing from cluster-scale deployments to containerized microservices. Telecommunications providers are adopting these lightweight configurations for real-time network optimization. The technology is miniaturizing infrastructure footprints while enabling sub-second anomaly detection across 5G edge locations.
CSRD disclosure requirements in Europe are mandating granular emissions tracking across supply chains. Industrial manufacturers are retrofitting data pipelines to capture Scope 3 carbon metrics from tiered suppliers. German automotive suppliers face the most acute compliance pressure, accelerating investment in supplier data integration platforms.
Subscription pricing for analytics tools is displacing perpetual license models in enterprise procurement. Chief data officers are consolidating vendor relationships around platforms offering usage-based scaling. This shift is most pronounced in United States financial services, where quarterly renegotiation cycles now dominate annual RFP processes.
Global Big Data Market Segmentation
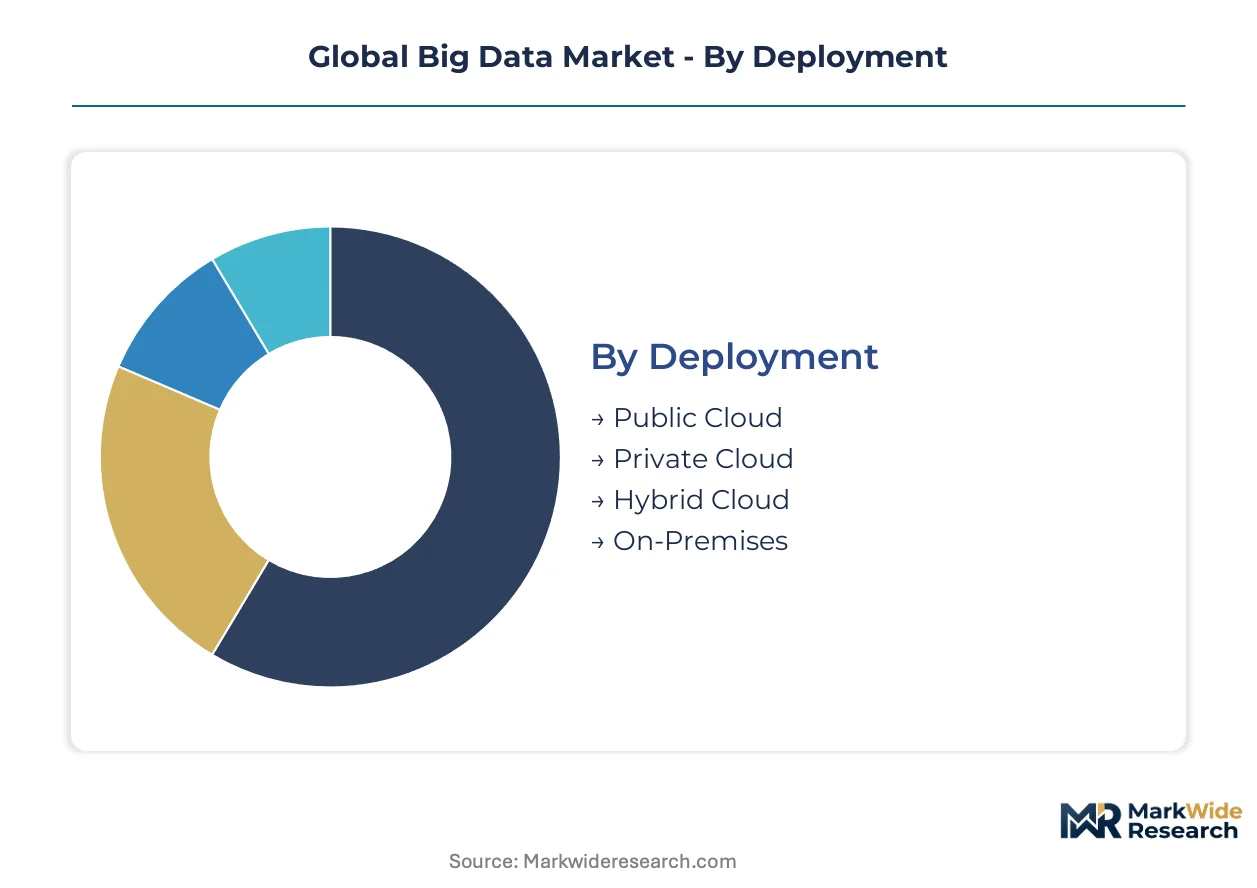
Deployment architecture determines cost structure and compliance posture across the Global Big Data Market. Solution type governs recurring revenue potential and talent requirements. End-user verticals and application domains define competitive intensity and growth trajectory.
Deployment:
Margin pools concentrate in configurations that minimize infrastructure capital while preserving data sovereignty controls.
- Public Cloud:Third-party infrastructure delivers elastic compute and storage without ownership burden. United States enterprises are abandoning on-premises capital expenditure for consumption-based scaling, though GDPR cross-border restrictions fragment European deployment strategies.
- Private Cloud:Dedicated single-tenant environments isolate sensitive workloads behind organizational firewalls. Financial institutions in Germany and Switzerland are mandating on-premise data lakes for trading algorithms and client portfolios under national banking secrecy frameworks.
- Hybrid Cloud:Orchestrated workloads span owned and leased infrastructure based on sensitivity tiers. Healthcare networks partition patient records on-premises while bursting analytics to public nodes for population health studies.
- On-Premises:Fully captive hardware estates persist in classified government facilities and legacy manufacturing sites. Defense contractors in the United States maintain air-gapped clusters for weapons systems telemetry.
Public Cloud holds installed capacity. Hybrid Cloud is rotating up the share rankings.
Solution:
Recurring subscription models concentrate in layers closest to decision-makers rather than infrastructure plumbing.
- Data Analytics Tools:Statistical and machine learning platforms transform raw information into predictive signals. Healthcare providers in the United States are procuring interpretable clinical decision support to satisfy HIPAA audit requirements and reduce liability exposure.
- Visualization Software:Interactive dashboards compress complex datasets into executive-facing narratives. Financial services compliance teams in London and Singapore are reconstructing emissions tracking interfaces for SEC and CSRD disclosure mandates.
- Storage Solutions:Distributed file systems and object stores manage petabyte-scale persistence. Amazon S3-compatible APIs dominate object storage procurement despite vendor lock-in risks.
- Processing Frameworks:Apache Spark and Flink engines execute distributed transformations across commodity clusters. Telecommunications providers miniaturize streaming microservices for 5G edge anomaly detection.
Data Analytics Tools command premium pricing. Visualization Software is gaining share fastest among procurement categories.
End User:
Regulatory pressure intensity varies sharply across verticals, reshaping vendor qualification requirements.
- Healthcare Providers:Hospital systems and payers deploy real-time clinical data lakes to optimize emergency department throughput. EU AI Act explainability mandates are accelerating procurement of interpretable patient analytics platforms across French and German hospital networks.
- Financial Institutions:Banks, insurers, and asset managers reconstruct pipelines for climate disclosure and fraud surveillance. SEC emerging rules on emissions tracking are forcing data architecture overhauls in United States capital markets.
- Government Agencies:National statistical offices and security services aggregate citizen-scale datasets for policy modeling. India's UIDAI infrastructure demonstrates population-scale biometric data lake feasibility.
- Retail Businesses:Consumer-facing chains personalize engagement through purchase pattern analysis. Brazilian and Indian retailers are adopting real-time recommendation engines to match mature-market personalization standards.
Healthcare Providers anchor current demand expansion. Financial Institutions are climbing the fastest in procurement velocity.
Application:
Latency requirements and data freshness demands fragment technical architectures across use cases.
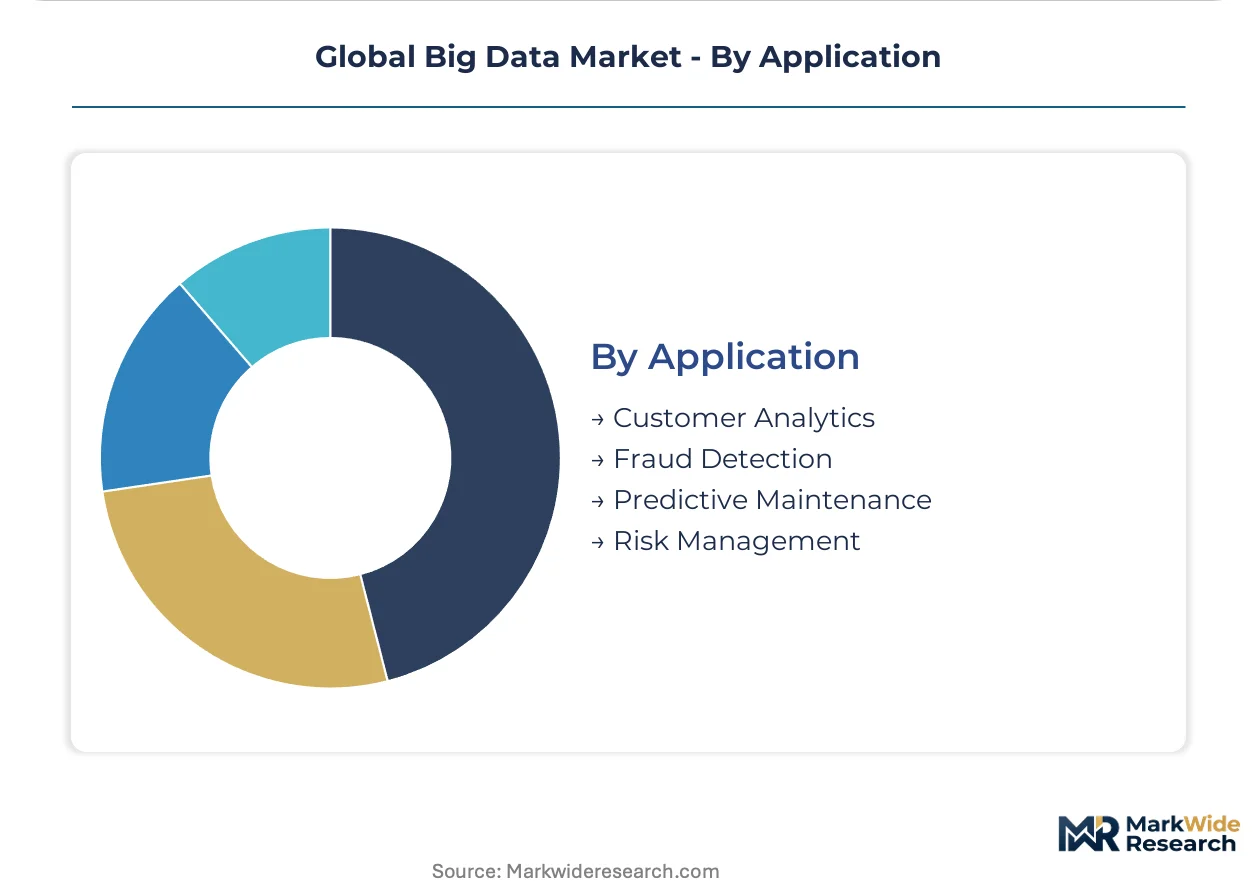
- Customer Analytics:Real-time personalization engines process clickstreams and transaction histories for immediate targeting. E-commerce platforms in São Paulo and Mumbai are investing in sub-second recommendation latency to compete with United States benchmarks.
- Fraud Detection:Anomaly scoring on payment flows and identity verification blocks synthetic transactions. United Kingdom banks are integrating open banking data feeds with behavioral biometrics for layered authentication.
- Predictive Maintenance:Sensor fusion on industrial equipment forecasts failure before operational impact. German automotive suppliers deploy edge analytics on welding robots to minimize assembly line downtime.
- Risk Management:Portfolio stress testing and counterparty exposure quantification guide capital allocation. Swiss reinsurers model climate catastrophe probabilities using satellite imagery and historical claims fusion.
Customer Analytics leads deployment volume. Fraud Detection is expanding most quickly in regulated verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States cloud infrastructure exports to European healthcare networks are accelerating cross-border data architecture deployments. German automotive suppliers and French hospital systems import American analytics platforms under strict EU AI Act compliance terms. This trade corridor shapes procurement patterns across the Atlantic.
United States
Enterprise abandonment of on-premises capital expenditure concentrates demand in cloud-native data architectures. SEC emerging rules on climate disclosure force financial institutions to reconstruct emissions-tracking pipelines. New York and San Francisco financial services clusters drive quarterly renegotiation cycles for usage-based analytics subscriptions.
Germany
Industrial manufacturers retrofit data pipelines to capture Scope 3 carbon metrics from tiered suppliers under CSRD mandates. The country's national banking secrecy frameworks mandate on-premise data lakes for trading algorithms. Bavarian automotive suppliers deploy edge analytics on welding robots to minimize assembly line downtime.
France
Hospital networks accelerate procurement of interpretable patient analytics platforms to satisfy EU AI Act explainability requirements. The national data protection regulator enforces strict cross-border transfer restrictions under GDPR. Paris-based healthcare clusters partition patient records on-premises while bursting population health analytics to public nodes.
India
Consumer-facing industries adopt real-time personalization engines to compete with mature-market standards. The national biometric identification authority demonstrates population-scale data lake feasibility. Mumbai and Bangalore e-commerce platforms invest in sub-second recommendation latency infrastructure.
Brazil
Retail chains deploy customer analytics applications to match United States personalization benchmarks. The national health surveillance agency aggregates citizen-scale datasets for policy modeling. São Paulo financial services clusters integrate open banking data feeds with behavioral biometrics for layered fraud authentication.
Global Big Data Market Vendor Landscape
Listed leaders compete with private specialists across cloud infrastructure and analytics software layers. The vendor base stratifies into three tiers: hyperscale cloud platforms, enterprise software incumbents, and venture-backed data-native specialists. Dominant competitive moves include strategic partnerships between cloud providers and vertical analytics firms, plus geographic expansion through localized data residency offerings.
Within the hyperscale tier, Microsoft Corporation and Amazon Web Services occupy positions defined by infrastructure breadth and storage economics respectively. IBM Corporation anchors the enterprise incumbent segment through specialized healthcare analytics. Databricks exemplifies the venture-backed data-native archetype with its lakehouse positioning. These three represent distinct strategic postures rather than interchangeable substitutes.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| Google LLC |
| Oracle Corporation |
| SAP SE |
| Salesforce.com, Inc. |
| Amazon Web Services |
| Teradata Corporation |
| Databricks |
| Others |
Supply Flow & Price Mechanics
Consumption-based subscription contracts lock in multi-year revenue visibility for cloud infrastructure providers while capping buyer exposure to capital expenditure. Healthcare networks in the United States and financial institutions in Germany favor these arrangements to align analytics spending with patient volume and trading activity fluctuations.
Pricing Analysis
Next-generation lakehouse architectures command premium positioning over legacy data warehouse deployments, while prior-generation Hadoop clusters trade at steep discounts in secondary markets. Three-tier pricing structure across premium, standard, and economy levels segments by query concurrency, data residency controls, and support response times. Pricing pressure stems from Amazon Web Services storage economics undercutting rivals in high-velocity streaming workloads. Mid-market retailers in Brazil and India exhibit the highest price sensitivity, while Swiss reinsurers and United States defense contractors accept premium tiers for air-gapped isolation and dedicated engineering support.
Supply Chain Analysis
Inbound logistics costs for specialized AI accelerator hardware face congestion at the Port of Los Angeles and container availability constraints on transpacific trade lanes. Semiconductor fabrication concentrates in Taiwan, South Korea, and the United States for advanced GPUs and custom ASICs. Raw material dependencies span rare earth elements from Chinese processing facilities, high-bandwidth memory from Korean suppliers, and silicon wafers from Japanese manufacturers. Single-source vulnerability around TSMC's leading-edge nodes threatens supply continuity for training clusters. Distribution runs through hyperscale cloud regions with localized data residency certifications, bypassing traditional value-added reseller channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed analytics services and professional implementation layers are expanding faster than raw compute or storage provisioning, creating attach-rate opportunities for vendors who bundle consulting with infrastructure.
For Market Incumbents: Secure interpretability certifications for EU AI Act compliance before competitors lock out European healthcare procurement. Defend margin position by embedding Watson Health and Azure Purview governance tools into existing enterprise agreements, neutralizing Databricks' lakehouse displacement threat through backward integration into metadata management and lineage tracking. For New Entrants and Emerging Players: Federated learning implementation services represent a service-layer gap where incumbents under-serve multi-party data collaborations. Target German automotive suppliers and French hospital networks seeking privacy-preserving analytics without centralizing sensitive datasets. Lead with open-source Spark-based tooling and localized data residency to bypass hyperscaler lock-in. For Investors and Strategic Acquirers: Venture-backed data-native specialists with vertical-specific compliance automation command scarcity premiums in due diligence. Frame long-term viability around recurring revenue concentration and gross retention rates above industry medians. Watch SEC climate disclosure rule enforcement intensity as the signal indicating pipeline reconstruction demand inflection in United States financial services.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Microsoft Azure Purview embedding with Salesforce Health Cloud accelerates HIPAA-compliant clinical data lake deployment. |
| Geographic Expansion | Localized data residency offerings in Frankfurt and Paris satisfy GDPR cross-border restrictions for EU healthcare networks. |
| Acquisition of Specialist Firm | Interpretable ML boutiques with EU AI Act certification expertise command premium multiples from incumbent acquirers. |
| Strategic Partnership | Telecommunications providers miniaturize Spark streaming microservices through 5G edge infrastructure alliances. |
| Product Launch | Real-time personalization engines with sub-second latency target São Paulo and Mumbai e-commerce platforms. |
Methodological Framework
The analysis maps cloud deployment architectures, analytics solution tiers, and end-user verticals, each validated through chief data officers, healthcare informatics directors, financial services compliance leads, and telecommunications infrastructure planners. Primary interviews with these stakeholders combine with secondary validation against SEC 10-K filings, hyperscaler capex disclosures, EU AI Act regulatory texts, and hospital procurement databases. Bottom-up segment sizing triangulates against top-down market envelope checks.
Consistency checks validate outputs against external benchmarks including cloud infrastructure revenue disclosures and vertical software spending surveys. The analytical framework models deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern across the projection horizon. CAGRs derive from segment-level growth rate synthesis and technology diffusion curve positioning. Forecast inputs include EU AI Act implementation timelines and SEC climate disclosure enforcement intensity.
Forecasts assume regulatory continuity in EU AI Act, GDPR, and HIPAA regimes; material policy shifts would require re-modeling. Technology disruption from quantum-resistant encryption or federated learning standardization could accelerate or compress adoption curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Customer Journey Analytics Market
Analytics
Web Analytics Market
Analytics
Spain Geospatial Imagery Analytics Market
Analytics
Big Data Analytics in Retail Market
Analytics
Spend Analytics Software Market
Analytics
BI and Analytics Market
Analytics
Italy ICT Market
Analytics
Imagery Analytics Market
Analytics
Text Analytics Market
Analytics
Operational Intelligence Market
Analytics
APAC Data Wrangling Market
Analytics
Europe Operational Intelligence Market
Analytics
Global Web Analytics Software Market
Analytics
Europe Emotion Analytics Market
Analytics
Mobile App Attribution Tool Market
Analytics
Weather Data Services Market