
 Spend Analytics Software Market | 2026-2036
Spend Analytics Software Market Size, Share, and Industry Trends Forecast 2026-2036
Spend Analytics Software Market Outlook
Enterprise-grade functionality is collapsing into mid-market price bands as cloud-native architectures reduce deployment overhead. Oracle Corporation leverages its database heritage to anchor complex spend classification across Fortune 500 accounts. SAP competes through tight ERP integration that sustains renewal rates in European manufacturing verticals. Coupa differentiates via network effects from its supplier commerce cloud, which dominates indirect spend automation.
Spend analytics software encompasses platforms that ingest, classify, and visualize procurement expenditure data using AI-driven categorization engines and multi-source data fusion pipelines. These systems apply machine learning to unstructured invoice fields, achieving classification accuracy above ninety percent while enabling supplier consolidation and contract compliance monitoring. Cloud-based deployment leads absolute growth as IT departments relinquish on-premises maintenance burdens, though hybrid configurations retain margin pools in regulated BFSI and healthcare end users where data residency rules persist. The solution layer fragments sharply: reporting modules command mature renewal streams, while forecasting and visualization capabilities attract new-logo growth as finance teams demand predictive cash-flow modeling.
FDA 21 CFR Part 11 and HIPAA constrain data handling for healthcare adopters, while the EU AI Act imposes algorithmic transparency requirements on automated spend classification tools deployed across European procurement operations. The SEC's climate disclosure rules and the EU CSRD extend compliance pressure into supply chain emissions tracking, broadening platform scope beyond pure cost analytics. Stakeholders must weigh sovereign cloud requirements against API ecosystem breadth when selecting deployment architecture for multi-country operations.
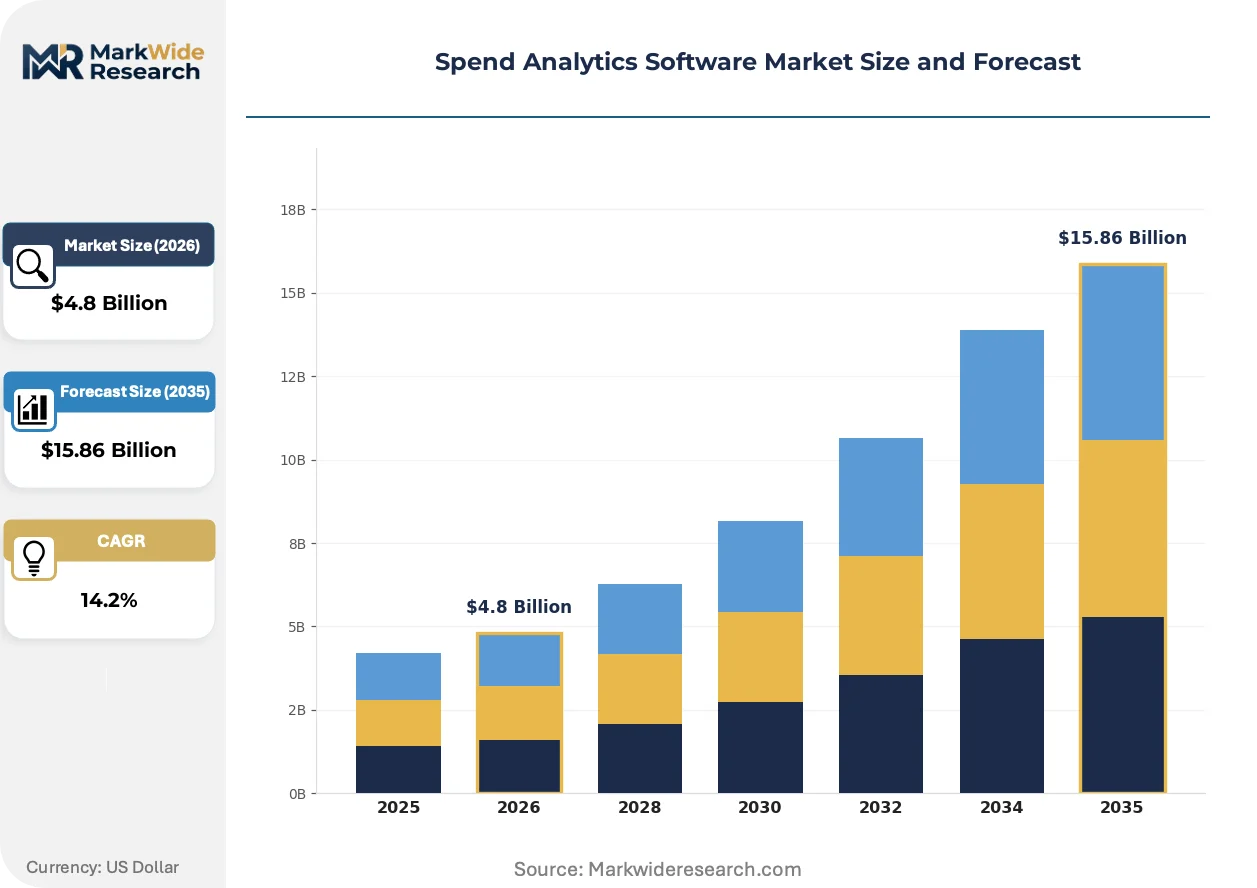
Market Dynamics
Cloud-native architectures are collapsing enterprise-grade spend analytics functionality into mid-market price bands, compressing vendor margins while expanding addressable buyer pools across manufacturing procurement teams.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:Procurement intelligence platforms face mandatory audit trails for automated spend classification, accelerating replacement of opaque legacy systems in European manufacturing operations.
- Cloud-based deployment:IT departments relinquish on-premises maintenance burdens, unlocking rapid implementation cycles for mid-market enterprises previously excluded from advanced analytics capabilities.
- Direct material sourcing optimization:Industrial buyers in Germany prioritize predictive analytics for supplier negotiations, concentrating demand for real-time commodity price forecasting modules.
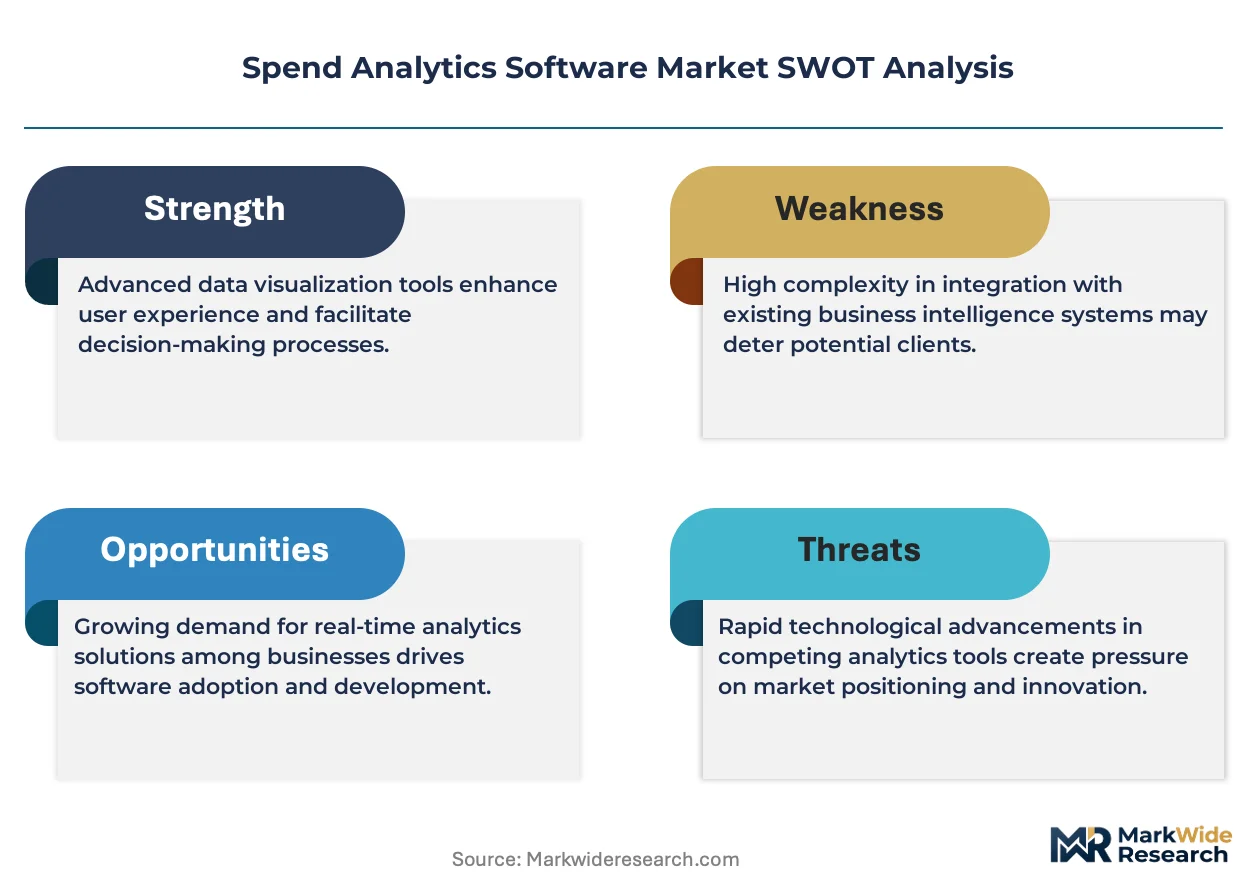
Market Restraints
- Data residency compliance costs:Hybrid deployment configurations retain margin pools in BFSI and healthcare end users where HIPAA and FDA 21 CFR Part 11 constrain cloud migration timelines.
- Unstructured invoice field complexity:Machine learning classification engines face accuracy degradation with non-standard supplier formats, requiring costly manual intervention for long-tail vendors.
- Legacy ERP integration friction:Tight coupling requirements with SAP and Oracle systems extend sales cycles and inflate professional services revenue dependence.
Strategic Opportunities
- Scope 3 emissions tracking:SEC climate disclosure rules and EU CSRD extend platform value beyond cost analytics into supply chain carbon accounting, creating new module expansion paths.
- Supplier commerce network effects:Indirect spend automation platforms capture transaction data liquidity that reinforces switching costs and sustains pricing power.
- API ecosystem breadth:Multi-source data fusion pipelines enable third-party risk intelligence integration, differentiating platforms in financial services procurement.
Industry Challenges
- AI/ML talent scarcity:Procurement technology vendors compete for data scientists capable of tuning categorization engines above ninety percent accuracy thresholds.
- Sovereign cloud fragmentation:Multi-country operations require architecture decisions weighing regional data localization mandates against unified analytics performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spend Analytics Software Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Retail, Manufacturing, Healthcare, BFSI Solution: Reporting, Data Integration, Forecasting, Visualization Industry Vertical: Telecommunications, Government, Education, Automotive |
| Companies Covered | Oracle Corporation, Sievo, Tropic, Suplari, IBM, Coupa, GEP, Ivalua, SAP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spend Analytics Software Market Strategic Shifts
Artificial intelligence is restructuring how procurement organizations extract intelligence from fragmented spend data, collapsing traditional service-heavy implementation models.
Natural language processing is decomposing unstructured invoice fields into structured classification schemas without manual mapping templates. Mid-market finance teams adopt these capabilities within weeks rather than quarters. The technology is decomposing incumbent advantages built on pre-configured industry taxonomies.
EU AI Act algorithmic transparency requirements impose documentation burdens on automated spend classification tools deployed across European procurement operations. Vendors must maintain model cards explaining categorization logic to regulators and audit committees. German automotive and industrial buyers now mandate such documentation in RFP evaluations.
Finance teams demand predictive cash-flow modeling capabilities that extend beyond historical reporting into forward-looking supplier payment scenarios. Subscription pricing for forecasting modules displaces perpetual licenses for mature reporting functionality. This preference shift concentrates in North American and European enterprises with complex multi-currency procurement operations.
Spend Analytics Software Market Segmentation
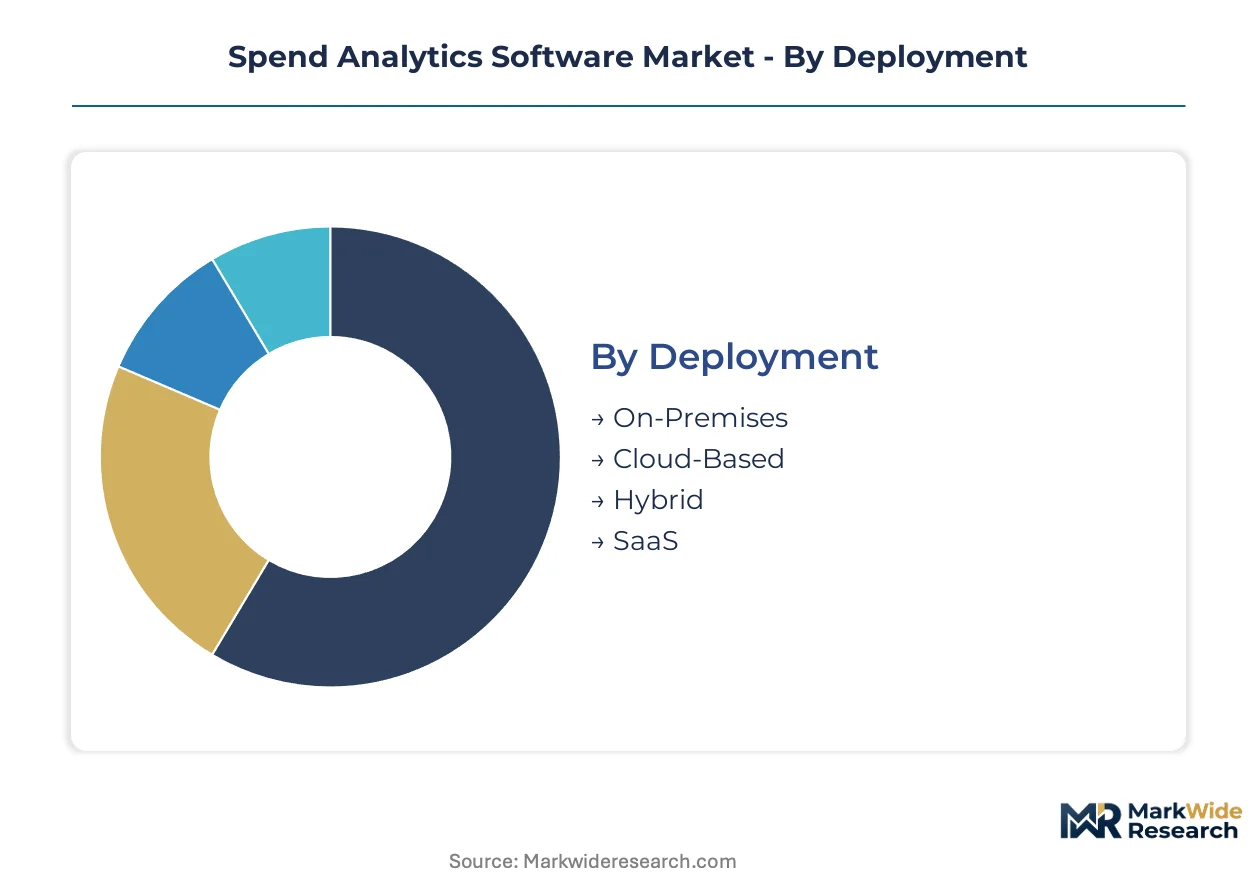
Spend analytics software vendors configure product architectures around deployment constraints, end-user procurement maturity, and solution layer specialization. Segmentation choices directly determine pricing power, implementation complexity, and renewal rate durability across buyer organizations.
Deployment:
Margin pools concentrate in hybrid configurations where data residency requirements sustain premium pricing against standardized cloud alternatives.
- On-Premises:Dedicated infrastructure installations within buyer-controlled data centers. Healthcare systems in Germany and BFSI institutions in Switzerland retain these deployments to satisfy GDPR and national banking regulator mandates for physical data control.
- Cloud-Based:Fully managed SaaS environments with elastic compute provisioning. Manufacturing procurement teams in the US and UK prioritize these for rapid supplier onboarding without capital expenditure commitments.
- Hybrid:Split architectures keeping sensitive spend data on-premises while pushing analytics processing to cloud nodes. This configuration commands the highest per-seat pricing due to engineering complexity and compliance consulting bundling.
- SaaS:Multi-tenant subscription platforms with standardized feature sets. Mid-market retail and education buyers drive volume here, accepting limited customization for predictable operational expenditure.
On-Premises holds installed capacity among regulated incumbents. Cloud-Based is rotating up the share rankings as IT departments relinquish infrastructure ownership.
End User:
Application intensity varies sharply by sector procurement sophistication and supplier base complexity.
- Manufacturing:Direct material sourcing operations with thousands of active suppliers and commodity price volatility exposure. German automotive buyers and US industrial conglomerates concentrate demand for predictive analytics modules that forecast raw material cost movements.
- BFSI:Financial institutions managing regulatory procurement spend across facilities, technology, and professional services. EU AI Act algorithmic transparency requirements now mandate auditable classification logic for automated spend analysis in European banking operations.
- Retail:High-volume indirect spend across marketing, logistics, and store operations. These buyers prioritize user-friendly visualization tools over deep statistical forecasting capabilities.
- Healthcare:Hospital systems and pharmaceutical manufacturers constrained by FDA 21 CFR Part 11 and HIPAA data handling rules. Hybrid deployment retention remains highest here due to patient data adjacency concerns.
Manufacturing captures the deepest per-seat revenue. Retail is climbing fastest as cloud-native tools penetrate mid-market merchandising operations.
Solution:
Module bundling strategies separate mature reporting renewals from new-logo growth in predictive capabilities.
- Forecasting:Predictive cash-flow modeling and commodity price projection engines using machine learning on historical spend patterns. Finance teams in multi-currency European enterprises and North American multinationals drive subscription expansion here.
- Reporting:Standardized dashboards and compliance documentation for procurement KPIs. This mature module sustains renewal revenue but faces pricing compression as basic functionality commoditizes.
- Data Integration:Multi-source pipeline construction connecting ERP, e-procurement, and supplier networks. API ecosystem breadth differentiates vendors competing for financial services accounts with complex legacy system estates.
- Visualization:Self-service analytics interfaces enabling business users to explore spend patterns without technical support. Mid-market adoption concentrates in retail and education verticals with limited dedicated procurement IT staff.
Reporting maintains the broadest installed base. Forecasting is expanding most quickly as CFO mandates extend procurement analytics into working capital optimization.
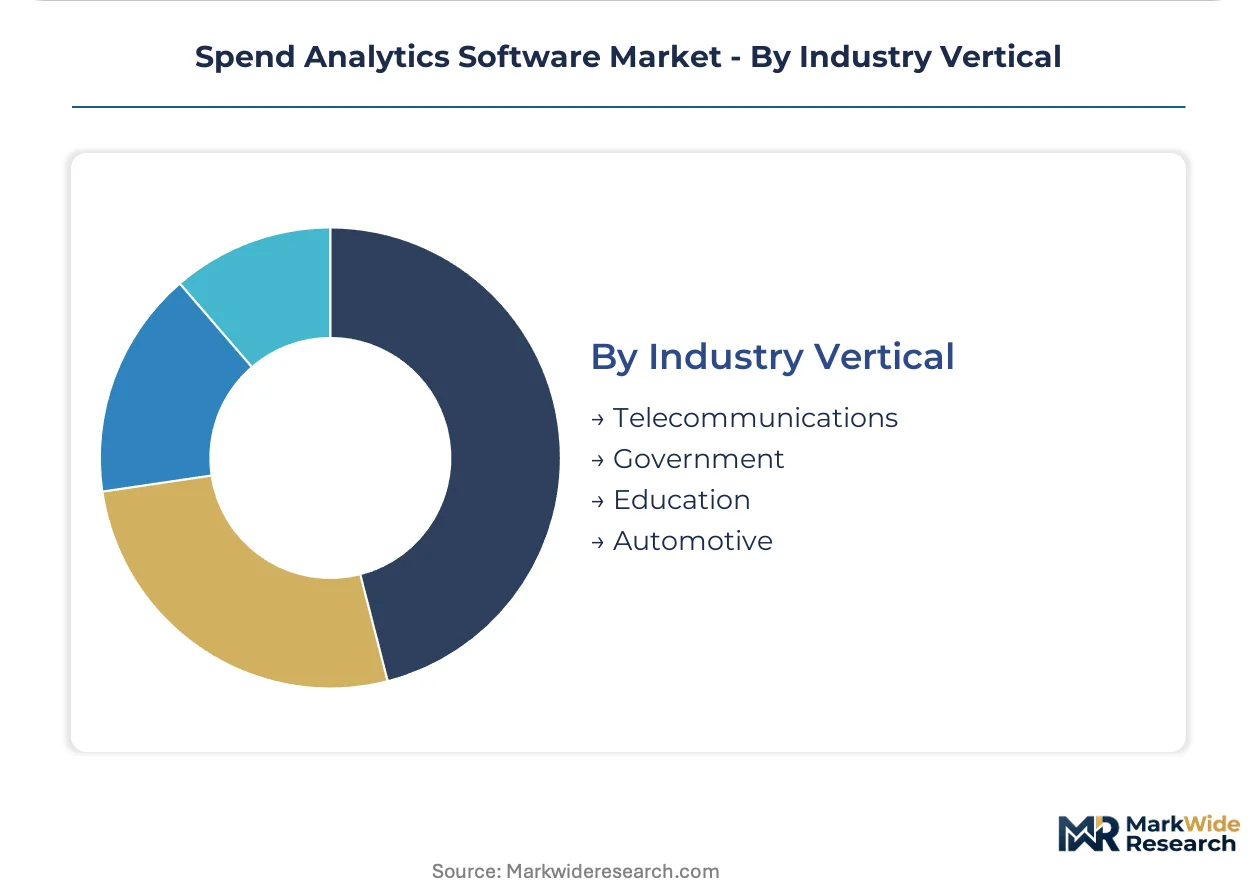
Industry Vertical:
Procurement data complexity and regulatory overlay determine vertical-specific platform requirements.
- Automotive:Tiered supplier hierarchies with just-in-sequence delivery requirements and commodity price pass-through clauses. German OEMs and US electric vehicle manufacturers demand real-time direct material cost tracking across global supply chains.
- Government:Public sector procurement bound by transparency mandates and small business set-aside tracking. Federal agencies in the US and national ministries in France prioritize audit trail completeness over predictive sophistication.
- Telecommunications:Capital-intensive network infrastructure spend with long-dated vendor contracts and technology refresh cycles. These buyers emphasize contract compliance monitoring and penalty recovery analytics.
- Education:Fragmented purchasing across research, facilities, and administrative functions with limited procurement centralization. Cloud-based SaaS penetration is highest here due to minimal IT staffing and budget constraints.
Automotive anchors premium solution pricing. Education is gaining share fastest as cloud economics unlock analytics access for resource-constrained institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spend analytics software demand concentrates in net-importing manufacturing economies where procurement optimization directly impacts trade balance competitiveness. Export-oriented industrial clusters drive adoption of predictive sourcing tools to offset input cost volatility.
United States
Multi-currency procurement operations at North American multinationals require real-time commodity price forecasting modules. SEC climate disclosure rules extend platform scope into supply chain emissions tracking for listed manufacturers. Chicago and Detroit automotive clusters prioritize direct material cost visibility across tiered supplier networks.
Germany
Industrial buyers in Baden-Württemberg and Bavaria mandate predictive analytics for supplier negotiations amid raw material volatility. EU AI Act algorithmic transparency requirements accelerate replacement of opaque legacy classification systems. Frankfurt banking operations now require auditable model documentation for automated spend analysis.
United Kingdom
Post-Brexit procurement complexity drives demand for multi-source data fusion pipelines connecting fragmented supplier systems. GDPR compliance constraints sustain hybrid deployment premiums in London financial services. Manchester and Birmingham manufacturing hubs adopt cloud-native tools for rapid supplier onboarding.
India
Mid-market enterprises in Maharashtra and Karnataka leverage SaaS platforms to bypass capital expenditure barriers for advanced analytics. RBI data localization guidelines shape architecture decisions for BFSI procurement intelligence. Bangalore IT services clusters integrate spend analytics into vendor management workflows.
Japan
Just-in-sequence delivery requirements at automotive OEMs demand real-time direct material tracking across keiretsu supplier hierarchies. METI supply chain resilience initiatives accelerate predictive sourcing adoption. Toyota City and Nagoya industrial corridors concentrate demand for contract compliance monitoring modules.
Spend Analytics Software Market Competitive Environment
Concentration sits with ERP-anchored incumbents and cloud-native specialists competing through divergent integration strategies. Three archetypes dominate: database heritage providers leveraging classification depth, network-effect platforms capturing transaction liquidity, and procurement-native suites emphasizing workflow automation. M&A activity targets AI/ML talent for categorization engine improvement, while strategic partnerships expand API ecosystem breadth for multi-source data fusion.
Within the ERP-anchored tier, Oracle Corporation and SAP exemplify database heritage positioning that sustains renewal rates through tight system coupling. Coupa occupies a network-effects position where supplier commerce cloud density reinforces switching costs. Cloud-native specialists Sievo and Suplari represent mid-market penetration strategies collapsing enterprise functionality into accessible price bands. IBM anchors hybrid deployment capabilities for regulated BFSI and healthcare verticals where data residency constraints persist.
| Leading Market Players |
|---|
| Oracle Corporation |
| Sievo |
| Tropic |
| Suplari |
| IBM |
| Coupa |
| GEP |
| Ivalua |
| SAP |
| Others |
Value Chain & Pricing Dynamics
Cloud-native deployment architectures are displacing legacy on-premises installations as the dominant delivery mechanism, simultaneously redrawing supply geography toward hyperscaler regions and compressing pricing economics across mid-market buyer segments. This substitution collapses enterprise-grade functionality into accessible subscription tiers while fragmenting vendor margin pools between standardized SaaS and compliance-heavy hybrid configurations.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with differentiation driven by AI model sophistication and EU AI Act audit trail completeness. Cost compression in the economy tier is intensifying because cloud-native entrants are collapsing implementation overhead into weeks rather than quarters. Procurement teams at German automotive manufacturers exhibit the lowest price sensitivity, prioritizing predictive accuracy and regulatory documentation over per-seat costs, while mid-market retail buyers drive the steepest discount negotiations.
Supply Chain Analysis
Just-in-time implementation preferences dominate among cloud-native adopters, while regulated BFSI and healthcare buyers maintain strategic stockpiles of on-premises capacity to satisfy data residency constraints. Engineering talent concentrates in the United States, Germany, and India, with machine learning classification expertise drawing from Bangalore IT services clusters, Berlin AI research institutes, and Silicon Valley hyperscaler alumni networks. Single-source vulnerability runs through NVIDIA GPU supply for model training workloads. Distribution runs through direct enterprise sales teams for Fortune 500 accounts and channel partners for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spend analytics software is entering a cyclical recovery phase as manufacturing procurement teams restart delayed digital transformation initiatives deferred during interest rate tightening. Raw material cost volatility across automotive and industrial supply chains is accelerating replacement of spreadsheet-dependent sourcing processes with predictive analytics platforms.
For Market Incumbents: Secure renewal rates in European manufacturing verticals by accelerating EU AI Act compliance documentation and embedding classification model cards into standard deliverables. Defend against cloud-native specialists by deepening API ecosystem breadth for multi-source data fusion pipelines that increase switching costs. Prioritize backward integration into supplier network data feeds to capture transaction liquidity before competitors establish network effects.
For New Entrants and Emerging Players: Anchor in mid-market education and retail verticals where procurement IT staffing constraints favor rapid-deployment SaaS configurations over customization-heavy enterprise suites. Target North American merchandising operations with self-service visualization tools that bypass lengthy professional services engagements. Pursue a channel-first go-to-market angle through regional ERP implementation partners already embedded in target accounts.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed procurement-native suites that have saturated their initial vertical beachheads and now require geographic or capability expansion capital. Five-to-ten year viability hinges on successful AI/ML talent retention and classification accuracy improvement above ninety percent thresholds. Monitor EU AI Act enforcement intensity as the signal to watch for compliance-driven replacement cycle acceleration. Revision becomes warranted when regulatory penalty severity crosses thresholds that trigger board-level procurement system audits.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | Auditable model documentation unlocks German automotive and Frankfurt banking procurement budgets. |
| Supplier Commerce Network Expansion | Transaction data liquidity from indirect spend automation reinforces platform switching costs. |
| Hybrid Deployment Architecture Development | Split on-premises and cloud configurations capture HIPAA-constrained healthcare renewal streams. |
| Predictive Cash-Flow Module Launch | Forward-looking capabilities displace perpetual licenses in multi-currency European enterprise accounts. |
| API Ecosystem Partnership Program | Third-party risk intelligence integration differentiates platforms in BFSI procurement evaluations. |
Study Parameters
A standing panel of procurement technology directors, CFOs at mid-market manufacturers, ERP implementation specialists, and cloud infrastructure architects provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation against SEC filings, hyperscaler capex disclosures, EU regulatory registers, and hospital procurement database extracts. Bottom-up deployment model sizing and top-down vertical spending estimates were triangulated to constrain forecast variance.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. The analytical framework modeled deployment configuration, organization size, vertical industry, integration complexity with legacy ERP estates, and regional regulatory adoption patterns. CAGRs were derived from segment-level growth rate reconciliation with macroeconomic manufacturing output indicators and IT software spending surveys. Forecast inputs included commodity price volatility indices for direct material sourcing modules and EU AI Act implementation timelines for compliance-driven replacement demand.
Decision-makers should treat outputs as directional under assumptions of continued cloud migration willingness and stable manufacturing capital expenditure; material deviation would warrant model refresh. Specific risk factors that could revise forecasts include sovereign cloud fragmentation disrupting multi-country deployment architectures and AI/ML talent scarcity constraining classification engine improvement velocity. Revision becomes warranted when regulatory enforcement intensity or interest rate environments cross thresholds that freeze procurement technology investment cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Human Resource Analytics Market
Analytics
Global Cognitive Analytics Market
Analytics
HR Analytics Market
Analytics
Content Analytics Software Market
Analytics
Analytics of Things (Aot) Market
Analytics
Analytics Sandbox Market
Analytics
Complex Event Processing Market
Analytics
Global Clickstream Analytics Market
Analytics
Content Intelligence Market
Analytics
South Korea Contact Center Analytics Market
Analytics
Mobile App Attribution Tool Market
Analytics
Predictive Analytics Market
Analytics
Business Analytics Market
Analytics
China Contact Center Analytics Market
Analytics
Hadoop Big Data Analytics Solution Market
Analytics
Network Analytics Services Market