
 GCC Digital Asset Management Market | 2026-2036
GCC Digital Asset Management Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Digital Asset Management Market Intelligence
Enterprise buyer concentration is consolidating across GCC media conglomerates and sovereign wealth-backed technology ventures, with procurement committees at fewer holding companies controlling larger platform contracts. Binance leverages its regional licensing through Bahrain and Dubai frameworks to anchor institutional custody discussions adjacent to DAM infrastructure. Adobe competes through Creative Cloud ecosystem lock-in among Gulf broadcasters and advertising agencies. Bynder specializes in mid-market SaaS deployment for retail chains expanding omnichannel content operations across Riyadh and Jeddah.
Digital Asset Management encompasses the systematic organization, storage, retrieval, and distribution of rich media files through metadata architectures, automated workflow engines, and rights-management protocols that enforce usage permissions across distributed teams. Cloud-Based deployment dominates procurement among GCC enterprises seeking elastic storage for 4K and emerging 8K video pipelines without capital-intensive server farms. Workflow Automation solutions capture expanding margin pools as broadcasters and government communication departments automate approval chains for time-sensitive content releases. On-Premises installations persist among defense-adjacent entities and certain Saudi healthcare networks with data sovereignty requirements that preclude offshore server locations.
ADGM's digital asset framework in Abu Dhabi and DMCC's crypto commodity licensing in Dubai create overlapping compliance obligations for platforms handling tokenized media rights and NFT-adjacent content provenance. SAMA's operational resilience standards and Bahrain's CBB crypto asset rules extend regulatory touchpoints into backup, disaster recovery, and audit trail specifications that DAM vendors must satisfy. Stakeholders should monitor how VARA's evolving Dubai virtual asset regulations and potential Saudi CMA digital securities guidance will reshape platform architecture requirements for content tokenization and fractionalized media ownership structures.
Market Dynamics
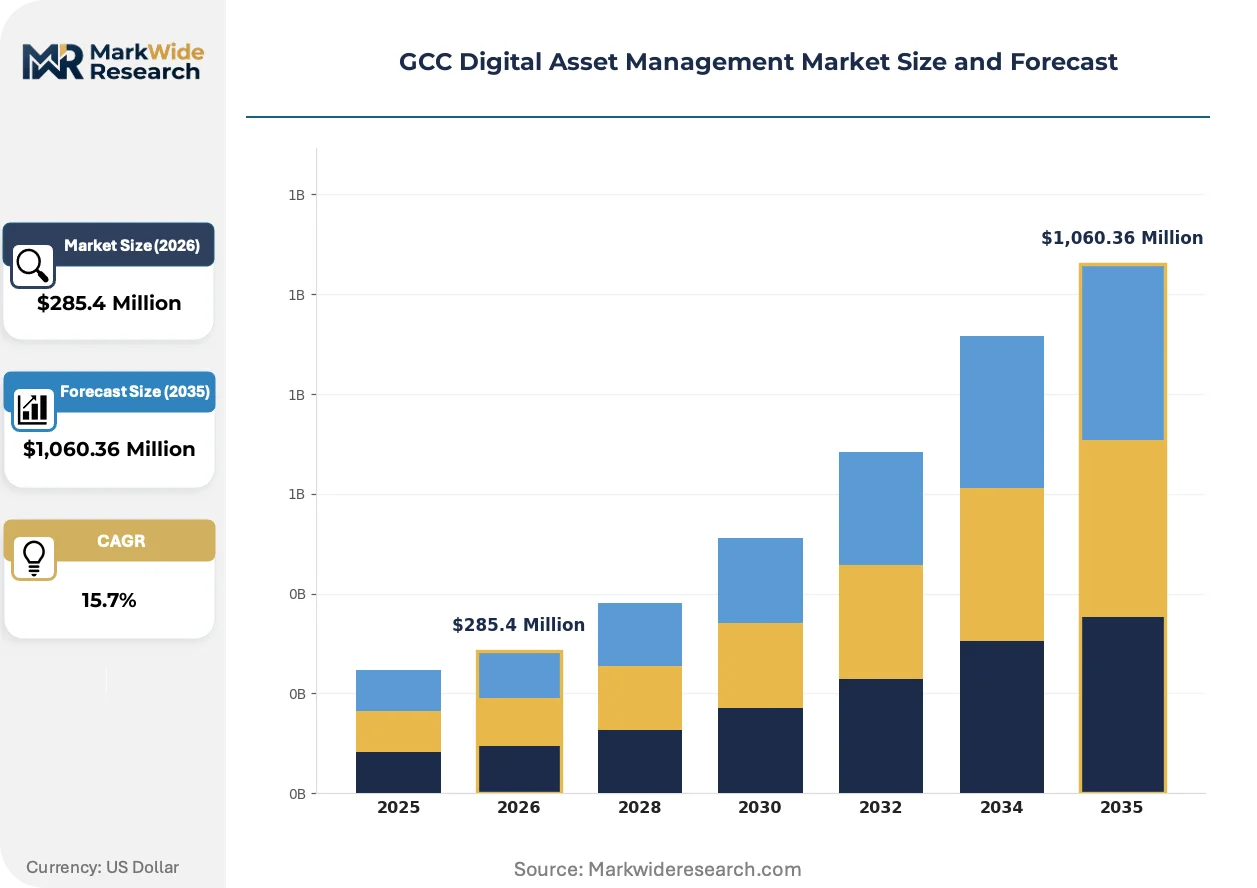
Cloud migration mandates from UAE and Saudi financial regulators are compressing procurement cycles, forcing sovereign wealth funds and media conglomerates to consolidate vendor relationships around platforms that satisfy ADGM, DMCC, and SAMA compliance obligations simultaneously.
Growth Catalysts
- Cloud Migration Mandates:SAMA's operational resilience standards and UAE central bank directives require financial institutions to migrate off legacy storage, creating immediate DAM procurement windows for vendors with compliant cloud architectures.
- 4K/8K Video Pipeline Expansion:Dubai Media City and Abu Dhabi Media Zone broadcasters are scaling production infrastructure, generating elastic storage demand that on-premises server farms cannot satisfy cost-effectively.
- Tokenized Media Rights Frameworks:VARA's evolving Dubai virtual asset regulations and ADGM's digital asset framework are legitimizing NFT-adjacent content provenance, opening DAM platform extensions for fractionalized media ownership tracking.
Market Restraints
- Data Sovereignty Requirements:Defense-adjacent Saudi entities and select healthcare networks operate under strict data localization rules that preclude offshore cloud server locations, limiting addressable market for pure-SaaS vendors.
- Integration Complexity:Legacy on-premises media asset management systems at established Gulf broadcasters require costly middleware development for API connectivity with modern cloud-native platforms.
- Talent Scarcity:Metadata architecture and automated workflow engineering expertise concentrates in Dubai and Riyadh, creating deployment bottlenecks for projects in secondary GCC cities.
Strategic Opportunities
- Oman and Bahrain Market Entry:Underpenetrated mid-market enterprises in Muscat and Manama lack dedicated DAM procurement committees, creating first-mover advantages for SaaS vendors with localized Arabic-language interfaces.
- Workflow Automation Unbundling:Government communication departments in Saudi Arabia and UAE are separating approval-chain automation from core storage contracts, opening standalone workflow module sales.
- AI-Powered Metadata Tagging:Convergence of computer vision and natural language processing is enabling automated descriptive indexing for Arabic-language video content, reducing manual cataloging labor costs by half.
Industry Challenges
- Multi-Jurisdictional Compliance Burden:Platforms must simultaneously satisfy ADGM's crypto asset custody rules, VARA's virtual asset framework, and SAMA's operational resilience standards, extending certification timelines.
- Legacy System Entrenchment:Established media conglomerates operate hybrid on-premises and cloud environments, forcing vendors to maintain dual deployment expertise and support structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Digital Asset Management Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $1,060.36 Million |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premises, Hybrid, Managed Services End User: Media & Entertainment, Retail, Healthcare, Education Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Solution: Digital Rights Management, Content Distribution, Workflow Automation, Analytics |
| Companies Covered | Binance, BitOasis, CoinMENA, ADGM, DMCC, Emirates NBD, Bynder, Adobe, Canto, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Digital Asset Management Market Strategic Shifts & Innovations
Metadata automation and AI-driven content indexing are compressing manual cataloging workflows across Gulf media operations. Sovereign wealth technology investments are accelerating platform modernization while regulatory convergence around virtual assets is reshaping architecture requirements.
AI-powered descriptive indexing is overtaking manual Arabic-language transcription and tagging workflows at Dubai and Abu Dhabi broadcasters. Media free zone enterprises are deploying computer vision models trained on regional content libraries to auto-generate searchable metadata. This capability is compressing content-to-archive cycles from days to hours, enabling same-day publishing workflows for time-sensitive news and entertainment releases.
VARA's Dubai virtual asset regulations and ADGM's digital asset framework are mandating immutable audit trails for tokenized media rights transactions. Platform vendors must now integrate blockchain-adjacent provenance logging alongside traditional DAM functionality. Financial services and media conglomerate procurement committees are prioritizing vendors with pre-certified compliance architectures, disqualifying legacy providers lacking modular audit capabilities.
Mid-market retail chains across Riyadh and Jeddah are consolidating omnichannel content operations under single DAM procurement decisions. Previously siloed e-commerce, physical retail, and social media teams are merging technology budgets to eliminate duplicate asset storage. This concentration is favoring SaaS vendors with native Arabic localization and regional data residency options over global providers with offshore server dependencies.
GCC Digital Asset Management Market Segmentation
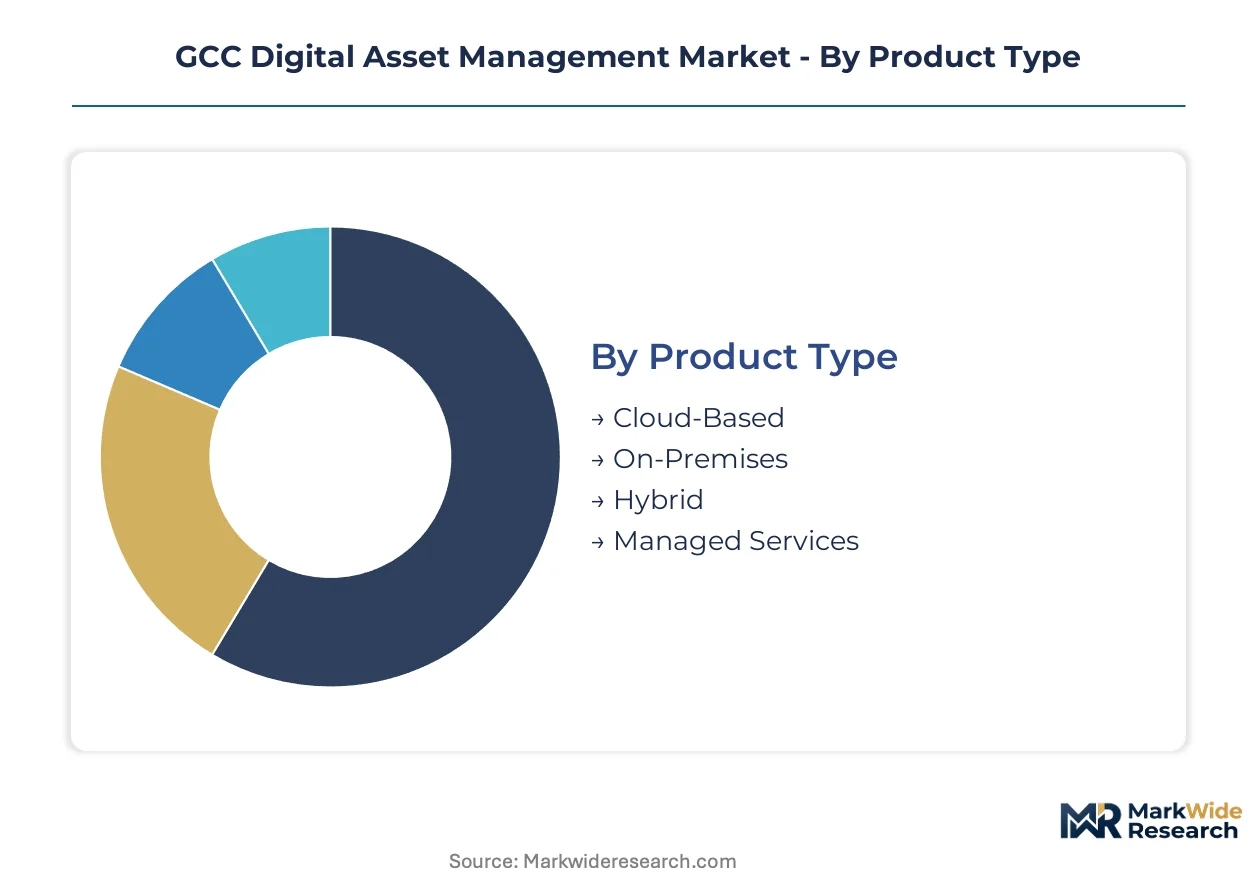
Segmentation in the GCC Digital Asset Management market reveals how procurement decisions split across technical architecture choices, regulatory compliance requirements, and content pipeline complexity. Understanding these divides exposes where vendor specialization creates defensible positioning versus where horizontal platforms capture cross-vertical contracts.
Product Type:
Technical architecture determines capital commitment cycles and operational control boundaries for Gulf enterprises managing exponential media growth.
- Cloud-Based:Elastic storage architectures eliminate server farm capital expenditure while enabling 4K and 8K video pipeline scaling. Dubai Media City broadcasters and Abu Dhabi sovereign wealth technology ventures dominate procurement, driven by SAMA and UAE central bank cloud migration mandates that compress vendor selection timelines.
- On-Premises:Dedicated hardware installations maintain complete data sovereignty and physical access control. Defense-adjacent Saudi entities and select healthcare networks in Riyadh and Jeddah mandate these deployments under strict data localization rules that preclude offshore server locations.
- Hybrid:Split architectures retain sensitive assets on local infrastructure while pushing distribution workloads to elastic cloud tiers. Government communication departments use this model to balance audit trail requirements with campaign velocity demands.
- Managed Services:Outsourced platform operation transfers maintenance burden to vendor specialists. Mid-market retail chains across Oman and Bahrain prefer this option to bypass scarce metadata engineering talent in secondary GCC cities.
Cloud-Based leads on scale; Managed Services leads on momentum.
End User:
Content velocity and regulatory exposure create divergent procurement priorities across vertical applications.
- Media & Entertainment:Broadcasters and production houses in Dubai Media City and Abu Dhabi Media Zone manage terabyte-scale daily ingest from 4K and emerging 8K sources. Workflow automation demands dominate RFP specifications as same-day publishing windows compress from days to hours.
- Retail:Omnichannel operators across Riyadh and Jeddah consolidate previously siloed e-commerce, physical store, and social media asset repositories. Arabic-language localization and regional data residency options determine vendor shortlists.
- Healthcare:Saudi hospital networks and UAE medical centers enforce patient data separation from marketing content workflows. On-premises or private cloud deployments satisfy data sovereignty requirements that pure-SaaS architectures cannot meet.
- Education:Universities and vocational institutes generate moderate-volume instructional media with limited rights complexity. Cost-sensitive procurement favors standardized SaaS tiers over customized enterprise implementations.
Media & Entertainment commands the largest contract values; Retail exhibits the steepest expansion trajectory.
Deployment Model:
Infrastructure control granularity and multi-jurisdictional compliance obligations shape platform architecture selection.
- Public Cloud:Shared infrastructure delivers lowest unit storage costs and automatic scaling. Financial institutions under UAE and Saudi regulatory cloud migration mandates accelerate procurement of these architectures.
- Private Cloud:Single-tenant environments isolate workloads while retaining cloud operational models. Saudi defense-adjacent entities and healthcare networks deploy these to satisfy data localization without reverting to legacy on-premises maintenance.
- Hybrid Cloud:Policy-driven workload placement routes sensitive processing to private tiers and burst capacity to public pools. Media conglomerates use this to protect pre-release content while enabling global distribution scale.
- Multi-Cloud:Redundant deployment across independent provider infrastructures eliminates single-vendor dependency. Sovereign wealth technology investments increasingly specify these architectures for operational resilience compliance.
Public Cloud dominates current procurement volume; Multi-Cloud is gaining share fastest among new enterprise deployments.
Solution:
Functional module unbundling creates standalone sales opportunities as procurement committees separate workflow automation from core storage contracts.
- Digital Rights Management:Permission protocol engines enforce usage boundaries across distributed teams and external partners. VARA's Dubai virtual asset regulations and ADGM's digital asset framework mandate immutable audit trails that extend traditional DRM into blockchain-adjacent provenance logging.
- Content Distribution:Accelerated delivery networks optimize rich media transmission across geographically dispersed endpoints. Broadcasters in Dubai Media City prioritize these modules to support same-day publishing workflows for time-sensitive releases.
- Workflow Automation:Approval chain engines route assets through stakeholder review sequences with automated escalation. Government communication departments in Saudi Arabia and UAE unbundle these from storage contracts, opening standalone module sales.
- Analytics:Usage pattern and performance dashboards inform content strategy and archive optimization decisions. Media conglomerates deploy these to identify underutilized assets for monetization or retirement.
Workflow Automation leads on new contract momentum; Digital Rights Management carries the highest compliance-driven premium pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UAE commands larger DAM contract values than Saudi Arabia, yet Riyadh's sovereign wealth technology investments are compressing procurement cycles faster. Bahrain and Oman remain underpenetrated, creating first-mover openings for SaaS vendors with Arabic localization.
United Arab Emirates
Dubai Media City broadcasters and Abu Dhabi sovereign wealth funds drive elastic cloud storage demand for 4K and 8K video pipelines. ADGM's digital asset framework and VARA's virtual asset regulations mandate immutable audit trails for tokenized media rights. Dubai's media free zones concentrate buyer clusters where procurement committees prioritize pre-certified compliance architectures.
Saudi Arabia
SAMA's operational resilience standards force financial institutions off legacy storage, creating immediate DAM procurement windows. Defense-adjacent entities and select healthcare networks in Riyadh and Jeddah enforce strict data localization rules that preclude offshore cloud servers. NEOM's technology investments and Riyadh's media conglomerates are consolidating vendor relationships around hybrid deployment models.
Bahrain
Mid-market enterprises in Manama lack dedicated DAM procurement committees, opening first-mover advantages for SaaS vendors. The Central Bank of Bahrain's crypto asset rules extend compliance touchpoints into backup and disaster recovery specifications that platforms must satisfy. Bahrain's financial services sector is migrating to cloud architectures under regulatory pressure, though at smaller contract values than UAE or Saudi peers.
Oman
Retail chains and government communication departments in Muscat generate moderate-volume DAM demand with limited legacy system entrenchment. The country's national technology regulator has issued cloud migration guidance without mandatory deadlines, extending sales cycles compared to UAE and Saudi markets. Oman's underpenetrated status favors vendors offering managed services to bypass scarce metadata engineering talent.
Qatar
Sovereign wealth-backed media ventures and education sector procurement drive DAM adoption in Doha. The Qatar Central Bank's operational standards for financial institutions create compliance obligations similar to SAMA's framework. Lusail's smart city infrastructure and Education City's digital transformation programs are consolidating content operations under single platform decisions.
GCC Digital Asset Management Market Key Industry Players
US-based software giants anchor one tier; European and regional specialists hold differentiated positions in compliance-heavy segments. Market structure tilts toward ecosystem lock-in, with broadcasters and advertising agencies consolidating around integrated creative suites rather than standalone storage platforms. Two strategic archetypes dominate: full-stack creative cloud providers and modular SaaS vendors with Arabic localization. Competitive moves center on certification pre-qualification for ADGM and VARA frameworks, plus workflow automation unbundling to capture standalone module sales.
Within the compliance-heavy tier, Binance leverages its regional licensing through Bahrain and Dubai frameworks to anchor institutional custody discussions adjacent to DAM infrastructure. Adobe and Bynder occupy positions at opposite ends of the deployment spectrum: Adobe exemplifies ecosystem lock-in among Gulf broadcasters through Creative Cloud integration, while Bynder represents mid-market SaaS specialization for retail chains expanding omnichannel operations across Riyadh and Jeddah.
| Leading Market Players |
|---|
| Binance |
| BitOasis |
| CoinMENA |
| ADGM |
| DMCC |
| Emirates NBD |
| Bynder |
| Adobe |
| Canto |
| Others |
Cost & Logistics Intelligence
Sovereign wealth technology ventures and media conglomerate procurement committees in Dubai and Riyadh concentrate buying power, compressing vendor margins through multi-year enterprise contracts that bundle storage, workflow automation, and compliance certification into single-source agreements.
Pricing Analysis
Capacity additions in UAE and Saudi cloud regions are reshaping price floors for elastic storage tiers as hyperscaler competition intensifies. Three-tier pricing structure across premium, standard, and economy levels separates sovereign wealth-backed deployments with dedicated infrastructure from mid-market SaaS subscriptions and managed service bundles for retail chains. Cost compression in standard tiers stems from hyperscaler price wars for financial services migrations under SAMA and UAE central bank mandates. Mid-market retail chains in secondary GCC cities exhibit highest price sensitivity, while defense-adjacent entities accept premium positioning for data sovereignty guarantees.
Supply Chain Analysis
Cloud infrastructure supply rests on hyperscaler data center investments concentrated in UAE, Saudi Arabia, and Bahrain. Compute hardware draws from Taiwanese semiconductor foundries, enterprise storage arrays feed from South Korean and Japanese component manufacturers, and specialized AI accelerators hinge on US and Chinese chip design houses. Single-source vulnerability runs through advanced GPU allocations for AI-powered metadata tagging workloads. Distribution runs through direct enterprise sales teams serving sovereign wealth funds and media free zones, supplemented by regional system integrators for mid-market deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC Digital Asset Management market functions as a regulatory compounder where ADGM's digital asset framework and VARA's evolving virtual asset regulations create successive procurement windows as compliance deadlines force platform refreshes.
For Market Incumbents: Anticipate margin compression from hyperscaler-backed challengers entering workflow automation segments by hardening certification moats around ADGM, VARA, and SAMA compliance architectures. Defensive consolidation moves center on acquiring Arabic-language AI metadata specialists and embedding blockchain-adjacent provenance logging as standard modules rather than premium add-ons. For New Entrants and Emerging Players: Enter via underpenetrated mid-market enterprises in Oman and Bahrain where dedicated DAM procurement committees remain absent and managed services bypass scarce technical talent. White-space targets include standalone workflow automation modules for Saudi government communication departments and AI-powered Arabic content indexing for education sector deployments. Go-to-market positioning emphasizes rapid deployment timelines and localized Arabic interfaces over feature depth. For Investors and Strategic Acquirers: Sovereign wealth technology funds are the most active acquirer in this space, consolidating vendor relationships around platforms satisfying multi-jurisdictional compliance obligations simultaneously. Long-term viability favors modular SaaS architectures with pre-certified compliance stacks over legacy on-premises providers facing integration complexity penalties. The signal to watch is VARA's final virtual asset custody rules, which will disqualify non-compliant platforms from media rights tokenization opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Certification Pre-Qualification | ADGM and VARA certifications open sovereign wealth procurement channels closed to uncertified rivals. |
| AI Metadata Engine Acquisition | Computer vision specialists trained on Arabic content libraries compress manual cataloging labor costs. |
| Workflow Automation Unbundling | Standalone approval-chain modules capture government communication department budgets separate from storage. |
| Regional Data Center Expansion | In-country server presence satisfies Saudi data localization requirements that preclude offshore cloud. |
| Blockchain Provenance Integration | Immutable audit trails for tokenized media rights align with VARA's virtual asset regulatory mandates. |
Research Approach
Multiple input streams — primary interviews with DAM procurement officers and platform engineers, secondary validation through regulatory filings and hyperscaler capex disclosures, and trade data on enterprise software imports — were reconciled through bottom-up and top-down triangulation. Stakeholder interviews encompassed CTOs at Dubai Media City broadcasters, IT procurement leads at Saudi retail conglomerates, integration specialists serving government communication departments, and compliance officers navigating ADGM and VARA frameworks. Secondary sources included SAMA operational resilience standards, VARA virtual asset consultation papers, UAE central bank cloud migration directives, and enterprise software spending patterns from regional technology distributors.
Historical spending trajectories were cross-referenced against panel input from procurement committees to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled encompass deployment architecture, end-use vertical, solution module type, and regional regulatory cluster complexity. CAGRs were derived from elasticity-adjusted adoption curves reflecting compliance deadline impacts and cloud migration mandate timing. Industry-specific forecast inputs incorporated 4K and 8K video pipeline scaling ratios, tokenized media rights transaction volume assumptions, and AI metadata automation penetration rates.
The model holds under stable regulatory enforcement timelines and continued hyperscaler data center investment in the region; deviation in VARA final rule issuance delays or Saudi data localization scope expansion would shift platform architecture demand materially. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Assets and Cryptocurrency Finance
Digital Currency Wallet Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency Exchanges Market
Digital Assets and Cryptocurrency Finance
Asset Tokenization Software Market
Digital Assets and Cryptocurrency Finance
Tokenization Solution Market
Digital Assets and Cryptocurrency Finance
Bitcoin Trading Software Market
Digital Assets and Cryptocurrency Finance
Online Microtransaction Market
Digital Assets and Cryptocurrency Finance
Global Hardware Wallets Market
Digital Assets and Cryptocurrency Finance
Virtual Currency Market
Digital Assets and Cryptocurrency Finance
Trading Data Platform Market
Digital Assets and Cryptocurrency Finance
Automated Trading Market
Digital Assets and Cryptocurrency Finance
Digital Asset Management (DAM) Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency Atms Market
Digital Assets and Cryptocurrency Finance
Bitcoin Market
Digital Assets and Cryptocurrency Finance
South Korea Online Trading Platform Market
Digital Assets and Cryptocurrency Finance
United States Digital Asset Management Market
Digital Assets and Cryptocurrency Finance
Spain Online Trading Platform Market