
 Malt Beverages Market | 2026-2036
Malt Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Malt Beverages Market Foresight
Single-source barley procurement is decoupling from traditional agricultural contracting across the malt beverages supply base. Anheuser-Busch InBev leverages captive malting facilities across multiple continents to secure base malt supply. Molson Coors Beverage Company anchors North American production through integrated brewing and packaging complexes. Heineken N.V. competes via distributed sourcing networks that blend regional barley varieties with specialty malt imports.
Malt beverages are fermented drinks produced from germinated cereal grains, primarily barley, through controlled kilning and mashing processes that convert starches to fermentable sugars, yielding alcohol content typically ranging from 0.5% to 8.0% ABV depending on style and attenuation. The lager segment dominates volume globally due to its crisp flavor profile and suitability for mass-scale continuous fermentation, while ale production sustains premium positioning through top-fermentation complexity and shorter conditioning cycles. Cans are displacing bottles in packaging type mix as aluminum recycling infrastructure matures and outdoor consumption occasions expand across retail and event channels.
FDA oversees alcohol labeling and ingredient disclosure requirements in the United States, while EFSA and national regulators across Europe enforce maximum residue limits for brewing additives and pesticide traces in malted grains. BIS in India mandates packaging standards and quality certifications for domestically distributed malt beverages, creating compliance thresholds for imported brands. Stakeholders must monitor evolving low-alcohol taxation frameworks and carbon accounting mandates that will determine facility investment priorities and regional market entry sequencing.
Market Dynamics
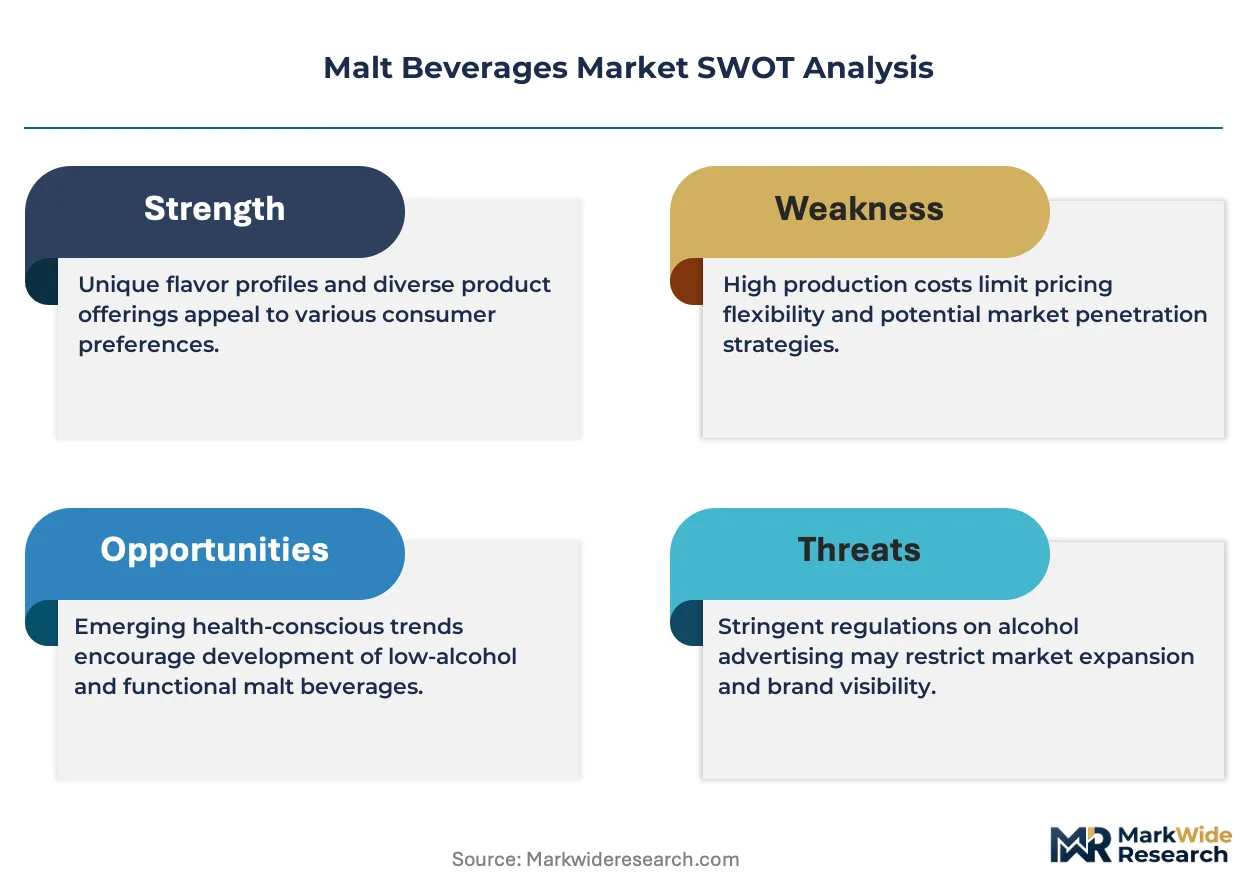
Clean-label ingredient mandates and low-alcohol taxation reforms are compressing formulation cycles across malt beverage portfolios, forcing producers to revalidate supply chains and accelerate R&D pipelines before regulatory deadlines crystallize.
Growth Catalysts
- EFSA additive residue limits:European brewers are reformulating with natural hop extracts and organic malt to preempt compliance thresholds, creating premium positioning for certified-clean products.
- Aluminum recycling infrastructure:Can packaging adoption is accelerating as circular-economy mandates in Germany and Brazil reward lightweight, infinitely recyclable formats over glass.
- Gen-Z on-premise consumption:Experience-driven drinking occasions in Vietnam and Nigeria are pulling craft lager and session ale volumes through modern trade channels.
Market Restraints
- Barley procurement concentration:Australian and Canadian malting barley supply is tightening due to climate volatility, exposing brewers to input cost spikes and contract renegotiation cycles.
- FDA labeling disclosure friction:Alcohol content precision requirements and allergen declaration rules are extending product launch timelines for imported brands entering US distribution.
- Non-alcoholic substitutes:Functional beverages and adaptogenic drinks are capturing occasion share among health-conscious millennials, particularly in urban coastal markets.
Strategic Opportunities
- Brazil middle-class expansion:São Paulo and Rio de Janeiro retail modernization is creating shelf space for premium imported lagers and local craft acquisitions.
- EU Green Deal carbon accounting:Brewery facility decarbonization incentives are enabling capital-efficient retrofitting of kilning and fermentation operations.
- E-commerce direct-to-consumer channels:Subscription-based craft beer platforms are bypassing traditional three-tier distribution in markets with relaxed shipping regulations.
Industry Challenges
- Master brewer talent scarcity:Specialized fermentation science and sensory evaluation expertise is concentrating at established producers, constraining craft scale-up capacity.
- Legacy ERP integration:Batch-tracking and quality-management software from the 2000s is creating data silos that obstruct real-time supply chain visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malt Beverages Market |
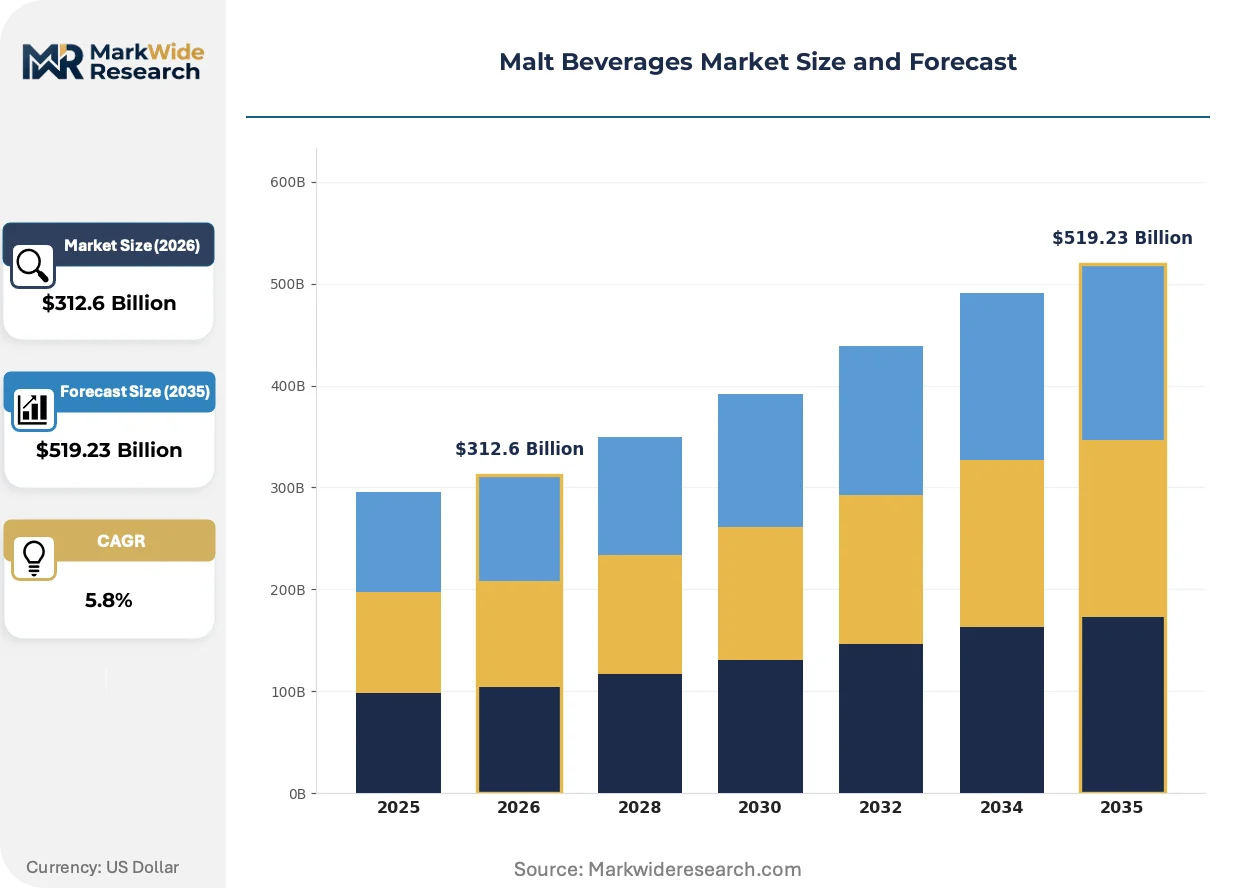
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $519.23 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pilsner, Lager, Ale, Stout Packaging Type: Bottles, Cans, Kegs, Draught End User: Retail Stores, Bars, Restaurants, Events Flavor Profile: Hoppy, Malty, Fruity, Spicy |
| Companies Covered | Molson Coors Beverage Company, China Resources Snow Breweries, Anheuser-Busch InBev, Boston Beer Company, Constellation Brands, Heineken N.V., Carlsberg Group, Asahi Group Holdings, Diageo plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malt Beverages Market Shifts & Advancements
Precision fermentation and enzyme engineering are collapsing traditional malting timelines, while regulatory carbon-footprint disclosure is embedding sustainability metrics into core product specifications.
Continuous fermentation technology is electrifying production economics for mid-scale brewers. Automated bioreactor systems from Switzerland and Denmark are enabling consistent lager output with 40% smaller facility footprints. Brazilian and Vietnamese producers are piloting these systems to bypass capital-intensive brewhouse construction.
REACH chemical safety registrations are tightening scrutiny on brewing aids and cleaning agents across European production facilities. ECHA substance evaluations are forcing reformulation of caustic sanitizers and foam-control additives. German and Czech producers are shifting to enzyme-based cleaning protocols to maintain operational licenses.
On-premise draft systems are fragmenting buyer concentration as micro-distribution networks proliferate. Independent taproom operators in Nigeria and Vietnam are sourcing directly from regional craft breweries, bypassing national wholesalers. This channel shift is most pronounced in Lagos and Ho Chi Minh City, where experiential consumption venues are multiplying.
Malt Beverages Market Segmentation
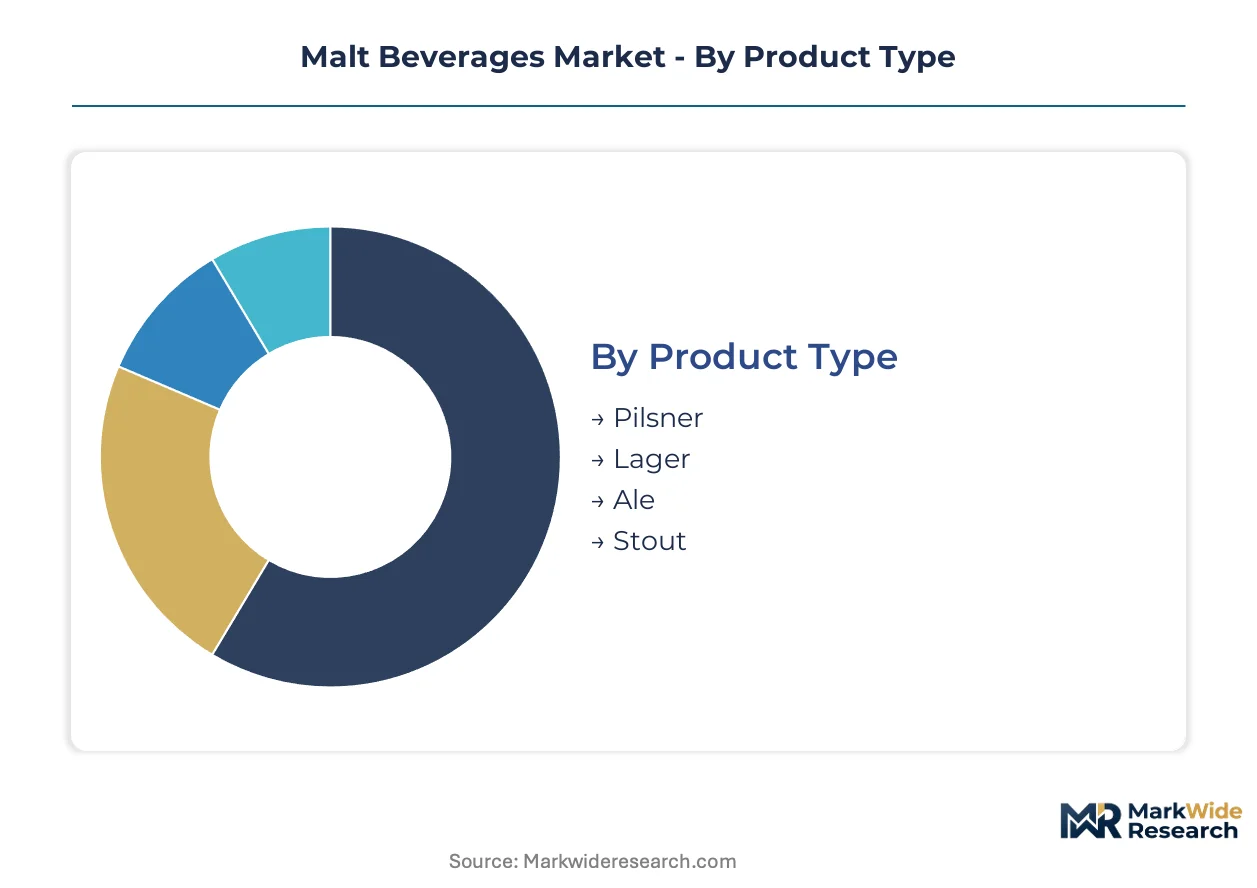
Malt beverage producers configure production lines around fermentation protocols and packaging formats that lock in capital deployment for decades. Segment boundaries determine where brewing conglomerates concentrate capacity investments versus where craft operators find entry points.
Product Type:
Lager and ale production systems demand the heaviest upfront capital outlays due to temperature-controlled fermentation infrastructure and extended conditioning cellars.
- Lager:Bottom-fermentation at near-freezing temperatures requires dedicated glycol-chilled tanks and extended lagering periods. Brazilian and Vietnamese brewers are scaling lager capacity to serve middle-class consumers migrating from informal alcohol to branded products. Most installed capacity flows through lager. Expansion is steepest in ale.
- Ale:Top-fermentation completes at ambient temperatures with shorter turnaround cycles, enabling smaller brewhouse footprints. Nigerian craft taprooms in Lagos are pulling session ale volumes through direct distribution networks that bypass national wholesalers.
- Pilsner:Pale lager subtype with soft water chemistry requirements and Saaz hop specifications.
- Stout:Dark roasted malt base with higher original gravity and nitrogen-widget packaging options.
Ale volumes are climbing the fastest as craft positioning commands price premiums in urban on-premise channels.
Packaging Type:
Packaging choice directly shapes logistics economics and recycling compliance burdens across distribution territories.
- Cans:Aluminum formats align with circular-economy mandates in Germany and Brazil, where lightweight infinite recyclability earns regulatory preference over glass. São Paulo retailers are expanding shelf facings for canned imports as local recycling infrastructure matures.
- Bottles:Glass packaging retains premium positioning in European hospitality settings where refillable deposit systems reduce per-use environmental cost. Ho Chi Minh City restaurants still specify long-neck bottles for formal dining occasions.
- Kegs:Stainless steel returnable containers dominate draft supply to bars and events with high throughput velocity.
- Draught:Direct-to-tap dispensing requires cold-chain infrastructure and line-cleaning protocols that concentrate with specialized service providers.
Can lines absorb the majority of new packaging investment. Draught distribution is expanding most quickly in experiential venue clusters.
End User:
Channel selection determines margin capture and working capital intensity through payment terms and inventory holding requirements.
- Bars:On-premise draft systems generate highest per-liter margins but require dedicated sales teams and line maintenance contracts. Nigerian independent taprooms in Lagos source directly from regional craft breweries, fragmenting traditional wholesaler concentration.
- Restaurants:Food-pairing occasions drive premium bottle and can placements with slower inventory turns but lower spoilage risk.
- Retail Stores:Off-premise volume concentrates in modern trade chains with centralized procurement and extended payment cycles.
- Events:Festival and stadium concessions demand mobile dispensing equipment and temporary licensing compliance.
Bar channels command the highest throughput per outlet. Event distribution is gaining share fastest as experiential consumption occasions multiply.
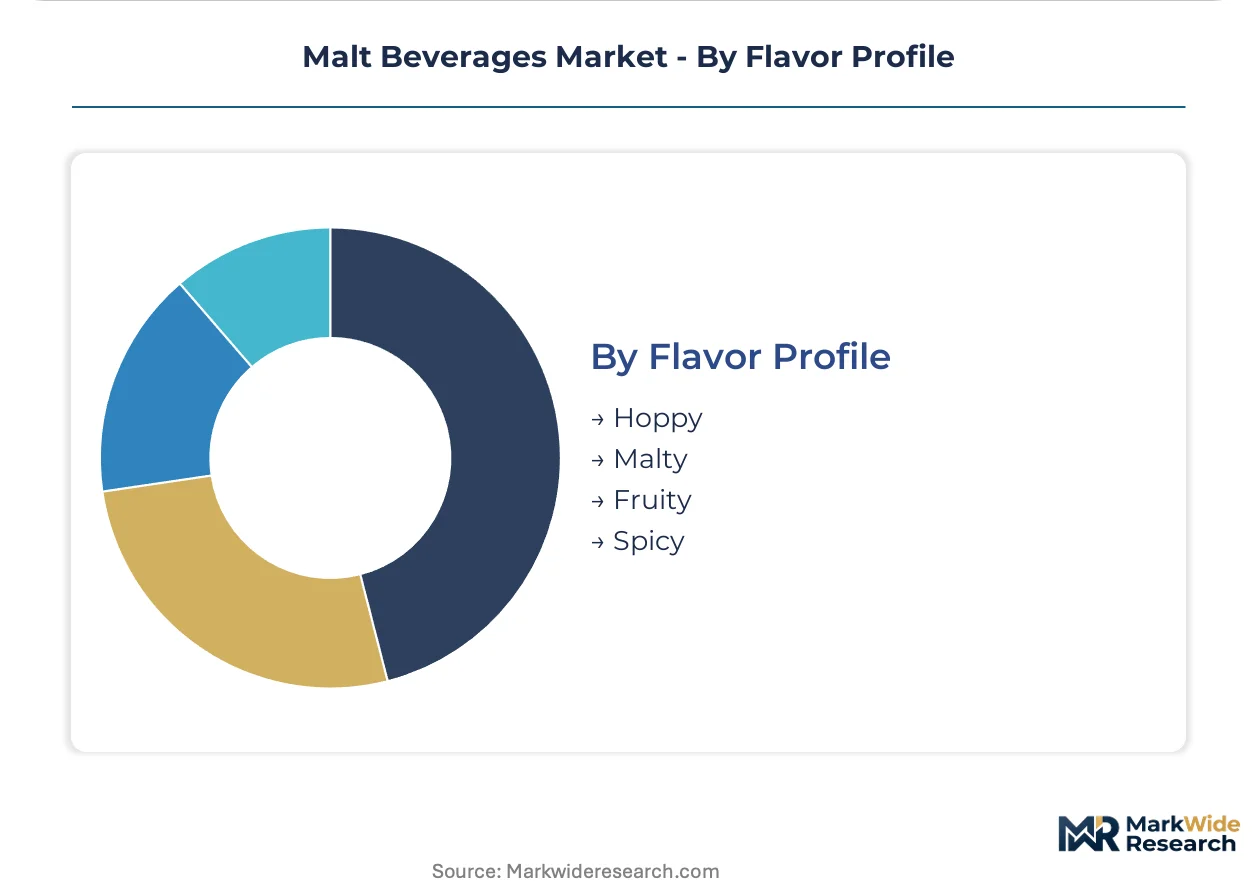
Flavor Profile:
Flavor positioning maps to raw material sourcing strategies and hop procurement contracts that lock in multi-year supply security.
- Hoppy:Elevated bitterness units require aggressive late-addition hopping and dry-hopping protocols that compress brewhouse utilization rates. German producers are reformulating with natural hop extracts to satisfy EFSA additive residue thresholds.
- Malty:Caramel and Munich malt varieties depend on specific kilning profiles that tie producers to captive malting facilities or long-term barley contracts.
- Fruity:Ester-forward profiles from expressive yeast strains appeal to entry-level craft consumers in Vietnamese urban markets.
- Spicy:Phenolic character from Belgian-style yeast requires precise fermentation temperature control to avoid off-flavor production.
Hoppy formulations anchor the most installed brewing capacity. Fruity profiles are expanding most quickly among Gen-Z trialists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting malt beverage investment toward jurisdictions with favorable low-alcohol taxation frameworks and streamlined carbon accounting protocols. Brazil and Vietnam attract capacity expansion due to compliance cost gaps versus European benchmarks. Nigeria leverages informal-to-formal trade conversion without equivalent excise burdens.
Brazil
São Paulo and Rio de Janeiro retail modernization drives premium lager and craft ale demand through expanding modern trade channels. ANVISA packaging standards and quality certifications create compliance thresholds that favor established importers with laboratory testing capabilities. Minas Gerais brewing clusters are absorbing regional craft acquisitions as independent producers seek scale economies.
Germany
EU Green Deal carbon accounting mandates accelerate brewery facility decarbonization investments across Bavaria and North Rhine-Westphalia. EFSA additive residue limits force reformulation toward natural hop extracts and organic malt sourcing. Munich and Hamburg production complexes anchor premium pilsner capacity serving hospitality refillable deposit systems.
Vietnam
Ho Chi Minh City experiential consumption venues multiply draft system installations for session ales and fruity craft lagers. BIS-equivalent national standards govern domestically distributed malt beverage quality certifications. Da Nang and Hanoi urban clusters pull volume through micro-distribution networks bypassing traditional national wholesalers.
Nigeria
Lagos independent taprooms source directly from regional craft breweries, fragmenting traditional wholesaler concentration in Africa's largest malt beverage market. National food and drug administration regulations mandate packaging standards for imported brands entering formal distribution. Abuja and Port Harcourt modern trade expansion creates shelf space for premium canned imports.
United States
FDA alcohol labeling precision requirements and allergen declaration rules extend product launch timelines for imported brands entering multi-state distribution. Pacific Northwest and Colorado craft brewing clusters concentrate specialized fermentation science talent. California and New York retail channels absorb the majority of low-alcohol innovation trials targeting health-conscious millennials.
Malt Beverages Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue craft positioning and regional micro-distribution. The market structures around three maturity tiers: multinational brewing conglomerates with captive malting networks, mid-scale regional operators with distributed sourcing, and craft specialists with direct-to-taproom channels. Consolidation pressure concentrates among lager volume leaders, while ale and specialty segments fragment across localized entrants. Dominant competitive moves include craft brewery acquisitions and continuous fermentation technology licensing.
Within the multinational tier, Anheuser-Busch InBev and Heineken N.V. exemplify divergent sourcing architectures—captive malting facilities versus blended regional and specialty import networks. Molson Coors Beverage Company anchors North American production through integrated brewing and packaging complexes. These three entities represent distinct strategic archetypes: vertical supply control, distributed sourcing flexibility, and regional production integration.
| Leading Market Players |
|---|
| Molson Coors Beverage Company |
| China Resources Snow Breweries |
| Anheuser-Busch InBev |
| Boston Beer Company |
| Constellation Brands |
| Heineken N.V. |
| Carlsberg Group |
| Asahi Group Holdings |
| Diageo plc |
| Others |
Supply & Pricing Matrix
Malting barley contract prices flow from Australian and Canadian agricultural futures through captive malting facilities to premium lager pricing tiers, with climate volatility compressing margins at standard-economy levels while organic certification commands shelf-space premiums in German and Brazilian modern trade channels.
Pricing Analysis
Input-cost pass-through from kilning energy and specialty hop procurement is reshaping tier boundaries across the malt beverage landscape. Three-tier pricing structure across premium, standard, and economy levels separates craft ale positioning from mass lager volumes, with EFSA additive residue thresholds and organic malt certification emerging as the primary price differentiation drivers. Pricing pressure stems from barley procurement concentration as Australian drought cycles tighten supply security, leaving economy-tier buyers most price-sensitive while premium craft consumers absorb formulation cost increases.
Supply Chain Analysis
Returnable keg flows and aluminum can recycling loops are embedding circular-economy compliance into logistics economics across European and Brazilian distribution networks. Supply concentrates in Australia, Canada, and Germany for malting barley, with specialty Saaz and Hallertau hop varieties drawing from Czech and German agricultural zones. Single-source vulnerability concentrates around climate-exposed barley regions, while downstream distribution runs through three-tier wholesale systems in the United States and direct-to-taproom micro-networks in Nigeria and Vietnam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The malt beverage market reads as a late-cycle quality story where millennial and Gen-Z demand is migrating toward low-alcohol certified-clean formulations that command permanent price premiums over standard lager tiers.
For Market Incumbents: Hedge barley procurement exposure through multi-continent captive malting capacity or long-term contract structures with Australian and Canadian agricultural cooperatives. Accelerate organic malt certification investment to preempt EFSA residue limit enforcement and defend shelf positioning against craft entrants exploiting clean-label positioning. Channel control through direct taproom ownership in Lagos and Ho Chi Minh City fragments wholesaler concentration.
For New Entrants and Emerging Players: Enter via session ale and fruit-forward craft lager segments in Vietnamese and Nigerian urban clusters where experiential consumption venues multiply faster than national wholesaler coverage. São Paulo modern trade expansion creates white-space for premium canned imports with ANVISA laboratory testing capabilities already established. Direct-to-consumer subscription platforms bypass three-tier friction in markets with relaxed interstate shipping regulations.
For Investors and Strategic Acquirers: Roll-up economics work for regional craft breweries with established taproom networks because Nigerian and Vietnamese micro-distribution fragmentation prevents national-scale organic growth. Target acquisition archetypes include Minas Gerais brewing clusters with existing quality certifications and sensory evaluation talent. Watch for inflection in continuous fermentation technology licensing volumes as Brazilian and Vietnamese producers pilot capital-efficient brewhouse alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Malting Facility Expansion | Anheuser-Busch InBev leverages multi-continent base malt supply security against climate volatility. |
| Organic Malt Certification Investment | EFSA additive residue thresholds force German producers toward certified-clean premium positioning. |
| Direct-to-Taproom Channel Development | Lagos independent venues fragment Nigerian wholesaler concentration through micro-distribution networks. |
| Continuous Fermentation Licensing | Swiss and Danish bioreactor systems enable Brazilian producers to bypass capital-intensive brewhouse construction. |
| Aluminum Can Line Conversion | German circular-economy mandates reward lightweight infinite recyclability over glass packaging formats. |
Research Methodology
Multiple input streams — primary interviews with master brewers and fermentation science directors, secondary validation through customs records and ANVISA quality certification databases, and triangulation across EFSA additive residue filings — were reconciled to construct bottom-up volume estimates and top-down market sizing for malt beverage segments across the analysis window.
Data-stream reconciliation anchored forecasting models on fermentation protocol segmentation, packaging format economics, and end-user channel margin structures throughout the projection horizon. CAGRs were derived from trend extrapolation of craft ale penetration rates, aluminum can adoption curves, and low-alcohol formulation trial volumes across Brazilian, Vietnamese, and Nigerian urban consumption clusters.
Inputs from EFSA enforcement timelines and FDA labeling precision requirements were available through the study window; gaps in real-time barley futures contract transparency introduce uncertainty bands around input cost assumptions. Forecasts reflect documented base-case assumptions regarding climate volatility patterns and excise taxation trajectories; periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Japanese Whisky Market
Alcoholic Beverages
Ouzo Market
Alcoholic Beverages
High-End Chinese Spirits Market
Alcoholic Beverages
Uganda Spirits Market
Alcoholic Beverages
Gluten Free Alcoholic Drinks Market
Alcoholic Beverages
Beer Brewing Machine Market
Alcoholic Beverages
Pinot Noir Market
Alcoholic Beverages
Rice Wine Market
Alcoholic Beverages
Crystal Malt Market
Alcoholic Beverages
Kegs Market
Alcoholic Beverages
Global Hard Seltzers Market
Alcoholic Beverages
US Frozen Cocktail Popsicles Market
Alcoholic Beverages
Sake and Plum Wine Market
Alcoholic Beverages
Asia-Pacific Tequila Market
Alcoholic Beverages
Beer Adjuncts Market
Alcoholic Beverages
Craft Wine Market