
 Dysphagia Supplements Market | 2026-2036
Dysphagia Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Dysphagia Supplements Market Analysis
Home care settings is broadening as the fastest-expanding end-use vertical for dysphagia supplements, shifting volume away from institutional channels. Nestlé Health Science leverages its clinical nutrition heritage to anchor premium positioning across European and North American home care networks. Abbott Laboratories competes through R&D intensity in condition-specific formulations. Kent Precision Foods Group specializes in texture-modified solutions for post-stroke and neurodegenerative patient cohorts.
Dysphagia supplements comprise texture-modified nutritional products engineered with controlled viscosity, typically measured in centipoise, to enable safe swallowing for patients with oropharyngeal motility disorders. These formulations integrate hydrocolloid thickeners such as xanthan gum or modified starch at precise concentrations to achieve International Dysphagia Diet Standardisation Initiative levels. Nutritional drinks command the largest revenue pool due to their complete macronutrient profile and ease of administration in acute care. Thickening agents represent the fastest-growing product type as clinicians seek flexible, dose-controlled viscosity modification for individualized patient protocols. Liquid formulations dominate hospital procurement, while powders gain traction in home care for shelf stability and cost efficiency.
The FDA exercises oversight through food additive regulations and medical food labeling requirements, while the European Medicines Agency coordinates with national health technology assessment bodies on reimbursement eligibility for prescribed nutrition. Japan's Ministry of Health, Labour and Welfare maintains stringent viscosity classification standards under its Foods for Specified Health Uses framework, directly influencing export formulation requirements. Stakeholders must monitor evolving reimbursement codes for texture-modified products across Medicare, Medicaid, and national health systems, as coverage determinations will dictate channel economics and patient access trajectories.
Market Dynamics
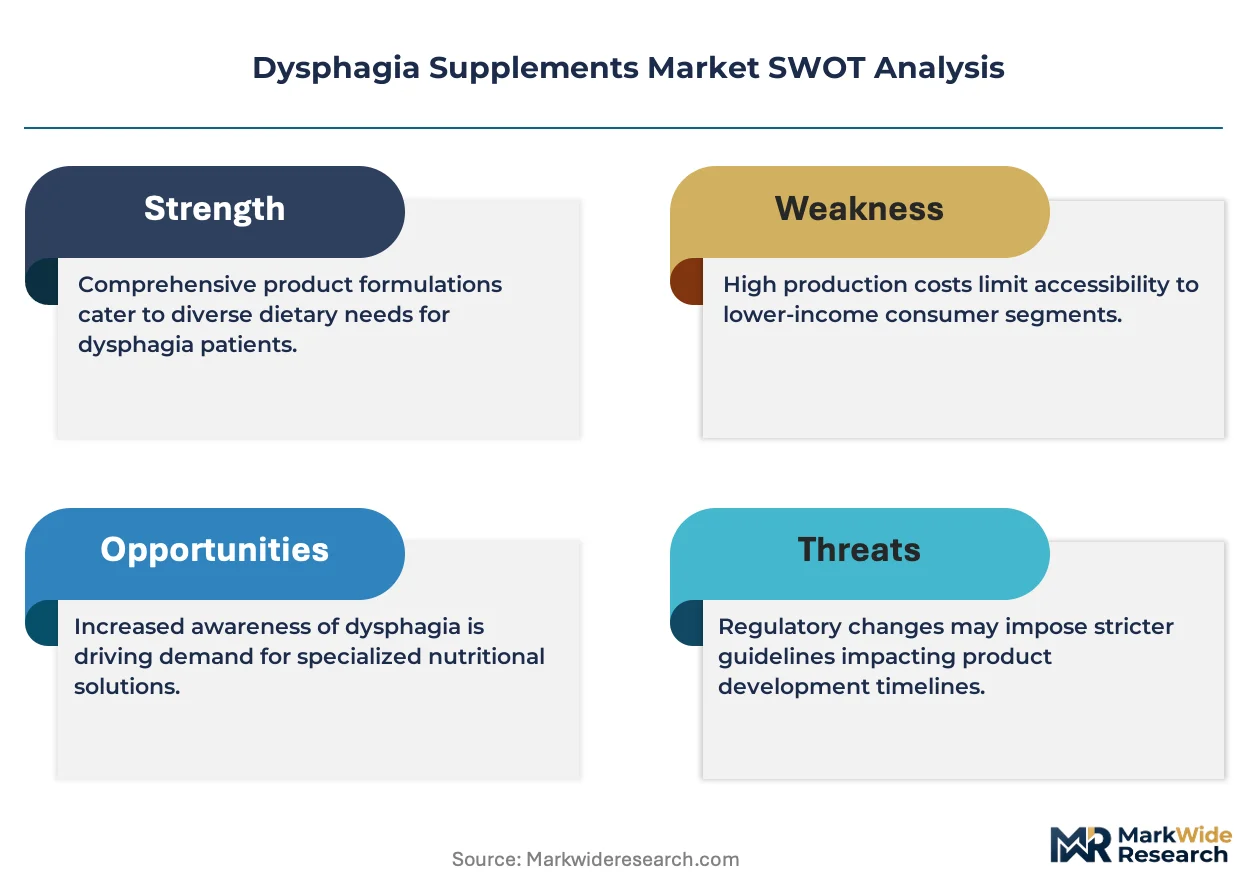
The FDA's updated labeling requirements for thickened products are compressing formulation cycles across manufacturers while simultaneously elevating quality barriers that favor scaled clinical nutrition portfolios over commodity producers.
Growth Catalysts
- Post-acute care infrastructure:Specialized nutrition protocols in United States rehabilitation centers are institutionalizing dysphagia supplement procurement as standard discharge planning.
- IDDSI framework adoption:The International Dysphagia Diet Standardisation Initiative's viscosity classification system is harmonizing cross-border product specifications and reducing regulatory friction for exporters.
- Xanthan gum processing advances:Modified hydrocolloid production techniques are enabling precise centipoise control at lower additive concentrations, improving patient palatability compliance.
Market Restraints
- Hydrocolloid input volatility:Xanthan gum and modified starch prices fluctuate with agricultural commodity cycles, compressing margin structures for mid-tier manufacturers lacking backward integration into fermentation capacity.
- Japan's FOSHU viscosity mandates:The Ministry of Health, Labour and Welfare's Foods for Specified Health Uses framework imposes testing protocols that add 12-18 months to product registration timelines for foreign entrants.
- Enteral nutrition substitution:Percutaneous endoscopic gastrostomy tube feeding protocols in severe neurodegenerative cases are displacing oral dysphagia supplements in institutional settings.
Strategic Opportunities
- Home care channel expansion:Direct-to-patient distribution models are bypassing traditional hospital procurement, capturing margin previously allocated to group purchasing organizations.
- Powder formulation shelf stability:Dry thickeners with 24-month stability profiles are penetrating rural and emerging markets where cold-chain infrastructure for ready-to-drink products remains underdeveloped.
- Medicare Advantage supplemental benefits:United States private plan flexibility for over-the-counter nutrition products is creating reimbursement pathways previously restricted to prescription medical foods.
Industry Challenges
- IDDSI compliance certification:Third-party viscosity verification laboratories face capacity constraints, extending product validation timelines and delaying commercial launches.
- Cross-functional formulation expertise:The intersection of food science, clinical nutrition, and swallowing physiology requires talent pools that remain concentrated in academic medical centers rather than commercial R&D departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dysphagia Supplements Market |
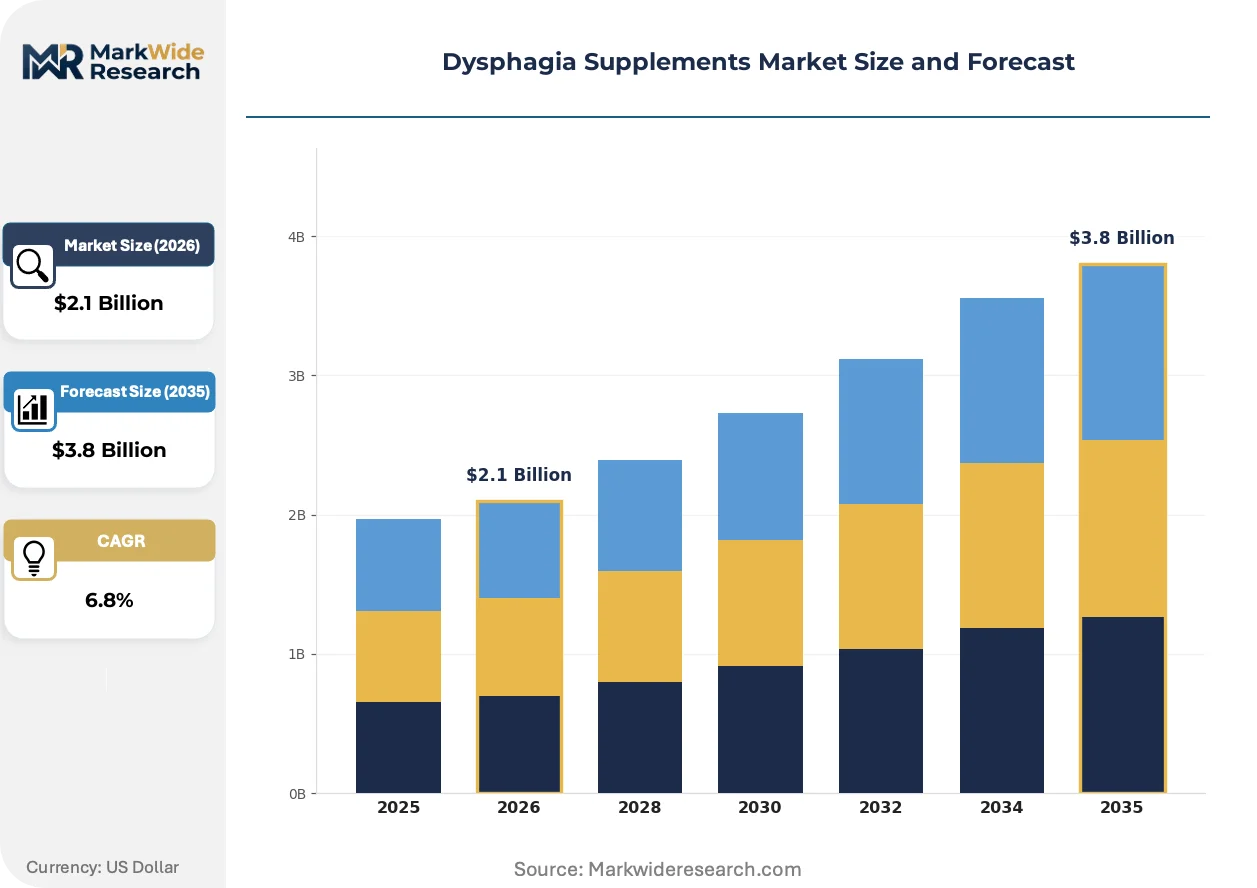
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nutritional Drinks, Thickening Agents, Bars, Powders End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Application: Healthcare, Elderly Care, Pediatric Care, Dietary Management Form: Liquid, Powder, Gel, Semi-Solid |
| Companies Covered | Abbott Laboratories, Nestlé Health Science, Danone S.A., Kent Precision Foods Group, Fresenius Kabi, Hormel Health Labs, Medtrition Inc., Saraya Co. Ltd., SimplyThick, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dysphagia Supplements Market Emerging Trajectories
Texture-modified nutrition is undergoing functional diversification beyond basic safety compliance, with manufacturers embedding sensorial and nutritional enhancements that transform dysphagia supplements from medical necessities into preference-driven consumption choices.
Precision hydrocolloid blending technology is expanding into the dysphagia supplement category as the dominant innovation vector. These systems enable real-time viscosity adjustment at the point of care rather than factory-fixed formulations. Hospital foodservice directors are piloting programmable dispensing units that customize thickness levels to individual swallow study results. The technology is expanding into home care settings through smartphone-connected thickeners that guide caregivers through measured preparation.
Europe's Medical Device Regulation (MDR) reclassification of certain enteral nutrition interfaces is creating spillover compliance requirements for dysphagia supplement packaging and delivery systems. Manufacturers serving EU markets must now document biocompatibility testing for spouted pouches and adaptive drinking vessels used with thickened products. German and French notified bodies are interpreting these requirements most stringently, forcing reformulation of closure mechanisms and label adhesives.
Hospital procurement departments are consolidating dysphagia supplement purchasing into broader clinical nutrition contracts, eroding standalone product line viability. Group purchasing organizations are bundling texture-modified beverages with enteral formulas and oral nutrition supplements into single-source agreements. This consolidation is most advanced in United States integrated delivery networks, where supply chain rationalization targets have eliminated redundant SKU proliferation across affiliated facilities.
Dysphagia Supplements Market Segmentation
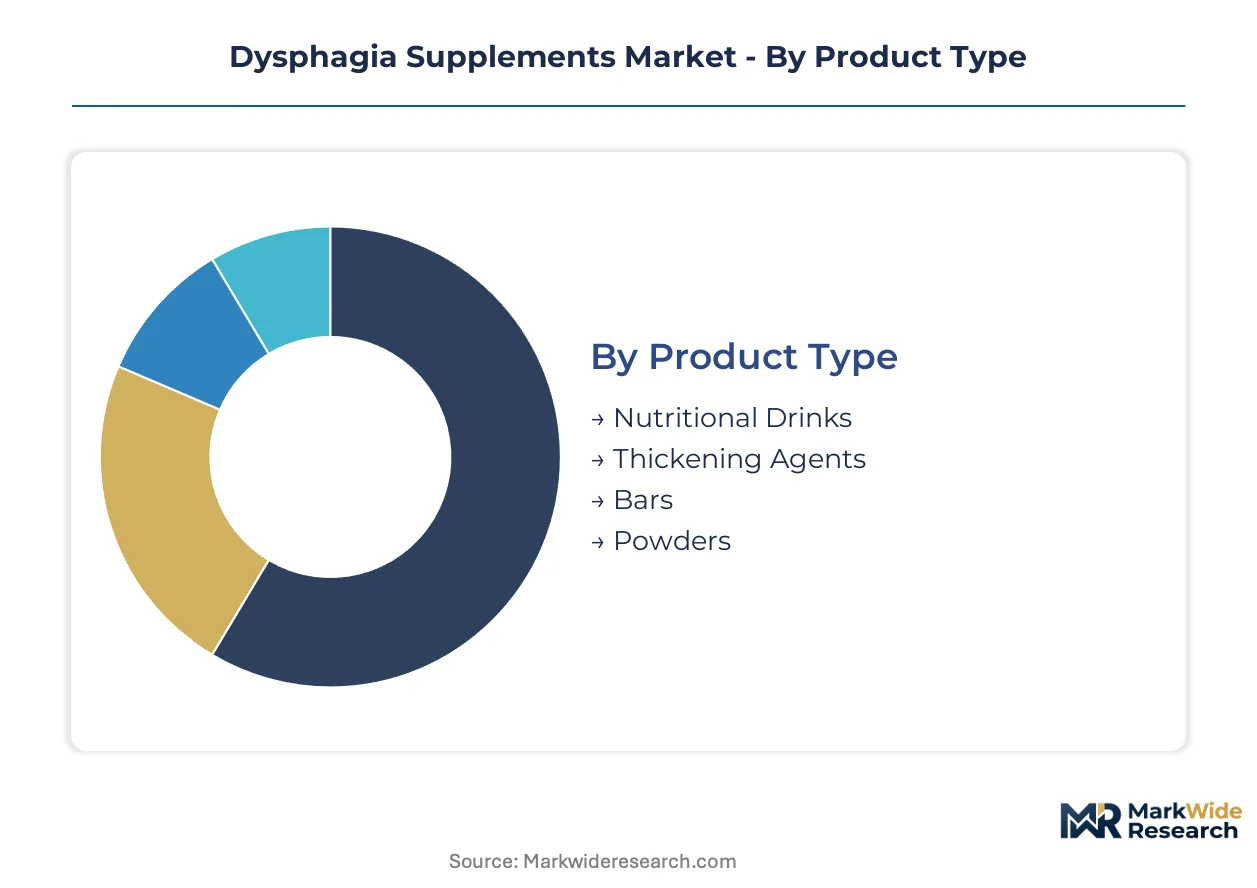
Dysphagia supplement segmentation reflects the tension between standardized viscosity protocols and patient-specific formulation needs. Manufacturers must balance IDDSI compliance requirements with flexible delivery systems that accommodate diverse swallowing pathologies across care settings.
Product Type:
Customization versus standardization spans this category from ready-to-use beverages to clinician-controlled additives.
- Nutritional Drinks:Complete macronutrient formulations with pre-calibrated viscosity levels, typically 150-400 centipoise for IDDSI Level 2-3 compliance. Demand concentrates in United States acute care hospitals where discharge planning protocols mandate standardized thickened nutrition. Medicare reimbursement codes for medical foods reinforce procurement volume in post-acute settings.
- Thickening Agents:Hydrocolloid-based powders or liquids enabling point-of-care viscosity modification. Xanthan gum and modified starch variants allow dose-controlled thickening for individualized swallow study results. Home care adoption accelerates as caregivers seek flexibility beyond factory-fixed formulations.
- Bars:Semi-solid texture-modified nutrition with integrated binding systems for patients tolerating spoon-thick consistencies.
- Powders:Dry concentrate formulations requiring reconstitution, valued for extended shelf stability and reduced shipping costs.
Leading the category by volume: Nutritional Drinks. Growing fastest: Thickening Agents.
End User:
Channel economics shift dramatically from institutional procurement to direct-to-patient distribution.
- Hospitals:Centralized purchasing through group buying organizations, with formulary committees dictating viscosity specifications and brand selection.
- Clinics:Outpatient swallowing assessment centers driving prescription volume for take-home thickening protocols.
- Home Care:The fastest-expanding channel as aging-in-place preferences redirect volume from institutional settings. Direct distribution models capture margin previously allocated to supply chain intermediaries.
- Rehabilitation Centers:Post-acute facilities in United States markets where specialized nutrition protocols anchor discharge readiness criteria.
Institutional channels dominate current procurement value. Home care demonstrates the steepest expansion trajectory.
Application:
Clinical indication severity determines formulation intensity and reimbursement eligibility.
- Healthcare:Acute and subacute medical settings managing dysphagia secondary to stroke, trauma, or surgical intervention. IDDSI framework compliance is non-negotiable.
- Elderly Care:Age-related oropharyngeal motility decline in long-term care facilities and community-dwelling populations. Palatability challenges drive flavor innovation and temperature-stable formulations.
- Pediatric Care:Congenital or developmental swallowing disorders requiring micronutrient-dense, age-appropriate flavor profiles and smaller volume protocols.
- Dietary Management:Condition-specific nutrition for diabetes, renal disease, or protein-energy malnutrition with concurrent dysphagia.
Elderly care generates the largest patient population. Healthcare settings command the highest per-patient formulation expenditure.
Form:
Physical state dictates supply chain requirements and preparation complexity at the point of use.
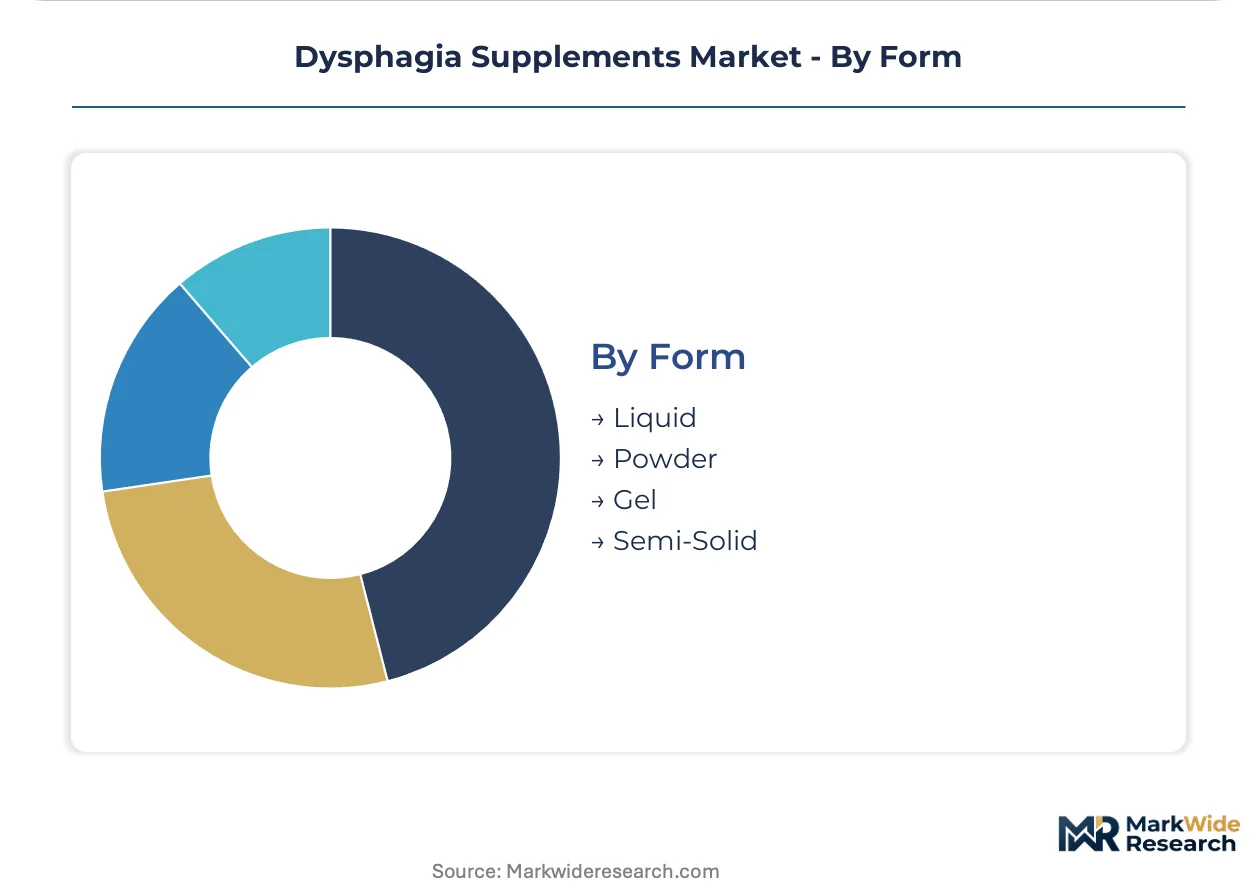
- Liquid:Ready-to-drink formulations with factory-calibrated viscosity, dominant in hospital foodservice where labor minimization priorities override per-unit cost premiums. Cold-chain dependence limits rural penetration.
- Powder:Dry concentrates with 18-24 month stability profiles, gaining traction in home care and emerging markets where refrigeration infrastructure is underdeveloped. Caregiver preparation error risk requires clear measurement guidance.
- Gel:Pre-thickened water and beverage bases with consistent rheological properties, valued for hydration protocols in long-term care.
- Semi-Solid:Pudding or mousse textures for patients requiring spoon-thick consistencies, often used in progressive neurodegenerative conditions.
Liquid formulations lead hospital procurement. Powder formats are climbing fastest in home care channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation standards diverge sharply between producing and consuming regions. Manufacturers concentrate in jurisdictions with established clinical nutrition infrastructure, while demand growth accelerates in aging populations across developed and emerging markets alike.
United States
Post-acute care rehabilitation centers and Medicare Advantage supplemental benefits drive institutional procurement volume. The FDA maintains oversight through food additive regulations and medical food labeling requirements that compress formulation cycles. Chicago and Minneapolis anchor North American production clusters where clinical nutrition heritage supports premium positioning.
Japan
Aging-in-place preferences and stringent viscosity classification standards under the Foods for Specified Health Uses framework shape product development priorities. The Ministry of Health, Labour and Welfare imposes testing protocols that extend registration timelines for foreign entrants. Tokyo and Osaka metropolitan areas concentrate domestic formulation expertise and distribution infrastructure.
Germany
Hospital procurement consolidation and the Medical Device Regulation reclassification of enteral nutrition interfaces create spillover compliance demands. German notified bodies interpret biocompatibility requirements for packaging most stringently within the European Union. Bavaria and Baden-Württemberg host specialized hydrocolloid processing facilities serving continental markets.
United Kingdom
National Health System reimbursement pathways for prescribed nutrition and IDDSI framework adoption harmonize cross-border specifications. The Medicines and Healthcare products Regulatory Agency coordinates with health technology assessment bodies on coverage determinations. The Southeast England corridor clusters clinical nutrition R&D alongside academic medical center partnerships.
Australia
Therapeutic Goods Administration oversight of medical foods and remote healthcare delivery models for rural populations create distinct channel economics. Powder formulation shelf stability gains traction where cold-chain infrastructure remains underdeveloped. Sydney and Melbourne concentrate distribution networks serving the Pacific region.
Dysphagia Supplements Market Vendor Landscape
Top-tier vendors anchor premium clinical nutrition portfolios, while mid-tier specialists compete on texture-modified formulation flexibility. The market structure reflects tiered capabilities across hydrocolloid processing, IDDSI compliance certification, and direct-to-patient distribution infrastructure. Three archetypes dominate: diversified nutrition conglomerates with backward integration into fermentation capacity; precision hydrocolloid specialists serving post-stroke and neurodegenerative cohorts; and adaptive technology providers enabling point-of-care viscosity customization. Consolidation pressure intensifies through hospital procurement bundling and group purchasing organization contract rationalization.
Within the diversified nutrition tier, Abbott Laboratories and Nestlé Health Science exemplify scale-driven positioning anchored by clinical heritage and R&D intensity across North American and European networks. Kent Precision Foods Group occupies a specialist position representing texture-modified solution providers focused on condition-specific patient protocols. These three entities collectively illustrate the competitive spectrum from integrated clinical nutrition platforms to targeted formulation expertise.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Nestlé Health Science |
| Danone S.A. |
| Kent Precision Foods Group |
| Fresenius Kabi |
| Hormel Health Labs |
| Medtrition Inc. |
| Saraya Co. Ltd. |
| SimplyThick |
| Others |
Supply Flow & Price Mechanics
Hospital procurement consolidation through United States group purchasing organizations is compressing contract margins and forcing suppliers to absorb freight volatility while maintaining IDDSI certification standards. This buyer concentration reshapes supplier economics toward volume-scaled production and captive hydrocolloid sourcing.
Pricing Analysis
Short lead-time premiums of 15-25% apply to IDDSI-certified thickeners needed for urgent discharge protocols in United States rehabilitation centers. Three-tier pricing structure across premium, standard, and economy levels separates Nestlé and Abbott clinical nutrition portfolios from private-label alternatives. Cost compression in mid-tier powders is intensifying because of xanthan gum price volatility tied to corn fermentation feedstock cycles. Home care caregivers show highest price sensitivity, while hospital formulary committees prioritize compliance reliability over per-unit cost.
Supply Chain Analysis
Freight costs from hydrocolloid fermentation hubs in China and corn-processing centers in the United States Midwest comprise 8-12% of landed product cost for European manufacturers. Supply concentrates in Germany for precision blending equipment, the United States for modified starch production, and China for xanthan gum fermentation capacity. Raw material dependencies include corn-derived dextrose for fermentation, guar gum as a xanthan substitute, and food-grade packaging films. Single-source vulnerability in Chinese xanthan gum concentration creates tariff exposure risk. Distribution runs through hospital group purchasing organizations in North America and pharmacy wholesalers in European home care channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race. Players are pursuing captive fermentation capacity to secure xanthan gum supply against agricultural commodity cycles.
For Market Incumbents: Deepen backward integration into hydrocolloid fermentation capacity to insulate margin structures from corn price volatility. Secure exclusive IDDSI certification partnerships with third-party viscosity laboratories to extend validation timelines that block mid-tier competitors. Defend against enteral nutrition substitution in severe neurodegenerative cases by embedding dysphagia supplements into broader clinical nutrition protocols. For New Entrants and Emerging Players: Launch via direct-to-patient subscription models in United States home care channels to bypass group purchasing organization gatekeeping. Target rural Medicare Advantage populations where powder formulation shelf stability addresses cold-chain gaps. White-space opportunities concentrate in pediatric dysphagia with micronutrient-dense, flavor-optimized formulations and in smartphone-connected thickeners guiding caregiver preparation. For Investors and Strategic Acquirers: The window for entry favors precision hydrocolloid specialists with IDDSI compliance infrastructure and established clinic distribution relationships. Long-term viability hinges on consolidation into clinical nutrition platforms serving bundled procurement contracts. Watch Medicare Advantage supplemental benefit expansions for over-the-counter nutrition as the signal for reimbursement pathway liberalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive xanthan gum production insulates margins from corn price volatility in agricultural commodity markets. |
| IDDSI Compliance Certification Investment | Third-party viscosity verification partnerships create regulatory barriers that delay competitor commercial launches. |
| Direct-to-Patient Distribution Launch | Home care channel bypass captures margin previously allocated to hospital group purchasing organizations. |
| Powder Formulation Shelf Stability Extension | 24-month stability profiles penetrate rural and emerging markets where cold-chain infrastructure remains underdeveloped. |
| Medicare Advantage Reimbursement Strategy | Supplemental benefit positioning creates coverage pathways for over-the-counter nutrition products beyond prescription medical foods. |
Methodological Framework
Independent corroboration across hospital procurement managers, dysphagia clinic directors, hydrocolloid R&D scientists, and group purchasing organization contract specialists underwrites the qualitative findings. Primary interviews with foodservice directors in United States rehabilitation centers and home care nurses in Japan validated texture-modified protocol adoption patterns. Secondary sources include FDA medical food labeling guidance, EMA health technology assessment reimbursement determinations, Japan's FOSHU framework documentation, and CMS Medicare Advantage benefit filings. Bottom-up demand modeling across end-use channels triangulates against top-down macroeconomic indicators.
Comparable-period anchoring to historical discharge planning protocol adoption and IDDSI framework implementation timelines structured the forecast window. Segmentation dimensions modeled include product type, end-user channel, clinical application severity, and physical formulation state. CAGRs derive from volume-weighted growth rates across institutional and home care channels. Industry-specific inputs include xanthan gum price indices, Medicare reimbursement code expansions, and enteral nutrition substitution rates in neurodegenerative patient populations.
Regulatory delay in Japan's FOSHU registration, hydrocolloid input cost spikes, and enteral nutrition technology substitution are the dominant revision risks. Forecasts reflect assumptions about IDDSI adoption velocity and Medicare Advantage benefit liberalization trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Immunity Boosting Food Market
Nutritional Supplements
Plant Based Protein Supplements Market
Nutritional Supplements
Organic Whey Protein Market
Nutritional Supplements
Complete Nutrition Products Market
Nutritional Supplements
Europe Omega-3 Products Market
Nutritional Supplements
Middle East and Africa Omega-3 Products Market
Nutritional Supplements
Forskolin Market
Nutritional Supplements
Coq10 Gummies Market
Nutritional Supplements
Energy Supplements Market
Nutritional Supplements
Nutrient Dense Food Products Market
Nutritional Supplements
Australia Nutraceuticals Market
Nutritional Supplements
Red Yeast Rice Market
Nutritional Supplements
Global Beta Glucan Market
Nutritional Supplements
Canada Nutraceuticals Market
Nutritional Supplements
Fish Collagen Market
Nutritional Supplements
Eggshell Membrane Powder Market