
 Europe Green Wall Market | 2026-2036
Europe Green Wall Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Green Wall Market Analysis
Aftermarket service revenue is fragmenting across installation, irrigation management, and seasonal maintenance contracts as project owners seek lifecycle partners rather than one-time suppliers. Biotecture Ltd anchors its position through vertical integration across design, installation, and automated systems. Sempergreen competes with specialized moss and sedum substrates calibrated for northern European climates. GreenBlue Urban Ltd leverages its channel control through specification relationships with landscape architects in British and Dutch municipal procurement.
Green walls are engineered vegetated facade systems integrating hydroponic or soil-based growing media, automated irrigation, and structural support frameworks to deliver thermal insulation, stormwater retention, and air-quality improvement in built environments. Modular green walls lead product-type configurations due to standardized installation and replacement economics, while hydroponic systems represent the fastest-growing segment driven by water-efficiency mandates in drought-prone southern European jurisdictions. Wall-mounted installations occupy the dominant share by installation method, though freestanding systems are gaining traction in hospitality and institutional settings where lease restrictions prohibit structural facade alterations.
The EU Green Deal and national transpositions through building performance standards are reshaping demand by mandating nature-based solutions in new construction and major renovation. ECHA's REACH framework governs substrate material safety and irrigation water chemistry, while CE marking requirements for structural fixing systems filter market access for non-compliant suppliers. Stakeholders must monitor the trajectory of the EU AI Act as automated irrigation and sensor-based maintenance systems become standard specification components.
Market Dynamics
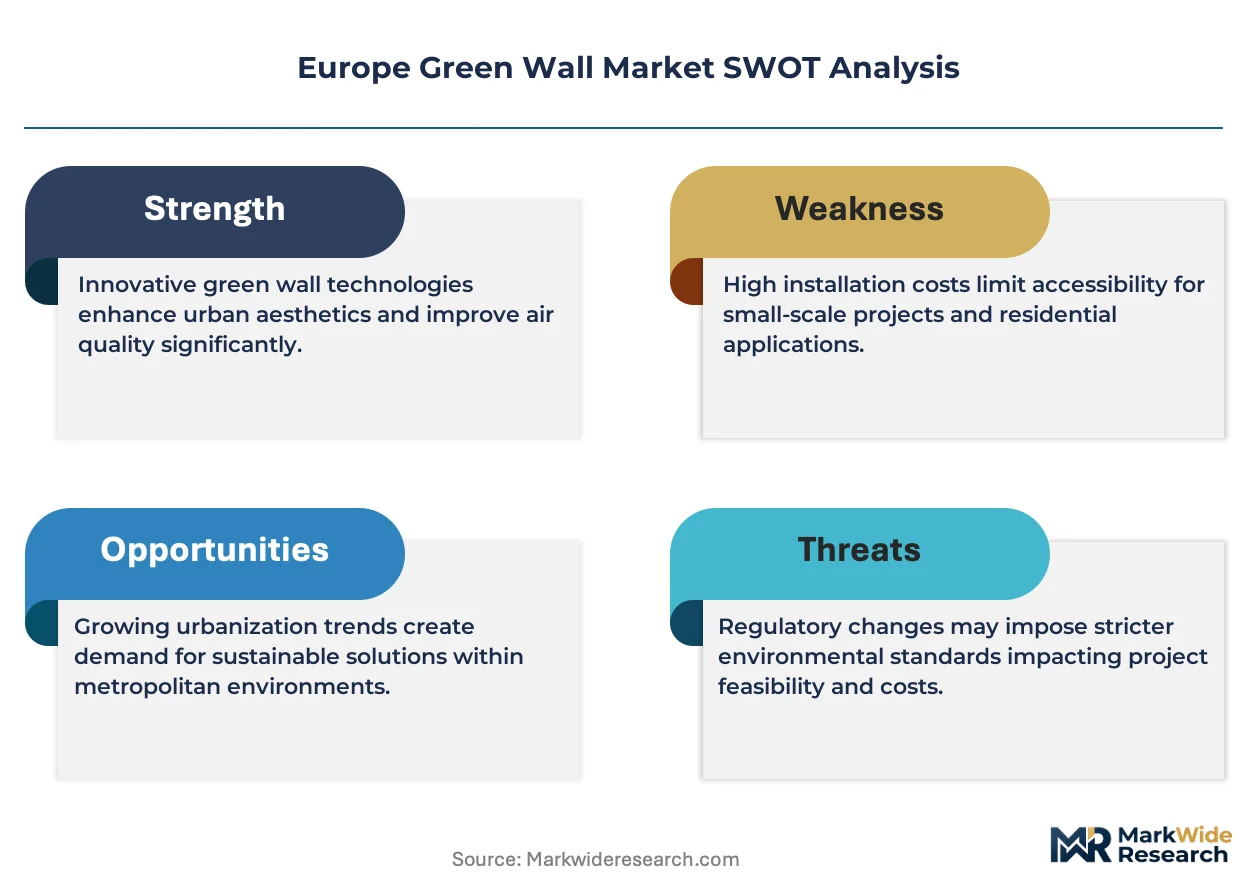
The EU Green Deal's building performance standards are compressing installation timelines for nature-based facade solutions across commercial real estate portfolios. Developers now face binding energy-efficiency mandates that elevate vegetated systems from aesthetic amenities to compliance infrastructure.
Growth Catalysts
- EU Green Deal transposition:National building codes in Germany, France, and the Netherlands now mandate nature-based solutions for major renovations, creating compliance-driven procurement pipelines.
- Rhine-Ruhr municipal greening ordinances:Advanced local mandates in Germany's industrial corridor accelerate specification of living walls in new commercial developments.
- Automated irrigation integration:Sensor-based maintenance systems reduce operational labor costs and extend plant survival rates in northern European climates.
Market Restraints
- Substrate material cost volatility:Peat and mineral wool inputs face supply pressure from ECHA REACH compliance costs and alternative demand from horticulture sectors.
- Southern European water scarcity:Irrigation restrictions in drought-prone Spanish and Italian jurisdictions limit hydroponic system deployment despite efficiency gains.
- Structural engineering complexity:Load-bearing assessments for retrofitted facades add 15-25% to project timelines compared to new construction specifications.
Strategic Opportunities
- Polish and Romanian underpenetration:Building stock modernization programs in these EU cohesion fund recipients lack established green wall supplier networks.
- EU AI Act convergence:Automated monitoring and predictive maintenance algorithms for vegetated facades qualify as high-risk AI systems, creating first-mover certification advantages.
- Hospitality freestanding systems:Lease-restricted hotel operators in Amsterdam, Paris, and Barcelona drive demand for non-structural living wall installations.
Industry Challenges
- Horticultural-technical skill scarcity:Installation crews require combined expertise in facade engineering, plant science, and irrigation automation that training pipelines have not scaled to match demand.
- CE marking timeline compression:Structural fixing systems must complete notified body assessments under accelerated project schedules, creating specification bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Green Wall Market |
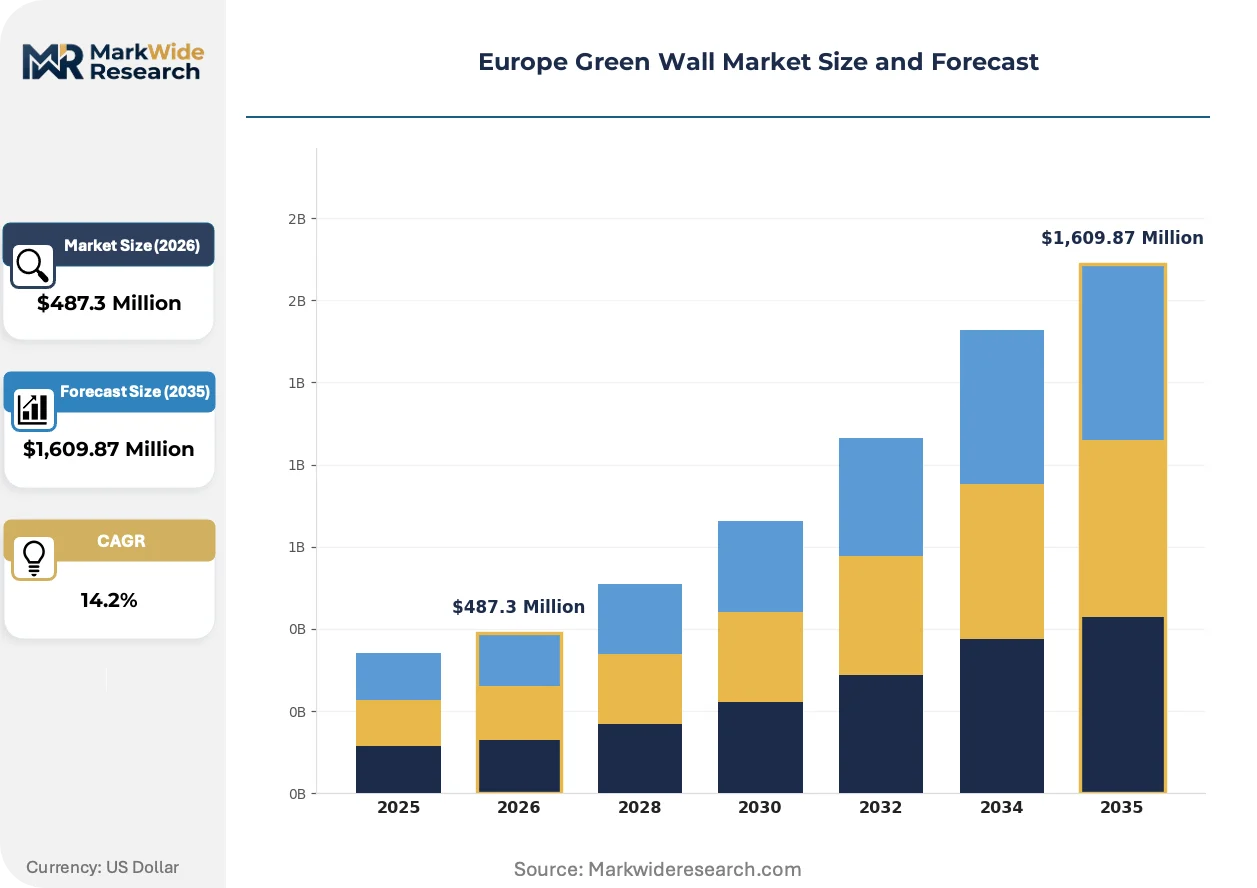
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,609.87 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Green Walls, Living Walls, Vertical Gardens, Hydroponic Systems End User: Residential, Commercial, Institutional, Hospitality Installation Method: Wall-mounted, Freestanding, Indoor, Outdoor Maintenance Type: Automated Systems, Manual Care, Seasonal Maintenance, Irrigation Management |
| Companies Covered | GSky Plant Systems Inc., Lang+Fulton, ANS Group Global Ltd., Moss Trend, Green Mood, Biotecture Ltd, Sempergreen, The Greenwall Company, GreenBlue Urban Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Green Wall Market Emerging Trajectories
Digital twin integration and substrate material science are compressing the traditional separation between design-phase visualization and operational-phase performance optimization. These converging capabilities reshape how owners evaluate lifecycle returns on vegetated facade investments.
Living facade digital twins are collapsing the information gap between architects, contractors, and facility managers. These virtual replicas simulate thermal performance, irrigation demand, and plant health trajectories before physical installation. German and Dutch engineering firms now embed twin platforms into municipal procurement specifications, forcing traditional suppliers to develop software competencies or partner with building information modeling specialists.
CE marking requirements for structural fixing systems are tightening material traceability and load-testing documentation. The framework filters market access for non-compliant suppliers while elevating specification influence for notified bodies in Germany, France, and Italy. Project owners increasingly require CE-marked components as a baseline eligibility criterion, compressing procurement shortlists to pre-certified vendors.
Facility management contracts are unbundling design-build from long-term horticultural maintenance. Property owners in London, Frankfurt, and Stockholm now tender irrigation management and seasonal plant replacement as separate service lines. This disintermediation creates openings for specialized horticultural service firms to capture recurring revenue streams that construction-phase contractors previously retained.
Europe Green Wall Market Segmentation
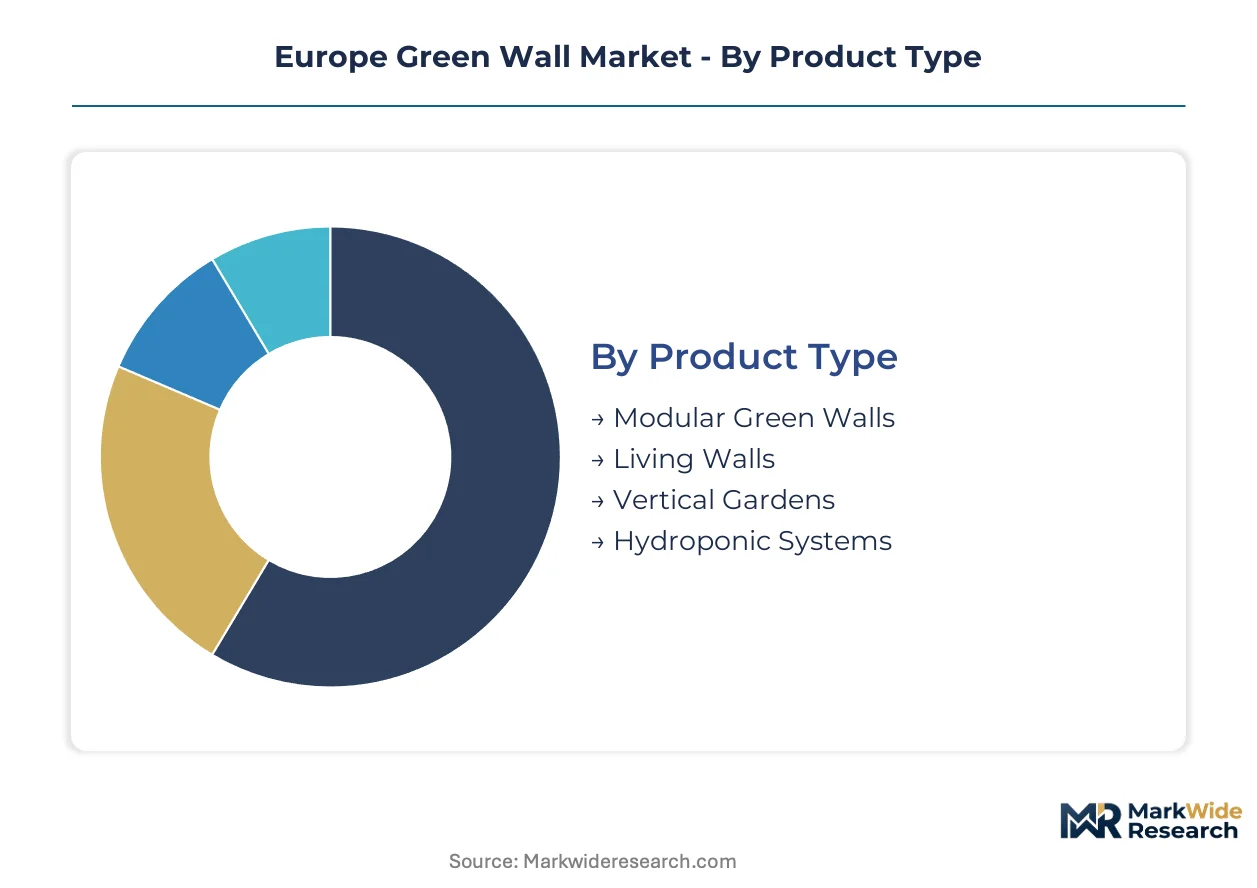
Segmentation in the Europe Green Wall Market reveals how procurement specifications diverge across building typologies and regulatory environments. Product configurations, installation constraints, and maintenance capabilities each create distinct competitive arenas with different margin profiles and lifecycle revenue potential.
Product Type:
Mature panel-based systems dominate commercial specification, while emerging hydroponic technologies capture water-efficiency mandates in southern European jurisdictions.
- Modular Green Walls:Pre-fabricated panel systems with standardized growing media and integrated irrigation channels enable rapid installation and component replacement. German and Dutch commercial developers specify these for Rhine-Ruhr and Rhine-Main office portfolios where municipal greening ordinances mandate compliance-ready facade solutions.
- Hydroponic Systems:Soil-free configurations circulate nutrient solutions through closed-loop irrigation, reducing water consumption by substantial margins versus substrate-based alternatives. Spanish and Italian procurement in drought-prone regions increasingly requires these systems despite higher capital costs, driven by irrigation restrictions under national water scarcity protocols.
- Living Walls:Engineered vegetated facades with soil-based growing media deliver thermal mass and stormwater retention for northern European climates.
- Vertical Gardens:Aesthetic-focused installations emphasizing plant variety and visual impact for hospitality and retail environments.
Modular Green Walls handle the majority of throughput; Hydroponic Systems are gaining share fastest.
End User:
Procurement scale separates institutional clients with multi-year maintenance contracts from residential buyers seeking one-time installation services.
- Commercial:Office and retail asset managers across Germany, France, and the Netherlands specify living walls as compliance infrastructure under EU Green Deal building performance standards. These clients demand lifecycle partnerships covering design, installation, and automated maintenance rather than transactional supplier relationships.
- Institutional:Municipal buildings, educational facilities, and healthcare campuses in Stockholm, Copenhagen, and Vienna integrate green walls into net-zero carbon strategies with 20-year operational horizons. Public procurement frameworks prioritize CE-marked structural components and documented substrate safety under ECHA REACH compliance.
- Hospitality:Hotels in Amsterdam, Paris, and Barcelona deploy freestanding systems where lease restrictions prohibit facade alterations.
- Residential:High-net-worth individual installations concentrate in London, Munich, and Zurich premium developments.
Commercial commands the largest project pipeline; Institutional offers the longest contract durations.
Installation Method:
Structural integration requirements create a cost tier separating permanent facade attachments from movable non-structural alternatives.
- Wall-mounted:Direct structural attachment to building envelopes delivers maximum thermal insulation and stormwater retention performance. German engineering firms specify these for new construction where load-bearing assessments occur during design phase, avoiding the 15-25% timeline compression penalties of retrofit projects.
- Freestanding:Self-supporting frameworks bypass structural engineering complexity for lease-restricted properties and temporary installations. Amsterdam hospitality operators and Paris retail landlords favor these where building ownership or heritage regulations prohibit permanent facade modifications.
- Indoor:Climate-controlled environments enable exotic plant species and year-round performance regardless of external weather conditions.
- Outdoor:Exterior installations face seasonal plant replacement cycles and irrigation automation requirements across variable European climates.
Wall-mounted absorbs the greatest installation volume; Freestanding climbs fastest on share.
Maintenance Type:
Service unbundling is fragmenting revenue streams between construction-phase contractors and specialized horticultural operators.
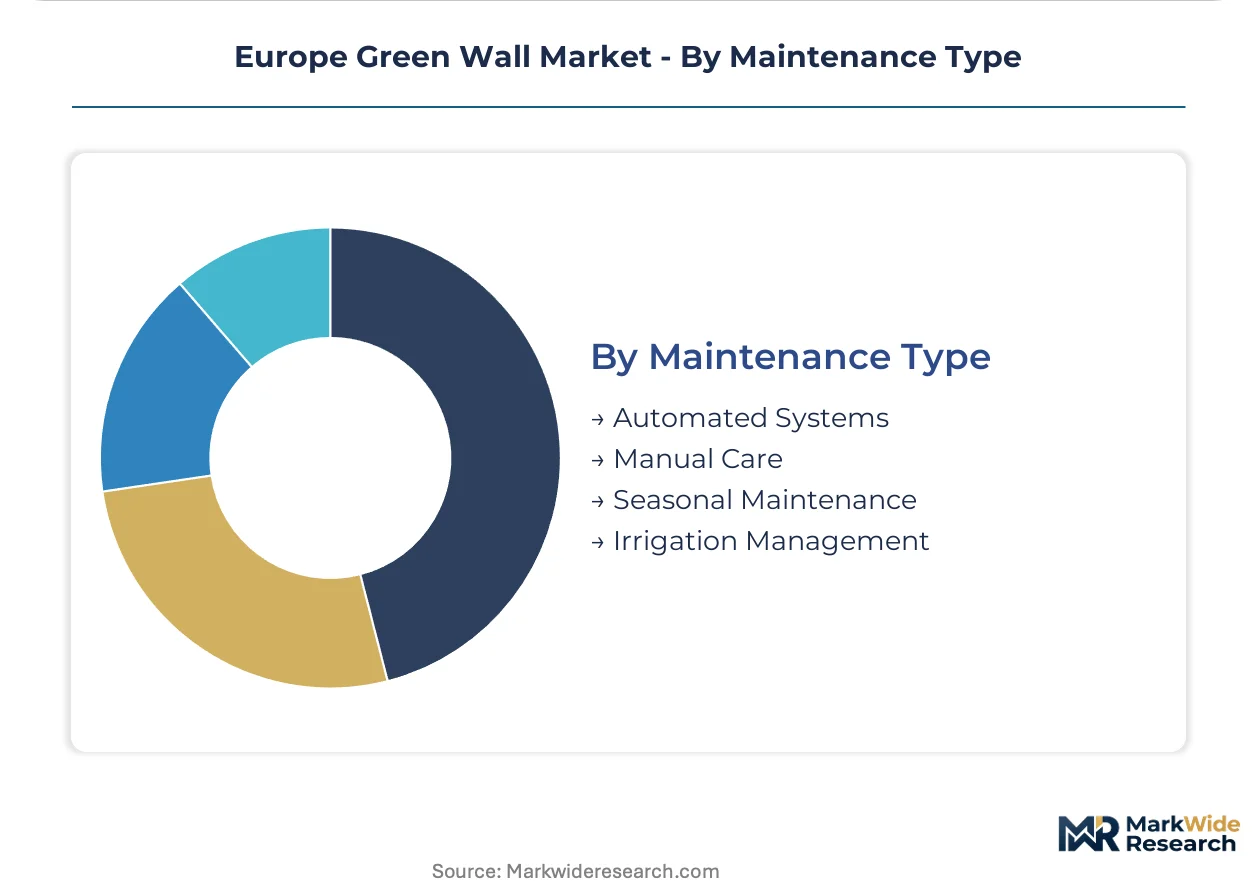
- Automated Systems:Sensor networks monitoring soil moisture, nutrient levels, and plant health transmit data to centralized management platforms. Frankfurt and Stockholm facility managers now require these capabilities as baseline specifications, with predictive maintenance algorithms qualifying as high-risk AI systems under pending EU AI Act frameworks.
- Irrigation Management:Dedicated water delivery optimization services address drought contingency protocols and municipal restriction compliance. Southern European jurisdictions particularly demand these specialized contracts separate from general horticultural maintenance.
- Manual Care:Traditional technician visits for pruning, pest management, and visual inspection retain relevance for smaller installations.
- Seasonal Maintenance:Plant replacement and substrate refresh cycles timed to growing seasons in northern European climates.
Automated Systems carry the heaviest specification weight; Irrigation Management is expanding most quickly as a standalone service line.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys green walls primarily as compliance infrastructure under building performance standards, while Dutch and French developers emphasize aesthetic differentiation in commercial portfolios. Southern European adoption patterns diverge sharply due to water scarcity protocols that reshape product specification.
Germany
Rhine-Ruhr and Rhine-Main corridors drive specification volume through municipal greening ordinances that mandate living walls in new commercial developments. The national building code transposes EU Green Deal energy-efficiency mandates that elevate vegetated facades from amenities to compliance requirements. Berlin and Frankfurt asset managers now tender automated irrigation systems as baseline specifications.
Netherlands
Amsterdam hospitality operators deploy freestanding systems where lease restrictions prohibit structural facade alterations. Municipal procurement frameworks prioritize CE-marked structural components and documented substrate safety under ECHA REACH compliance. Randstad landscape architects specification relationships channel demand toward integrated design-installation partners.
France
Paris retail landlords favor non-structural installations where heritage regulations block permanent modifications. The national building performance standard transposition creates compliance-driven procurement pipelines for major renovation projects. Lyon and Marseille commercial developers specify modular panel systems for standardized installation economics.
United Kingdom
London facility managers unbundle design-build from long-term horticultural maintenance, creating separate service line tenders. CE marking requirements for structural fixing systems filter market access and compress procurement shortlists. Premium residential installations concentrate in Greater London and Manchester luxury developments.
Spain
Barcelona hotel operators drive freestanding system demand amid strict irrigation restrictions under national water scarcity protocols. Hydroponic configurations capture specification share despite higher capital costs due to closed-loop water efficiency. Madrid commercial retrofits face 15-25% timeline compression penalties from load-bearing assessment complexity.
Europe Green Wall Market Vendor Landscape
Capability concentration sits with vertically integrated specialists; scale advantage sits with modular system fabricators. The vendor base separates into three strategic tiers: design-installation integrators controlling project pipelines, substrate specialists optimizing for climate-specific performance, and automated systems developers capturing recurring maintenance revenue. Dominant competitive moves include specification partnerships with landscape architects and backward integration into irrigation automation technology.
Among UK-based integrators, Biotecture Ltd anchors the vertically integrated tier through captive control of design, installation, and automated systems. Sempergreen occupies a position within the substrate specialization archetype, with Dutch engineering orientation toward northern European climate calibration. GreenBlue Urban Ltd exemplifies the specification-relationship model through channel control in British and Dutch municipal procurement.
| Leading Market Players |
|---|
| GSky Plant Systems Inc. |
| Lang+Fulton |
| ANS Group Global Ltd. |
| Moss Trend |
| Green Mood |
| Biotecture Ltd |
| Sempergreen |
| The Greenwall Company |
| GreenBlue Urban Ltd. |
| Others |
Supply Flow & Price Mechanics
ECHA REACH compliance costs for substrate materials determine both pricing tier spreads and supply chain shape across the Europe Green Wall Market. Peat and mineral wool input volatility compresses margins for standardized panel systems while elevating premium positioning for hydroponic alternatives with certified material traceability.
Pricing Analysis
Project-based contracts dominate procurement for commercial and institutional installations, with lifecycle service bundling commanding premium positioning over transactional supply-only arrangements. Price differentiation separates CE-marked structural systems with automated irrigation integration from basic panel configurations without predictive maintenance capabilities. Cost compression in substrate-based tiers is intensifying because ECHA compliance documentation requirements add material overhead that non-certified competitors cannot absorb. Municipal procurement frameworks in Germany and the Netherlands exhibit lowest price sensitivity due to compliance mandate urgency, while Spanish hospitality operators facing water scarcity protocols prioritize capital efficiency over operational expenditure minimization.
Supply Chain Analysis
Tariff exposure between peat-exporting Baltic states and mineral wool producers in Germany and the Netherlands dominates upstream risk assessment for substrate-dependent suppliers. Manufacturing concentration in Germany, the Netherlands, and Belgium feeds continental distribution networks for modular panel systems, while hydroponic component fabrication draws from specialized irrigation technology clusters in Italy and Switzerland. Single-source vulnerability sits with automated sensor suppliers for predictive maintenance platforms, where notified body certification timelines create specification bottlenecks. Distribution runs through specification relationships with landscape architects and engineering firms that control municipal and commercial procurement shortlists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Green Wall Market sits at a platform-economics inflection where digital twin integration and automated irrigation interoperability are collapsing traditional boundaries between construction-phase contractors and operational-phase service providers.
For Market Incumbents: Harden specification control through captive automated maintenance platform development that locks facility managers into recurring revenue relationships. Deepen backward integration into substrate material science to insulate margin position from ECHA REACH compliance cost volatility. Secure notified body partnerships for accelerated CE marking timelines that compress competitor market access windows. For New Entrants and Emerging Players: Polish and Romanian building stock modernization programs lack established supplier networks and present immediate white-space capture opportunities. Target hospitality freestanding system demand in Barcelona and Amsterdam where lease restrictions prohibit incumbent wall-mounted solutions. Pursue specification partnerships with Randstad landscape architects as the primary channel entry mechanism. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors automated systems developers with recurring revenue visibility over project-dependent installation contractors. Acquisition targets should demonstrate predictive maintenance algorithm capabilities that qualify for EU AI Act high-risk system certification. Monitor ECHA substrate material restriction trajectories as the signal indicating which technology configurations will sustain margin expansion versus face commoditization pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Integration | German engineering firms now embed twin specifications into municipal procurement frameworks. |
| Automated Irrigation Technology Acquisition | Sensor-based maintenance systems reduce operational labor costs in northern European climates. |
| CE Marking Certification Investment | Notified body assessments filter market access for structural fixing system suppliers. |
| Hydroponic System Manufacturing Scale-Up | Water-efficiency mandates in drought-prone Spanish and Italian jurisdictions drive specification shift. |
| Horticultural Maintenance Service Unbundling | London and Frankfurt facility managers now tender irrigation management as separate service lines. |
Methodological Framework
A spread of perspectives from facade engineering consultants, municipal procurement officers, landscape architects, and facility management directors converged on the working assumptions underpinning this analysis. Primary field engagement with commercial real estate developers in Germany, France, and the Netherlands combined with secondary validation against EU Green Deal implementation timelines, ECHA REACH regulatory filings, and municipal greening ordinance documentation. Bottom-up project pipeline assessment across Rhine-Ruhr and Rhine-Main corridors triangulated against top-down market sizing from building stock modernization program disclosures.
Demand-supply balance framing anchored the analytical approach across the projection horizon, with segmentation modeling across product type, installation method, end-user category, and maintenance configuration. CAGRs were derived from installation volume trajectories weighted by regional regulatory mandate intensity and substrate material cost evolution assumptions. Forecast inputs incorporated EU AI Act implementation timelines for automated system classification and ECHA substrate restriction scenario planning.
Practitioners should monitor ECHA material restriction proposals and EU AI Act high-risk system certification trajectories for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environment & Sustainability
Europe Air Quality Monitoring Market
Environment & Sustainability
Asia-Pacific Waste Management Market
Environment & Sustainability
Trash Rakes Market
Environment & Sustainability
Air Quality Control Systems Market
Environment & Sustainability
Global Weatherization Services Market
Environment & Sustainability
Soil Remediation Technologies Market
Environment & Sustainability
Global Mist Eliminator Market
Environment & Sustainability
APAC Bio-Medical Waste Management Market
Environment & Sustainability
Solid Waste Management Market
Environment & Sustainability
Philippines Gravity-Based Water Purifier Market
Environment & Sustainability
Water Pipeline Leak Detection System Market
Environment & Sustainability
United States Green Cement Market
Environment & Sustainability
Marine Waste Handling Equipment Market
Environment & Sustainability
Electronic Waste Recycling Market
Environment & Sustainability
Indoor Air Purification Market
Environment & Sustainability
Sustainable Palm Oil Market