
 Mineral Turpentine Market | 2026-2036
Mineral Turpentine Market Size, Share, and Industry Trends Forecast 2026-2036
Mineral Turpentine Market Foresight
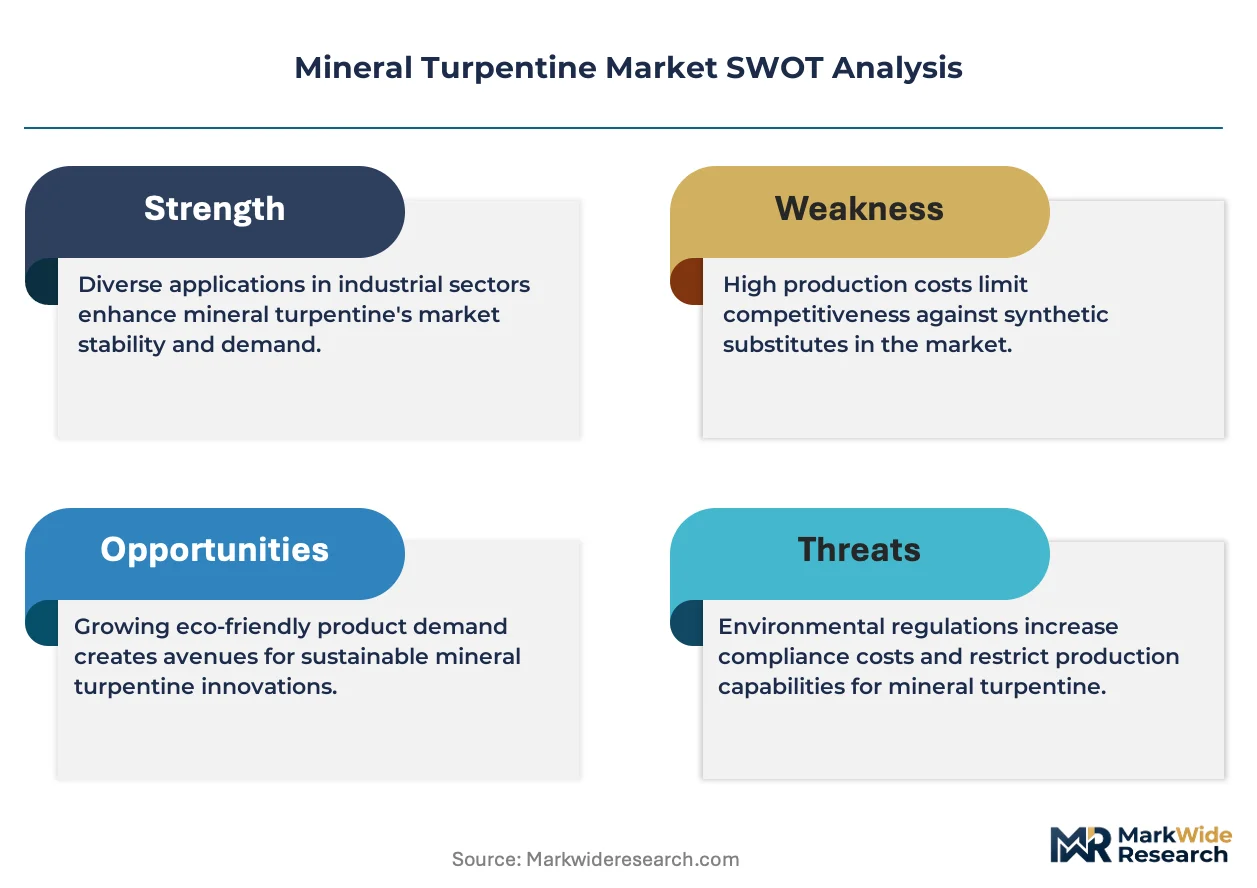
Water-based solvent formulations is hardening competition for traditional mineral turpentine in decorative coatings, forcing producers to defend volume through purity grades and technical service. Indian Oil Corporation Ltd leverages its nationwide refinery network to sustain feedstock cost advantages across domestic industrial clusters. DHC Solvent Chemie GmbH anchors its position through specialized distilled grades serving European coatings manufacturers with stringent VOC thresholds. Bharat Petroleum Corporation Limited competes on distribution density, extending direct supply lines to construction chemical formulators in western and southern India.
Mineral turpentine comprises a refined petroleum distillate fraction with a typical boiling range of 140–200°C, serving primarily as a solvent, diluent, and cleaning agent in surface coating systems. The product type landscape shows distilled grades occupying the largest volume share due to their compatibility with alkyd and oil-based paint systems, while synthetic variants are gaining traction where odor profiles and evaporation rates require tighter control. Application demand clusters heavily in paints and coatings, with cleaning agents representing a faster-growing niche as industrial maintenance protocols standardize degreasing chemistries across automotive and institutional end users.
REACH registration requirements in Europe and EPA VOC regulations in the United States are elevating compliance costs and restricting high-aromatic formulations in consumer-facing applications. India's BIS certification mandates and China's GB standards on solvent emissions are similarly reshaping product specifications for import and domestic sale. Stakeholders must monitor regulatory divergence between jurisdictions while evaluating backward integration into refinery streams or forward formulation partnerships to preserve margin structures.
Market Dynamics
Water-based solvent formulations are compressing traditional mineral turpentine volumes in decorative coatings, forcing producers to differentiate through technical service and purity specifications rather than commodity positioning.
Growth Catalysts
- Infrastructure build-out in India and China:Road construction, residential housing, and automotive manufacturing clusters in Gujarat, Maharashtra, Guangdong, and Jiangsu are driving solvent procurement for paint thinning and surface preparation.
- REACH registration tiering:European coatings manufacturers seeking compliant diluents are redirecting procurement toward registered mineral turpentine grades with verified substance data sheets.
- Industrial maintenance standardization:Automotive OEMs and institutional facilities are formalizing degreasing protocols that specify petroleum-based solvents for equipment cleaning and metal surface preparation.
Market Restraints
- Crude oil price volatility:Naphtha feedstock costs fluctuate with Brent crude movements, compressing margin predictability for non-integrated blenders.
- VOC emission ceilings:EPA regulations in the United States and China's GB standards are restricting high-aromatic formulations in consumer-facing architectural coatings.
- Waterborne technology substitution:Acrylic and polyurethane dispersions are capturing share in interior decorative applications where odor and flash-off time drive specification.
Strategic Opportunities
- Specialty distilled grades for automotive refinishing:Collision repair shops and OEM touch-up operations require controlled evaporation profiles that synthetic mineral spirits can address.
- India's PLI scheme for chemical manufacturing:Domestic production incentives are enabling backward integration into refinery streams for solvent producers with captive feedstock access.
- Recycling and reclamation services:Industrial users in Germany and the Netherlands are contracting closed-loop solvent recovery to meet circular economy reporting under CSRD.
Industry Challenges
- REACH data gap bridging:Small and mid-sized formulators lack toxicological study resources to complete substance dossiers for full registration, forcing reliance on lead registrant consortia.
- Formulation requalification timelines:Paint manufacturers face 18-24 month validation cycles when switching between solvent grades, locking in supplier relationships and delaying competitive substitution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mineral Turpentine Market |
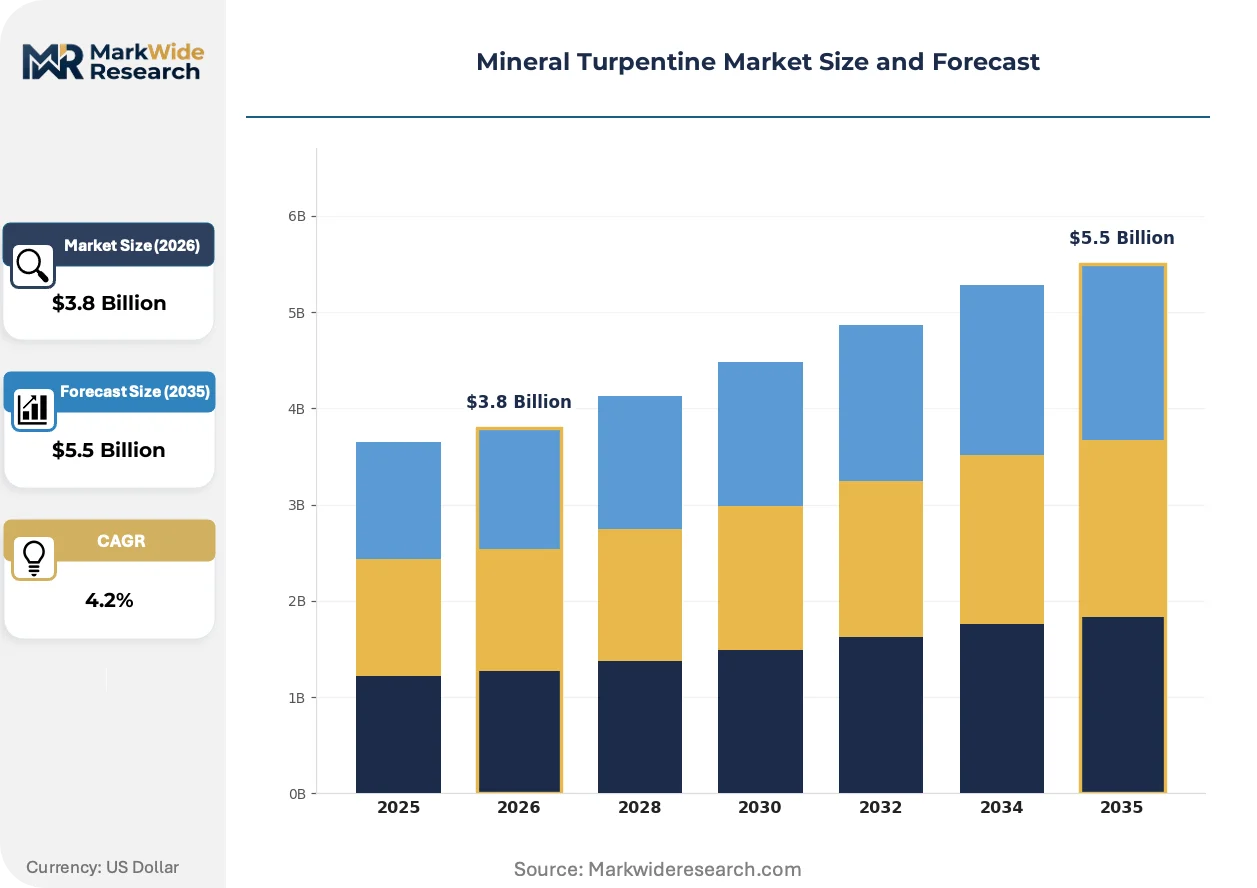
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Distilled, Synthetic, Refined, Technical Application: Paints, Adhesives, Coatings, Cleaning Agents End User: Construction, Automotive, Industrial, Institutional Distribution Channel: Direct Sales, Online Retail, Distributor, Wholesaler |
| Companies Covered | Al Sanea, DHC Solvent Chemie GmbH, Indian Oil Corporation Ltd, GSB Chemical Co. Pty. Ltd, Global Petro, Bharat Petroleum Corporation Limited, Alshall International Co., Sydney Solvents, Hindustan Petroleum Corporation Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mineral Turpentine Market Shifts & Advancements
Reformulation pressures and regulatory tiering are fragmenting the solvent specification landscape, creating distinct competitive arenas based on purity certification, emission profiles, and technical service depth rather than commodity pricing alone.
Synthetic mineral turpentine produced through catalytic reforming of C9-C12 hydrocarbons is overtaking conventional distilled grades in automotive OEM and aerospace coating applications. Tier 1 suppliers in Stuttgart and Wolfsburg specify synthetic variants for their narrower boiling ranges and consistent evaporation curves. This technology is overtaking traditional refinery-sourced products in premium industrial segments where batch-to-batch consistency determines coating defect rates.
China's GB 38508-2020 standard on volatile organic compound content in cleaning agents is forcing domestic formulators to reduce aromatic solvent loading in metal degreasers and equipment cleaners. The regulation mandates maximum VOC thresholds for 12 product categories, with compliance verification through third-party testing. Industrial chemical distributors in Shanghai and Shenzhen are restructuring product portfolios to emphasize low-aromatic mineral spirits for manufacturing sector clients.
Direct procurement relationships between construction chemical formulators and refinery-based solvent producers are consolidating channel structures in India. Large paint manufacturers in Mumbai and Chennai are negotiating annual offtake agreements with Indian Oil and Bharat Petroleum, bypassing traditional distributor markups. This pattern is most visible in western and southern India where infrastructure project clusters create sufficient volume concentration to justify dedicated supply logistics.
Mineral Turpentine Market Segmentation
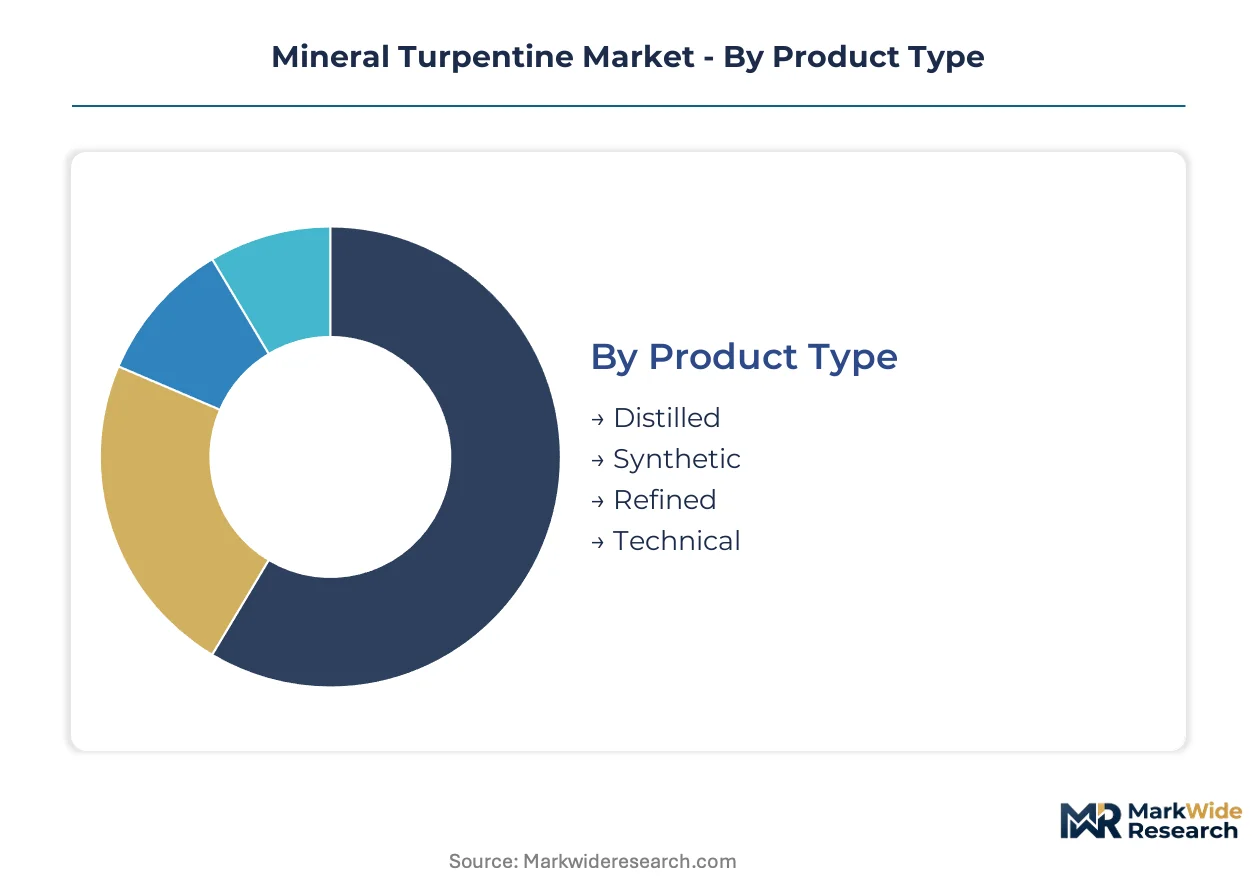
Mineral turpentine procurement decisions hinge on certification requirements that vary sharply across product grades and end-use applications. Formulators must match solvent specifications to regulatory thresholds in REACH-registered European coatings, BIS-certified Indian construction chemicals, and GB-compliant Chinese industrial cleaners.
Product Type:
REACH registration tiering and BIS purity mandates impose divergent compliance burdens across solvent grades, with full substance dossiers required for European market access while domestic Indian sales emphasize Bureau of Indian Standards certification.
- Distilled:Conventional petroleum fractionation yields a 140–200°C boiling range compatible with alkyd and oil-based paint systems. Demand concentrates in Indian construction chemical clusters across Gujarat and Maharashtra, where infrastructure project timelines prioritize cost-effective thinning agents over synthetic alternatives.
- Synthetic:Catalytic reforming of C9-C12 hydrocarbons delivers narrower boiling ranges and controlled evaporation curves. Automotive OEM touch-up operations in Stuttgart and Wolfsburg specify these variants to minimize coating defect rates in collision repair workflows.
- Refined:Additional hydrotreating reduces aromatic content for GB 38508-2020 compliance in Chinese metal degreasers.
- Technical:Lower purity grades serve industrial maintenance protocols where odor tolerance permits economy positioning.
Leading the category by volume: Distilled. Growing fastest: Synthetic.
Application:
Cost tiering separates architectural coatings from precision industrial formulations, with premium pricing attaching to solvent grades that satisfy VOC emission ceilings in consumer-facing products.
- Paints:Alkyd resin thinning dominates volume consumption across residential and commercial construction. Indian paint manufacturers in Mumbai and Chennai negotiate direct offtake agreements with refinery-based producers to bypass distributor markups in western and southern India.
- Coatings:Protective and marine applications require higher flash-point specifications. Demand clusters in Guangdong and Jiangsu province manufacturing hubs serving automotive and shipbuilding sectors.
- Adhesives:Solvent-borne pressure-sensitive formulations in packaging and footwear manufacturing.
- Cleaning Agents:Industrial degreasing protocols standardizing across German automotive OEMs and Dutch institutional facilities.
Volume concentration: Paints. Steepest expansion trajectory: Cleaning Agents.
End User:
Customer type determines specification stringency, with automotive and institutional buyers imposing batch-to-batch consistency requirements that commodity-grade suppliers cannot satisfy.
- Construction:Decorative and protective coating formulators represent the largest procurement base. Road construction and residential housing expansion in India and China drive solvent consumption for surface preparation and paint thinning across industrial hubs.
- Automotive:Collision repair shops and OEM refinishing operations demand controlled evaporation profiles. Tier 1 suppliers in Germany specify synthetic mineral spirits to meet narrow formulation windows.
- Industrial:Equipment maintenance and metal fabrication facilities with standardized degreasing chemistries.
- Institutional:Facility management protocols in the Netherlands contracting closed-loop solvent recovery under CSRD circular economy reporting.
Dominant procurement volume: Construction. Gaining share fastest: Automotive.
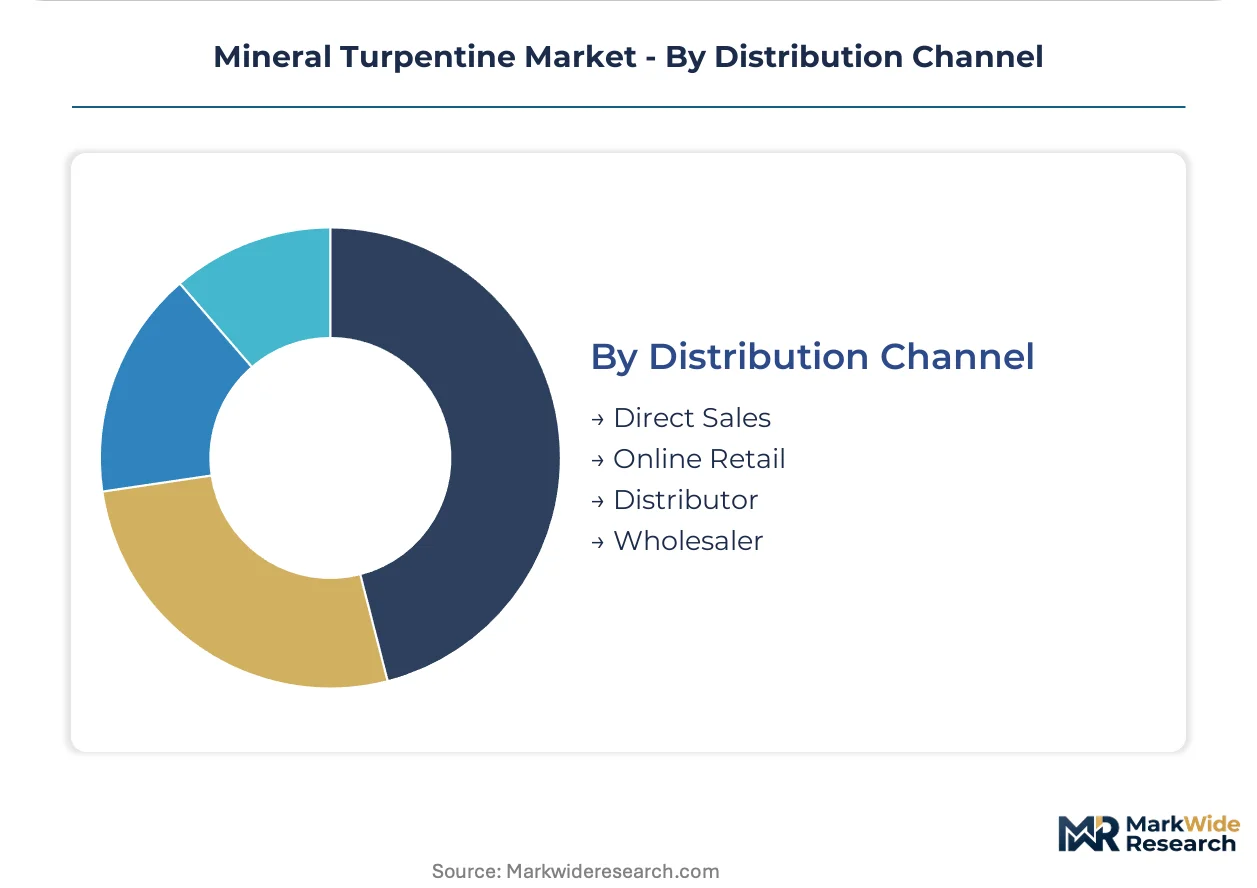
Distribution Channel:
Supply concentration in refinery-adjacent regions favors direct procurement models where volume thresholds justify dedicated logistics, while fragmented demand relies on distributor networks for technical service and just-in-time delivery.
- Direct Sales:Annual offtake agreements between construction chemical formulators and Indian Oil or Bharat Petroleum eliminate intermediary margins. Western and southern India infrastructure clusters create sufficient concentration to support dedicated supply lines.
- Distributor:Technical service and formulation support for mid-sized paint manufacturers lacking in-house solvent specification expertise.
- Wholesaler:Bulk consolidation for smaller industrial maintenance operations across secondary cities.
- Online Retail:Emerging channel for standardized grades in consumer DIY applications with limited penetration in professional industrial procurement.
Primary volume pathway: Direct Sales. Expanding most quickly: Distributor networks with technical service capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for mineral turpentine concentrates in Asia-Pacific manufacturing belts and European coatings hubs, with infrastructure build-out and automotive production driving procurement across industrial clusters. Regulatory divergence between REACH-registered European grades and BIS-certified Indian formulations fragments supply specifications. Refinery proximity dictates competitive positioning, as integrated producers leverage captive naphtha streams against merchant blenders exposed to crude volatility.
China
Guangdong and Jiangsu province manufacturing corridors absorb the largest solvent volumes for automotive and shipbuilding coatings. GB 38508-2020 VOC emission ceilings force reformulation of metal degreasers toward low-aromatic mineral spirits. Shanghai distributors are restructuring portfolios to emphasize compliant grades for manufacturing sector clients.
India
Gujarat and Maharashtra infrastructure clusters drive paint thinning demand across road construction and residential housing timelines. BIS certification mandates reshape import and domestic sale specifications for construction chemical formulators. Mumbai and Chennai paint manufacturers negotiate direct offtake agreements with Indian Oil and Bharat Petroleum, bypassing traditional distributor networks.
Germany
Stuttgart and Wolfsburg automotive OEM touch-up operations specify synthetic mineral turpentine for controlled evaporation profiles. REACH registration tiering elevates compliance costs for coatings manufacturers seeking verified substance data sheets. Industrial users in the Netherlands and Germany contract closed-loop solvent recovery services to meet CSRD circular economy reporting obligations.
United States
EPA VOC regulations restrict high-aromatic formulations in consumer-facing architectural coatings across major metropolitan construction markets. Automotive refinishing shops in collision repair corridors demand consistent batch-to-batch solvent performance. Merchant blenders face margin compression from naphtha feedstock volatility tied to Brent crude movements.
Saudi Arabia
Petrochemical integration along the Gulf Coast generates refined distillate streams for regional solvent supply. Construction chemical formulators in Riyadh and Jeddah procure thinning agents for protective coatings across infrastructure build-out phases. Domestic producers leverage refinery adjacency to serve Gulf Cooperation Council industrial maintenance sectors.
Mineral Turpentine Market Competitive Landscape
Capacity expansion dominates the current landscape as refinery-integrated producers extend distillation capacity to capture solvent demand from coatings formulators. The market structures around three tiers: national oil companies with captive feedstock, specialized European distillers serving REACH-compliant grades, and regional distributors providing technical service to mid-sized formulators. Strategic archetypes include backward-integrated refiners, purity-grade specialists, and channel-dense national marketers. Competitive moves center on direct procurement relationships with construction chemical clusters and portfolio diversification into low-aromatic formulations for VOC-regulated markets.
Among the integrated refinery tier, Indian Oil Corporation Ltd and Bharat Petroleum Corporation Limited exemplify national oil company positioning through distribution density across western and southern India industrial corridors. DHC Solvent Chemie GmbH represents the specialized European distiller archetype, anchoring supply relationships with coatings manufacturers facing stringent REACH and VOC thresholds. These three entities illustrate the competitive spectrum from feedstock-integrated scale to regulatory-specialized technical service.
| Leading Market Players |
|---|
| Al Sanea |
| DHC Solvent Chemie GmbH |
| Indian Oil Corporation Ltd |
| GSB Chemical Co. Pty. Ltd |
| Global Petro |
| Bharat Petroleum Corporation Limited |
| Alshall International Co. |
| Sydney Solvents |
| Hindustan Petroleum Corporation Limited |
| Others |
Supply & Pricing Matrix
Synthetic mineral turpentine production through catalytic reforming of C9-C12 hydrocarbons is compressing cost economics for conventional refinery-sourced grades while simultaneously concentrating supply among petrochemical-integrated producers with captive reforming capacity. This dual shift redraws competitive boundaries between merchant blenders exposed to naphtha volatility and backward-integrated players controlling feedstock streams.
Pricing Analysis
Volume concentrates in distilled grades serving Indian construction chemical clusters where cost-per-liter dominates procurement decisions, while margins concentrate in synthetic variants specified by Stuttgart and Wolfsburg automotive OEMs for their narrow boiling ranges. Price differentiation hinges on REACH registration tiering and BIS certification compliance, with registered European grades commanding technical service premiums. Cost compression in conventional distilled segments is intensifying because Indian Oil and Bharat Petroleum leverage refinery adjacency to undercut merchant blenders. Small formulators in western India exhibit the highest price sensitivity, while German automotive refinishing shops prioritize batch consistency over unit economics.
Supply Chain Analysis
Regional distribution centers in Mumbai, Chennai, and Ahmedabad anchor hub-and-spoke patterns serving western and southern India infrastructure clusters, while Shanghai and Shenzhen distributors restructure portfolios around GB 38508-2020 compliance. Supply concentrates in India, China, and Germany, with feedstock drawn from Gulf Coast petrochemical integration and domestic refinery streams. Raw material dependencies center on naphtha fractions, catalytic reformate, and hydrotreated distillates. Single-source vulnerability runs through concentrated refinery-based production in Gujarat and Maharashtra. Distribution runs through direct annual offtake agreements between large paint manufacturers and national oil companies, bypassing traditional wholesale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race where control over naphtha feedstock streams or downstream formulation partnerships determines margin sustainability. Players are pursuing captive refinery access as the decisive upstream lever.
For Market Incumbents: Cement supply relationships with construction chemical formulators in Gujarat and Maharashtra through dedicated logistics and technical service teams. Deepen backward integration into refinery distillation capacity to defend against naphtha price volatility eroding blender margins. Prioritize REACH dossier completion for European coatings manufacturers seeking verified substance data sheets.
For New Entrants and Emerging Players: Begin with low-aromatic refined grades serving Chinese metal degreaser formulators navigating GB 38508-2020 compliance thresholds. Target industrial maintenance protocols in German automotive OEMs and Dutch institutional facilities where standardized degreasing chemistries create specification stickiness. Lead with closed-loop solvent recovery services under CSRD circular economy reporting requirements.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by national oil companies seeking distribution density in high-growth Asian markets. Long-term viability rests on feedstock integration rather than formulation technology differentiation. Watch for BIS certification mandate expansion beyond current construction chemical coverage as the signal indicating regulatory-driven consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Refinery Streams | Indian Oil Corporation leverages captive naphtha access to undercut merchant blenders in domestic clusters. |
| REACH Registration Tiering Investment | DHC Solvent Chemie GmbH anchors European supply relationships through verified substance data sheets. |
| Low-Aromatic Grade Portfolio Expansion | Shanghai distributors restructure offerings to meet GB 38508-2020 VOC thresholds for manufacturing clients. |
| Direct Procurement Relationship Development | Mumbai paint manufacturers bypass distributor markups through annual offtake agreements with Bharat Petroleum. |
| Closed-Loop Solvent Recovery Services | German industrial users contract circular economy solutions to satisfy CSRD reporting obligations. |
Research Methodology
Independent corroboration across refinery operations data, customs trade records, and coatings manufacturer procurement disclosures underwrites the qualitative findings in this analysis. Primary interviews with plant managers at Indian and Chinese solvent production facilities, procurement leads at downstream paint manufacturers, and technical R&D directors at European coatings formulators were combined with secondary validation from SEC 10-K filings, Bureau of Indian Standards certification databases, and China GB standards documentation. Bottom-up volume estimates from individual production facilities were triangulated against top-down demand assessments from end-use application analysis.
Rate-of-change decomposition across the projection horizon separates volume growth in construction coatings from value growth in automotive refinishing applications. The analytical framework models demand by product grade tier, end-use industry concentration, regional production hub proximity, and regulatory compliance cluster. CAGRs were derived from segment-level growth trajectory analysis incorporating infrastructure spending patterns, automotive production forecasts, and solvent emission standard implementation timelines. Feedstock cost volatility assumptions and REACH registration completion schedules served as key forecast inputs.
Underlying measurement precision varies by segment; synthetic and refined grades carry tighter precision than technical grades due to more concentrated producer bases and clearer specification boundaries. Forecasts reflect documented assumptions regarding regulatory implementation timing, feedstock price correlation coefficients, and substitution elasticity between solvent-borne and waterborne formulations. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Ortho-Xylene Market
Solvents
2 - Ethyl Anthraquinone Market
Solvents
Benzene and Its Derivatives Market
Solvents
1, 1-Difluoroethane Market
Solvents
Diethyl Ether Market
Solvents
Retardant Solvent Market
Solvents
Potassium Formate Market
Solvents
Glycerol Market
Solvents
Hydrosol Market
Solvents
Para Nitrochlorobenzene Market
Solvents
Global Xylenols Market
Solvents
Mixed Xylene Market
Solvents
Ethyl Pyruvate Market
Solvents
Crotonaldehyde Market
Solvents
Allyl Cyanide Market
Solvents
1,2-Ethanedithiol Market