
 Global Elderly Nutrition Market | 2026-2036
Global Elderly Nutrition Market Size, Share, and Industry Trends Forecast 2026-2036
Global Elderly Nutrition Market Analysis
Plant-derived protein isolates are pivoting toward cost parity with dairy-based casein in elderly nutrition formulations. Abbott Laboratories leverages its clinical nutrition infrastructure to sustain hospital and nursing home contracts across North America. Nestlé S.A. anchors its Gerber and Nutren portfolios in regulated medical food channels, while Danone S.A. differentiates through specialized texture-modified products for dysphagia patients.
Elderly nutrition encompasses scientifically formulated products designed to address age-related physiological changes including reduced gastric acid secretion, diminished protein synthesis efficiency, and compromised nutrient absorption, typically delivering enhanced micronutrient density with adjusted caloric profiles. These formulations serve to prevent sarcopenia, support immune function, and maintain bone mineral density in populations over sixty-five years. Protein supplements command the deepest margin pools due to clinical validation requirements and prescription-linked reimbursement pathways, while ready-to-drink liquid formulations within the formulation dimension are expanding fastest as swallowing difficulties rise among advanced-age cohorts. Meal replacement products occupy a mature position in institutional channels but face margin compression from generic competitors.
The FDA exercises pre-market notification authority over medical foods claiming disease-specific benefits, while the EMA's nutrition and health claims regulation restricts promotional language across European Union member states. Japan's Ministry of Health, Labour and Welfare maintains positive list systems for functional food ingredients that shape product development priorities for exporters. Stakeholders must monitor evolving reimbursement classifications for oral nutritional supplements as payors tighten evidence requirements for cost coverage.
Market Dynamics
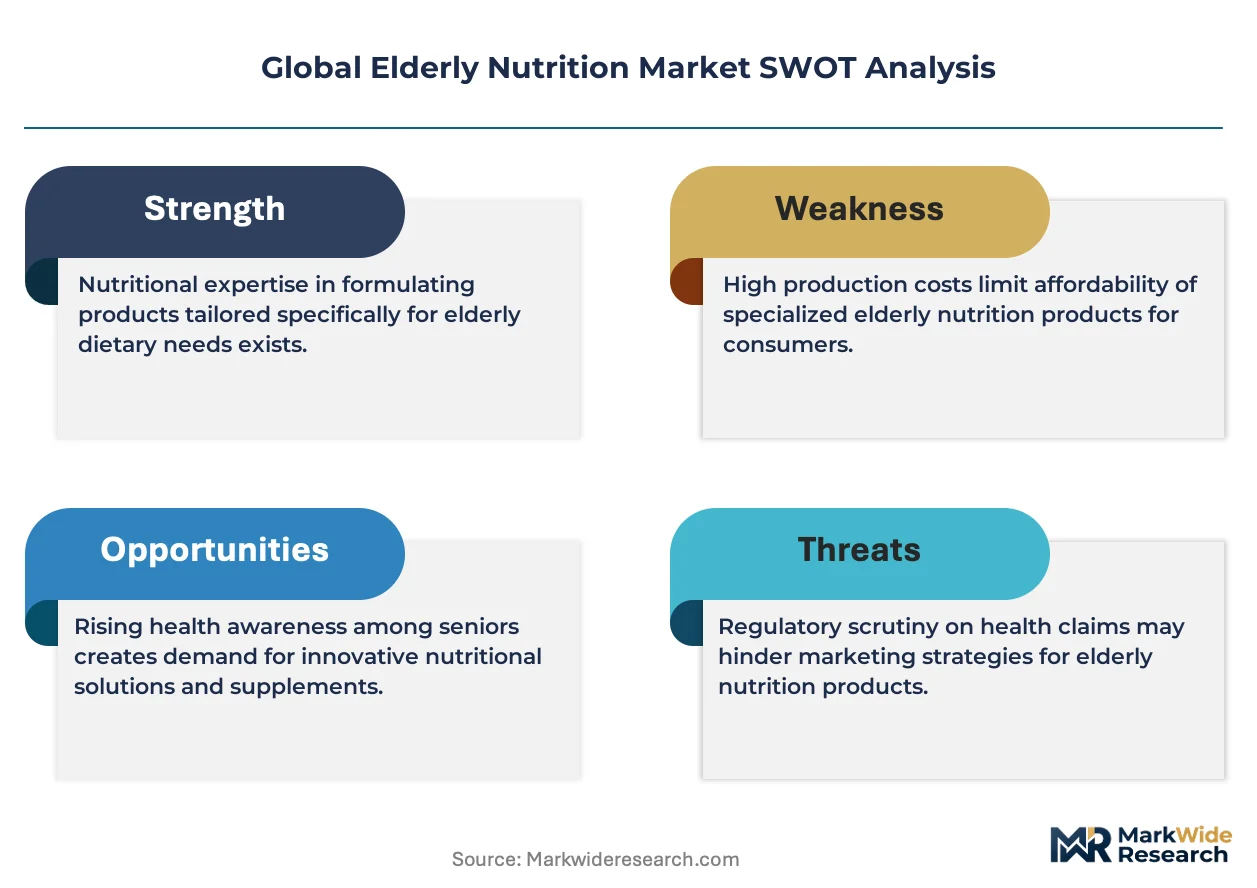
Reimbursement pathway fragmentation is compressing commercial timelines for elderly nutrition entrants, as payors in Germany, Japan, and the United States impose divergent evidence thresholds for cost coverage of oral nutritional supplements.
Growth Catalysts
- Japan's functional food positive list:The Ministry of Health, Labour and Welfare maintains ingredient pre-approval systems that accelerate product registration for protein-enriched formulations targeting sarcopenia prevention.
- Texture-modified liquid formulations:Dysphagia prevalence among advanced-age cohorts is pulling hospital and nursing home procurement toward ready-to-drink products with viscosity-adjusted profiles.
- Germany's medical nutrition reimbursement:Statutory health insurance coverage for prescription-linked oral nutritional supplements institutionalizes procurement volume in acute and post-acute care settings.
Market Restraints
- Whey protein concentrate volatility:Dairy commodity price swings compress margin predictability for formulations dependent on animal-derived protein bases.
- EMA health claims restriction:The nutrition and health claims regulation constrains promotional language for disease-specific benefits across European Union member states.
- Plant protein isolate cost premiums:Pea and rice protein extraction scale limitations sustain input cost disadvantages versus dairy casein in volume applications.
Strategic Opportunities
- Home care channel expansion:Japan's community-based long-term care insurance system reimburses protein supplementation for ambulatory elderly, opening direct-to-patient distribution models.
- FDA medical food notification pathway:Pre-market notification authority creates regulatory clarity for disease-specific formulations targeting malabsorption disorders.
- AI-driven personalization:Nutritional genomics platforms converging with metabolic profiling enable individualized micronutrient dosing for polymorbid elderly populations.
Industry Challenges
- Clinical validation timelines:Randomized controlled trial requirements for sarcopenia endpoint claims extend product development cycles beyond typical food and beverage horizons.
- Cross-border formulation harmonization:Divergent maximum permitted vitamin and mineral levels between FDA, EFSA, and Japan's MHLW specifications fragment manufacturing scale economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Elderly Nutrition Market |
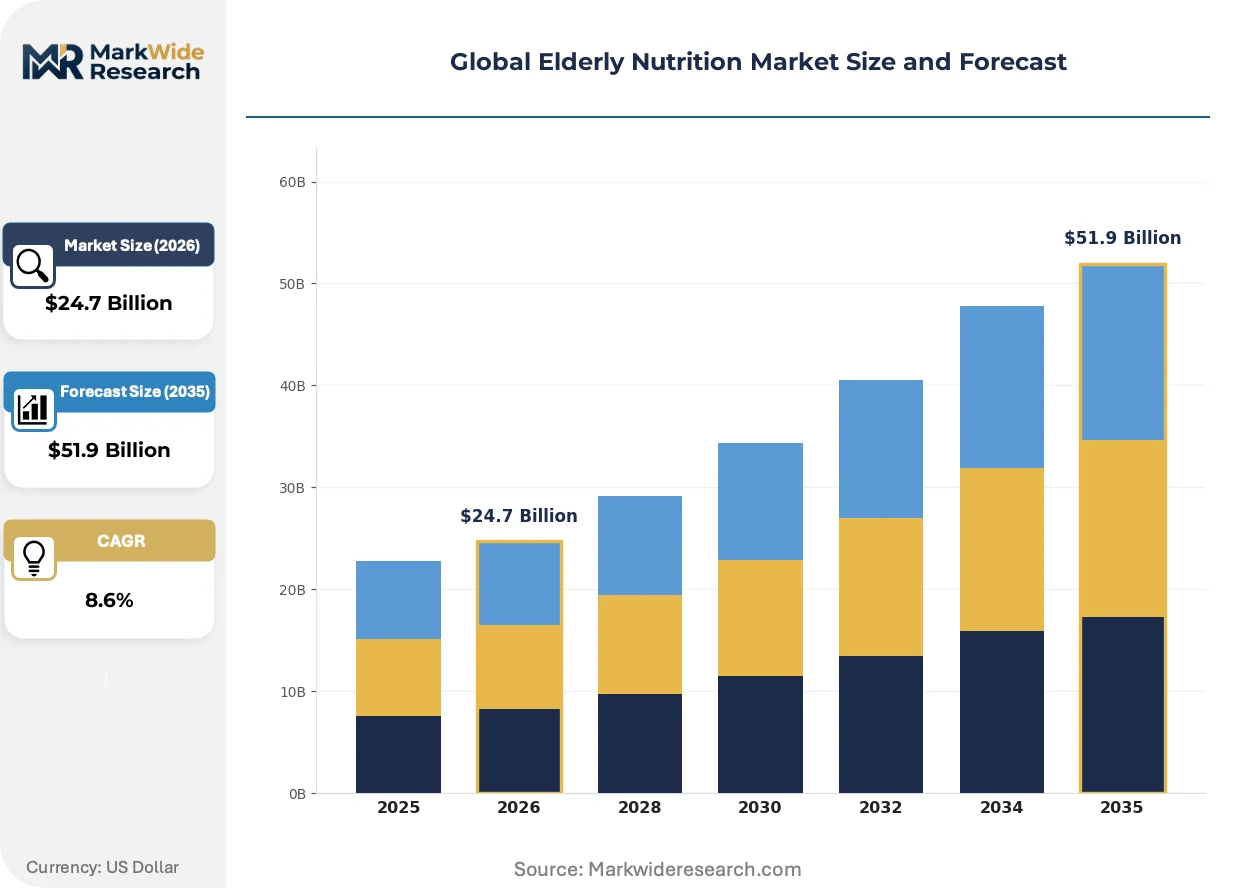
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $51.9 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Supplements, Nutritional Beverages, Meal Replacement Products, Fortified Foods End User: Independent Living, Assisted Living, Nursing Homes, Home Care Distribution Channel: Online Stores, Supermarkets, Pharmacies, Health Food Stores Formulation: Powder, Liquid, Ready-to-Drink, Granules |
| Companies Covered | Bayer AG, Otsuka Pharmaceuticals Co., Ltd., Abbott Laboratories, Koninklijke DSM N.V., Herbalife Nutrition Ltd., Nestlé S.A., Fresenius Kabi AG, Meiji Holdings Co., Ltd., Danone S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Elderly Nutrition Market Emerging Trajectories
Precision fermentation and enzymatic protein modification are collapsing traditional boundaries between medical food and mainstream nutrition, enabling bioactive peptide delivery at pharmaceutical-grade consistency.
Precision fermentation of dairy-identical proteins is rewriting cost structures for hypoallergenic elderly formulations. Japanese ingredient suppliers and North American biotechnology firms are scaling contract manufacturing capacity for lactose-free, immunoglobulin-enriched isolates. This biotechnology is compressing the premium gap between plant-derived and animal-derived protein sources while eliminating supply chain exposure to dairy commodity cycles.
The FDA's updated dietary supplement labeling requirements mandate quantitative disclosure of added sugars, fiber, and specific micronutrients in standardized formats. Manufacturers reformulating elderly nutrition portfolios must reconcile legacy label inventories with compliance deadlines or face enforcement action. Ready-to-drink liquid products with complex multi-ingredient matrices face the steepest redesign costs and shortest adaptation windows.
Hospital purchasing consortiums are consolidating supplier panels and unbundling nutritional services from device and pharmaceutical contracts. Group purchasing organizations in the United States now negotiate oral nutritional supplement pricing through dedicated nutrition category managers rather than general food service procurement. This concentration shifts bargaining power toward institutional buyers and compresses allowable margins for contract-dependent manufacturers.
Global Elderly Nutrition Market Segmentation
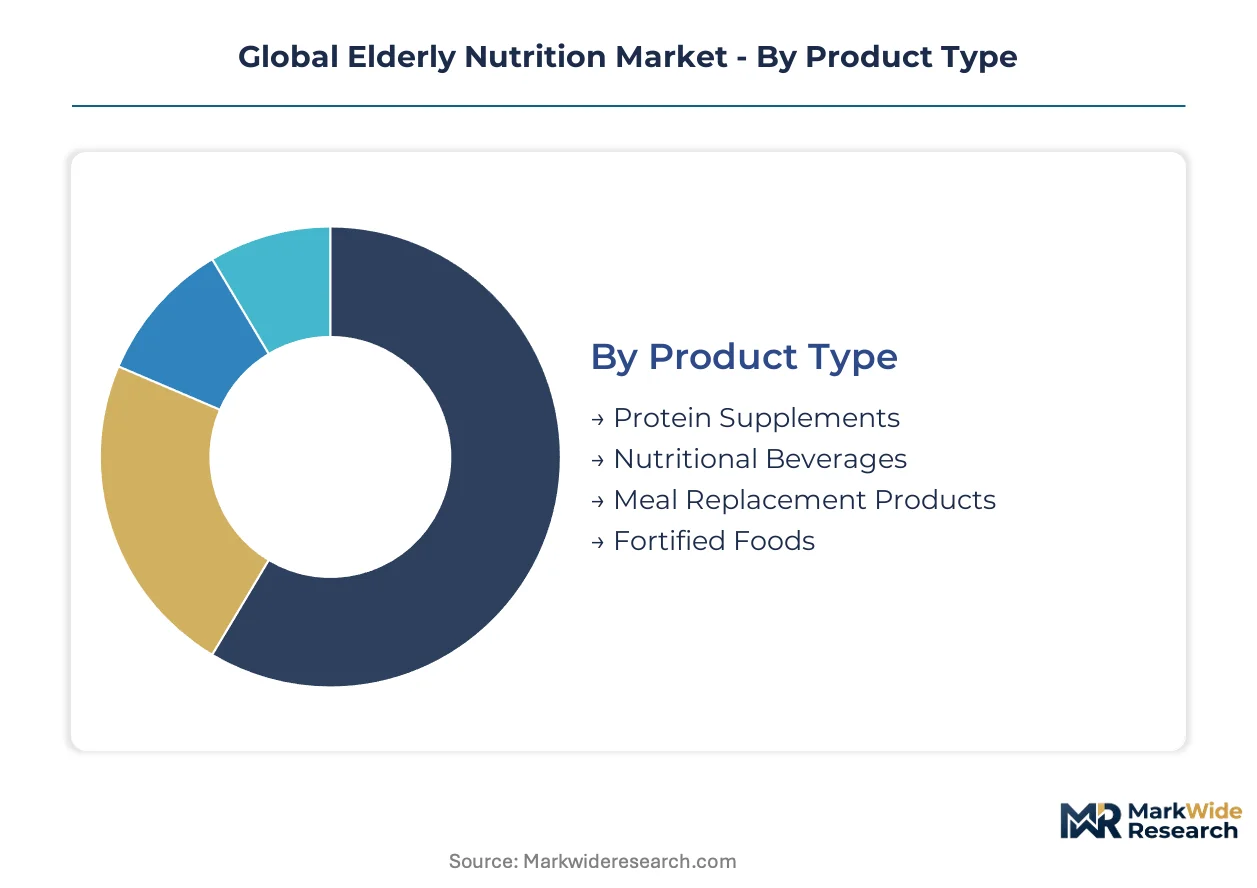
Segmentation in elderly nutrition separates clinically validated formulations from wellness-oriented products, with reimbursement eligibility and texture modification requirements determining channel access. Protein density, viscosity profiles, and micronutrient fortification levels vary sharply across institutional versus home-based consumption contexts.
Product Type:
Standalone therapeutic formulations operate on prescription-linked reimbursement pathways, while embedded nutrition in fortified foods competes through retail shelf placement and functional positioning.
- Protein Supplements:Concentrated isolates and hydrolysates delivering 15-30g protein per serving target sarcopenia prevention in clinical protocols. Hospital purchasing consortiums in the United States and statutory insurance reimbursement in Germany institutionalize procurement volume for prescription-grade formulations.
- Nutritional Beverages:Ready-to-drink liquids with adjusted caloric density and enhanced micronutrient profiles serve dysphagia patients and post-acute recovery protocols. Japan's community-based long-term care insurance system reimburses these products for ambulatory elderly, accelerating home care channel expansion.
- Meal Replacement Products:Complete nutrition bars and shakes positioned for convenience compete against generic alternatives in retail environments.
- Fortified Foods:Functional cereals, dairy, and snacks with added protein and vitamins target preventive consumption outside medical supervision.
Volume placements concentrate in protein supplements; the faster expansion belongs to nutritional beverages.
End User:
Customer type determines formulation specification, with texture modification and feeding assistance requirements escalating across the care continuum.
- Home Care:Direct-to-patient distribution models leverage reimbursement pathways in Japan and Germany for protein-enriched formulations. Aging-in-place preferences among advanced-age cohorts pull procurement toward ambulatory delivery systems and telehealth-integrated nutrition counseling.
- Nursing Homes:Texture-modified products with IDDSI-compliant viscosity standards dominate institutional procurement for dysphagia management. Group purchasing organizations in the United States negotiate oral nutritional supplements through dedicated category managers, compressing supplier margins.
- Assisted Living:Semi-independent residents require convenient formats balancing clinical efficacy with self-administration feasibility.
- Independent Living:Preventive positioning and retail accessibility drive selection criteria outside reimbursement frameworks.
Procurement volume clusters in nursing homes; assisted living facilities are climbing the fastest as transitional care models expand.
Distribution Channel:
Channel selection determines margin structure, with pharmacy and institutional pathways capturing reimbursement-linked premiums versus retail price competition.
- Pharmacies:Prescription-linked oral nutritional supplements flow through this channel in Germany, Japan, and the United States, with statutory coverage validating clinical positioning. Pharmacist counseling requirements reinforce adherence protocols for polymorbid elderly populations.
- Online Stores:Direct-to-consumer platforms enable subscription models for specialized formulations targeting niche dietary requirements. Japan's functional food positive list accelerates product registration visibility for exporters seeking cross-border e-commerce penetration.
- Supermarkets:Mass-market fortified foods and standard nutritional beverages compete on shelf placement and promotional pricing.
- Health Food Stores:Premium positioning for organic and plant-derived protein isolates targets consumer willingness to pay outside reimbursement systems.
Transaction density peaks in pharmacies; online stores are gaining share fastest as home care reimbursement expands.
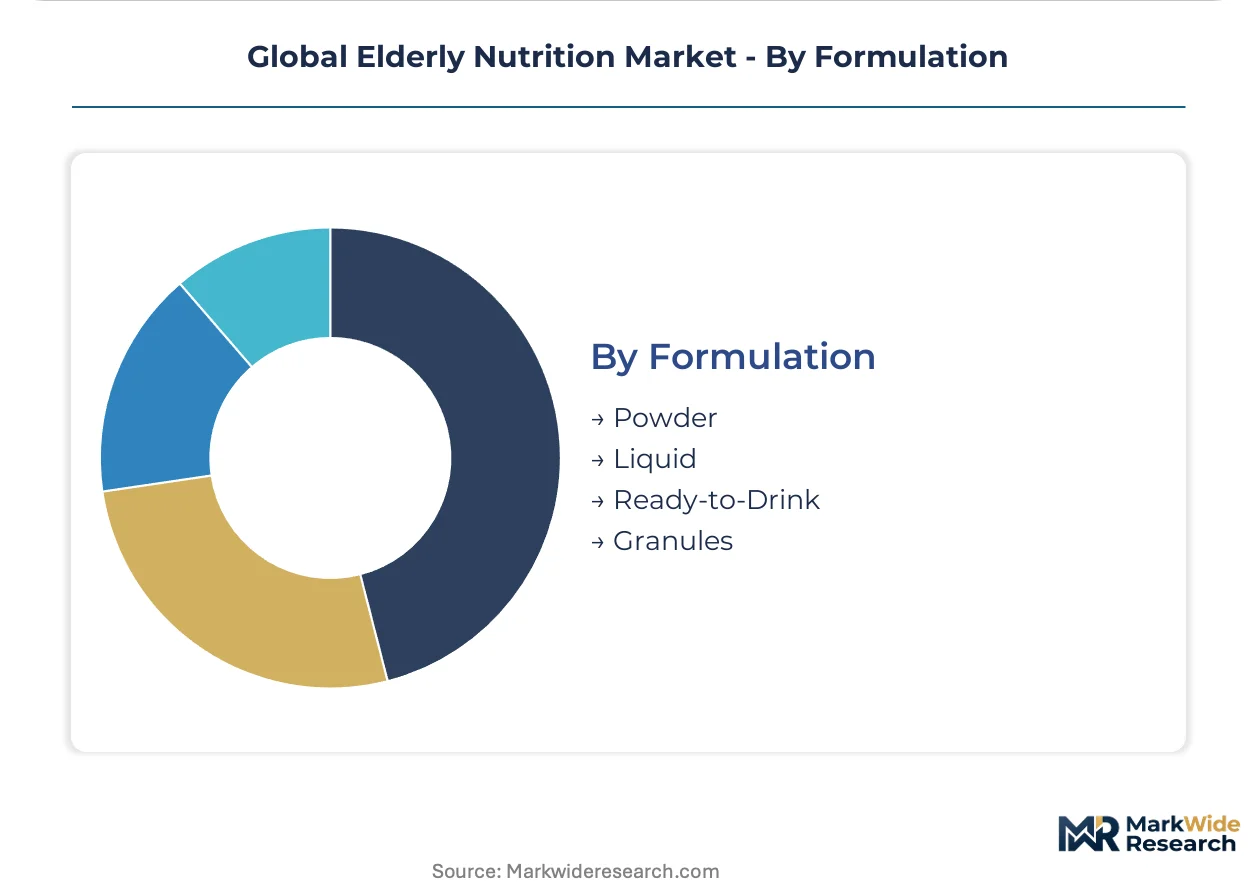
Formulation:
Physical form dictates manufacturing complexity, with liquid matrices requiring sterile processing and powder formats enabling longer shelf stability.
- Ready-to-Drink:Pre-mixed liquids with viscosity-adjusted profiles address swallowing difficulties without preparation requirements. FDA's updated dietary supplement labeling mandates quantitative disclosure of added sugars and fiber, forcing redesign of multi-ingredient matrices with compressed adaptation windows.
- Liquid:Concentrates requiring dilution offer flexibility in caloric density adjustment for individualized protocols. Precision fermentation of dairy-identical proteins enables hypoallergenic formulations with pharmaceutical-grade consistency.
- Powder:Dry blends provide cost efficiency and extended stability for institutional bulk procurement.
- Granules:Rapid-dissolve formats target patients with limited stirring capability or equipment access.
Institutional procurement favors powder for cost control; ready-to-drink formats are expanding most quickly as dysphagia prevalence rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Institutional procurement for elderly nutrition concentrates in Germany, Japan, and the United States, where reimbursement pathways validate clinical-grade formulations and shape cross-border investment priorities for manufacturers.
United States
Hospital purchasing consortiums and Medicare Advantage plans drive volume for prescription-linked oral nutritional supplements. The FDA exercises pre-market notification authority over medical foods claiming disease-specific benefits, tightening quality verification protocols for entrants. Abbott Laboratories anchors its clinical nutrition infrastructure in North American hospital and nursing home contracts.
Germany
Statutory health insurance coverage for medical nutrition accelerates institutional procurement in acute and post-acute care settings. EMA nutrition and health claims regulation restricts promotional language for disease-specific benefits across EU member states. The KBA and federal procurement frameworks in Berlin and Munich concentrate distribution negotiations for contract-dependent manufacturers.
Japan
Community-based long-term care insurance reimburses protein supplementation for ambulatory elderly, expanding home care channel uptake. The Ministry of Health, Labour and Welfare maintains positive list systems for functional food ingredients that accelerate product registration for sarcopenia-targeted formulations. Tokyo and Osaka clusters host contract manufacturing capacity for texture-modified liquid products.
China
Aging demographics and rising healthcare expenditure pull demand toward fortified foods and nutritional beverages in urban centers. SAMR and NMPA oversight of health food registration creates compliance barriers for imported clinical formulations. Shanghai and Beijing metropolitan areas concentrate distribution infrastructure for premium positioning outside reimbursement systems.
Switzerland
Swissmedic regulation of medical foods and high per-capita healthcare spending support premium-tier nutritional positioning. Precision fermentation biotechnology clusters in Basel and Zurich enable pharmaceutical-grade protein isolate production for hypoallergenic elderly formulations. Nestlé S.A. leverages its Gerber and Nutren portfolios in regulated medical food channels.
Global Elderly Nutrition Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical-grade clinical nutrition consolidating around vertically integrated multinationals while private-label fortified foods fragment among regional processors. Three archetypes dominate: diversified nutrition conglomerates with hospital system contracts, biotechnology-enabled precision fermentation specialists, and generic powder blenders serving institutional bulk procurement. Competitive moves concentrate on M&A for reimbursement pathway access and capacity expansion for precision fermentation scale-up.
Within the diversified conglomerate tier, Abbott Laboratories, Nestlé S.A., and Danone S.A. exemplify distinct strategic positioning. Abbott leverages North American clinical infrastructure for institutional contract retention. Nestlé anchors regulated medical food channels through portfolio breadth. Danone differentiates through specialized texture-modified products for dysphagia management. These three occupy positions that reflect divergent bets on reimbursement-linked versus retail-accessible growth vectors.
| Leading Market Players |
|---|
| Bayer AG |
| Otsuka Pharmaceuticals Co., Ltd. |
| Abbott Laboratories |
| Koninklijke DSM N.V. |
| Herbalife Nutrition Ltd. |
| Nestlé S.A. |
| Fresenius Kabi AG |
| Meiji Holdings Co., Ltd. |
| Danone S.A. |
| Others |
Supply Flow & Price Mechanics
Japan's functional food positive list system gates qualified supply access for elderly nutrition entrants, with MHLW pre-approval requirements simultaneously filtering out commodity-grade competitors and validating premium-tier pricing for compliant formulations. This regulatory architecture concentrates pricing power among manufacturers with established Tokyo and Osaka manufacturing footprints while forcing non-compliant players toward generic retail channels without reimbursement linkage.
Pricing Analysis
Volume placements cluster in institutional powder procurement while margin pools concentrate in prescription-linked protein supplements. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade clinical formulations from retail-accessible fortified foods and generic bulk blends. Pricing pressure stems from hospital purchasing consortium consolidation in the United States, where dedicated nutrition category managers compress supplier margins through unbundled contract negotiations. Generic powder blenders serving nursing home bulk procurement exhibit highest price sensitivity; biotechnology-enabled precision fermentation specialists command lowest sensitivity due to hypoallergenic differentiation.
Supply Chain Analysis
Japan's domestic-content mandates for functional food registration reshape sourcing priorities for exporters seeking MHLW positive list inclusion. Manufacturing gravity centers on Japan, Germany, and Switzerland, with Tokyo-Osaka clusters hosting texture-modified liquid production and Basel-Zurich precision fermentation capacity serving hypoallergenic formulations. Raw material dependencies hinge on dairy-derived protein isolates, plant-based pea and rice proteins, and enzymatically modified bioactive peptides. Single-source vulnerability runs through precision fermentation contract manufacturing capacity concentrated in North American biotechnology firms. Distribution runs through pharmacy and institutional channels capturing reimbursement-linked premiums versus retail price competition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's pre-market notification authority over medical foods creates a cost-of-compliance moat that entrenches Abbott Laboratories, Nestlé S.A., and Danone S.A. while filtering out undercapitalized entrants lacking clinical validation infrastructure.
For Market Incumbents: Lock in reimbursement pathway access through backward integration into precision fermentation capacity, eliminating dairy commodity exposure while securing pharmaceutical-grade protein consistency. Deepen hospital system contract retention by embedding AI-driven personalization platforms into existing clinical nutrition infrastructure. Threat substitution from biotechnology-enabled specialists demands preemptive capacity expansion in hypoallergenic formulations before cost parity collapses premium positioning. For New Entrants and Emerging Players: Begin with Japan's home care channel expansion under community-based long-term care insurance reimbursement, where direct-to-patient distribution models bypass entrenched hospital purchasing consortiums. Target texture-modified liquid formulations for dysphagia patients as the most penetrable segment, with IDDSI-compliant viscosity standards creating technical barriers that filter out commodity competitors. Go-to-market angle: telehealth-integrated nutrition counseling bundled with subscription-based protein supplementation. For Investors and Strategic Acquirers: Germany's statutory health insurance coverage expansion for medical nutrition is the leading indicator that institutional procurement volume will concentrate further in contract-dependent manufacturers with established Berlin and Munich distribution frameworks. Long-term viability favors vertically integrated players controlling precision fermentation scale-up and clinical validation infrastructure. Acquisition target archetype: biotechnology-enabled contract manufacturers with MHLW-registered capacity. Signal to watch: FDA enforcement action against legacy label inventories failing updated dietary supplement disclosure requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Eliminates dairy commodity exposure while enabling pharmaceutical-grade protein consistency for hypoallergenic formulations. |
| Reimbursement Pathway Expansion | Japan's MHLW positive list registration accelerates product visibility for exporters seeking cross-border penetration. |
| AI-Driven Personalization Platform | Nutritional genomics convergence enables individualized micronutrient dosing for polymorbid elderly populations. |
| Texture-Modified Product Line Extension | IDDSI-compliant viscosity standards address dysphagia prevalence among advanced-age cohorts in nursing home procurement. |
| Hospital System Partnership Consolidation | GPO category manager negotiations in the United States compress margins for contract-dependent manufacturers without scale. |
Methodological Framework
Independent corroboration across regulatory filings, hospital procurement databases, and functional food registration records underwrites the qualitative findings in this study. Primary interviews with clinical nutrition directors, formulary managers at statutory health insurers, GPO contracts specialists, and precision fermentation R&D leads combined with secondary validation from FDA medical food notifications, EMA health claims registers, and MHLW positive list publications. Bottom-up demand modeling across product type, end user, distribution channel, and formulation dimensions triangulates against top-down macroeconomic indicators.
Rate-of-change decomposition separates volume growth drivers from value expansion mechanisms across the analysis window. Segmentation modeling incorporates product type, end user care setting, distribution channel access, and physical formulation matrix. CAGRs derive from iterative convergence of demand-side adoption curves and supply-side capacity expansion timelines. Forecast inputs include reimbursement pathway evolution in Germany and Japan, precision fermentation cost reduction trajectories, and dysphagia prevalence projections among advanced-age cohorts.
Underlying measurement precision varies by segment; prescription-linked protein supplements and texture-modified liquids carry tighter precision than generic fortified foods due to reimbursement data availability. Forecasts reflect assumptions regarding regulatory stability in FDA medical food authority and MHLW positive list continuity. Reimbursement classification tightening by payors, dairy commodity price volatility, and cross-border formulation harmonization failures constitute specific revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Global Nutraceutical Ingredients Market
Nutritional Supplements
Fat Powders Market
Nutritional Supplements
Brain Health Supplement Market
Nutritional Supplements
Ready-To-Use Therapeutic Food Market
Nutritional Supplements
China Whey Protein Market
Nutritional Supplements
Latin America Herbal Supplements Market
Nutritional Supplements
Microencapsulated Fish Oil Market
Nutritional Supplements
Japan Whey Protein Market
Nutritional Supplements
Europe Dietary Supplements Market
Nutritional Supplements
Mineral Supplements Market
Nutritional Supplements
Global Vitamin Supplements Market
Nutritional Supplements
Bone Broth Protein Powder Market
Nutritional Supplements
Global Nutraceutical Market
Nutritional Supplements
Mood Support Supplements Market
Nutritional Supplements
Global Proanthocyanidins Market
Nutritional Supplements
Indonesia Beauty Supplements Market