
 Ready-To-Assemble (RTA) Furniture Market | 2026-2036
Ready-To-Assemble (RTA) Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Ready-To-Assemble (RTA) Furniture Market Insights
Modular bundling of storage, workspace, and display components into single SKUs is expanding consumer choice in compact living environments. IKEA leverages its global design-to-flat-pack pipeline to sustain cost leadership across multiple continents. Sauder Woodworking Co. anchors North American production with specialized MDF fabrication capabilities. Dorel Industries Inc. competes across juvenile, home, and commercial furniture segments with integrated distribution networks.
Ready-to-assemble furniture denotes flat-packed components shipped disassembled for end-user construction, typically using cam-lock fasteners, dowel joints, or slide-together rails engineered for tool-free or minimal-tool assembly. Particle board and medium-density fiberboard dominate material inputs due to dimensional stability, uniform surface quality, and compatibility with melamine lamination processes that resist wear in residential and commercial settings. Cabinet and shelving unit categories lead volume throughput given their ubiquity in household and office storage applications, while desk segments capture margin pools from remote-work furniture upgrades. Online retail channels are displacing traditional furniture stores as primary discovery and purchase pathways, particularly among millennial and Generation Z buyer cohorts.
The EPA oversees formaldehyde emission standards under the Toxic Substances Control Act, while California's Air Resources Board maintains CARB Phase 2 compliance thresholds that de facto govern national material sourcing decisions. The EU Ecolabel and FSC chain-of-custody certification create market access preconditions for European distribution, particularly in Germany and Scandinavian markets where environmental purchasing criteria carry substantial weight. Stakeholders must monitor evolving extended producer responsibility frameworks and packaging waste directives that could mandate take-back programs or redesign of flat-pack shipping cartons.
Market Dynamics
California's CARB Phase 2 formaldehyde emission standards have become the de facto national benchmark for engineered wood sourcing, forcing manufacturers to reformulate adhesives and resin systems across North American production networks.
Growth Catalysts
- Remote-work infrastructure:Home office furniture demand from distributed workforces sustains volume throughput for desk and storage categories across suburban markets.
- REACH compliance migration:European chemical safety protocols are accelerating substitution of urea-formaldehyde binders with bio-based alternatives in panel manufacturing.
- Urban density patterns:Micro-apartment construction in Berlin, Stockholm, and Copenhagen is normalizing modular, reconfigurable furniture systems.
Market Restraints
- Resin input volatility:Methanol and formaldehyde feedstock prices fluctuate with natural gas benchmarks, compressing margin predictability for particle board suppliers.
- Asian supply concentration:Melamine-impregnated decorative paper production clusters in China and South Korea create single-source dependency risks for laminating operations.
- Dimensional tolerance limits:MDF moisture absorption in humid climates restricts outdoor and bathroom furniture applications.
Strategic Opportunities
- Take-back program mandates:Extended producer responsibility frameworks in Germany and France will reward closed-loop material recovery systems.
- Augmented reality integration:AR-assisted assembly guidance is reducing return rates and customer service burden for direct-to-consumer channels.
- Rural e-commerce penetration:Last-mile delivery optimization opens underserved postal codes in Poland, Hungary, and Romania.
Industry Challenges
- CAD-to-CAM translation gaps:Design files require manual rework for CNC routing compatibility across incompatible software ecosystems.
- FSC chain-of-custody audit costs:Certification maintenance consumes disproportionate administrative bandwidth for mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ready-To-Assemble (RTA) Furniture Market |
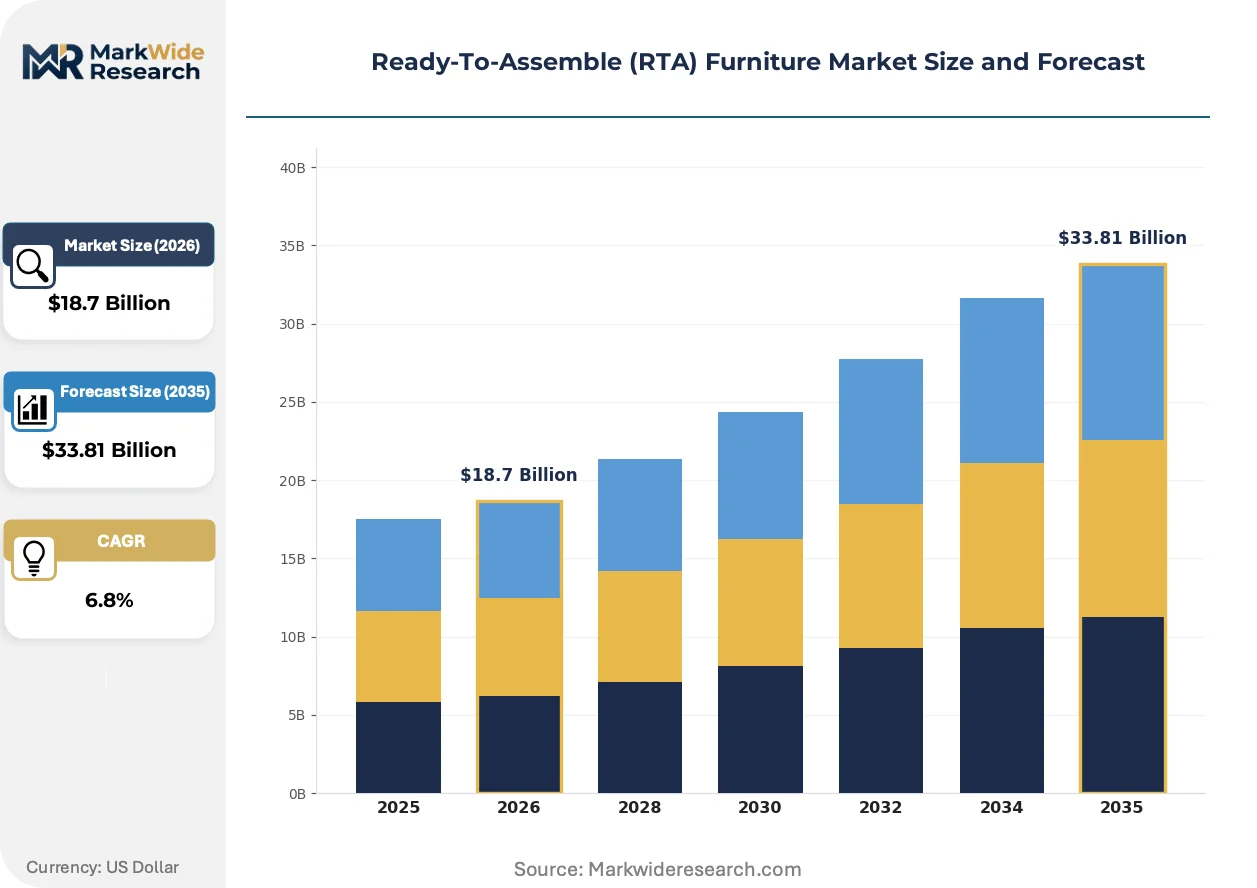
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cabinets, Desks, Tables, Shelving Units Material: Particle Board, MDF, Plywood, Solid Wood End User: Households, Offices, Retail Stores, Educational Institutions Sales Channel: Online Retail, Furniture Stores, Home Improvement Centers, Wholesale Distributors |
| Companies Covered | IKEA, Sauder Woodworking Co., Dorel Industries Inc., Tvilum A/S, Whalen Furniture, Walker Edison Furniture Company LLC, South Shore Furniture, Wayfair, Zinus Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ready-To-Assemble (RTA) Furniture Market Trends and Innovations
Digital fabrication workflows and biomaterial substitution are compressing design-to-delivery cycles while regulatory pressure on indoor air quality is reshaping adhesive chemistry across the value chain.
Parametric design software is unifying engineering, nesting optimization, and packaging simulation into single-platform workflows. Furniture brands serving millennial first-time buyers are adopting these tools to reduce prototype iterations. This convergence is unifying cost estimation with real-time material yield calculations, collapsing traditional silos between design studios and factory floor systems.
REACH Annex XVII restrictions on formaldehyde-releasing substances are tightening permissible emission thresholds for interior-grade panels. German and French distributors now require third-party emissions testing documentation as a listing prerequisite. Cabinet and children's furniture categories face the steepest compliance burden, with manufacturers accelerating phenol-formaldehyde and soy-based adhesive trials.
Rental and subscription furniture models are displacing outright ownership among urban graduates entering volatile housing markets. Platforms targeting Amsterdam, Copenhagen, and Vienna are bundling assembly, maintenance, and end-of-life retrieval into monthly fees. This reconfiguration shifts capital expenditure from consumers to inventory-heavy operators, concentrating credit risk with fleet managers rather than retail networks.
Ready-To-Assemble (RTA) Furniture Market Segmentation
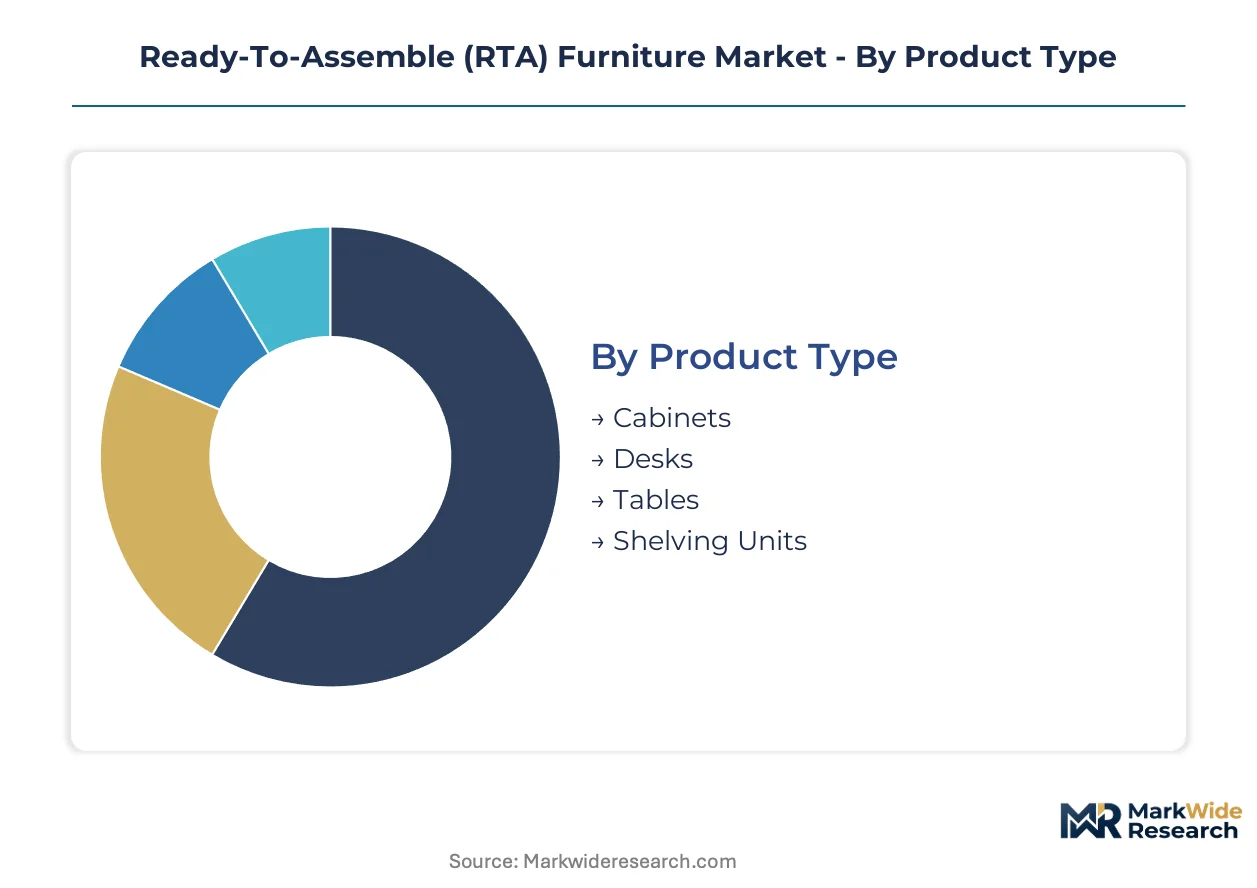
Segmentation in the RTA furniture market reveals how flat-pack engineering adapts to distinct performance requirements and purchasing contexts. Material specifications and distribution channels determine compliance pathways and margin structures across residential and commercial deployments.
Product Type:
Standalone storage systems dominate residential procurement, while integrated workspace solutions embed into multi-functional living environments.
- Cabinets:Enclosed storage systems with hinged doors and adjustable shelving, typically constructed from melamine-laminated particle board. Demand concentrates in German and Swedish urban apartments where space optimization overrides aesthetic customization, driven by rental market turnover and frequent relocation patterns.
- Desks:Work surface assemblies with integrated cable management and modular leg configurations. North American suburban households upgrading home offices sustain volume throughput, constrained by dimensional tolerance limits when shipped via parcel networks.
- Tables:Dining and occasional surface units with knock-down leg attachments. Commercial food service and co-working spaces in Copenhagen and Amsterdam favor reconfigurable geometries.
- Shelving Units:Open-frame storage with adjustable tier heights. Retail back-of-house and educational library systems in France and Poland specify heavy-duty load ratings.
Volume placements concentrate in Cabinets; the faster expansion belongs to Desks.
Material:
Cost tier stratification separates commodity panel products from premium solid wood offerings, with mid-grade fiberboard capturing the largest addressable base.
- Particle Board:Resin-bonded wood chips pressed into uniform panels, valued for dimensional stability and lamination compatibility. CARB Phase 2 compliance costs have compressed margins for North American producers sourcing urea-formaldehyde alternatives.
- MDF:Fine wood fiber panels with smooth surface quality ideal for painted finishes and intricate routing. Moisture absorption sensitivity restricts bathroom and outdoor applications in humid climates.
- Plywood:Cross-laminated veneer construction offering screw-holding strength and edge durability. Premium kitchen and children's furniture segments in Germany specify birch and beech variants.
- Solid Wood:Natural lumber components with visible grain and joinery, commanding price premiums in Scandinavian design markets. Limited flat-pack compatibility constrains scalability.
Particle Board commands the highest shipment volumes; solid wood is climbing the fastest as sustainability credentials reshape purchasing criteria.
End User:
Application context determines assembly complexity tolerance and durability specifications across residential and institutional procurement.
- Households:Individual consumers purchasing for primary residences, secondary homes, or rental properties. Millennial first-time buyers in Berlin and Vienna drive online discovery and direct-to-consumer fulfillment.
- Offices:Corporate procurement of workstations, storage, and meeting furniture. Distributed workforce policies have fragmented bulk purchasing into decentralized facility budgets.
- Retail Stores:Merchandising fixtures, backroom storage, and customer seating requiring rapid reconfiguration. Seasonal turnover demands quick-assembly designs with minimal tool requirements.
- Educational Institutions:Dormitory, classroom, and administrative furniture subject to public tender processes. Extended producer responsibility mandates in France influence material selection.
Households generate the dominant order flow; educational procurement is gaining share fastest as infrastructure renewal programs accelerate.
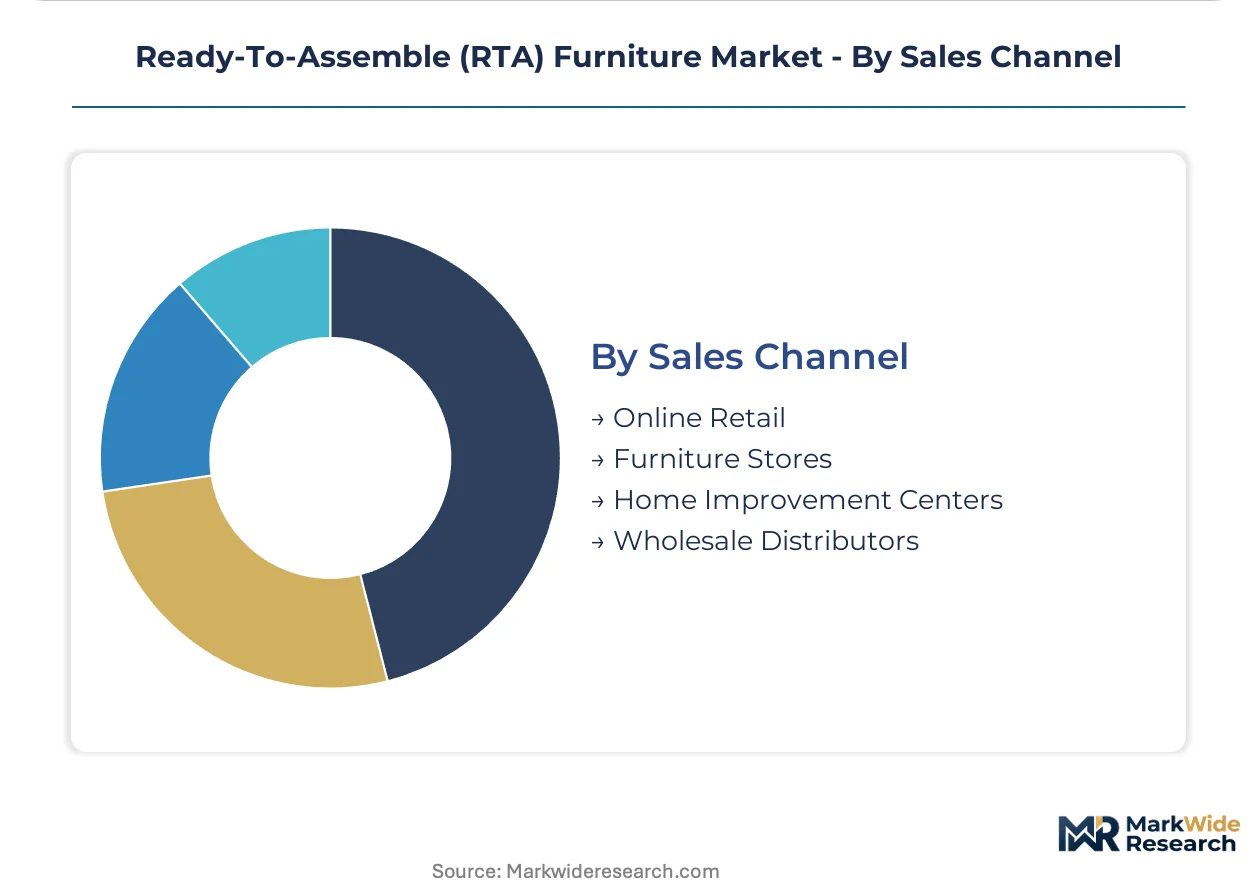
Sales Channel:
Customer type and geography dictate channel preference, with digital penetration varying sharply by age cohort and urban density.
- Online Retail:Direct-to-consumer platforms and marketplace listings with AR-assisted assembly guidance. Return rate reduction through virtual pre-purchase visualization is reshaping logistics economics.
- Furniture Stores:Physical showrooms with tactile evaluation and white-glove delivery options. Suburban and rural markets in Poland and Hungary retain dependence on in-person selection.
- Home Improvement Centers:Big-box retailers with self-serve pickup and project bundling. Weekend DIY traffic patterns align with storage and garage organization categories.
- Wholesale Distributors:B2B volume procurement serving property management, hospitality, and institutional clients. Credit terms and project financing differentiate competitive positioning.
Online retail is expanding most quickly; furniture stores retain the largest transaction value per order.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones have concentrated particle board laminating operations, drawing melamine-impregnated paper suppliers into clustered manufacturing corridors that serve export-oriented flat-pack producers.
United States
Suburban home office conversions sustain desk and storage category demand across Texas and Florida metro corridors. The EPA's formaldehyde emission standards under the Toxic Substances Control Act govern engineered wood imports. North Carolina's Piedmont Triad hosts specialized MDF fabrication facilities serving big-box retail distribution networks.
Germany
Berlin and Hamburg rental market turnover drives frequent furniture replacement cycles among urban graduates. The EU Ecolabel and FSC chain-of-custody certification create mandatory listing prerequisites for retail distribution. North Rhine-Westphalia's Ruhr industrial belt concentrates panel pressing operations with integrated adhesive formulation capabilities.
China
Guangdong and Zhejiang provinces export knock-down furniture components to European and North American assembly operations. The Ministry of Ecology and Environment enforces dual carbon goals that reshape resin system sourcing decisions. Dongguan's manufacturing cluster specializes in cam-lock fastener and hardware kit production for global supply chains.
Poland
Warsaw and Krakow micro-apartment construction normalizes modular, reconfigurable storage systems for young professional households. Extended producer responsibility frameworks under EU packaging waste directives mandate take-back program readiness. Lower Silesia's woodworking belt hosts particle board laminating operations with German retail supply contracts.
Ready-To-Assemble (RTA) Furniture Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: global design-to-flat-pack operators with captive retail networks, regional panel fabricators with specialized MDF capabilities, and direct-to-consumer platforms with augmented reality assembly tools. Competitive moves concentrate on geographic expansion into Central European e-commerce corridors and backward integration into adhesive formulation operations.
Among Scandinavian-anchored global operators, IKEA exemplifies the design-to-flat-pack archetype with supply chain density across multiple continents. Sauder Woodworking Co. and Dorel Industries Inc. represent North American manufacturing specialists with integrated distribution networks spanning juvenile, home, and commercial furniture segments. These three companies occupy distinct competitive positions without direct overlap in core operational models.
| Leading Market Players |
|---|
| IKEA |
| Sauder Woodworking Co. |
| Dorel Industries Inc. |
| Tvilum A/S |
| Whalen Furniture |
| Walker Edison Furniture Company LLC |
| South Shore Furniture |
| Wayfair |
| Zinus Inc. |
| Others |
Pricing and Supply Chain Analysis
California's CARB Phase 2 formaldehyde emission standards gate qualified supply for premium-tier RTA furniture access, forcing adhesive reformulation investments that stratify manufacturers between certified and non-compliant tiers while reshaping procurement premiums across North American and European distribution networks.
Pricing Analysis
Margin tightening in mid-grade particle board reflects resin input volatility tied to natural gas benchmarks and the cost of urea-formaldehyde substitution trials. Three-tier pricing structure across premium, standard, and economy levels separates FSC-certified birch plywood products from CARB-compliant MDF and commodity particle board alternatives. Price differentiation hinges on certification grade and geographic delivery cost, with German and Scandinavian buyers absorbing premiums for EU Ecolabel compliance. First-time millennial buyers in urban apartments exhibit highest price sensitivity, while institutional procurement in educational and corporate segments prioritizes durability specifications over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany's Ruhr belt and North Carolina's Piedmont Triad anchor hub-and-spoke patterns serving big-box retail and direct-to-consumer channels. Manufacturing concentrates in China, Poland, and Germany, with Guangdong and Zhejiang provinces supplying cam-lock hardware and melamine-impregnated decorative paper. Raw material dependencies include methanol-formaldehyde feedstocks, birch and beech veneer, and soy-based adhesive alternatives. Single-source vulnerability risks cluster in Asian melamine paper production. Distribution runs through integrated retail networks and third-party logistics providers with last-mile optimization for parcel-scale flat-pack delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Augmented reality assembly guidance is displacing legacy printed instruction manuals, compressing return rates and customer service costs for direct-to-consumer operators while resetting competitive minimums for digital customer experience.
For Market Incumbents: To counter subscription furniture platforms displacing outright ownership in Amsterdam, Copenhagen, and Vienna, IKEA and Sauder Woodworking Co. should deepen captive supply of bio-based adhesive formulations and acquire AR-assisted assembly technology capabilities to defend channel control against digitally native entrants. For New Entrants and Emerging Players: REACH Annex XVII restrictions on formaldehyde-releasing substances in Europe open a window for phenol-formaldehyde and soy-based adhesive specialists to capture share in cabinet and children's furniture segments. White-space targets include rural e-commerce corridors in Poland, Hungary, and Romania with optimized last-mile delivery, and rental-subscription bundling for urban graduate households in Berlin and Stockholm. For Investors and Strategic Acquirers: Mandatory extended producer responsibility frameworks in Germany and France are the leading indicator that closed-loop material recovery capabilities will separate viable acquisition targets from stranded asset risks. Focus on mid-scale manufacturers with FSC chain-of-custody certification and integrated adhesive formulation operations, watching for take-back program mandates as the inflection signal for valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adhesive Formulation | Captive supply of CARB Phase 2 and REACH-compliant resin systems insulates margin from methanol feedstock volatility. |
| AR-Assisted Assembly Platform Launch | Virtual pre-purchase visualization reduces return rates for Wayfair and Zinus direct-to-consumer fulfillment operations. |
| Closed-Loop Take-Back Program | Extended producer responsibility compliance in Germany and France creates competitive differentiation for circular material recovery. |
| Rural E-Commerce Channel Expansion | Last-mile optimization in Poland, Hungary, and Romania captures underserved postal codes outside major metro furniture store networks. |
| Bio-Based Binder Certification Investment | Soy-based and phenol-formaldehyde adhesive trials position suppliers for REACH Annex XVII emission threshold tightening. |
Research Methodology
Document review covered trade association filings, customs records for particle board and MDF imports, EPA and ECHA regulatory dockets, and company sustainability disclosures, complemented by interviews with RTA furniture product development directors, big-box retail category buyers, adhesive formulation chemists, and flat-pack logistics specialists. Secondary validation drew from CARB emission testing databases, FSC chain-of-custody audit reports, and EU packaging waste directive implementation trackers. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Cross-referencing historical shipment data against panel manufacturer production surveys and retail point-of-sale tracking informed the analytical framework. Segmentation dimensions modeled include product type, material grade tier, end-use application, and sales channel complexity. CAGRs were derived from slope analysis of validated baseline data projected through the forecast period, incorporating remote-work furniture demand indices, urban apartment construction permits, and e-commerce penetration rates as industry-specific inputs.
The model assumes a particular technology adoption path for augmented reality assembly tools and bio-based adhesive substitution; alternative pathways for soy-based binder commercialization or AR hardware cost curves would alter the outlook. Forecasts reflect documented assumptions around regulatory enforcement timing and consumer willingness-to-pay for sustainability credentials. Decision-makers should treat outputs as directional within the stated assumption set, recognizing that resin feedstock price shocks or accelerated extended producer responsibility mandates could materially revise trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Armchair on Casters Market
Furniture
Kids and Nursery Furniture Market
Furniture
Bounding Table Market
Furniture
Netherlands Home Furniture Market
Furniture
GCC Smart Furniture Market
Furniture
Europe Sustainable Home Furniture Market
Furniture
Indonesia Home Furniture Market
Furniture
Saudi Arabia Home Furniture Market
Furniture
Poland Home Furniture Market
Furniture
Fireplace Mantels Market
Furniture
United Arab Emirates Furniture Market
Furniture
US Secondary Wood Products Market
Furniture
Recliner Chair Market
Furniture
HORECA Furniture Market
Furniture
North America School Furniture Market
Furniture
Eco-Friendly Furniture Market