
 Smart Finance Connectivity Market | 2026-2036
Smart Finance Connectivity Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Finance Connectivity Market Intelligence
Enterprise buyer concentration among tier-one retail banks is restructuring procurement patterns across the Smart Finance Connectivity landscape. Visa Inc. leverages its network infrastructure to sustain dominance in tokenized payment corridors. Mastercard Inc. anchors real-time clearing capabilities across multiple continental hubs. Stripe competes aggressively on developer-centric API architectures that reduce integration friction for mid-market financial institutions.
Smart Finance Connectivity denotes the integrated hardware, software, and protocol layers that enable secure, real-time data exchange between financial institutions, end-users, and third-party service providers, typically operating through RESTful APIs with sub-100 millisecond latency requirements and AES-256 encryption standards. Its primary commercial purpose centers on eliminating fragmentation across payment rails, trading systems, and wealth management portals while maintaining regulatory-compliant audit trails. Payment Solutions within the Service Type dimension occupies the largest current revenue pool as legacy ACH and card networks undergo API modernization, while AI Applications across the Technology dimension represents the fastest-expanding segment as predictive risk scoring and conversational interfaces penetrate retail and institutional workflows alike. Hybrid Cloud deployment models are capturing disproportionate margin expansion by balancing latency-sensitive on-premise cores with elastic public cloud bursts for batch analytics.
The US Office of the Comptroller of the Currency and the Federal Reserve Board shape domestic market access through open banking guidance and real-time payment infrastructure mandates, while the European Banking Authority enforces PSD2-driven account aggregation and strong customer authentication standards that dictate product architecture across the continent. The Monetary Authority of Singapore and the Reserve Bank of India impose similarly granular data localization and consent-management frameworks that vendors must embed natively. Stakeholders must monitor which regulatory jurisdiction's compliance timeline becomes the binding constraint for their platform roadmaps.
Market Dynamics
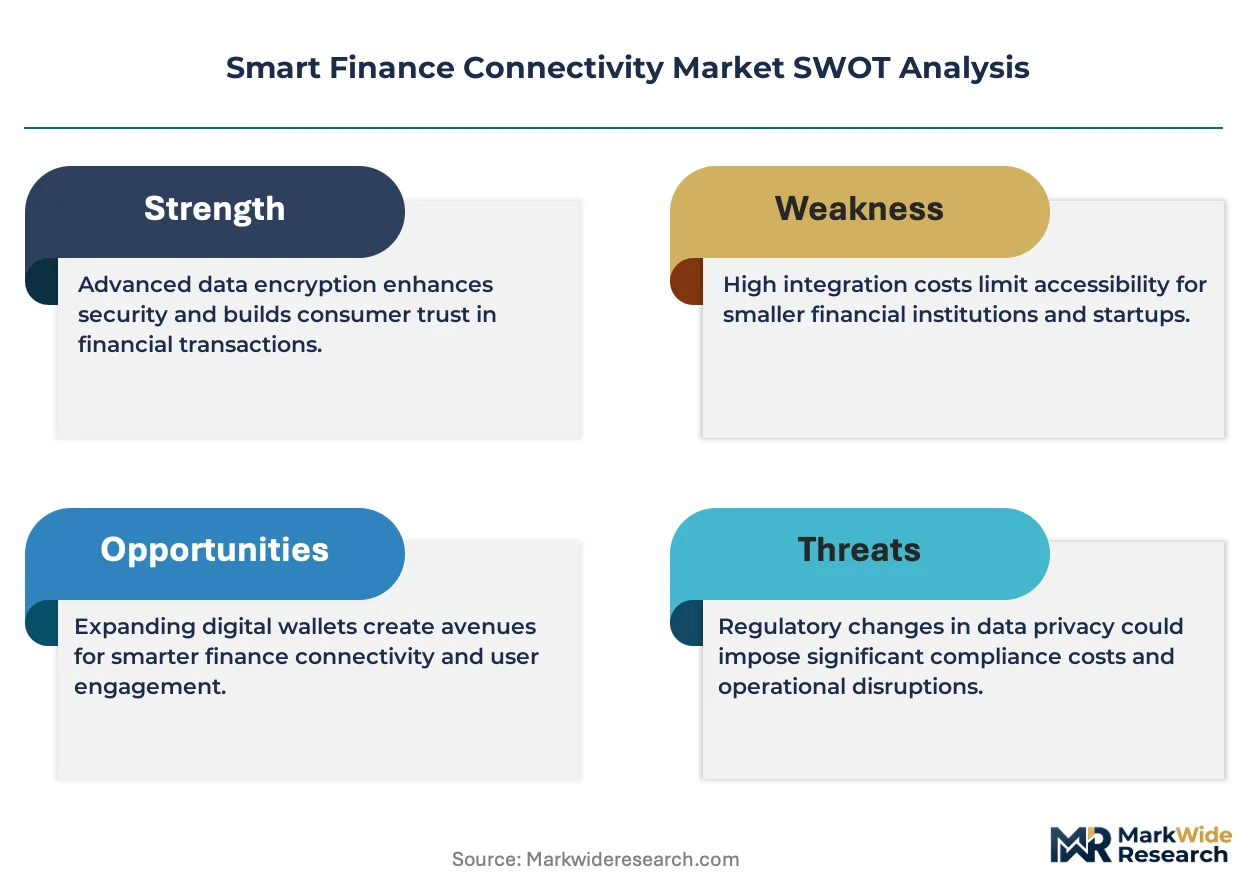
Open banking mandates under PSD2 and equivalent frameworks are dismantling legacy data silos across retail banking, forcing institutions to rebuild core infrastructure around API-first architectures with real-time interoperability requirements.
Growth Catalysts
- PSD2 Strong Customer Authentication:European retail banks must expose account data through standardized APIs, creating mandatory procurement cycles for connectivity middleware.
- Real-time payment rails:The Federal Reserve's FedNow service and equivalent instant settlement networks in the United Kingdom and Singapore are compressing transaction windows from days to seconds.
- Embedded finance penetration:Non-bank platforms in e-commerce and mobility services are white-labeling banking functions, expanding addressable demand beyond traditional financial institutions.
Market Restraints
- Core system replacement costs:Mainframe-dependent institutions face capital outlays exceeding typical three-year IT budgets to achieve API-native infrastructure.
- Specialized engineering scarcity:Talent pools for financial-grade cryptography and low-latency protocol design concentrate in London, New York, and Singapore, creating hiring bottlenecks elsewhere.
- Data localization fragmentation:India's Reserve Bank and China's central bank impose conflicting residency requirements that fragment cloud deployment strategies.
Strategic Opportunities
- Wealth management API penetration:Discretionary portfolio services in Germany and Switzerland remain under-automated relative to payments, creating whitespace for robo-advisory connectivity layers.
- AI-driven risk orchestration:Convergence of machine learning inference with streaming transaction data enables predictive fraud detection at authorization-time latency thresholds.
- India's account aggregator framework:The RBI's consent-based data sharing architecture is mandating new infrastructure for hundreds of regional banks lacking in-house development capacity.
Industry Challenges
- ISO 20022 migration complexity:Cross-border payment networks require message format standardization that demands multi-year transformation programs for correspondent banking relationships.
- Multi-cloud orchestration:Hybrid deployments spanning on-premise cores, private cloud, and hyperscaler instances introduce latency variance and security perimeter fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Finance Connectivity Market |
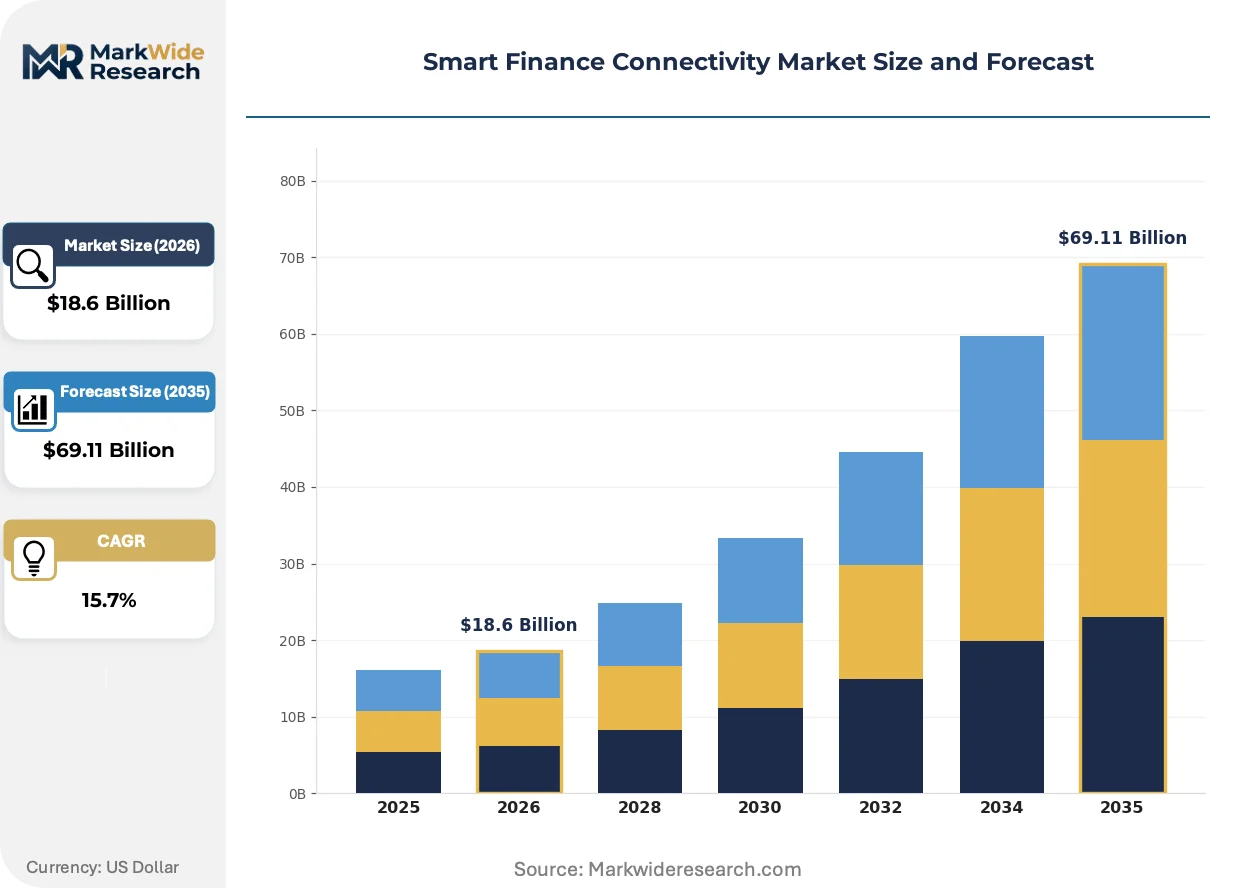
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $69.11 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | End User Type: Investment Firms, Financial Advisors, Hedge Funds, Retail Investors Service Type: Wealth Management, Trading Platforms, Payment Solutions, Financial Analytics Technology: Blockchain, AI Applications, Cloud Computing, IoT Solutions Deployment Model: On-Premise, Public Cloud, Private Cloud, Hybrid Cloud |
| Companies Covered | Visa Inc., Mastercard Inc., PayPal Holdings Inc., Stripe, Adyen, Fiserv, Diebold Nixdorf, Incorporated, Digi International Inc., IMS Evolve, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Finance Connectivity Market Strategic Shifts & Innovations
Distributed ledger protocols and programmable settlement layers are reconfiguring trust architectures in wholesale financial markets, displacing traditional correspondent banking relationships with atomic settlement mechanisms.
Blockchain-based tokenization of money-market instruments and sovereign debt is decentralizing custody and clearing functions that historically concentrated in central securities depositories. Institutional treasurers at asset managers and corporate finance functions are piloting these instruments for intraday liquidity management. The structural consequence is compressing counterparty exposure windows from T+2 settlement cycles to real-time delivery-versus-payment.
Europe's Digital Operational Resilience Act imposes mandatory ICT risk management frameworks and incident reporting thresholds across payment service providers and critical financial market infrastructure. Firms must map third-party dependencies and conduct threat-led penetration testing at 12-month intervals. Cloud service providers serving EU-headquartered banks are restructuring contractual liability clauses and data processing agreements to satisfy DORA's direct oversight provisions.
Enterprise buyers are unbundling connectivity procurement from core banking system contracts, creating standalone vendor relationships for API management and tokenization services. Tier-two institutions in the United States and United Kingdom are bypassing traditional core banking vendors to contract directly with specialized fintech infrastructure providers. This pattern concentrates procurement leverage with chief technology officers rather than traditional vendor relationship managers.
Smart Finance Connectivity Market Segmentation
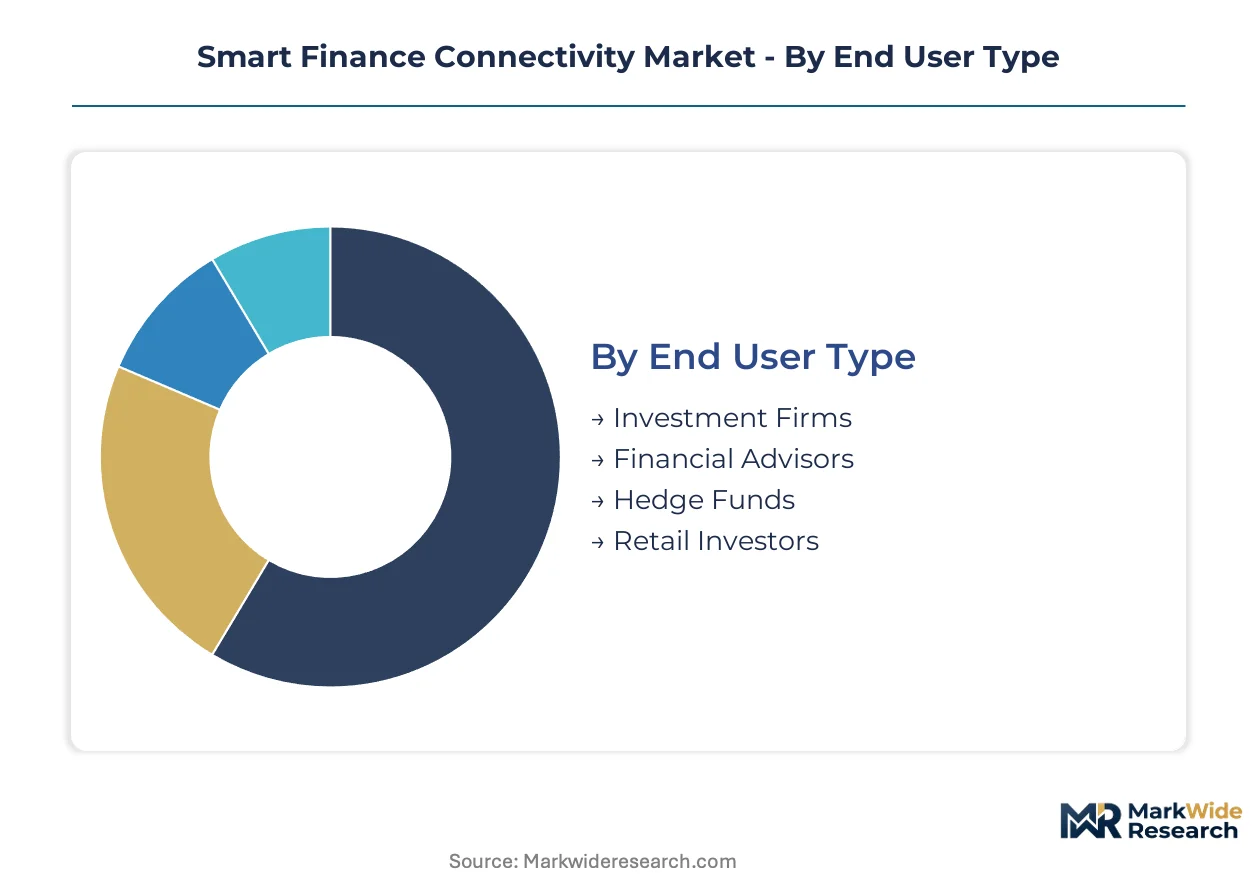
Smart Finance Connectivity architectures must align infrastructure investment with distinct latency, security, and integration requirements across user types and service modalities. Segmentation reveals where API-native platforms displace legacy middleware versus where embedded connectivity layers suffice.
End User Type:
Investment Firms operate standalone trading infrastructure demanding sub-millisecond co-location access, while Retail Investors consume connectivity through embedded mobile brokerage applications with tolerance for higher latency.
- Investment Firms:Institutional asset managers deploy direct market access APIs for equity and fixed-income execution, with procurement concentrating among quantitative funds in the United States and United Kingdom where regulatory latency requirements are most stringent. Capital markets infrastructure spending here tracks trading volume volatility rather than steady-state AUM growth.
- Hedge Funds:Systematic and multi-strategy funds require normalized data feeds across fragmented liquidity venues, driving demand for cross-asset connectivity layers that aggregate alternative trading systems and dark pools. Prime brokerage relationships in London and New York determine vendor selection criteria.
- Financial Advisors:Registered investment advisors rely on custodial API integrations for portfolio rebalancing and performance reporting, with technology adoption concentrated among hybrid robo-advisory platforms.
- Retail Investors:Self-directed brokerage users access markets through mobile-first interfaces, with connectivity abstracted behind platform providers rather than direct infrastructure relationships.
Investment Firms lead volumes today; Retail Investors are gaining share fastest through commission-free platform expansion.
Service Type:
Payment Solutions command the largest current procurement cycles as legacy ACH and card networks undergo mandatory API modernization, while Financial Analytics represents the emerging margin expansion opportunity.
- Payment Solutions:Real-time payment rails including FedNow and equivalent instant settlement networks require ISO 20022 message transformation layers. Demand concentrates among tier-one retail banks in Germany and Singapore where regulatory deadlines for legacy system retirement are binding.
- Wealth Management:Discretionary portfolio services in Switzerland and Germany remain under-automated relative to payments, creating whitespace for robo-advisory connectivity layers that unify custody, reporting, and rebalancing functions. Private banks face compressed margins that favor outsourced infrastructure over in-house development.
- Trading Platforms:Multi-asset execution venues require normalized connectivity to fragmented liquidity sources, with procurement decisions driven by co-location proximity to major exchange data centers.
- Financial Analytics:Streaming risk calculation and predictive scoring engines demand GPU-accelerated inference pipelines integrated with transaction data flows.
Payment Solutions anchor current revenue; Wealth Management is climbing the fastest as advisory digitization accelerates.
Technology:
AI Applications and Blockchain occupy opposite ends of the maturity spectrum, with cloud-native machine learning pipelines achieving production scale while distributed ledger protocols remain in institutional pilot phases.
- AI Applications:Predictive fraud detection and conversational interfaces penetrate retail and institutional workflows alike, with inference latency requirements driving edge computing deployments alongside core cloud infrastructure. Natural language processing for regulatory document analysis concentrates among compliance technology vendors in London and New York.
- Blockchain:Tokenized money-market instruments and atomic settlement mechanisms reconfigure wholesale market trust architectures, displacing traditional correspondent banking relationships. Institutional treasurers at asset managers pilot these instruments for intraday liquidity management.
- Cloud Computing:Elastic compute and storage resources enable burst capacity for batch analytics and regulatory reporting without permanent infrastructure commitment.
- IoT Solutions:Connected point-of-sale terminals and embedded payment hardware extend connectivity to physical commerce environments with offline transaction queueing capabilities.
Cloud Computing underpins current deployment; AI Applications show the steepest expansion trajectory as model serving infrastructure matures.
Deployment Model:
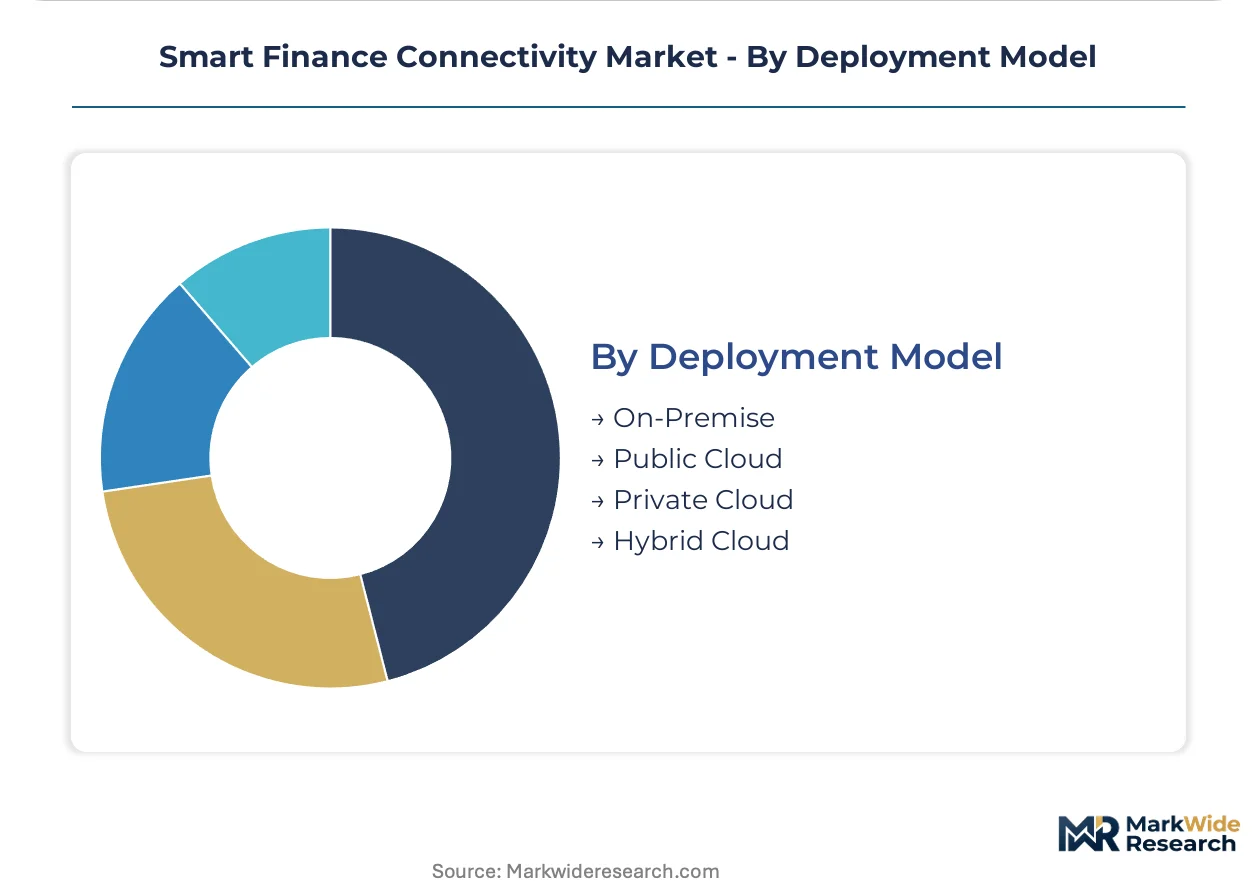
Latency sensitivity and data residency requirements fragment deployment strategies across on-premise cores, sovereign cloud instances, and elastic public cloud bursts.
- Hybrid Cloud:Balances latency-sensitive on-premise transaction processing with elastic public cloud capacity for batch analytics and model training. India's Reserve Bank and China's central bank impose conflicting residency requirements that fragment multi-cloud orchestration strategies.
- Private Cloud:Dedicated infrastructure meets stringent European Banking Authority data processing requirements for payment service providers under PSD2 and DORA frameworks.
- On-Premise:Mainframe-dependent institutions maintain legacy cores for core banking functions while layering API gateways for regulatory interoperability.
- Public Cloud:Hyperscaler instances serve development environments and non-production workloads with consumption-based economics.
Hybrid Cloud dominates new procurement; Private Cloud is expanding most quickly among EU-regulated institutions responding to DORA oversight provisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States outpaces Germany in real-time payment infrastructure deployment, while Singapore matches London's regulatory sophistication with stricter data localization mandates. National regulatory timelines now determine vendor procurement cycles more than technology readiness.
United States
The Federal Reserve's FedNow service and OCC open banking guidance are accelerating core system replacements among regional banks. The SEC's custody rule amendments reshape connectivity requirements for investment advisors. New York and San Francisco host the densest concentrations of fintech infrastructure engineering talent.
Germany
PSD2 strong customer authentication deadlines and BaFin's DORA implementation timeline compress procurement windows for savings banks. The Bundesbank's instant payment settlement mandate eliminates batch processing tolerance. Frankfurt's banking cluster drives demand for ISO 20022 message transformation layers.
United Kingdom
The Financial Conduct Authority's open banking standards and PSR's reimbursement rules for authorized push payment fraud reshape liability architectures. The Bank of England's real-time gross settlement modernization demands sub-second latency compliance. London's Square Mile concentrates prime brokerage connectivity procurement.
Singapore
MAS data localization requirements and Project Guardian's tokenized asset pilots create dual compliance burdens for wealth management platforms. The FAST instant payment network mandates API-native infrastructure for all retail banks. The Marina Bay financial district anchors Southeast Asia's connectivity engineering hub.
India
RBI's account aggregator framework and UPI volume thresholds force hundreds of regional banks into outsourced connectivity partnerships. The central bank's data storage localization rules fragment cloud deployment strategies. Mumbai and Bangalore concentrate domestic fintech infrastructure development capacity.
Smart Finance Connectivity Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across procurement tiers, creating a bifurcated vendor landscape. Tier-one retail banks favor end-to-end platform contracts with established network operators, while mid-market institutions unbundle connectivity from core banking systems. Three archetypes dominate: global payment networks with tokenization infrastructure, developer-centric API platforms, and specialized middleware vendors for legacy system integration. Competitive moves concentrate on strategic partnerships with cloud hyperscalers and vertical integration into fraud detection capabilities.
Within the network infrastructure tier, Visa Inc. and Mastercard Inc. occupy positions defined by real-time clearing scale and tokenized payment corridor dominance. Stripe exemplifies the developer-centric archetype, anchoring procurement patterns among mid-market financial institutions seeking reduced integration friction. These three entities represent distinct competitive vectors—incumbent network reach, incumbent network reach, and API-native agility—rather than overlapping market contests.
| Leading Market Players |
|---|
| Visa Inc. |
| Mastercard Inc. |
| PayPal Holdings Inc. |
| Stripe |
| Adyen |
| Fiserv |
| Diebold Nixdorf, Incorporated |
| Digi International Inc. |
| IMS Evolve |
| Others |
Cost & Logistics Intelligence
Cloud infrastructure spot pricing indices from AWS, Azure, and Google Cloud Platform cascade through Smart Finance Connectivity procurement tiers, compressing margins for API gateway providers serving mid-market banks while sustaining premium pricing for sub-millisecond co-location services in Frankfurt and Singapore. This cost transmission mechanism stratifies vendor economics across deployment models and latency requirements.
Pricing Analysis
Capacity additions in hyperscaler regions are reshaping price floors for cloud-native connectivity layers, forcing traditional middleware vendors toward consumption-based SaaS models. Pricing stratifies across premium co-location, standard API gateway, and economy batch-processing tiers, with differentiation driven by latency SLAs and encryption certification levels. Cost compression in standard tiers is intensifying because hyperscalers bundle financial services compliance into base compute pricing. Regional banks exhibit highest price sensitivity; quantitative hedge funds demonstrate lowest.
Supply Chain Analysis
Refurbishment flows for legacy mainframe connectivity hardware create secondary supply channels for tier-two institutions modernizing on constrained budgets. Component sourcing concentrates in Taiwan for semiconductor fabrication, Ireland for European data center infrastructure, and India for software engineering capacity. Raw material dependencies span silicon wafers, specialized optical transceivers, and cryptographic security modules. Single-source vulnerability in advanced chip fabrication threatens delivery timelines. Distribution runs through direct enterprise sales for tier-one banks and channel partners for mid-market institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where PSD2 strong customer authentication deadlines and FedNow deployment timelines generate recurring procurement cycles independent of macroeconomic conditions. Compliance-driven infrastructure replacement creates predictable demand visibility for connectivity vendors.
For Market Incumbents: Extend tokenization infrastructure into real-time payment corridors before developer-centric platforms capture FedNow integration contracts. Incumbents must consolidate prime brokerage connectivity relationships in London and New York against API-native challengers. Backward integration into cloud hyperscaler partnerships secures capacity allocation during demand surges. Investment in ISO 20022 message transformation capabilities defends correspondent banking revenue pools.
For New Entrants and Emerging Players: Enter via India's account aggregator framework where hundreds of regional banks lack in-house API development capacity. Wealth management connectivity in Switzerland and Germany presents the most penetrable whitespace relative to saturated payment solutions. A direct-to-CTO sales motion bypassing traditional vendor relationship managers accelerates procurement cycles among tier-two institutions unbundling connectivity from core banking contracts.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized middleware vendors possessing legacy system integration expertise that hyperscalers cannot replicate internally. Long-term viability hinges on recurring revenue concentration among regulated institutions with multi-year compliance roadmaps. Acquisition targets should demonstrate embedded relationships with European savings banks facing DORA implementation deadlines. Practitioners should monitor RBI consent-architecture deployment velocity and BaFin enforcement patterns for early demand signals.
| Strategic Initiative | Industry Significance |
|---|---|
| API Gateway Modernization | FedNow and instant payment rails demand sub-100 millisecond latency compliance from regional banks. |
| Hybrid Cloud Certification | EBA and MAS data residency frameworks require sovereign cloud instances with embedded encryption. |
| AI Risk Orchestration Integration | GPU-accelerated inference pipelines enable predictive fraud detection at authorization-time thresholds. |
| ISO 20022 Transformation | Cross-border payment networks mandate message format standardization for correspondent banking relationships. |
| Wealth Management Platform Expansion | Robo-advisory connectivity layers capture margin expansion in under-automated discretionary portfolio services. |
Research Approach
Bottom-up financial institution procurement modeling reconciled against top-down cloud infrastructure spending tracking forms the analytical core of this study. Primary interviews with chief technology officers at tier-one retail banks, API product managers at payment networks, regulatory compliance leads at European savings banks, and infrastructure procurement officers at asset managers were validated against secondary sources including SEC 10-K filings from listed connectivity vendors, ECB and Federal Reserve payment system reports, and cloud hyperscaler financial services vertical disclosures. Triangulation between demand-side budget allocation surveys and supply-side capacity expansion announcements ensures measurement consistency.
Historical trendline analysis of payment infrastructure spending patterns informed projection frameworks across the analysis window. Segmentation dimensions modeled include service type, deployment model, end user category, and regulatory jurisdiction cluster. CAGRs were derived from regression analysis of procurement cycle timing and compliance deadline clustering. Forecast inputs incorporate FedNow adoption velocity, PSD2 enforcement trajectory, and cloud infrastructure price elasticity estimates specific to financial services workloads.
Inputs from central bank regulatory filings and payment network operator disclosures were available through the study window; gaps in real-time transaction volume data from private blockchain pilots introduce uncertainty bands around distributed ledger adoption forecasts. Practitioners should monitor DORA implementation enforcement patterns and RBI account aggregator licensing velocity for early demand inflection signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Europe Fintech Cloud Market
FinTech
Japan AI in Fintech Market
FinTech
Embedded Finance Market
FinTech
Cloud AI in Fintech Market
FinTech
Robo-Advisory Software Market
FinTech
Middle East AI in Fintech Market
FinTech
AI in Fintech Market
FinTech
Transaction Monitoring Software Market
FinTech
Global Fin Tech Blockchain Market
FinTech
Digital Banking Platform Market
FinTech
Asia-Pacific Fintech Market
FinTech
Asia-Pacific Neo Banking Market
FinTech
Fintech Cloud Market
FinTech
Financial App Market
FinTech
North America Fintech Cloud Market
FinTech
IT Financial Management Tools Market