
 Europe Sustainable Mattress Market | 2026-2036
Europe Sustainable Mattress Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Sustainable Mattress Market Insights
Portuguese natural latex processors is pivoting toward certified organic supply chains to serve European mattress manufacturers. Emma Sleep GmbH leverages direct-to-consumer logistics to control pricing across its home market. Hilding Anders International AB anchors wholesale relationships with major hospitality chains in Scandinavia. Simba Sleep Limited differentiates through hybrid foam-spring designs engineered for circular end-of-life disassembly.
A sustainable mattress incorporates bio-based or recycled inputs—natural latex derived from Hevea brasiliensis sap, organic cotton batting, or repurposed steel coils—manufactured through processes minimizing volatile organic compound emissions and enabling material recovery at product end-of-life. Its primary commercial purpose is to deliver ergonomic sleep surfaces while satisfying environmental performance criteria for building certifications and corporate sustainability procurement. Latex and organic cotton material types command premium positioning as consumers associate botanical sourcing with durability and indoor air quality. The hospitality end-user segment generates concentrated volume from hotel chain refurbishment cycles, while residential direct-to-consumer channels capture higher per-unit margins through subscription-style delivery models.
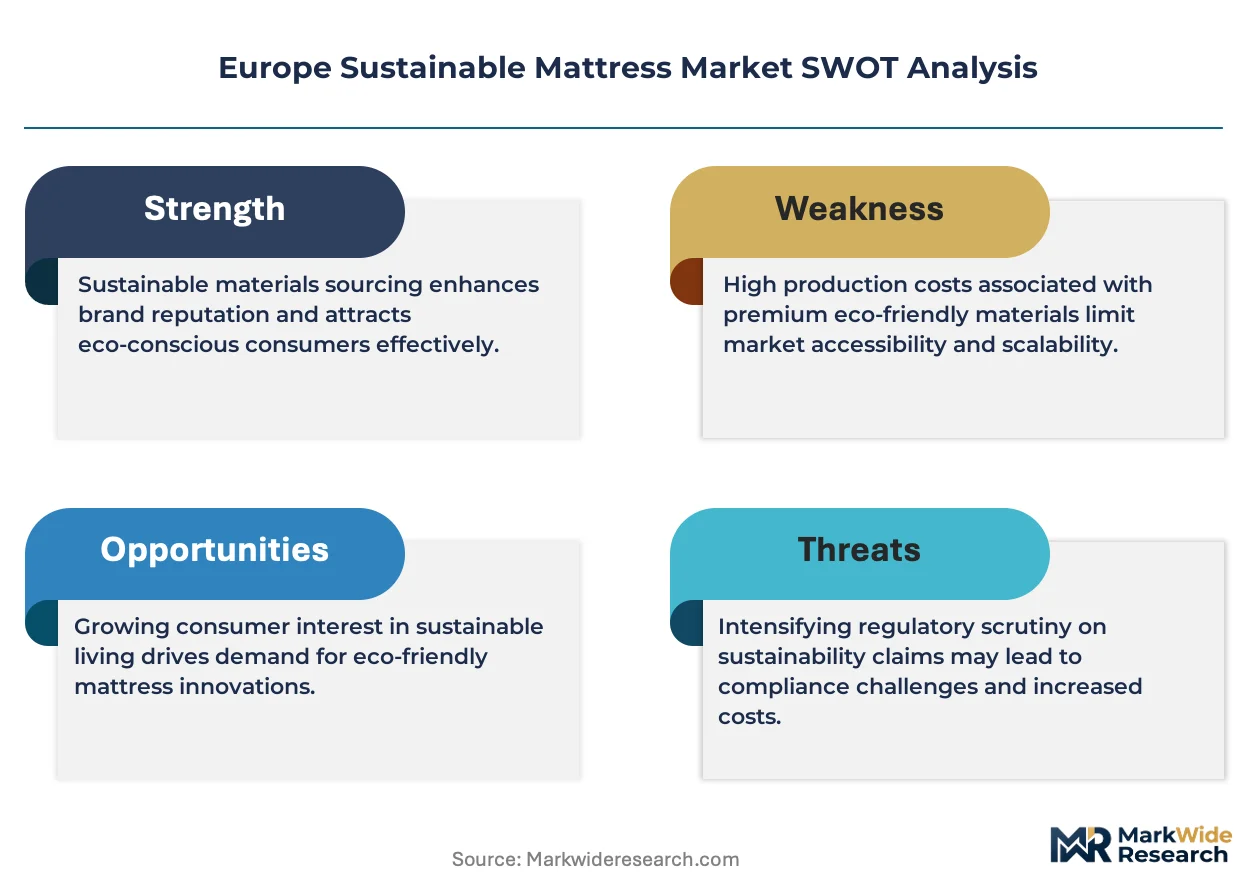
The EU Green Deal sets binding targets for textile circularity that mattress producers must address through design-for-recycling protocols. ECHA REACH regulates chemical content in polyurethane foams, restricting legacy flame retardants and pushing reformulation toward halogen-free alternatives. National extended producer responsibility schemes in France and the Netherlands now assign end-of-life collection costs to manufacturers, reshaping cost structures. Stakeholders must monitor how the EU AI Act and digital product passport requirements will force granular supply chain disclosure across raw material tiers.
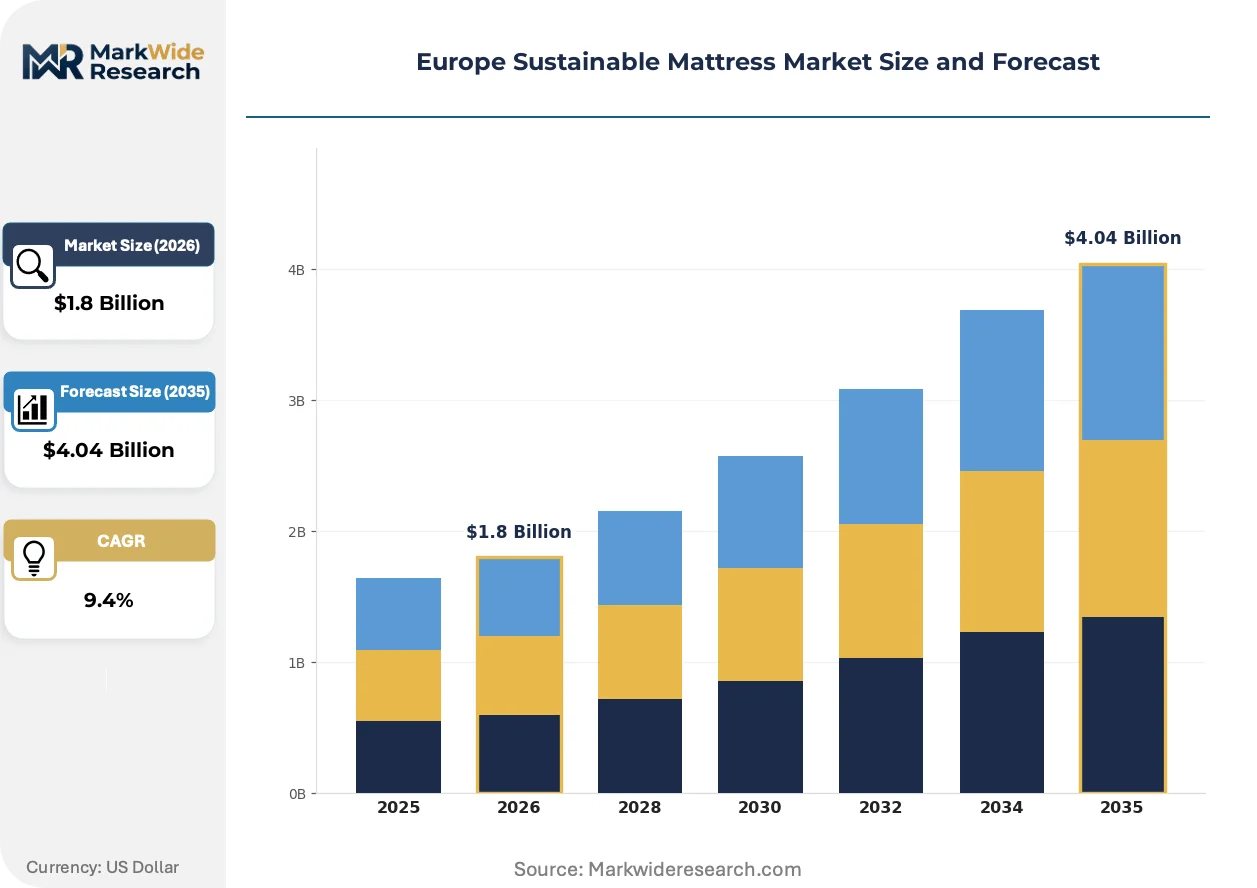
Market Dynamics
EU Green Deal textile circularity mandates and ECHA REACH chemical restrictions are forcing mattress manufacturers to redesign supply chains around certified bio-based inputs and end-of-life material recovery protocols.
Growth Catalysts
- ECHA REACH flame retardant restrictions:Legacy halogenated additives face phase-out deadlines, compelling polyurethane foam reformulation toward bio-based alternatives that qualify for EU Green Deal procurement tenders.
- Hospitality refurbishment cycles:Northern European hotel chains now specify Cradle to Cradle certification in bedding RFPs, concentrating volume demand from Berlin and Munich renovation projects.
- Natural latex processing advances:Portuguese suppliers have scaled certified organic Hevea brasiliensis supply chains, reducing raw material lead times for continental manufacturers.
Market Restraints
- Organic cotton input cost volatility:Climate-driven yield fluctuations in Turkey and Egypt squeeze margin structures for manufacturers dependent on GOTS-certified batting.
- Steel coil supply concentration:Benelux foundries control repurposed spring supply for circular mattress designs, creating single-source vulnerability for mid-tier producers.
- Reformulation technical limits:Halogen-free flame retardants in high-density foams currently fail German BfR migration standards for infant bedding applications.
Strategic Opportunities
- Netherlands extended producer responsibility gaps:Mattress collection infrastructure remains underdeveloped outside Randstad urban corridors, opening logistics partnership entry points.
- Digital product passport readiness:EU AI Act supply chain disclosure requirements will favor early adopters of blockchain-tracked natural latex provenance systems.
- Hybrid channel convergence:Direct-to-consumer subscription models are merging with hospitality bulk procurement platforms, enabling volume-tier pricing without wholesale intermediaries.
Industry Challenges
- Cradle to Cradle certification timeline compression:Material health assessment bottlenecks at accredited labs delay product launches by 8-14 months for reformulated foam lines.
- Circular disassembly skill scarcity:Component separation for steel coil and latex recovery requires retrained technician workforces that German vocational programs have not yet scaled.
- Legacy ERP integration friction:Batch-level chemical tracking for REACH compliance conflicts with existing inventory management systems at mid-sized manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Sustainable Mattress Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Latex, Memory Foam, Organic Cotton, Recycled Materials Distribution Channel: Online Retail, Specialty Stores, Department Stores, Direct-to-Consumer End User: Residential, Hospitality, Healthcare, Student Accommodation Price Tier: Economy, Mid-Range, Premium, Luxury |
| Companies Covered | Emma Sleep GmbH, Tempur Sealy International Inc., Leggett & Platt Incorporated, Relyon Beds Limited, Kingsdown Inc., Hilding Anders International AB, Silentnight Group, Simba Sleep Limited, IKEA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Sustainable Mattress Market Trends and Innovations
Material traceability systems and automated production controls are compressing certification timelines while regulatory disclosure mandates force granular supply chain visibility across raw material tiers.
Blockchain-enabled latex provenance tracking is automating compliance documentation for EU digital product passport requirements. Portuguese processors and German mattress assemblers are piloting shared ledger systems that reduce audit preparation from weeks to hours. This automation is compressing competitive advantage windows for manufacturers still reliant on manual chain-of-custody paperwork.
The EU AI Act's supply chain transparency mandates will require disclosure down to plantation-level Hevea sourcing by 2027. French and Dutch regulators are already enforcing preview standards through national extended producer responsibility schemes. Hospitality procurement teams in Scandinavia now exclude bidders unable to demonstrate tier-three material traceability.
Subscription-style residential delivery is displacing traditional retail showroom purchases among urban German and Austrian consumers. Emma Sleep GmbH and direct-to-consumer rivals have trained buyers to expect compressed trial periods and seamless return logistics. This channel rotation is most visible in Berlin and Munich, where mattress-in-a-box volumes now exceed conventional furniture store sales for certified sustainable product lines.
Europe Sustainable Mattress Market Segmentation
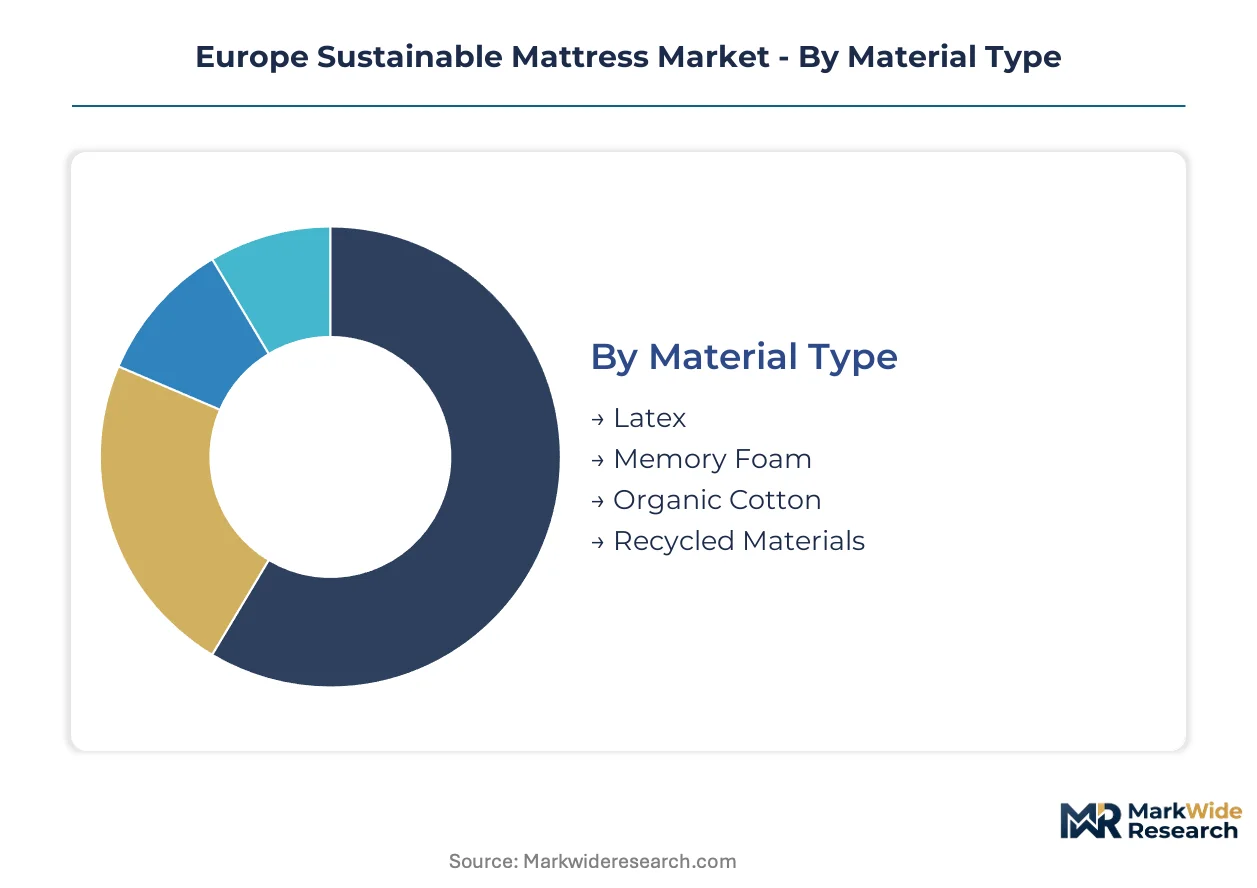
Material composition and distribution economics determine competitive positioning in Europe's sustainable mattress market. Certification requirements and procurement channel evolution create divergent margin structures across segment boundaries.
Material Type:
Buyers prioritize indoor air quality credentials and circular end-of-life recovery potential when selecting mattress composition.
- Latex:Natural Hevea brasiliensis sap formulations dominate hospitality procurement in Germany, where Berlin and Munich hotel renovations specify Cradle to Cradle certification. Portuguese processors have scaled certified organic supply chains, reducing continental manufacturer lead times.
- Organic Cotton:GOTS-certified batting commands premium residential positioning in Austria and Switzerland, though climate-driven yield fluctuations in Turkey and Egypt squeeze margin structures for dependent producers.
- Memory Foam:Bio-based polyurethane reformulations address ECHA REACH flame retardant restrictions, with halogen-free alternatives qualifying for EU Green Deal procurement tenders.
- Recycled Materials:Repurposed steel coils from Benelux foundries enable circular mattress designs, creating single-source vulnerability for mid-tier producers.
Latex leads on scale; organic cotton leads on momentum.
Distribution Channel:
Channel selection reflects buyer price sensitivity and the need for tactile evaluation versus digital convenience.
- Direct-to-Consumer:Subscription-style delivery models trained German and Austrian urban buyers to expect compressed trial periods and seamless return logistics, displacing traditional retail showroom purchases.
- Online Retail:Aggregator platforms consolidate comparison shopping for certified sustainable lines, though margin compression intensifies from platform fee structures.
- Specialty Stores:Physical presence enables Cradle to Cradle certification verification and ergonomic testing, sustaining relevance in premium residential segments.
- Department Stores:Legacy furniture retailers lose share to channel specialists as hospitality procurement migrates to dedicated bedding platforms.
Direct-to-Consumer captures the steepest expansion trajectory; specialty stores retain margin leadership.
End User:
Volume concentration and certification stringency vary sharply across institutional versus residential demand.
- Hospitality:Northern European hotel chains specify certified sustainable bedding in RFPs, concentrating volume demand from refurbishment cycles in Scandinavia and German urban centers.
- Residential:Urban German and Austrian consumers drive mattress-in-a-box volumes exceeding conventional furniture store sales for certified lines.
- Healthcare:German BfR migration standards for infant bedding applications restrict halogen-free flame retardant adoption in high-density foams, limiting material options.
- Student Accommodation:Bulk procurement from university housing authorities prioritizes economy-tier pricing with basic EU Green Deal compliance.
Hospitality leads on scale; residential gains share fastest.
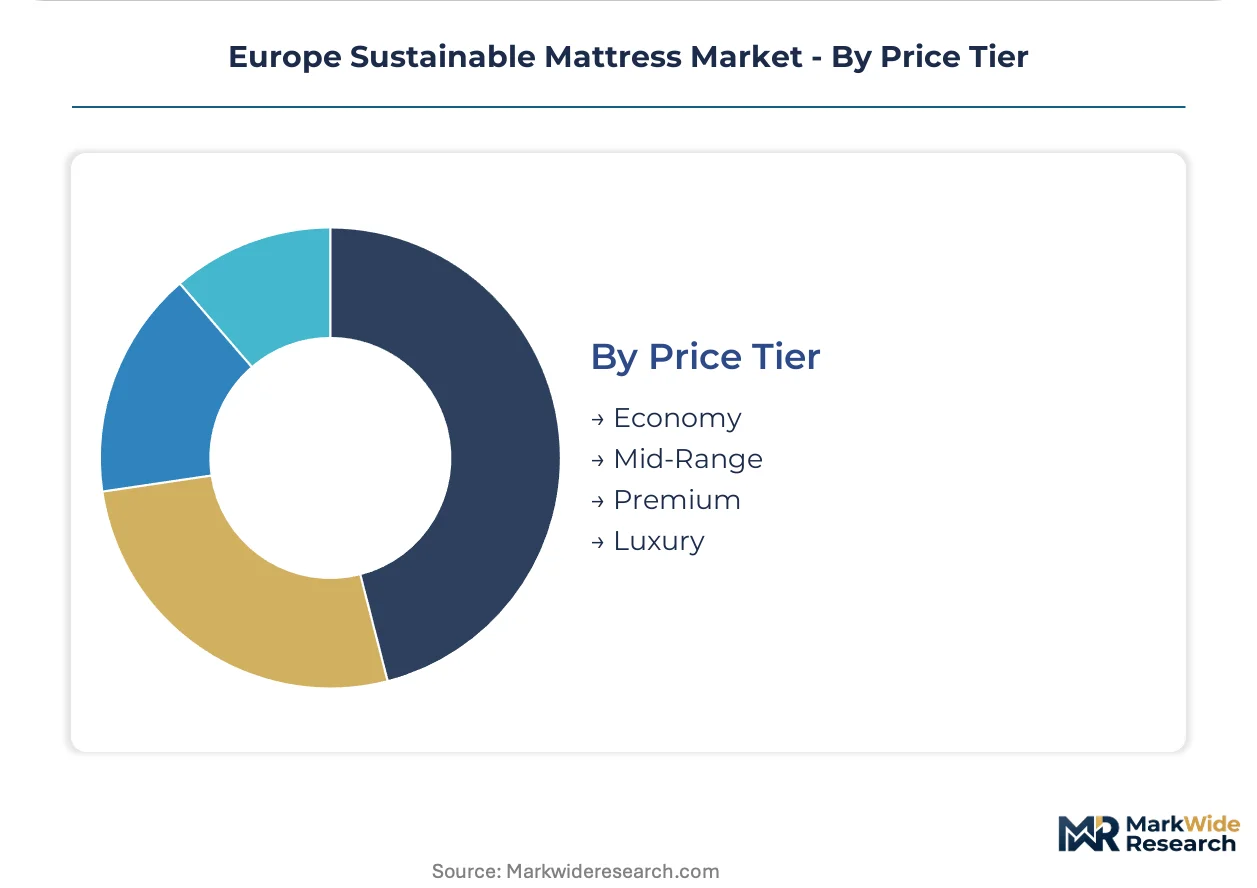
Price Tier:
Premium positioning correlates with certification depth and supply chain traceability investment.
- Premium:Blockchain-tracked natural latex provenance and plantation-level Hevea sourcing disclosure command pricing power ahead of EU AI Act mandates.
- Luxury:Handmade construction with full material recovery protocols targets high-net-worth buyers in Swiss and Austrian alpine resort markets.
- Mid-Range:Hybrid foam-spring designs engineered for circular disassembly balance cost and environmental performance for mass-market adoption.
- Economy:Basic recycled content compliance satisfies minimum EU Green Deal procurement thresholds without traceability investment.
Premium leads on scale; luxury climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers relocate assembly to jurisdictions with lighter compliance burdens while maintaining distribution proximity to high-margin demand centers.
Germany
Hotel refurbishment cycles in Berlin and Munich drive concentrated demand for Cradle to Cradle certified bedding. The German BfR enforces strict migration standards for infant bedding applications, limiting halogen-free flame retardant adoption. Bavaria hosts vocational training programs attempting to scale circular disassembly technician workforces.
Netherlands
Randstad urban corridors dominate mattress collection infrastructure while rural regions present partnership gaps for logistics entrants. Extended producer responsibility schemes assign end-of-life costs directly to manufacturers, reshaping cost structures. Eindhoven-based processors pilot blockchain-tracked natural latex provenance systems ahead of EU AI Act mandates.
France
National extended producer responsibility enforcement previewing EU digital product passport standards excludes bidders lacking tier-three material traceability. The country's textile circularity regulator pressures manufacturers toward design-for-recycling protocols. Paris and Lyon hospitality procurement teams now mandate certified sustainable bedding in chain-wide RFPs.
Sweden
Scandinavian hospitality chains anchor wholesale volume relationships with certified suppliers. Swedish environmental regulators align national standards with EU Green Deal textile circularity targets ahead of formal deadlines. Stockholm and Gothenburg hotel renovation projects concentrate demand for organic cotton and natural latex compositions.
Portugal
Natural latex processors have scaled certified organic Hevea brasiliensis supply chains, reducing raw material lead times for continental European manufacturers. Portuguese agricultural regulators monitor plantation-level sourcing disclosure requirements anticipated under EU AI Act implementation. The Alentejo region hosts expanding organic rubber cultivation clusters serving mattress assemblers.
Europe Sustainable Mattress Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer subscription models and circular design specializations. The vendor base clusters around three strategic archetypes: integrated foam-spring hybrid engineers, pure-play natural material specialists, and platform-agnostic private-label suppliers. Dominant competitive moves include wholesale relationship anchoring with hospitality chains and backward integration into certified organic raw material supply.
Among German-based operators, Emma Sleep GmbH exemplifies the direct-to-consumer archetype through logistics-controlled pricing strategies. Hilding Anders International AB anchors wholesale hospitality relationships across Scandinavian markets. Simba Sleep Limited occupies a position within the circular design tier, represented through hybrid foam-spring architectures engineered for end-of-life disassembly.
| Leading Market Players |
|---|
| Emma Sleep GmbH |
| Tempur Sealy International Inc. |
| Leggett & Platt Incorporated |
| Relyon Beds Limited |
| Kingsdown Inc. |
| Hilding Anders International AB |
| Silentnight Group |
| Simba Sleep Limited |
| IKEA |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up specialists in German mattress assembly anchor pricing discipline through captive logistics networks, while their supply choices concentrate around Portuguese latex processors and Benelux steel foundries to manage ECHA REACH compliance costs.
Pricing Analysis
Retailer markup compression in hospitality procurement channels intensifies margin pressure as Northern European hotel chains consolidate bedding RFPs around Cradle to Cradle certification tiers. Three-tier pricing structure across premium certification, standard compliance, and economy basic levels separates blockchain-tracked plantation-provenance latex from conventional organic cotton and recycled-content entry products. Direct-to-consumer subscription models capture higher per-unit economics by eliminating distributor margin layers, though platform fee structures at online aggregators erode net pricing power. Residential buyers in Berlin and Munich exhibit lowest price sensitivity for certified sustainable lines, while student accommodation procurement teams prioritize economy-tier positioning.
Supply Chain Analysis
Certification gating through EU Green Deal textile circularity mandates and ECHA REACH chemical restrictions funnels qualified suppliers toward Portuguese organic Hevea plantations, Turkish GOTS-certified cotton ginners, and Benelux circular steel foundries. Raw material dependencies center on natural latex sap, organic batting, and repurposed coil springs. Single-source vulnerability concentrates in Benelux foundry capacity for circular mattress designs. Distribution runs through direct-to-consumer compressed delivery platforms and hospitality bulk procurement systems, with specialty stores retaining premium residential channel relevance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe sustainable mattress market reads as a late-cycle quality story as hospitality procurement shifts toward plantation-level traceability specifications ahead of EU AI Act mandates.
For Market Incumbents: Anchor wholesale relationships with Scandinavian and German hospitality chains through Cradle to Cradle certification depth, while backward integration into Portuguese latex processing defends margin position against direct-to-consumer entrants. Prioritize blockchain-tracked provenance systems to meet tier-three disclosure requirements before compliance windows narrow. For New Entrants and Emerging Players: Enter via underdeveloped mattress collection infrastructure in Dutch rural corridors outside Randstad urban clusters, where extended producer responsibility cost structures create partnership entry points. Target economy-tier student accommodation procurement with basic EU Green Deal compliance products, leveraging digital product passport readiness as differentiation against legacy ERP-constrained mid-tier manufacturers. For Investors and Strategic Acquirers: Hospitality-focused private equity is the most active acquirer in this space, rolling up mid-cap specialists with certified organic supply chain control. Five-to-ten year viability hinges on plantation-level sourcing disclosure capabilities. Monitor German BfR migration standard revisions for infant bedding as signal for halogen-free flame retardant reformulation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Organic Supply | Portuguese Hevea plantation control secures ECHA REACH-compliant latex access ahead of disclosure mandates. |
| Blockchain Provenance System Deployment | Shared ledger automation compresses EU digital product passport audit preparation from weeks to hours. |
| Hospitality Procurement Platform Integration | Direct bulk contracting with Berlin and Munich hotel renovators concentrates volume without wholesale intermediaries. |
| Circular Disassembly Workforce Scaling | Bavarian vocational programs address technician scarcity for steel coil and latex recovery operations. |
| Direct-to-Consumer Subscription Launch | Compressed trial periods and seamless return logistics displace conventional furniture store channels in urban Germany. |
Research Methodology
Direct dialogue with mattress manufacturer procurement directors, Portuguese latex processor operations managers, hospitality chain sustainability officers, and ECHA regulatory affairs specialists grounded qualitative findings, cross-referenced with EU customs trade data, Cradle to Cradle certification registry filings, national extended producer responsibility scheme reports, and hospitality RFP documentation. Secondary validation drew from SEC filings of listed bedding suppliers and EU Green Deal implementation guidance. Bottom-up segment sizing triangulated against top-down market value reconstruction.
Bottom-up volume modeling by material type, distribution channel, end-user segment, and price tier converged with top-down macroeconomic elasticity assumptions across the projection horizon. CAGRs derived from segment-level growth rate reconciliation with regulatory timeline impacts. Forecast inputs incorporated ECHA REACH flame retardant phase-out deadlines, EU AI Act supply chain disclosure implementation pacing, and hospitality refurbishment cycle clustering in German urban centers.
Inputs from certification body registries and national EPR scheme administrators were available through the study window; gaps in plantation-level Hevea sourcing disclosure rates introduce uncertainty bands around premium segment penetration assumptions. Forecasts reflect documented elasticity parameters and regulatory implementation assumptions. A model refresh is warranted upon material change in EU AI Act enforcement timing or German BfR migration standard revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Global Multifunctional Home Furniture Market
Furniture
Europe Sustainable Furniture Market
Furniture
Global Smart Furniture Market
Furniture
North America Home Furniture Market
Furniture
US Contract Furniture and Furnishing Market
Furniture
Pedicure Chair Market
Furniture
GCC Luxury Furniture Market
Furniture
China Furniture Market
Furniture
Indonesia Home Furniture Market
Furniture
Pool Tables Market
Furniture
Asia-Pacific Free Standing Electrical Height-Adjustable Tables Market
Furniture
North America Furniture Market
Furniture
Saudi Arabia Furniture Market
Furniture
Piano Stools Market
Furniture
Spain Furniture Market
Furniture
Europe Furniture Market