
 Global Film Thickness Measurement Market | 2026-2036
Global Film Thickness Measurement Market Size, Share, and Industry Trends Forecast 2026-2036
Global Film Thickness Measurement Market Analysis
Equipment leasing and pay-per-use metrology service contracts are rewriting competitive access rules for precision film measurement. Bruker Corporation leverages its installed base of X-ray fluorescence systems to sustain recurring revenue from semiconductor clients. KLA Corporation anchors its position through deep specialization in optical critical dimension tools for sub-7nm process nodes. Thermo Fisher Scientific competes by extending its analytical instrumentation portfolio into inline coating verification for automotive OEMs.
Film thickness measurement encompasses non-destructive techniques for quantifying deposited layer dimensions from nanometers to millimeters using optical interferometry, eddy current induction, or ultrasonic pulse-echo methods, serving quality assurance across vapor deposition, sputtering, and electrochemical coating processes. Optical technology dominates current revenue as wafer fabs demand sub-angstrom resolution for dielectric stack characterization, while ultrasonic systems gain ground in heavy industrial coating inspection where penetration depth exceeds optical limits. The semiconductor end user segment occupies the deepest value pools, though aerospace production monitoring applications are accelerating as thermal barrier coating specifications tighten for next-generation turbine blades.
EPA emission standards for volatile organic compounds in coating operations and China's GB standards for electronic product environmental protection are elevating measurement precision requirements across manufacturing jurisdictions. ISO 2808 and ASTM D7091 provide the metrological backbone for cross-border equipment qualification and laboratory accreditation. Stakeholders must calibrate portfolio investments against the shifting boundary between contact and non-contact technologies as substrate materials diversify beyond traditional silicon and metal alloys.
Market Dynamics
EUV lithography scaling below 3nm is compressing measurement tolerances across Taiwan and South Korean semiconductor fabs, forcing metrology suppliers to recalibrate resolution specifications against dielectric stack complexity rather than standalone thickness metrics.
Growth Catalysts
- EUV Node Compression:Sub-3nm lithography in Hsinchu and Pyeongtaek clusters demands sub-angstrom optical resolution for multi-layer dielectric characterization, pulling investment into interferometric systems.
- China's Dual Carbon Goals:Beijing's 2060 carbon neutrality mandate tightens coating thickness tolerances for photovoltaic and battery electrode manufacturing, elevating inline X-ray fluorescence deployment.
- F-Gas Regulation:The EU's phasedown of hydrofluorocarbon propellants in thermal spray operations forces aerospace OEMs to verify alternative barrier coating uniformity through ultrasonic pulse-echo methods.
Market Restraints
- Optical Limitation in Heavy Industry:Penetration depth constraints below 50 microns on steel substrates prevent optical interferometry from displacing eddy current methods in shipyard and pipeline inspection.
- Sensor Supply Concentration:German and Japanese photodetector manufacturers control 80% of high-sensitivity CCD supply for spectroscopic ellipsometry, exposing tool builders to single-source risk.
- Capital Intensity of Qualification:ISO 17025 laboratory accreditation for film thickness reference standards requires 18-24 month validation cycles, freezing smaller metrology service providers out of semiconductor supply chains.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for semiconductor and display manufacturing in Gujarat and Tamil Nadu create first-mover openings for portable stylus profilometer vendors serving contract assembly operations.
- Automotive Battery Coating:Solid-state electrolyte deposition for electric vehicle cells requires non-destructive verification of ceramic layer uniformity, opening ultrasonic resonance methods to gigafactory scale deployment.
- Convergence of AI and Spectroscopy:Machine learning pattern recognition applied to reflectance spectra is digitizing real-time thickness mapping, compressing measurement cycles from minutes to seconds in roll-to-roll manufacturing.
Industry Challenges
- Metrology Talent Scarcity:Semiconductor fabs in Daegu and Tainan compete for spectroscopic ellipsometry specialists capable of interpreting Mueller matrix data for anisotropic thin films.
- Legacy System Integration:Automotive paint shops in Stuttgart and Detroit face protocol mismatches when connecting new inline eddy current probes to 1990s-era SCADA architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Film Thickness Measurement Market |
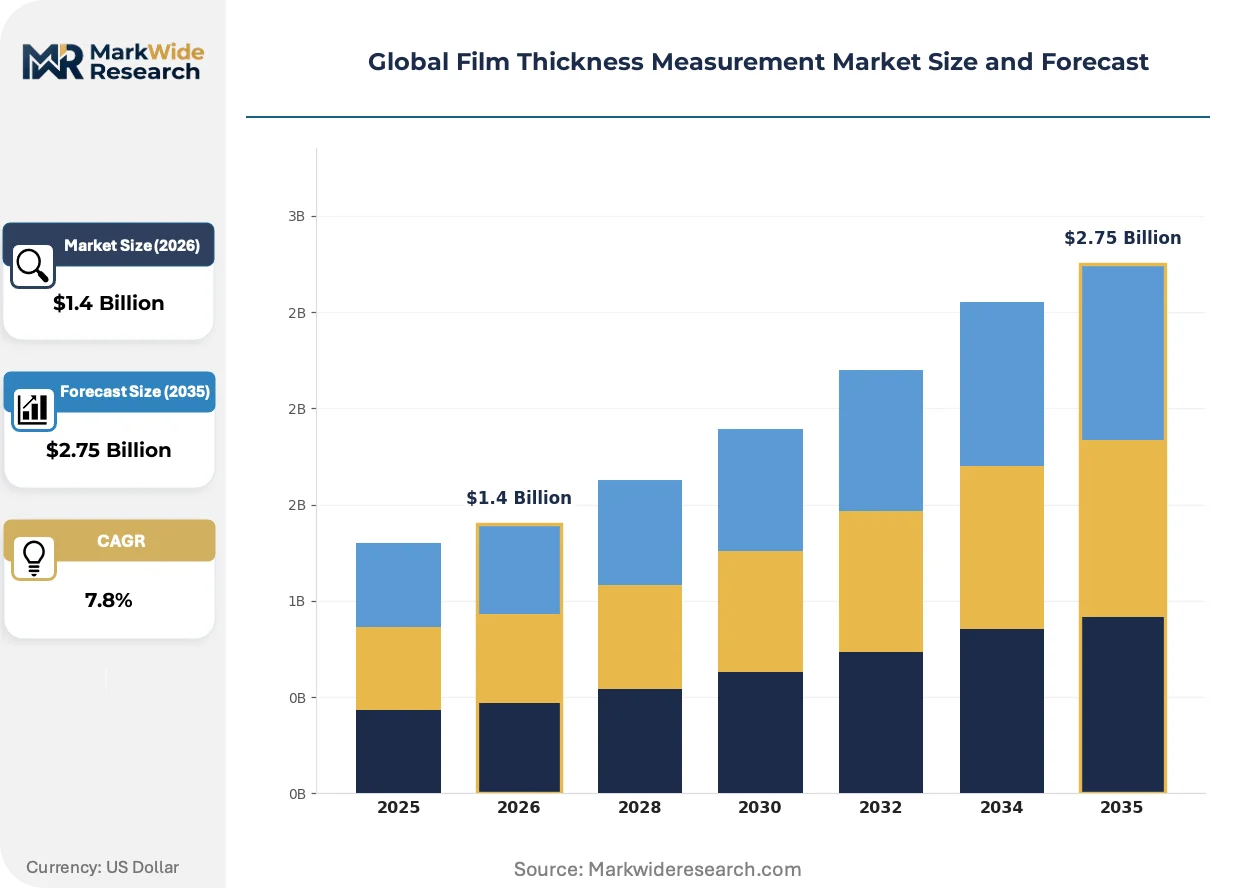
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.75 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical, X-Ray, Ultrasonic, Laser Technology: Non-Contact, Contact, Mechanical, Electromagnetic End User: Semiconductor, Automotive, Coating, Aerospace Application: Quality Control, Research & Development, Production Monitoring, Surface Analysis |
| Companies Covered | Elcometer Limited, Fischer Technology, ElektroPhysik, Paul N. Gardner, KERN & SOHN GmbH, Bruker Corporation, Spectris plc, KLA Corporation, Thermo Fisher Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Film Thickness Measurement Market Emerging Trajectories
Measurement modality boundaries are dissolving as semiconductor process control demands merge with industrial coating verification, compressing the historical separation between laboratory-grade optical systems and production-floor ultrasonic tools.
Terahertz time-domain spectroscopy is digitizing dielectric characterization for opaque polymer films and ceramic thermal barriers previously inaccessible to visible-light interferometry. Aerospace OEMs in Toulouse and Seattle are piloting terahertz gauges for turbine blade coating inspection, collapsing the gap between R&D metrology and inline quality gates. The technology is digitizing thickness mapping workflows that previously required destructive cross-sectioning, compressing feedback loops from hours to milliseconds.
China's GB/T standards for electronic product environmental protection are elevating measurement traceability requirements across contract manufacturers in Shenzhen and Suzhou. The regulations mandate documented calibration chains for all coating thickness data submitted with export documentation, forcing domestic metrology providers to pursue ISO 17025 accreditation previously held only by multinational laboratories. Display panel makers are responding by consolidating supplier qualification around accredited service contracts rather than capital equipment purchases.
Foundry customers in Taiwan are unbundling metrology service contracts from capital equipment sales, compressing vendor relationships toward pay-per-wafer pricing models. KLA Corporation and domestic competitors face margin pressure as TSMC and Samsung Foundry shift procurement toward outcome-based verification services with guaranteed measurement uncertainty specifications. This reconfiguration is most visible in Hsinchu Science Park, where equipment utilization clauses now dominate contract negotiations over upfront system pricing.
Global Film Thickness Measurement Market Segmentation
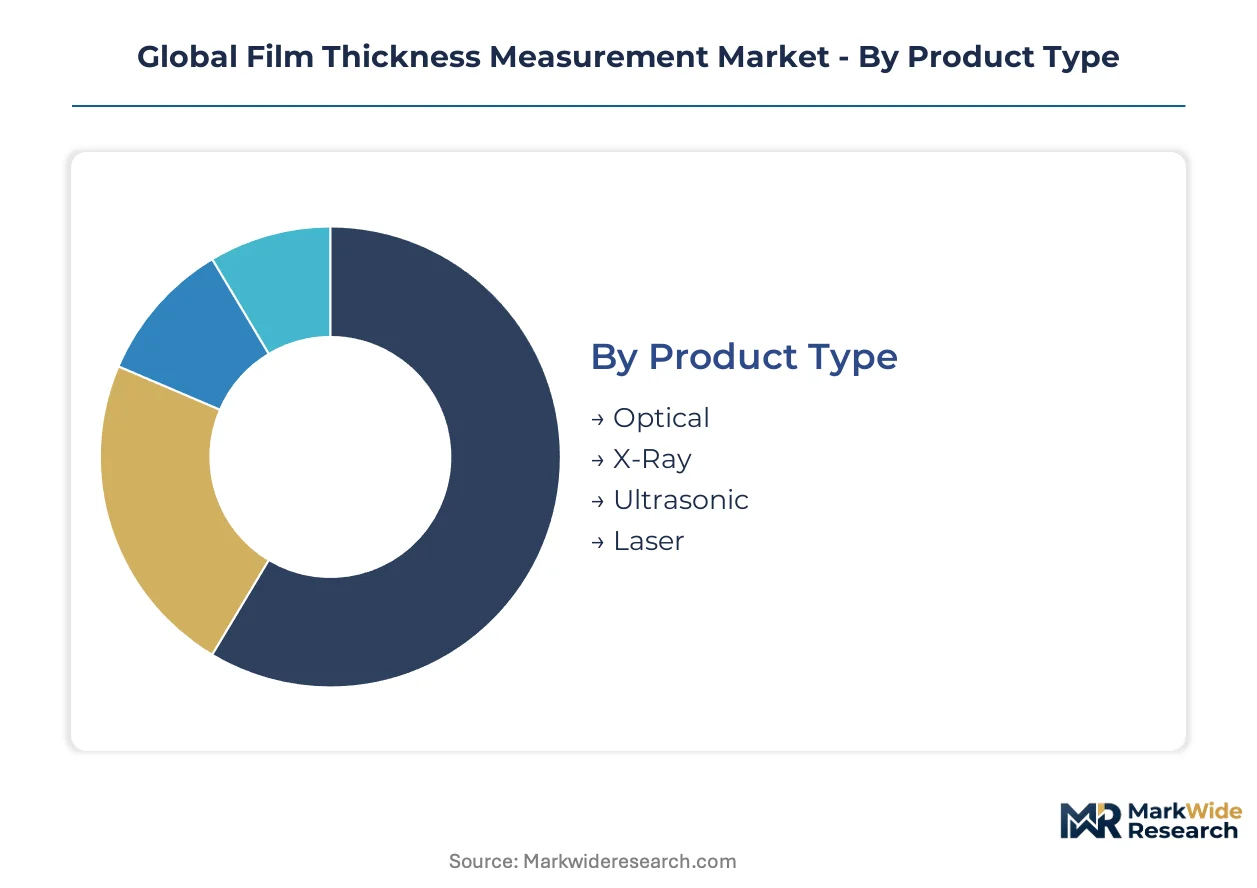
Film thickness measurement equipment fragments across measurement physics, automation interfaces, and end-use precision requirements. Each segmentation axis reveals distinct procurement patterns and technical qualification barriers that vendors must navigate.
Product Type:
Optical systems anchor wafer-level metrology while ultrasonic and X-ray modalities penetrate industrial coating verification where substrate opacity blocks visible wavelengths.
- Optical:Interferometric and spectroscopic ellipsometry systems achieve sub-angstrom resolution on dielectric stacks. Taiwan Semiconductor Manufacturing Company and Samsung Foundry in Pyeongtaek specify these for EUV node characterization below 3nm where layer complexity exceeds single-parameter measurement.
- X-Ray:X-ray fluorescence and reflectometry quantify elemental composition alongside thickness on photovoltaic electrodes and battery current collectors. China's dual carbon goals are elevating inline deployment across Suzhou and Hefei manufacturing parks for carbon-accountable coating verification.
- Ultrasonic:Pulse-echo gauges penetrate steel, concrete, and ceramic thermal barriers beyond optical limits. Aerospace OEMs in Seattle and Toulouse pilot these for turbine blade coating inspection where thickness exceeds 50 microns.
- Laser:Confocal and triangulation sensors map surface topography on roll-to-roll manufacturing lines. Display panel makers in Gumi and Tainan integrate laser profilometers for polarizer film alignment verification.
The dominant share belongs to Optical, while Ultrasonic is closing the gap fastest as heavy industrial specifications tighten.
Technology:
Automation architecture and substrate material constraints determine whether fabs deploy contact stylus profilometers or non-destructive optical gauges.
- Non-Contact:Interferometry, ellipsometry, and eddy current methods preserve delicate films on semiconductor wafers and display substrates. South Korean foundries mandate non-contact protocols for all production-critical measurements to eliminate particle generation.
- Contact:Stylus profilometers provide traceable reference measurements for ISO 17025 calibration chains. German automotive paint shops in Stuttgart retain contact methods for clearcoat verification where regulatory documentation requires destructive correlation.
- Mechanical:Magnetic and eddy current gauges dominate shipyard and pipeline inspection. Japanese shipbuilders in Nagasaki specify mechanical probes for marine coating surveys where electromagnetic interference from welding operations complicates electronic systems.
- Electromagnetic:Eddy current and magnetic induction sensors quantify non-conductive coatings on metal substrates. Indian steel mills under the PLI scheme deploy electromagnetic gauges for galvanized sheet verification at Gujarat and Tamil Nadu facilities.
Non-Contact commands the semiconductor value pool, though Mechanical retains pricing power in maritime and energy infrastructure.
End User:
Precision requirements and measurement throughput separate semiconductor fab procurement from automotive paint shop specifications.
- Semiconductor:Foundries in Hsinchu and Daegu demand sub-nanometer repeatability for gate stack and interconnect dielectric characterization. EUV lithography scaling below 3nm compresses tolerance bands, forcing metrology suppliers to recalibrate against anisotropic thin film models.
- Automotive:OEMs in Detroit and Stuttgart verify paint film build, battery electrode coating, and thermal barrier uniformity. Solid-state electrolyte deposition for electric vehicle cells is opening ultrasonic resonance methods to gigafactory-scale deployment.
- Coating:Industrial applicators serving construction and consumer goods monitor spray deposition and electroplating thickness. EPA emission standards for volatile organic compounds are elevating measurement precision requirements across US coating operations.
- Aerospace:Turbine blade manufacturers in Toulouse and Seattle tighten thermal barrier coating specifications for next-generation engines. F-Gas Regulation phasedown of hydrofluorocarbon propellants is forcing verification of alternative barrier chemistries.
Semiconductor absorbs the deepest R&D investment, yet Automotive is expanding most quickly as battery coating verification scales.
Application:
Measurement location—laboratory, production line, or quality gate—determines system mobility, cycle time, and data integration requirements.
- Quality Control:Incoming inspection and final audit stations require portable or benchtop systems with documented traceability. Chinese GB standards for electronic product environmental protection mandate calibration chains for all export documentation.
- Research & Development:Materials science laboratories in Cambridge and Tsukuba probe novel deposition chemistries and substrate combinations. Terahertz time-domain spectroscopy is digitizing dielectric characterization for opaque polymer films previously inaccessible to visible-light methods.
- Production Monitoring:Inline sensors feed real-time thickness data to SCADA and MES systems for closed-loop process control. Foundry customers in Taiwan are unbundling metrology service contracts from capital equipment sales, compressing vendor relationships toward pay-per-wafer pricing.
- Surface Analysis:Combined thickness and roughness mapping supports root-cause analysis of adhesion failures and optical defects. Machine learning pattern recognition applied to reflectance spectra is compressing measurement cycles from minutes to seconds in roll-to-roll manufacturing.
Production Monitoring captures the largest equipment volume, while Research & Development carries the highest per-system pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian semiconductor clusters generate sustained equipment demand while European aerospace and North American automotive sectors drive application diversification. Export flows concentrate through specialized metrology service contracts rather than standalone system shipments.
China
Beijing's dual carbon goals and GB standards for electronic product environmental protection tighten coating verification requirements across photovoltaic and battery electrode manufacturing. Suzhou and Hefei manufacturing parks deploy inline X-ray fluorescence systems for carbon-accountable production documentation. Display panel makers in Shenzhen consolidate supplier qualification around accredited service contracts rather than capital purchases.
South Korea
Samsung Foundry and SK Hynix in Pyeongtaek and Daegu compress measurement tolerances for sub-3nm EUV node characterization. The national semiconductor strategy under METI-equivalent programs elevates metrology infrastructure investment. Hsinchu-Tainan corridor competitors drive cross-strait procurement standardization for optical critical dimension tools.
United States
EPA emission standards for volatile organic compounds in coating operations elevate precision requirements across automotive paint shops and industrial applicators. Seattle and Detroit aerospace and automotive clusters pilot terahertz gauges for turbine blade and battery coating inspection. Solid-state electrolyte deposition for electric vehicle cells opens ultrasonic resonance methods to gigafactory-scale deployment.
Germany
Stuttgart automotive paint shops retain contact profilometer methods for clearcoat verification where regulatory documentation requires destructive correlation. The F-Gas Regulation phasedown forces verification of alternative thermal barrier chemistries through ultrasonic pulse-echo methods. Bavarian and North Rhine-Westphalian industrial clusters anchor European demand for eddy current coating inspection systems.
Japan
Tokyo Electron and Shin-Etsu supply chain requirements propagate sub-angstrom optical specifications through Nagoya and Kyushu materials clusters. JIS standards for electronic product environmental protection mandate documented calibration chains for export coating data. Tsukuba research laboratories pilot terahertz time-domain spectroscopy for opaque polymer film characterization previously inaccessible to visible-light methods.
Global Film Thickness Measurement Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying photodetectors, interferometric objectives, and precision motion stages. The vendor base separates into consolidated metrology conglomerates with multi-physics portfolios and specialized regional fabricators serving single-industry niches. Three archetypes dominate: semiconductor-dedicated optical specialists, diversified analytical instrumentation conglomerates, and industrial coating gauge manufacturers. Competitive moves center on outcome-based service contract unbundling and spectroscopic AI integration for real-time thickness mapping.
Among diversified analytical instrumentation conglomerates, Bruker Corporation and Thermo Fisher Scientific occupy positions spanning laboratory-grade systems to inline production verification. KLA Corporation exemplifies the semiconductor-dedicated archetype through deep specialization in sub-7nm process control. These three anchors represent distinct strategic postures: recurring revenue leverage from installed X-ray fluorescence bases, portfolio extension into automotive OEM coating verification, and pay-per-wafer pricing compression in foundry relationships.
| Leading Market Players |
|---|
| Elcometer Limited |
| Fischer Technology |
| ElektroPhysik |
| Paul N. Gardner |
| KERN & SOHN GmbH |
| Bruker Corporation |
| Spectris plc |
| KLA Corporation |
| Thermo Fisher Scientific Inc. |
| Others |
Supply Flow & Price Mechanics
Hsinchu Science Park's concentrated metrology infrastructure compresses equipment pricing power for optical critical dimension systems serving Taiwan Semiconductor Manufacturing Company and Samsung Foundry. Tool vendors face margin compression as foundry procurement shifts toward pay-per-wafer service contracts with guaranteed measurement uncertainty specifications rather than upfront capital sales.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing for ultrasonic and eddy current coating gauges. Price differentiation rests on ISO 17025 certification tier and volume scale, with accredited laboratory systems commanding premium positioning over unverified portable units. Cost compression in mid-tier optical systems is intensifying because Chinese domestic vendors are qualifying sub-angstrom interferometric platforms for photovoltaic electrode inspection. Automotive paint shops in Stuttgart and Detroit exhibit highest price sensitivity due to legacy SCADA integration costs, while semiconductor fabs in Pyeongtaek demonstrate lowest sensitivity given process control criticality.
Supply Chain Analysis
High-sensitivity CCD photodetectors feed from German and Japanese component specialists controlling spectroscopic ellipsometry sensor supply. Precision motion stages and interferometric objectives draw from Taiwan, Germany, and Japan manufacturing clusters. Single-source vulnerability concentrates in photodetector supply chains, exposing tool builders to disruption risk. Distribution runs through direct equipment sales for semiconductor fabs and accredited metrology service contracts for industrial coating verification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Film Thickness Measurement Market is recovering from capital expenditure cyclicality as EUV lithography node transitions below 3nm force foundry metrology refresh cycles. Equipment utilization clauses now dominate contract negotiations over upfront system pricing.
For Market Incumbents: Entrench through backward integration into photodetector supply chains and captive calibration laboratory networks in Hsinchu and Daegu. KLA Corporation and Bruker Corporation must defend against emerging Chinese optical specialists by accelerating ISO 17025 accreditation for domestic service contracts. Capacity addition in Tamil Nadu and Gujarat under India's PLI scheme offers geographic diversification against Taiwan Strait concentration risk.
For New Entrants and Emerging Players: India's contract assembly operations in semiconductor and display manufacturing present the most penetrable white-space for portable stylus profilometer vendors. Solid-state electrolyte deposition verification for automotive battery gigafactories offers second-mover openings for ultrasonic resonance specialists. A service-first go-to-market angle—pay-per-measurement contracts rather than capital equipment sales—aligns with foundry procurement shifts in East Asia.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors diversified analytical instrumentation conglomerates with recurring revenue streams from installed X-ray fluorescence bases. Long-term viability hinges on spectroscopic AI integration capabilities for real-time thickness mapping. The signal to watch is terahertz time-domain spectroscopy adoption rates in Toulouse and Seattle aerospace clusters as inflection indicator for next-generation modality displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photodetector Supply | Reduces single-source exposure from German and Japanese CCD manufacturers for tool builders. |
| ISO 17025 Accreditation Expansion | Unlocks semiconductor supply chain access previously frozen to unqualified metrology service providers. |
| Pay-per-Wafer Service Contract Unbundling | Aligns vendor relationships with TSMC and Samsung Foundry procurement shifts toward outcome-based verification. |
| Terahertz Gauge Pilot Deployment | Collapses feedback loops from hours to milliseconds for turbine blade coating inspection in Toulouse and Seattle. |
| AI-Pattern Recognition Integration | Compresses measurement cycles from minutes to seconds in roll-to-roll manufacturing lines. |
Methodological Framework
Operator-level perspectives from fab metrology engineers, coating quality managers, and analytical instrumentation procurement leads anchored the qualitative base. The research combined primary interviews with secondary validation through SEC 10-K filings, customs and trade data for photodetector component flows, and ISO 17025 accreditation registries. Bottom-up equipment shipment tallies and top-down semiconductor capital expenditure forecasts were triangulated against foundry utilization rates.
Scenario-bracketing framed analytical sensitivity across the projection horizon. Segmentation dimensions modeled include measurement physics, automation interface, end-use precision requirement, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle analysis and process node transition timelines. Forecast inputs incorporated EUV lithography scaling roadmaps and China's dual carbon policy implementation trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese domestic optical specialists or accelerated terahertz commercialization would shift outcomes. Material shifts in F-Gas Regulation enforcement or Taiwan Strait logistics disruption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
US Eddy-Current Testing Market
Testing Equipment
Chromatography Market
Testing Equipment
Chromatography Data Systems Market
Testing Equipment
Global Residue Testing Market
Testing Equipment
Flammability Tester Market
Testing Equipment
Glass Testing Equipment Market
Testing Equipment
Water Penetration Tester Market
Testing Equipment
Next-Generation Titrators Market
Testing Equipment
Liquid Chromatography Mass Spectrometry (LCMS) Market
Testing Equipment
Solar Testing Equipment Market
Testing Equipment
High-Temperature Corrosion and Creep Testing Equipment for Process Industries Market
Testing Equipment
Gold Purity Tester Market
Testing Equipment
Material Tester Market
Testing Equipment
Chemical Detection Equipment Market
Testing Equipment
Global Circular Dichroism (CD) Spectrometers Market
Testing Equipment
Microplastics Particle Size and Shape Characterization Systems Market