
 Stock Media Software Market | 2026-2036
Stock Media Software Market Size, Share, and Industry Trends Forecast 2026-2036
Stock Media Software Market Analytics
North American cloud infrastructure expansion is reshaping how stock media platforms distribute high-resolution assets to enterprise clients. Adobe leverages extensive plugin ecosystems across creative workflows to sustain platform stickiness among marketing agencies and production companies. Blackmagic Design anchors hardware-software integration for DaVinci Resolve users, while Unity Software competes through real-time 3D asset pipelines serving gaming and virtual production studios.
Stock media software comprises digital asset libraries and management tools that store, index, and license pre-produced video, image, audio, and 3D content through metadata-driven search and rights-clearance engines, typically delivering files via CDN with codec optimization for broadcast, web, and mobile formats. Video stock and image stock categories dominate current revenue pools as enterprise marketing teams scale content velocity across channels. Subscription-based licensing now outpaces rights-managed models among freelancers and mid-sized agencies seeking predictable cost structures, while API access integration grows fastest as DAM platforms and video editors embed stock search directly into production pipelines.
FCC content guidelines in the United States, EU copyright directives under the Digital Services Act, and Japan's METI standards for digital content distribution each shape permissible use cases and platform liability frameworks for stock media operators. ISO 27001 and SOC 2 compliance increasingly gate enterprise procurement decisions as buyers scrutinize asset provenance and creator payment transparency. Stakeholders must weigh platform consolidation against niche specialization as generative AI tools begin displacing conventional stock workflows in high-volume creative segments.
Market Dynamics
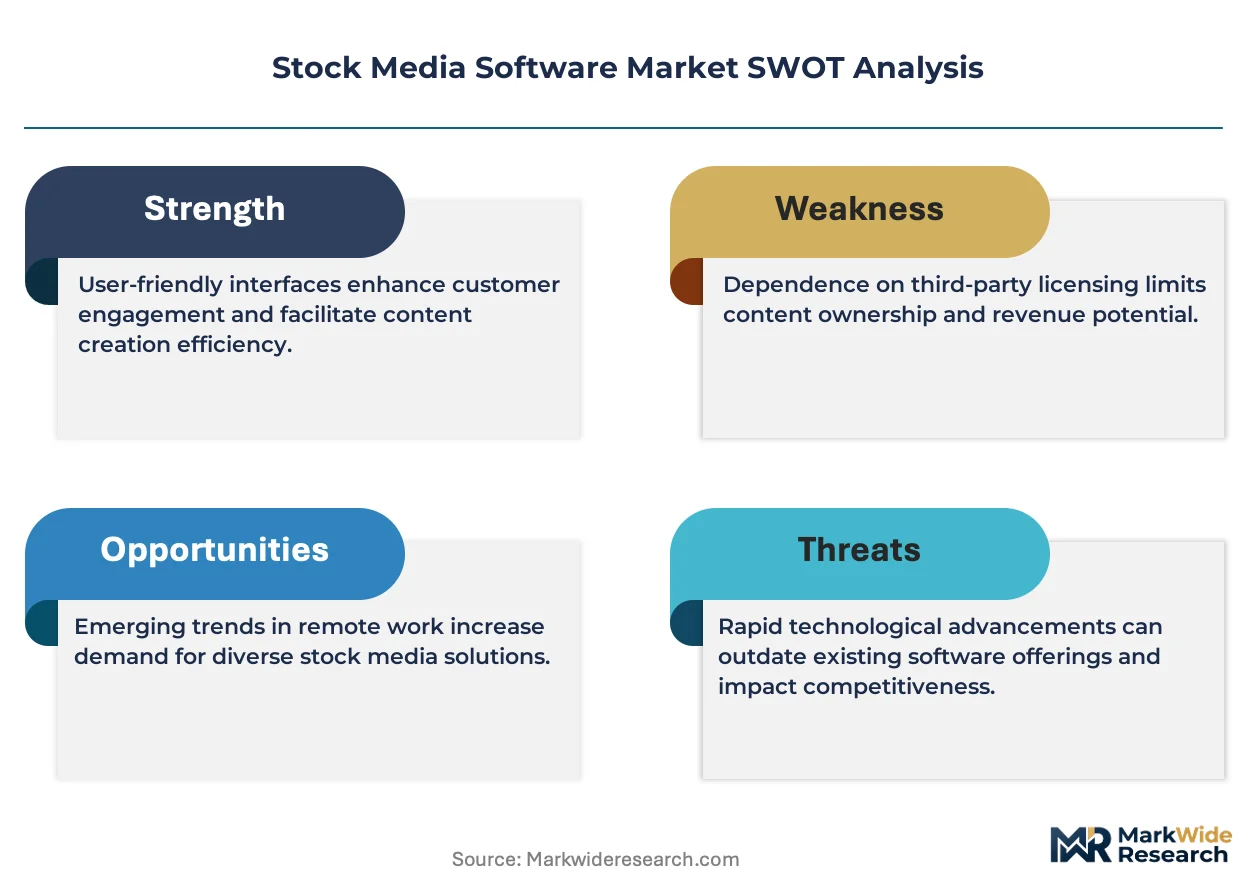
Generative AI tools are compressing demand for conventional stock media workflows as marketing agencies automate image and video generation, forcing platforms to reposition around curation, rights management, and premium authentic content.
Growth Catalysts
- API-first integration standards:Video editors and DAM platforms now embed stock search directly into production pipelines, accelerating adoption among mid-sized agencies seeking workflow efficiency.
- FCC content guidelines:United States broadcast compliance requirements drive enterprise procurement of rights-cleared assets with verified provenance chains and creator payment transparency.
- Cloud-native delivery architectures:CDN-optimized codec distribution enables real-time access to high-resolution assets across distributed creative teams in Germany, Japan, and the United States.
Market Restraints
- Creator supply concentration:Top-contributor economies cluster in North American and Western European urban centers, creating bottleneck risks for diverse content verticals.
- EU copyright directive friction:Digital Services Act liability frameworks impose content verification burdens that increase operational overhead for platforms serving European enterprise clients.
- Generative substitution threat:Text-to-image and text-to-video models from OpenAI and Midjourney displace volume-based stock licensing in high-frequency creative segments.
Strategic Opportunities
- Virtual production convergence:Real-time 3D asset pipelines merging game engines with LED volume stages create demand for spatially indexed, motion-capture-ready stock libraries.
- India content localization:Underpenetrated regional language markets offer white space for platforms building creator networks in Hindi, Tamil, and Telugu verticals.
- ISO 27001 compliance differentiation:Enterprise procurement gates increasingly favor platforms with certified data governance, creating margin expansion for compliant operators.
Industry Challenges
- Metadata taxonomy standardization:Inconsistent keyword hierarchies across platforms force buyers to execute redundant searches, degrading user experience and conversion rates.
- Legacy DAM integration complexity:Enterprise clients require custom API development to connect cloud stock libraries with on-premise asset management systems, extending sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stock Media Software Market |
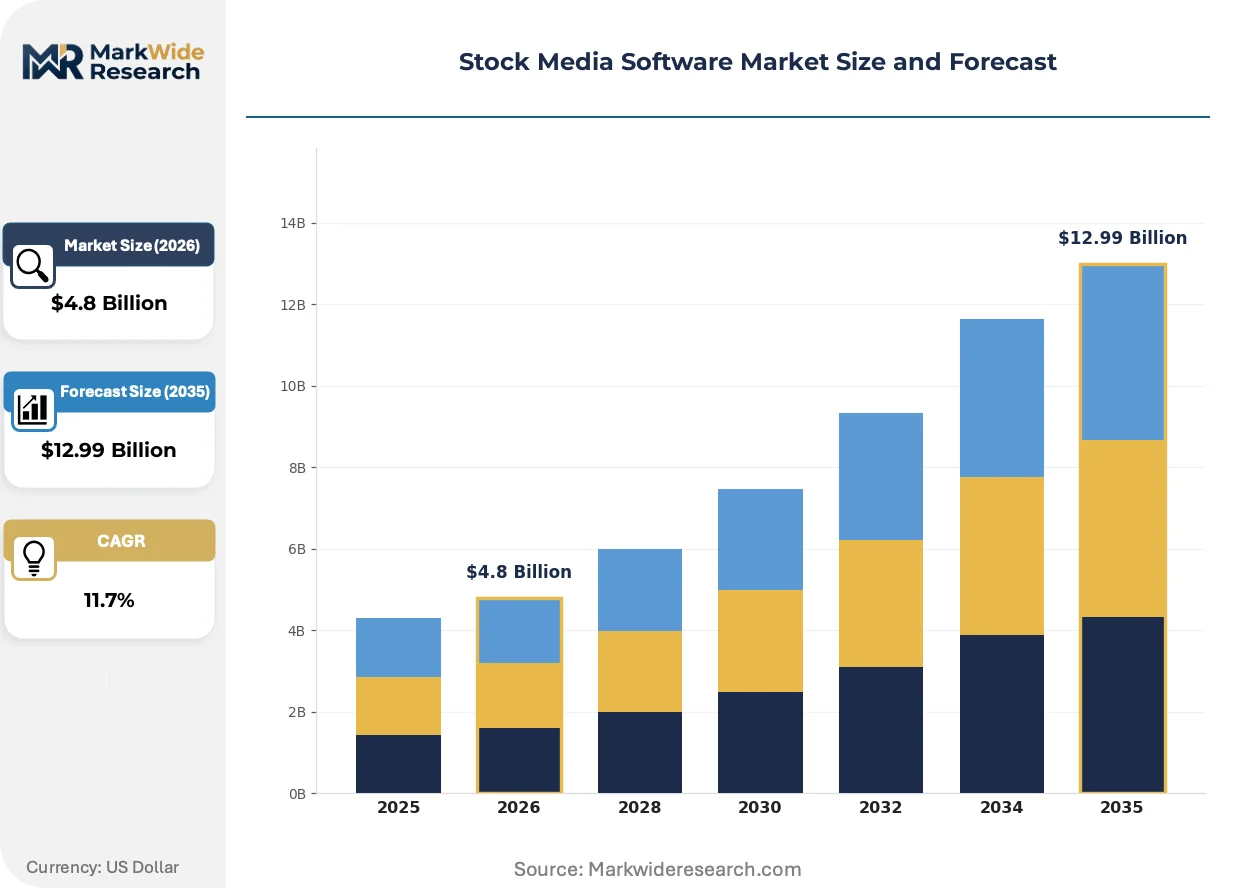
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Video Stock, Image Stock, Audio Stock, 3D Models End User: Marketing Agencies, Production Companies, Freelancers, Educational Institutions Licensing Model: Royalty-Free, Rights-Managed, Editorial Use, Subscription-Based Integration: API Access, Plugin Support, Standalone Software, Cloud Integration |
| Companies Covered | Avid Technology, Grass Valley, Adobe, Magix, DaVinci Resolve, Autodesk, Blackmagic Design, VEGAS Creative Software, Unity Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stock Media Software Market Evolving Landscape
Codec optimization and edge delivery infrastructure are redefining how high-resolution assets reach production pipelines. Three developments are restructuring competitive positioning across the value chain.
AV1 codec adoption is migrating from experimental deployment to default delivery standard for web-optimized video assets. Streaming platforms and social media marketing teams now mandate AV1-compatible source files to reduce bandwidth costs. This compression technology is migrating from niche sustainability-focused buyers to mainstream enterprise procurement specifications, compressing storage and transmission economics for 4K and 8K workflows.
Japan's METI standards for digital content distribution now require granular creator attribution and resale royalty tracking across secondary licensing markets. These transparency mandates increase platform development costs while creating competitive moats for operators with robust provenance infrastructure. Production companies in Tokyo and Osaka are prioritizing vendors with METI-compliant audit trails, shifting procurement criteria from price-per-asset to governance certification.
Subscription fatigue among freelance creators is driving unbundling of stock access from all-you-can-download models toward credit-based micro-purchases. Individual designers and solo videographers now favor à-la-carte licensing for project-specific needs rather than recurring commitments. This behavioral pivot is most visible in United States and German freelancer communities, where platform churn rates have intensified competitive investment in retention tooling and flexible pricing architectures.
Stock Media Software Market Segmentation
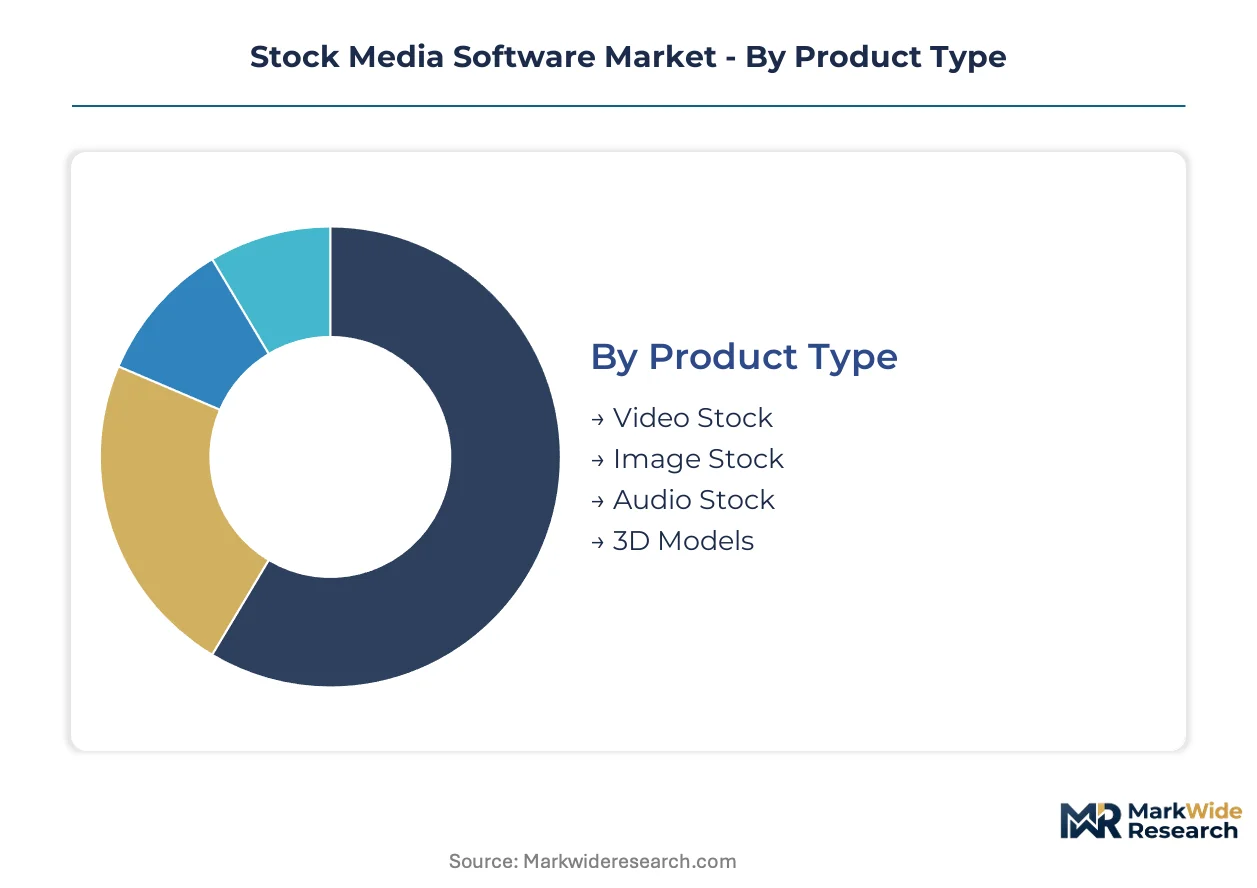
Segmentation in stock media software reveals how procurement patterns diverge between high-volume enterprise workflows and specialized creator needs. Understanding these divides exposes where platform investments in codec optimization, API infrastructure, and compliance tooling generate differential returns.
Product Type:
Mature formats dominate current revenue pools while emerging asset categories reshape competitive positioning.
- Video Stock:Time-based media assets delivered through CDN-optimized pipelines with codec variants for broadcast, social, and mobile endpoints. Marketing agencies in the United States now specify AV1-compatible source files to compress bandwidth costs across distributed production teams. Video stock retains volume leadership; 3D models hold the steepest expansion curve.
- Image Stock:Raster and vector graphics indexed through metadata-driven search engines with rights-clearance automation. German production companies prioritize ISO 27001-certified platforms when sourcing campaign imagery, shifting procurement criteria from price-per-asset to data governance credentials.
- Audio Stock:Music beds, sound effects, and voice-over libraries with stem separation and tempo-matching algorithms.
- 3D Models:Spatially indexed assets optimized for game engines and virtual production LED volumes.
Video stock commands the largest procurement budgets; 3D models are climbing the fastest as real-time pipelines converge with broadcast workflows.
End User:
Customer archetypes span predictable enterprise commitments to volatile project-based purchasing.
- Marketing Agencies:Multi-seat subscription clients requiring API-embedded search within DAM platforms and creative suites. These buyers in Japan now demand METI-compliant creator attribution trails, extending vendor evaluation cycles but reducing compliance risk.
- Production Companies:High-asset-volume users with custom integration requirements for on-premise infrastructure and cloud-hybrid pipelines. FCC content guidelines in the United States drive procurement of rights-cleared assets with verified provenance chains.
- Freelancers:Solo creators exhibiting subscription fatigue and migrating toward credit-based micro-purchase models.
- Educational Institutions:Campus-wide licensing clients with volume-discounted access for curriculum integration and student training.
Marketing agencies anchor platform revenue stability; freelancers are gaining share fastest as unbundled pricing architectures proliferate.
Licensing Model:
Cost structures range from predictable subscriptions to transaction-heavy rights negotiations.
- Royalty-Free:Perpetual usage rights with standardized pricing tiers based on resolution and distribution scope. Mid-sized agencies favor this model for campaign work requiring rapid asset deployment without usage tracking overhead.
- Rights-Managed:Context-specific licensing with geographic, temporal, and medium restrictions enforced through contractual terms. High-value broadcast placements in Germany and Japan still require this granular control for talent and location releases.
- Editorial Use:News and documentary licensing with restricted commercial application boundaries.
- Subscription-Based:Recurring access fees with download quotas or unlimited tiers replacing per-asset transactions.
Subscription-based licensing captures the broadest user base; rights-managed contracts sustain the highest per-asset margins.
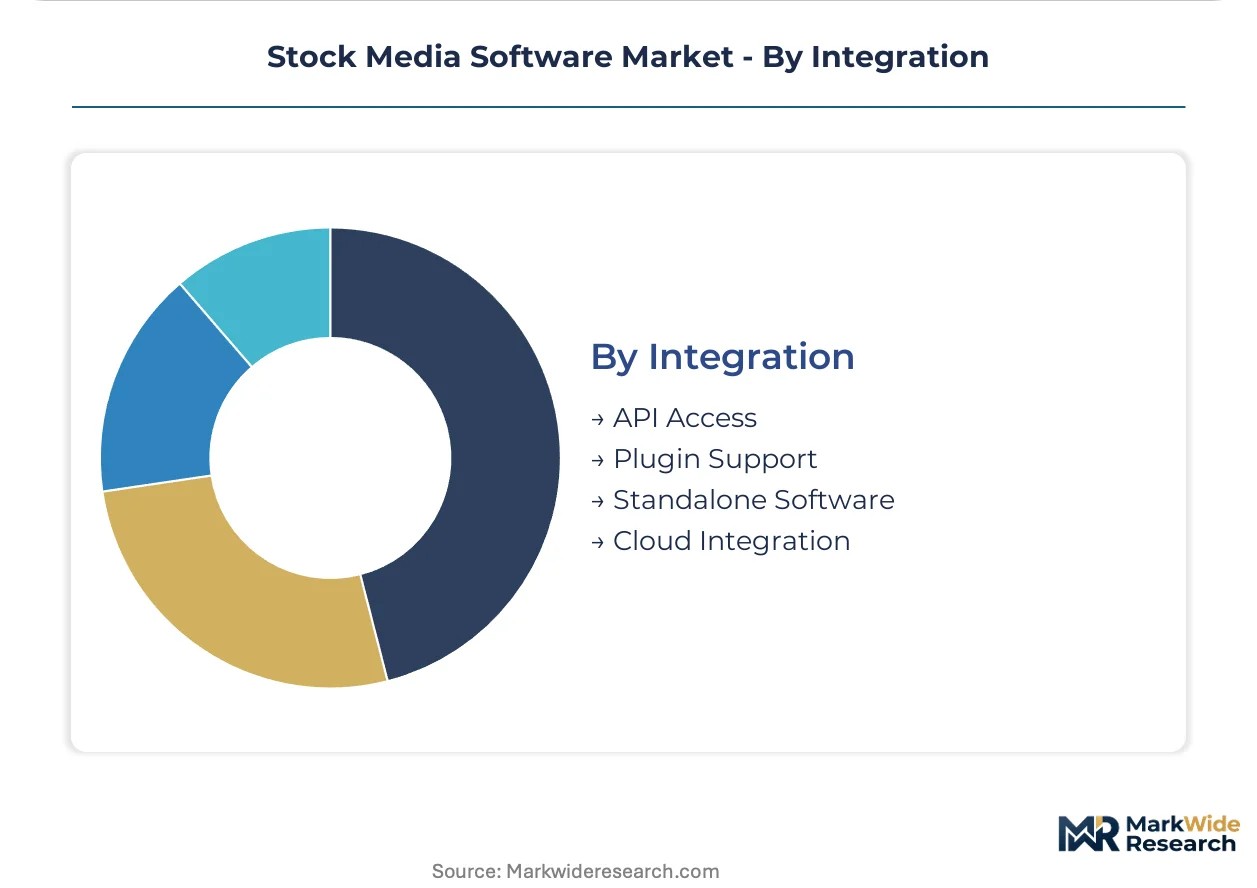
Integration:
Technical connection methods determine workflow friction and platform switching costs.
- API Access:Programmatic search and retrieval endpoints enabling embedded stock functionality within third-party production tools. Adobe's plugin ecosystem demonstrates how API-first integration sustains platform stickiness among agency creative teams.
- Plugin Support:Native extensions for video editors, design applications, and DAM platforms with single-sign-on authentication.
- Standalone Software:Dedicated client applications with offline asset management and local rendering capabilities.
- Cloud Integration:Browser-based interfaces with real-time collaboration features and distributed team access controls.
API access drives enterprise procurement decisions; cloud integration is expanding most quickly as remote production teams proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Creator supply concentrates in North American and Western European metropolitan clusters, while procurement demand clusters in jurisdictions with broadcast infrastructure and marketing agency density. This geographic split shapes platform investment priorities across compliance, codec delivery, and creator network expansion.
United States
Marketing agencies in New York and Los Angeles drive enterprise subscription volumes for video and image stock. FCC content guidelines mandate rights-cleared assets with verified provenance chains, extending vendor evaluation cycles for broadcast-facing production companies. Cloud infrastructure expansion across Northern Virginia and Oregon data centers enables real-time CDN delivery of 4K and 8K assets to distributed creative teams.
Germany
Production companies in Berlin and Munich prioritize ISO 27001-certified platforms when sourcing campaign imagery, shifting procurement criteria toward data governance credentials. EU copyright directives under the Digital Services Act impose content verification burdens that increase operational overhead for platforms serving enterprise clients. The Cologne-Bonn corridor hosts concentrated post-production facilities integrating API-first stock search into hybrid cloud-on-premise pipelines.
Japan
METI standards for digital content distribution require granular creator attribution and resale royalty tracking across secondary licensing markets. Production companies in Tokyo and Osaka prioritize vendors with compliant audit trails, extending procurement evaluation timelines. The Osaka-Kyoto-Kobe zone anchors broadcast technology infrastructure driving demand for motion-capture-ready 3D asset libraries.
India
Underpenetrated regional language markets offer expansion white space for platforms building creator networks in Hindi, Tamil, and Telugu verticals. The country's national digital content regulator imposes evolving compliance frameworks for foreign-operated stock platforms. Mumbai and Bengaluru clusters concentrate post-production talent pools seeking credit-based micro-purchase alternatives to subscription fatigue.
United Kingdom
London-based marketing agencies anchor European demand for API-embedded stock search within DAM platforms and creative suites. GDPR compliance requirements shape platform data governance investments for enterprise procurement. The Manchester-Leeds corridor expands as a secondary hub for production companies requiring rights-managed assets with geographic and temporal licensing restrictions.
Stock Media Software Market Competitive Landscape
Creative-suite incumbents and specialized production-tool vendors split the market along workflow-integration depth. Adobe leverages extensive plugin ecosystems across creative workflows to sustain platform stickiness among marketing agencies. Blackmagic Design anchors hardware-software integration for DaVinci Resolve users. Unity Software competes through real-time 3D asset pipelines serving gaming and virtual production studios. Dominant competitive moves include API-first partnership architectures and vertical integration into creator payment infrastructure.
Within the creative-suite tier, Adobe exemplifies platform stickiness through embedded workflow integration. Among specialized production-tool vendors, Blackmagic Design and Unity Software occupy positions defined by hardware-software convergence and real-time pipeline architecture respectively. These three anchors represent divergent strategic bets on where stock media value accrues—curation and rights management versus generative displacement resilience versus spatially indexed 3D asset libraries.
| Leading Market Players |
|---|
| Avid Technology |
| Grass Valley |
| Adobe |
| Magix |
| DaVinci Resolve |
| Autodesk |
| Blackmagic Design |
| VEGAS Creative Software |
| Unity Software |
| Others |
Value Network & Pricing Analysis
Overcapacity in North American cloud infrastructure is compressing storage delivery costs while simultaneously intensifying price competition among stock media platforms competing for enterprise marketing agency contracts.
Pricing Analysis
FCC content guidelines dictate the pricing tier structure for broadcast-compliant assets in the United States, separating premium rights-cleared tiers from standard web-optimized offerings. Pricing stratifies across enterprise subscription, mid-market seat-based, and freelancer credit-purchase tiers. Cost compression in the freelancer segment is intensifying because generative AI tools displace volume-based licensing. Marketing agencies exhibit the lowest price sensitivity due to bundled procurement through creative suites, while solo videographers demonstrate acute sensitivity to recurring commitments.
Supply Chain Analysis
Raw content feeds from creator networks in the United States, Germany, and Japan anchor upstream supply for premium authentic assets. Codec licensing fees, cloud storage provisioning, and CDN edge node deployment constitute primary cost inputs. Single-source vulnerability concentrates in creator supply clusters across North American and Western European metropolitan centers. Distribution runs through API-embedded pipelines into DAM platforms and video editing suites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stock media software functions as a service-attach business where API integration layers and compliance certification services expand faster than per-asset licensing, creating durable recurring revenue streams.
For Market Incumbents: Pre-empt generative AI displacement by deepening curation infrastructure and creator payment transparency systems. Build ISO 27001 and METI-compliant audit trails to gate enterprise procurement decisions. Acquire niche 3D asset libraries serving virtual production LED volume workflows before specialized competitors consolidate spatial indexing capabilities.
For New Entrants and Emerging Players: Establish a beachhead in India's underpenetrated regional language markets by building creator networks in Hindi, Tamil, and Telugu verticals. Target credit-based micro-purchase models for freelancer communities exhibiting subscription fatigue in the United States and Germany. Lead with codec-optimized delivery infrastructure to differentiate from legacy platform incumbents.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among API-first platforms embedding stock search directly into creative workflows and DAM systems. Long-term viability hinges on provenance infrastructure resilience against generative substitution and regulatory transparency mandates. Monitor AV1 codec adoption velocity as an inflection indicator for infrastructure-dependent platform economics.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Adobe's plugin ecosystem demonstrates how embedded workflow access sustains platform stickiness among marketing agencies. |
| Compliance Certification Investment | ISO 27001 and METI-compliant audit trails increasingly gate enterprise procurement decisions in Germany and Japan. |
| Virtual Production Asset Pipeline | Real-time 3D libraries for LED volume stages capture demand from Unity Software and Blackmagic Design user bases. |
| Regional Creator Network Expansion | Hindi, Tamil, and Telugu verticals in India offer white space for platforms building localized content supply. |
| Flexible Pricing Architecture | Credit-based micro-purchases address subscription fatigue among United States and German freelancer communities. |
Research Methodology
Initial hypotheses were tested against primary input from platform product managers, creative technology procurement officers, post-production facility directors, and stock media contributor network leads and refined through secondary validation against SEC filings, hyperscaler capex disclosures, CDN infrastructure deployment data, and creative software partnership announcements. Bottom-up estimates of seat-based subscriptions and API call volumes were triangulated against top-down assessments of marketing agency technology spend.
Demand-supply balance modeling across the projection horizon incorporated deployment model, organization size, vertical application, integration complexity, and regional adoption pattern as segmentation dimensions. CAGRs were derived from trend extrapolation of subscription conversion rates and API embedding velocity. Forecast inputs included AV1 codec adoption curves and METI compliance implementation timelines.
Stress conditions across generative AI substitution rates, creator network churn, and regulatory enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about enterprise procurement gate evolution and cloud infrastructure cost trajectories. Cross-checking against hyperscaler media services revenue disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Recruiting Software Market
Software & Services
Social Collaboration Software Market
Software & Services
Video Server Software Market
Software & Services
Nonconformance Management Software Market
Software & Services
Global Embedded Hypervisor Software Market
Software & Services
Stone Analysis Software Market
Software & Services
Email Checker Tools Market
Software & Services
Enterprise Mobility Software Market
Software & Services
Coaching Management Software Market
Software & Services
Train Reservation Software Market
Software & Services
UI Design Software Market
Software & Services
Global Survey Software Market
Software & Services
HVAC Solution Software Market
Software & Services
Global Animation Software Market
Software & Services
Europe Database Management Software Market
Software & Services
North America IT Services Market