
 Global Online Assessment Software Market | 2026-2036
Global Online Assessment Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Online Assessment Software Market Foresight
Direct enterprise sales channels for assessment platforms is fragmenting as self-service SaaS onboarding and marketplace distribution gain share. Mercer LLC leverages its consulting heritage to anchor premium workforce analytics bundles. Pearson VUE sustains dominance in high-stakes certification infrastructure through controlled test-center networks. McGraw-Hill Education Holdings LLC competes in K-12 and higher-ed institutional procurement cycles with integrated content-assessment packages.
Online assessment software comprises digital platforms that administer, proctor, score, and analyze examinations across remote or supervised environments, typically incorporating browser lockdown protocols, biometric identity verification, and machine-learning anomaly detection to preserve test integrity. These systems serve commercial and educational buyers by replacing paper-based evaluation with scalable, auditable, and geographically unrestricted testing infrastructure. Cloud-Based deployment leads volume adoption among mid-market enterprises seeking zero-maintenance infrastructure, while Remote Proctoring commands disproportionate R&D investment as AI-enabled surveillance and browser forensics redefine credentialing trust models. Candidate Management solutions occupy mature margin pools in enterprise HR tech stacks, whereas Result Analytics represents the fastest-growing attach as predictive workforce intelligence gains procurement priority.
The EU AI Act, GDPR, and ISO 27001 collectively shape product architecture by mandating algorithmic explainability for automated scoring, restricting cross-border data flows, and requiring certified information security management systems for government contracts. The US Department of Education and state-level accreditation boards influence demand through accessibility standards and federal student aid eligibility tied to validated assessment outcomes. Stakeholders must monitor evolving AI governance timelines and procurement certification requirements to align platform roadmaps with buyer compliance thresholds.
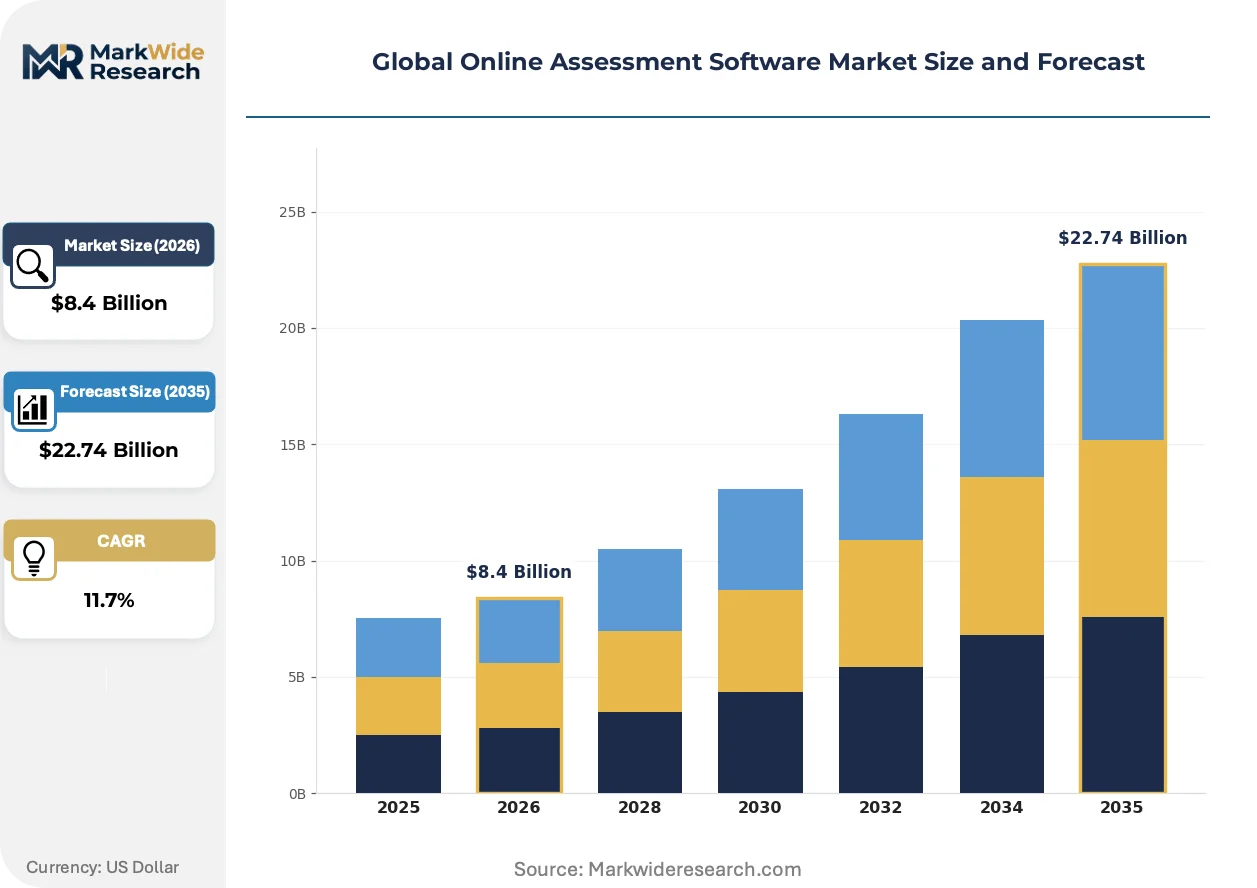
Market Dynamics
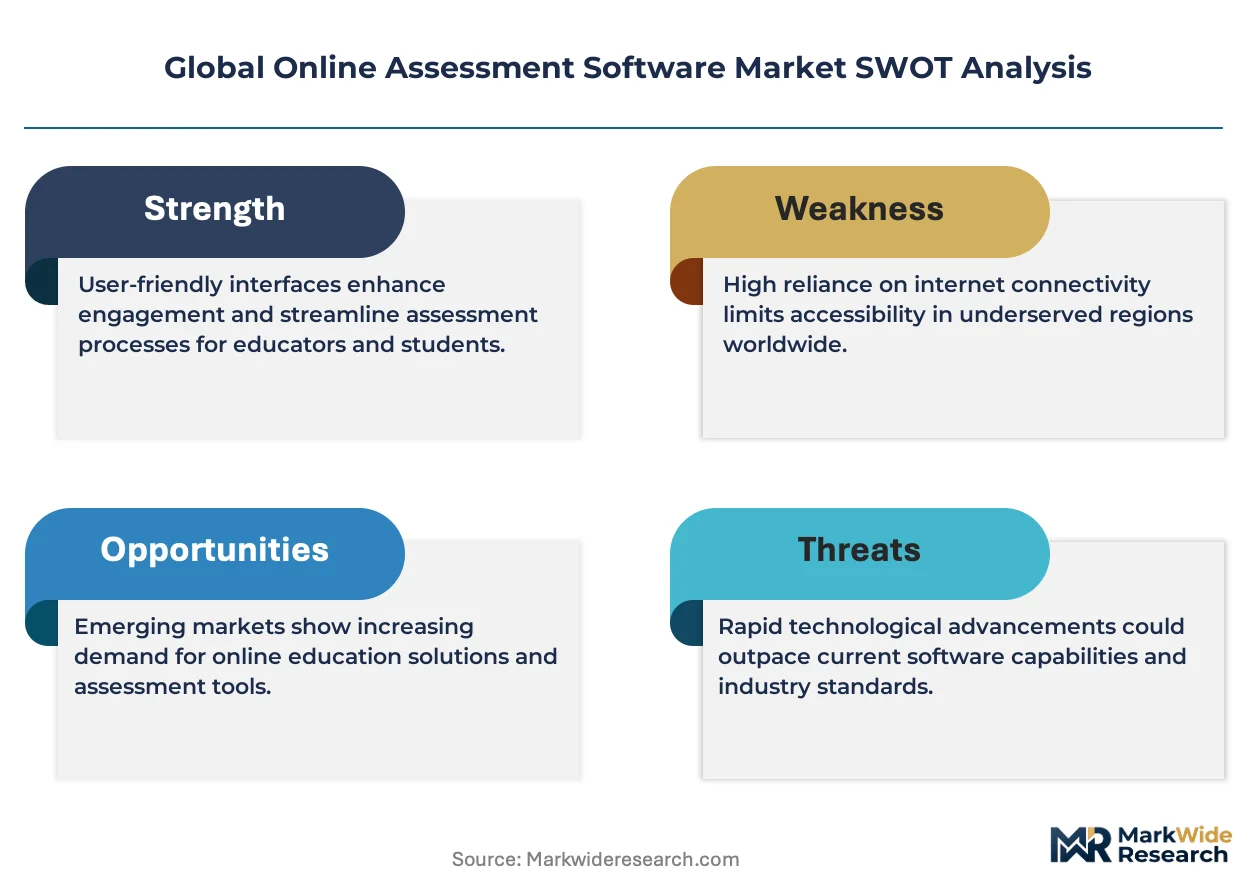
The EU AI Act's algorithmic explainability mandates are compressing vendor R&D cycles as automated scoring systems face mandatory transparency audits across European deployments.
Growth Catalysts
- Remote Proctoring Infrastructure:Federal contracting certification bodies in the United States are mandating biometric identity verification and browser forensics for security-cleared workforce credentialing.
- GDPR Compliance Frameworks:Cross-border data flow restrictions are creating procurement preference for EU-hosted assessment clouds among German automotive and French pharmaceutical training departments.
- Machine-Learning Anomaly Detection:Pattern-recognition algorithms are reducing manual proctor review hours by flagging suspicious behavior sequences in real-time examination sessions.
Market Restraints
- ISO 27001 Certification Costs:Government contract eligibility requires certified information security management systems that mid-tier SaaS vendors struggle to fund.
- Biometric Data Storage Liability:Facial recognition and keystroke dynamics create permanent breach exposure under GDPR's right-to-erasure conflicts with audit trail retention.
- Browser Lockdown Evasion:Virtual machine masking and secondary device coordination undermine integrity claims, forcing continuous countermeasure investment.
Strategic Opportunities
- India's Skilling Ecosystem:The country's PLI scheme-linked workforce development programs are digitizing vocational certification at scale for manufacturing and IT services sectors.
- Predictive Workforce Intelligence:Result analytics modules are attaching to enterprise HR tech stacks as performance forecasting gains procurement priority over standalone testing.
- API-First Distribution:Marketplace embedding through learning management system connectors is displacing direct enterprise sales cycles for mid-market penetration.
Industry Challenges
- Algorithmic Bias Auditing Talent:Scarce data scientists capable of validating fairness metrics across demographic subgroups are bottlenecking product releases.
- Accessibility Standard Harmonization:WCAG 2.1, Section 508, and EN 301 549 create conflicting technical requirements for screen-reader compatibility and keyboard navigation.
- Legacy Assessment Migration:Paper-based credentialing bodies face multi-year content digitization and psychometric validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Online Assessment Software Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $22.74 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS, Virtual Private Cloud Solution Type: Test Creator, Candidate Management, Result Analytics, Remote Proctoring, Reporting Dashboard Use Case: Corporate Recruitment, Employee Training, Academic Testing, Certification Exams, Skill Assessment End User: Educational Institutions, Enterprises, Government Agencies, Training Providers, Certification Bodies |
| Companies Covered | Mercer LLC, McGraw-Hill Education Holdings LLC, Blackboard Inc, Pearson VUE, PSI Services LLC, Mettl, Canvas by Instructure Inc, Moodle Pty Ltd, Questionmark Computing Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Online Assessment Software Market Shifts & Advancements
Artificial intelligence surveillance capabilities are merging with zero-trust security architectures to redefine credentialing trust models across both commercial and educational deployments.
AI-proctored evaluation platforms are hybridizing rule-based anomaly detection with generative adversarial network simulations to anticipate cheating methodologies before they surface in live examinations. Large state university systems in the United States are piloting these systems for high-stakes admissions testing. This convergence is compressing the competitive window for standalone browser-lockdown vendors.
The EU AI Act's risk-classification framework is forcing algorithmic scoring transparency through mandatory technical documentation and human oversight protocols for high-stakes decisions. Vendors must now maintain explainability logs that trace automated judgments to specific feature weights. European higher-education procurement committees are prioritizing compliant platforms for Erasmus+ mobility credential recognition.
Self-service SaaS onboarding is displacing six-month enterprise sales cycles as HR technology buyers demand immediate sandbox access and usage-based pricing without professional services dependencies. This pattern is most visible among mid-market enterprises in the United Kingdom and Netherlands seeking zero-maintenance infrastructure for seasonal hiring spikes.
Global Online Assessment Software Market Segmentation
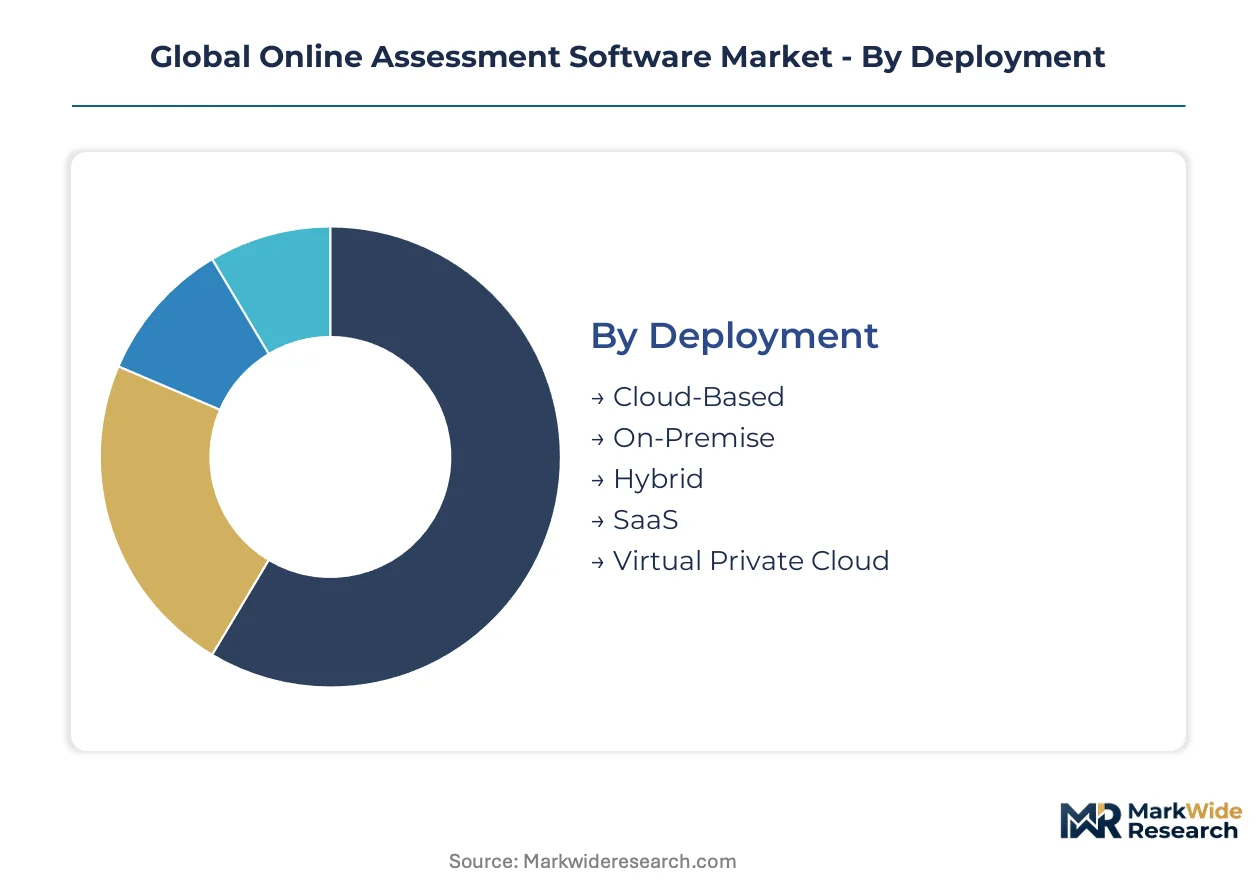
Deployment architecture determines infrastructure ownership costs and compliance posture for assessment buyers across regulated industries. Solution functionality shapes procurement priorities as HR technology stacks consolidate around integrated talent intelligence platforms.
Deployment:
Cloud-Based deployments turn over fastest among mid-market buyers seeking immediate sandbox access, while On-Premise contracts renew on multi-year cycles with heavy professional services dependencies.
- Cloud-Based:Zero-maintenance infrastructure delivered through multi-tenant architectures eliminates server provisioning overhead. German automotive and French pharmaceutical training departments favor EU-hosted instances to satisfy GDPR cross-border data flow restrictions.
- On-Premise:Dedicated hardware installations within buyer data centers preserve complete data sovereignty. Federal contracting certification bodies in the United States mandate this architecture for security-cleared workforce credentialing where classified content cannot transit external networks.
- Hybrid:Split configurations keep sensitive biometric data on-premises while pushing analytics workloads to scalable cloud compute.
- SaaS:Self-service onboarding with usage-based pricing displaces six-month enterprise sales cycles for seasonal hiring spikes.
- Virtual Private Cloud:Isolated cloud environments blend operational flexibility with single-tenant security isolation for healthcare and financial services compliance.
Cloud-Based anchors the volume base while SaaS gains share at the steepest rate.
Solution Type:
Functional modules stratify by margin profile, with established categories commanding mature pricing and emerging capabilities capturing premium attach rates.
- Remote Proctoring:AI-enabled surveillance combining browser forensics with biometric identity verification redefines credentialing trust models. Large state university systems in the United States pilot these systems for high-stakes admissions testing.
- Result Analytics:Predictive workforce intelligence modules attach to enterprise HR technology stacks as performance forecasting gains procurement priority over standalone testing functionality.
- Test Creator:Item banking and psychometric validation tools support legacy assessment migration from paper-based credentialing bodies.
- Candidate Management:Applicant tracking integration occupies mature margin pools within established HR information system ecosystems.
- Reporting Dashboard:Visualization layers aggregate examination outcomes for accreditation board compliance documentation.
Candidate Management anchors the volume base while Result Analytics climbs the fastest.
Use Case:
Application intensity varies by buyer sophistication, with transactional testing giving way to continuous competency validation in advanced implementations.
- Corporate Recruitment:High-volume screening of applicant pipelines demands scalable automation with minimal false-positive rates.
- Academic Testing:Semester-cycle examination windows create concentrated infrastructure load requiring elastic capacity provisioning.
- Certification Exams:High-stakes professional credentialing requires ISO 27001 certified information security management systems for government contract eligibility.
- Employee Training:Competency gap analysis drives recurring assessment touchpoints integrated with learning management system workflows.
- Skill Assessment:India's PLI scheme-linked workforce development programs digitize vocational certification at scale for manufacturing and IT services sectors.
Academic Testing anchors the volume base while Skill Assessment expands most quickly.
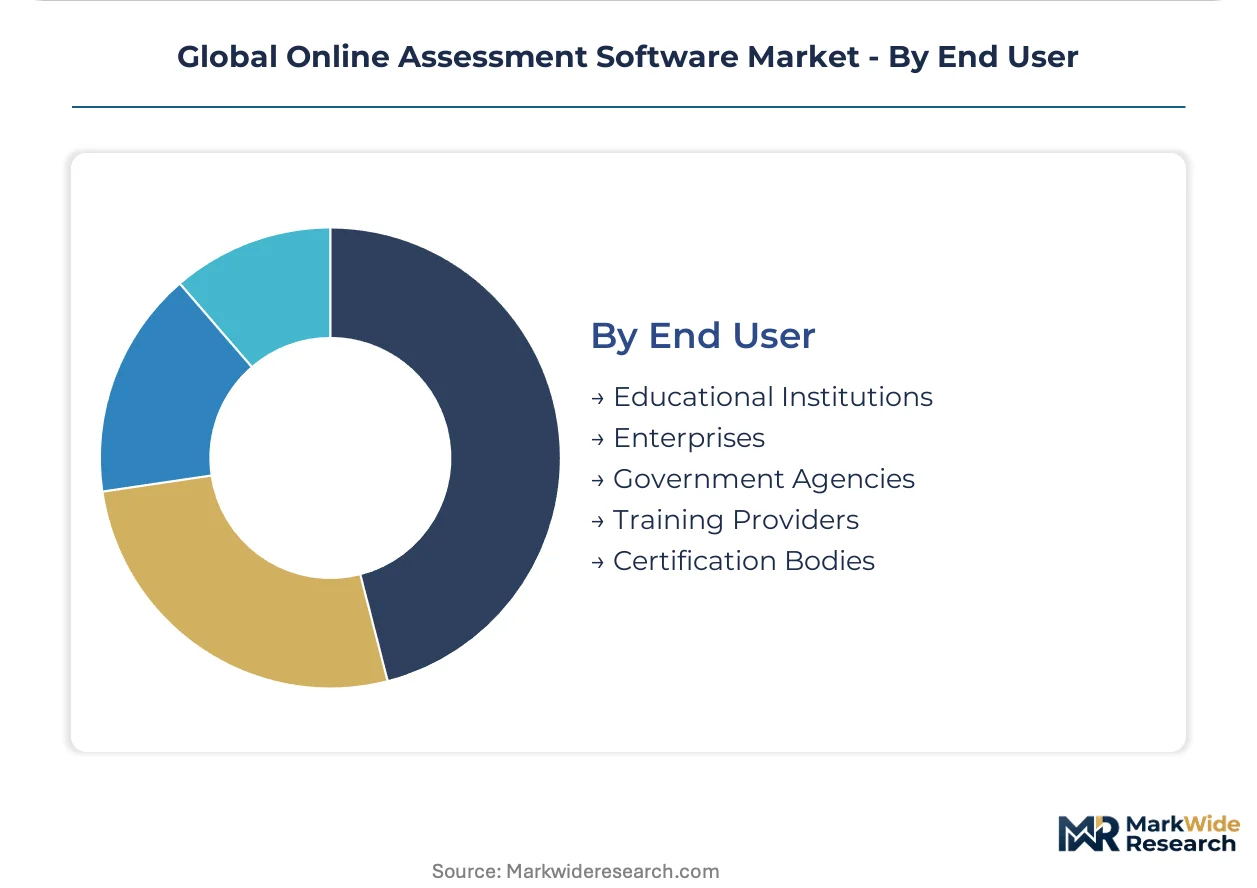
End User:
Procurement authority concentrates differently across buyer types, with centralized IT governance in enterprises contrasting against decentralized department-level purchasing in higher education.
- Educational Institutions:State university systems and K-12 districts navigate accessibility standard harmonization across WCAG 2.1, Section 508, and EN 301 549 requirements.
- Enterprises:Multinational corporations consolidate assessment spending through HR technology platform renewals with integrated analytics bundles.
- Government Agencies:Federal and state-level procurement mandates biometric verification and browser lockdown protocols for security-cleared positions.
- Training Providers:Commercial skills academies prioritize API-first distribution through learning management system marketplace embedding.
- Certification Bodies:Professional associations face multi-year content digitization and psychometric validation timelines migrating from legacy paper-based delivery.
Educational Institutions anchor the volume base while Enterprises show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The transatlantic fiber optic cable networks and EU-US Data Privacy Framework infrastructure position the United States and European Union as the dominant data corridors for assessment platform hosting. Cloud region density in Northern Virginia, Frankfurt, and Amsterdam underwrites latency-sensitive remote proctoring deployments.
United States
Federal contracting certification bodies mandate biometric identity verification for security-cleared workforce credentialing. The Department of Education influences procurement through accessibility standards tied to federal student aid eligibility. Large state university systems in California and Texas pilot AI-proctored admissions testing at scale.
Germany
Automotive training departments at Volkswagen and BMW digitize vocational certification for manufacturing workforce development. GDPR cross-border data flow restrictions create preference for EU-hosted assessment clouds. Frankfurt's financial services cluster demands ISO 27001 certified platforms for compliance documentation.
India
PLI scheme-linked workforce development programs digitize vocational certification for manufacturing and IT services sectors. The country's central bank and skill development ministry coordinate on standardized assessment frameworks. Bengaluru and Hyderabad's technology corridors host assessment platform R&D centers serving domestic and export markets.
United Kingdom
Mid-market enterprises in London and Manchester seek zero-maintenance SaaS infrastructure for seasonal hiring spikes. The Information Commissioner's Office enforces GDPR-aligned data protection standards for assessment data processing. Oxford and Cambridge university presses drive demand for high-stakes academic testing platforms.
France
Pharmaceutical training departments at Sanofi and L'Oréal mandate EU-hosted assessment clouds for regulatory compliance. The CNIL enforces algorithmic transparency requirements under the EU AI Act for automated scoring systems. Paris-Saclay research cluster experiments with predictive workforce intelligence modules.
Global Online Assessment Software Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct competitive tiers. Established consulting conglomerates anchor premium workforce analytics bundles through professional services integration. Specialized proctoring technology vendors compete on AI surveillance capabilities and browser forensics innovation. Open-source learning management platforms capture institutional volume through API-first distribution and zero licensing costs. Dominant competitive moves include strategic partnerships with HR technology stacks and portfolio diversification into predictive analytics modules.
Within the consulting-anchored tier, Mercer LLC exemplifies professional services heritage applied to workforce intelligence bundling. Pearson VUE occupies a position representing controlled test-center network dominance for high-stakes certification infrastructure. Among education-technology specialists, McGraw-Hill Education Holdings LLC sits within the integrated content-assessment package archetype serving K-12 and higher-ed procurement cycles.
| Leading Market Players |
|---|
| Mercer LLC |
| McGraw-Hill Education Holdings LLC |
| Blackboard Inc |
| Pearson VUE |
| PSI Services LLC |
| Mettl |
| Canvas by Instructure Inc |
| Moodle Pty Ltd |
| Questionmark Computing Limited |
| Others |
Supply & Pricing Matrix
Transatlantic fiber optic cable networks between Northern Virginia and Frankfurt impose latency-sensitive bandwidth costs that concentrate AI-proctored platform hosting in these corridors, compressing margins for vendors serving EU buyers while enabling premium pricing for sub-100ms proctoring guarantees to federal contracting bodies in the United States.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with ISO 27001 certification and EU AI Act compliance separating premium tiers from standard offerings. Price differentiation hinges on biometric data retention policies and algorithmic explainability documentation depth. Cost compression in the mid-market SaaS tier is intensifying because self-service onboarding displaces professional services revenue. Federal certification bodies show least price sensitivity, while Indian vocational training programs under PLI schemes exhibit highest elasticity.
Supply Chain Analysis
Export-control regimes limiting AI surveillance technology flows to certain jurisdictions fragment cloud infrastructure deployment options for vendors seeking unified global platforms. Supply concentrates in the United States, Germany, and India for core platform development, with biometric hardware components sourced from Taiwan and South Korea. The supply chain rests on GPU compute availability and specialized camera sensor manufacturing. Single-source vulnerability in EU-hosted cloud regions creates procurement preference for multi-region redundancy. Distribution runs through HR technology marketplace connectors and direct enterprise sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as multinational enterprises consolidate assessment spending through integrated HR technology platform renewals, compressing vendor margins and favoring bundled analytics providers over standalone testing specialists.
For Market Incumbents: Pre-empt API-first distribution displacement by embedding remote proctoring modules directly into learning management system workflows before marketplace connectors commoditize standalone access. Acquire specialist result analytics firms to anchor predictive workforce intelligence bundles. Defend against open-source Moodle deployments by tightening integration with Canvas and Blackboard institutional footprints. For New Entrants and Emerging Players: Build out zero-trust security architecture credentials targeting federal contracting certification bodies in the United States, where incumbent complacency around on-premise deployment creates white-space opportunity. India's PLI-linked vocational certification programs represent the most penetrable geography. Pursue channel partnerships with German automotive training departments seeking GDPR-compliant EU-hosted alternatives. For Investors and Strategic Acquirers: Carve-out targets emerge from education-technology conglomerates divesting non-core assessment assets amid platform consolidation. Long-term viability favors vendors with algorithmic bias auditing capabilities and explainability documentation infrastructure. Monitor EU AI Act enforcement timelines as inflection indicator for compliance-premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding proctoring APIs into Canvas and Blackboard workflows captures institutional procurement cycles. |
| Acquisition of Specialist Firm | Purchasing result analytics vendors anchors predictive workforce intelligence bundles for Mercer-style positioning. |
| Strategic Partnership | Alliances with German automotive training departments unlock GDPR-compliant EU-hosted deployment demand. |
| Geographic Expansion | Establishing Bengaluru R&D centers serves India's PLI-linked vocational certification digitization programs. |
| Product Launch | Releasing algorithmic explainability dashboards satisfies EU AI Act mandates for European higher-ed procurement. |
Research Methodology
Cross-validation between primary interviews with CTOs, HR technology procurement officers, and university IT directors and secondary validation through SEC filings, hyperscaler capex disclosures, and EU regulatory filings anchors the qualitative findings. Bottom-up triangulation against top-down market sizing ensures segmentation coherence across deployment models, organization size tiers, vertical applications, integration complexity levels, and regional adoption patterns.
Calibration against historical platform adoption curves and biometric technology diffusion rates shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include cloud deployment architecture, solution functionality modules, use case intensity, and end-user procurement authority. CAGRs derive from elasticity-adjusted replacement cycle analysis and attach-rate progression for analytics modules. Forecast inputs incorporate EU AI Act implementation timelines and federal certification mandate expansion trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by open-source learning management platforms or hyperscaler cloud entrants would shift outcomes. Material shifts in GDPR enforcement stringency or US federal accessibility standard harmonization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
G Suite Technology Services Market
Software & Services
Test Management Software Market
Software & Services
Global Corporate Wellness Software Market
Software & Services
Online Recruitment Software Market
Software & Services
Compositing Software Market
Software & Services
Performing Arts Software Market
Software & Services
Middle East HR Payroll Software Market
Software & Services
Global Construction Management Software Market
Software & Services
PAC Programming Software Market
Software & Services
Construction Enterprise Resource Planning (ERP) Software Market
Software & Services
Electronic Data Interchange (EDI) Software Market
Software & Services
Software Market
Software & Services
Exploration and Production (E&P) Software Market
Software & Services
Collaborative Office Software Market
Software & Services
Global Microscopy Software Market
Software & Services
Supplier Quality Management Applications Market