
 Convertible Shipper Display Market | 2026-2036
Convertible Shipper Display Market Size, Share, and Industry Trends Forecast 2026-2036
Convertible Shipper Display Market Outlook
Subscription-based design refresh services for seasonal campaign artwork is hardening as a recurring revenue layer atop physical display procurement. Smurfit Kappa Group leverages its European mill network to sustain captive supply of corrugated fiberboard grades optimized for retail-ready conversion. WestRock Company anchors its position through in-house structural design studios that compete on speed-to-shelf for CPG brands. DS Smith differentiates via circular material certification programs that control premium positioning in beauty and personal care channels.
A convertible shipper display is a dual-function packaging unit engineered from corrugated fiberboard or hybrid substrates, typically rated for 20–50 pounds stacked compression, that ships as a protective transit container and converts via tear-strip or fold-out mechanisms into a point-of-sale presentation fixture without repacking. Its primary purpose is eliminating the labor cost and damage risk of secondary handling between distribution center and retail floor. Cardboard displays lead volume due to established recycling infrastructure and lower per-unit material cost, while hybrid displays represent the fastest-expanding margin pool as brands seek metal-reinforced corners combined with printable paper surfaces. Point of Sale applications dominate current deployment, though Retail Promotions use cases are widening fastest as grocers adopt modular planogram systems.
FDA food-contact substance notifications govern recycled paper barriers in displays serving the Food & Beverage vertical, while EPA recycled content guidelines shape supplier qualification for corrugated inputs. The EU Green Deal packaging rules are forcing substrate substitutions that increase testing burden but open certified sustainable material premiums. Stakeholders must monitor how state-level extended producer responsibility laws in California and New York alter cost allocation between display manufacturers and brand owners.
Market Dynamics
Labor cost compression at retail distribution centers is accelerating shipper display adoption as grocers eliminate secondary handling between backroom and shelf. The EU Packaging and Packaging Waste Regulation tightens material traceability requirements that favor certified corrugated solutions over conventional alternatives.
Growth Catalysts
- EU Green Deal packaging rules:Mandates for recyclable retail-ready formats drive substrate substitution toward certified fiberboard grades in Germany and France.
- Modular planogram systems:Grocery chains in the United States deploy standardized shelf dimensions that reward displays with precise dimensional tolerances.
- Beauty and personal care channels:Premium brands demand circular material certification programs that validate supply chain sustainability claims.
Market Restraints
- OCC price volatility:Old corrugated containerboard input costs fluctuate with Chinese import policies, compressing converter margins unpredictably.
- Mill concentration in Scandinavia:Kraftliner supply tightens when Nordic producers curtail output, straining captive supply arrangements.
- Recycled fiber technical limits:FDA food-contact substance notifications restrict barrier coatings in displays serving fresh produce categories.
Strategic Opportunities
- Subscription design services:Seasonal artwork refresh contracts create recurring revenue atop physical display procurement for CPG brands.
- Hybrid substrate convergence:Metal-reinforced corners combined with printable paper surfaces capture premium positioning in electronics unboxing experiences.
- California EPR legislation:Extended producer responsibility laws shift cost allocation toward display manufacturers, favoring vertically integrated suppliers.
Industry Challenges
- Structural engineering talent scarcity:Fold-out mechanism design requires specialized CAD skills that outpace vocational training pipeline output.
- Multi-jurisdiction certification timelines:Parallel FDA and EU EFSA approvals for food-contact barriers delay product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Convertible Shipper Display Market |
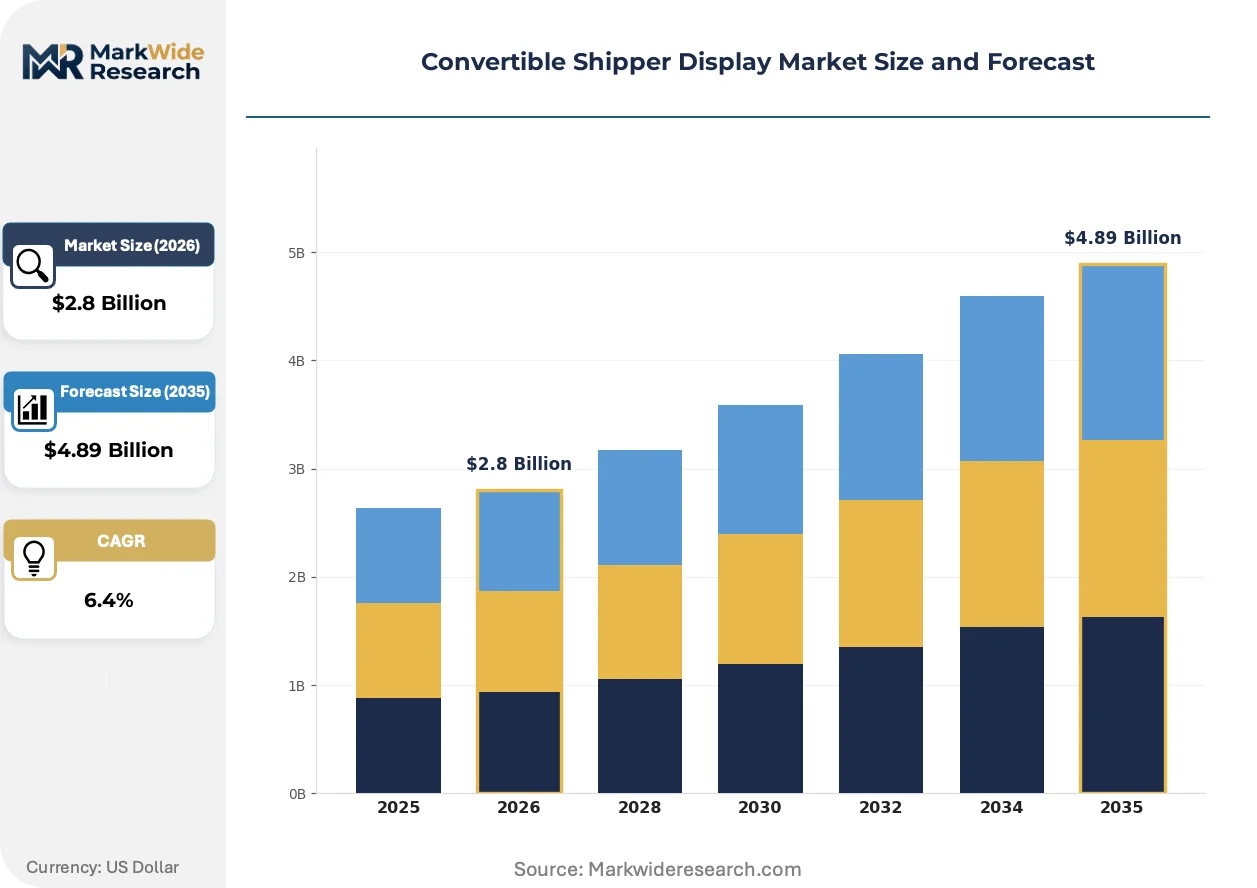
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardboard Displays, Plastic Displays, Metal Displays, Hybrid Displays Use Case: Retail Promotions, Trade Shows, Seasonal Campaigns, Point of Sale Material: Recycled Paper, Corrugated Fiberboard, Wood, Acrylic Industry Vertical: Food & Beverage, Beauty & Personal Care, Consumer Electronics, Apparel |
| Companies Covered | Smurfit Kappa Group, WestRock Company, International Paper Company, DS Smith, Sonoco Products Company, Menasha Packaging Company, Packaging Corporation of America, Georgia-Pacific LLC, Delkor Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Convertible Shipper Display Market Strategic Shifts
Digital print integration and automated conversion equipment are compressing design-to-shelf timelines from weeks to days. Three developments dominate current investment patterns.
High-speed inkjet printheads are automating variable data artwork generation for regional campaign customization. Beverage brands deploy this capability for city-specific promotional runs with 48-hour turnaround requirements. The technology is automating batch-size economics that previously favored generic national designs.
REACH substance restrictions on per- and polyfluoroalkyl substances force grease-resistant barrier reformulation across EU-serving production lines. Corrugated converters invest in mineral-oil-free coatings to maintain food-contact compliance. Fresh produce shippers face the steepest reformulation burden given moisture exposure during cold chain transit.
CPG procurement teams consolidate vendor relationships around end-to-end structural design and manufacturing partners. Single-source accountability replaces fragmented bidding between separate design studios and converters. This concentration is most pronounced among North American mass-market retailers with centralized category management functions.
Convertible Shipper Display Market Segmentation
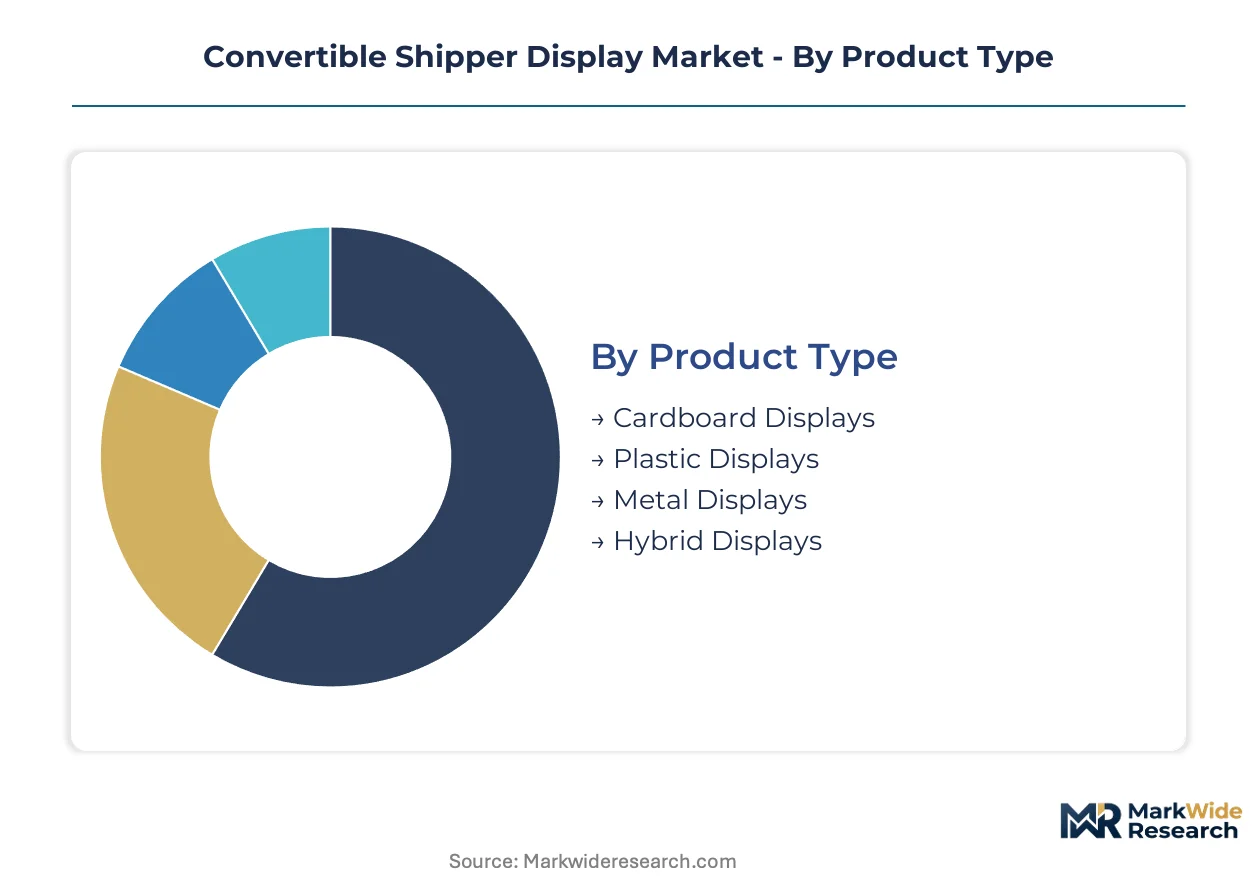
Convertible shipper displays serve divergent supply chain requirements across substrate technologies, activation contexts, material specifications, and channel verticals. Each segmentation axis reveals distinct margin structures and compliance burdens that shape supplier positioning strategies.
Product Type:
Structural engineering and substrate composition define performance thresholds for transit-to-display conversion.
- Cardboard Displays:Engineered from corrugated fiberboard grades rated for 20–50 pounds stacked compression, these units leverage established recycling infrastructure and lower per-unit material cost. Demand concentrates in grocery retail across Germany and France, where EU Green Deal packaging rules mandate recyclable retail-ready formats.
- Hybrid Displays:Metal-reinforced corners combined with printable paper surfaces capture premium positioning. Electronics unboxing experiences and beauty brand activations drive adoption fastest as companies seek structural durability with premium surface aesthetics.
- Plastic Displays:Thermoformed PET or PP substrates suit moisture-exposed cold chain applications where fiberboard barriers face technical limits.
- Metal Displays:Steel or aluminum frames support heavy merchandise categories with extended floor-life requirements beyond single-use campaign durations.
Cardboard displays lead on scale; hybrid displays lead on momentum.
Use Case:
Activation context determines dimensional tolerances, graphic refresh cycles, and retailer handling protocols.
- Point of Sale:Immediate-conversion fixtures positioned at checkout or aisle-end locations dominate current deployment volume. US grocery chains deploy standardized shelf dimensions that reward displays with precise dimensional tolerances.
- Retail Promotions:Modular planogram systems are widening fastest as mass-market retailers adopt centralized category management functions requiring rapid planogram reconfiguration.
- Seasonal Campaigns:Subscription-based design refresh services generate recurring revenue atop physical procurement for CPG brands rotating artwork quarterly.
- Trade Shows:Reusable conversion mechanisms suit multi-event activation circuits where transport damage risk exceeds retail handling intensity.
Point of Sale anchors volume concentration; Retail Promotions shows the steepest expansion trajectory.
Material:
Input specifications govern compliance pathways, barrier performance, and end-of-life recovery economics.
- Corrugated Fiberboard:Kraftliner and recycled medium combinations form the structural backbone of mainstream shipper displays. Nordic mill concentration creates supply tightness when producers curtail output.
- Recycled Paper:Post-consumer fiber grades face FDA food-contact substance notification requirements that restrict barrier coatings in fresh produce applications.
- Wood:Pallet-grade timber substitutes suit heavy-load agricultural and beverage applications where compression strength exceeds fiberboard ratings.
- Acrylic:Clear or printed sheet stock serves premium cosmetic presentations requiring transparency or high-gloss surface finish.
Corrugated fiberboard commands procurement scale; recycled paper faces the steepest regulatory reformulation burden.
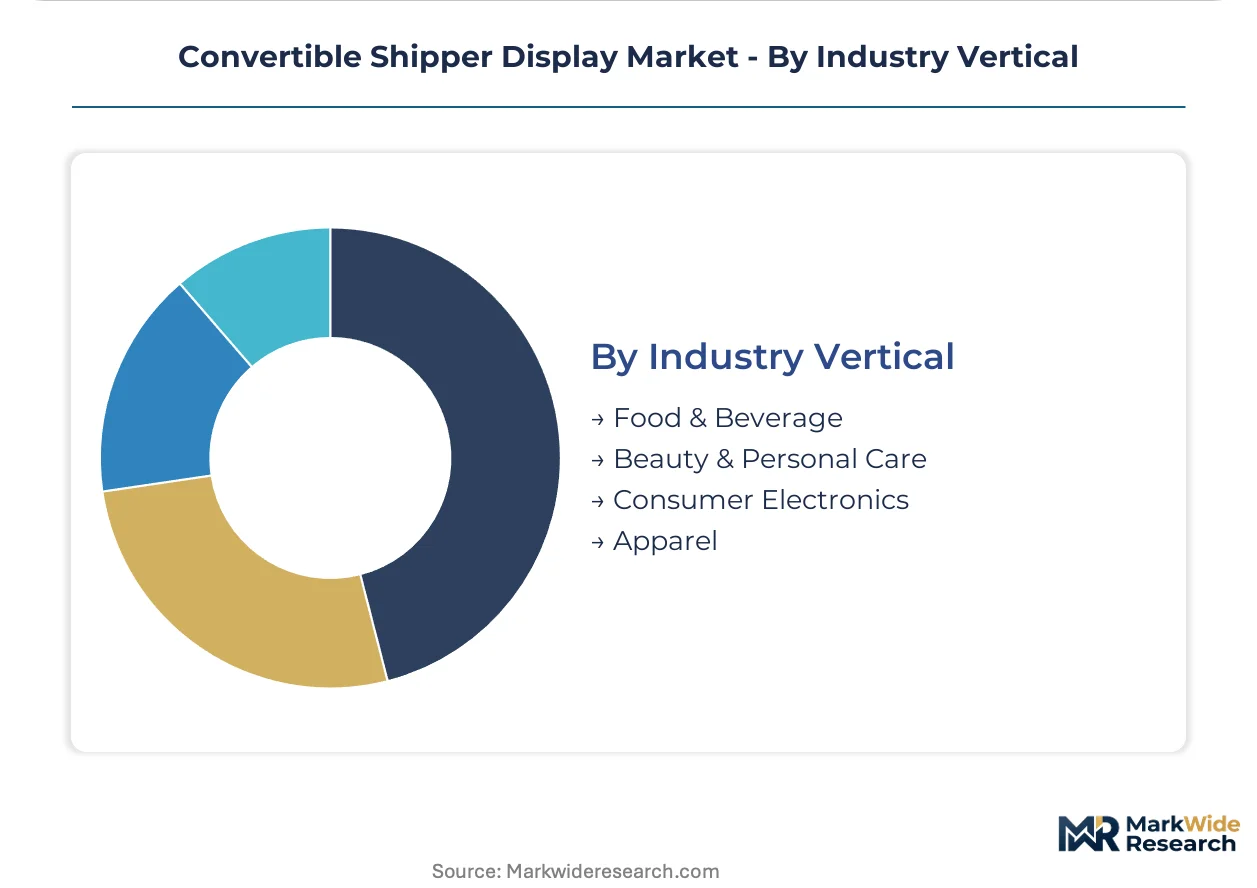
Industry Vertical:
End-use channel requirements differentiate certification needs, graphic complexity, and shelf-life expectations.
- Food & Beverage:Displays serving this vertical face parallel FDA and EU EFSA approvals for food-contact barriers that delay product launches. REACH substance restrictions on per- and polyfluoroalkyl substances force grease-resistant coating reformulation.
- Beauty & Personal Care:Premium brands demand circular material certification programs that validate supply chain sustainability claims and support premium pricing.
- Consumer Electronics:Unboxing experience requirements drive hybrid substrate adoption for structural protection combined with printable brand surfaces.
- Apparel:Soft-goods handling tolerates lighter fiberboard grades with reduced compression ratings compared to beverage or electronics applications.
Food & Beverage generates the largest procurement volume; Beauty & Personal Care offers the highest margin certification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's retail-ready packaging mandates contrast with the United States' modular planogram adoption, revealing how regulatory frameworks and retailer consolidation patterns shape divergent growth trajectories across major convertible shipper display markets.
United States
Mass-market grocers deploy standardized shelf dimensions that reward displays with precise dimensional tolerances. EPA recycled content guidelines shape supplier qualification for corrugated inputs. The Midwest industrial corridor surrounding Chicago hosts concentrated converter capacity serving CPG brands with rapid turnaround requirements.
Germany
Retail chains mandate shelf-ready packaging formats that eliminate backroom handling labor. EU Green Deal packaging rules drive substrate substitution toward certified fiberboard grades. The Baden-Württemberg region anchors production clusters where converters integrate circular material certification programs.
France
Beauty and personal care brands demand circular material validation for premium channel positioning. REACH substance restrictions on per- and polyfluoroalkyl substances force grease-resistant barrier reformulation. The Île-de-France region concentrates design-to-sprint studios serving Paris-headquartered FMCG headquarters.
China
Electronics unboxing experiences drive hybrid substrate adoption combining structural protection with printable brand surfaces. GB standards govern recycled fiber content declarations in retail-ready formats. The Yangtze River Delta manufacturing belt hosts integrated converter-printing operations for export-oriented consumer brands.
India
Modern trade expansion in metropolitan markets introduces retail-ready packaging requirements previously confined to traditional trade. BIS certification standards for corrugated board grades influence procurement specifications. The Maharashtra-Gujarat industrial corridor develops converter capacity serving domestic FMCG distribution networks.
Convertible Shipper Display Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated fiberboard producers capturing premium-tier relationships while regional converters serve price-sensitive volume accounts. The vendor base organizes around three strategic archetypes: captive mill-network operators, design-forward structural engineering studios, and scale-driven commodity converters. M&A activity concentrates on design capability acquisition, while capacity expansion targets hybrid substrate production lines.
Among European integrated producers, Smurfit Kappa Group and DS Smith occupy positions emphasizing captive supply security and circular certification programs respectively. WestRock Company represents the North American design-speed archetype, anchoring competitive positioning through in-house structural studios. These three exemplify how geographic mill access and service model differentiation create distinct competitive vectors without overlapping segment focus.
| Leading Market Players |
|---|
| Smurfit Kappa Group |
| WestRock Company |
| International Paper Company |
| DS Smith |
| Sonoco Products Company |
| Menasha Packaging Company |
| Packaging Corporation of America |
| Georgia-Pacific LLC |
| Delkor Systems |
| Others |
Value Chain & Pricing Dynamics
Structural CAD specialists concentrated in the Baden-Württemberg region and Chicago industrial corridor command wage premiums that widen pricing spreads between premium design-forward displays and commodity-grade corrugated units. Labor-cost differentials between these engineering hubs and lower-cost converter regions feed directly into three-tier pricing stratification across certified sustainable, standard recyclable, and economy-grade shipper displays.
Pricing Analysis
Capacity additions in Germany and the United States are reshaping price floors for certified fiberboard grades as captive mill networks expand output. Three-tier pricing structure across premium circular-certified, standard retail-ready, and economy-grade transactional tiers dominates procurement contracts. Price differentiation hinges on EU Green Deal compliance certification and volume-scale commitments from CPG brands. Pricing pressure stems from OCC input cost volatility driven by Chinese import policy shifts, with mass-market grocery chains exhibiting highest price sensitivity and beauty brands showing least.
Supply Chain Analysis
EU EFSA food-contact qualification and FDA notification pathways gate supplier access to Food & Beverage vertical procurement lists. Supply concentrates in Germany, the United States, and China as integrated producers anchor regional hub strategies. Raw material dependencies center on Nordic kraftliner, recycled OCC streams, and mineral-oil-free barrier coatings. Single-source vulnerability around Scandinavian mill concentration creates supply tightness risk when producers curtail output. Distribution runs through converter-direct relationships with centralized retail category management functions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as retail labor-cost elimination mandates harden across German and US grocery chains. The structural shift toward shelf-ready packaging formats provides durable demand visibility.
For Market Incumbents: Acquire structural design studios with fold-out mechanism CAD specialization to capture subscription-based seasonal artwork refresh contracts. Consolidate vendor relationships around end-to-end accountability to defend against fragmented converter competition. Invest in captive kraftliner supply arrangements to mitigate Nordic mill concentration risk. For New Entrants and Emerging Players: Enter via hybrid substrate production lines serving electronics unboxing and beauty brand activations where premium positioning tolerates higher unit economics. Target Indian modern trade expansion corridors where retail-ready packaging requirements are newly penetrating metropolitan markets. Pursue circular material certification as primary go-to-market credential. For Investors and Strategic Acquirers: Integrated fiberboard producers are the most active acquirer in this space, seeking design capability to complete vertical coverage. Five-to-ten-year viability rests on regulatory tailwinds for recyclable formats and labor-cost compression at retail. Monitor California and New York extended producer responsibility legislation progression as inflection signal for cost-allocation shifts toward display manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Design Service Launch | Seasonal artwork refresh contracts generate recurring revenue atop physical display procurement for CPG brands. |
| Hybrid Substrate Production Line Investment | Metal-reinforced corners with printable paper surfaces capture premium positioning in electronics unboxing channels. |
| Circular Material Certification Program | EU Green Deal compliance validates supply chain sustainability claims for beauty and personal care vertical access. |
| Captive Kraftliner Supply Arrangement | Nordic mill network integration mitigates output curtailment risk and secures fiberboard grade consistency. |
| Structural Design Studio Acquisition | Fold-out mechanism CAD capabilities compress speed-to-shelf timelines for centralized retail category management. |
Study Parameters
Bottom-up CPG brand procurement modeling reconciled against top-down corrugated converter capacity tracking forms the analytical core of this study. Primary interviews with structural packaging engineers, retail category buyers, corrugated plant managers, and sustainability compliance officers were validated against secondary sources including EPA recycled content guidelines, EU EFSA food-contact barrier filings, customs trade data for OCC and kraftliner flows, and SEC 10-K disclosures from integrated fiberboard producers. Triangulation between demand-side procurement patterns and supply-side mill output data ensures cross-verified volume and value estimates.
Input-output matrices map substrate technology, activation context, material specification, and industry vertical dimensions across the projection horizon. Segmentation modeling captures cardboard, hybrid, plastic, and metal display types; Point of Sale, Retail Promotions, Seasonal Campaigns, and Trade Show use cases; corrugated fiberboard, recycled paper, wood, and acrylic materials; and Food & Beverage, Beauty & Personal Care, Consumer Electronics, and Apparel verticals. CAGRs were derived from regression analysis against retail square footage expansion, grocery labor-cost indices, and regulatory compliance timeline assumptions.
Inputs from EPA, FDA, and EU regulatory filings were available through the study window; gaps in real-time OCC spot pricing and private-label CPG procurement contract terms introduce uncertainty bands around margin projections. Forecasts reflect documented assumptions about EU Green Deal implementation pacing and US state-level extended producer responsibility adoption. A model refresh is warranted upon material change in Chinese OCC import policy or Nordic kraftliner producer output decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Textile Composites Market
Others
Asia-Pacific Social Media Management Market
Others
Electrical Calibration Equipment Market
Others
Latin America Automotive HVAC Market
Others
Transportation Lighting Market
Others
Hotel Wardrobe Market
Others
Global Simulation in Healthcare Market
Others
Infant Positioning Aids Market
Others
South Korea Automotive LED Lighting Market
Others
Griffin Beaker Market
Others
North America Flexographic Printing Market
Others
Mobile Edge Computing Market
Others
Bimodal Identity Management Solutions Market
Others
Global Social Networking Market
Others
Industrial Air Purifiers Market
Others
AC Switchgear Market