
 Online to Offline Commerce Market | 2026-2036
Online to Offline Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Online to Offline Commerce Market Outlook
Subscription-based delivery memberships is shifting the unit economics of online to offline commerce from transactional margins to recurring revenue pools. Alibaba Group Holding Limited anchors super-app ecosystems that bundle food delivery, grocery, and local services into unified payment flows. DoorDash, Inc. dominates North American suburban density through exclusive quick-commerce partnerships with national pharmacy and convenience chains. JD.com, Inc. leverages captive warehouse networks to sustain same-day fulfillment promises at lower per-order cost than asset-light competitors.
Online to offline commerce denotes digital order origination paired with physical fulfillment, typically orchestrated through API-connected inventory systems, geofenced pickup zones, and real-time fleet dispatch algorithms that optimize last-mile handoffs. The primary commercial purpose is to merge digital discovery convenience with immediate product availability, reducing cart abandonment while capturing impulse purchases that pure e-commerce cannot serve. Mobile apps and social media platforms represent the fastest-expanding origination channels, as short-form video commerce triggers location-based fulfillment requests. In-store pickup and curbside pickup models retain the highest margin pools because they eliminate last-mile delivery subsidy, though same-day delivery commands premium pricing from time-sensitive retail consumers.
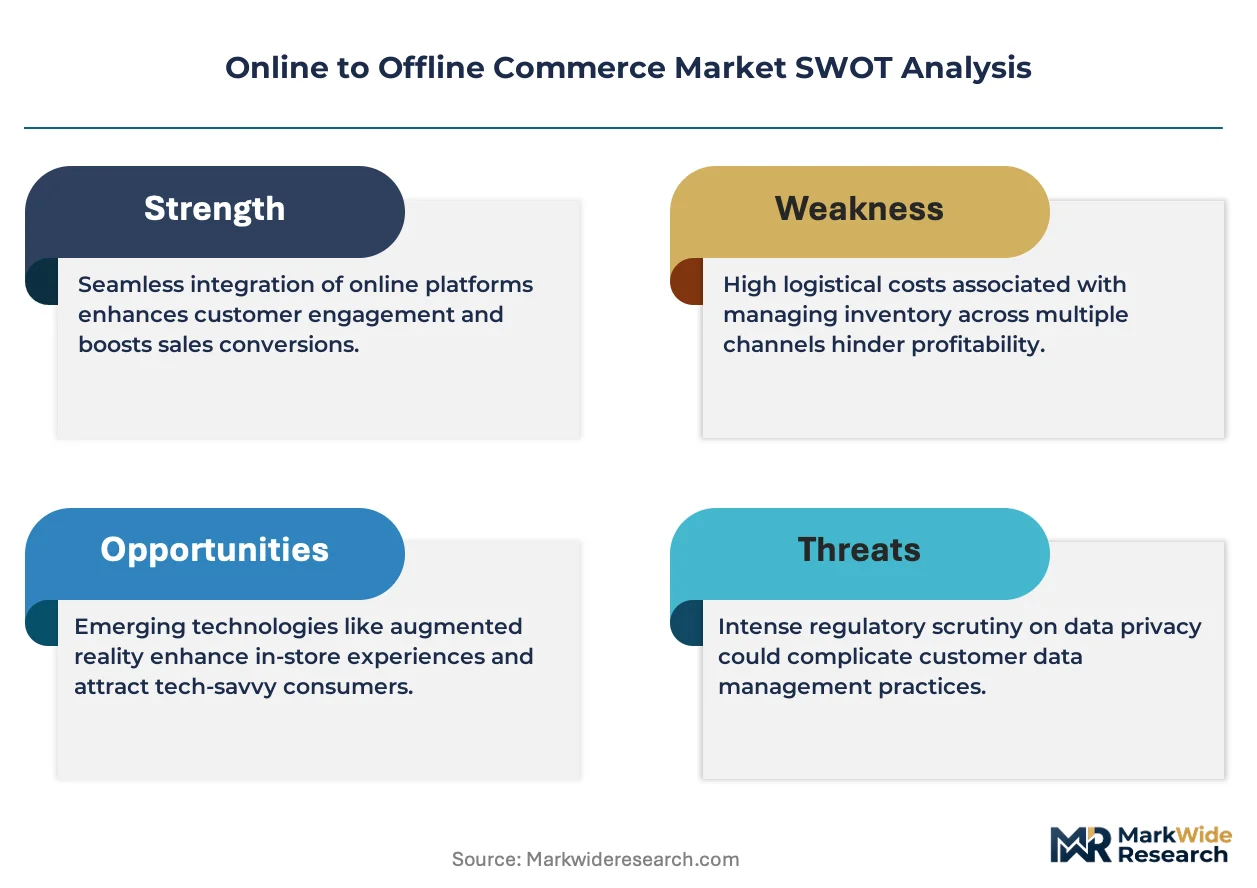
The US Federal Trade Commission scrutinizes platform self-preferencing in local commerce marketplaces, while China's SAMR enforces anti-monopoly provisions that constrain exclusive merchant contracts. India's Digital Personal Data Protection Act imposes consent-layer requirements on customer location tracking used for proximity-based promotions. Stakeholders must monitor how divergent data governance frameworks fragment the technical stack required to operate across multiple national markets.
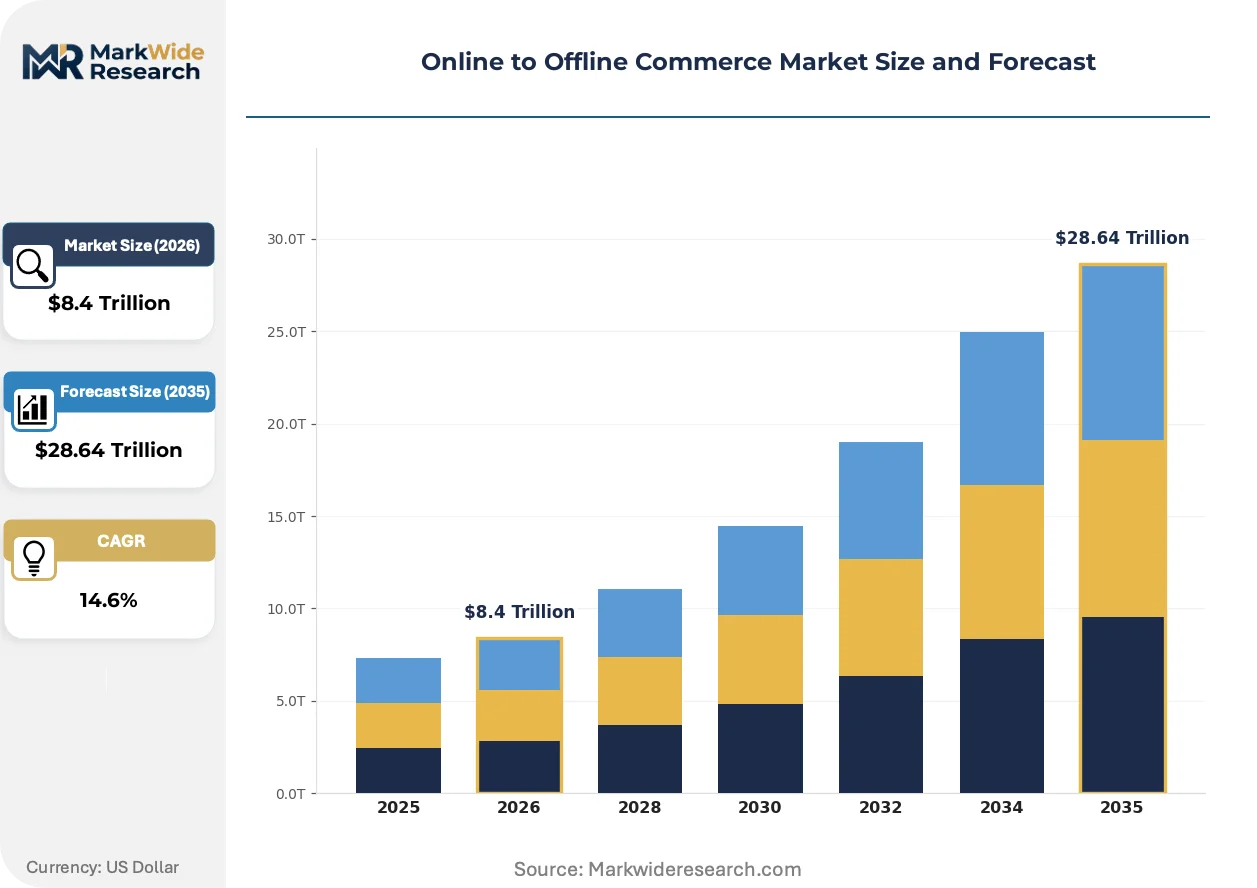
Market Dynamics
Subscription-based delivery memberships are compressing unit economics toward recurring revenue pools, forcing platforms to engineer captive fulfillment networks that lock in consumer lifetime value through bundled service ecosystems.
Growth Catalysts
- Click-and-collect infrastructure:Grocery retailers are retrofitting urban stores with geofenced pickup zones and API-connected inventory systems. This channel eliminates last-mile delivery subsidy while capturing impulse purchases.
- India's Digital Personal Data Protection Act:Consent-layer requirements on location tracking are pushing platforms toward privacy-preserving proximity algorithms. Compliance investments are accelerating technical differentiation among compliant operators.
- Short-form video commerce:Mobile apps and social platforms trigger location-based fulfillment requests through real-time content-to-checkout pipelines. This origination channel is expanding fastest across Southeast Asian urban corridors.
Market Restraints
- Data localization mandates:China's SAMR rules force platform architecture fragmentation, raising engineering costs for cross-border operators. Technical stacks must replicate across jurisdictional boundaries.
- Urban logistics corridor saturation:Last-mile fleet density in São Paulo and Mumbai is approaching congestion limits. Delivery time promises face hard physical constraints.
- Merchant exclusivity constraints:Anti-monopoly provisions in multiple jurisdictions limit platform ability to lock in supply. Contract flexibility favors multi-homing merchants.
Strategic Opportunities
- Brazilian secondary cities:Underpenetrated urban logistics networks outside São Paulo and Rio offer first-mover advantages for platform operators building captive warehouse networks.
- Quick-commerce pharmacy partnerships:National pharmacy chains in suburban North American markets represent untapped fulfillment density for subscription-based delivery memberships.
- Unified payment flow convergence:Super-app ecosystems bundling food delivery, grocery, and local services create cross-subsidy opportunities between high-frequency and high-margin categories.
Industry Challenges
- Real-time fleet dispatch algorithm talent:Scarcity of engineers with geospatial optimization expertise is constraining same-day fulfillment promise expansion. Compensation inflation is compressing platform margins.
- Legacy POS integration friction:In-store pickup models require API connections to fragmented merchant inventory systems. Technical debt in mid-market retail slows rollout velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online to Offline Commerce Market |
| Market Size in 2026 | $8.4 Trillion |
| Market Size in 2035 | $28.64 Trillion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Customer Type: Retail Consumers, Business Clients, Enterprises, Service Providers Platform Type: E-commerce Sites, Mobile Apps, Social Media, Marketplaces Payment Method: Credit/Debit Cards, Digital Wallets, Bank Transfers, Cash Fulfillment Model: In-Store Pickup, Same-Day Delivery, Curbside Pickup, Direct Shipping |
| Companies Covered | DoorDash, Inc., Delivery Hero SE, Alibaba Group Holding Limited, Zomato Limited, Grab Holdings Limited, Meituan, Uber Technologies, Inc., Walmart Inc., JD.com, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online to Offline Commerce Market Strategic Shifts
Platform operators are racing to consolidate fragmented fulfillment infrastructure into unified technical stacks that can simultaneously serve multiple origination channels without duplicating fixed costs.
Geofenced curbside pickup technology is consolidating order handoff efficiency across grocery, pharmacy, and convenience verticals. Urban retailers in dense Indian and Brazilian corridors are adopting these systems fastest. The technology is consolidating margin pools previously lost to last-mile delivery subsidies into captive in-store fulfillment networks.
China's SAMR anti-monopoly enforcement is constraining exclusive merchant contracting practices. Platform self-preferencing scrutiny from the US Federal Trade Commission is forcing marketplace operators to unbundle search ranking algorithms from captive fulfillment services. Quick-commerce operators in both jurisdictions are responding by deepening direct warehouse ownership to maintain service differentiation.
Time-sensitive retail consumers are compressing switching cycles between delivery promise windows. Same-day delivery premiums are displacing next-day tolerance in urban Indian and Southeast Asian markets. This behavior is most visible among pharmacy and convenience categories where stockout avoidance drives platform loyalty.
Online to Offline Commerce Market Segmentation
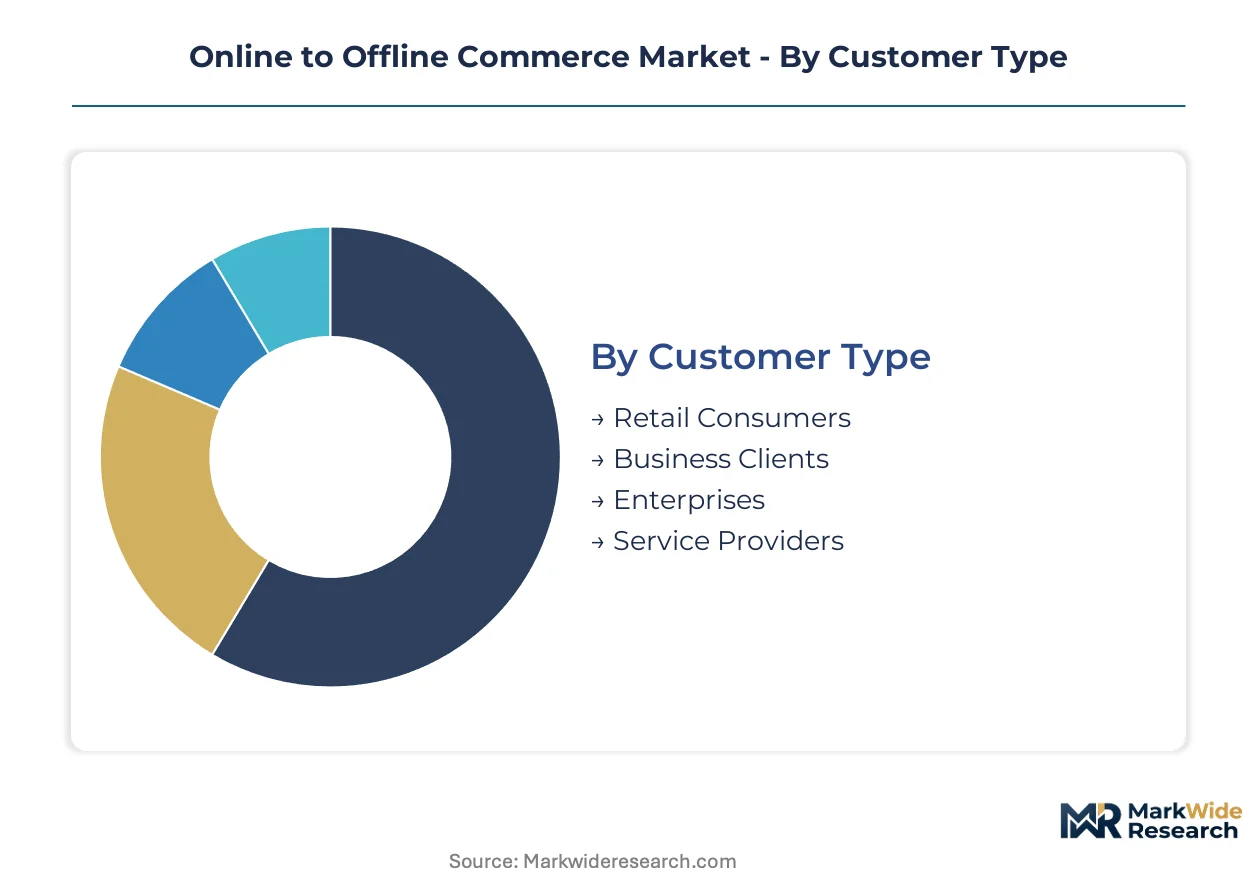
Segmentation in online to offline commerce reveals how order origination channels, fulfillment infrastructure, and payment flows determine platform economics. Each dimension carries distinct margin profiles and capital intensity requirements that shape competitive positioning.
Customer Type:
Upgrade cycles across customer segments track digital maturity and procurement centralization, with enterprise accounts demanding API-first integration while retail consumers pivot through mobile-native discovery.
- Retail Consumers:Individual purchasers initiating orders through mobile apps and social platforms. Demand clusters in urban Indian and Southeast Asian corridors where short-form video commerce triggers impulse fulfillment requests.
- Business Clients:Small and mid-size operations purchasing through subscription memberships. Procurement concentrates in North American suburban density where quick-commerce pharmacy partnerships reduce stockout risk.
- Enterprises:Large organizations requiring unified procurement dashboards and consolidated invoicing. Technical integration complexity slows adoption outside vertically integrated supply chains.
- Service Providers:Third-party logistics and fleet operators intermediating last-mile handoffs. Margin pressure intensifies as urban logistics corridor saturation hardens in São Paulo and Mumbai.
Retail Consumers sit at the top of the volume ranking, with Business Clients climbing the fastest.
Platform Type:
Platform architecture investments stratify by origination cost tier, with super-app ecosystems commanding the highest fixed-cost bases but capturing cross-category payment flow convergence.
- E-commerce Sites:Web-based storefronts with legacy inventory management systems. Merchant adoption lags in Brazilian secondary cities where mobile-first penetration outpaces desktop infrastructure.
- Mobile Apps:Native applications with geofenced pickup coordination and real-time fleet dispatch. Demand concentrates across China's urban logistics networks where SAMR data localization rules shape technical stack replication.
- Social Media:Short-form video platforms embedding checkout flows within content feeds. This segment expands most quickly through Southeast Asian urban corridors as live commerce triggers location-based fulfillment.
- Marketplaces:Aggregator platforms connecting fragmented merchant supply with centralized demand. US FTC self-preferencing scrutiny constrains search algorithm unbundling from captive fulfillment services.
Mobile Apps anchor the revenue base, while Social Media gains share fastest.
Payment Method:
Payment flow configuration varies by customer trust thresholds and regulatory consent-layer requirements, with digital wallets displacing card rails in privacy-sensitive markets.
- Credit/Debit Cards:Traditional card networks processing through PCI-compliant gateways. Dominant in North American suburban markets with established banking infrastructure.
- Digital Wallets:Stored-value and tokenized payment systems integrated into super-app ecosystems. India's Digital Personal Data Protection Act accelerates privacy-preserving proximity algorithm adoption among compliant wallet operators.
- Bank Transfers:Direct account-to-account settlement through real-time payment rails. Preferred by Enterprise segments for reduced interchange costs on high-volume procurement.
- Cash:Physical currency exchange at pickup points or through collection agents. Persistent in Brazilian secondary cities and Indian tier-2 urban corridors with underpenetrated digital banking.
Digital Wallets lead transaction volume, with Bank Transfers expanding most quickly among Enterprise procurement.
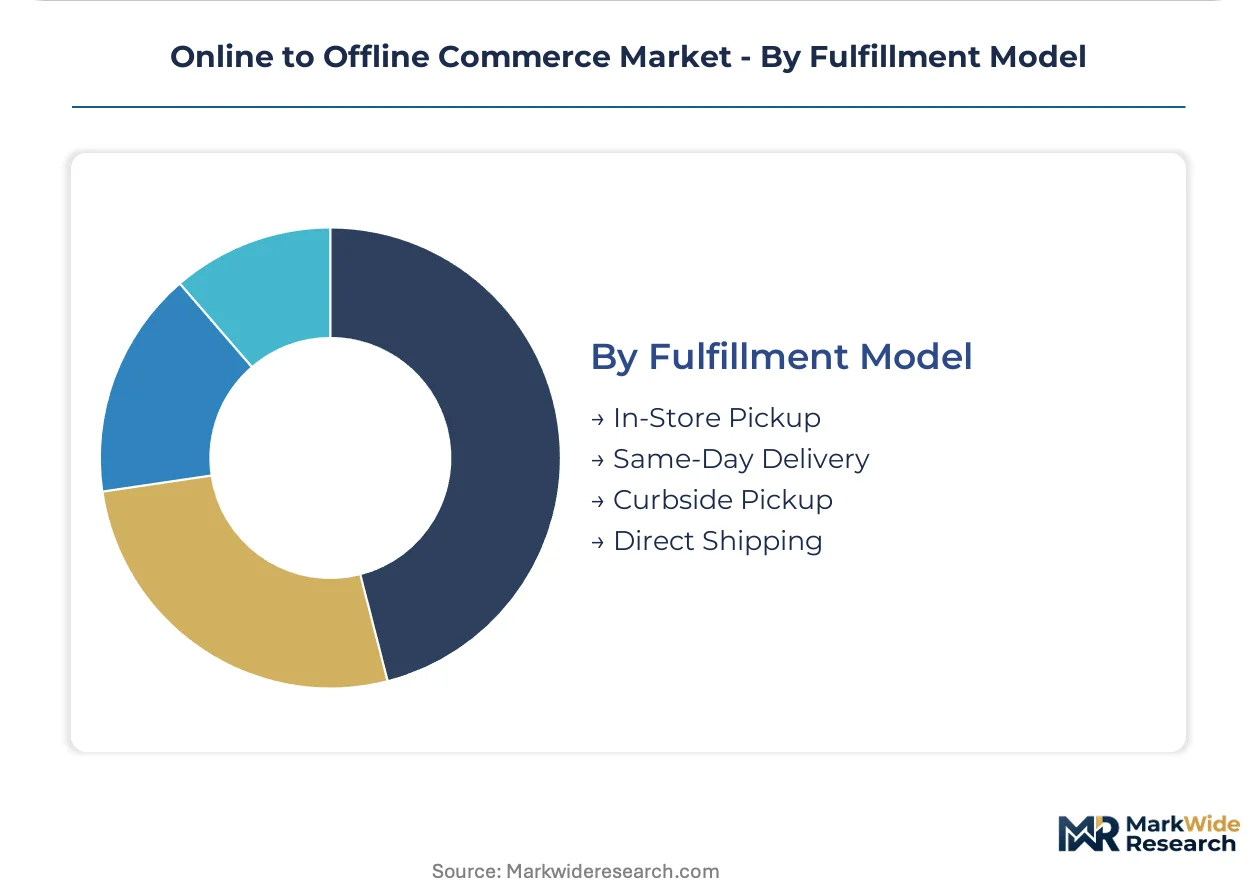
Fulfillment Model:
Fulfillment infrastructure maturity determines margin retention, with pickup models eliminating last-mile subsidy while delivery promises capture time-sensitive premiums.
- In-Store Pickup:Customer collection from dedicated pickup zones with API-connected inventory visibility. Grocery retailers retrofitting urban stores capture margin pools previously lost to delivery subsidies.
- Same-Day Delivery:Compressed fulfillment windows through captive warehouse networks and algorithmic fleet dispatch. JD.com leverages captive infrastructure to sustain promises at lower per-order cost than asset-light competitors.
- Curbside Pickup:Geofenced handoff coordination without parking or store entry. Urban retailers in dense Indian and Brazilian corridors adopt these systems fastest.
- Direct Shipping:Traditional parcel delivery from centralized distribution centers. Merchant exclusivity constraints across multiple jurisdictions limit platform ability to lock in supply for this model.
In-Store Pickup retains the highest margin pool, with Same-Day Delivery commanding the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's SAMR data localization mandates force platform architecture replication that raises engineering costs, while India's Digital Personal Data Protection Act accelerates privacy-preserving proximity algorithm adoption among compliant operators.
China
Super-app ecosystems bundle food delivery, grocery, and local services into unified payment flows across urban logistics networks. SAMR anti-monopoly enforcement constrains exclusive merchant contracting practices, forcing platforms toward direct warehouse ownership. Shanghai and Beijing anchor captive fulfillment network expansion as operators deepen infrastructure control.
United States
Subscription-based delivery memberships dominate North American suburban density through quick-commerce partnerships with national pharmacy chains. FTC scrutiny of platform self-preferencing forces marketplace operators to unbundle search ranking algorithms from captive fulfillment services. DoorDash anchors exclusive suburban partnerships while urban corridors face merchant multi-homing pressure.
India
Short-form video commerce triggers location-based fulfillment requests across Southeast Asian urban corridors, with Mumbai approaching last-mile fleet congestion limits. The Digital Personal Data Protection Act imposes consent-layer requirements on customer location tracking, pushing platforms toward privacy-preserving proximity algorithms. Bangalore and Delhi-NCR concentrate technical differentiation investments among compliant operators.
Brazil
Underpenetrated urban logistics networks outside São Paulo and Rio offer first-mover advantages for platform operators building captive warehouse networks. Cash persistence at pickup points slows digital wallet displacement in tier-2 urban corridors. Minas Gerais and Paraná represent expansion targets for geofenced curbside pickup retrofitting.
Germany
Enterprise procurement through subscription memberships concentrates in established banking infrastructure corridors. GDPR compliance requirements shape API-connected inventory system architecture for cross-border operators. The Rhine-Ruhr metropolitan region anchors B2B fulfillment density as platforms engineer unified procurement dashboards.
Online to Offline Commerce Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with super-app ecosystems commanding the highest fixed-cost bases while asset-light aggregators capture origination volume. The vendor base concentrates around three strategic archetypes: captive fulfillment network operators, marketplace aggregators, and subscription membership platforms. M&A activity targets geofenced pickup technology providers, while capacity expansion focuses on Brazilian and Indian secondary city warehouse networks.
Within the super-app ecosystem tier, Alibaba Group Holding Limited and Meituan exemplify unified payment flow convergence across food delivery, grocery, and local services. JD.com, Inc. occupies a position among captive warehouse network operators leveraging owned infrastructure to sustain same-day fulfillment promises. These three Chinese entities anchor distinct competitive vectors—ecosystem bundling versus fulfillment ownership—within the broader market structure.
| Leading Market Players |
|---|
| DoorDash, Inc. |
| Delivery Hero SE |
| Alibaba Group Holding Limited |
| Zomato Limited |
| Grab Holdings Limited |
| Meituan |
| Uber Technologies, Inc. |
| Walmart Inc. |
| JD.com, Inc. |
| Others |
Value Chain & Pricing Dynamics
Urban logistics labor cost indices in São Paulo and Mumbai cascade through last-mile fulfillment networks into three-tier pricing structures across premium, standard, and economy service levels. Subscription membership pools absorb fixed cost volatility while per-transaction fees compress under fleet density saturation.
Pricing Analysis
Capacity additions in Brazilian secondary cities are reshaping price floors for same-day delivery promises. Pricing stratifies across premium, standard, and economy tiers based on fulfillment speed guarantees and inventory proximity. Cost compression in standard-tier suburban markets is intensifying because DoorDash exclusive partnerships lock in merchant supply. Enterprise procurement segments show least price sensitivity due to consolidated invoicing efficiencies, while retail consumers in Indian tier-2 corridors exhibit highest elasticity to delivery fee fluctuations.
Supply Chain Analysis
Engineering talent shortages in Chinese and Indian urban technology corridors constrain real-time fleet dispatch algorithm development. Fulfillment infrastructure draws from warehouse construction materials, API middleware licenses, and geofencing hardware modules. Single-source vulnerability concentrates in JD.com-style captive warehouse networks where proprietary systems resist interoperability. Distribution runs through API-connected inventory systems into geofenced pickup zones or algorithm-coordinated last-mile fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in online to offline commerce rests on eliminating last-mile delivery subsidies through curbside pickup retrofitting and converting transactional users into subscription pools.
For Market Incumbents: Lock in merchant supply through exclusive quick-commerce partnerships with national pharmacy and convenience chains before FTC self-preferencing scrutiny hardens. Deepen direct warehouse ownership in São Paulo and Mumbai to sustain same-day promises against asset-light competitors. Geofenced pickup technology acquisitions defend margin pools from delivery subsidy erosion. For New Entrants and Emerging Players: Privacy-preserving proximity algorithms offer entry leverage into Indian urban corridors where Digital Personal Data Protection Act compliance creates technical differentiation barriers. Brazilian secondary cities present the most penetrable geography given underdeveloped captive warehouse networks. Go-to-market through cash-integrated pickup points in Minas Gerais and Paraná bypasses digital wallet infrastructure gaps. For Investors and Strategic Acquirers: Consolidation pressure builds where urban logistics corridor saturation meets scarce geospatial optimization engineering talent. Long-term viability favors platforms with unified payment flow convergence across food, grocery, and local service bundles. Acquisition targets should display API-first inventory integration and geofenced curbside deployment capability. Watch for inflection when short-form video commerce origination exceeds 40% of location-based fulfillment requests in Southeast Asian markets.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Warehouse Network Expansion | JD.com demonstrates lower per-order fulfillment cost than asset-light competitors through owned infrastructure. |
| Geofenced Curbside Technology Deployment | Urban retailers in Indian and Brazilian corridors capture margin pools previously lost to last-mile subsidies. |
| Super-App Payment Flow Convergence | Alibaba bundles food delivery, grocery, and local services into unified ecosystems that cross-subsidize categories. |
| Privacy-Preserving Proximity Algorithm Development | India's Digital Personal Data Protection Act pushes compliant operators toward technical differentiation. |
| Exclusive Pharmacy Partnership Structuring | DoorDash anchors North American suburban density through national chain quick-commerce arrangements. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement captured platform operations executives, merchant supply leads, fleet dispatch engineers, and urban logistics planners. Secondary validation drew from SAMR regulatory filings, FTC enforcement dockets, SEC 10-K infrastructure disclosures, and customs data on warehouse construction imports. Bottom-up order volume modeling and top-down addressable market sizing underwent iterative triangulation.
Comparable historical periods anchored the projection horizon to observed adoption curves across mobile-first commerce transitions. Segmentation dimensions spanned customer type, platform architecture, payment method, and fulfillment model, with API integration complexity as an industry-specific overlay. CAGRs derived from logistic curve fitting to subscription membership penetration rates and short-form video commerce origination trajectories. Fleet density limits and data localization compliance costs served as boundary constraints.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory fragmentation across SAMR, FTC, and Digital Personal Data Protection Act jurisdictions. Assumptions reflect current merchant exclusivity constraint severity and urban congestion inflection points. Material deviation in cross-border data flow restrictions or last-mile autonomous vehicle deployment warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Singapore E-Commerce Market
E-Commerce Solutions
Canada E-Commerce Market
E-Commerce Solutions
Digital Gift Cards (Egift Cards) Market
E-Commerce Solutions
Hungary E-Commerce Market
E-Commerce Solutions
Quiet Commerce Market
E-Commerce Solutions
India Quick Commerce Market
E-Commerce Solutions
Vietnam E-Commerce Market
E-Commerce Solutions
Europe Dropshipping Market
E-Commerce Solutions
Brazil E-Commerce Market
E-Commerce Solutions
Mobile Commerce Market
E-Commerce Solutions
South Korea E-Commerce Market
E-Commerce Solutions
Argentina E-Commerce Market
E-Commerce Solutions
Indonesia E-Services Market
E-Commerce Solutions
Malaysia E-Commerce Market
E-Commerce Solutions
Conversational Commerce Market
E-Commerce Solutions
Nigeria Alcohol E-Commerce Market