
 Europe Food Platform-To-Consumer Delivery Market | 2026-2036
Europe Food Platform-To-Consumer Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Food Platform-To-Consumer Delivery Market Foresight
GDPR enforcement around algorithmic management is shifting compliance burdens for delivery platforms operating across member states. Just Eat Takeaway.com leverages its restaurant network density to sustain market presence in Northern Europe. Deliveroo anchors its competitive profile through grocery partnerships that extend beyond pure meal delivery. Uber Eats differentiates via technology leadership in route optimization and customer analytics.
Food platform-to-consumer delivery encompasses digital intermediaries that connect end-users with prepared meals, groceries, and specialty items through mobile applications and web interfaces, typically processing orders within 30-60 minute fulfillment windows. Restaurant Delivery dominates transaction volumes across the continent, though Grocery Delivery captures expanding margin pools as basket sizes grow and subscription models deepen retention. Mobile App interfaces lead technology adoption, while AI Recommendation engines represent the fastest-growing capability investment as platforms compete on personalization accuracy.
The EU Platform Work Directive, alongside national implementations by Germany's KBA-influenced labor frameworks and France's CNIL oversight of rider data processing, tightens operational requirements for platform employment models. EFSA guidelines on food safety during transit and REACH-aligned packaging standards further shape product handling protocols. Stakeholders must monitor how courier reclassification rulings in Brussels, Berlin, and Paris cascade into cost structures and pricing flexibility.
Market Dynamics
The EU Platform Work Directive is forcing delivery platforms to reclassify couriers as employees, compressing margin structures and accelerating automation investments across Germany, France, and the United Kingdom.
Growth Catalysts
- Urban Employment Density:Working professionals in metropolitan France and Germany generate concentrated demand for sub-30-minute fulfillment, sustaining order frequency during peak commute windows.
- GDPR Algorithmic Governance:The regulation mandates transparency in rider dispatch systems, compelling platforms to invest in explainable AI that improves courier retention and reduces regulatory friction.
- Grocery Basket Expansion:Partnerships with supermarket chains in the United Kingdom extend platform utility beyond prepared meals, capturing higher-margin recurring purchases through subscription bundling.
Market Restraints
- Courier Reclassification Costs:Germany's KBA-influenced labor frameworks and France's CNIL oversight impose payroll tax burdens that erode per-order economics for platforms operating hybrid employment models.
- Input Cost Volatility:Fuel price fluctuations across the eurozone directly impact last-mile delivery costs, with rural route density insufficient to absorb per-kilometer expense spikes.
- Substitution Threat:Dark kitchen operators and quick-commerce specialists with captive courier fleets bypass platform intermediation, capturing high-frequency urban demand through direct channels.
Strategic Opportunities
- Eastern European Expansion:Poland and Romania exhibit underpenetrated platform density relative to Western Europe, with rising digital payment adoption creating viable entry conditions for scaled operators.
- AI Route Convergence:Integration of predictive demand modeling with real-time traffic systems enables dynamic pricing that captures willingness-to-pay premiums during supply-constrained windows.
- EFSA Cold Chain Mandates:The food safety framework creates compliance barriers for unqualified competitors, allowing certified platforms to command premium positioning through verified handling protocols.
Industry Challenges
- Data Engineering Talent Scarcity:Platforms struggle to recruit machine learning specialists capable of optimizing dispatch algorithms under GDPR-constrained data architectures.
- Legacy POS Integration:Independent restaurants across Southern Europe operate fragmented ordering systems that resist API standardization, delaying real-time menu synchronization and inventory visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Food Platform-To-Consumer Delivery Market |
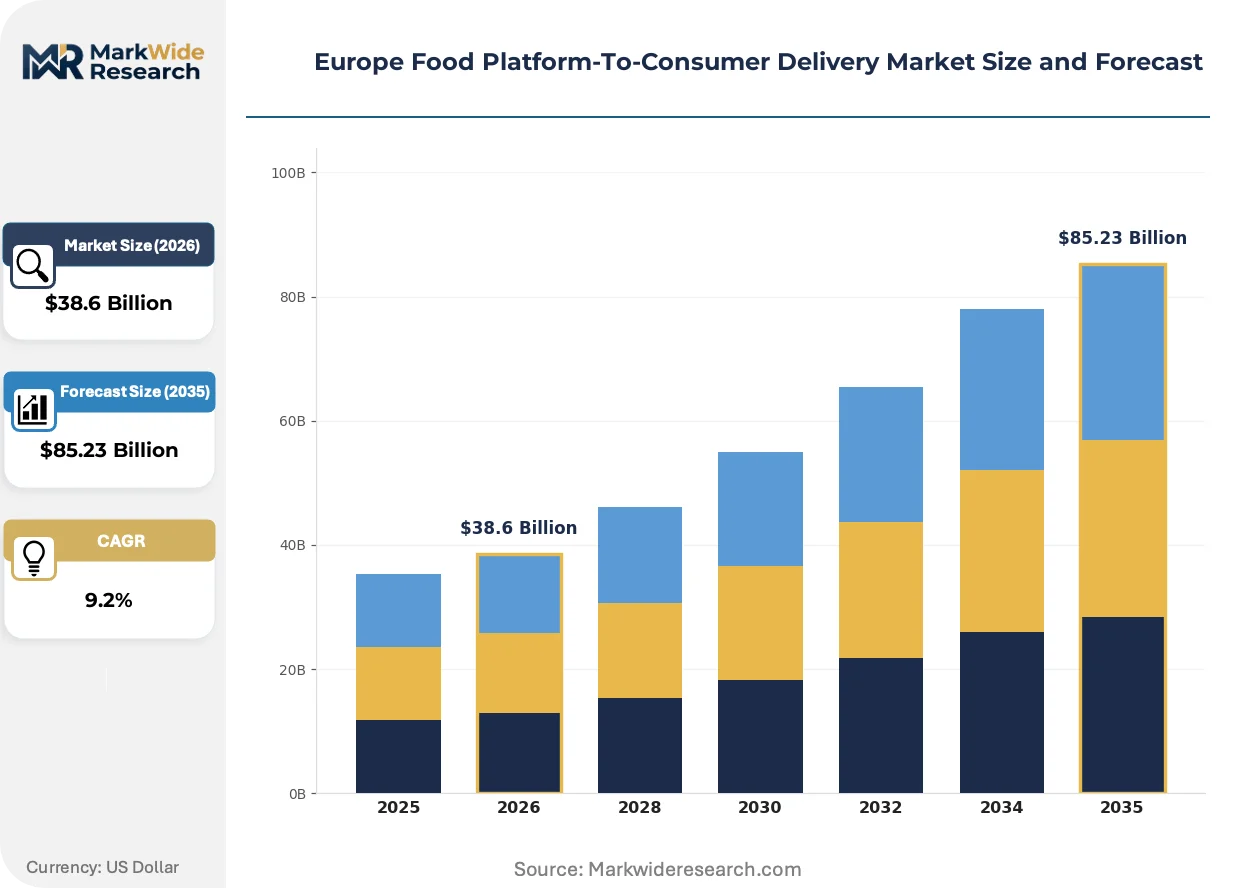
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $85.23 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Grocery Delivery, Meal Kits, Restaurant Delivery, Specialty Food Customer Type: Individual Consumers, Families, Seniors, Working Professionals Pricing Model: Subscription, Pay-Per-Delivery, Tiered Pricing, Free Delivery Technology: Mobile App, Web Platform, Delivery Tracker, AI Recommendation |
| Companies Covered | Just Eat Takeaway.com, Deliveroo, Uber Eats, Delivery Hero, Foodhub, Glovo, DoorDash, Bolt Food, Lieferando, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Food Platform-To-Consumer Delivery Market Shifts & Advancements
Algorithmic personalization is overtaking static menu browsing as the primary interface between platforms and consumers, compressing decision cycles and reorder latency across European metropolitan markets.
AI recommendation engines analyze historical purchase patterns, dietary preferences, and temporal context to surface individualized meal suggestions. Urban professionals in London and Paris adopt these interfaces at accelerating rates, reducing average order completion time by eliminating browse-to-decision friction. The technology is overtaking conventional category-based navigation, consolidating platform competitive advantage around data infrastructure depth rather than restaurant network scale alone.
The EU AI Act imposes risk classification requirements on automated decision systems affecting working conditions, including courier dispatch algorithms. Platforms must document training data provenance and algorithmic logic for regulatory audit, increasing compliance overhead but creating defensible moats against undercapitalized competitors. France's CNIL and Germany's KBA coordinate enforcement priorities, with multi-jurisdictional operators facing overlapping disclosure obligations that favor standardized pan-European technical architectures.
Subscription bundling is displacing transactional purchasing as the dominant customer relationship model. British and German consumers increasingly prefer flat-fee delivery memberships that reduce per-order cognitive load and increase platform switching costs. Quick-commerce operators in Amsterdam and Berlin accelerate this shift through grocery-meal hybrid subscriptions that capture weekly household spend, forcing pure-play meal platforms to expand category coverage or concede frequency to integrated competitors.
Europe Food Platform-To-Consumer Delivery Market Segmentation
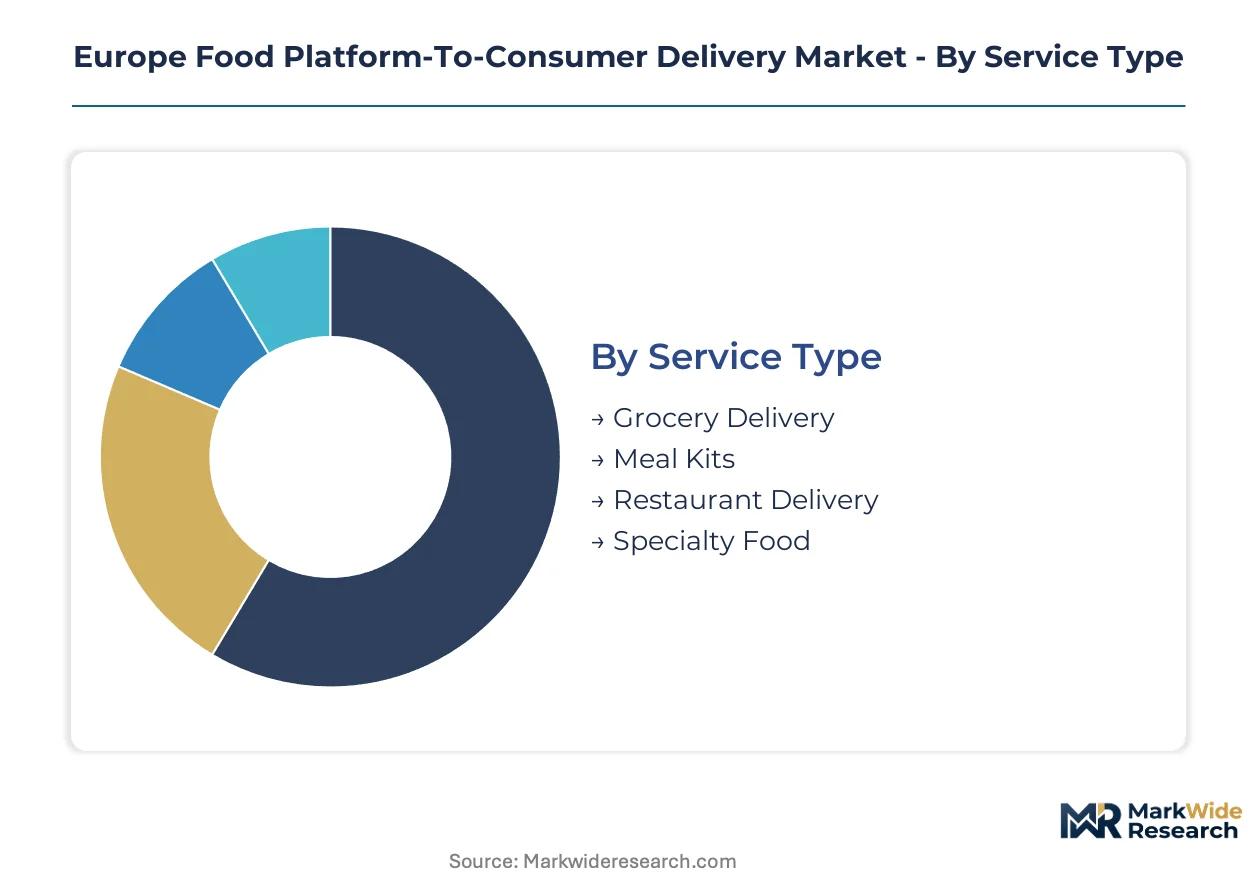
Segmentation in the Europe Food Platform-To-Consumer Delivery Market reveals how capital allocation, customer acquisition costs, and technology infrastructure requirements vary dramatically across service configurations. Platform operators must align resource deployment with segment-specific margin profiles and fulfillment complexity.
Service Type:
Capital intensity varies sharply across service configurations, with cold-chain infrastructure and inventory carrying costs creating divergent investment thresholds for market entry.
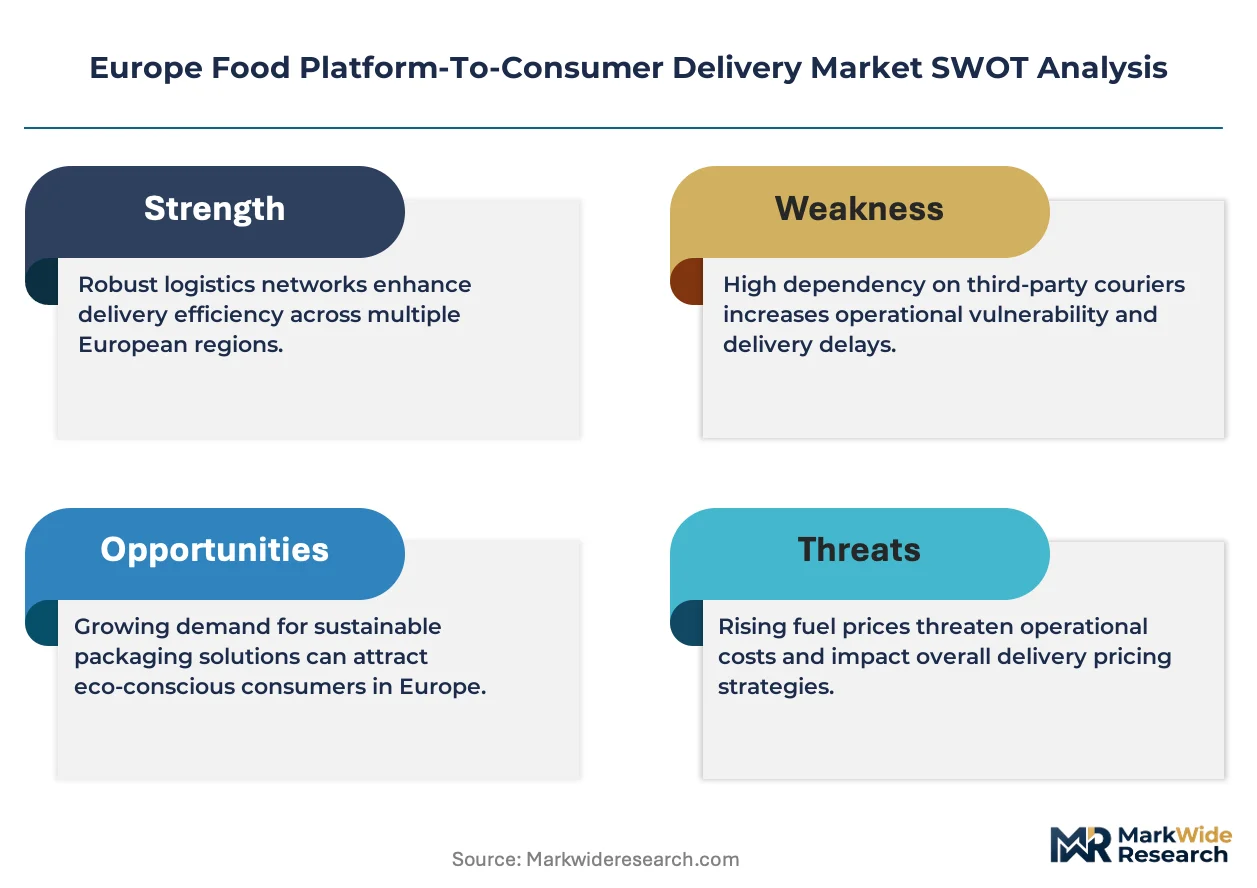
- Restaurant Delivery:Asset-light intermediation model connecting consumers with existing kitchen capacity through dispatch algorithms. Urban professionals in London and Paris generate the highest order frequency, though commission compression from restaurant partners constrains unit economics.
- Grocery Delivery:Requires substantial upfront investment in warehouse networks, temperature-controlled fleets, and real-time inventory systems. Basket sizes in Germany and the United Kingdom justify the capital outlay as subscription models deepen customer retention.
- Meal Kits:Centralized production facilities with precise portion control and recipe standardization. The segment demands significant logistics coordination for time-sensitive ingredient freshness.
- Specialty Food:Niche procurement relationships with artisanal producers and regional suppliers across France and Italy. Limited scale restricts platform coverage to premium metropolitan zones.
Restaurant Delivery absorbs the bulk of installed capacity; Grocery Delivery is expanding most quickly.
Customer Type:
Customer acquisition economics follow predictable patterns based on household structure and digital engagement intensity.
- Working Professionals:Time-constrained urban employees in metropolitan France and Germany prioritize speed over price, generating premium delivery fees during peak commute windows. GDPR-compliant algorithmic personalization drives reorder frequency for this cohort.
- Families:Multi-person households in the United Kingdom favor subscription bundling that reduces per-order cognitive load and captures weekly grocery-meal hybrid spend.
- Individual Consumers:Single-person households with sporadic ordering patterns and high price sensitivity. Platform switching costs remain minimal for this segment.
- Seniors:Emerging adoption curve requiring simplified interface design and telephone backup support. France's CNIL oversight of data processing creates compliance complexity for health-related recommendation algorithms targeting this demographic.
Working Professionals generate the highest revenue per user; Families are climbing the fastest in absolute customer additions.
Pricing Model:
Margin structures and customer lifetime value calculations diverge fundamentally based on how platforms monetize access versus transactions.
- Subscription:Flat-fee membership models prevalent in British and German markets reduce per-order friction and increase switching costs. The model demands substantial upfront marketing investment to achieve critical subscriber mass.
- Pay-Per-Delivery:Transactional pricing dominant in Southern Europe where digital payment penetration lags and consumer preference favors flexibility over commitment.
- Tiered Pricing:Three-tier structures separating premium, standard, and economy service levels based on delivery speed and restaurant exclusivity. EFSA cold chain mandates create compliance barriers that justify premium tier positioning.
- Free Delivery:Loss-leading acquisition tactic subsidized by restaurant commissions or advertising revenue. Sustained deployment requires substantial balance sheet capacity.
Subscription models command the steepest expansion trajectory; Pay-Per-Delivery retains the largest active user base in absolute terms.
Technology:
Platform differentiation increasingly depends on proprietary data infrastructure rather than restaurant network scale alone.
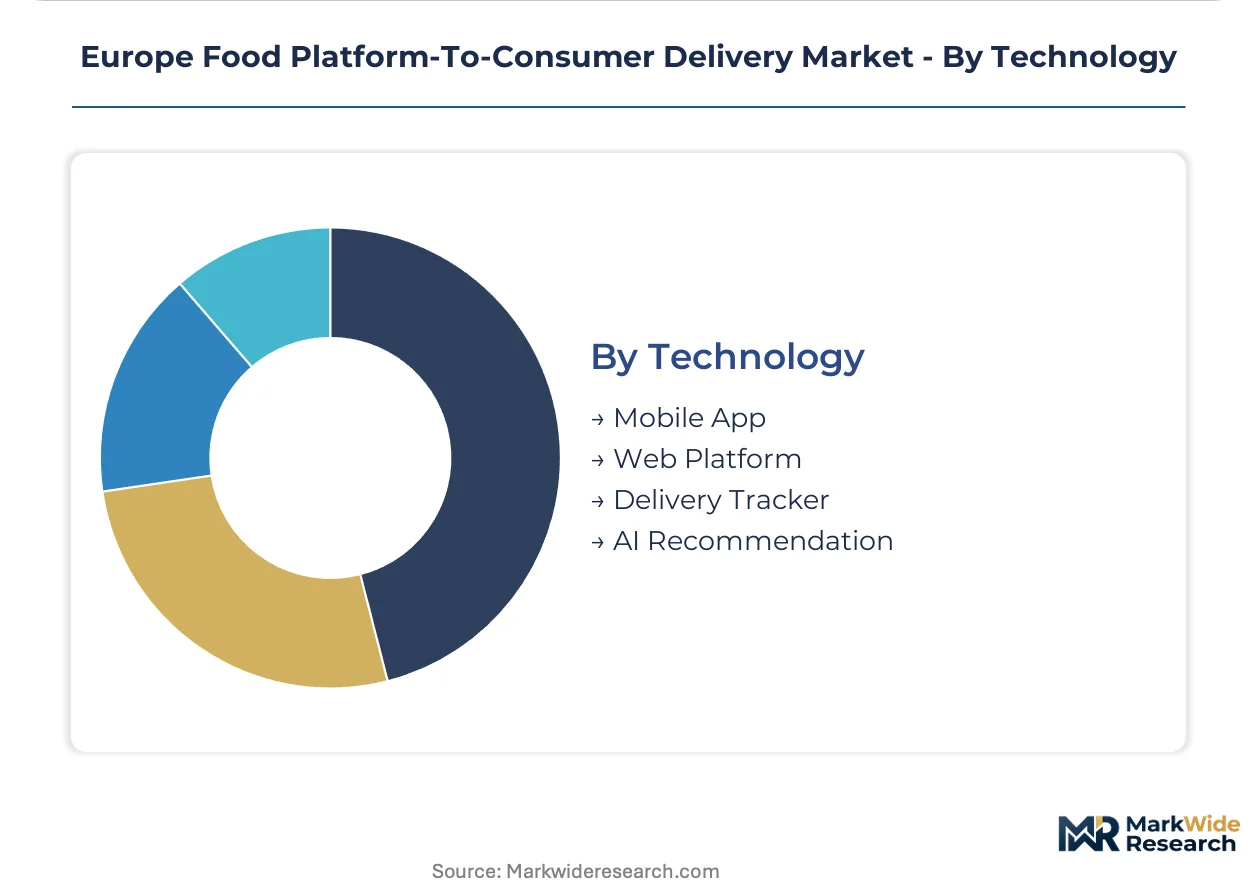
- AI Recommendation:Machine learning engines analyzing purchase history and temporal context to surface individualized suggestions. The EU AI Act imposes risk classification and documentation requirements on these automated decision systems.
- Mobile App:Primary interface for urban professionals in Amsterdam and Berlin, with biometric authentication and one-tap reordering reducing completion friction.
- Delivery Tracker:Real-time GPS visualization and predictive arrival windows. Integration with GDPR-mandated transparency in rider dispatch systems increases development overhead.
- Web Platform:Residual channel for corporate catering and desktop ordering scenarios. Maintenance requirements decline as mobile adoption accelerates.
Mobile App infrastructure supports the majority of transaction volume; AI Recommendation capabilities are gaining share fastest as competitive differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Greater Paris metropolis and London's Tech City zone concentrate platform development capital through R&D tax credits and digital infrastructure subsidies. These incentive corridors attract algorithm engineering talent and cold-chain logistics investment. Dense urban employment patterns sustain sub-30-minute fulfillment demand.
Germany
Working professionals in Berlin and Munich generate concentrated order frequency during peak commute windows. The KBA-influenced labor frameworks impose payroll tax burdens on hybrid employment models. The Rhine-Ruhr corridor anchors dark kitchen infrastructure expansion as platforms automate to offset courier reclassification costs.
United Kingdom
Families in Greater London favor subscription bundling that captures weekly grocery-meal hybrid spend. GDPR algorithmic governance mandates transparency in rider dispatch systems. Manchester and Birmingham witness rapid grocery partnership scaling as basket sizes justify warehouse network investments.
France
Urban professionals in Paris prioritize speed over price, generating premium delivery fees during lunch and dinner rushes. CNIL oversight of rider data processing tightens compliance requirements for automated decision systems. The Île-de-France region hosts platform AI development centers subject to EU AI Act risk classification rules.
Netherlands
Amsterdam's quick-commerce operators accelerate subscription bundling through grocery-meal hybrid models. EFSA cold chain mandates create compliance barriers for unqualified competitors. The Randstad conurbation supports dense courier networks that enable dynamic pricing during supply-constrained windows.
Poland
Rising digital payment adoption in Warsaw and Krakow creates viable entry conditions for scaled operators. REACH-aligned packaging standards shape product handling protocols for cross-border fulfillment. The Silesian metropolitan area attracts logistics investment as platforms seek underpenetrated density relative to Western Europe.
Europe Food Platform-To-Consumer Delivery Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation pressure intensifies as courier reclassification costs compress margin structures and accelerate automation investments. Three archetypes dominate: restaurant network aggregators, grocery expansion platforms, and technology-led optimization engines. M&A activity concentrates on dark kitchen assets and AI dispatch capabilities, while strategic partnerships with supermarket chains extend category coverage.
Within the aggregator archetype, Just Eat Takeaway.com and Delivery Hero occupy positions sustained by restaurant network density. Among technology-led players, Uber Eats exemplifies route optimization investment. Glovo represents the grocery expansion vector through its quick-commerce positioning. These three entities anchor the competitive structure as regulatory compliance costs favor capitalized operators with standardized pan-European technical architectures.
| Leading Market Players |
|---|
| Just Eat Takeaway.com |
| Deliveroo |
| Uber Eats |
| Delivery Hero |
| Foodhub |
| Glovo |
| DoorDash |
| Bolt Food |
| Lieferando |
| Others |
Supply & Pricing Matrix
REACH-aligned packaging standards gate qualified supply access and premium-tier pricing eligibility across European food delivery corridors. Platforms lacking certified cold-chain partners forfeit EFSA-compliant positioning and the margin premiums attached to verified handling protocols.
Pricing Analysis
Lead-time-driven pricing stratification separates sub-30-minute premium delivery from standard 45-60 minute economy tiers across metropolitan corridors. Subscription models in Germany and the United Kingdom reduce per-order friction while pay-per-delivery dominates Southern European price-sensitive segments. Pricing pressure stems from courier reclassification payroll burdens under KBA and CNIL frameworks. Families exhibit lowest price sensitivity through bundled grocery-meal commitments; individual consumers switch platforms for marginal discounts.
Supply Chain Analysis
Dual-sourcing mandates from quick-commerce operators and dark kitchen networks require platforms to qualify multiple courier fleet providers and warehouse partners. Supply concentration rests on Germany, the Netherlands, and Poland for cold-chain logistics infrastructure. Raw material dependencies span temperature-controlled packaging, lithium-ion battery cells for e-bike fleets, and cloud compute capacity for dispatch algorithms. Single-source vulnerability concentrates in algorithm engineering talent pools. Distribution runs through mobile application interfaces with API-linked restaurant POS systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's food delivery sector occupies a technology-transition phase where AI recommendation engines displace static menu browsing as the primary consumer interface. Legacy category-based navigation loses engagement share to predictive personalization systems.
For Market Incumbents: Deepen proprietary data infrastructure investments to defend against quick-commerce substitution threats. Acquire dark kitchen assets in the Rhine-Ruhr corridor to automate fulfillment and offset KBA-imposed courier reclassification costs. Prioritize GDPR-compliant explainable AI development to reduce regulatory friction in dispatch systems.
For New Entrants and Emerging Players: AI-first route optimization capabilities provide entry leverage into underpenetrated Eastern European markets. Target Poland and Romania where digital payment adoption creates viable platform density conditions absent incumbent saturation. Deploy grocery-meal hybrid subscription models to capture weekly household spend before pure-play meal platforms expand category coverage.
For Investors and Strategic Acquirers: Brussels courier reclassification rulings are the leading indicator that margin compression will accelerate automation capex cycles. Long-term viability favors capitalized operators with standardized pan-European technical architectures capable of absorbing EU AI Act compliance overhead. Monitor EFSA cold chain certification adoption rates as the signal for which platforms command premium positioning defensibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Dark Kitchen Network Expansion | Automated fulfillment in the Rhine-Ruhr corridor offsets KBA payroll tax burdens. |
| AI Dispatch Capability Acquisition | Route optimization talent scarcity creates defensive moats against undercapitalized competitors. |
| Grocery Partnership Scaling | Supermarket alliances in Manchester and Birmingham extend platform utility beyond prepared meals. |
| GDPR-Compliant Explainable AI Investment | Transparency in rider dispatch systems improves courier retention under CNIL oversight. |
| Eastern European Market Entry | Warsaw and Krakow digital payment adoption enables viable platform density expansion. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with platform operations executives, restaurant network managers, courier fleet coordinators, and grocery partnership leads combined with EFSA guideline documents, KBA labor framework interpretations, and EU Platform Work Directive implementation texts. Bottom-up order volume modeling and top-down digital payment penetration analysis provided triangulation across data sources.
Granularity-level modeling addressed service type, customer archetype, pricing model, and technology capability dimensions across the projection horizon. CAGRs derived from urban employment density trajectories, subscription adoption curves, and AI infrastructure investment cycles. Cold-chain compliance cost structures and courier reclassification expense profiles informed segment-specific margin projections.
Several conditions sit outside the modeled scope, including potential EU AI Act enforcement severity variations and national derogations from Platform Work Directive harmonization. Forecasts reflect documented assumptions about digital payment adoption velocity and dark kitchen automation timelines. Deviation in Brussels courier classification jurisprudence would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
United Kingdom Same Day Delivery Market
E-Commerce Solutions
Middle East and Africa E-Commerce Apparel Market
E-Commerce Solutions
Southeast Asia Cross-Border E-Commerce Market
E-Commerce Solutions
Europe E-Commerce Watch Market
E-Commerce Solutions
Austria E-Commerce Market
E-Commerce Solutions
Online Apparel Retailing Market
E-Commerce Solutions
Digital Gift Cards (Egift Cards) Market
E-Commerce Solutions
Brazil E-Commerce Market
E-Commerce Solutions
South Korea Ecommerce Logistics Market
E-Commerce Solutions
Hungary E-Commerce Market
E-Commerce Solutions
Global Shopping Cart Market
E-Commerce Solutions
Cross Border Ecommerce Market
E-Commerce Solutions
Greece E-Commerce Market
E-Commerce Solutions
India Alcohol E-Commerce Market
E-Commerce Solutions
Bedding E-Commerce Platform Market
E-Commerce Solutions
North America Automotive E-Commerce Market