
 Food E Commerce Market | 2026-2036
Food E Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Food E Commerce Market Intelligence
The EU's General Data Protection Regulation (GDPR) is rebalancing the cost-of-entry calculus for new platforms by mandating stringent consumer data privacy standards. Global giants like Amazon leverage extensive compliance infrastructures to navigate these complex international rules. Specialized services such as HelloFresh differentiate through curated subscription models that build direct customer trust. Meanwhile, delivery-focused platforms like Instacart compete by optimizing their vast last-mile logistics networks for speed and convenience.
Food e-commerce encompasses the digital transaction and subsequent physical delivery of food items, from raw ingredients to prepared meals. These operations depend on a technology stack including real-time inventory management, secure payment gateways, and route optimization algorithms. While the grocery product type constitutes the largest volume share, the subscription services segment represents the fastest-growing category. Among distribution channels, delivery apps and marketplaces are gaining ground over direct-to-consumer online grocery store models.
Regulatory oversight from bodies like the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) dictates stringent food handling, temperature control, and labeling requirements. In emerging markets, agencies such as India's FSSAI are establishing new standards for online food aggregators to ensure consumer safety and product traceability. Stakeholders must now decide how to invest in cold chain logistics and sustainable packaging to meet both regulatory pressures and evolving consumer expectations.
Market Dynamics
The convergence of AI-driven logistics platforms with a tightening global regulatory framework for food safety and data privacy is the central force shaping the market. This dual pressure compels platforms to innovate on both efficiency and compliance simultaneously.
Growth Catalysts
- AI-Powered Logistics:AI algorithms for route optimization and inventory management reduce delivery times and spoilage, improving efficiency for perishable goods.
- Business-to-Business Segment Expansion:Restaurants are increasingly sourcing ingredients through e-commerce platforms, bypassing traditional wholesale channels for greater efficiency and choice.
- Mobile Internet Penetration:High-speed mobile access in markets like India and Brazil expands the consumer base for app-based delivery and online grocery services.
Market Restraints
- Cold Chain Logistics Costs:High capital expenditure for refrigerated warehousing and temperature-controlled transport creates a significant financial barrier for new entrants.
- Fragmented International Regulations:Divergent rules like the EU's GDPR and India's FSSAI standards increase compliance costs and operational complexity for platforms.
- Last-Mile Delivery Complexity:Reliable delivery in congested urban environments is a persistent logistical challenge that impacts profitability and customer retention.
Strategic Opportunities
- Subscription Model Specialization:Curated subscription boxes for niche diets, like plant-based or gluten-free, build direct customer relationships and recurring revenue.
- Rural and Tier-2 City Expansion:Extending services beyond major urban centers in countries like Brazil presents a growth frontier, requiring adapted logistics models.
- Blockchain for Traceability:Integrating blockchain can enhance food safety and meet traceability demands from regulators like the EFSA and FDA.
Industry Challenges
- Sustainable Packaging Transition:Shifting to environmentally friendly packaging materials at scale presents cost and supply chain challenges while meeting consumer and regulatory expectations.
- Food Handling Standardization:Ensuring consistent adherence to temperature control and handling protocols, as mandated by the FDA and EFSA, across a distributed network of gig workers is a major operational hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food E Commerce Market |
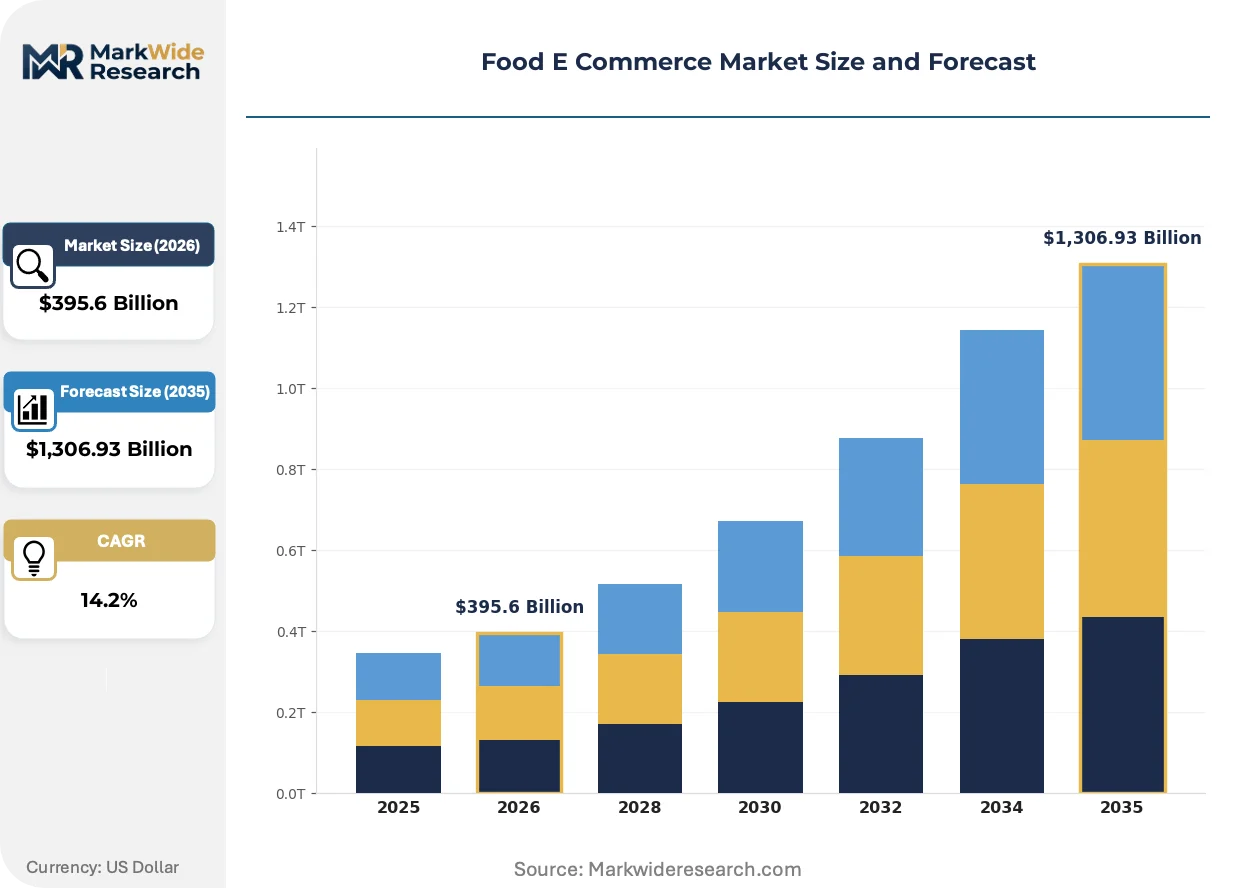
| Market Size in 2026 | $395.6 Billion |
| Market Size in 2035 | $1,306.93 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grocery, Snacks, Beverages, Bakery Customer Type: Individuals, Families, Businesses, Restaurants Distribution Channel: Online Grocery Stores, Delivery Apps, Marketplaces, Subscription Services Order Size: Single Items, Small Baskets, Bulk Orders, Wholesale |
| Companies Covered | Walmart, Amazon, Kroger, Instacart, DoorDash, Target, Uber Eats, HelloFresh, Sysco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food E Commerce Market Strategic Shifts & Innovations
A fundamental shift toward hyper-personalization, enabled by data analytics, is occurring alongside the industrialization of last-mile logistics. This dynamic creates new competitive arenas where both curated experiences and operational scale define market leadership.
Artificial intelligence in logistics management provides predictive demand forecasting and dynamic route optimization. Large-scale delivery platforms and grocery marketplaces are rapidly adopting these systems to improve unit economics. This technological advantage is consolidating market share around players who can afford the significant upfront investment in data science infrastructure.
The European Union's General Data Protection Regulation (GDPR) mandates strict consumer data privacy and consent protocols for all platforms operating within the region. This regulation elevates the cost and complexity of compliance, creating a higher barrier to entry. Consequently, new and smaller food e-commerce ventures face disadvantages against established giants with extensive legal and compliance infrastructures.
Consumer purchasing behavior is moving from transactional, on-demand orders toward relationship-based subscription services. This trend disrupts the marketplace aggregator model by fostering direct brand loyalty and predictable revenue streams for specialized providers. The shift is most pronounced in the meal-kit segment and for curated groceries in North American and European urban markets.
Food E Commerce Market Segmentation
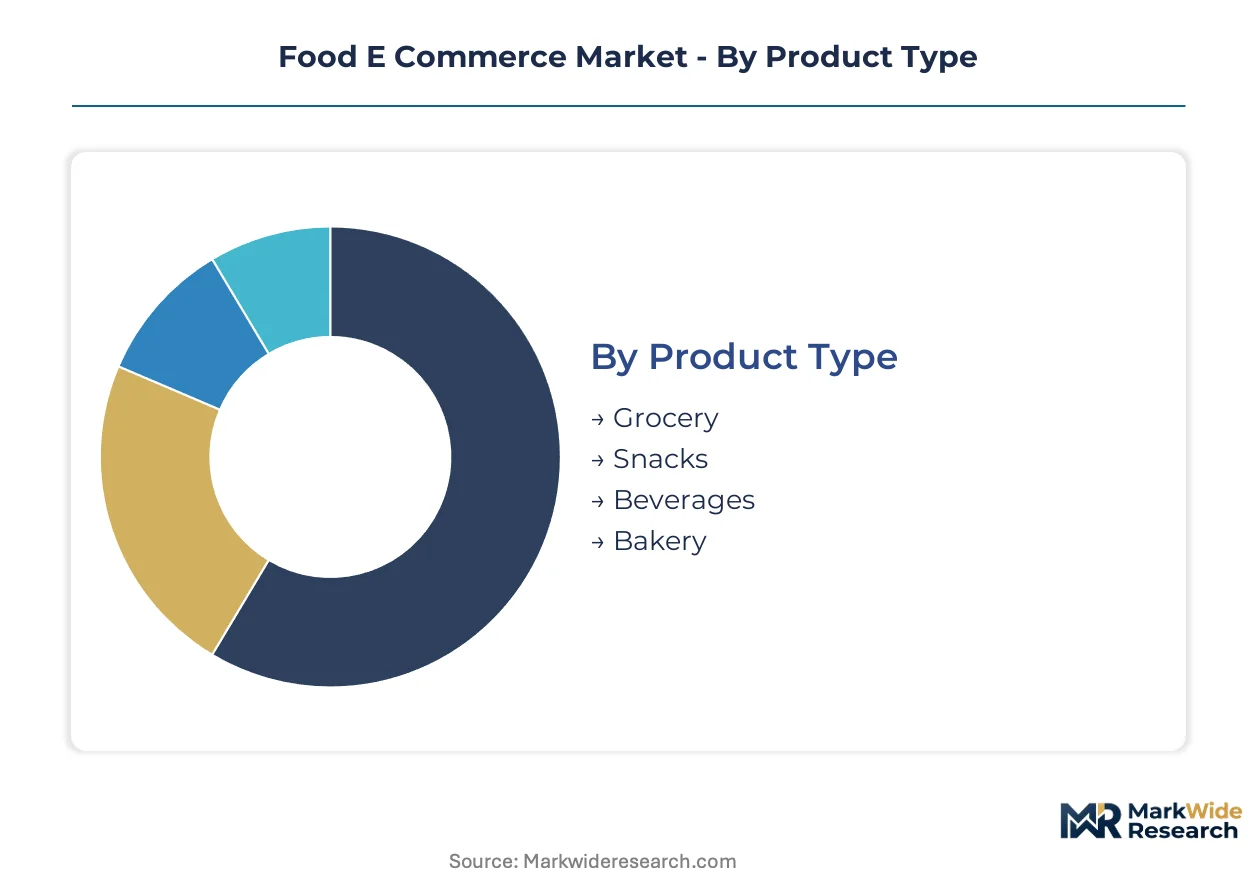
The food e-commerce market's segmentation provides a granular view of how diverse offerings and operational models cater to varied consumer and business demands. Understanding these distinctions helps platforms strategically allocate resources and refine service delivery. Each segment reflects unique purchasing behaviors and logistical requirements within the digital food supply chain.
Product Type:
The food e-commerce market's product type segmentation reveals how consumer preferences are upgrading their digital grocery baskets, moving beyond basic staples to specialized items.
- Grocery:This segment includes a broad range of everyday essentials, fresh produce, dairy, and pantry items, forming the foundational demand for online food retail. Demand concentrates in major urban centers like Mumbai and São Paulo, driven by convenience and mobile internet penetration.
- Snacks:This category encompasses packaged foods, confectionery, and savory items, often purchased for immediate consumption or quick replenishment. Consumer demand for snacks is strong in markets such as India and Brazil, reflecting a preference for convenient, ready-to-eat options.
- Beverages:This segment covers non-alcoholic drinks, including juices, soft drinks, and bottled water, typically ordered alongside other food items.
- Bakery:This segment includes fresh bread, pastries, cakes, and other baked goods, often requiring specialized handling and timely delivery.
Grocery sits at the top of the volume ranking, with Snacks climbing the fastest.
Customer Type:
Customer type segmentation highlights how different consumer groups drive specific service demands and platform innovations within the food e-commerce ecosystem.
- Individuals:This segment comprises single consumers or small households purchasing food for personal consumption, prioritizing convenience and diverse product selection. Demand for individual orders is widespread across global cities, reflecting busy urban lifestyles.
- Restaurants:This B2B segment includes eateries sourcing ingredients, prepared foods, and supplies directly from e-commerce platforms to streamline their procurement. The expansion of this segment is particularly notable in countries like the United States and Germany, where digital sourcing enhances operational efficiency.
- Families:This segment involves households with multiple members, typically placing larger orders that include a variety of groceries and meal solutions.
- Businesses:This category covers corporate clients, catering services, and other organizations purchasing food for employees or specific events.
Individuals represent a foundational customer base, while the Restaurants segment demonstrates significant B2B expansion.
Distribution Channel:
The distribution channel segmentation outlines the evolving operational models platforms deploy to reach consumers effectively, influencing market reach and service differentiation.
- Delivery Apps:These platforms facilitate on-demand delivery of prepared meals and groceries from various vendors, leveraging extensive last-mile logistics networks. Global demand for delivery apps is concentrated in densely populated urban areas, including London and New York, due to their speed and convenience.
- Subscription Services:This segment offers curated meal kits, specialized groceries, or regular replenishment of staples on a recurring basis, fostering direct customer relationships. Growth in subscription services is prominent in North American and European markets, catering to niche diets and convenience.
- Online Grocery Stores:These are dedicated digital storefronts operated by traditional supermarkets or pure-play e-grocers, offering a wide array of products for scheduled delivery.
- Marketplaces:These platforms aggregate multiple food vendors, allowing consumers to compare products and prices from various sellers within a single interface.
Delivery Apps and Marketplaces are consolidating consumer interaction, with Subscription Services showing rapid expansion.
Order Size:
Order size segmentation reflects how varied purchasing patterns influence logistics and inventory strategies for food e-commerce providers.
- Small Baskets:This segment includes orders with a limited number of items, often for immediate needs or quick top-ups, common among individual consumers. Logistical optimization for small baskets is critical in congested urban environments like Tokyo and Paris.
- Wholesale:This category encompasses large-volume orders placed by businesses, such as restaurants or institutions, requiring bulk pricing and specialized delivery logistics. The B2B wholesale segment is expanding in markets like the United States and China, driven by restaurant e-procurement.
- Single Items:This segment involves the purchase of one or two specific products, typically driven by urgency or specific cravings.
- Bulk Orders:This segment represents larger-than-average consumer purchases, often for household stocking or special occasions, requiring efficient packaging and delivery.
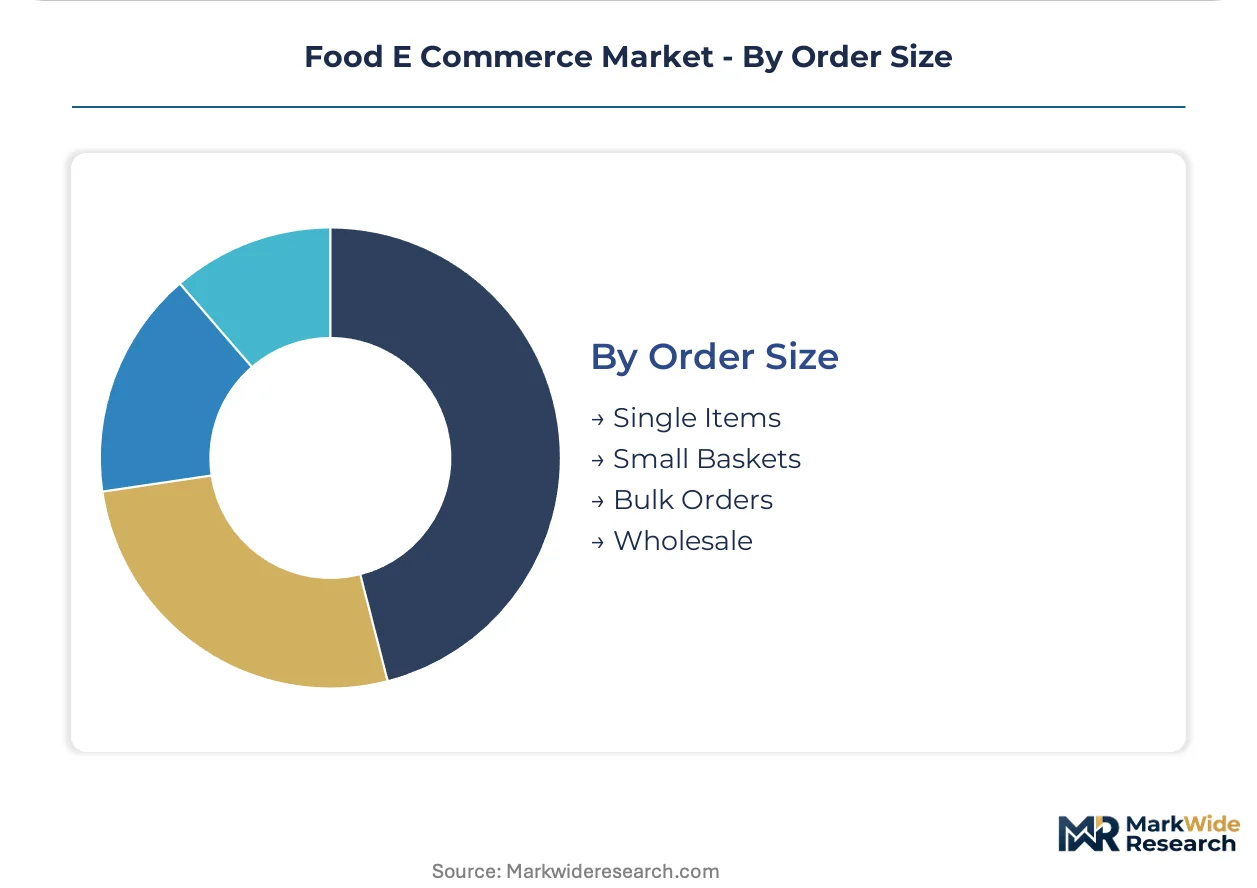
Small Baskets dominate individual consumer transactions, while Wholesale orders are increasingly important for business customers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A skilled technology workforce underpins the expansion of food e-commerce platforms across key global markets. This talent concentration drives innovation in logistics, payment systems, and customer engagement. Regulatory frameworks also play a crucial role in shaping market development and operational standards across diverse geographies.
India
Demand for app-based delivery and online grocery services is high, driven by extensive mobile internet penetration. The FSSAI establishes new standards for online food aggregators, ensuring consumer safety and product traceability. Major urban centers like Mumbai and Delhi-NCR exhibit concentrated demand for convenient digital food solutions.
Brazil
Mobile internet penetration and a growing middle class fuel the expansion of food e-commerce, particularly in metropolitan areas. National food safety regulations, enforced by agencies like ANVISA, dictate stringent handling and labeling requirements for online food sales. São Paulo and Rio de Janeiro represent key hubs for last-mile logistics and platform growth.
United States
The business-to-business segment demonstrates significant expansion, with restaurants increasingly sourcing ingredients online for operational efficiency. The US Food and Drug Administration (FDA) mandates rigorous food handling and labeling protocols for all e-commerce food providers. Major cities such as New York and Los Angeles drive substantial demand for both individual and B2B food deliveries.
Germany
B2B e-procurement by restaurants contributes to substantial market growth, alongside a rising consumer preference for curated subscription models. European Food Safety Authority (EFSA) guidelines influence food safety standards and traceability demands across the German market. Berlin and Munich are key centers for technology adoption and logistics innovation in food e-commerce.
United Kingdom
Delivery apps and online grocery stores are gaining considerable ground, capitalizing on dense urban populations and convenience-seeking consumers. The General Data Protection Regulation (GDPR) sets stringent consumer data privacy standards for all platforms operating within the region. London serves as a primary hub for delivery app concentration and competitive last-mile logistics optimization.
Food E Commerce Market Key Industry Players
The competitive structure tilts toward a tiered landscape, balancing global technology giants with specialized local innovators. This market features a mix of broad-spectrum e-commerce platforms and niche service providers. Strategic archetypes include large-scale aggregators, curated subscription services, and dedicated last-mile logistics operators. Dominant competitive moves involve significant investment in technology infrastructure and strategic partnerships to expand geographic reach.
Global e-commerce giants like Amazon exemplify market leadership through extensive compliance infrastructures and broad service offerings. Instacart occupies a strong position within the last-mile delivery segment, optimizing vast logistics networks for speed and convenience. HelloFresh represents the specialized subscription model, building direct customer relationships through curated meal kits and personalized offerings.
| Leading Market Players |
|---|
| Walmart |
| Amazon |
| Kroger |
| Instacart |
| DoorDash |
| Target |
| Uber Eats |
| HelloFresh |
| Sysco |
| Others |
Cost & Logistics Intelligence
Vertical integration into cold chain logistics anchors platform supply positions, directly influencing service reliability and pricing power in the food e-commerce market. This strategic choice dictates operational costs and speed, crucial for perishable goods delivery.
Pricing Analysis
The bundled-versus-unbundled service split significantly influences pricing strategies in food e-commerce. Subscription models, offering curated meal kits from HelloFresh, utilize value-based pricing, differentiating through convenience and personalization for consumers. Transactional per-unit pricing dominates delivery apps like Instacart, where geographic delivery costs and speed are key differentiators. Pricing softness stems from intense competition among delivery platforms in urban centers, making individual consumers highly price-sensitive to delivery fees and product markups.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke patterns characterize the food e-commerce supply chain, concentrating perishable goods near major urban hubs like Mumbai and London. Supply relies heavily on fresh produce from local farms and packaged goods from global manufacturers. A key structural risk is cold chain logistics chokepoints, particularly for temperature-sensitive items mandated by the FDA and EFSA. Distribution runs through a hybrid model combining dedicated fleet operations and gig-economy last-mile delivery networks, impacting cost structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The food e-commerce market operates as a regulatory compounder, with stringent standards like the EU's GDPR driving demand for robust compliance infrastructures. This regulatory environment accelerates investment in secure data handling and operational transparency.
For Market Incumbents:To counter emerging specialized niche players, large incumbents must deepen vertical integration into supply chain control, particularly for cold chain logistics and sustainable packaging materials. Investing in AI-powered predictive demand forecasting and route optimization platforms strengthens operational efficiency, a key lever against margin pressure. Expanding B2B offerings to restaurants in underserved tier-2 cities provides a defensive growth strategy.
For New Entrants and Emerging Players:AI-driven hyper-personalization represents a potent technology-first wedge for new entrants targeting curated subscription services. Focus on niche diets, such as plant-based or gluten-free meal kits, allows market penetration in North American and European urban markets. A direct-to-consumer online grocery store model emphasizing product traceability via blockchain offers a distinct go-to-market angle.
For Investors and Strategic Acquirers:Roll-up economics work for specialized logistics providers because fragmented last-mile delivery networks present consolidation opportunities. Long-term viability favors platforms capable of navigating diverse international regulations like India's FSSAI and the US FDA. Acquiring mid-sized regional delivery apps with strong local market penetration represents a suitable target archetype. The signal to watch is the sustained profitability of cold chain logistics operations across multiple geographies.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in AI-Powered Logistics Platforms | Improves delivery efficiency and reduces spoilage for perishable goods in congested urban centers. |
| Expand B2B Restaurant Sourcing | Captures growing demand from restaurants in the United States and Germany, bypassing traditional wholesale. |
| Develop Niche Subscription Services | Builds direct customer trust and recurring revenue streams for specialized diets in European markets. |
| Implement Blockchain for Traceability | Enhances food safety compliance with regulators like the EFSA and FDA across global supply chains. |
| Optimize Cold Chain Infrastructure | Reduces operational costs and ensures product integrity for temperature-sensitive items in Brazil and India. |
Research Approach
Coverage spans India, Brazil, the United States, Germany, and the United Kingdom, with primary inputs from each region. The analysis combines in-depth interviews with industry stakeholders, including e-commerce platform executives, logistics managers, food safety regulators, and restaurant procurement leads. Secondary validation draws from national food safety authority reports (FSSAI, FDA, EFSA) and mobile internet penetration statistics. This approach leverages bottom-up data collection triangulated with top-down market sizing.
Rate-of-change decomposition underpins the analytical framework, projecting market evolution across the analysis window. Segmentation dimensions modeled include product type (grocery, snacks), customer type (individuals, restaurants), distribution channel (delivery apps, subscription services), and regional regulatory frameworks. Compound Annual Growth Rates were derived from historical data trends and projected future adoption rates. Mobile internet penetration in emerging markets serves as a key forecast input.
The model holds under current regulatory stability and sustained mobile internet penetration; deviation in global economic downturns or major supply chain disruptions would shift projections. Forecasts reflect assumptions regarding technological advancements in AI logistics and evolving consumer purchasing behaviors. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Quiet Commerce Market
E-Commerce Solutions
Italy E-Commerce Market
E-Commerce Solutions
Switzerland E-Commerce Market
E-Commerce Solutions
Quick Commerce Market
E-Commerce Solutions
Lithuania E-Commerce Market
E-Commerce Solutions
Nigeria Alcohol E-Commerce Market
E-Commerce Solutions
India E-Commerce Warehousing Market
E-Commerce Solutions
UAE Ecommerce Market
E-Commerce Solutions
Middle East and Africa E-Commerce Apparel Market
E-Commerce Solutions
Alcohol E-Commerce Market
E-Commerce Solutions
Asia Pacific E-Commerce Market
E-Commerce Solutions
Hong Kong E-Commerce Market
E-Commerce Solutions
E-Commerce Buy Now Pay Later Market
E-Commerce Solutions
Europe E-Commerce Apparel Market
E-Commerce Solutions
Bulgaria E-Commerce Market
E-Commerce Solutions
North America B2B E-Commerce Market