
 Online Apparel Retailing Market | 2026-2036
Online Apparel Retailing Market Size, Share, and Industry Trends Forecast 2026-2036
Online Apparel Retailing Market Outlook
Digital merchandising talent is reorganizing how online apparel retailers build conversion funnels, with data scientists and AI-trained stylists now central to inventory curation. Amazon leverages its logistics infrastructure to sustain next-day delivery expectations across North America. Shein anchors its competitive edge through real-time demand sensing that compresses design-to-ship cycles. Zalando dominates European market share by operating localized fulfillment networks with country-specific return policies.
Online apparel retailing encompasses the digital sale of wearable garments through internet-based platforms, where product presentation relies on algorithmic recommendation engines, virtual try-on overlays, and dynamic sizing databases to reduce return rates. The primary commercial purpose centers on collapsing geographic distance between inventory pools and dispersed consumer bases while capturing behavioral data for predictive restocking. Activewear within product type segments records outsized momentum as hybrid work norms normalize athleisure across weekday wardrobes. Social media as a distribution channel extends beyond discovery into embedded checkout, with TikTok Shop and Instagram Shopping converting scroll behavior directly to transactions. Brand websites retain margin concentration for luxury price tier players who restrict marketplace presence to preserve exclusivity controls.
The EU Digital Services Act and GDPR jointly constrain how European platforms deploy behavioral targeting for apparel ads, forcing reliance on first-party purchase histories rather than third-party tracking pixels. The FTC in the United States scrutinizes greenwashing claims in sustainable fashion marketing, elevating compliance costs for brands promoting recycled materials. China's SAMR enforces pricing transparency rules during live-stream promotional events, limiting flash-sale tactics that previously drove impulse apparel volume. Stakeholders must weigh regulatory fragmentation against the efficiency gains of unified global platform architectures.
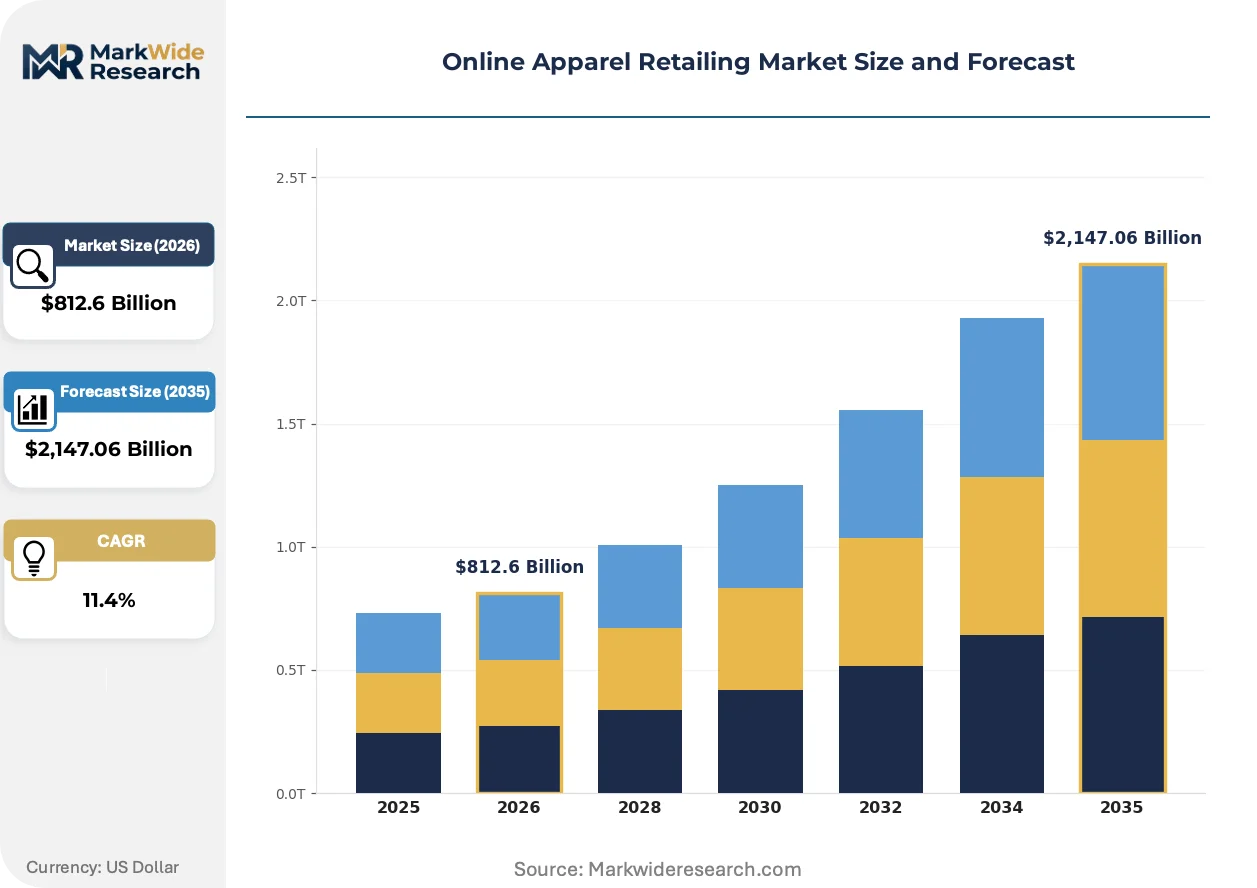
Market Dynamics
Live-stream commerce infrastructure is compressing discovery-to-purchase cycles from weeks to minutes, forcing legacy catalog-based retailers to rebuild their entire merchandising stack around real-time inventory exposure and influencer-hosted product demonstrations.
Growth Catalysts
- EU Digital Services Act:Platform accountability mandates for product listings are elevating trust signals that reduce cart abandonment rates in cross-border transactions.
- Mobile-first purchasing behaviors:Young adult professionals in urban centers now complete majority of transactions through native apps with embedded payment wallets.
- Hybrid work normalization:Athleisure demand has permanently expanded weekday wardrobe categories previously confined to weekend use.
Market Restraints
- Return logistics cost concentration:Apparel's 25-40% return rates drain margin pools, with reverse shipping and inspection labor consuming fulfillment budgets.
- GDPR behavioral targeting constraints:European platforms face elevated customer acquisition costs as third-party tracking pixels lose viability.
- Cotton price volatility:Input cost swings for natural fibers compress gross margins during promotional pricing cycles.
Strategic Opportunities
- Virtual try-on overlays:AR sizing tools reduce fit-related returns by letting shoppers visualize garments on body-scanned avatars.
- TikTok Shop integration:Social commerce embeds checkout directly into entertainment feeds, collapsing the traditional funnel.
- India's tier-two city expansion:Underpenetrated urban clusters beyond Mumbai and Delhi offer first-mover positioning for localized fulfillment.
Industry Challenges
- AI stylist talent scarcity:Merchandising teams lack data scientists capable of training recommendation engines on sparse purchase histories.
- Greenwashing compliance exposure:FTC scrutiny of recycled material claims demands documentation systems many brands have not built.
- Legacy warehouse management integration:Real-time demand sensing requires API connectivity that older fulfillment software cannot support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Apparel Retailing Market |
| Market Size in 2026 | $812.6 Billion |
| Market Size in 2035 | $2,147.06 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: T-Shirts, Dresses, Jeans, Activewear Customer Type: Men, Women, Children, Unisex Distribution Channel: Direct-to-Consumer, Marketplaces, Brand Websites, Social Media Price Tier: Luxury, Mid-Range, Budget, Discount |
| Companies Covered | Amazon, Alibaba Group, Walmart, JD.com, Shein, Zalando, ASOS, Rakuten, Inditex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Apparel Retailing Market Strategic Shifts
Algorithmic inventory curation is displacing human buyer intuition across digital storefronts, with machine learning models now dictating which SKUs receive homepage placement based on micro-segment conversion probability rather than seasonal planning calendars.
Generative AI for virtual styling is decomposing the traditional personal shopper role into scalable software layers. Mid-market retailers in Germany and France are deploying these tools to offer curated outfit recommendations without human labor costs. The technology is compressing the competitive gap between mass-market platforms and boutique styling services.
China's SAMR pricing transparency enforcement during live-stream events is eliminating flash-sale psychology that previously drove impulse volume. Promotional events must now display historical pricing data, reducing the urgency that anchored Shein's demand-sensing model. Domestic platforms are responding by shifting toward membership-based loyalty programs with guaranteed discounts.
Scroll-to-purchase behavior is replacing search-intent shopping as the dominant discovery mode. TikTok Shop and Instagram Shopping convert entertainment engagement directly into transactions without platform switching. This pattern concentrates in China's tier-one cities where live-stream hosts have built parasocial trust relationships with repeat viewers.
Online Apparel Retailing Market Segmentation
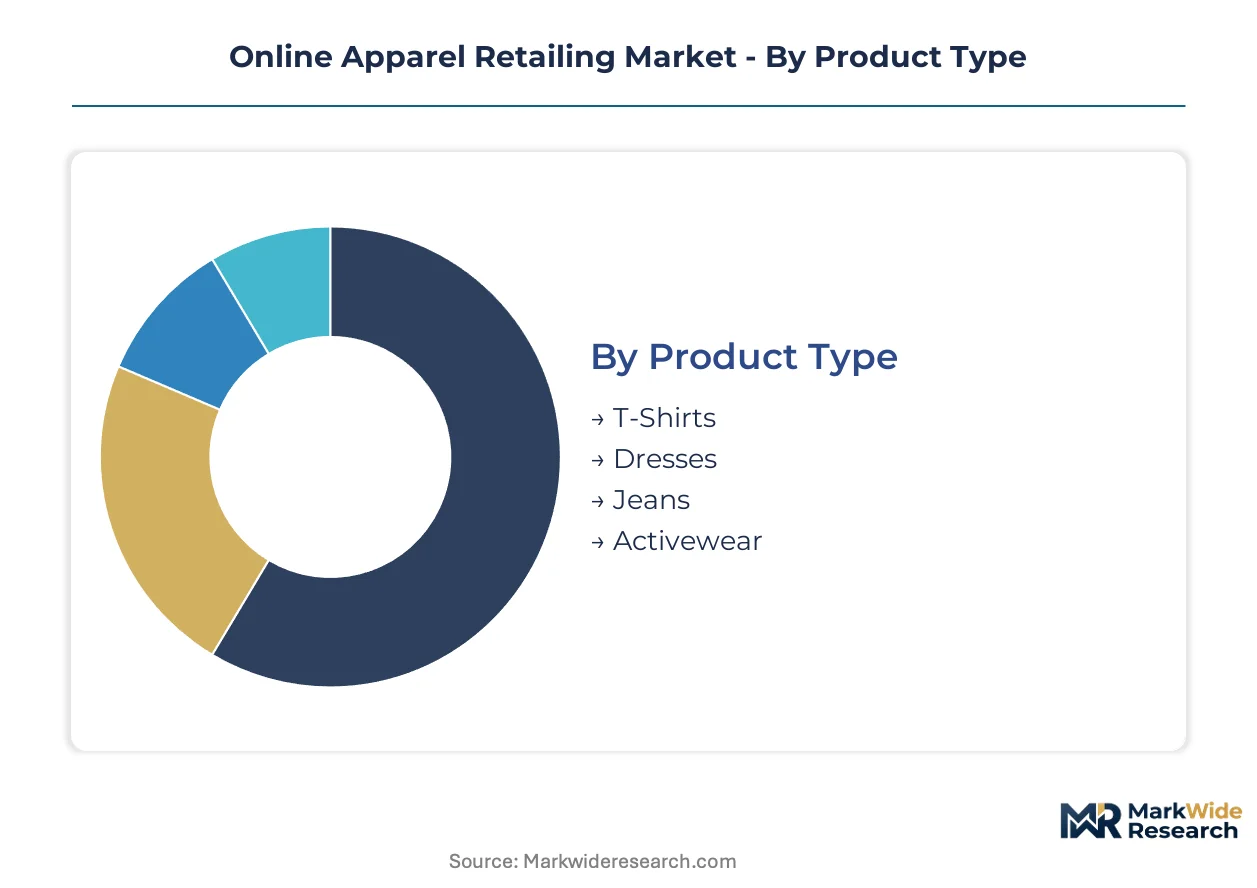
Segmentation in online apparel retailing determines where capital deploys for maximum conversion efficiency. Distinct margin profiles across product types, customer cohorts, and distribution channels force platform operators to prioritize inventory mix and marketing spend allocation.
Product Type:
Margin pools concentrate in athleisure and denim categories where repeat purchase rates offset higher customer acquisition costs.
- Activewear:Technical fabrics with moisture-wicking and compression properties dominate this segment. Demand clusters in China's tier-one cities where live-stream hosts demonstrate stretch and breathability in real time; hybrid work normalization sustains weekday wear occasions that previously required formal attire.
- Jeans:Denim construction varies by weight and elastane blend percentage, with raw selvedge commanding premium positioning. European consumers drive fit innovation through virtual try-on adoption that reduces size-related returns.
- T-Shirts:Cotton-jersey basics with varying GSM weights serve as high-frequency replenishment items.
- Dresses:Seasonal silhouette variation requires rapid design-to-ship cycles that strain legacy supply chains.
Activewear holds installed capacity. Jeans is rotating up the share rankings.
Customer Type:
Volume concentration tilts toward women, though men demonstrate higher basket values per transaction.
- Women:This cohort generates the majority of browsing sessions and purchase frequency across all distribution channels. Urban professionals in India and Southeast Asia drive mobile-first adoption with embedded wallet payments.
- Men:Lower browsing intensity converts to higher average order values when purchase intent forms. Athleisure and denim categories capture disproportionate share here.
- Children:Size turnover velocity creates replenishment cycles every four to six months.
- Unisex:Gender-neutral styling expands addressable audience per SKU.
Women maintains volume leadership. Men is climbing the fastest in value contribution.
Distribution Channel:
Control over customer data and margin retention varies sharply by channel architecture.
- Social Media:Embedded checkout within TikTok Shop and Instagram Shopping collapses discovery-to-purchase latency. Scroll-to-purchase behavior in China's tier-one cities converts entertainment engagement without platform switching.
- Brand Websites:Luxury price tier operators restrict marketplace presence to preserve exclusivity and full-margin capture. First-party data enables predictive restocking algorithms.
- Direct-to-Consumer:Subscription models and membership programs build recurring revenue pools.
- Marketplaces:Amazon and regional platforms aggregate demand but compress margins through fee structures and price transparency.
Brand websites hold installed capacity. Social media is gaining share fastest.
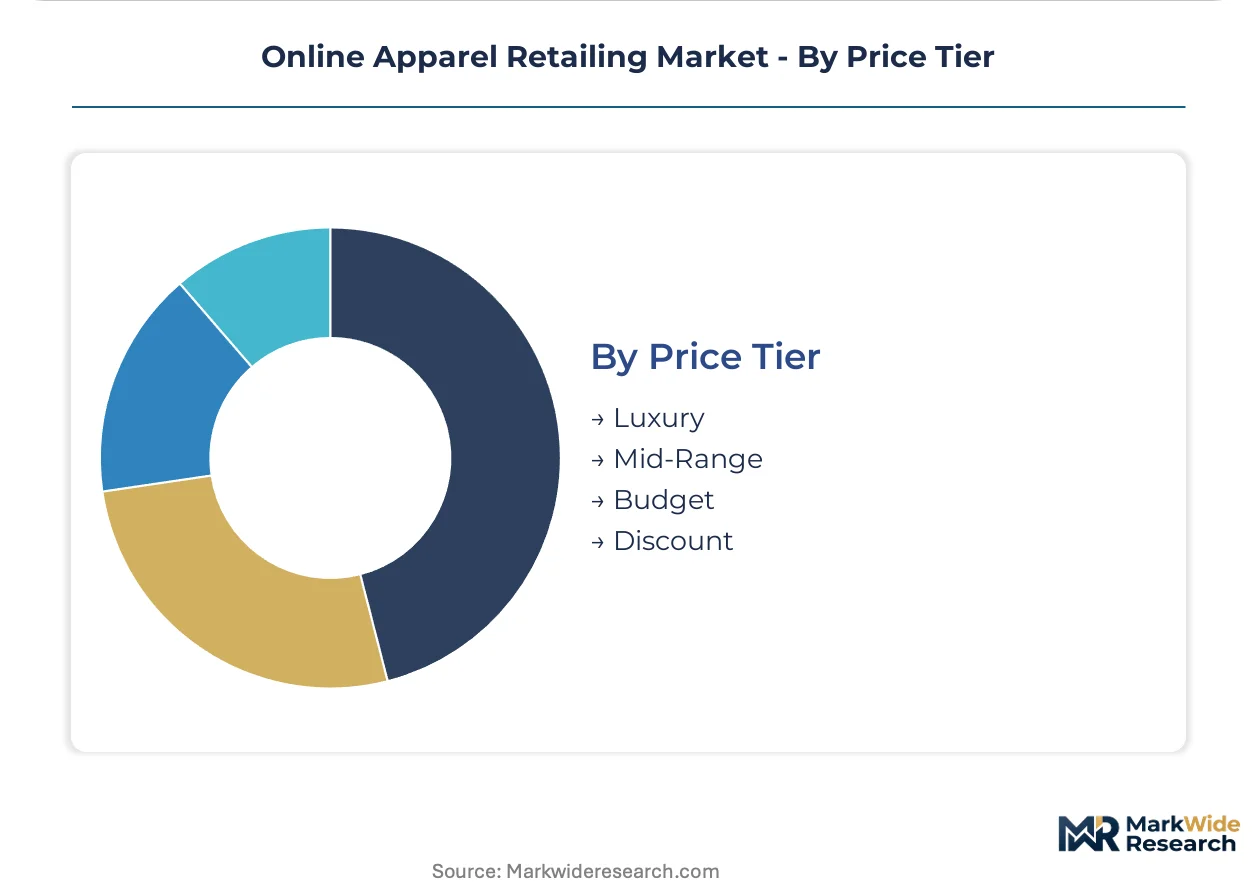
Price Tier:
Pricing stratification determines fulfillment infrastructure requirements and return rate exposure.
- Luxury:Authenticity verification and white-glove delivery services justify premium positioning. GDPR constraints on behavioral targeting in Europe force reliance on first-party purchase histories for customer acquisition.
- Mid-Range:This tier balances quality perception with accessibility, capturing urban professional cohorts in Germany and France.
- Budget:Volume-driven models depend on real-time demand sensing to minimize inventory risk.
- Discount:Flash-sale psychology faces regulatory headwinds as China's SAMR enforces historical pricing transparency.
Mid-Range holds installed capacity. Luxury is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in online apparel retailing concentrates in China's tier-one cities while margin compression defines European operations under GDPR constraints. The United States sustains premium fulfillment economics through logistics density. India's emerging urban clusters present first-mover positioning for localized infrastructure.
China
Live-stream commerce in Shanghai and Beijing converts entertainment engagement into transactions through parasocial host-viewer relationships. SAMR enforces pricing transparency rules that eliminate flash-sale psychology from promotional events. The Yangtze River Delta anchors real-time demand sensing infrastructure that compresses design-to-ship cycles for fast-fashion platforms.
United States
Next-day delivery expectations sustain customer loyalty across urban population centers with logistics network density. FTC scrutiny of greenwashing claims in sustainable fashion marketing elevates compliance documentation requirements. The Pacific Northwest and Northeast corridor concentrate fulfillment automation investments that reduce per-unit handling costs.
Germany
Mid-market urban professionals drive adoption of AI-powered virtual styling tools that reduce fit-related returns. GDPR constraints on behavioral targeting force reliance on first-party purchase histories for customer acquisition. Berlin and Munich anchor localized fulfillment networks with country-specific return policies that sustain Zalando's European market position.
India
Tier-two city expansion beyond Mumbai and Delhi creates underpenetrated demand clusters for mobile-first purchasing with embedded wallet payments. RBI oversight of digital payment infrastructure shapes checkout flow design for domestic platforms. Bangalore and Hyderabad concentrate technology talent for recommendation engine development serving price-sensitive apparel segments.
United Kingdom
Social commerce integration through TikTok Shop and Instagram Shopping collapses traditional discovery-to-purchase funnels for young adult professionals. The UK Information Commissioner's Office enforces GDPR-aligned consent mechanisms for personalized apparel advertising. London anchors luxury brand website operations that restrict marketplace presence to preserve exclusivity controls and full-margin capture.
Online Apparel Retailing Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the online apparel retailing ecosystem. The market structure fragments between platform aggregators with logistics infrastructure, fast-fashion specialists with demand-sensing capabilities, and luxury houses with exclusivity-controlled distribution. Three strategic archetypes dominate: vertically integrated logistics platforms, real-time inventory turnover specialists, and brand-direct premium operators. Competitive moves concentrate on fulfillment network expansion and social commerce integration partnerships.
Among logistics-anchored platforms, Amazon and JD.com occupy positions defined by infrastructure scale and delivery velocity rather than merchandising differentiation. Shein exemplifies the demand-sensing archetype with compressed supply chain cycles, while Zalando represents European market specialization through localized fulfillment architecture. Alibaba Group anchors the marketplace aggregation model across Asia-Pacific operations. These three company groupings illustrate how divergent capital deployment strategies—warehouse automation, supplier network integration, and regional compliance systems—create distinct competitive positions without direct feature parity.
| Leading Market Players |
|---|
| Amazon |
| Alibaba Group |
| Walmart |
| JD.com |
| Shein |
| Zalando |
| ASOS |
| Rakuten |
| Inditex |
| Others |
Value Chain & Pricing Dynamics
Cotton-to-polyester blend substitution in fast-fashion manufacturing simultaneously redraws sourcing geography toward Southeast Asian petrochemical hubs and compresses per-unit material costs for budget-tier operators. This input shift feeds directly into pricing elasticity calculations across European and North American markets where fiber content labeling influences consumer willingness-to-pay.
Pricing Analysis
Price spreads between Shanghai-sourced activewear and Milan-positioned luxury athleisure stretch across a four-to-one ratio, reflecting embedded logistics and brand premium stratification. Three-tier pricing structure across premium, standard, and economy levels dominates, with certification grade and after-sales service bundling as primary differentiation drivers. Cost compression in budget tiers intensifies because of SAMR-mandated pricing transparency eliminating flash-sale psychology. Price sensitivity concentrates among young adult professionals in China's tier-one cities, while luxury cohorts demonstrate inelastic demand.
Supply Chain Analysis
Suez Canal transit volatility exposes European replenishment schedules to 10-14 day disruption windows that compress margin pools during peak seasonal demand. Manufacturing concentrates in Bangladesh, Vietnam, and China, with cotton, elastane blends, and recycled polyester as core material dependencies. Single-source vulnerability in Chinese dyeing and finishing capacity creates concentration risk for color-responsive fast-fashion cycles. Distribution runs through regional fulfillment hubs with last-mile handoff to localized courier networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
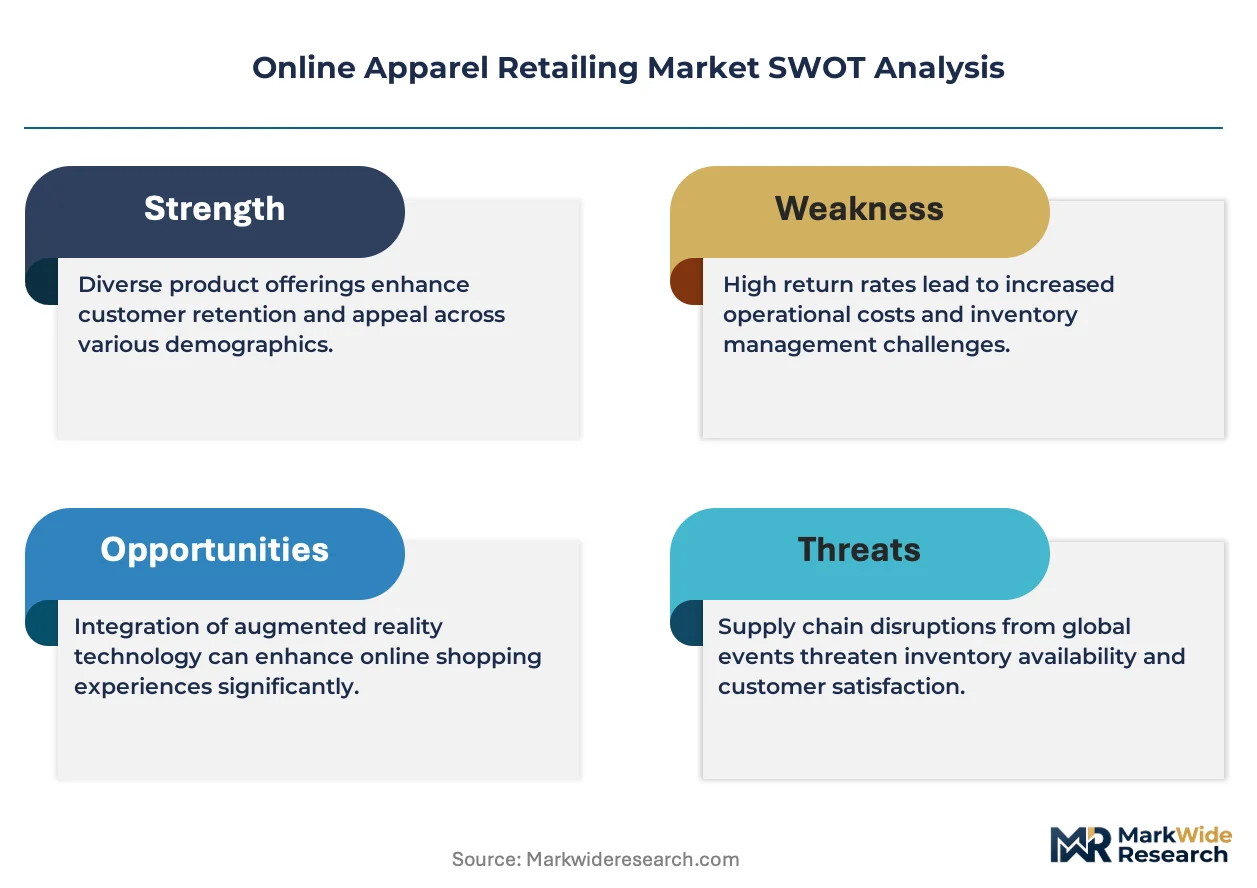
The market rewards players who control scarce capabilities in real-time demand sensing and AI-trained merchandising talent, with execution gaps widening between infrastructure-heavy incumbents and agile specialists.
For Market Incumbents: Compound data science capabilities by acquiring boutique AI styling firms and embedding recommendation engines directly into native apps. Vertical integration into last-mile fulfillment in India's tier-two cities defends against emerging local platforms. Channel control through exclusive brand website operations preserves margin concentration against marketplace fee compression. For New Entrants and Emerging Players: EU Digital Services Act compliance certification fast-track opens positioning for transparent cross-border platforms targeting European mid-market professionals. White-space concentrates in virtual try-on overlay deployment for denim and activewear categories where fit-related returns drain incumbent profitability. Direct-to-consumer subscription models with embedded styling algorithms offer differentiated go-to-market positioning. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fast-fashion platforms lacking live-stream commerce infrastructure. Long-term viability hinges on demand-sensing technology ownership rather than inventory scale. Acquisition targets with proprietary supplier networks in Vietnam and Bangladesh signal defensible positioning. Watch for inflection when regulatory enforcement of greenwashing claims forces documentation system investments that strain undercapitalized operators.| Strategic Initiative | Industry Significance |
|---|---|
| Live-Stream Commerce Infrastructure Buildout | Parasocial host-viewer relationships in Shanghai and Beijing compress discovery-to-purchase latency below traditional catalog cycles. |
| AI Styling Talent Acquisition | Machine learning engineers trained on sparse apparel purchase histories enable algorithmic inventory curation displacing human buyer intuition. |
| Regional Fulfillment Localization | Country-specific return policies in Germany and France sustain Zalando's European market position against pan-regional competitors. |
| Virtual Try-On Technology Deployment | AR sizing tools reduce 25-40% return rates that drain margin pools across denim and dress categories. |
| First-Party Data Architecture Investment | GDPR-compliant purchase history systems replace third-party tracking pixels for European customer acquisition. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with digital merchandising executives, fulfillment network managers, social commerce platform engineers, and sustainable sourcing directors. Secondary validation drew from customs trade records, EU Digital Services Act regulatory filings, SEC apparel retailer disclosures, and live-stream commerce transaction databases. Bottom-up SKU-level demand modeling triangulated against top-down macro consumption indicators.
Across the analysis window, projections incorporate product type segmentation by technical fabric properties, customer cohort purchasing frequency patterns, distribution channel data ownership structures, and price tier fulfillment infrastructure requirements. CAGRs were derived from regression analysis against mobile commerce penetration curves and hybrid work normalization indices. Forecast inputs include cotton price volatility scenarios and live-stream host supply elasticity assumptions.
Underlying assumptions cover sustained mobile wallet adoption in urban India, with deviation risk concentrated in regulatory enforcement intensity across EU member states. Forecasts reflect documented assumptions on generative AI styling tool adoption rates. Revision becomes warranted when SAMR pricing transparency enforcement crosses thresholds that fundamentally alter flash-sale promotional economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Online on-Demand Laundry Service Market
E-Commerce Solutions
Brazil E-Commerce Market
E-Commerce Solutions
Clothing E-Commerce Platform Market
E-Commerce Solutions
Pharma E-Commerce Market
E-Commerce Solutions
United Kingdom E-Commerce Logistics Market
E-Commerce Solutions
France E-Commerce Market
E-Commerce Solutions
Pharmaceutical E-Commerce Market
E-Commerce Solutions
United States E-Commerce Logistics Market
E-Commerce Solutions
Cross-Border B2C E-Commerce Market
E-Commerce Solutions
Sweden E-Commerce Market
E-Commerce Solutions
United States Same-Day Delivery Market
E-Commerce Solutions
United States E-Commerce Market
E-Commerce Solutions
Global Subscription E Commerce Market
E-Commerce Solutions
Serbia E-Commerce Market
E-Commerce Solutions
Nigeria E-Commerce Market
E-Commerce Solutions
Japan Cross Border E Commerce Market