
 Spain E-Commerce Logistics Market | 2026-2036
Spain E-Commerce Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Spain E-Commerce Logistics Market Insights
The last-mile delivery network in Spain is fragmenting as regional specialists challenge legacy parcel carriers. SEUR leverages its nationwide depot footprint to sustain next-day coverage across provincial capitals. Celeritas competes through specialized temperature-controlled capacity for pharmaceutical and fresh-food e-commerce. DHL anchors premium cross-border flows from its Madrid hub, connecting Iberian sellers to European Union destinations.
Spain e-commerce logistics encompasses the physical movement, storage, and information management of goods ordered through digital retail platforms, typically involving parcel sortation hubs operating at throughput rates exceeding thousands of items per hour with barcode-and-scanner tracking granularity. Its primary commercial purpose is collapsing order-to-delivery cycle times while minimizing cost per shipment for online merchants. Last-mile delivery occupies the largest value pool given urban density challenges and rising consumer expectations for evening and weekend windows. AI-powered logistics represents the fastest-expanding technology segment as route-optimization algorithms reduce fuel consumption and failed-delivery rates. Warehousing is maturing toward automated goods-to-person systems, though margin compression limits adoption among mid-tier operators.
Spain's Directorate General of Traffic enforces emissions standards that accelerate electric van adoption among delivery fleets, while the Ministry of Transport's sustainable mobility frameworks impose carbon-reporting obligations on logistics providers serving urban centers. The Spanish Data Protection Agency applies GDPR-aligned rules to consumer address databases and delivery tracking records, raising compliance costs for technology investments. Stakeholders must monitor how Madrid and Barcelona municipal low-emission zones expand delivery window restrictions and reshape fleet composition requirements.
Market Dynamics
Spain's e-commerce logistics sector faces a structural squeeze between Madrid and Barcelona municipal low-emission zones and consumer expectations for same-day fulfillment. Fleet electrification mandates from the Ministry of Transport force capital reallocation while urban density intensifies last-mile cost pressures.
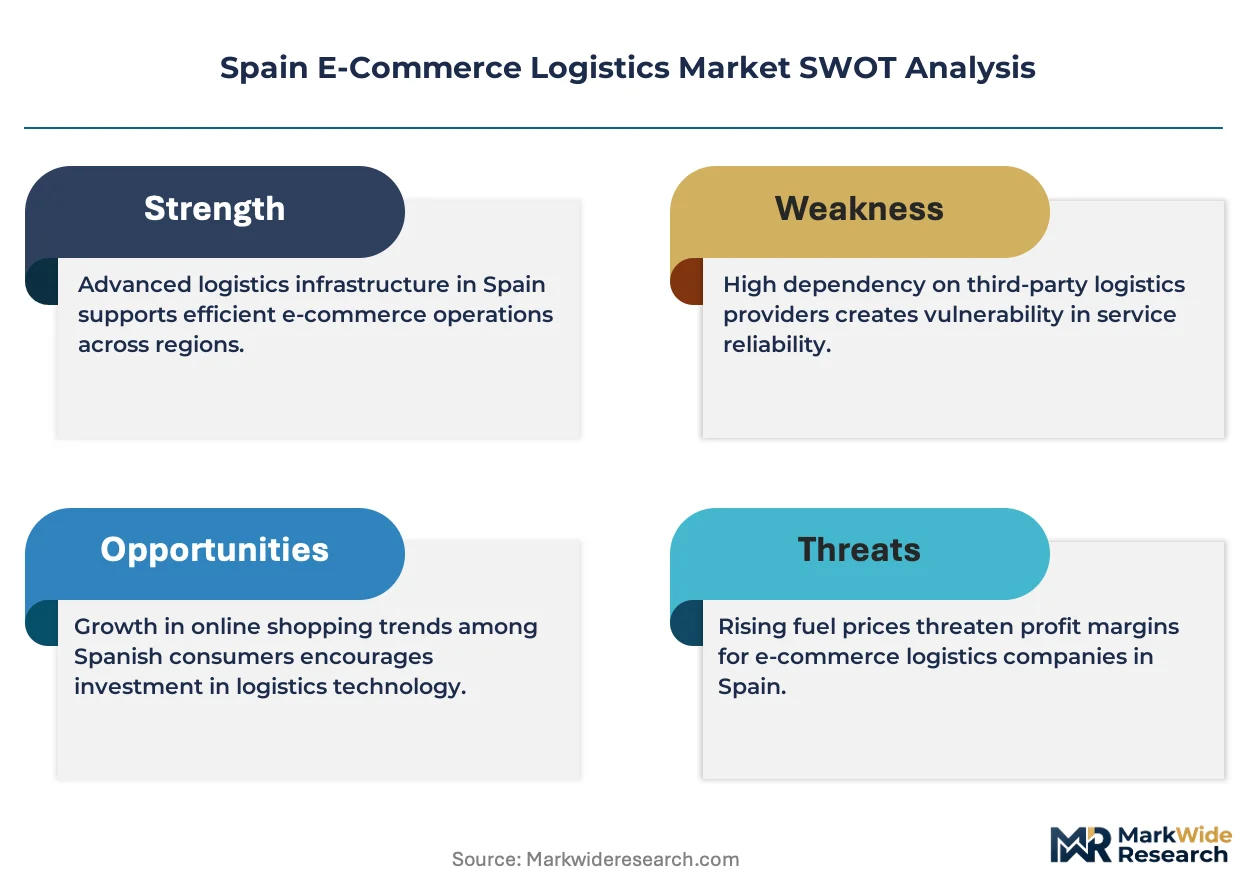
Growth Catalysts
- GDPR-aligned data frameworks:The Spanish Data Protection Agency enforces strict consumer address database rules. Logistics providers invest in compliance infrastructure that creates competitive moats against informal operators.
- Fashion and apparel e-commerce:Spanish consumers have shifted clothing purchases online at accelerating velocity. This vertical demands flexible returns infrastructure that specialized carriers monetize through premium service tiers.
- AI-powered route optimization:Machine learning algorithms reduce failed-delivery rates and fuel consumption simultaneously. Mid-tier operators deploy these tools to defend margin position against national incumbents.
Market Restraints
- Lithium-ion battery supply concentration:Electric van conversion depends on battery cell imports from Asian manufacturing clusters. Spanish fleet operators face procurement delays and currency exposure.
- Warehousing land scarcity:Madrid's logistics corridor exhibits industrial plot shortages near population centers. Automated goods-to-person systems require floorplates that command premium lease rates.
- Technical limitation in temperature control:Pharmaceutical and fresh-food e-commerce demands precise cold chain maintenance. Regional specialists lack nationwide coverage to capture scale economies.
Strategic Opportunities
- Andalusian fulfillment expansion:Seville and Malaga exhibit underpenetrated same-day delivery coverage. Infrastructure investment here captures tourism-driven seasonal demand spikes.
- Cross-border premium flows:Iberian sellers require dedicated EU destination connectivity. Madrid hub operators can anchor consolidated export services for mid-market merchants.
- Sustainable mobility frameworks:Carbon-reporting obligations from the Ministry of Transport favor early fleet electrification adopters. Compliance leadership translates to municipal contract eligibility.
Industry Challenges
- Route optimization engineering talent:AI algorithm deployment requires scarce data science specialization. Spanish technical universities produce insufficient graduates for logistics sector demand.
- Barcode-and-scanner system integration:Legacy parcel sortation hubs operate below automated throughput potential. Retrofit capex competes with greenfield electric vehicle procurement for limited capital budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain E-Commerce Logistics Market |
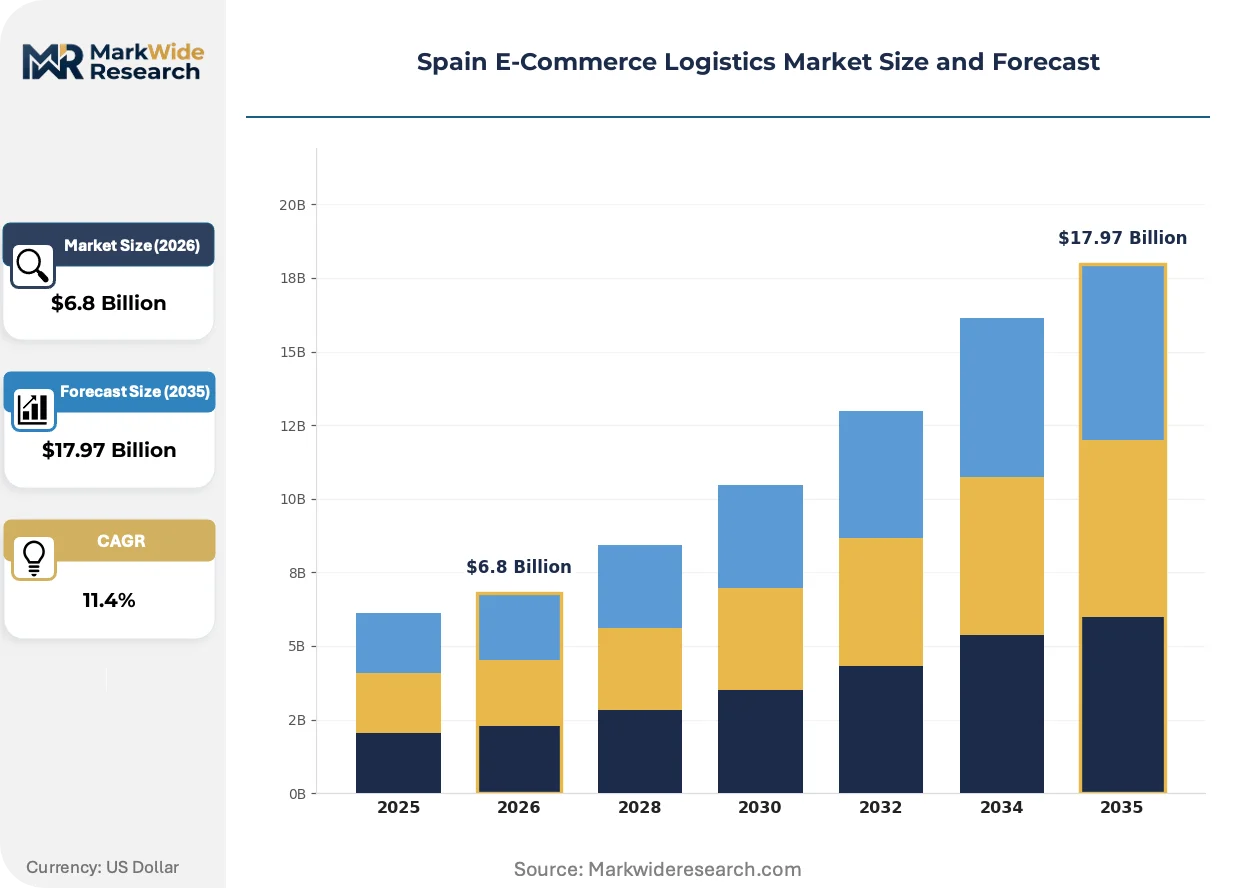
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Last Mile Delivery, Warehousing, Freight Forwarding, Order Fulfillment Customer Type: B2B, B2C, C2C, OEM Delivery Mode: Standard Shipping, Express Delivery, Same-Day Delivery, Drop Shipping Technology: Tracking Systems, Automation Tools, AI-Powered Logistics, Cloud-Based Solutions |
| Companies Covered | SEUR, Celeritas, DHL, UPS, Correos Express, MRW, Nacex, CTT Express, Amphora Logistics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain E-Commerce Logistics Market Trends and Innovations
Digital twin technology is compressing planning cycles across Spanish fulfillment networks. Virtual replicas of warehouse operations and delivery routes enable scenario testing before physical capital deployment.
Cloud-based warehouse management systems are virtualizing inventory visibility across multi-node networks. Mid-tier Spanish operators adopt these platforms to match national carrier transparency without proprietary infrastructure investment. Real-time stock positioning is virtualizing the traditional hub-and-spoke model into distributed micro-fulfillment architectures.
The Ministry of Transport's sustainable mobility frameworks impose escalating carbon-reporting granularity on urban delivery fleets. Logistics providers serving Madrid and Barcelona must document emissions per route and vehicle class. Temperature-controlled specialists face the steepest compliance burden as refrigeration units complicate electrification timelines.
Spanish consumers now expect evening and weekend delivery windows as standard rather than premium offerings. Traditional business-hours distribution models lose share to flexible scheduling platforms. Fashion and apparel merchants in Barcelona metropolitan area report the highest consumer switching sensitivity to delivery slot availability.
Spain E-Commerce Logistics Market Segmentation
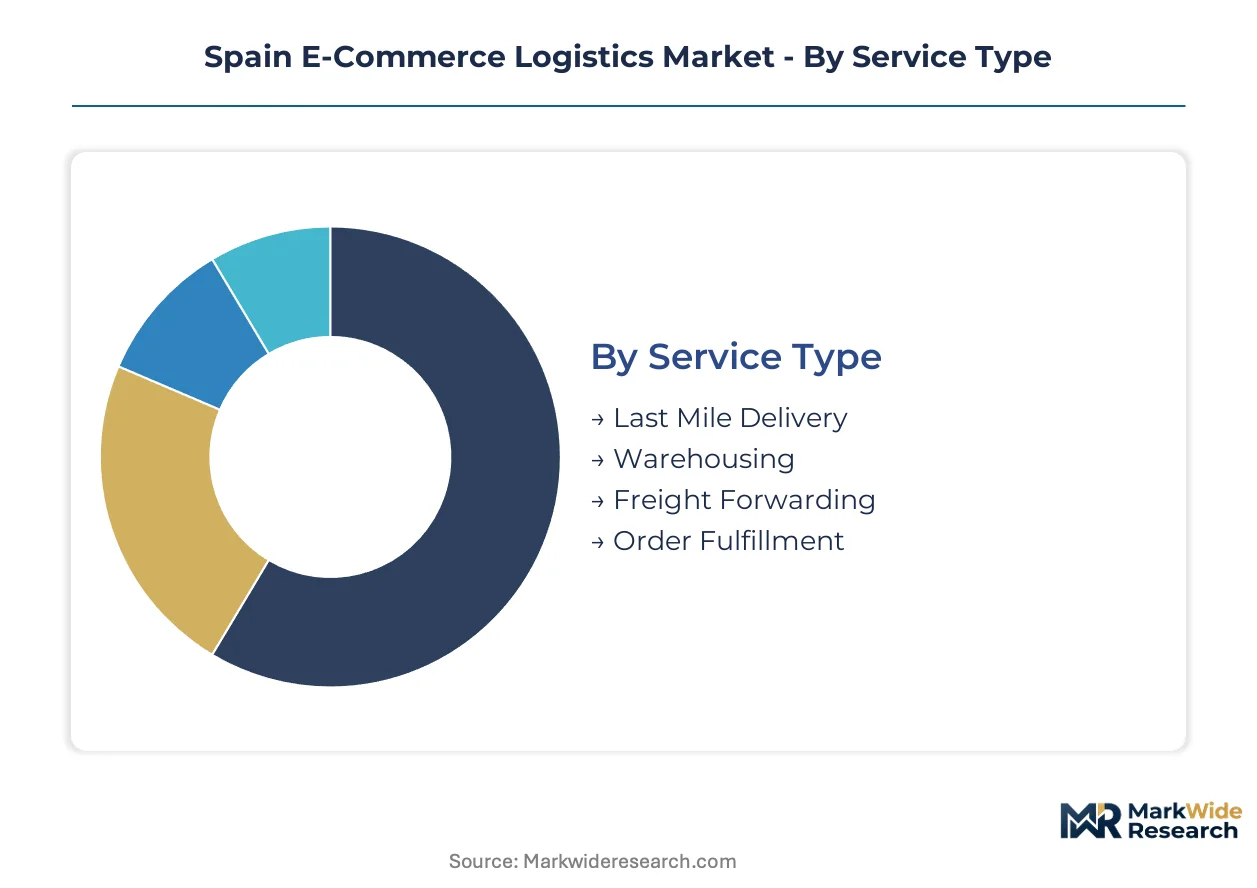
Spain's e-commerce logistics market fragments across service delivery models, customer relationship structures, and technology deployment intensity. Each segmentation axis reveals distinct margin profiles and capital requirements that reshape competitive positioning among Madrid and Barcelona operators.
Service Type:
After-sales service intensity varies dramatically across service categories, with returns handling and customer communication demands driving operational complexity.
- Last Mile Delivery:Urban route networks with electric van fleets navigate Madrid and Barcelona low-emission zones. Consumer expectations for evening and weekend windows intensify driver scheduling complexity and fuel cost management.
- Warehousing:Automated goods-to-person systems require floorplates near population centers where Madrid's logistics corridor faces industrial plot shortages. Fashion and apparel merchants demand flexible returns processing infrastructure that elevates labor intensity.
- Freight Forwarding:Cross-border consolidation services connect Iberian sellers to EU destinations through Madrid hub operations.
- Order Fulfillment:Pick-pack-ship operations integrate with merchant inventory systems for same-day service promises.
Last Mile Delivery holds the largest share; momentum sits with Warehousing as automation investments accelerate.
Customer Type:
Cost tier differentiation separates enterprise-grade contract logistics from transactional parcel services with diverging technology requirements.
- B2C:Individual consumer shipments dominate volume flows with highest last-mile cost sensitivity. Barcelona metropolitan fashion merchants report acute consumer switching based on delivery slot availability.
- B2B:Commercial account relationships sustain contracted capacity commitments and scheduled delivery windows. Industrial procurement patterns favor consolidated freight over parcel fragmentation.
- C2C:Peer-to-peer marketplace shipments require flexible pickup infrastructure and simplified returns protocols.
- OEM:Original equipment manufacturer logistics demands specialized handling for component and finished goods distribution.
B2C commands volume leadership; B2B exhibits the steepest expansion trajectory as merchant consolidation proceeds.
Delivery Mode:
Application context determines speed premium capture, with urban density enabling faster service tiers that suburban and rural networks cannot replicate.
- Same-Day Delivery:Micro-fulfillment architectures position inventory within Madrid and Barcelona municipal boundaries. Tourism-driven seasonal demand spikes in Andalusian corridors test network elasticity.
- Express Delivery:Premium positioning relies on dedicated fleet segments and priority sortation handling.
- Standard Shipping:Economy tier absorbs bulk volume through deferred network utilization and hub consolidation.
- Drop Shipping:Inventory bypass models shift warehousing burden to suppliers while logistics providers manage information flows.
Standard Shipping retains volume dominance; Same-Day Delivery is climbing the fastest as consumer expectations reset.
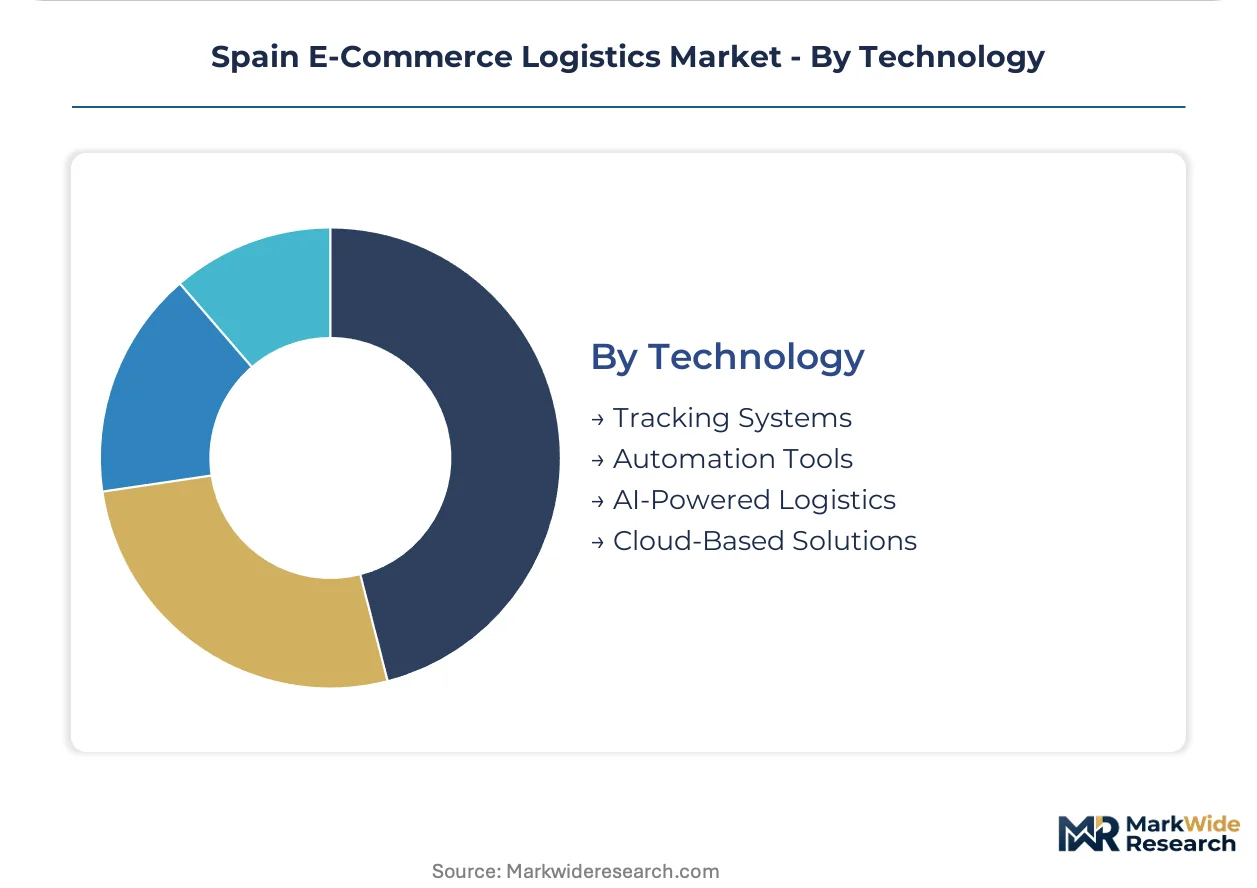
Technology:
Supply concentration in algorithm development and cloud infrastructure creates capability gaps between national incumbents and mid-tier operators.
- AI-Powered Logistics:Machine learning route optimization reduces failed-delivery rates and fuel consumption simultaneously. Spanish technical universities produce insufficient data science graduates for sector demand.
- Cloud-Based Solutions:Virtualized inventory visibility enables multi-node network management without proprietary infrastructure investment.
- Tracking Systems:Barcode-and-scanner granularity supports parcel sortation hub throughput exceeding thousands of items per hour.
- Automation Tools:Goods-to-person robotics and conveyor systems compress labor cost per shipment in high-volume facilities.
Tracking Systems maintains installed base leadership; AI-Powered Logistics is gaining share fastest as margin pressure intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's Ministry of Transport deploys sustainable mobility frameworks that reshape fleet composition requirements across autonomous communities. Municipal low-emission zones in Madrid and Barcelona accelerate electric van procurement timelines. Regional fulfillment density concentrates around the Madrid logistics corridor and Catalonia's industrial belt.
Madrid
Same-day delivery expectations concentrate demand around the capital's fulfillment center cluster. The Directorate General of Traffic enforces emissions standards that accelerate electric van adoption among last-mile operators. The Madrid logistics corridor exhibits industrial plot shortages that elevate automated warehouse lease rates.
Catalonia
Barcelona metropolitan fashion merchants report acute consumer switching sensitivity to delivery slot availability. Municipal low-emission zones impose expanding delivery window restrictions on urban fleets. The Port of Barcelona anchors cross-border consolidation services connecting Iberian sellers to EU destinations.
Andalusia
Seville and Malaga exhibit underpenetrated same-day delivery coverage relative to tourism-driven seasonal demand spikes. Spain's national postal regulator applies sustainability mandates that reshape fleet requirements in southern corridors. The Costa del Sol corridor tests network elasticity during peak summer consumption periods.
Basque Country
Industrial procurement patterns in Bilbao and San Sebastián favor consolidated freight over parcel fragmentation for B2B e-commerce flows. The Ministry of Transport's carbon-reporting obligations apply to logistics providers serving urban centers across the northern coast. The region's manufacturing base generates specialized handling requirements for component distribution.
Valencia
The port city's container throughput supports import-heavy e-commerce inventory positioning for eastern Spain. Regional specialists compete through temperature-controlled capacity for pharmaceutical and fresh-food e-commerce. Valencia's logistics infrastructure captures Mediterranean trade flows while facing electrification timelines tied to municipal sustainability frameworks.
Spain E-Commerce Logistics Market Competitive Landscape
On the supply side, the industry is tiered between national postal incumbents, international integrators, and regional specialists. Legacy parcel carriers defend position through depot footprint density while challengers deploy AI-powered route optimization to compress cost structures. Three strategic archetypes dominate: nationwide network operators, temperature-controlled specialists, and cross-border premium service providers. Competitive moves concentrate on fleet electrification timing and micro-fulfillment node placement.
Within the national incumbent tier, SEUR leverages its nationwide depot footprint to sustain next-day coverage across provincial capitals. Celeritas competes through specialized temperature-controlled capacity for pharmaceutical and fresh-food e-commerce. DHL anchors premium cross-border flows from its Madrid hub, connecting Iberian sellers to European Union destinations.
| Leading Market Players |
|---|
| SEUR |
| Celeritas |
| DHL |
| UPS |
| Correos Express |
| MRW |
| Nacex |
| CTT Express |
| Amphora Logistics |
| Others |
Pricing and Supply Chain Analysis
Lithium-ion battery cell imports from South Korean and Chinese manufacturing clusters concentrate upstream procurement leverage, compressing margin pools for Spanish fleet operators who must absorb currency exposure and procurement delays into their last-mile delivery pricing.
Pricing Analysis
Volume-discount tiering structures separate enterprise contract logistics from transactional parcel services, with fashion and apparel merchants commanding scale-based reductions. Price differentiation rests on delivery speed guarantees and returns-handling sophistication, where same-day premiums widen against standard shipping compression. Pricing pressure stems from municipal low-emission zone compliance costs that operators cannot fully pass to price-sensitive B2C consumers. Small and mid-tier online merchants exhibit acute price sensitivity, while premium cross-border sellers absorb higher rates for EU destination connectivity.
Supply Chain Analysis
Contract-manufacturing concentration for electric van powertrains sits with BYD, Renault, and Mercedes-Benz assembly facilities in France, Germany, and China. Geographic supply concentration draws battery cells from South Korea, Japan, and China, while chassis components feed from German and Czech automotive corridors. Raw material dependencies center on lithium carbonate, nickel sulfate, and rare-earth magnets for drivetrain efficiency. Supply chain risk hinges on single-source vulnerability for battery management systems. Distribution runs through Madrid hub consolidation for Iberian-wide last-mile injection.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's e-commerce logistics sector is approaching a platform-economics inflection where merchant marketplace consolidation and API-native fulfillment interoperability reshape competitive boundaries.
For Market Incumbents: Pre-empt regional specialist encroachment by accelerating micro-fulfillment node placement in Andalusian corridors before tourism-driven demand spikes cement competitor positioning. Prioritize backward integration into electric van fleet ownership over leasing structures to capture residual value and insulate against lithium-ion battery procurement volatility. SEUR's depot density advantage must translate into automated sortation retrofit programs that defend throughput economics against AI-powered challengers. For New Entrants and Emerging Players: Establish a beachhead in temperature-controlled pharmaceutical logistics where Celeritas lacks nationwide coverage and compliance burdens deter generalist expansion. Target Seville and Malaga metropolitan zones for same-day infrastructure investment, exploiting underpenetrated delivery density relative to seasonal demand elasticity. A go-to-market angle anchored to GDPR-compliant address database infrastructure creates differentiation against informal operators lacking compliance moats. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated warehousing as Madrid logistics corridor land scarcity elevates goods-to-person system deployment thresholds. Long-term viability favors operators with secured industrial plot access and electrification compliance leadership translating to municipal contract eligibility. Acquisition target archetypes include regional temperature-controlled specialists with Andalusian footprint and mid-tier AI-route-optimization platforms facing talent scarcity constraints. Monitor lithium-ion battery supply agreement durations as inflection indicator for fleet conversion timeline risk.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Acceleration | Ministry of Transport carbon-reporting obligations favor early adopters for municipal contract eligibility in Madrid and Barcelona low-emission zones. |
| Micro-Fulfillment Node Expansion | Seville and Malaga positioning captures tourism-driven seasonal demand spikes before incumbent depot density solidifies. |
| AI Route Optimization Deployment | Machine learning algorithms reduce failed-delivery rates for mid-tier operators defending margin position against SEUR network scale. |
| Temperature-Controlled Capacity Buildout | Pharmaceutical and fresh-food e-commerce demands precise cold chain maintenance that regional specialists lack nationwide coverage to fulfill. |
| Cross-Border Premium Service Consolidation | Madrid hub operators anchor consolidated export services connecting Iberian sellers to EU destinations through DHL-anchored infrastructure. |
Research Methodology
A spread of perspectives from logistics operations directors, fleet procurement managers, fashion merchant supply chain leads, and municipal transport planners converged on the working assumptions driving this analysis. Primary interviews with SEUR network planners, Celeritas pharmaceutical logistics specialists, and Barcelona metropolitan fulfillment operators combined with secondary validation from Directorate General of Traffic emissions filings, Ministry of Transport sustainable mobility framework disclosures, and Spanish Data Protection Agency GDPR enforcement records. Bottom-up service tier volume estimates and top-down national e-commerce flow projections underwent iterative reconciliation.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling service type, customer relationship structure, delivery mode commitment, and technology deployment intensity as core segmentation dimensions. CAGRs derived from logistic curve penetration modeling applied to fashion and apparel e-commerce velocity trends, electric van fleet conversion timelines, and automated warehousing adoption thresholds. Forecast inputs incorporated municipal low-emission zone expansion schedules and lithium-ion battery procurement lead time assumptions.
Sensitivities concentrate around battery supply chain disruption, Madrid logistics corridor land availability deterioration, and GDPR enforcement intensity escalation. Forecasts reflect documented assumptions subject to revision from regulatory framework modifications or technology cost curve inflections. Quarterly review of fleet electrification procurement queues and municipal contract award patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
South Korea Ecommerce Logistics Market
E-Commerce Solutions
Argentina E-Commerce Market
E-Commerce Solutions
E-Tailing Market
E-Commerce Solutions
US SMS Marketing Market
E-Commerce Solutions
Global Online Book Services Market
E-Commerce Solutions
E-Commerce in Nigeria Market
E-Commerce Solutions
Omnichannel Commerce Software Market
E-Commerce Solutions
Bulgaria E-Commerce Market
E-Commerce Solutions
Philippines E-Commerce Market
E-Commerce Solutions
E-Commerce Technology Market
E-Commerce Solutions
Saudi Arabia Delivery Apps Market
E-Commerce Solutions
Sweden E-Commerce Market
E-Commerce Solutions
Quiet Commerce Market
E-Commerce Solutions
Cross-Border E-Commerce Logistics Market
E-Commerce Solutions
Mexico E-Commerce Market
E-Commerce Solutions
Courier Express and Parcel (CEP) Market