
 Australia E-Commerce Market | 2026-2036
Australia E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Australia E-Commerce Market Analysis
A shortage of last-mile logistics specialists is redrawing operational priorities across Australian online retail. Woolworths Group Ltd leverages its existing store network for click-and-collect density, while Coles Group Ltd sustains competitive pressure through automated fulfillment center investments. Amazon Commercial Services Pty Ltd anchors its position with distribution hubs in Sydney and Melbourne that enable next-day delivery benchmarks.
Australia e-commerce denotes the digital sale and fulfillment of goods and services through web-based platforms and mobile applications, relying on integrated payment gateways, inventory management systems, and courier networks for order completion. Its commercial purpose centers on reducing friction between product discovery and delivery, replacing or augmenting physical retail footprints. Online marketplaces currently dominate transaction volume by aggregating third-party sellers under unified discovery layers, while buy now pay later methods are capturing disproportionate growth in average order value expansion. Electronics and home goods within product category segmentation command the deepest margin pools due to higher ticket sizes and lower return rates relative to clothing.
The Australian Competition and Consumer Commission enforces platform transparency rules that affect marketplace fee disclosures and search ranking algorithms, while the Australian Prudential Regulation Authority oversees buy now pay later providers as credit products expand. The Reserve Bank of Australia's retail payments regulation shapes interchange cost structures that flow through to merchant pricing. Stakeholders must monitor how evolving data localization requirements and consumer protection amendments will alter customer acquisition economics and platform compliance burdens.
Market Dynamics
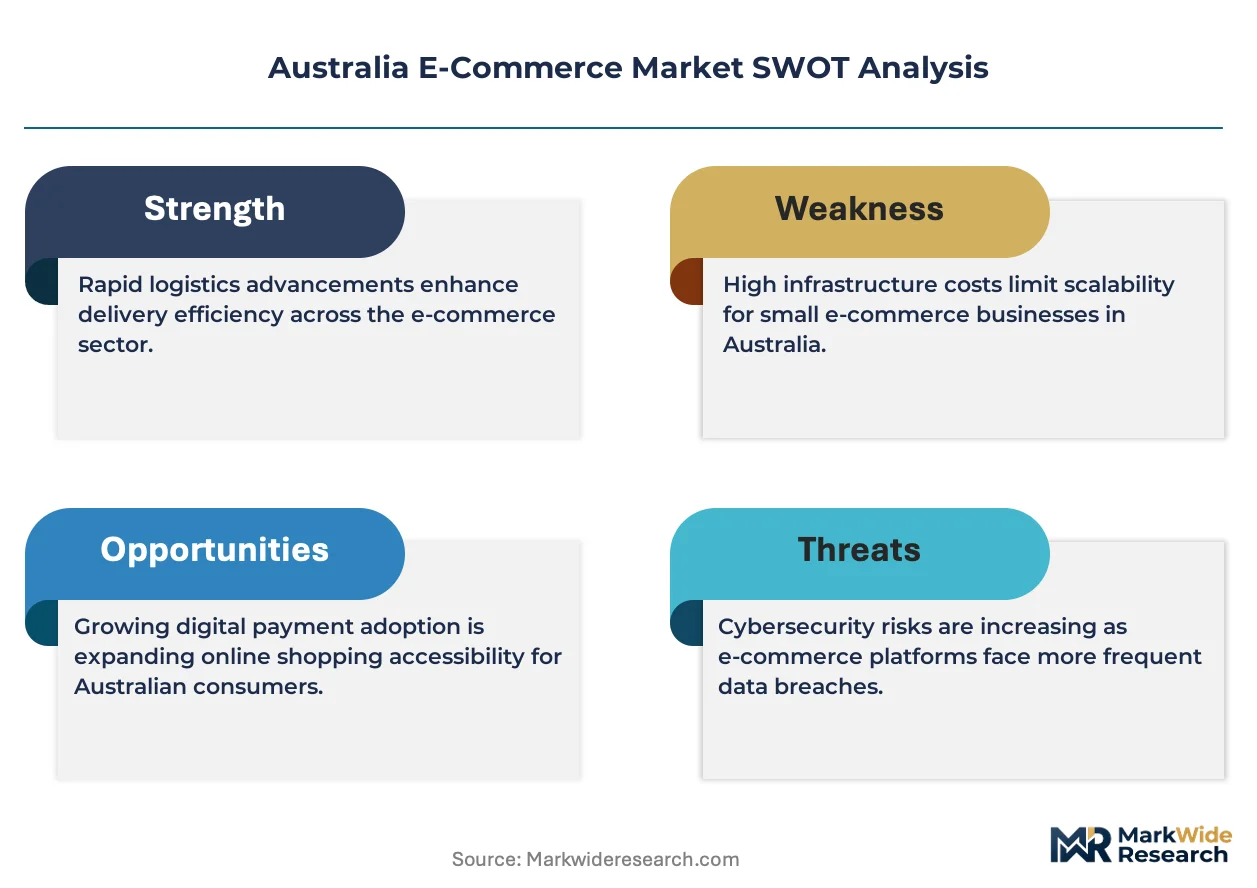
The Australian Competition and Consumer Commission's platform transparency mandates are forcing marketplace operators to overhaul fee disclosure architectures and search ranking methodologies, compressing margin structures while elevating compliance expenditures.
Growth Catalysts
- Buy Now Pay Later Credit Reclassification:The Australian Prudential Regulation Authority's oversight of deferred payment instruments as credit products is legitimizing installment purchasing, expanding average order values across discretionary categories.
- Same-Day Fulfillment Infrastructure:Automated picking systems and micro-fulfillment centers in Sydney and Melbourne are compressing delivery windows, locking in metropolitan household retention.
- Grocery Digital Migration:Metropolitan households are adopting scheduled replenishment for fresh food, converting historically resistant categories to online channels.
Market Restraints
- Last-Mile Labor Scarcity:Courier network capacity constraints in Australian urban corridors are inflating per-delivery costs and capping peak-period throughput.
- Interchange Cost Pass-Through:Reserve Bank of Australia retail payment regulations structure merchant service fees that erode thin-margin categories.
- Data Localization Compliance:Evolving domestic data storage mandates are fragmenting cloud architecture investments and duplicating infrastructure spend.
Strategic Opportunities
- Regional Queensland Penetration:Logistics network gaps outside Brisbane-Southeast Queensland corridor present first-mover consolidation potential for fulfillment density.
- Voice-Enabled Reordering:Smart speaker integration with pantry management systems is creating frictionless replenishment loops in household consumables.
- Carbon-Neutral Delivery Mandates:Emerging state-level emissions disclosure requirements for transport are advantaging electric fleet operators with preemptive certification.
Industry Challenges
- Warehouse Automation Talent Gap:Robotics integration specialists and fulfillment systems engineers command premium compensation, constraining rollout velocity for automated facilities.
- Legacy ERP Synchronization:Inventory visibility across physical stores and digital channels requires real-time middleware that many incumbent retailers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia E-Commerce Market |
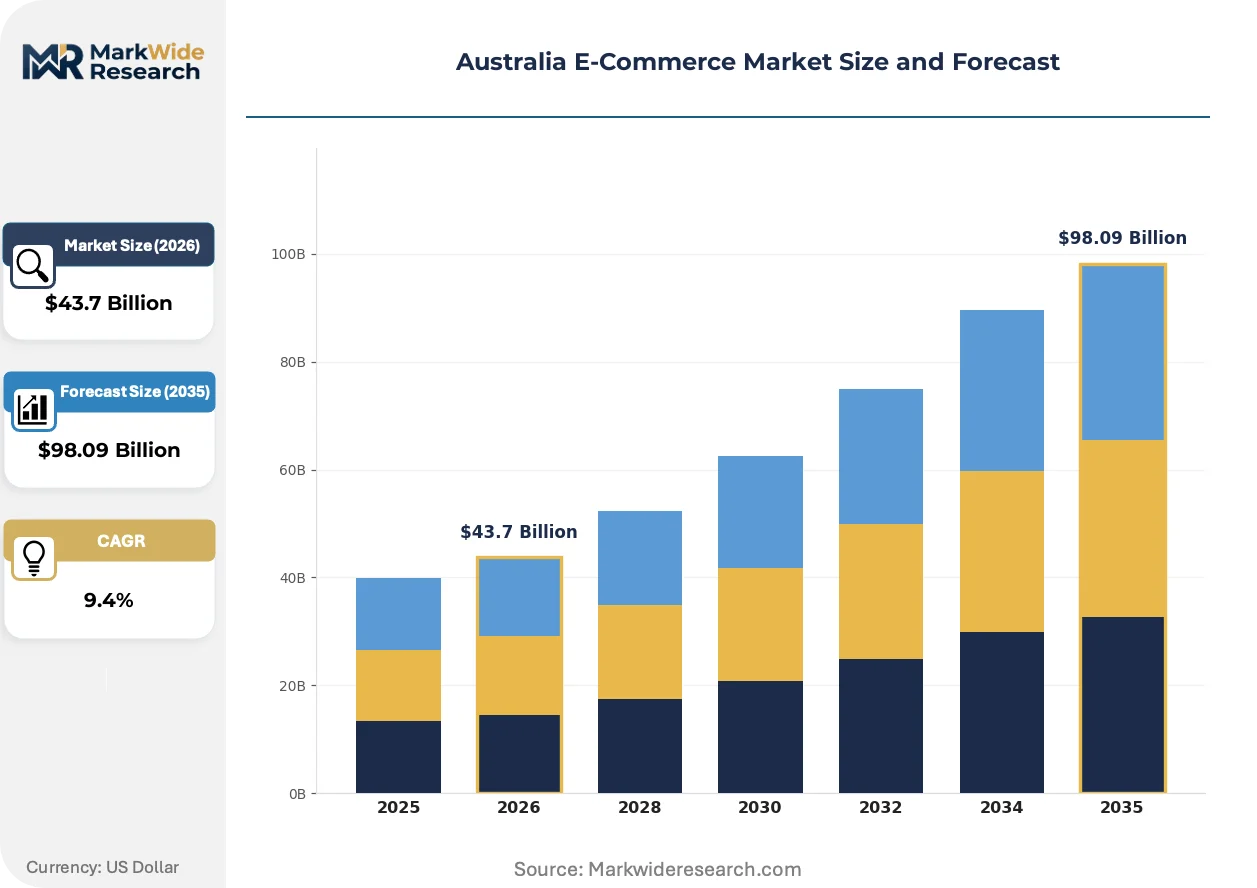
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $98.09 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Category: Electronics, Clothing, Home Goods, Beauty Products Sales Channel: Direct Sales, Online Marketplaces, Social Commerce, Subscription Services Customer Type: Individual Consumers, Small Businesses, Corporates, Non-profits Payment Method: Credit Card, PayPal, Buy Now Pay Later, Bank Transfer |
| Companies Covered | Amazon Commercial Services Pty Ltd, eBay Australia Pty Ltd, Kogan.com Ltd, Woolworths Group Ltd, Coles Group Ltd, JB Hi-Fi Ltd, Catch.com.au, MyDeal Ltd, Temple & Webster Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia E-Commerce Market Emerging Trajectories
Platform architecture and fulfillment methodology are undergoing simultaneous transformation as regulatory pressure intersects with automation capability and shifting household purchasing rituals.
Headless commerce architecture is decomposing monolithic platform stacks into modular API-first components. Mid-market retailers in Melbourne and Sydney are adopting microservices for checkout, inventory, and payment orchestration. This decomposition is enabling faster experimentation with subscription models and marketplace integrations without full platform replacement.
The Australian Competition and Consumer Commission's mandatory fee transparency rules are exposing previously opaque commission structures. Third-party sellers now receive standardized cost breakdowns before listing. Electronics and home goods vendors are responding by diversifying across multiple marketplaces to arbitrage fee differentials.
Scheduled replenishment is displacing episodic purchasing in metropolitan grocery categories. Sydney households are converting to automated reordering for staples, with delivery windows tied to commute patterns. This behavioral shift is most visible in dual-income households with predictable consumption cadences, where platform stickiness derives from pantry integration rather than price competition.
Australia E-Commerce Market Segmentation
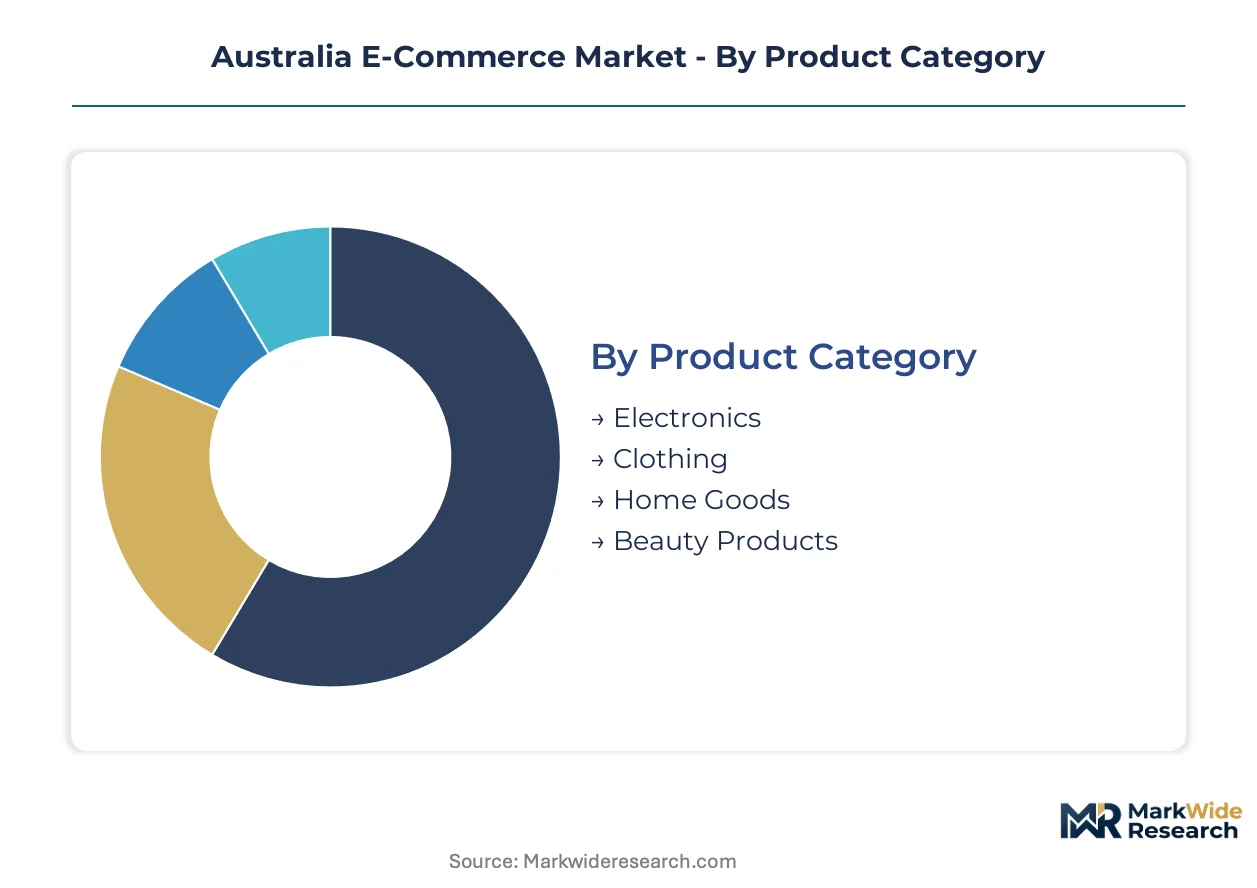
Segmentation in Australian e-commerce reveals how substitution pressures and channel economics reshape competitive boundaries. Understanding these divisions exposes where margin compression concentrates and which customer cohorts drive platform loyalty.
Product Category:
Electronics and home goods face intensifying substitution from physical retail as click-and-collect narrows the convenience gap, while clothing and beauty contend with return-rate economics that erode digital margins.
- Electronics:High-ticket consumer durables including smartphones, laptops, and home appliances with standardized specifications that reduce purchase risk online. Demand concentrates in Sydney and Melbourne where same-day fulfillment infrastructure supports immediate replacement cycles. The Australian Competition and Consumer Commission's warranty disclosure rules elevate compliance costs for cross-border sellers.
- Clothing:Apparel and footwear with high return rates due to fit uncertainty, requiring sophisticated sizing algorithms and reverse logistics capabilities. Metropolitan households in dual-income brackets drive volume through mobile-first discovery, though margin pressure from free return policies persists.
- Home Goods:Furniture, kitchenware, and décor with bulky fulfillment requirements.
- Beauty Products:Cosmetics and skincare with sensory-dependent purchase decisions.
Electronics retains volume leadership; beauty products hold the steepest expansion curve.
Sales Channel:
Channel economics diverge sharply between inventory-risk models and commission-based aggregation, with cost-to-serve determining which structures absorb regulatory fee-transparency mandates most effectively.
- Online Marketplaces:Third-party aggregation platforms that unify discovery, payment, and fulfillment infrastructure under standardized terms. Sydney and Melbourne seller density creates network effects that lock in merchant participation despite commission pressure from the Australian Competition and Consumer Commission's disclosure requirements.
- Direct Sales:Brand-owned digital storefronts with full margin capture and customer data ownership. Volume concentrates among established retailers with existing physical footprints that enable click-and-collect integration and returns handling.
- Social Commerce:Transaction completion within social media environments with influencer-mediated discovery.
- Subscription Services:Recurring replenishment models with predictable revenue and pantry integration.
Online marketplaces dominate transaction volume; subscription services are climbing the fastest.
Customer Type:
Procurement sophistication separates segments, with organizational buyers demanding invoice integration and volume pricing that consumer-facing platforms struggle to accommodate.
- Individual Consumers:Household purchasers with episodic or replenishment-driven demand patterns, segmented by metropolitan density and income bracket. Sydney and Melbourne concentration reflects logistics infrastructure availability and delivery speed expectations.
- Small Businesses:Sole traders and micro-enterprises purchasing supplies and equipment through consumer-grade interfaces with limited procurement formalization.
- Corporates:Organizational buyers with negotiated terms, purchase order workflows, and compliance documentation requirements.
- Non-profits:Mission-driven organizations with constrained budgets and donation-dependent purchasing cycles.
Individual consumers anchor revenue; corporates show the strongest share gain.
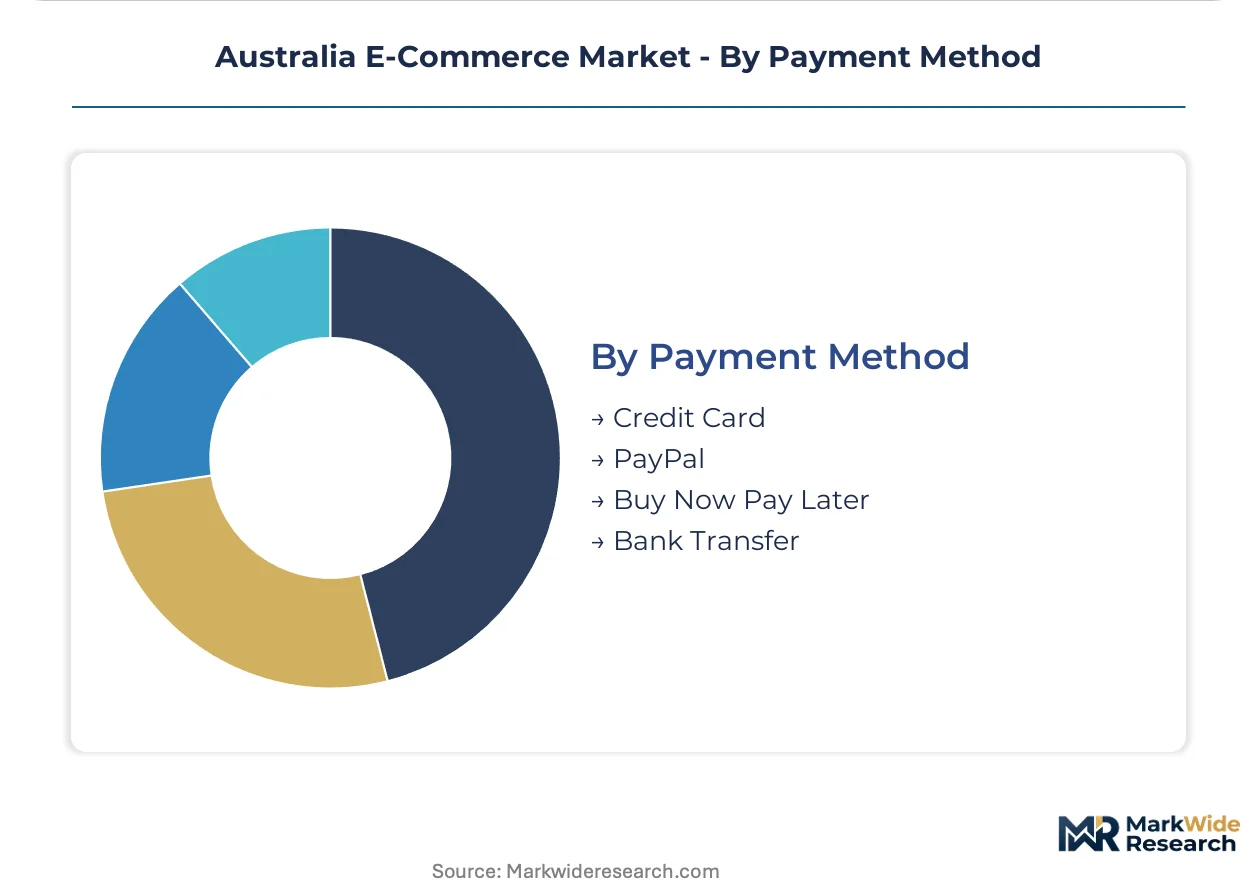
Payment Method:
Payment infrastructure fragmentation reflects regulatory classification debates and merchant cost pass-through strategies that reshape checkout conversion.
- Buy Now Pay Later:Deferred installment instruments now regulated as credit products by the Australian Prudential Regulation Authority, legitimizing the category while imposing capital requirements. Average order value expansion concentrates in discretionary categories among metropolitan millennials.
- Credit Card:Dominant payment rails with interchange cost structures shaped by Reserve Bank of Australia retail payments regulation. Merchant service fees erode thin-margin categories, driving platform investment in alternative rails.
- PayPal:Wallet-based checkout with buyer protection and guest conversion advantages.
- Bank Transfer:Direct debit with lowest merchant cost but highest friction and settlement delay.
Credit card retains transaction leadership; buy now pay later is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Australian e-commerce concentrates sharply in Sydney and Melbourne, where same-day fulfillment infrastructure commands premium delivery fees, while regional markets absorb higher per-order logistics costs that compress merchant margins.
New South Wales
Sydney's dual-income households drive scheduled replenishment adoption for grocery and fresh food categories. The Australian Competition and Consumer Commission's platform transparency mandates reshape fee disclosure for marketplace operators based in the state. Parramatta and Macquarie Park host emerging fulfillment clusters where automated micro-centers compress delivery windows for metropolitan catchments.
Victoria
Melbourne's dense inner suburbs support the highest click-and-collect penetration rates among Australian capitals. The Reserve Bank of Australia's retail payments regulation structures interchange costs that flow through to merchant pricing statewide. The Dandenong South industrial corridor anchors major distribution hubs serving southeastern logistics networks.
Queensland
Brisbane-Southeast Queensland generates accelerating demand for grocery digital migration among metropolitan households. State-level emissions disclosure requirements for transport operators are emerging, advantaging early electric fleet certification. Logan and Redland Bay host developing fulfillment infrastructure addressing last-mile gaps outside the capital corridor.
Western Australia
Perth's geographic isolation inflates per-delivery costs and extends fulfillment timelines relative to eastern capitals. Data localization compliance requirements fragment cloud architecture investments for retailers operating across state borders. The Perth Airport industrial zone concentrates limited automated warehousing capacity serving the isolated market.
South Australia
Adelaide's smaller metropolitan scale limits same-day fulfillment infrastructure deployment compared to larger capitals. The Australian Prudential Regulation Authority's buy now pay later oversight as credit products affects installment purchasing penetration among younger demographics. Edinburgh Parks hosts the primary logistics cluster connecting South Australia to interstate distribution networks.
Australia E-Commerce Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across Australian e-commerce. The market structures around a consolidated tier of integrated retail conglomerates with physical store networks, a fragmented long tail of pure-play digital specialists, and platform aggregators with third-party seller density. Three strategic archetypes dominate: incumbent grocers leveraging click-and-collect infrastructure, global marketplace operators with distribution scale, and category-focused pure-plays with curated assortment depth. Competitive moves concentrate on automated fulfillment center rollout and strategic partnerships for last-mile courier capacity.
Among integrated retail conglomerates, Woolworths Group Ltd and Coles Group Ltd exemplify the store-network arbitrage archetype, converting existing physical footprints into fulfillment nodes. Amazon Commercial Services Pty Ltd anchors the global platform tier with distribution infrastructure concentrated in Sydney and Melbourne. These three entities occupy distinct competitive positions without direct overlap in core capability emphasis.
| Leading Market Players |
|---|
| Amazon Commercial Services Pty Ltd |
| eBay Australia Pty Ltd |
| Kogan.com Ltd |
| Woolworths Group Ltd |
| Coles Group Ltd |
| JB Hi-Fi Ltd |
| Catch.com.au |
| MyDeal Ltd |
| Temple & Webster Group |
| Others |
Supply Flow & Price Mechanics
Automated fulfillment center scale economies in Sydney and Melbourne compress per-unit delivery costs while establishing price floors that smaller regional operators cannot match. This concentration of same-day infrastructure locks metropolitan households into premium service tiers and fragments pricing power across state boundaries.
Pricing Analysis
Configured-to-order grocery replenishment commands a 15-20% premium over standard slot-based delivery in Australian metropolitan markets. Three-tier pricing structure across premium, standard, and economy levels stratifies around delivery speed and pantry integration depth. Cost compression in economy tiers is intensifying because Reserve Bank of Australia interchange regulations inflate merchant service fees that platforms attempt to recover through checkout surcharges. Small businesses purchasing through consumer-grade interfaces demonstrate highest price sensitivity; corporates with negotiated procurement terms show lowest.
Supply Chain Analysis
China and Vietnam anchor apparel and electronics manufacturing for Australian e-commerce platforms, while domestic automated warehousing concentrates in Sydney and Melbourne. Robotics integration for fulfillment draws from German and Japanese component suppliers. Single-source vulnerability in last-mile courier networks creates systemic risk during peak demand periods. Distribution runs through click-and-collect nodes at incumbent grocer physical stores, supplemented by dedicated micro-fulfillment centers in inner metropolitan catchments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australian e-commerce functions as a defensive-moat market where click-and-collect infrastructure density creates switching costs that lock metropolitan households into established platforms.
For Market Incumbents: Compound network advantages by deepening automated fulfillment center deployment in Parramatta and Dandenong South corridors. Expand same-day delivery catchments through electric fleet certification that satisfies emerging Queensland emissions disclosure requirements. Vertical integration into last-mile courier capacity addresses labor scarcity that threatens peak-period throughput. For New Entrants and Emerging Players: Lead with white-space consolidation in regional Queensland outside the Brisbane-Southeast corridor, where logistics network gaps create first-mover potential for fulfillment density. Target voice-enabled pantry integration as a go-to-market angle that bypasses established platform discovery layers through smart speaker reordering loops. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors automated fulfillment specialists with robotics integration capabilities and established Sydney-Melbourne infrastructure footprints. Long-term viability hinges on regulatory entrenchment through Australian Competition and Consumer Commission compliance architectures that elevate barriers for cross-border entrants. The signal to watch is buy now pay later credit reclassification enforcement by the Australian Prudential Regulation Authority, which will reshape customer acquisition economics.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Fulfillment Center Deployment | Micro-fulfillment density in Parramatta and Macquarie Park compresses delivery windows for Sydney metropolitan retention. |
| Electric Fleet Certification Program | Preemptive state-level emissions compliance in Queensland advantages operators against pending transport disclosure mandates. |
| Voice-Enabled Pantry Integration | Smart speaker reordering loops create frictionless replenishment stickiness in dual-income household consumables. |
| Headless Commerce Architecture Migration | API-first platform decomposition enables faster experimentation with subscription models without full stack replacement. |
| Last-Mile Courier Capacity Partnership | Strategic alliances address labor scarcity that caps peak-period throughput in Australian urban corridors. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of Australian Bureau of Statistics retail trade data, Reserve Bank of Australia payment system publications, and Australian Competition and Consumer Commission platform inquiry reports. Interviews with fulfillment center operations directors, grocery category managers at major retailers, last-mile logistics coordinators, and buy now pay later product leads informed demand-side validation. Top-down market sizing from macro retail flows was triangulated against bottom-up transaction volume estimates from marketplace operator disclosures.
Segmentation dimensions modeled include product category, sales channel, customer type, payment method, and metropolitan density tier across the analysis window. CAGRs were derived from trend extrapolation of historical transaction growth adjusted for regulatory intervention impacts. Forecast inputs incorporate automated fulfillment center rollout schedules and Australian Prudential Regulation Authority credit oversight implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained metropolitan household income growth and stable logistics labor availability would require recalibration. Forecasts reflect assumptions about platform fee transparency compliance costs and data localization infrastructure spend. Recalibration cycles align with material shifts in Reserve Bank of Australia retail payments regulation and state-level transport emissions policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
North America E-Commerce Market
E-Commerce Solutions
Serbia E-Commerce Market
E-Commerce Solutions
Albania E-Commerce Market
E-Commerce Solutions
E-Commerce Market
E-Commerce Solutions
Quick Commerce Market
E-Commerce Solutions
Europe E-Commerce Market
E-Commerce Solutions
Metaverse in E-Commerce Market
E-Commerce Solutions
Mobile Commerce Market
E-Commerce Solutions
Poland E-Commerce Market
E-Commerce Solutions
Argentina E-Commerce Market
E-Commerce Solutions
Automotive E-Commerce Market
E-Commerce Solutions
Europe E-Commerce Watch Market
E-Commerce Solutions
India E-Commerce Market
E-Commerce Solutions
Hyperlocal Delivery App Market
E-Commerce Solutions
T-Commerce Market
E-Commerce Solutions
Alcohol E-Commerce Market