
 Italy E-Commerce Market | 2026-2036
Italy E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Italy E-Commerce Market Outlook
The Italy e-commerce landscape is pivoting on a widening gap between premium experiential platforms and commodity-driven marketplaces. Amazon.it leverages its fulfillment infrastructure to dominate same-day delivery in dense northern corridors. Zalando sustains brand loyalty through curated fashion assortments and flexible return policies. Shein competes aggressively on ultra-fast fashion cycles and social-native merchandising.
Italy e-commerce encompasses digitally mediated transactions for goods and services, executed through web interfaces and mobile applications with integrated payment gateways, inventory management systems, and last-mile logistics orchestration. The sector functions as a commercial infrastructure layer connecting fragmented Italian retail supply with digitally native consumption patterns. Fashion and electronics anchor current transaction volumes, while B2B procurement platforms represent the fastest-expanding customer type as industrial buyers migrate from legacy purchasing channels. Mobile payments and click-and-collect models capture disproportionate margin pools by reducing cart abandonment and optimizing inventory turns.
EU Digital Services Act obligations and Italy's national consumer protection framework enforced by AGCM reshape marketplace liability, mandating algorithmic transparency and counterfeit removal protocols. GDPR compliance costs filter smaller merchants toward platform-dependent selling models rather than independent storefronts. Stakeholders must monitor how AGCM enforcement of the EU AI Act on recommendation engines alters traffic allocation economics for Italian marketplace sellers.
Market Dynamics
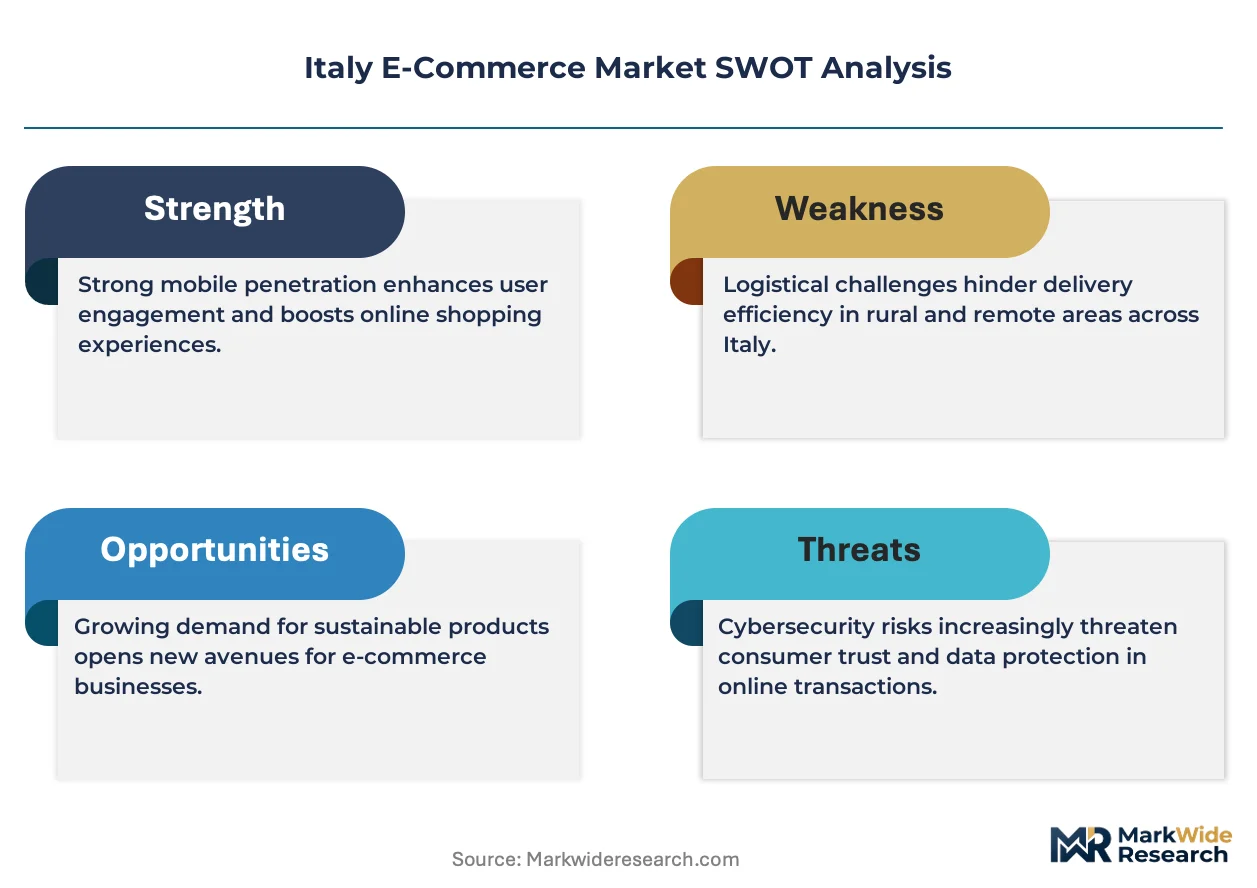
The Italy e-commerce market is compressing around platform consolidation and regulatory compliance costs, with the EU Digital Services Act forcing marketplace operators to restructure liability frameworks and algorithmic transparency protocols.
Growth Catalysts
- GDPR-Compliant Infrastructure:Italian merchants are migrating to platform-native storefronts to offload data governance burdens, accelerating marketplace dependency and reducing independent site proliferation.
- Mobile Payment Rails:Satispay and Nexi integration into checkout flows is collapsing cart abandonment rates in fashion and electronics verticals.
- Milan Logistics Corridor:Same-day fulfillment density in Lombardy is pulling inventory positioning northward, concentrating warehousing investment around intermodal freight nodes.
Market Restraints
- AGCM Enforcement Friction:Italy's competition authority is intensifying scrutiny of algorithmic ranking systems, creating compliance lag for marketplace operators adapting to EU Digital Services Act mandates.
- Last-Mile Cost Structure:Alpine topography and fragmented urban cores outside Milan-Rome-Turin drive per-delivery costs substantially above Benelux benchmarks.
- Counterfeit Liability Exposure:Platform operators now bear direct responsibility for IP-infringing listings, forcing investment in seller verification and automated takedown systems.
Strategic Opportunities
- Southern Italy Underpenetration:Campania, Sicily, and Calabria exhibit e-commerce penetration gaps of 40-60% versus northern benchmarks, creating white space for localized fulfillment investment.
- B2B Procurement Platforms:Industrial buyers in Emilia-Romagna's manufacturing belt are migrating from legacy purchasing channels to integrated supply platforms.
- Click-and-Collect Networks:Grocery chains are retrofitting store networks as pickup nodes, blending inventory efficiency with consumer convenience preferences.
Industry Challenges
- GDPR-Technical Talent Scarcity:Marketplace operators face acute shortages of data protection officers and privacy engineers capable of implementing Article 22 automated decision-making audits.
- Legacy ERP Integration:Mid-market Italian retailers struggle to synchronize inventory, pricing, and fulfillment data across fragmented backend systems and marketplace APIs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy E-Commerce Market |
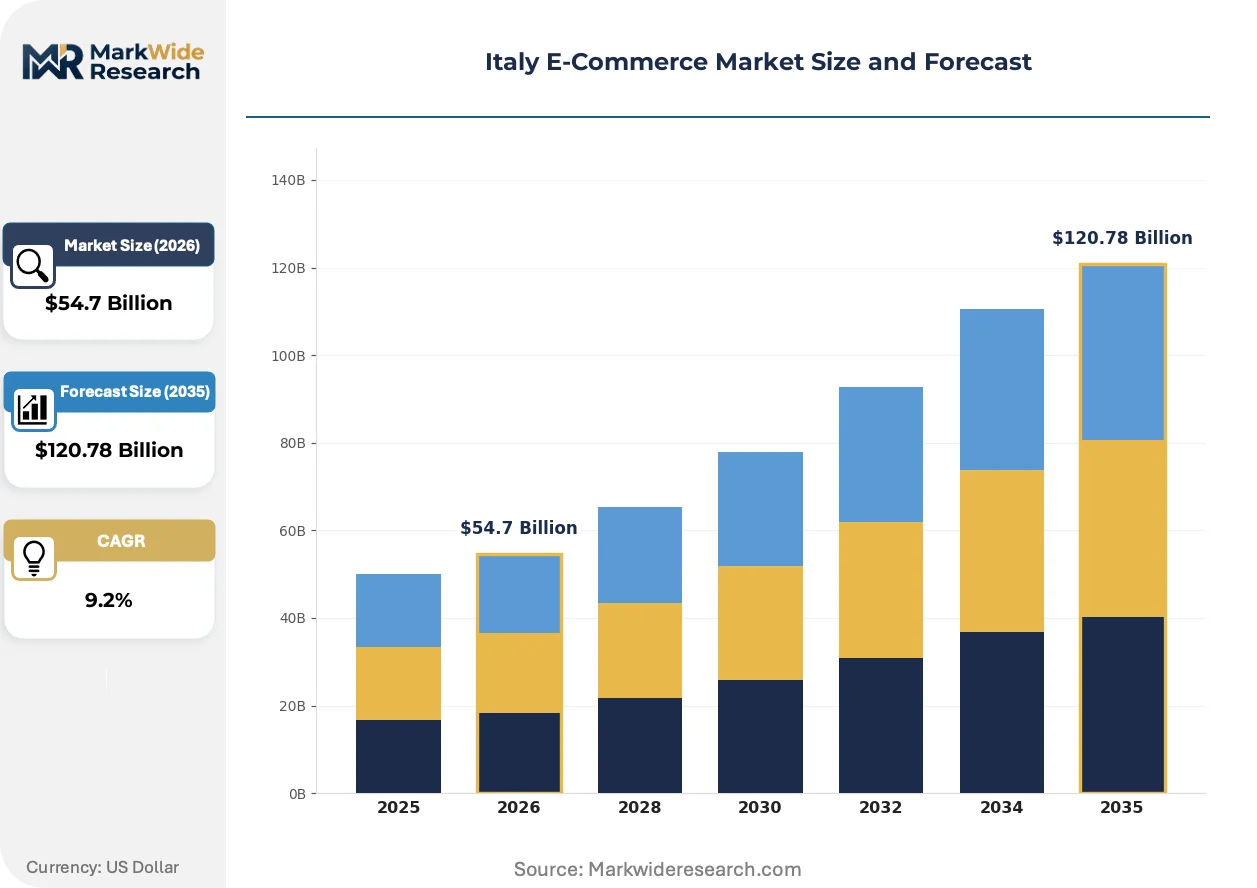
| Market Size in 2026 | $54.7 Billion |
| Market Size in 2035 | $120.78 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fashion, Electronics, Home Goods, Beauty Customer Type: B2C, B2B, C2C, Direct-to-Consumer Payment Method: Credit Cards, PayPal, Bank Transfers, Mobile Payments Delivery Model: Standard Shipping, Express Delivery, Click & Collect, Same-Day Delivery |
| Companies Covered | Amazon.it, Shein, Zalando, eBay, Subito, Esselunga, Apple, Temu, Unieuro, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy E-Commerce Market Strategic Shifts
Italian e-commerce is pivoting from transaction volume growth toward margin compression through automation and regulatory adaptation, with technology and policy forces restructuring competitive economics.
Warehouse robotics and automated sortation systems are penetrating Italian fulfillment centers as labor costs rise and delivery speed expectations tighten. Third-party logistics providers in the Po Valley are deploying autonomous mobile robots for goods-to-person picking. This capital investment is automating order processing throughput and reducing per-unit handling costs for high-velocity fashion SKUs.
The EU AI Act's risk classification framework is reshaping how Italian marketplaces deploy recommendation engines and dynamic pricing algorithms. High-risk systems now require conformity assessments and human oversight protocols before deployment. Fashion and electronics platforms are most affected, with engineering teams rearchitecting ranking systems to satisfy transparency and non-discrimination requirements.
Italian consumers are consolidating purchase journeys around super-app interfaces that merge shopping, payment, and delivery tracking. Younger demographics in Rome and Milan expect native-app experiences with integrated loyalty and financing options. This behavioral shift is pressuring standalone e-commerce sites to migrate into platform ecosystems or invest heavily in proprietary app development.
Italy E-Commerce Market Segmentation
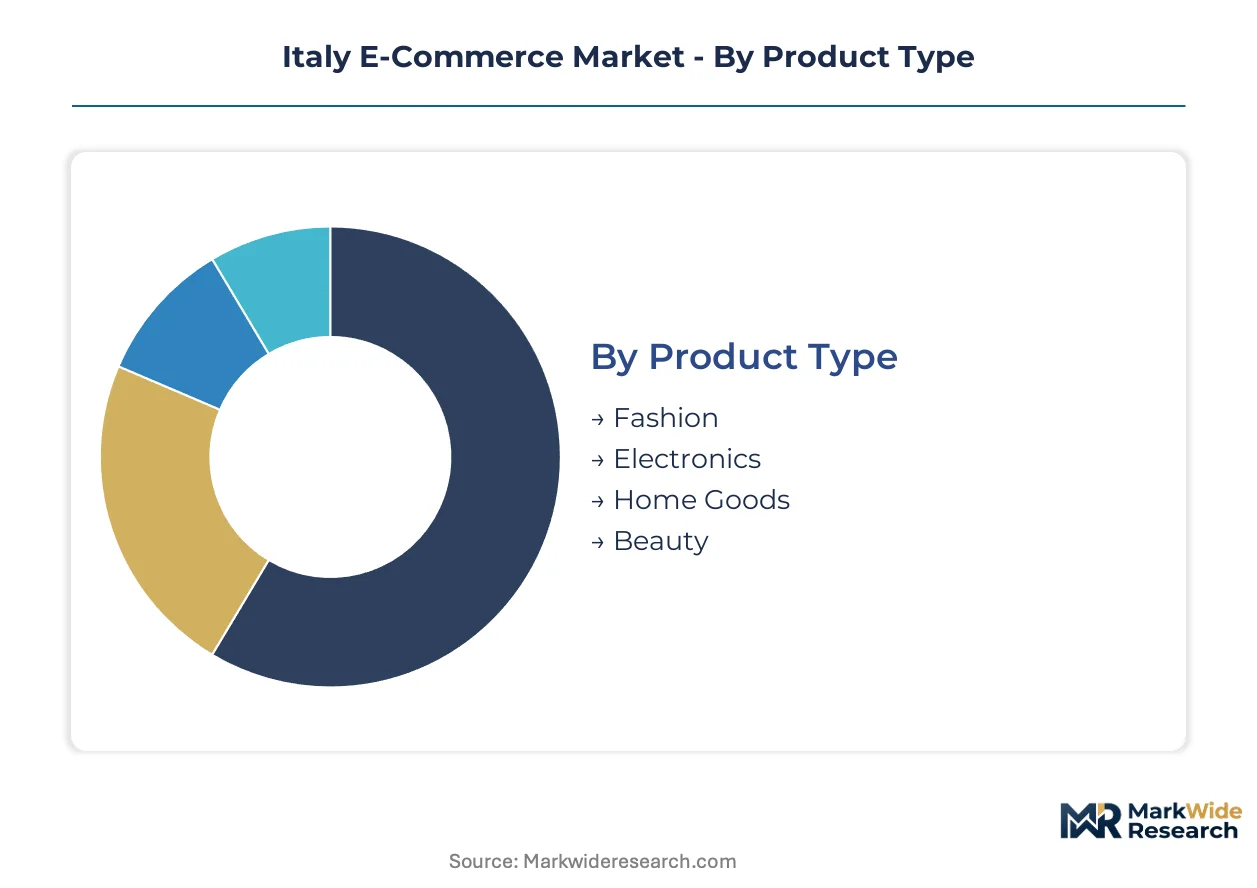
Italian e-commerce segments reveal divergent capital requirements and margin structures. Fashion and electronics command premium fulfillment investments while B2B procurement platforms reshape industrial purchasing workflows. Payment and delivery infrastructure choices directly determine customer acquisition economics and repeat purchase rates.
Product Type:
Fashion absorbs the heaviest upfront investment in photography studios, size-return logistics, and trend-responsive inventory. Electronics demands certification compliance and technical support infrastructure.
- Fashion:Apparel, footwear, and accessories dominate transaction volumes with high return rates averaging 30-40% for online orders. Milan's design houses and Prato's textile suppliers anchor supply, while Zalando's curated marketplace model pressures independent retailers to match flexible return policies and same-day Lombardy delivery.
- Electronics:Smartphones, laptops, and consumer appliances require CE marking compliance and warranty service networks. Demand concentrates in Rome and Milan's tech-savvy demographics, with AGCM enforcement of counterfeit removal protocols forcing marketplace operators to verify authorized distributor status before listing.
- Home Goods:Furniture and décor carry elevated shipping costs due to dimensional weight pricing.
- Beauty:Cosmetics and skincare face strict INCI labeling requirements under EU cosmetics regulation.
Most installed capacity flows through Fashion. Expansion is steepest in Electronics.
Customer Type:
Volume concentration varies sharply by transaction size and procurement sophistication. B2B platforms capture enterprise procurement budgets while D2C brands retain margin control.
- B2C:Individual consumers purchasing through marketplace intermediaries or brand storefronts. Northern Italy's dense urban corridor from Milan to Turin generates the highest per-capita spending, with mobile-first discovery driving impulse purchases in fashion and beauty verticals.
- B2B:Industrial buyers in Emilia-Romagna's manufacturing belt and Veneto's machinery clusters migrate from legacy purchasing to integrated supply platforms. Procurement automation reduces maverick spending and consolidates vendor relationships for mid-sized Italian manufacturers.
- C2C:Peer-to-peer transactions through classified and auction platforms.
- Direct-to-Consumer:Brand-owned storefronts bypassing marketplace commissions.
B2C captures the largest transaction volume base. B2B platforms are climbing the fastest as industrial digitization accelerates.
Payment Method:
Checkout infrastructure investments determine cart completion rates and fraud exposure. Mobile payment rails require API integration but reduce abandonment.
- Credit Cards:Visa and Mastercard networks dominate high-value transactions with chargeback protection. Northern Italian consumers prefer credit for electronics purchases over €500, though PSD2 strong customer authentication adds friction to mobile checkout flows.
- Mobile Payments:Satispay and Nexi-powered wallets collapse checkout steps to biometric confirmation. Adoption concentrates in Milan and Rome's younger demographics, with grocery and fashion verticals seeing measurable abandonment reduction after integration.
- PayPal:Trusted intermediary for cross-border purchases and buyer protection.
- Bank Transfers:SEPA instant payments for high-trust B2B transactions.
Credit card infrastructure holds the most installed processing capacity. Mobile payments are gaining share fastest among under-35 demographics.
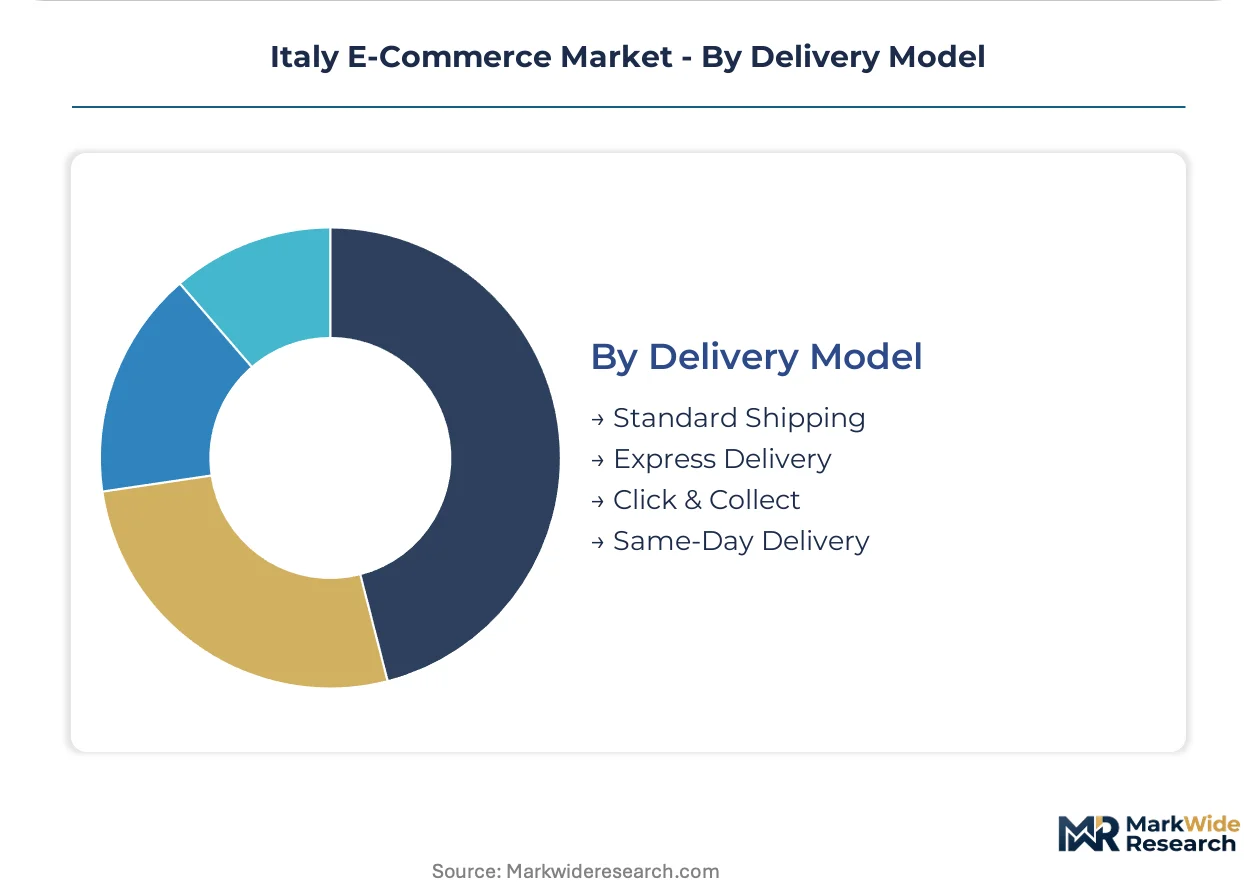
Delivery Model:
Fulfillment capital allocation separates premium experience providers from cost-optimized competitors. Same-day density requires warehouse positioning in expensive urban cores.
- Same-Day Delivery:Courier networks operating within 4-hour windows from micro-fulfillment centers. Amazon.it and grocery chains anchor this segment in Milan's logistics corridor, where intermodal freight nodes enable rapid inventory replenishment and route optimization.
- Click & Collect:In-store pickup from retail locations repurposed as fulfillment nodes. Esselunga and Coop retrofit supermarket networks across northern Italy, blending inventory efficiency with consumer convenience preferences and eliminating last-mile variable costs.
- Standard Shipping:2-5 day delivery through national postal and parcel networks.
- Express Delivery:24-48 hour premium service with tracking and time windows.
Standard shipping retains the broadest installed base. Same-day delivery is expanding most quickly in Lombardy and Lazio.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's e-commerce density exceeds Spain's southern regions yet trails Germany's Ruhr corridor, creating a mid-tier European position where northern logistics investment outpaces southern market development.
Lombardy
Milan's fashion houses and B2B procurement platforms drive transaction concentration, while AGCM enforcement of EU Digital Services Act mandates tightens marketplace compliance protocols. Micro-fulfillment centers cluster around intermodal freight nodes in the Po Valley, enabling same-day delivery density unmatched elsewhere in Italy.
Piedmont
Turin's automotive supply chain digitization accelerates industrial e-commerce adoption among tier-two component suppliers. GDPR-compliant data governance investments filter smaller merchants toward platform-native storefronts. Warehouse robotics penetration in the Alessandria logistics corridor automates high-velocity fashion SKU processing.
Veneto
Venice-Treviso furniture manufacturers migrate catalog distribution to integrated B2B platforms, displacing legacy trade fair channels. EU AI Act conformity assessments reshape recommendation engine deployments for regional marketplace operators. Padua's pharmaceutical cluster experiments with temperature-controlled last-mile delivery networks.
Emilia-Romagna
Bologna's packaging machinery sector anchors Italy's fastest-expanding B2B procurement platform segment, with industrial buyers consolidating vendor relationships through digitized supply channels. Satispay integration into manufacturing payment workflows reduces transaction friction for mid-sized exporters. Parma's food processing belt tests click-and-collect retrofitting for ingredient supply chains.
Lazio
Rome's public administration e-procurement modernization creates spillover demand for B2B platform expertise among SME suppliers. Nexi-powered mobile wallets capture disproportionate share in electronics and beauty verticals among younger demographics. Fiumicino's cargo infrastructure supports cross-border fulfillment for luxury goods exporters targeting Middle Eastern markets.
Italy E-Commerce Market Competitive Environment
Top-tier vendors anchor Milan's logistics corridor, while mid-market specialists concentrate in category-specific verticals with narrower geographic footprints. The competitive structure splits between fulfillment-heavy generalists and curation-focused fashion platforms. Three archetypes dominate: infrastructure-integrated marketplaces, social-native ultra-fast fashion operators, and grocery chains retrofitting physical networks as pickup nodes. M&A activity concentrates on last-mile logistics acquisitions, while strategic partnerships between payment rails and marketplace operators reshape checkout economics.
Among infrastructure-integrated operators, Amazon.it exemplifies the fulfillment-density archetype through its northern Italian warehouse network. Zalando occupies a position within the curated fashion tier, leveraging flexible return policies to sustain brand loyalty. Shein represents the social-native ultra-fast fashion model, competing through rapid trend cycles and algorithmic merchandising rather than owned logistics assets.
| Leading Market Players |
|---|
| Amazon.it |
| Shein |
| Zalando |
| eBay |
| Subito |
| Esselunga |
| Apple |
| Temu |
| Unieuro |
| Others |
Value Chain & Pricing Dynamics
Industrial warehouse rental indices across Lombardy's Po Valley corridor cascade through Italian e-commerce fulfillment economics, compressing margins for same-day delivery operators while elevating pricing power for platform-integrated sellers with captive logistics assets.
Pricing Analysis
Capacity additions in Milan's micro-fulfillment corridor are reshaping price floors for last-mile delivery services, forcing independent merchants toward platform-native storefronts. Three-tier pricing structure across premium, standard, and economy levels separates Amazon.it's same-day subscribers from Esselunga's click-and-collect users from postal standard-shipping customers. Price differentiation hinges on delivery speed guarantees and return policy flexibility. Pricing pressure stems from Satispay's zero-merchant-fee model disrupting traditional payment processing economics. B2C fashion buyers exhibit highest price sensitivity, while B2B procurement platforms in Emilia-Romagna demonstrate lowest sensitivity due to workflow integration value.
Supply Chain Analysis
Dual-sourcing mandates from AGCM compliance protocols require marketplace operators to qualify multiple logistics providers for EU Digital Services Act liability coverage. Geographic supply concentration centers on China for electronics components, Bangladesh for textile inputs, and Germany for warehouse automation equipment. Raw material dependencies span semiconductor chips, synthetic fabrics, and corrugated packaging. Supply chain risk concentrates in single-source vulnerability for CE-certified electronics distributors. Distribution runs through Amazon.it's northern Italian fulfillment network, Zalando's European cross-border hubs, and Coop's retrofitted grocery pickup nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italian e-commerce represents a late-cycle quality story as industrial buyers prioritize GDPR-compliant procurement platforms over cost-optimized commodity marketplaces, rewarding vendors with certified data governance infrastructure.
For Market Incumbents: Extend same-day delivery density through micro-fulfillment expansion in Turin and Verona before Satispay-integrated competitors capture Lombardy periphery. Consolidate seller verification capabilities to preempt AGCM enforcement actions on counterfeit liability. Vertical integration into warehouse robotics through Alessandria corridor partnerships reduces per-unit handling costs against Shein's asset-light model. For New Entrants and Emerging Players: Begin with B2B procurement platforms targeting Parma's food processing belt, where legacy purchasing channels retain 60% share. Southern Italy's Campania and Sicily corridors offer white-space opportunity with 40-60% penetration gaps versus northern benchmarks. Go-to-market leverage rests on Satispay-native checkout integration and Esselunga pickup node partnerships. For Investors and Strategic Acquirers: Asymmetric upside sits with GDPR-certified logistics specialists serving AGCM-regulated marketplace operators. Five-to-ten year viability favors platforms with captive warehousing in Milan-Turin corridor and B2B procurement automation capabilities. Watch for Satispay merchant acquisition rates as inflection indicator for platform dependency shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Micro-Fulfillment Expansion | Same-day density in Lombardy corridor defends against Amazon.it infrastructure advantage. |
| GDPR Compliance Certification | AGCM enforcement of EU Digital Services Act mandates elevates certified platform economics. |
| B2B Procurement Platform Launch | Emilia-Romagna manufacturing belt migration from legacy channels captures enterprise budgets. |
| Click-and-Collect Network Retrofit | Coop and Esselunga store conversions eliminate last-mile variable costs in grocery vertical. |
| Warehouse Robotics Deployment | Po Valley autonomous mobile robot adoption compresses fashion SKU handling costs. |
Study Parameters
Direct dialogue with marketplace operations directors, AGCM compliance officers, logistics procurement leads, and Satispay integration specialists grounded qualitative findings in operational reality. Secondary validation drew from EU Digital Services Act regulatory filings, AGCM enforcement decisions, Nexi transaction volume disclosures, and Lombardy industrial real estate leasing data. Bottom-up merchant surveys across Milan, Turin, and Bologna triangulated against top-down platform revenue estimates.
Segment-level outputs across product type, customer archetype, payment rail, and delivery model were stress-tested against warehouse robotics deployment rates and B2B procurement platform adoption curves. CAGRs were derived from logistics capacity expansion schedules and mobile payment penetration trajectories rather than extrapolated historical trends. Forecast inputs incorporated EU AI Act conformity assessment timelines and Alpine topography constraints on last-mile routing algorithms.
Caveats apply where AGCM enforcement intensity or EU AI Act implementation delays could materially shift the outlook. Deviation in Satispay merchant acquisition velocity or Amazon.it warehouse expansion pacing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Global Healthcare E-Commerce Market
E-Commerce Solutions
M-Commerce Market
E-Commerce Solutions
Omnichannel Commerce Software Market
E-Commerce Solutions
Serbia E-Commerce Market
E-Commerce Solutions
Indonesia E-Services Market
E-Commerce Solutions
Czech Republic E-Commerce Market
E-Commerce Solutions
New Zealand E-Commerce Market
E-Commerce Solutions
Slovenia E-Commerce Market
E-Commerce Solutions
3D Interactive Ticketing Solutions Market
E-Commerce Solutions
Online on-Demand Laundry Service Market
E-Commerce Solutions
Indonesia Ecommerce Logistics Market
E-Commerce Solutions
US Pharma E-Commerce Market
E-Commerce Solutions
Philippines E-Commerce Market
E-Commerce Solutions
Ireland E-Commerce Market
E-Commerce Solutions
Saudi Arabia E-Commerce Market
E-Commerce Solutions
Global Ecommerce Platform Market