
 Polysorbate 40 Market | 2026-2036
Polysorbate 40 Market Size, Share, and Industry Trends Forecast 2026-2036
Polysorbate 40 Market Analytics
REACH compliance is rebalancing the cost-of-entry calculus for European suppliers of polysorbate 40, forcing investment in traceability systems and impurity profiling that smaller traders cannot absorb. BASF SE leverages its integrated oleochemicals network to control feedstock costs across multiple production sites. Lonza Group AG anchors its position through pharmaceutical-grade certification that meets FDA and EMA excipient guidelines simultaneously. Croda International Plc differentiates via bio-based sourcing credentials that align with customer sustainability mandates.
Polysorbate 40 is a polyoxyethylene sorbitan monopalmitate nonionic surfactant with a hydrophilic-lipophilic balance near 15.6, synthesized through esterification of sorbitan with palmitic acid followed by ethoxylation; it functions primarily as an emulsifier and stabilizer in oil-in-water systems across food, pharmaceutical, and cosmetic matrices. Pharmaceutical Grade commands the deepest margin pool due to endotoxin and peroxide specification thresholds that exclude commodity producers, while Food Grade sustains volume leadership through bakery and dairy applications. The Emulsifier application dominates functional demand, though Surfactant use in topical formulations is expanding fastest as cosmetic brands reformulate away from ethoxylated alternatives with higher 1,4-dioxane risk profiles.
The US FDA, EMA, and China's NMPA collectively govern polysorbate 40 market access through divergent pharmacopeial monographs—USP-NF, Ph. Eur., and ChP—that create compliance fragmentation for multinational suppliers. ISO 10993 biocompatibility testing and ICH Q3D elemental impurity guidelines add further qualification layers for pharmaceutical-grade material. Stakeholders must monitor how regional pharmacopeia harmonization efforts and emerging nitrosamine contamination protocols reshape specification requirements and supplier qualification timelines.
Market Dynamics
Pharmaceutical-grade polysorbate 40 supply is tightening as FDA and EMA excipient purity standards diverge on peroxide and endotoxin thresholds, forcing dual-track qualification investments that favor integrated oleochemical producers over commodity traders.
Growth Catalysts
- Biologics Stabilization Demand:Protein-based therapeutics manufacturing is absorbing pharmaceutical-grade volumes as monoclonal antibody formulations require polysorbate 40 for aggregation prevention during freeze-thaw cycles.
- REACH Compliance Barriers:ECHA registration requirements for ethoxylated surfactants are culling marginal European suppliers and consolidating share among analytical-capability leaders.
- China Vaccine Localization:NMPA-qualified domestic producers are displacing imported excipients as Sinovac and Sinopharm build captive supply chains for COVID-19 and influenza vaccine adjuvants.
Market Restraints
- Palmitic Acid Feedstock Volatility:Malaysian and Indonesian palm oil price swings transmit directly to polysorbate 40 production economics, compressing margins for non-integrated formulators.
- Ethoxylation Capacity Concentration:Contract ethoxylators in the US Gulf Coast and Rotterdam harbor zone control critical processing infrastructure, creating chokepoint risk for specialty-grade output.
- 1,4-Dioxane Contamination Scrutiny:California Proposition 65 litigation and EU CLP reclassification of trace dioxane are elevating analytical costs and liability exposure for cosmetic-grade applications.
Strategic Opportunities
- India CDMO Expansion:CDSCO's accelerated excipient approval pathways for export-oriented biologics facilities are opening qualification windows for pharmaceutical-grade suppliers near Hyderabad and Bengaluru clusters.
- Bio-Based Sorbitol Feedstocks:Catalytic hydrogenation of wheat and tapioca-derived glucose is integrating into European production lines to meet EU Green Deal renewable content mandates.
- Continuous Processing Adoption:Micro-reactor ethoxylation technology is reducing batch-to-batch variability and enabling real-time release testing that compresses pharmaceutical customer qualification timelines.
Industry Challenges
- Analytical Chemist Scarcity:ICP-MS and GC-MS expertise for elemental impurity and nitrosamine detection is commanding premium wages, delaying method validation for smaller producers.
- Multinational Pharmacopeia Divergence:Simultaneous compliance with USP-NF, Ph. Eur., and ChP monographs requires redundant stability testing protocols that extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polysorbate 40 Market |
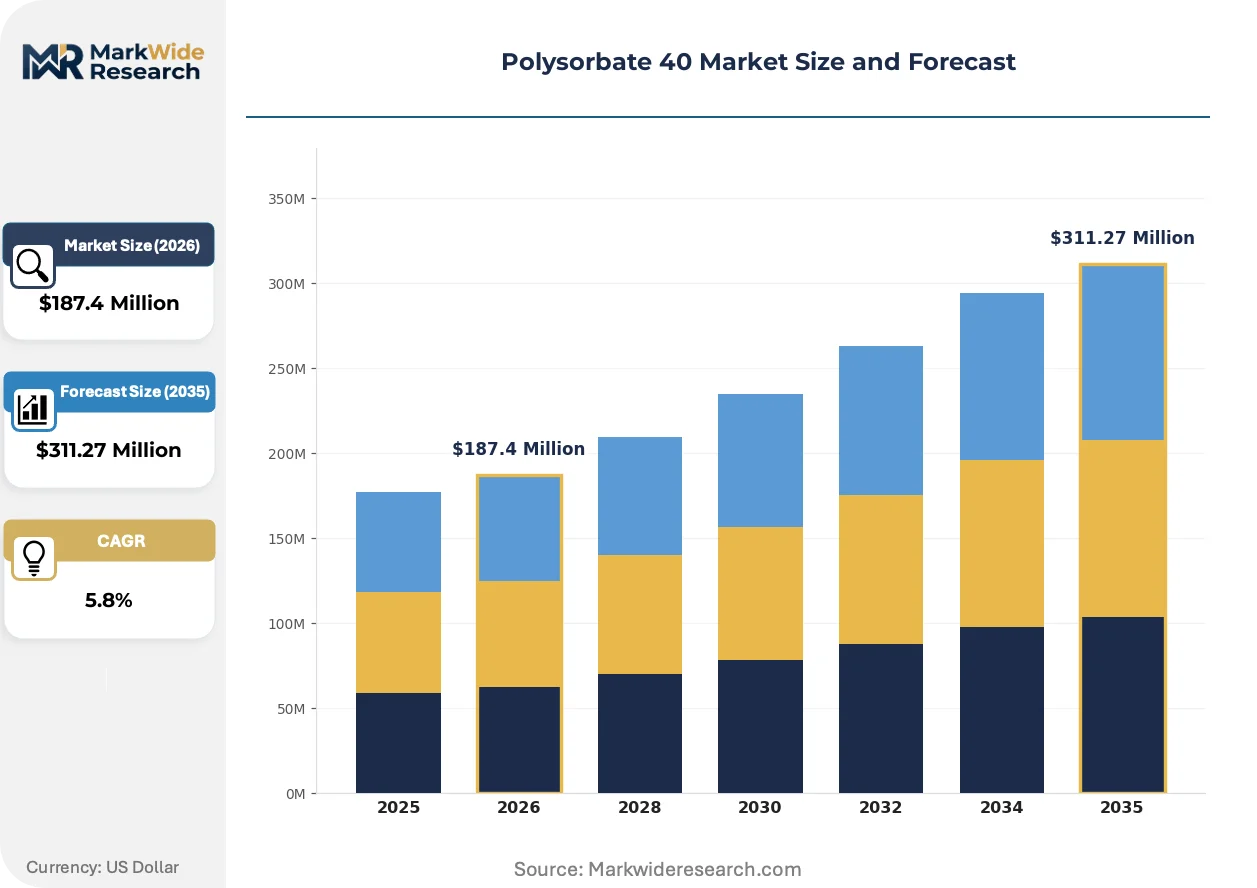
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Cosmetic Grade, Industrial Grade Application: Emulsifier, Stabilizer, Surfactant, Thickening Agent End User: Food & Beverage, Cosmetics, Pharmaceuticals, Chemical Manufacturing Distribution Channel: Direct Sales, Online Sales, Distributors, Retail |
| Companies Covered | BASF SE, Lonza Group AG, Kao Corporation, Huntsman Corporation, Fine Organics, Croda International Plc, Mohini Organics Pvt. Ltd., Solvay SA, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polysorbate 40 Market Evolving Landscape
Polysorbate 40 manufacturing is pivoting toward closed-system processing and renewable feedstock verification as pharmaceutical customers embed sustainability metrics into supplier scorecards alongside traditional purity specifications.
Membrane filtration technology is integrating into downstream purification trains to replace traditional activated carbon treatments for peroxide and aldehyde removal. Lonza and BASF are retrofitting multi-purpose surfactant lines with tangential flow filtration skids that reduce solvent consumption and improve batch consistency. This integration is compressing the capital cost gap between pharmaceutical-grade and food-grade production, enabling mid-tier suppliers to pursue dual-certification strategies.
EMA's 2023 update to nitrosamine risk assessment guidelines for excipients is forcing polysorbate 40 suppliers to implement secondary amine screening and nitrosation inhibitor protocols. The industrial consequence is a bifurcation between suppliers with in-house LC-MS/MS capability and those dependent on third-party testing. Pharmaceutical-grade material destined for parenteral applications is bearing the heaviest compliance burden, with some formulators switching to polysorbate 80 where monograph flexibility permits.
Cosmetic brands are compressing supplier rosters from multi-source commodity purchasing to single-source pharmaceutical-grade partnerships with full batch traceability. L'Oréal and Estée Lauder procurement teams are auditing ethoxylation reactor conditions and feedstock provenance as direct extensions of finished-product safety claims. This consolidation is most visible in Western European markets where Sephora and Douglas distribution networks amplify brand accountability pressures.
Polysorbate 40 Market Segmentation
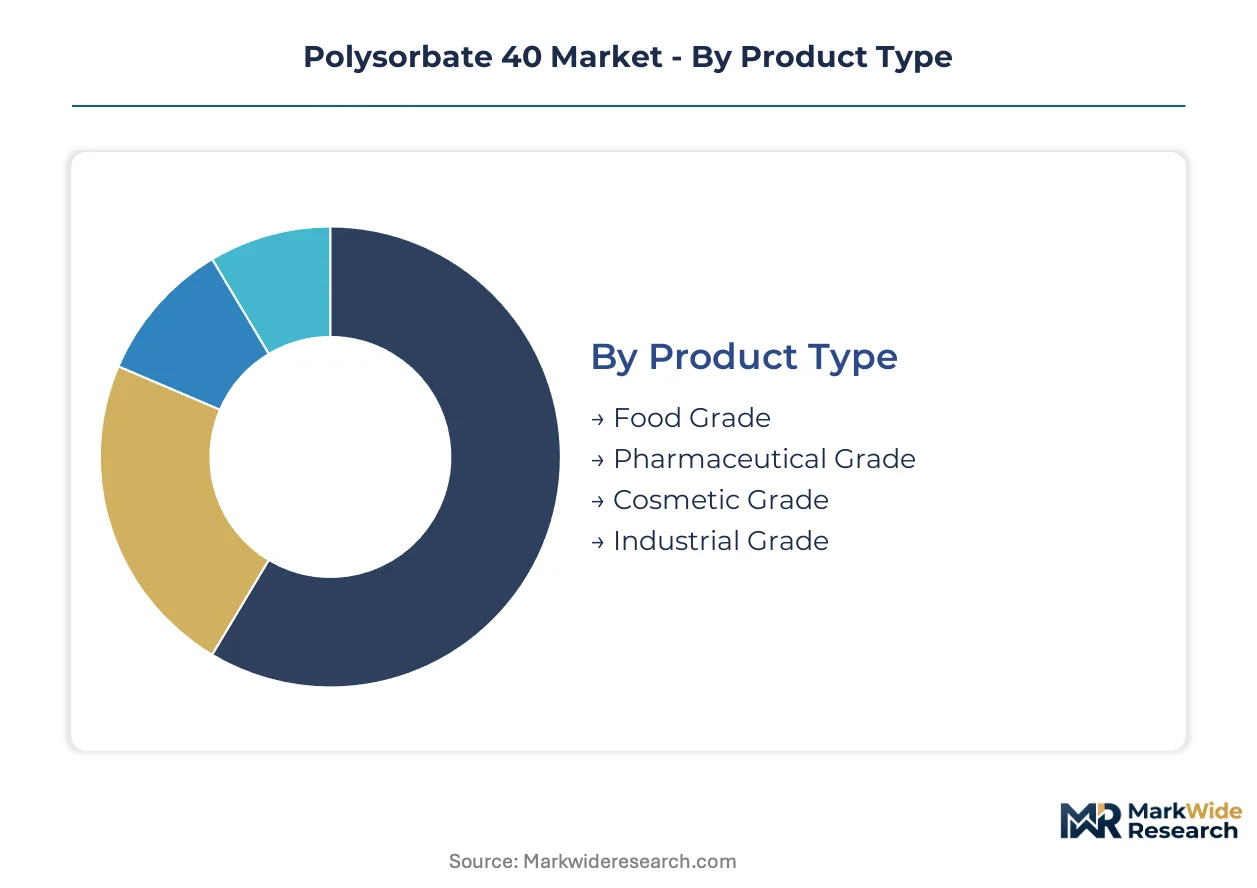
Polysorbate 40 specifications diverge sharply across grades, with endotoxin thresholds and peroxide limits determining access to pharmaceutical value pools. Grade purity dictates qualification timelines and customer switching costs.
Product Type:
Specification thresholds separate commodity supply from certified pharmaceutical channels.
- Food Grade:Permits higher peroxide and moisture content per Codex Alimentarius standards. Bakery and dairy processors in Germany and France absorb volume through regional distributors with minimal analytical documentation.
- Pharmaceutical Grade:Enforces USP-NF endotoxin limits below 10 EU/g and peroxide ceilings near 5 meq O₂/kg. Monoclonal antibody formulators at CDMO clusters in Hyderabad and Boston require this grade for parenteral stability.
- Cosmetic Grade:Navigates EU CLP and California Proposition 65 1,4-dioxane thresholds. L'Oréal and Estée Lauder procurement teams audit ethoxylation reactor conditions for trace contamination.
- Industrial Grade:Serves metalworking fluid and textile auxiliary applications with relaxed purity protocols. Price sensitivity dominates purchasing decisions among Southeast Asian manufacturers.
Mature deployment sits with Food Grade. Newer deployment is concentrated in Pharmaceutical Grade.
Application:
Functional roles map directly to formulation complexity and regulatory burden.
- Emulsifier:Oil-in-water stabilization demands hydrophilic-lipophilic balance precision near 15.6. Ice cream and margarine manufacturers in the Netherlands and Wisconsin specify this function for texture consistency.
- Stabilizer:Prevents protein aggregation during freeze-thaw cycles in biologics. FDA-inspected facilities in North Carolina and Massachusetts specify polysorbate 40 for monoclonal antibody shelf-life extension.
- Surfactant:Topical formulations in dermatological creams require low-irritation profiles. Kao Corporation and Shiseido reformulation programs in Japan favor this application for sensitive-skin positioning.
- Thickening Agent:Modifies viscosity in aqueous systems without ionic charge interference. Niche adoption in specialty coatings and personal care gels.
Volume leadership belongs to Emulsifier. Surfactant is climbing the fastest as cosmetic brands exit higher-risk ethoxylated alternatives.
End User:
Customer sophistication determines specification stringency and supplier qualification depth.
- Food & Beverage:Bakery, dairy, and confectionery processors drive commodity-scale consumption. Nestlé and Unilever procurement specifications emphasize kosher and halhal certification alongside HACCP compliance.
- Cosmetics:Clean-beauty mandates and Sephora accountability protocols are compressing supplier rosters. Full batch traceability from palm oil plantation to finished emulsion is becoming standard.
- Pharmaceuticals:Parenteral and vaccine applications impose ICH Q3D elemental impurity guidelines and ISO 10993 biocompatibility testing. Sinovac and Sinopharm localization programs in China are qualifying domestic sources.
- Chemical Manufacturing:Industrial surfactant blending and agrochemical formulation absorb lower-purity volumes. Price elasticity exceeds specification sensitivity.
Margin concentration favors Pharmaceuticals. Chemical Manufacturing holds volume scale without value capture.
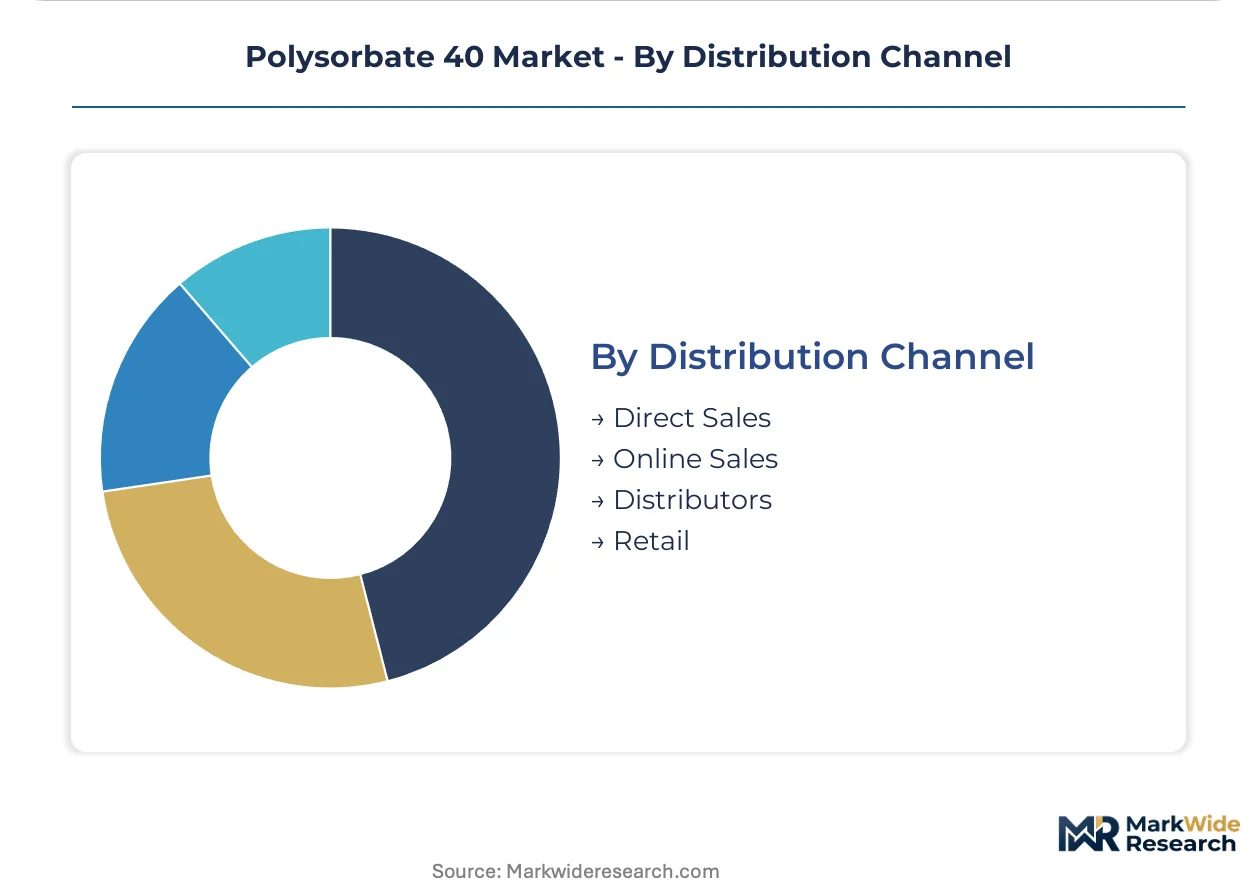
Distribution Channel:
Channel selection reflects customer technical capability and order fragmentation.
- Direct Sales:Pharmaceutical and food multinationals negotiate frame contracts with BASF and Croda for multi-site supply security. Technical service integration justifies premium positioning.
- Online Sales:Cosmetic ingredient marketplaces and specialty chemical platforms serve small-batch formulators. Alibaba and specialty distributors handle COA verification for mid-tier buyers.
- Distributors:Regional chemical distributors stock food and industrial grades for just-in-time delivery. Brenntag and Univar Solutions maintain refrigerated warehousing for peroxide-sensitive inventory.
- Retail:Hobbyist cosmetic formulators and small food processors purchase through specialty ingredient shops. Minimal volume, maximum fragmentation.
Direct Sales anchors pharmaceutical value. Distributors dominate food and industrial throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Jiangsu province excipient parks attract polysorbate 40 producers through VAT rebates and streamlined NMPA pre-approval pathways. This zone architecture concentrates pharmaceutical-grade capacity near vaccine formulators.
United States
Massachusetts and North Carolina biologics clusters consume pharmaceutical-grade volumes for monoclonal antibody stabilization. FDA's tightened peroxide thresholds in USP-NF monographs compel suppliers to upgrade analytical infrastructure. Greater Boston CDMOs specify endotoxin-tested material for parenteral formulations.
Germany
BASF's Ludwigshafen oleochemicals complex integrates backward into palm oil derivatives, insulating production from Malaysian feedstock volatility. REACH registration requirements for ethoxylated surfactants filter marginal traders from the market. Hamburg distributors maintain refrigerated warehousing for peroxide-sensitive pharmaceutical inventory.
China
Sinovac and Sinopharm vaccine localization programs qualify domestic polysorbate 40 sources to displace imports. NMPA's excipient GMP guidelines align with ICH Q3D elemental impurity standards. Jiangsu province excipient parks cluster producers near Wuxi biologics facilities.
India
Hyderabad and Bengaluru CDMO clusters drive pharmaceutical-grade qualification demand for export-oriented biologics. CDSCO's accelerated excipient approval pathways compress supplier onboarding timelines. Gujarat chemical manufacturers expand food-grade capacity for Nestlé and Unilever regional operations.
Japan
Kao Corporation and Shiseido cosmetic reformulations favor polysorbate 40 surfactant applications for sensitive-skin positioning. METI's chemical substance management frameworks impose traceability requirements on ethoxylated surfactants. Osaka-Kobe industrial zone maintains specialty surfactant blending capacity for personal care formulators.
Polysorbate 40 Market Competitive Landscape
German and Swiss producers anchor one tier; Asian specialists hold contract manufacturing and regional supply positions. The vendor base separates into integrated oleochemical majors, pharmaceutical-grade certification leaders, and regional commodity processors. Three archetypes dominate: feedstock-integrated multinationals, analytical-capability specialists, and price-competitive regional formulators. Capacity expansion and dual pharmacopeia qualification represent the dominant competitive moves.
Among integrated oleochemical producers, BASF SE and Evonik Industries AG exemplify the feedstock-control archetype through multi-site production networks. Lonza Group AG occupies a position within the pharmaceutical-grade certification tier, with Croda International Plc representing the sustainability-differentiation vector through bio-based sourcing credentials. These three companies illustrate how competitive positioning fragments across technical capability, supply chain integration, and customer compliance requirements rather than converging on single-factor dominance.
| Leading Market Players |
|---|
| BASF SE |
| Lonza Group AG |
| Kao Corporation |
| Huntsman Corporation |
| Fine Organics |
| Croda International Plc |
| Mohini Organics Pvt. Ltd. |
| Solvay SA |
| Evonik Industries AG |
| Others |
Value Network & Pricing Analysis
ICP-MS and GC-MS analytical chemist scarcity in Germany and Switzerland widens the spread between pharmaceutical-grade premiums and commodity-grade spot pricing, as labor-cost differentials compound with certification overhead to stratify the market into compliance-haves and have-nots.
Pricing Analysis
Short lead-time premiums command substantial markups over standard-contract pharmaceutical-grade polysorbate 40, while spot inventory in Rotterdam and Singapore trades at discounts reflecting peroxide degradation risk. Three-tier pricing structure across pharmaceutical, food, and industrial grades separates certified excipient supply from commodity channels, with endotoxin testing and dual pharmacopeia compliance driving the premium tier. Pricing pressure stems from Malaysian palm oil feedstock volatility transmitting directly to oleochemical derivative margins. Chemical Manufacturing buyers exhibit highest price sensitivity, while parenteral biologics formulators absorb premiums for supply security.
Supply Chain Analysis
Workforce availability constraints in Ludwigshafen, Rotterdam, and Singapore limit expansion of pharmaceutical-grade ethoxylation capacity despite demand absorption from biologics clusters. Supply concentrates in Germany, China, and Malaysia, with backward integration into palm oil derivatives anchoring cost positions for integrated majors. Critical dependencies include Malaysian and Indonesian crude palm oil, sorbitol from wheat and tapioca glucose hydrogenation, and specialized ethoxylation catalysts. Single-source vulnerability runs through US Gulf Coast and Rotterdam harbor zone contract ethoxylators controlling specialty-grade infrastructure. Distribution runs through direct frame contracts for pharmaceutical multinationals and regional chemical distributors for food-grade just-in-time delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polysorbate 40 market access functions as a cost-of-compliance story where EMA's nitrosamine risk assessment guidelines and FDA's tightened peroxide thresholds erect analytical-capability barriers that protect qualified incumbents from commodity competition.
For Market Incumbents: Anchor market position through captive ethoxylation capacity addition in Jiangsu province excipient parks near Wuxi biologics facilities, while simultaneously hardening defenses against nitrosamine contamination litigation through in-house LC-MS/MS screening protocols. Certification investment in simultaneous USP-NF and Ph. Eur. compliance creates switching-cost moats against regional commodity formulators. For New Entrants and Emerging Players: The premium-to-economy price-point gap in pharmaceutical-grade polysorbate 40 opens qualification windows for analytical-capability specialists targeting CDSCO's accelerated excipient approval pathways at Hyderabad and Bengaluru CDMO clusters. White-space concentration sits with export-oriented biologics facilities seeking dual-source security, best accessed through technical service partnerships that compress customer onboarding timelines. For Investors and Strategic Acquirers: Re-rating potential sits with integrated oleochemical producers given nitrosamine protocol implementation and continuous processing adoption as margin-expansion catalysts. Long-term viability favors feedstock-integrated majors with pharmaceutical-grade certification depth over commodity traders exposed to REACH compliance culling. The signal to watch is NMPA qualification velocity for domestic Chinese producers displacing import dependency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Palm Oil Derivatives | BASF's Ludwigshafen complex insulates margin from Malaysian feedstock price swings. |
| Continuous Processing Adoption | Micro-reactor ethoxylation at Lonza reduces batch variability for real-time pharmaceutical release. |
| Dual Pharmacopeia Qualification | Simultaneous USP-NF and Ph. Eur. compliance extends addressable market for certified suppliers. |
| Bio-Based Sorbitol Feedstock Transition | Catalytic hydrogenation of wheat-derived glucose meets EU Green Deal renewable mandates. |
| Nitrosamine Screening Protocol Implementation | In-house LC-MS/MS capability separates pharmaceutical-grade suppliers from third-party dependent traders. |
Research Methodology
Independent corroboration across primary interviews with pharmaceutical formulators, excipient procurement leads, analytical laboratory directors, and oleochemical plant managers underwrites the qualitative findings, validated against secondary sources including USP-NF and Ph. Eur. monograph updates, FDA and EMA excipient guidance documents, customs trade data for palm oil derivatives, and SEC filings from integrated chemical producers. Bottom-up demand modeling from biologics capacity expansion pipelines triangulates against top-down supply-side capacity assessments across ethoxylation reactor networks.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by grade tier, application function, end-use industry, and regional production hub, with CAGRs derived from regression against biologics manufacturing expansion, vaccine production forecasts, and cosmetic formulation reformulation rates. Key inputs include monoclonal antibody pipeline density, NMPA excipient GMP implementation velocity, and REACH registration completion rates for ethoxylated surfactants.
Underlying measurement precision varies by segment; pharmaceutical-grade volume forecasts carry tighter precision than industrial-grade projections given visibility into CDMO frame contracts and regulatory filing pipelines. Forecasts embed assumptions regarding palm oil price stability, nitrosamine protocol harmonization timelines, and regional pharmacopeia convergence that could shift materially. A small set of triggers—NMPA domestic qualification acceleration, EMA nitrosamine limit tightening, and continuous processing technology diffusion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Wetting Agents Market
Surfactants
Global Hydrophobically Modified Alkali Swellable Emulsion (HASE) Market
Surfactants
Isopropyl Myristate Market
Surfactants
Cetanol Market
Surfactants
Sodium Lauroyl Glycinate Market
Surfactants
Global Sodium Lauryl Ether Sulfate [SLES] Market
Surfactants
TEA Esterquats Market
Surfactants
Bio-Based Surfactants Market
Surfactants
Linear Alkylbenzene Sulfonate (LAS) Market
Surfactants
Alkyl Polyglycoside (APG) Market
Surfactants
Trisiloxane Market
Surfactants
Sodium Lauroyl Sarcosinate Market
Surfactants
Cyclotetrasiloxane Market
Surfactants
Surfactant EOR Market
Surfactants
Benzyl Trimethyl Ammonium Chloride Market
Surfactants
Soap Salts Market