
 Global Sodium Lauryl Ether Sulfate [SLES] Market | 2026-2036
Global Sodium Lauryl Ether Sulfate [SLES] Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sodium Lauryl Ether Sulfate [SLES] Market Foresight
Formulation-as-a-service is pivoting how SLES suppliers capture value, with technical support and custom blending subscriptions replacing pure commodity transactions. BASF SE leverages its global technical service network to anchor long-term supply relationships with multinational detergent brands. Galaxy Surfactants Limited dominates the Indian subcontinent through backward integration into fatty alcohol feedstocks and dedicated export infrastructure.
Sodium lauryl ether sulfate is an anionic surfactant produced by ethoxylation of lauryl alcohol followed by sulfation, typically containing two to three moles of ethylene oxide per mole of alcohol and functioning primarily as a foaming and cleansing agent in aqueous formulations. Liquid SLES commands the largest volume share due to its direct pumpability into continuous detergent manufacturing lines, while powder and flake grades attract premium positioning in concentrated personal care formats where water reduction drives freight economics. Industrial cleaners and textile processing represent structurally faster-growing application pools as manufacturing automation raises throughput requirements for high-foam, low-residue surfactant systems.
REACH registration requirements in Europe, EPA Safer Choice certification in the United States, and BIS quality mandates in India collectively elevate compliance costs for non-integrated producers while creating regulatory moats for established compounders. ECHA's persistent scrutiny of ethoxylated surfactant metabolites is forcing reformulation roadmaps across the supplier base. Stakeholders must monitor feedstock volatility in palm kernel and coconut oil derivatives alongside evolving biodegradability thresholds to align capacity decisions with tomorrow's specification regimes.
Market Dynamics
Formulation-as-a-service is restructuring how SLES suppliers capture value, with technical support and custom blending subscriptions displacing pure commodity transactions across the surfactant value chain.
Growth Catalysts
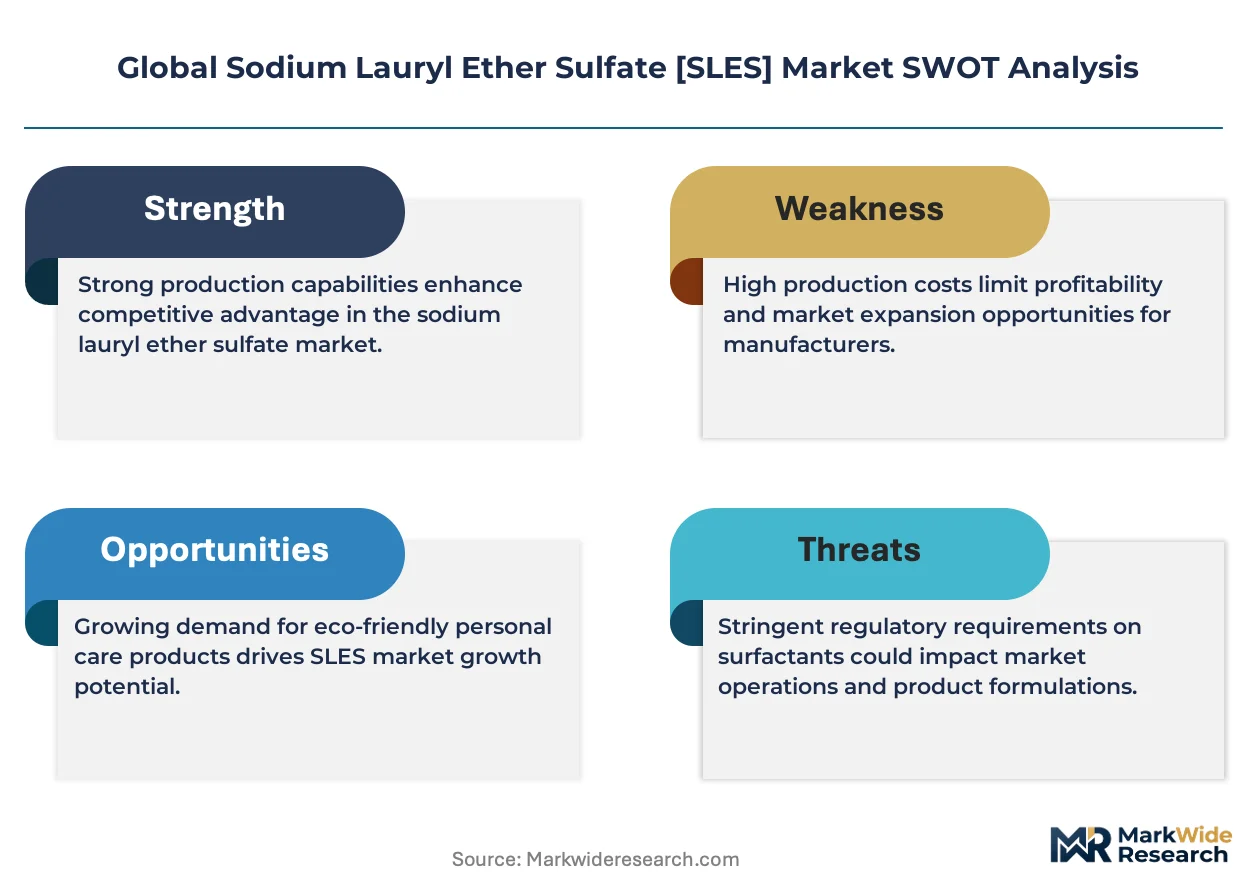
- REACH compliance pressure:ECHA's tightening scrutiny of ethoxylated surfactant metabolites is forcing reformulation roadmaps that favor compliant compounders over non-integrated producers.
- Household detergent concentration:Consumer migration toward compact liquid formats is elevating SLES loading rates per wash cycle in premium home care brands.
- India manufacturing scale-up:Domestic fatty alcohol capacity expansion and dedicated export infrastructure are positioning Indian suppliers to serve Southeast Asian personal care markets.
Market Restraints
- Palm kernel oil volatility:Feedstock price swings in Malaysian and Indonesian oleochemical supply chains compress margin stability for non-backward-integrated compounders.
- Supplier concentration in lauryl alcohol:Southeast Asian oleochemical majors control critical upstream feedstock, creating bottleneck risk for European and North American sulfonation facilities.
- 1,4-dioxane residue thresholds:California Proposition 65 litigation and state-level contamination limits are elevating purification capex for ethoxylated surfactant producers.
Strategic Opportunities
- Brazil personal care penetration:ANVISA regulatory harmonization with EU safety standards is opening formulation export pathways for compliant Asian SLES suppliers.
- EPA Safer Choice certification:Federal procurement preference for certified cleaning products is creating specification moats for qualified surfactant vendors in institutional channels.
- Bio-based ethylene oxide integration:Convergence of sugarcane-derived EO with conventional sulfonation infrastructure is enabling carbon footprint differentiation in premium personal care lines.
Industry Challenges
- Sulfonation reactor engineering talent:Specialized process safety expertise for continuous SO3 sulfonation is scarce outside established German and Indian engineering clusters.
- Multi-jurisdiction registration synchronization:Parallel REACH, EPA TSCA, and BIS filing timelines create compliance drag for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sodium Lauryl Ether Sulfate [SLES] Market |
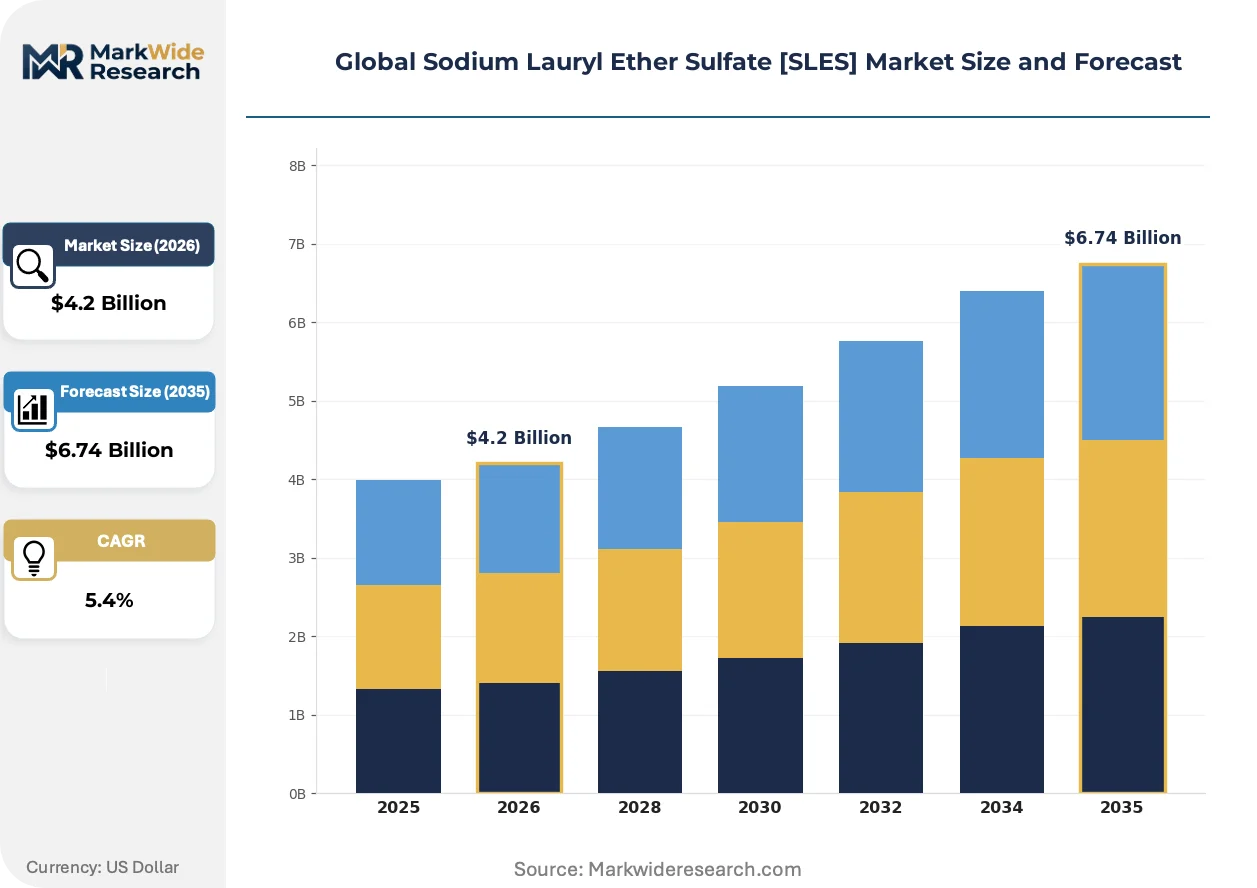
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $6.74 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Flakes, Pastille Application: Personal Care, Household Detergents, Industrial Cleaners, Textile Processing End User Industry: Cosmetics Manufacturers, Chemical Suppliers, Cleaning Service Providers, Textile Producers Packaging Type: Drums, Bags, Bulk Containers, Carboys |
| Companies Covered | Galaxy Surfactants Limited, Evonik Industries AG, BASF SE, Croda International Plc, Clariant AG, Stepan Company, Kao Corporation, Solvay S.A., Huntsman International LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sodium Lauryl Ether Sulfate [SLES] Market Shifts & Advancements
Biodegradability certification is becoming a gatekeeping specification in institutional procurement, with carbon footprint transparency and ethoxylation traceability emerging as parallel differentiators in premium surfactant segments.
Low-1,4-dioxane SLES grades are absorbing capital allocation from legacy sulfonation lines as personal care brands face retailer-driven contamination limits. European and North American formulators are retrofitting molecular distillation capacity at twice the pace of Asian facilities. The technology is absorbing margin pressure from downstream certification requirements while enabling premium positioning in baby care and sensitive-skin applications.
ECHA's persistent evaluation of ethoxylated surfactant metabolites is compressing approval timelines for conventional SLES homolog distributions. Downstream formulators are pre-emptively qualifying alternative ethoxylation ranges to derisk registration non-compliance. Personal care applications in Germany and France are most affected, with local brands accelerating reformulation roadmaps ahead of sunset clause deadlines.
Subscription-based technical service contracts are displacing spot purchasing in multinational detergent procurement. Brand owners are unbundling formulation development from raw material supply, creating recurring revenue pools for compounders with dedicated application laboratories. This pattern is most visible in North American household care, where CPG procurement teams are consolidating vendor panels around full-service surfactant partners.
Global Sodium Lauryl Ether Sulfate [SLES] Market Segmentation
SLES specification tiers determine manufacturing economics and regulatory compliance burdens across downstream value chains. Formulators select grades based on ethoxylation distribution, residual impurity thresholds, and handling characteristics that align with continuous production infrastructure.
Product Type:
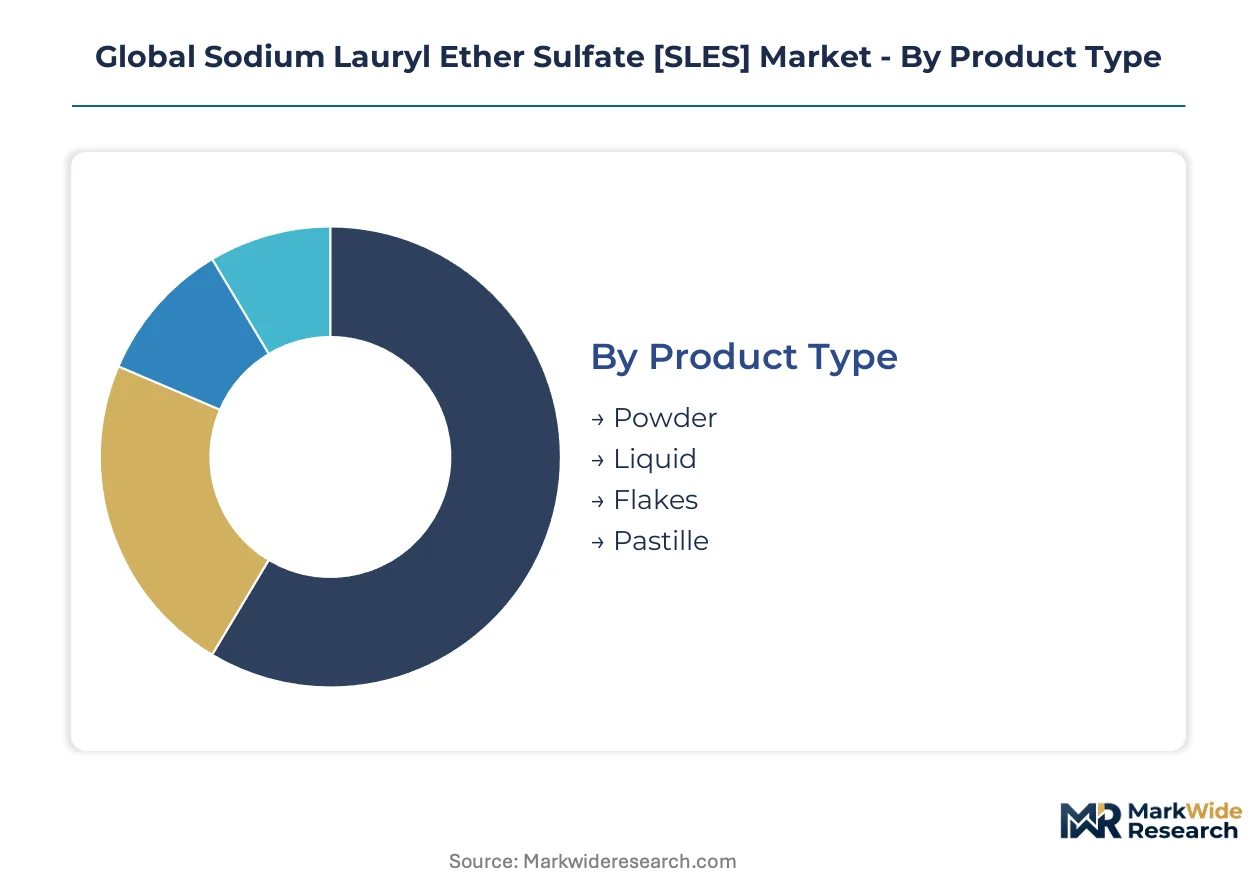
Supply concentration in liquid sulfonation lines shapes competitive positioning across physical form categories, with reactor utilization rates driving margin differentials between integrated and toll-manufactured volumes.
- Liquid:Dominates continuous detergent manufacturing through direct pumpability into automated batching systems. Demand concentrates in German and US household care plants where high-throughput lines favor bulk liquid delivery over solid handling infrastructure.
- Powder:Spray-dried grades enable water-free personal care concentrates with superior freight economics for export formulations. Growth accelerates in Southeast Asian contract manufacturing serving European private label brands seeking carbon footprint reduction through reduced shipping weight.
- Flakes:Low-dust handling properties suit manual compounding operations in small-batch cosmetics manufacturing.
- Pastille:Uniform dissolution kinetics attract premium positioning in specialty industrial cleaner tablets and unit-dose laundry systems.
Today's leader: Liquid. Tomorrow's challenger: Powder.
Application:
Cost tier stratification separates commodity surfactant procurement from specification-grade qualification programs, with personal care commanding premium multiples over institutional cleaning contracts.
- Household Detergents:Volume anchor consuming standard-grade liquid SLES in concentrated laundry and dish formulations. Procurement concentrates in Unilever and Henkel supply chains where backward-integrated oleochemical captivity limits merchant market access.
- Personal Care:Low-1,4-dioxane specifications and narrow ethoxylation distributions command certification premiums in baby shampoo and sensitive-skin segments. Demand clusters in Mumbai and São Paulo manufacturing hubs serving domestic middle-class expansion.
- Industrial Cleaners:High-foam, low-residue requirements from automated CIP systems in food processing plants drive specification differentiation.
- Textile Processing:Scouring and wetting applications in Bangladesh and Vietnam garment manufacturing favor economical flake grades with tolerant impurity profiles.
Household detergents anchor current volumes. Personal care claims the steepest expansion trajectory through premiumization and emerging market penetration.
End User Industry:
Customer type fragmentation creates diverging service intensity requirements, with cosmetics manufacturers demanding technical support that chemical suppliers rarely replicate.
- Chemical Suppliers:Merchant distributors and toll compounders purchasing bulk liquid for reblending into formulated cleaning products. Procurement leverage concentrates in Rotterdam and Singapore trading hubs with access to multi-origin feedstock arbitrage.
- Cosmetics Manufacturers:Direct qualification relationships with sulfonation facilities for custom ethoxylation ranges and preservative-free certifications. L'Oréal and Estée Lauder supply chains enforce vendor consolidation around audited manufacturing sites.
- Cleaning Service Providers:Institutional purchasers selecting EPA Safer Choice certified grades for federal and municipal contract eligibility.
- Textile Producers:Price-sensitive procurement of standard flake grades through regional distributors with local language technical documentation.
Chemical suppliers dominate transaction volume. Cosmetics manufacturers define margin extraction through specification premiums.
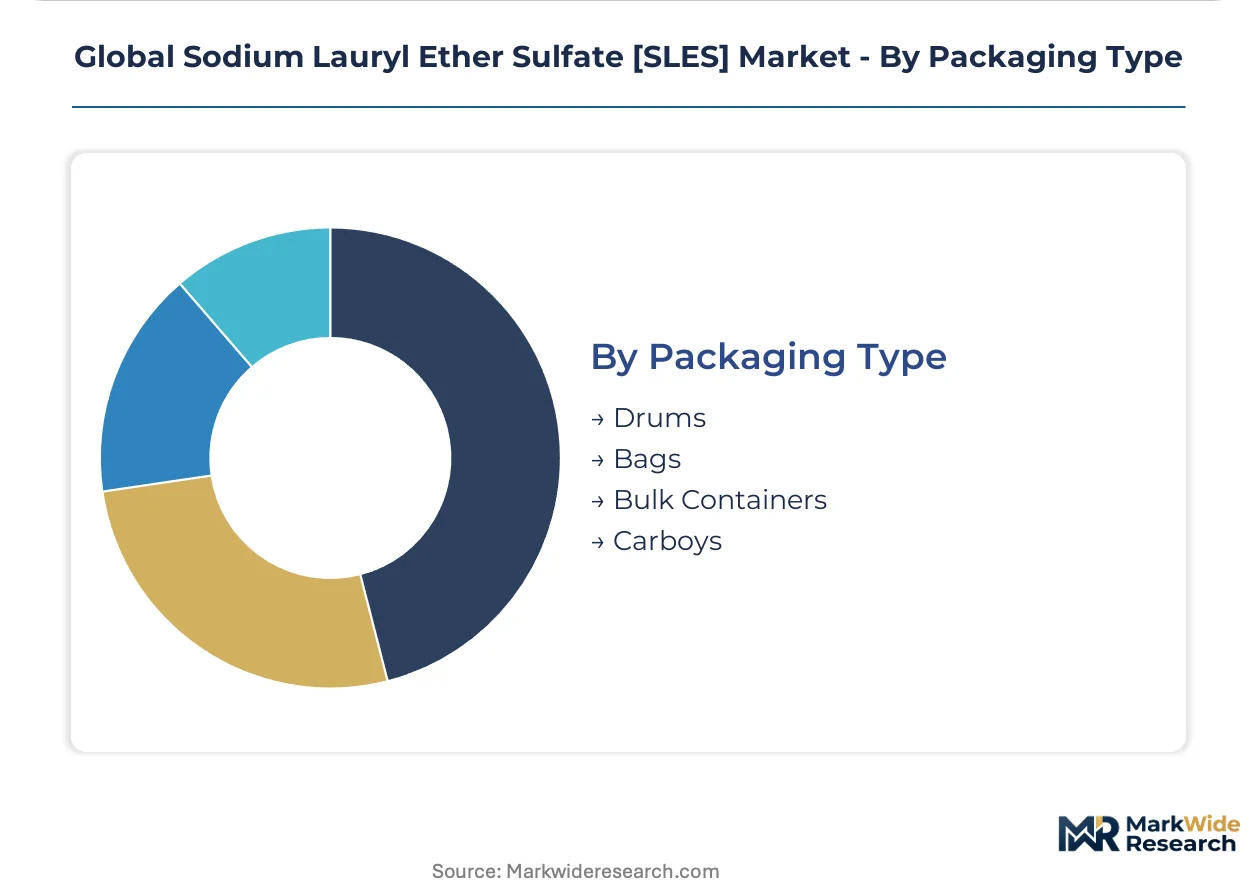
Packaging Type:
Geography determines packaging economics, with drum and carboy prevalence in fragmented markets and bulk infrastructure concentrating in manufacturing clusters with dedicated chemical logistics.
- Bulk Containers:ISO tank and flexitank delivery to continuous manufacturing lines in Basel and Cincinnati detergent plants. Volume concentration enables lowest unit logistics costs for qualified high-volume offtakers with dedicated unloading infrastructure.
- Drums:Standard 200-liter steel and polyethylene containers serving mid-scale compounders without bulk handling capability. Demand persists in Mexican and Indonesian personal care manufacturing where capital constraints limit tank farm investment.
- Bags:Multi-layer laminated sacks for powder and flake grades in textile and industrial cleaner distribution.
- Carboys:20-25 liter polyethylene containers for laboratory sampling and small-batch cosmetics formulators.
Bulk containers lead manufacturing economics. Drum flexibility captures fragmented demand in emerging manufacturing bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium-grade SLES procurement volumes through REACH-compliant household detergent plants, while India scales merchant-market supply through backward-integrated oleochemical infrastructure. Divergent regulatory timelines and feedstock access create distinct competitive terrains across manufacturing clusters.
United States
EPA Safer Choice certification drives institutional cleaning procurement toward qualified surfactant vendors. California Proposition 65 litigation elevates 1,4-dioxane purification requirements for ethoxylated surfactant producers. Cincinnati and Chicago manufacturing corridors concentrate continuous detergent lines favoring bulk liquid SLES delivery through dedicated chemical logistics infrastructure.
Germany
ECHA's persistent evaluation of ethoxylated surfactant metabolites compresses registration timelines for conventional SLES homologs. REACH sunset clauses force reformulation roadmaps among personal care brands in Düsseldorf and Hamburg supply chains. BASF SE anchors technical service relationships with multinational detergent manufacturers seeking compliant compounder partnerships.
India
Domestic fatty alcohol capacity expansion positions Indian suppliers to serve Southeast Asian personal care markets. BIS quality mandates elevate compliance costs for non-integrated producers while creating regulatory moats for established compounders. Galaxy Surfactants Limited dominates the Mumbai-Pune manufacturing belt through dedicated export infrastructure and captive feedstock supply.
Brazil
ANVISA regulatory harmonization with EU safety standards opens formulation export pathways for compliant Asian SLES suppliers. Middle-class expansion in São Paulo and Rio de Janeiro accelerates personal care penetration requiring surfactant qualification programs. Local distributors bridge language barriers for textile processors sourcing economical flake grades.
China
Dual carbon goals and tightening MEE environmental standards reshape sulfonation facility permitting in coastal manufacturing zones. Yangtze River Delta chemical parks concentrate oleochemical derivatives serving domestic detergent brands and export markets. NMPA-aligned cosmetic safety assessments drive vendor consolidation around audited manufacturing sites.
Global Sodium Lauryl Ether Sulfate [SLES] Market Competitive Landscape
Top-tier vendors anchor specification-grade supply through integrated technical service networks, while merchant-market compounders compete on feedstock arbitrage and regional logistics flexibility. The vendor base stratifies across three functional tiers: global compounders with captive oleochemical assets, regional sulfonation specialists serving institutional channels, and toll manufacturers dependent on spot feedstock procurement. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with backward integration into fatty alcohol supply chains emerging as a structural differentiator.
Within the global compounder tier, BASF SE and Evonik Industries AG occupy positions defined by REACH-compliant manufacturing infrastructure and multi-jurisdiction registration portfolios. Galaxy Surfactants Limited exemplifies the regional specialist archetype through Indian subcontinent dominance. These three entities represent divergent strategic postures: German-headquartered integrated chemical conglomerates versus Asia-Pacific feedstock-anchored compounders.
| Leading Market Players |
|---|
| Galaxy Surfactants Limited |
| Evonik Industries AG |
| BASF SE |
| Croda International Plc |
| Clariant AG |
| Stepan Company |
| Kao Corporation |
| Solvay S.A. |
| Huntsman International LLC |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap sulfonation specialists across India and Southeast Asia anchor supply discipline through captive fatty alcohol production, translating upstream cost control into pricing power over merchant-market compounders dependent on spot oleochemical procurement.
Pricing Analysis
Capacity additions in India are reshaping price floors for standard-grade liquid SLES across Asian export corridors. Three-tier pricing structure across low-1,4-dioxane premium, REACH-compliant standard, and economical flake grades separates personal care certification premiums from industrial volume contracts. Pricing pressure stems from Malaysian palm kernel oil volatility compressing margins for non-integrated producers. Institutional cleaning service providers exhibit highest price sensitivity, while cosmetics manufacturers absorb premiums for audited supply chains.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Mumbai orchestrate hub-and-spoke patterns for drum and bulk container fulfillment. Manufacturing concentrates in Germany, India, and China, with each hub serving distinct specification tiers. Feedstock supply draws from Indonesian and Malaysian oleochemical complexes, with coconut and palm kernel oil derivatives feeding sulfonation lines. Single-source vulnerability in lauryl alcohol supply creates bottleneck exposure for European and North American compounders lacking backward integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The SLES market functions as a stable compounder anchored by irreplaceable surfactant demand in household and personal care formulations, with regulatory compliance creating durable moats for qualified producers.
For Market Incumbents: Deepen captive fatty alcohol supply through Southeast Asian plantation partnerships or dedicated ethoxylation capacity investments. Anchor technical service relationships with multinational detergent brands to defend against formulation-as-a-service competitors. Prioritize low-1,4-dioxane purification infrastructure ahead of California Proposition 65 litigation expansion. For New Entrants and Emerging Players: EPA Safer Choice certification in the United States opens a window for compliant Asian suppliers to penetrate federal procurement channels previously blocked by incumbent vendor panels. Target institutional cleaning service providers seeking certified grades for municipal contract eligibility. Pursue toll-manufacturing partnerships with established sulfonation facilities to bypass capital-intensive reactor engineering barriers. For Investors and Strategic Acquirers: Valuations sit cheapest among regional sulfonation specialists with underutilized capacity and untapped export infrastructure. Five-to-ten year viability hinges on feedstock integration depth rather than geographic diversification alone. Monitor ECHA sunset clause timelines for ethoxylated surfactant metabolites as the critical inflection signal for reformulation-driven supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fatty Alcohol | Captive oleochemical supply insulates margin stability against Malaysian palm kernel price swings. |
| Low-1,4-Dioxane Purification Investment | Molecular distillation capacity unlocks premium positioning in baby care and sensitive-skin segments. |
| EPA Safer Choice Certification | Federal procurement preference creates specification moats in institutional cleaning channels. |
| Technical Service Subscription Models | Recurring revenue from formulation development displaces commodity spot purchasing patterns. |
| Southeast Asian Export Infrastructure | Dedicated logistics corridors position Indian suppliers to serve Vietnam and Indonesia personal care growth. |
Research Methodology
Direct dialogue with sulfonation plant managers, procurement leads at multinational detergent brands, distribution channel partners in Rotterdam and Singapore trading hubs, and technical R&D directors at personal care formulators grounded qualitative findings. Secondary validation drew from customs and trade data, Cefic surfactant industry reports, SEC 10-K disclosures from listed chemical producers, and BIS quality mandate documentation. Bottom-up volume modeling triangulated against top-down oleochemical demand estimates.
Segmented outputs across liquid, powder, flake, and pastille physical forms; household detergent, personal care, industrial cleaner, and textile processing applications; and chemical supplier, cosmetics manufacturer, cleaning service provider, and textile producer end-user categories structured the analytical framework. CAGRs were derived from ethoxylation capacity expansion trajectories, REACH registration timelines, and emerging market penetration curves across the projection horizon. Feedstock price elasticity and regulatory compliance cost curves informed scenario boundaries.
Revisions become necessary when ECHA metabolite evaluations accelerate sunset clauses, palm kernel oil supply disruptions exceed historical volatility bands, or ANVISA harmonization timelines in Brazil shift materially. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Cyclopentasiloxane Market
Surfactants
Tetrabutylammonium Bromide Market
Surfactants
Natural Surfactants Market
Surfactants
Polysorbate 40 Market
Surfactants
Superwetting Surfactants Market
Surfactants
Cationic Surfactants Market
Surfactants
Global Oilfield Surfactants Market
Surfactants
Asia Pacific Biosurfactants Market
Surfactants
Alkyl Polyglucosides Market
Surfactants
Global Demulsifiers Market
Surfactants
Glycol Monostearate Market
Surfactants
Microemulsions Market
Surfactants
Non-Ionic Surfactants Market
Surfactants
Green Surfactants Market
Surfactants
Global Barium Petroleum Sulfonate Market
Surfactants
Global Calcium Sulfonate Market