
 Global Detergent Polymers Market | 2026-2036
Global Detergent Polymers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Detergent Polymers Market Analysis
Asian petrochemical producers is expanding detergent polymer capacity to serve surfactant compounders across Southeast Asia and South Asia. BASF SE leverages backward integration into acrylic acid monomers to secure feedstock margins for its dispersant polymer lines. Dow Inc. anchors North American supply through its carbomer and acrylate copolymer manufacturing footprint. Solvay SA specializes in high-performance polycarboxylates for automatic dishwashing tablets, a segment where European formulators dominate procurement.
Detergent polymers encompass water-soluble macromolecules—typically polycarboxylates, polyacrylates, and modified polyethylene glycol derivatives—that function as anti-redeposition agents, viscosity modifiers, and chelating aids in cleaning formulations, with molecular weights ranging from 2,000 to 100,000 Daltons depending on end-use rheology requirements. Synthetic polymers currently occupy the largest revenue pool in product type segmentation, though biodegradable polymers are capturing margin growth as formulators face pressure from ECHA's microplastic restriction proposals. Within application segments, household cleaning sustains the dominant volume position, while industrial cleaning generates premium pricing due to concentrated alkaline formulations requiring thermal stability.
REACH registration requirements govern polymer import and production volumes across European Union member states, compelling non-EU manufacturers to appoint only representatives or establish local tolling partnerships. EPA Safer Choice labeling in the United States steers consumer goods brands toward polymers meeting biodegradability and aquatic toxicity thresholds, narrowing the qualified supplier base. China's GB standards for detergent products mandate specific phosphorus content limits that indirectly favor polycarboxylate builders over traditional phosphate alternatives. Stakeholders must monitor regulatory divergence between jurisdictions where polymer registration obligations fragment compliance costs and reshape competitive access.
Market Dynamics
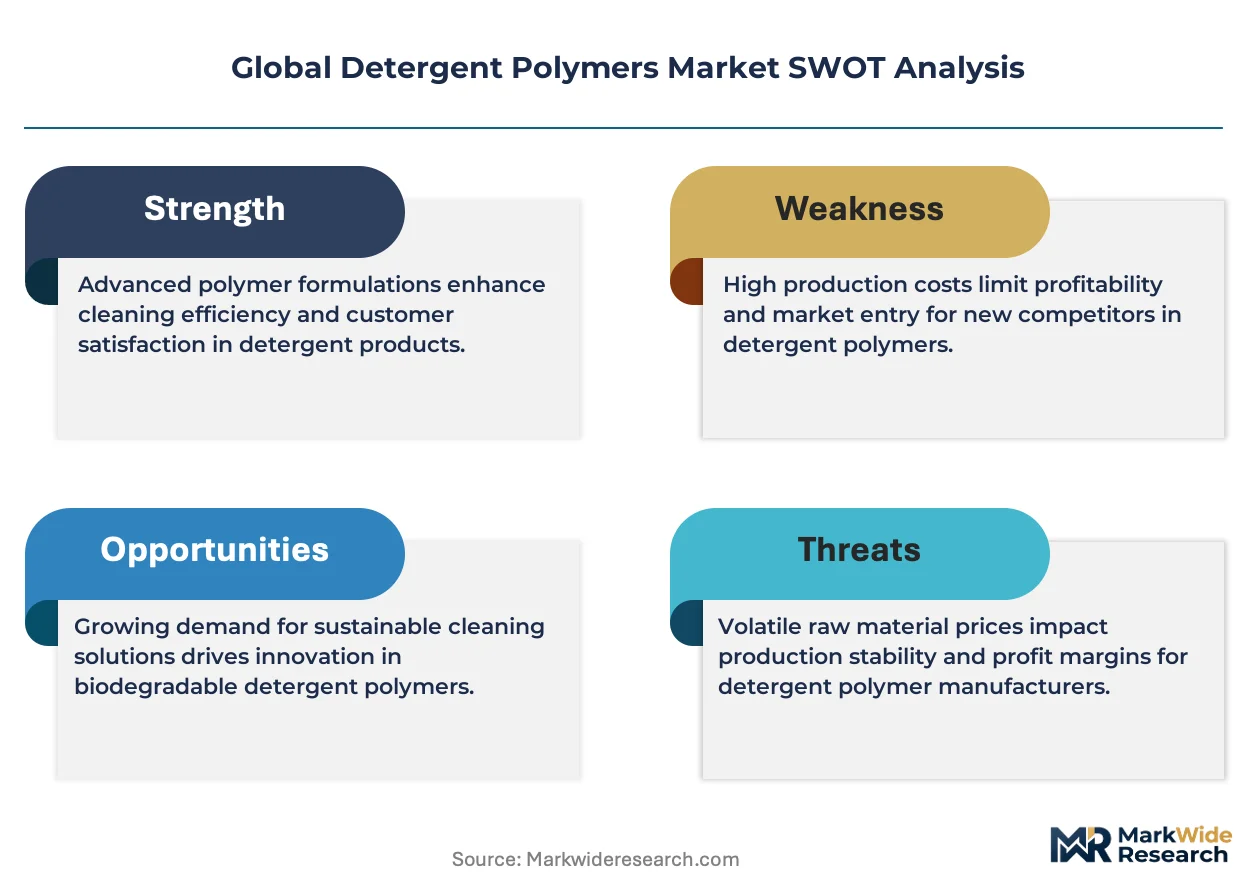
REACH registration requirements and ECHA microplastic restriction proposals are compressing the qualified supplier base, forcing formulators to accelerate biodegradable polymer qualification timelines while synthetic polycarboxylate producers defend incumbent positions through backward integration into acrylic acid feedstocks.
Growth Catalysts
- EU Green Deal mandates:Biodegradable polymer alternatives gain procurement priority as formulators pre-empt ECHA microplastic restrictions in automatic dishwashing and laundry applications.
- Household cleaning concentration:High-efficiency detergent formulations require specialized dispersant polymers with tailored molecular weights for compact liquid and pod formats.
- China's phosphorus limits:GB standards for detergent products indirectly favor polycarboxylate builders over phosphate alternatives, redirecting procurement toward polymer-based chelating systems.
Market Restraints
- Acrylic acid feedstock volatility:Crude oil derivative pricing swings compress margins for polyacrylate manufacturers lacking captive monomer supply.
- German production cluster concentration:BASF SE and Evonik Industries anchor European supply, creating geographic single-point vulnerability for REACH-registered imports.
- Biodegradability performance gap:Current bio-based alternatives fail to match synthetic polycarboxylates on thermal stability in industrial alkaline formulations.
Strategic Opportunities
- India's PLI scheme for specialty chemicals:Domestic detergent polymer capacity expansion targets import substitution for Southeast Asian surfactant compounders.
- EPA Safer Choice labeling:Aquatic toxicity thresholds create first-mover advantage for polymer producers achieving biodegradability certification ahead of US consumer goods brand mandates.
- Automatic dishwashing tablet growth:European formulator dominance in this segment rewards polycarboxylate specialists with high-performance thermal stability specifications.
Industry Challenges
- Polymer registration timeline compression:REACH only representative appointments and dossier preparation strain regulatory affairs capacity at mid-scale producers.
- Legacy formulation integration:Biodegradable polymer drop-in compatibility with existing surfactant systems requires extensive requalification testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Detergent Polymers Market |
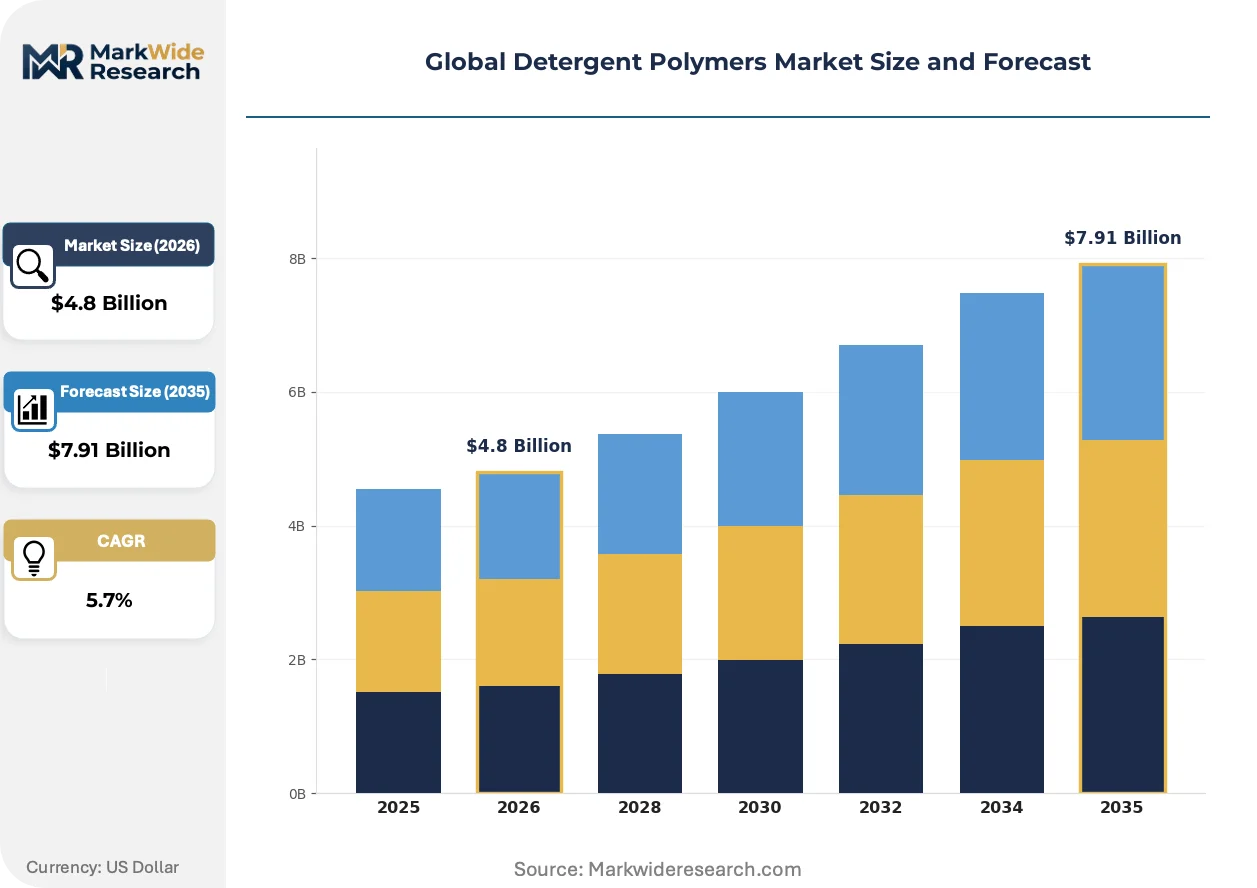
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic Polymers, Biodegradable Polymers, Functional Polymers, Copolymers Application: Household Cleaning, Industrial Cleaning, Personal Care, Textile Care End Use Industry: Consumer Goods, Healthcare, Food and Beverage, Automotive Form: Granular, Liquid, Powder, Gel |
| Companies Covered | BASF SE, Dow Inc., Clariant AG, Solvay SA, Ashland Global Holdings, Lubrizol Corporation, Nouryon, Evonik Industries, Croda International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Detergent Polymers Market Emerging Trajectories
Formulation chemistry is pivoting toward bio-based macromolecular architectures as regulatory pressure intensifies on petroleum-derived synthetics, while procurement patterns concentrate around suppliers with integrated feedstock security.
Enzyme-polymer hybrid systems are expanding into high-performance laundry applications, combining protease and lipase activity with modified polyethylene glycol derivatives to prevent soil redeposition on synthetic fabrics. European premium detergent brands have accelerated adoption of these co-formulated systems. This convergence is expanding into mid-tier household segments previously served by commodity polycarboxylates alone.
REACH polymer registration obligations now govern import volumes across all EU member states, compelling Asian producers to establish tolling partnerships or only representative structures. The compliance cost burden falls heaviest on specialty polymer grades below 1,000 tonne annual volumes. Automatic dishwashing tablet formulators in Germany and France are consolidating procurement around REACH-registered suppliers with established dossier histories.
Direct sourcing from polymer producers is displacing traditional distributor intermediaries among large surfactant compounders seeking technical collaboration on molecular weight customization. This channel compression is most visible in Southeast Asia, where regional detergent manufacturers now engage BASF and Dow technical service teams directly rather than through regional chemical traders.
Global Detergent Polymers Market Segmentation
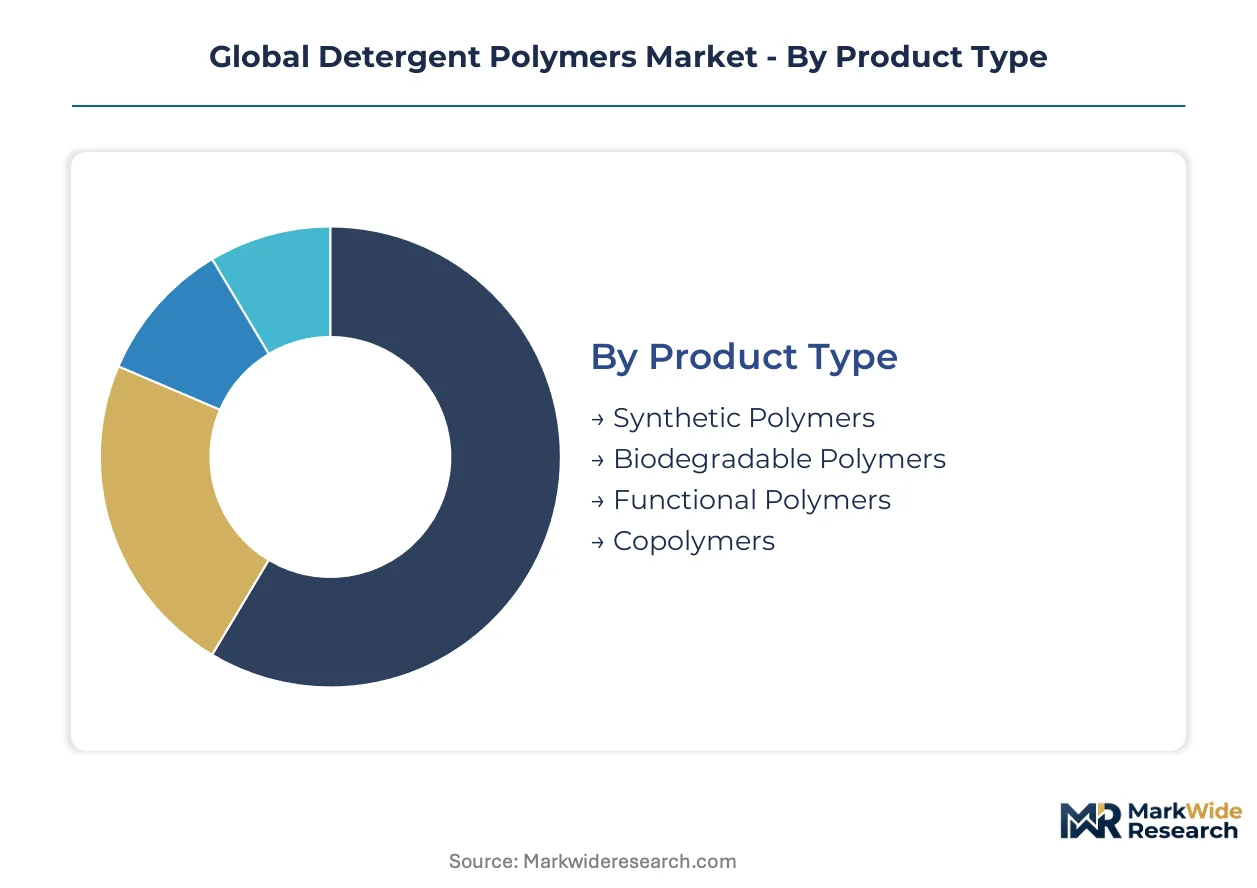
Segmentation in the detergent polymers market determines procurement patterns and margin structures. Polymer architecture, application intensity, and regulatory compliance requirements create distinct commercial zones with divergent investment profiles.
Product Type:
Synthetic polycarboxylate production demands the heaviest capital commitment due to acrylic acid monomer infrastructure and REACH dossier preparation costs.
- Synthetic Polymers:Petroleum-derived polycarboxylates and polyacrylates dominate current manufacturing footprints. German production clusters anchored by BASF SE and Evonik Industries concentrate capacity for these water-soluble macromolecules with molecular weights between 2,000 and 100,000 Daltons.
- Biodegradable Polymers:Bio-based alternatives capture procurement priority as EU Green Deal mandates and ECHA microplastic restrictions reshape formulation requirements. REACH registration timelines compress as formulators accelerate qualification of thermal-stable biodegradable architectures for automatic dishwashing applications.
- Functional Polymers:Modified polyethylene glycol derivatives serve specialized rheology modification roles in concentrated liquid detergents.
- Copolymers:Acrylate-based block structures enable tailored dispersant performance across pH ranges.
Synthetic polymers absorb the bulk of installed capacity; biodegradable alternatives are expanding most quickly.
Application:
Volume concentration and pricing power diverge sharply across cleaning contexts, with thermal stability requirements driving formulation complexity.
- Household Cleaning:Laundry detergents and surface cleaners generate the dominant demand volume for anti-redeposition polymers. China's GB phosphorus limits redirect procurement toward polycarboxylate builders in compact liquid and pod formats across Southeast Asian surfactant compounders.
- Industrial Cleaning:Concentrated alkaline formulations command premium pricing due to stringent thermal stability specifications. Automatic dishwashing tablets in Germany and France consolidate procurement around REACH-registered polycarboxylate specialists.
- Personal Care:Mild surfactant systems employ low-molecular-weight polyacrylates for viscosity control.
- Textile Care:Fabric softener formulations utilize cationic polymer derivatives for fiber conditioning.
Household applications anchor volume procurement; industrial cleaning generates the steepest expansion trajectory in value terms.
End Use Industry:
Regulatory exposure and certification requirements fragment demand across downstream sectors with divergent compliance burdens.
- Consumer Goods:Detergent brands drive specification standards through direct polymer producer engagement, displacing traditional distributor channels. EPA Safer Choice labeling steers procurement toward aquatic-toxicity-compliant grades in the United States.
- Healthcare:Medical device cleaning protocols demand validated polymer residues with documented biocompatibility profiles.
- Food and Beverage:Processing equipment sanitation requires food-contact-approved polymer chemistries under national safety frameworks.
- Automotive:Parts washing operations utilize high-alkaline stable polymers for heavy-duty degreasing formulations.
Consumer goods concentrate procurement volume; healthcare applications are climbing the fastest on regulatory compliance premiums.
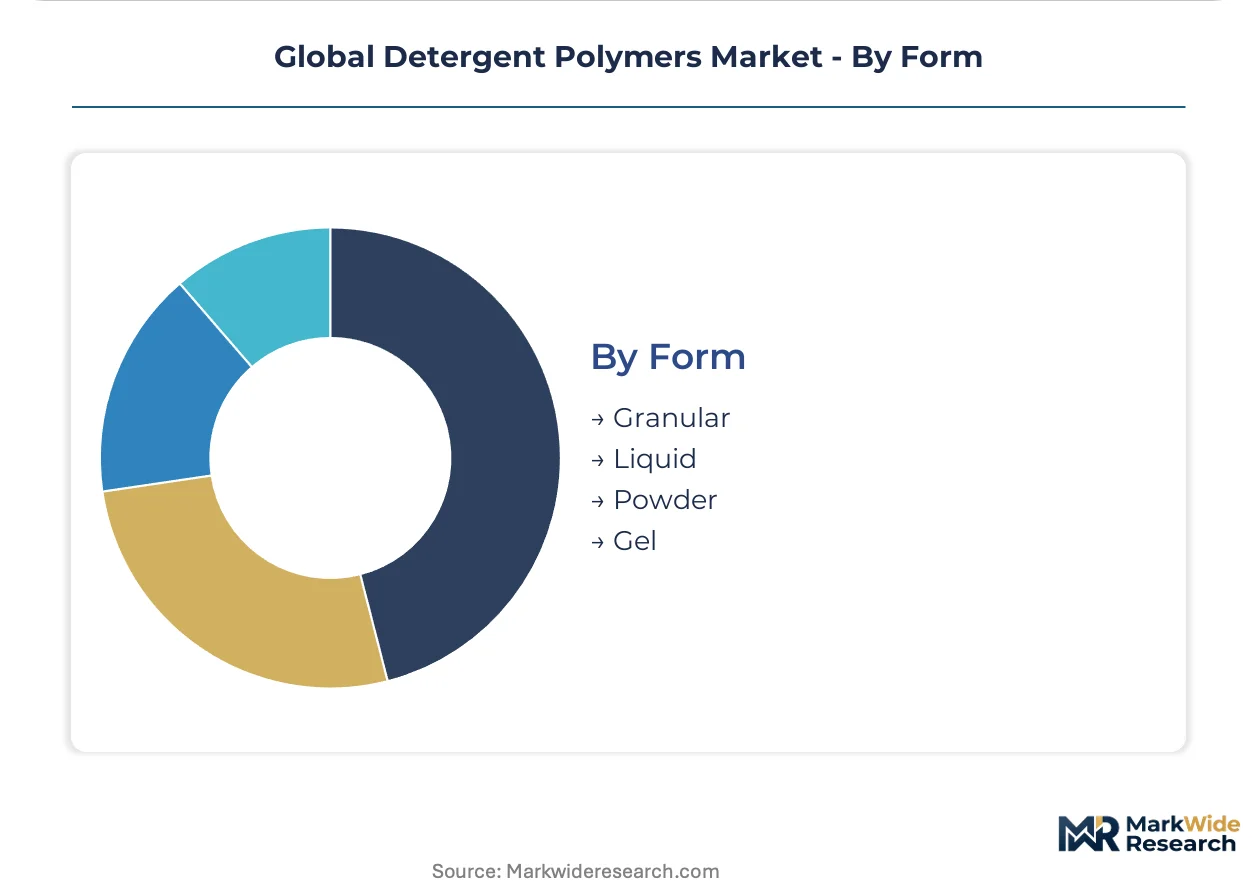
Form:
Physical state determines supply chain configuration and technical service intensity across customer tiers.
- Liquid:Ready-to-pump concentrates dominate high-throughput surfactant compounder operations. Dow Inc.'s carbomer manufacturing footprint anchors North American liquid polymer supply for direct technical collaboration models.
- Granular:Spray-dried polycarboxylate beads serve powder detergent manufacturers with extended shelf stability requirements.
- Powder:Fine-milled grades enable rapid dissolution in cold-water laundry applications.
- Gel:Thixotropic formulations support specialized dispensing systems in institutional cleaning contexts.
Liquid forms command the largest share of active production lines; gel formats are gaining share fastest in automated dosing installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Acrylic acid feedstock security anchors regional production economics, with German petrochemical corridors and US Gulf Coast refineries supplying monomer inputs to polymer conversion facilities.
Germany
Automatic dishwashing tablet formulators in Ludwigshafen and Marl drive polycarboxylate procurement for thermal-stable alkaline formulations. REACH registration dossiers from ECHA govern import volumes for non-EU polymer suppliers. BASF SE and Evonik Industries maintain integrated production clusters along the Rhine corridor, converting captive acrylic acid into dispersant polymer lines.
United States
EPA Safer Choice labeling steers consumer goods brands toward aquatic-toxicity-compliant polymer grades for laundry and surface cleaning applications. Carbomer and acrylate copolymer manufacturing concentrates along the Texas-Louisiana petrochemical belt. Dow Inc. anchors domestic supply through technical service partnerships with direct surfactant compounder engagement.
China
GB standards mandating phosphorus content limits redirect detergent procurement toward polycarboxylate builders over traditional phosphate alternatives. Asian petrochemical producers expand polymer capacity to serve surfactant compounders across Southeast Asia and South Asia. Yangtze River Delta chemical parks host expanding dispersant polymer conversion lines.
India
PLI scheme incentives for specialty chemicals target domestic detergent polymer capacity expansion for import substitution. Maharashtra and Gujarat industrial corridors attract investment in water-soluble macromolecule production. Southeast Asian surfactant compounders increasingly source from Indian manufacturing bases rather than European imports.
France
Premium detergent brands in the Île-de-France region accelerate adoption of enzyme-polymer hybrid systems for high-performance laundry applications. ECHA microplastic restriction proposals compress qualification timelines for biodegradable alternatives. Automatic dishwashing tablet formulators consolidate procurement around REACH-registered suppliers with established regulatory histories.
Global Detergent Polymers Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue biodegradable certification and regional tolling partnerships. The supplier base concentrates around integrated petrochemical conglomerates with captive acrylic acid supply and mid-scale specialty polymer houses dependent on merchant monomer markets. Three archetypes dominate: backward-integrated majors controlling feedstock economics, REACH-registered European specialists defending formulation partnerships, and Asian expansionists capturing Southeast Asian surfactant demand. Competitive moves center on capacity expansion in India and China plus accelerated biodegradable polymer qualification to pre-empt ECHA restrictions.
Within the integrated-major archetype, BASF SE and Dow Inc. exemplify feedstock-secured positioning through acrylic acid monomer control. Evonik Industries occupies a specialist tier focused on high-performance polycarboxylates for thermal-demanding applications. These three entities anchor distinct competitive vectors: German production cluster concentration, North American direct technical service models, and European premium formulation partnerships.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc. |
| Clariant AG |
| Solvay SA |
| Ashland Global Holdings |
| Lubrizol Corporation |
| Nouryon |
| Evonik Industries |
| Croda International |
| Others |
Supply Flow & Price Mechanics
Acrylic acid monomer costs cascade through three pricing tiers as merchant-dependent producers absorb volatility while backward-integrated majors stabilize margins. REACH registration expenses compress mid-scale specialty grades below 1,000 tonne volumes, forcing price stratification between dossier-secured German suppliers and tolling-dependent Asian entrants.
Pricing Analysis
Technical service bundling separates premium polycarboxylate supply from unbundled commodity grades. Three-tier pricing structure across premium, standard, and economy levels reflects REACH certification status, thermal stability specifications, and molecular weight customization depth. Price erosion runs through economy grades as Asian capacity expansion intensifies competition for Southeast Asian surfactant compounders. Large consumer goods brands exhibit lowest price sensitivity, prioritizing formulation partnership continuity over per-kilogram savings.
Supply Chain Analysis
REACH dossier completion gates European market access, filtering qualified suppliers to integrated majors and established specialists. Production concentrates in Germany, the United States, and China, with German Rhine corridor clusters converting captive acrylic acid and Yangtze River Delta parks expanding dispersant polymer lines. Feedstock supply draws from petroleum derivative markets and bio-based monomer pilot streams. Single-source vulnerability concentrates around German production clusters for REACH-registered automatic dishwashing grades. Distribution runs through direct technical service partnerships displacing traditional chemical traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around REACH-registered incumbents as ECHA microplastic restrictions force unqualified producers toward exit. Regulatory compliance costs disproportionately burden mid-scale players lacking integrated feedstock economics.
For Market Incumbents: To counter biodegradable polymer qualification timelines compressing synthetic polycarboxylate demand, accelerate thermal-stable bio-based architectures through R&D partnerships with European premium formulators. Anchor position by expanding tolling partnerships in India under PLI scheme incentives, securing Southeast Asian surfactant compounder procurement before Asian expansionists consolidate regional share.
For New Entrants and Emerging Players: Begin with biodegradable polymer certification targeting EPA Safer Choice thresholds, capturing US consumer goods brand procurement ahead of incumbent requalification cycles. India's specialty chemicals PLI scheme offers the most penetrable geography for import substitution capacity. Pursue direct technical collaboration models with Maharashtra and Gujarat surfactant compounders, bypassing distributor intermediaries that incumbents still employ.
For Investors and Strategic Acquirers: Distressed-cycle entries favor REACH-registered mid-scale specialists in France and Germany with established dossier histories but strained working capital from acrylic acid feedstock volatility. Long-term viability centers on backward integration capability or bio-based polymer pivot optionality. Monitor ECHA microplastic restriction implementation timelines as the critical inflection signal for biodegradable polymer valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Acid | BASF SE and Dow Inc. secure feedstock margins against merchant monomer volatility. |
| Biodegradable Polymer Qualification | Pre-emptive REACH dossier preparation captures EU Green Deal procurement shifts. |
| India PLI Scheme Capacity Expansion | Domestic production targets Southeast Asian surfactant compounder import substitution. |
| Direct Technical Service Partnerships | Channel compression displaces regional chemical traders across ASEAN markets. |
| Enzyme-Polymer Hybrid Co-Development | European premium brands accelerate adoption for high-performance laundry applications. |
Methodological Framework
Independent corroboration across polymer plant managers, procurement leads at surfactant compounders, distribution channel partners, and technical R&D directors underwrites the qualitative findings. Secondary validation draws from customs and trade data, Cefic industry reports, SEC 10-K filings, and REACH registration databases. Bottom-up capacity modeling triangulates against top-down demand aggregation from end-use industry consumption patterns.
Rate-of-change decomposition separates volume growth from value expansion across synthetic versus biodegradable polymer architectures, household versus industrial application intensity, and liquid versus granular physical formats. CAGRs derive from segment-level elasticity modeling against feedstock price scenarios and regulatory implementation timelines. Forecast inputs incorporate acrylic acid monomer supply curves and ECHA restriction proposal adoption probabilities.
Underlying measurement precision varies by segment; REACH-registered synthetic polycarboxylates carry tighter precision than emerging biodegradable alternatives. Forecasts reflect assumptions on regulatory implementation pace and feedstock cost trajectories. A model refresh is warranted upon material change in ECHA microplastic restriction finalization or major acrylic acid supply disruption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Cationic Surfactants Market
Surfactants
Surfactant EOR Market
Surfactants
Global Demulsifiers Market
Surfactants
Disodium Laureth Sulfosuccinate Market
Surfactants
Defoamers Market
Surfactants
Specialty Surfactants Market
Surfactants
Cocamidopropyl Betaine Market
Surfactants
Cetyl Chloride Market
Surfactants
Surfactant Cleansers and Adjuvants Market
Surfactants
Selenium Sulphide Market
Surfactants
Global Saponin Market
Surfactants
North America Non-Ionic Surfactants Market
Surfactants
Global Silicone Surfactants Market
Surfactants
Alkyl Polyglucosides Market
Surfactants
Non-Ionic Surfactants Market
Surfactants
Powder Defoamers Market