
 On-Shelf Availability Solutions Market | 2026-2036
On-Shelf Availability Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
On-Shelf Availability Solutions Market Analytics
Aftermarket service revenue is rewriting value capture in on-shelf availability technology. SAP SE leverages its enterprise software footprint to bundle shelf-analytics with broader retail ERP contracts. Impinj, Inc. anchors the RFID hardware layer with tag and reader specialization for real-time inventory tracking. IBM Corporation competes through hybrid cloud architectures that process edge sensor data in distributed retail environments.
On-shelf availability solutions comprise integrated hardware-software systems that detect product presence, quantity, and placement status using RFID tags, computer vision cameras, IoT weight sensors, or barcode scanners, transmitting telemetry to centralized analytics platforms for stockout alerting and replenishment triggering. RFID technology leads deployment in apparel and electronics retail due to tag cost reductions and bulk-read reliability. Computer vision is expanding fastest among grocery and pharmacy operators seeking planogram compliance verification without physical shelf audits. Analytics tools command the highest margin pools as retailers prioritize predictive demand forecasting over basic inventory visibility.
The EU AI Act classifies automated shelf-monitoring systems by risk tier, imposing conformity requirements on computer vision deployments in European retail spaces. The FDA regulates pharmacy shelf-monitoring accuracy where drug availability tracking intersects with patient safety protocols. Retailers must monitor how NIST cybersecurity frameworks reshape data governance requirements for IoT sensor networks transmitting inventory telemetry across store environments. Stakeholders should evaluate which technology architecture—edge-heavy or cloud-centralized—aligns with emerging compliance obligations before scaling multi-store deployments.
Market Dynamics
Retail labor shortages and margin compression are accelerating deployment of autonomous shelf-monitoring systems that eliminate manual stock checks while tightening inventory accuracy.
Growth Catalysts
- EU AI Act compliance mandates:European retailers face conformity requirements for automated vision systems, creating procurement urgency for certified on-shelf availability platforms that satisfy risk-tier classifications.
- RFID tag cost deflation:Unit economics below five cents per tag in apparel and electronics retail enable item-level tracking at scale, expanding addressable deployment scenarios.
- German supermarket automation investment:Labor cost pressures and 24-hour trading norms in metropolitan stores drive demand for real-time replenishment triggering without human shelf audits.
Market Restraints
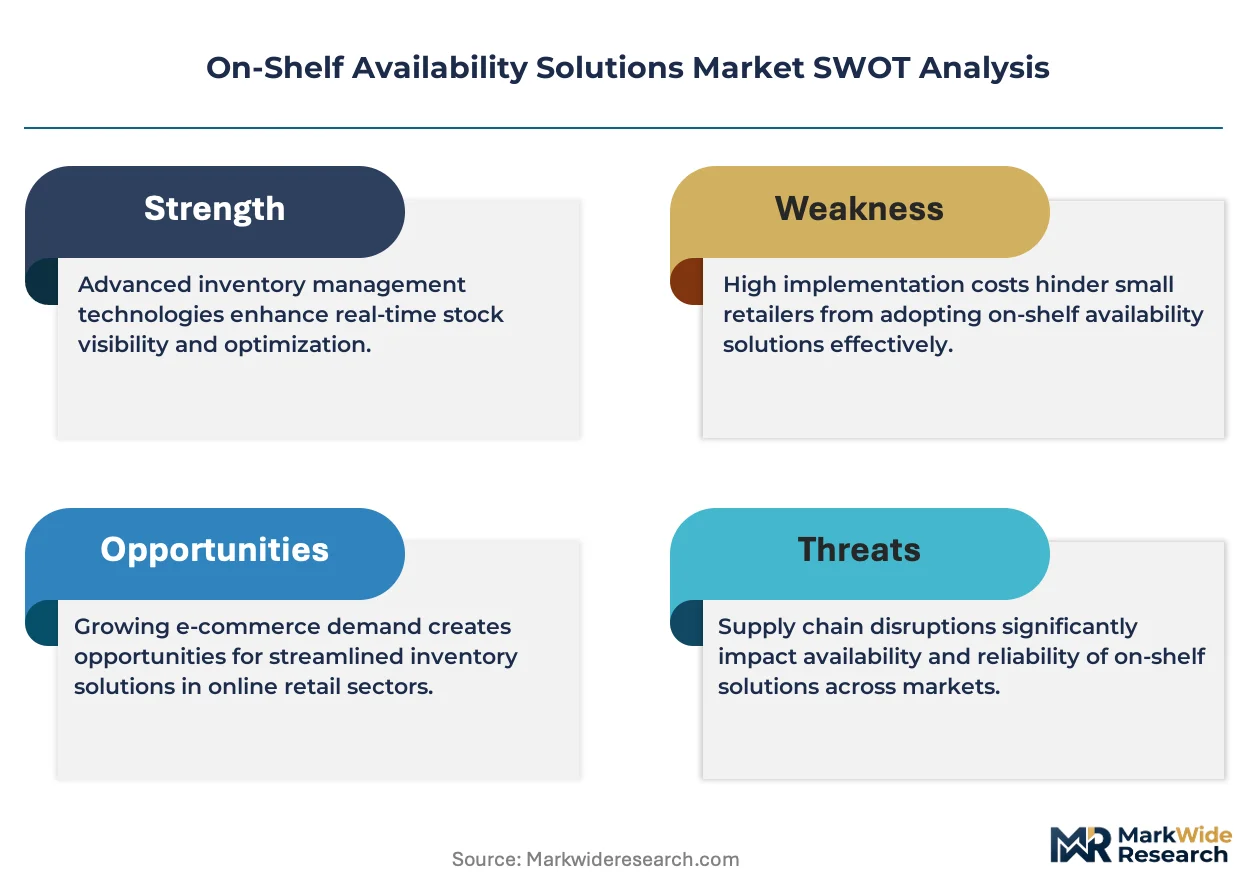
- Computer vision hardware cost concentration:Edge camera arrays and GPU processing units for real-time inference represent substantial upfront capital outlay, slowing adoption among mid-tier grocery operators.
- GDPR data governance friction:Video analytics capturing shopper proximity to shelves triggers strict consent and retention protocols, complicating deployment architecture in European retail spaces.
- Legacy ERP integration complexity:Proprietary inventory management systems in established retail chains resist seamless API connectivity with modern shelf-monitoring telemetry platforms.
Strategic Opportunities
- Pharmacy cold-chain integration:Temperature-sensitive drug tracking combined with on-shelf availability monitoring addresses patient safety protocols regulated by FDA and EMA, opening high-margin vertical specialization.
- India organized retail expansion:Reliance Retail and D-Mart format rollouts create greenfield deployment opportunities without legacy infrastructure constraints.
- Edge-AI chip efficiency gains:Convergence of low-power inference processors and 5G private networks enables camera-only deployments without fiber backhaul, reducing installation costs.
Industry Challenges
- Computer vision model drift:Packaging redesigns and seasonal merchandise rotations degrade detection accuracy, requiring continuous retraining pipelines and labeled dataset maintenance.
- Multi-sensor fusion complexity:Weight sensors, RFID readers, and vision systems generate conflicting stock signals that demand sophisticated arbitration logic, stretching systems integration capabilities.
- ISO/IEC 27001 certification timelines:Retailers mandate information security management system compliance for cloud-connected inventory platforms, extending vendor qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | On-Shelf Availability Solutions Market |
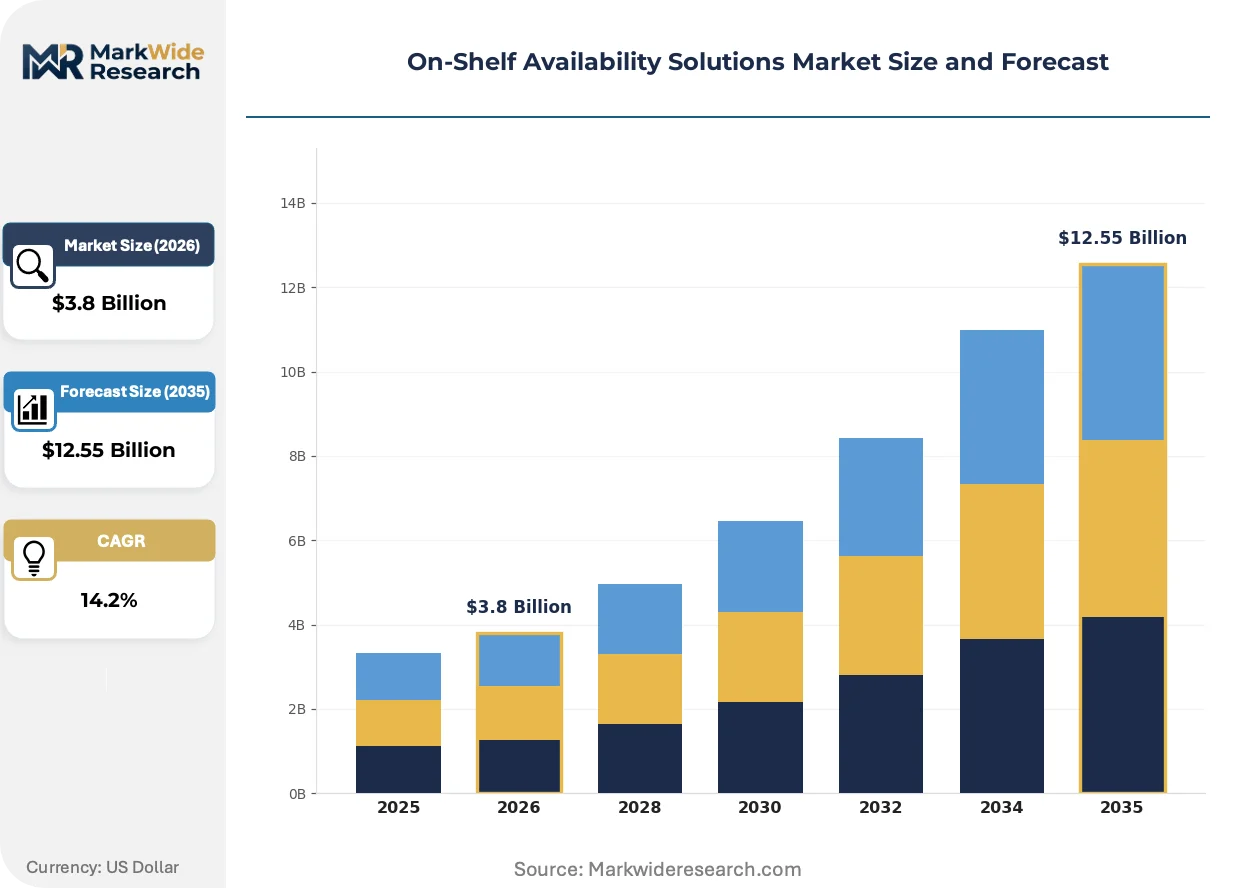
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: RFID, Computer Vision, IoT Sensors, Barcode Scanning Product Type: Retail Software, Inventory Management, Analytics Tools, Reporting Solutions End User: Supermarkets, Grocery Stores, Pharmacies, E-commerce Platforms Service Type: Maintenance Support, Installation Services, Consulting, Training |
| Companies Covered | Retail Velocity, Impinj, Inc., IBM Corporation, NEOGRID, Frontier Field Marketing, SAP SE, Panasonic Corporation, eBest IOT, Retail Solutions, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
On-Shelf Availability Solutions Market Evolving Landscape
Autonomous replenishment orchestration is replacing visibility-only deployments as retailers demand closed-loop systems that trigger supplier orders without human intervention.
Generative AI models trained on shelf imagery are rendering obsolete rule-based planogram compliance tools that required manual template configuration for each store format. Mass merchandisers in the United States are deploying these systems across hypermarket footprints within eighteen-month rollout windows. The technology compresses category reset timelines from weeks to days while eliminating thirdogram audit contracts.
CSRD sustainability reporting requirements in Europe mandate supply chain transparency that extends to in-store product availability and waste metrics. Retailers must now disclose stockout-related food waste volumes, creating accountability pressure that favors automated monitoring over sampling-based audits. Grocery chains in France and the Netherlands are prioritizing shelf-analytics vendors with embedded carbon-footprint tracking modules.
Buyer consolidation among top-ten global retailers is compressing vendor qualification cycles and favoring multi-year outcome contracts over pilot-to-scale procurement. Tier-one grocers in Japan and Germany now demand guaranteed availability improvement percentages with penalty clauses, displacing traditional software licensing models. This shift concentrates procurement influence with category managers who control cross-border technology standards.
On-Shelf Availability Solutions Market Segmentation
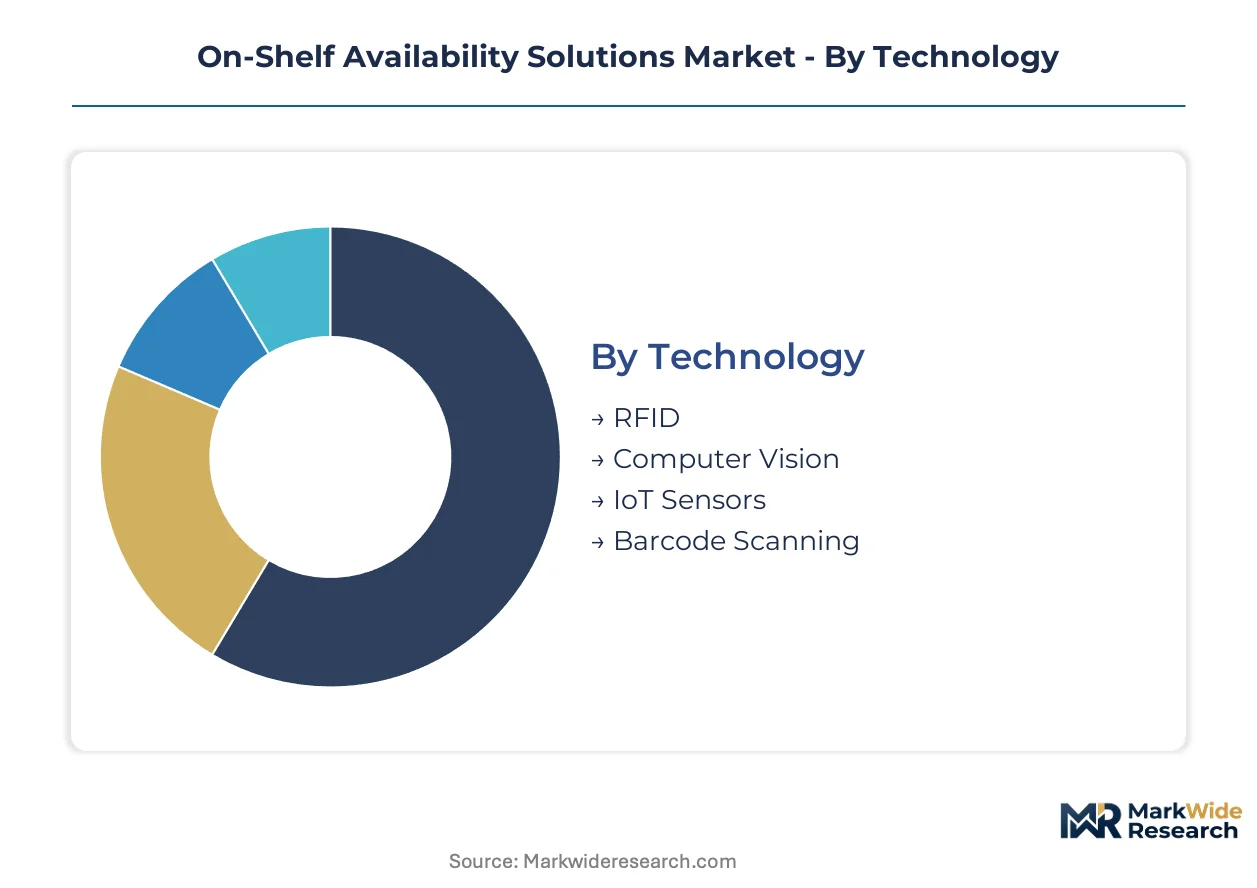
Technology architecture determines deployment economics and compliance pathways for on-shelf availability systems. Each segmentation dimension reveals distinct margin pools and integration complexity that shape vendor positioning and procurement priorities across retail verticals.
Technology:
Cost tier separates mature hardware from emerging inference platforms, with unit economics and installation complexity driving adoption sequencing across retail formats.
- RFID:Passive UHF tags and fixed reader arrays enable bulk inventory detection without line-of-sight constraints. German supermarket chains deploy RFID at scale for apparel and electronics aisles where five-cent tag economics justify item-level tracking.
- Computer Vision:Edge GPU clusters process real-time shelf imagery through convolutional neural networks for planogram compliance and stockout detection. Grocery operators in the United States and Japan prioritize camera-only deployments where GDPR and privacy regulations permit shopper-anonymous inference at the edge.
- IoT Sensors:Weight-sensitive shelf pads and capacitive presence detectors transmit telemetry through low-power mesh networks.
- Barcode Scanning:Handheld and fixed laser scanners maintain relevance in cost-constrained deployments and legacy system retrofits.
RFID holds installed capacity. Computer Vision is rotating up the share rankings.
Product Type:
Application maturity varies sharply, with predictive platforms commanding premium pricing against commodity visibility layers.
- Analytics Tools:Machine learning pipelines forecast demand signals and automate replenishment triggering based on shelf-telemetry patterns. Mass merchandisers prioritize vendors embedding carbon-footprint modules to satisfy CSRD disclosure requirements in France and the Netherlands.
- Retail Software:Shelf-monitoring middleware integrates with ERP systems and supplier portals for closed-loop inventory orchestration.
- Inventory Management:Real-time stock-level dashboards and alert systems form the foundational visibility layer.
- Reporting Solutions:Compliance documentation and audit trails support regulatory submissions to FDA and EMA for pharmacy deployments.
Retail Software holds installed capacity. Analytics Tools is rotating up the share rankings.
End User:
Customer type dictates sensor density requirements and regulatory exposure, with healthcare and food retail presenting divergent compliance frameworks.
- Supermarkets:Large-format grocery operators deploy multi-sensor fusion across thousands of SKUs with 24-hour trading norms. Metropolitan stores in Germany drive demand for autonomous replenishment without human shelf audits.
- Pharmacies:Cold-chain integration for temperature-sensitive drugs intersects with patient safety protocols regulated by FDA and EMA, opening high-margin vertical specialization.
- Grocery Stores:Smaller-format operators balance deployment cost against stockout loss reduction.
- E-commerce Platforms:Dark store and micro-fulfillment center operators adapt shelf-monitoring for robotic picking environments.
Supermarkets hold installed capacity. Pharmacies is rotating up the share rankings.
Service Type:
Margin capture shifts toward recurring revenue as hardware commoditization pressures upfront license models.
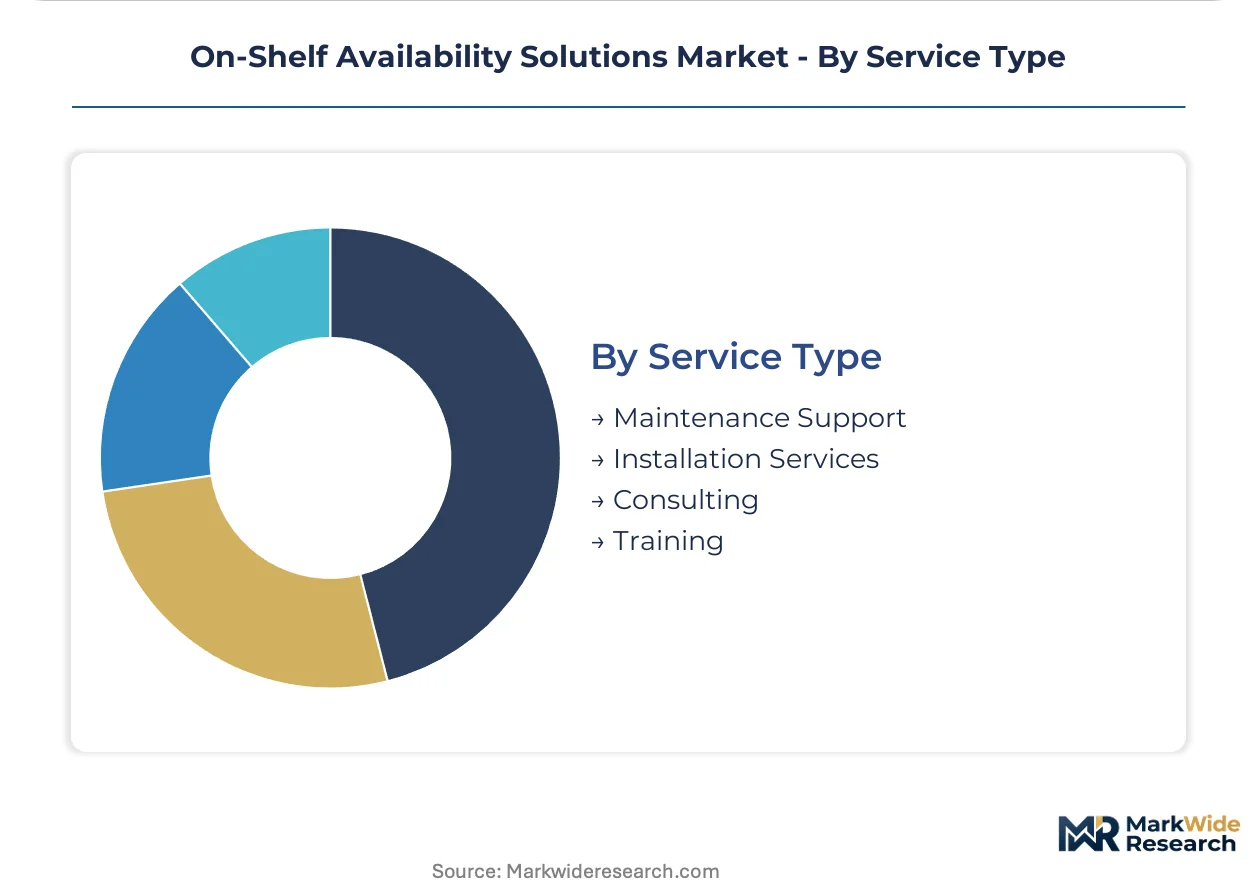
- Maintenance Support:Continuous model retraining and sensor calibration contracts address computer vision drift from packaging redesigns and seasonal merchandise rotations.
- Installation Services:Site survey, network provisioning, and legacy ERP integration for multi-store rollouts.
- Consulting:Change management and workflow redesign for autonomous replenishment orchestration.
- Training:Category manager and store associate certification for exception-handling in automated environments.
Installation Services hold installed capacity. Maintenance Support is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate lowest price elasticity for shelf-monitoring systems, absorbing premium hardware costs for labor substitution. Mid-tier grocers in India and Brazil face acute capital constraints, compressing vendor margins and favoring phased rollouts.
United States
FDA pharmacy regulations and mass merchandiser consolidation drive demand for closed-loop replenishment systems. The CSRD disclosure framework influences multinational retailers with European operations to standardize on carbon-footprint-enabled analytics. Walmart and Target's technology clusters in Bentonville and Minneapolis mandate guaranteed availability percentages with penalty clauses.
Germany
24-hour trading norms in metropolitan stores and EU AI Act conformity requirements accelerate procurement urgency for certified computer vision platforms. The country's national data protection authority enforces strict GDPR protocols for shopper-anonymous edge inference. REWE and Edeka's automation investments concentrate in North Rhine-Westphalia and Bavaria.
Japan
Labor shortages in convenience retail and METI's Society 5.0 automation incentives compress deployment timelines for autonomous shelf-monitoring. JIS standards govern IoT sensor interoperability in multi-vendor retail environments. Seven-Eleven Japan and Lawson format rollouts concentrate technology procurement in the Kanto and Kansai metropolitan corridors.
India
Reliance Retail and D-Mart expansion creates greenfield deployment opportunities without legacy ERP constraints. FSSAI food safety tracking requirements intersect with shelf-availability monitoring for perishable categories. Technology adoption clusters in Maharashtra and Karnataka where organized retail penetration advances fastest.
France
ANSM pharmaceutical traceability mandates and CSRD sustainability reporting requirements drive dual-compliance procurement for pharmacy and grocery operators. CNIL consent protocols shape video analytics architecture for shelf-monitoring deployments. Carrefour's technology standardization efforts concentrate in Île-de-France and Auvergne-Rhône-Alpes logistics corridors.
On-Shelf Availability Solutions Market Competitive Landscape
Enterprise software bundlers and specialized hardware manufacturers split the market into contrasting margin architectures. SAP SE leverages ERP integration depth to capture multi-year outcome contracts with penalty structures. Impinj anchors the RFID hardware layer with tag and reader specialization. IBM Corporation competes through hybrid cloud architectures processing edge sensor data. M&A activity concentrates on computer vision startups with FDA-compliant pharmacy modules. Strategic partnerships between sensor hardware vendors and 5G network operators reshape installation economics.
Within the enterprise software tier, SAP SE and IBM Corporation represent contrasting approaches to retail technology bundling. SAP SE exemplifies the ERP-anchored archetype that embeds shelf-analytics within broader procurement contracts. IBM Corporation occupies a position emphasizing distributed cloud processing for multi-store telemetry aggregation. Impinj, Inc. sits within the specialized hardware archetype, anchoring RFID infrastructure deployment with unit economics driven by tag cost deflation. These three companies collectively illustrate how vendor qualification cycles compress toward multi-year performance guarantees as buyer consolidation accelerates.
| Leading Market Players |
|---|
| Retail Velocity |
| Impinj, Inc. |
| IBM Corporation |
| NEOGRID |
| Frontier Field Marketing |
| SAP SE |
| Panasonic Corporation |
| eBest IOT |
| Retail Solutions, Inc. |
| Others |
Value Network & Pricing Analysis
The Rotterdam-Frankfurt logistics corridor shapes cost dynamics for edge camera arrays and RFID reader hardware, concentrating supply power with German distributors while downstream price differentiation separates ERP-integrated analytics bundles from standalone sensor deployments.
Pricing Analysis
Aftermarket service revenue drives lifetime value capture as retailers shift from perpetual licenses to multi-year maintenance contracts covering model retraining and sensor calibration. Three-tier pricing structure across premium, standard, and economy levels separates FDA-compliant pharmacy modules from basic grocery visibility layers. Price differentiation hinges on ISO/IEC 27001 certification status and ERP integration depth. Cost compression in mid-tier computer vision hardware is intensifying because GPU unit economics lag behind RFID tag deflation, stretching procurement cycles for regional grocery operators.
Supply Chain Analysis
Contract manufacturing concentration rests with Taiwanese ODMs for edge AI chipsets and German EMS providers for industrial-grade sensor housings. Component sourcing draws from South Korea for memory modules, China for camera lens assemblies, and Japan for precision weight sensors. Raw material dependencies include rare earth elements for RFID antenna substrates, high-purity silicon for inference processors, and copper for mesh network cabling. Single-source vulnerability concentrates in GPU accelerator supply. Distribution runs through value-added resellers with vertical retail specialization rather than direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern vendor selection as retailers demand interoperability between shelf-monitoring telemetry and supplier ERP portals, compressing standalone hardware margins while expanding analytics platform value capture.
For Market Incumbents: Build switching-cost moats through deep SAP and Oracle ERP integration that embeds shelf-analytics within procurement workflows. Incumbents should anchor multi-year outcome contracts with guaranteed availability percentages and penalty structures to lock out point-solution competitors. Vertical integration into edge AI chip design reduces dependency on NVIDIA supply allocations. Certification investment in EU AI Act conformity creates procurement urgency that favors established vendors with compliance documentation. For New Entrants and Emerging Players: Build out pharmacy cold-chain specialization where FDA and EMA patient safety protocols create high-margin barriers to commoditization. India's organized retail expansion offers greenfield deployment without legacy infrastructure constraints. Target D-Mart and Reliance Retail format rollouts with camera-only architectures that bypass fiber backhaul requirements. Go-to-market angle should emphasize 5G private network partnerships that reduce installation timelines versus incumbent hybrid cloud approaches. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial automation conglomerates with undermonetized retail computer vision divisions. Long-term viability centers on vendors with embedded carbon-footprint tracking modules that satisfy CSRD disclosure requirements. Acquisition archetype prioritizes computer vision startups with FDA-compliant pharmacy modules and existing EMA rapporteur relationships. Signal to watch is buyer consolidation among top-ten global retailers demanding cross-border technology standardization.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Interoperability with SAP ERP contracts displaces standalone sensor vendors. |
| Regulatory Certification | EU AI Act conformity accelerates procurement urgency in German retail chains. |
| Vertical Specialization | Pharmacy cold-chain modules command premium pricing under FDA oversight. |
| Strategic Partnership | 5G network operator alliances reduce edge deployment costs for camera-only systems. |
| Acquisition of Specialist Firm | Computer vision startups with FDA modules address high-margin healthcare vertical. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with category managers at German supermarket chains, pharmacy compliance officers, RFID hardware procurement leads, and edge AI platform engineers. Secondary validation drew from EU AI Act implementation guidance, FDA 21 CFR Part 11 submissions for pharmacy tracking systems, SEC 10-K disclosures from retail technology vendors, and customs data on RFID tag imports. Bottom-up sensor deployment counts triangulated against top-down retail automation capex estimates.
Calibration against historical adoption curves in German 24-hour trading formats and Japanese convenience retail informed projection elasticity. Segmentation dimensions modeled include technology architecture, product type maturity, end-user regulatory exposure, and service revenue mix across the analysis window. CAGRs derived from weighted average of hardware cost deflation trajectories and software margin expansion patterns. Forecast inputs incorporated EU AI Act compliance timelines and CSRD disclosure rollout schedules.
Sensitivities concentrate around RFID tag cost deflation velocity and GDPR enforcement consistency for video analytics. Forecasts reflect documented assumptions on retailer consolidation pace and edge AI chip efficiency gains. Quarterly review of pharmacy automation capex and 5G private network deployment metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
IT Asset Management Solutions (ITAM) Market
Digital Solutions
Digital Signage Systems Market
Digital Solutions
Middle East and Africa Digital Scent Technology Market
Digital Solutions
Employee Recognition and Reward System Market
Digital Solutions
Cloud E-Signature Tools Market
Digital Solutions
North America 3D Rendering Services Market
Digital Solutions
Quality Process Management Application Market
Digital Solutions
North America Smart Card Market
Digital Solutions
Commodity Supply Chain Management Solution Market
Digital Solutions
Germany Digital Twin Market
Digital Solutions
Digital Commerce Platform Market
Digital Solutions
Healthcare Computerized Maintenance Management System Market
Digital Solutions
Global Transport Management Software Market
Digital Solutions
Global Commerce Cloud Solution Market
Digital Solutions
Australia System Integration Market
Digital Solutions
Virtual Workspace Solutions Market