
 Talent Management Software Market | 2026-2036
Talent Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Talent Management Software Market Analysis
Platform bundling is pivoting from standalone modules toward unified suites that combine recruitment, performance tracking, and learning management in single contracts. Workday leverages its native cloud architecture to anchor enterprise accounts seeking consolidated human capital data. Oracle competes through deep integration with existing ERP footprints across Fortune 500 installations. SAP SuccessFactors differentiates by embedding workforce analytics directly into operational planning workflows.
Talent management software comprises integrated applications for workforce acquisition, development, retention, and succession planning, typically delivered through cloud-native architectures with API connectivity to payroll and enterprise resource systems. The primary commercial purpose centers on reducing employee turnover costs and accelerating time-to-productivity across structured organizational hierarchies. Cloud-based deployment leads segment traction as IT departments prioritize subscription economics over capital-intensive on-premises infrastructure. Recruitment solutions within the solution category capture disproportionate investment as labor shortages intensify competition for specialized technical and clinical roles. Large enterprises dominate end-user demand, though SMEs represent the fastest-growing buyer cohort as vendor pricing stratifies across premium, standard, and economy tiers.
The US Equal Employment Opportunity Commission enforces algorithmic fairness mandates that shape vendor product design for automated candidate screening. The EU AI Act imposes risk-classification requirements on AI-driven hiring tools, directly affecting market access for platforms deployed across European multinational operations. ISO 30415 standards for human resource management provide voluntary frameworks that procurement teams increasingly embed in RFP evaluation criteria. Stakeholders must monitor how divergent regulatory timelines between American federal agencies and European bodies will fragment compliance roadmaps and reshape vendor competitive positioning.
Market Dynamics
Platform consolidation is compressing vendor margins as enterprise buyers demand unified suites over point solutions, forcing mid-tier providers to choose between acquisition, niche specialization, or exit.
Growth Catalysts
- EU AI Act risk classification:Mandatory algorithmic transparency for high-risk hiring applications creates compliance-driven replacement cycles across European multinational operations.
- Healthcare workforce shortages:Hospital systems deploy integrated talent platforms to reduce clinical turnover and accelerate specialized recruitment pipelines.
- API-first architectures:Native connectivity to payroll and ERP systems eliminates integration friction that previously stalled enterprise deployments.
Market Restraints
- Cloud infrastructure concentration:Reliance on hyperscale providers creates single-point-of-failure exposure and limits vendor negotiating leverage on hosting costs.
- ISO 30415 certification complexity:Voluntary diversity and inclusion standards require substantial implementation resources without guaranteed procurement preference.
- Legacy ERP entrenchment:Deep Workday, Oracle, and SAP footprints create switching costs that freeze competitive displacement for 5-7 year contract cycles.
Strategic Opportunities
- SME pricing stratification:Economy-tier subscriptions open addressable market among 500-5,000 employee organizations previously priced out of enterprise platforms.
- Skills-based hiring convergence:Integration of credential verification APIs with assessment engines creates new value layer beyond traditional resume parsing.
- US EEOC algorithmic guidance:Federal enforcement of adverse impact testing creates advisory service revenue streams adjacent to core software licensing.
Industry Challenges
- Machine learning engineering scarcity:Talent to build bias-detection and explainability features commands premium compensation that strains R&D budgets.
- Cross-border data residency:Divergent GDPR, state-level privacy laws, and sector-specific healthcare requirements fragment product architecture and delay releases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Talent Management Software Market |
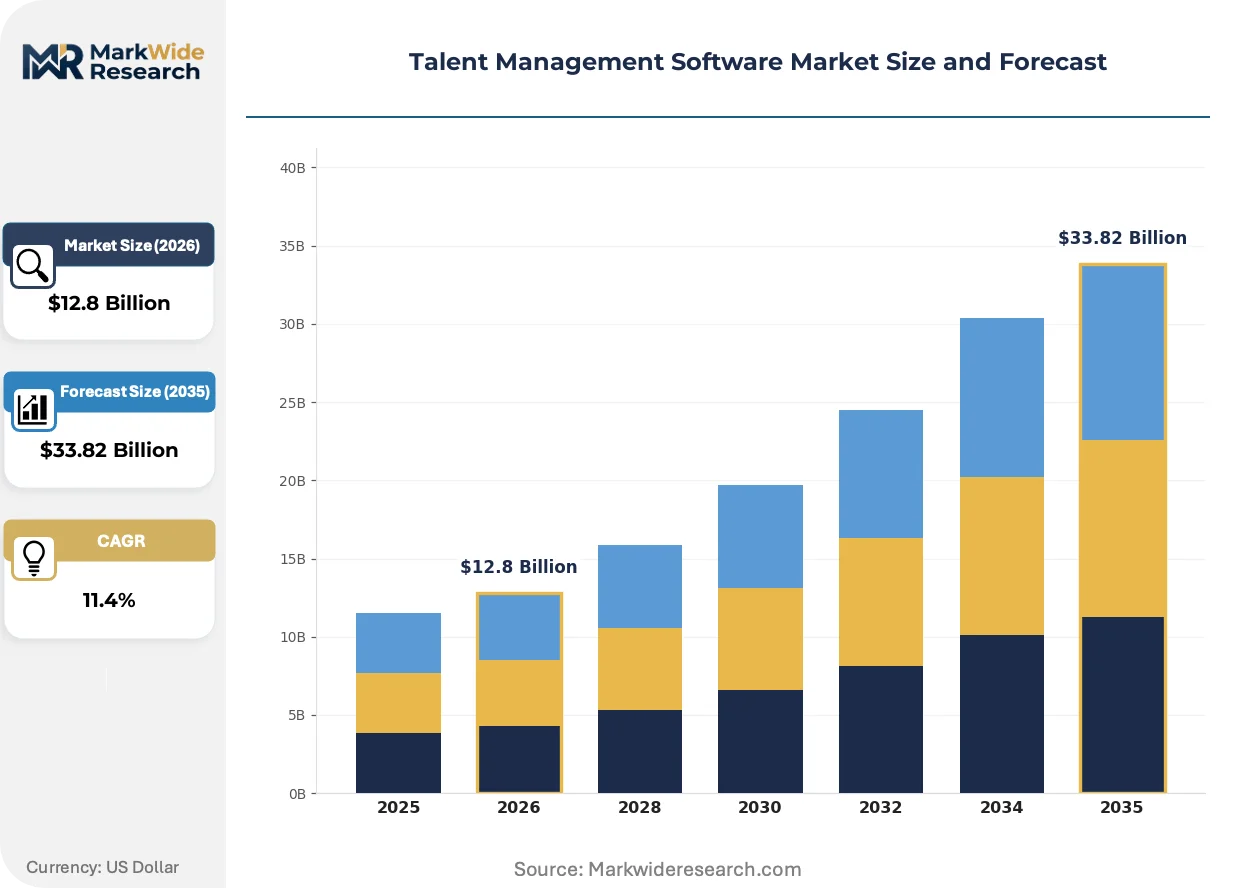
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $33.82 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: SMEs, Large Enterprises, Government, Non-Profits Solution: Recruitment, Performance Management, Learning Management, Succession Planning Service Type: Consulting, Implementation, Maintenance, Support |
| Companies Covered | Workday, SAP SuccessFactors, Oracle, ADP, Cornerstone OnDemand, UKG, Ceridian, Paycom, Ultimate Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Talent Management Software Market Emerging Trajectories
Generative capabilities are embedding into candidate communication and internal mobility workflows, compressing the gap between automation and human judgment in hiring decisions.
Natural language processing is expanding into structured interview transcription and competency mapping. Mid-market HR departments adopt these tools faster than Fortune 500 peers due to lower change-management overhead. The technology is expanding into performance review automation and succession planning documentation previously handled by dedicated analysts.
The EU AI Act imposes conformity assessment obligations on automated decision systems used in recruitment. Vendors must maintain technical documentation and human oversight protocols for tools deployed across European operations. Multinational employers are consolidating vendor selection to platforms with pre-certified compliance rather than managing fragmented regulatory exposure.
Subscription unbundling is fragmenting traditional suite contracts as specialized point solutions demonstrate superior functionality in narrow domains. Talent acquisition teams procure best-of-breed assessment and sourcing tools outside centralized IT procurement. This pattern is most visible in technology and financial services verticals where hiring velocity determines competitive position.
Talent Management Software Market Segmentation
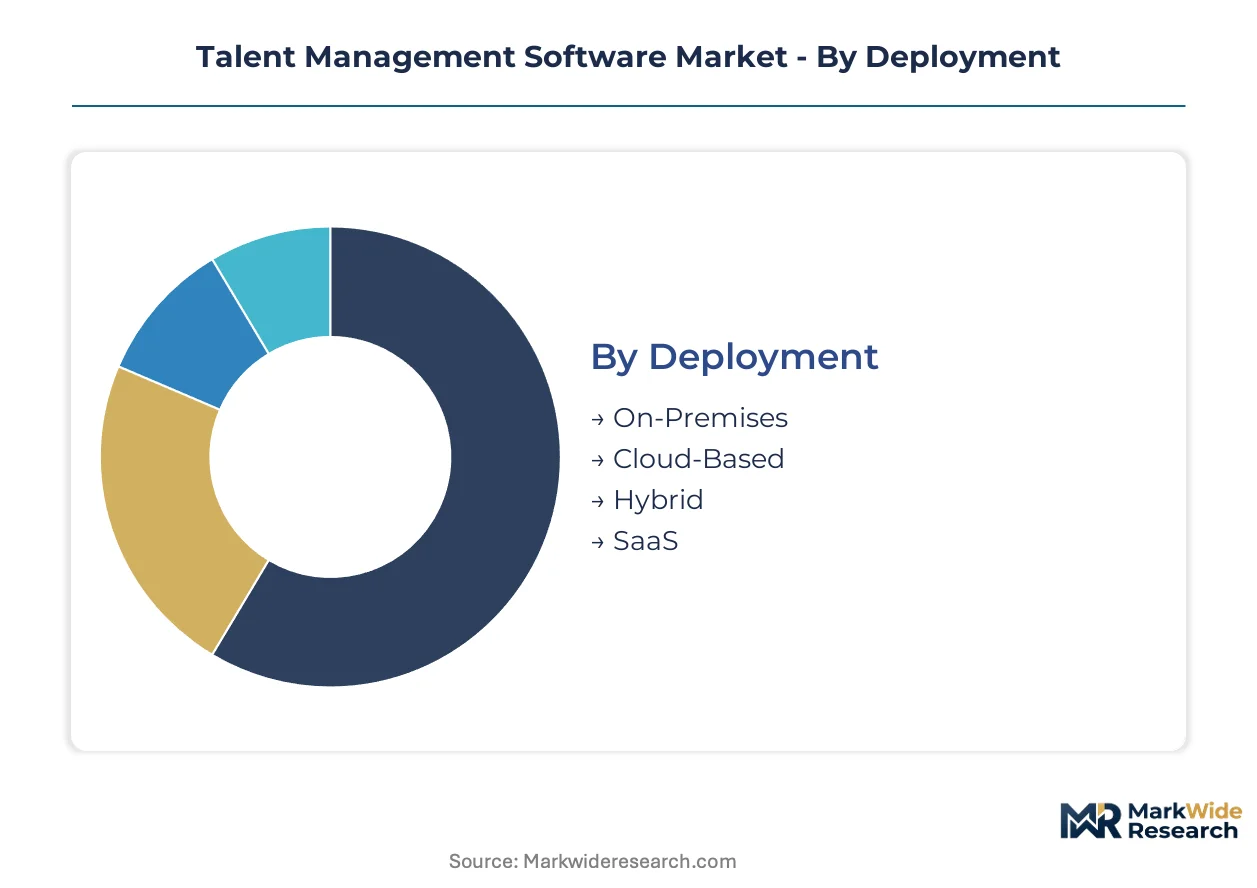
Talent management software segments along deployment architecture, organizational scale, functional scope, and service engagement depth. These divisions determine pricing elasticity, sales cycle length, and vendor resource allocation across the value chain.
Deployment:
Cloud-based deployments command premium pricing against legacy on-premises infrastructure, while hybrid architectures capture organizations in transition states.
- On-Premises:Installed within client data centers with dedicated hardware ownership. Demand concentrates among defense contractors and financial institutions in Germany subject to strict data sovereignty requirements.
- Cloud-Based:Fully managed multi-tenant SaaS delivery with elastic scaling. Healthcare systems in the United States drive replacement cycles as IT departments abandon capital-intensive refresh programs.
- Hybrid:Core HR data remains on-premises while recruitment modules deploy via cloud. German automotive manufacturers favor this architecture to satisfy works council data access requirements.
- SaaS:Subscription-native delivery with API-first integration design. Mid-market technology companies in India adopt these platforms to bypass internal infrastructure buildouts.
Today's leader: Cloud-Based. Tomorrow's challenger: Hybrid.
End User:
Enterprise buyers consolidate vendor relationships while smaller organizations prioritize rapid deployment over customization depth.
- SMEs:Organizations with 50-999 employees seeking standardized workflows without dedicated HRIS staff. These buyers in Brazil represent the steepest expansion trajectory as local vendors introduce economy-tier pricing.
- Large Enterprises:Complex multi-entity structures requiring global payroll integration and localized compliance. Fortune 500 headquarters in the United States anchor vendor R&D roadmaps through multi-year commitments.
- Government:Public sector procurement with mandatory competitive bidding and security clearance requirements. Federal agencies in Canada drive demand for FedRAMP-equivalent certification standards.
- Non-Profits:Mission-driven organizations with constrained budgets and high volunteer coordination needs. International NGOs in Switzerland prioritize donor reporting integration over advanced analytics.
Large Enterprises generate the majority of current revenue. SMEs are gaining share fastest among new vendor signings.
Solution:
Functional modules compete for budget priority based on measurable ROI timelines and regulatory pressure intensity.
- Recruitment:Applicant tracking, sourcing automation, and candidate relationship management. Hospital systems across France deploy these tools to address nursing shortages intensified by EU working time directives.
- Performance Management:Goal alignment, continuous feedback, and compensation linkage. Technology companies in Israel adopt these modules to retain engineering talent amid sector-specific wage inflation.
- Learning Management:Skills development, compliance training, and career pathway visualization. Manufacturing firms in Japan integrate these systems with METI-certified vocational credential frameworks.
- Succession Planning:Leadership pipeline development and critical role risk assessment. Family-owned conglomerates in South Korea mandate these tools to manage generational leadership transitions.
Recruitment solutions currently dominate procurement budgets. Learning Management is climbing the fastest as skills-based hiring mandates expand.
Service Type:
Professional services margins vary dramatically by engagement complexity and client technical maturity.
- Consulting:Organizational design, change management, and process reengineering advisory. Healthcare networks in Australia purchase these services to navigate ISO 30415 diversity standard implementation.
- Implementation:System configuration, data migration, and integration development. ERP replacement projects in the United Kingdom generate 12-18 month implementation cycles for complex multi-module deployments.
- Maintenance:Ongoing platform updates, security patching, and performance optimization. Government clients in Saudi Arabia require localized maintenance teams to satisfy data residency commitments.
- Support:Help desk, user training, and troubleshooting services. SME buyers in Mexico prioritize Spanish-language support availability over advanced feature depth.
Implementation services capture the highest per-contract value. Support contracts are expanding most quickly as installed bases mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise software for workforce management originated in United States technology corridors during the late 1990s client-server era, then migrated to cloud-native delivery as Silicon Valley infrastructure matured. Vendor development subsequently dispersed to European regulatory centers and Asian implementation hubs.
United States
Fortune 500 headquarters in New York and California drive premium contract values for unified human capital platforms. The EEOC enforces algorithmic fairness mandates that reshape product roadmaps for automated screening tools. Healthcare systems in Texas and Florida accelerate replacement cycles to address clinical workforce shortages.
Germany
Automotive manufacturers and industrial conglomerates demand hybrid deployment models satisfying works council data access requirements. The EU AI Act imposes conformity assessment obligations on recruitment algorithms deployed across Bavarian and Baden-Württemberg operations. Frankfurt-based financial institutions prioritize ISO 30415 diversity certification in procurement evaluations.
United Kingdom
Financial services firms in London procure best-of-breed assessment tools outside centralized IT frameworks. The Information Commissioner's Office enforces GDPR-aligned transparency requirements for automated hiring decisions. ERP replacement projects in Manchester and Birmingham generate extended implementation cycles for multi-module deployments.
India
Mid-market technology companies in Bangalore and Hyderabad adopt SaaS-native platforms to bypass internal infrastructure buildouts. The Ministry of Electronics and Information Technology promotes data localization standards affecting cloud architecture decisions. Domestic vendors in Mumbai introduce economy-tier pricing to capture 500-5,000 employee organizations.
Japan
Manufacturing firms integrate learning management systems with METI-certified vocational credential frameworks. The Personal Information Protection Commission mandates explicit consent protocols for AI-driven candidate evaluation. Family-owned conglomerates in Osaka and Nagoya mandate succession planning tools to manage generational leadership transitions.
Talent Management Software Market Vendor Landscape
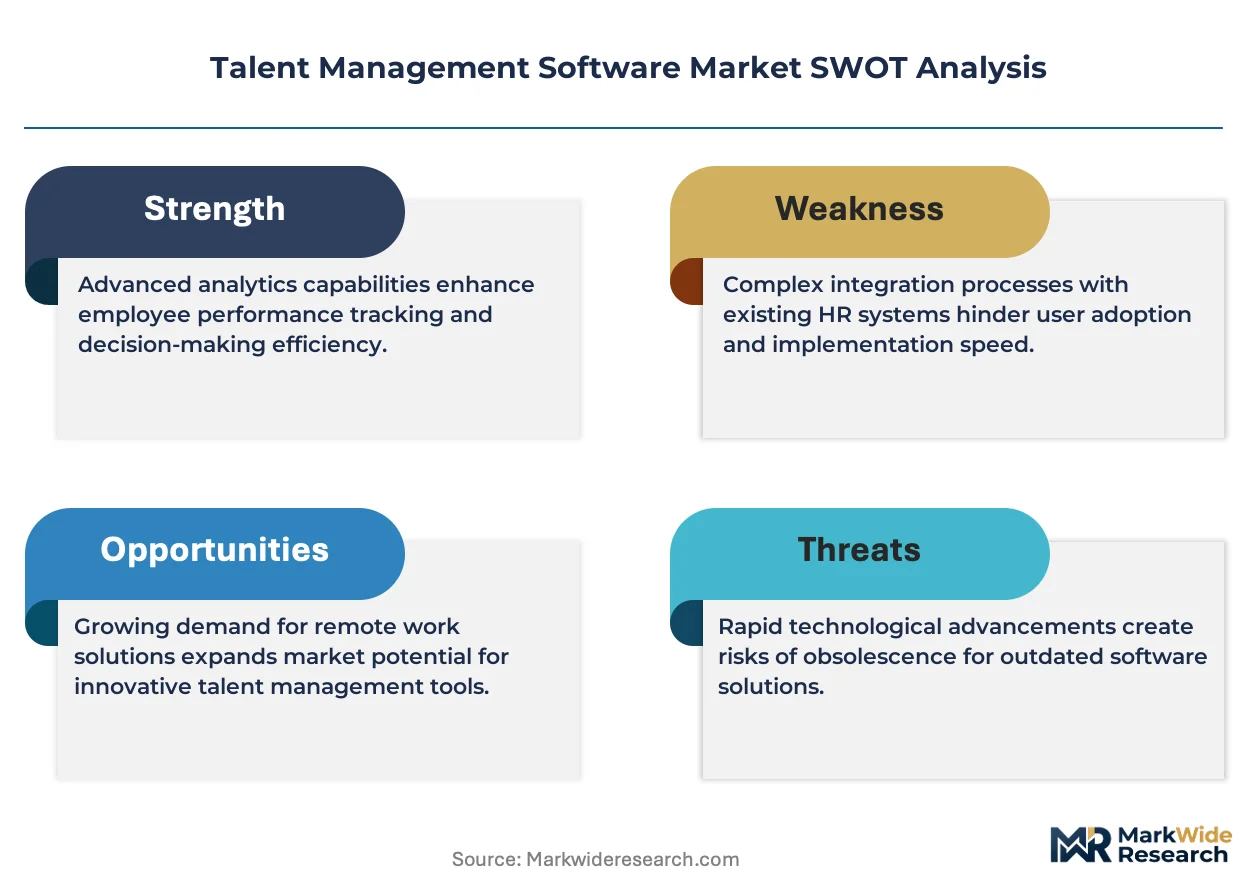
The competitive structure tilts toward consolidated platform providers with native cloud architectures. Enterprise buyers compress vendor margins by demanding unified suites over point solutions, forcing mid-tier providers toward acquisition or niche specialization. Three archetypes dominate: ERP-integrated incumbents, standalone cloud specialists, and payroll-anchored diversification plays. M&A activity and API-first ecosystem partnerships constitute the primary competitive vectors as vendors race to enclose workflow adjacencies.
Among ERP-integrated incumbents, SAP SuccessFactors and Oracle occupy positions exemplifying deep operational system entrenchment, while Workday represents the cloud-native architecture archetype that anchors enterprise accounts seeking consolidated human capital data. These three entities illustrate how vendor selection increasingly consolidates around platforms with pre-certified compliance rather than fragmented regulatory exposure.
| Leading Market Players |
|---|
| Workday |
| SAP SuccessFactors |
| Oracle |
| ADP |
| Cornerstone OnDemand |
| UKG |
| Ceridian |
| Paycom |
| Ultimate Software |
| Others |
Supply Flow & Price Mechanics
Cloud infrastructure costs from Amazon Web Services, Microsoft Azure, and Google Cloud Platform cascade through vendor pricing tiers as hyperscale hosting fees absorb 15-25 percent of SaaS subscription revenue, compressing margins for economy-tier providers while enterprise buyers leverage volume commitments to lock in rate ceilings.
Pricing Analysis
Subscription-based SaaS pricing with annual or multi-year contracts dominates revenue capture across deployment tiers. Price differentiation hinges on API integration depth and ISO 30415 diversity certification status. Pricing pressure intensifies as mid-market vendors undercut enterprise suites with modular point solutions. SME buyers in Brazil and India exhibit highest price sensitivity, while Fortune 500 headquarters in the United States prioritize compliance bundling over per-seat cost optimization.
Supply Chain Analysis
Direct-to-enterprise sales channels handle complex multi-module deployments requiring 12-18 month implementation cycles, while partner networks and system integrators serve mid-market acceleration. Engineering talent concentrates in the United States, India, and Israel. Platform development draws from scarce machine learning engineering pools and specialized compliance advisory capacity. Single-source vulnerability in hyperscale cloud hosting creates concentration risk. Distribution runs through value-added resellers in Europe and direct field organizations in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunity concentrates in advisory services adjacent to core licensing, where EU AI Act compliance mandates and EEOC algorithmic fairness enforcement create premium-tier pricing power for explainability and bias-audit capabilities.
For Market Incumbents: Anchor enterprise accounts through native cloud architecture consolidation that absorbs adjacent HRIS spend. Deepen ISO 30415 certification investment to differentiate procurement evaluations. Defend against subscription unbundling by embedding workforce analytics directly into operational planning workflows rather than treating talent modules as standalone purchases. For New Entrants and Emerging Players: The gap between premium suite pricing and economy-tier subscriptions creates entry space for API-first point solutions targeting 500-5,000 employee organizations in India and Brazil. Skills-based hiring convergence offers the most penetrable application layer, where credential verification APIs integrated with assessment engines bypass entrenched resume-parsing incumbents. Lead with rapid deployment guarantees measured in weeks rather than quarters. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier providers face margin compression from unified suite demands and cannot achieve acquisition scale or niche specialization. Viable targets combine pre-certified EU AI Act compliance with existing healthcare system installations. Watch hiring velocity metrics in technology and financial services verticals as early indicators of procurement pattern shifts toward best-of-breed fragmentation or suite consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified recruitment-performance-learning suites capture enterprise procurement consolidation mandates. |
| Acquisition of Specialist Firm | Explainability and bias-detection engineering teams address EU AI Act conformity assessment gaps. |
| Geographic Expansion | Data localization compliance in Germany and Saudi Arabia opens public sector and healthcare contracts. |
| Strategic Partnership | Hyperscaler alliances with AWS and Azure reduce hosting cost exposure and accelerate go-to-market. |
| Product Launch | Generative capabilities in candidate communication differentiate mid-market offerings from legacy automation. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured perspectives from CHROs, IT procurement officers, platform engineers, and compliance advisory leads at healthcare systems and technology firms across the United States, Germany, and India. Secondary validation drew from SEC filings, EU regulatory submissions, hyperscaler capex disclosures, and hospital procurement databases. Bottom-up deployment counts and top-down vendor revenue estimates were reconciled through iterative triangulation.
Historical reference periods anchored growth trajectory modeling across the projection horizon. Segmentation dimensions included deployment architecture, organizational scale, functional solution scope, and regional regulatory cluster. CAGRs were derived from fitted trend analysis against comparable technology adoption curves. Forecast inputs incorporated healthcare workforce shortage intensity, EU AI Act implementation timelines, and API-first architecture penetration rates.
Caveats apply where regulatory divergence between American federal agencies and European bodies, or sudden shifts in cloud infrastructure pricing, could materially shift the outlook. Forecasts reflect assumptions about compliance cost pass-through rates and SME pricing elasticity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Asia-Pacific Accounting Software Market
Software & Services
Exploration and Production Accounting System Software Market
Software & Services
Multivariate Testing Software Market
Software & Services
Open Source Bug Tracking Tool Market
Software & Services
Network Bandwidth Management Software Market
Software & Services
Fire Software Market
Software & Services
Global AR Game Engine Software Market
Software & Services
Media Planning Software Market
Software & Services
Global Club Management Software Market
Software & Services
Global Knowledge Management Software Market
Software & Services
UK Applicant Tracking System Market
Software & Services
Investor Relations (IR) Website Builder Software Market
Software & Services
Global Address Verification Software Market
Software & Services
ELD Compliance Software Market
Software & Services
Indonesia IT Services Market
Software & Services
Global Inside Sales Software Market