
 Software Defined Broadcasting Market | 2026-2036
Software Defined Broadcasting Market Size, Share, and Industry Trends Forecast 2026-2036
Software Defined Broadcasting Market Analytics
Broadcast distribution architecture is tilting from purpose-built hardware chains toward software-centric IP workflows. Harmonic Inc. leverages its VOS platform to consolidate encoding, packaging, and delivery functions on commercial off-the-shelf servers. Ericsson AB anchors European telco deployments with its MediaFirst portfolio, while Evertz Microsystems Ltd. dominates live production routing through software-defined video networking.
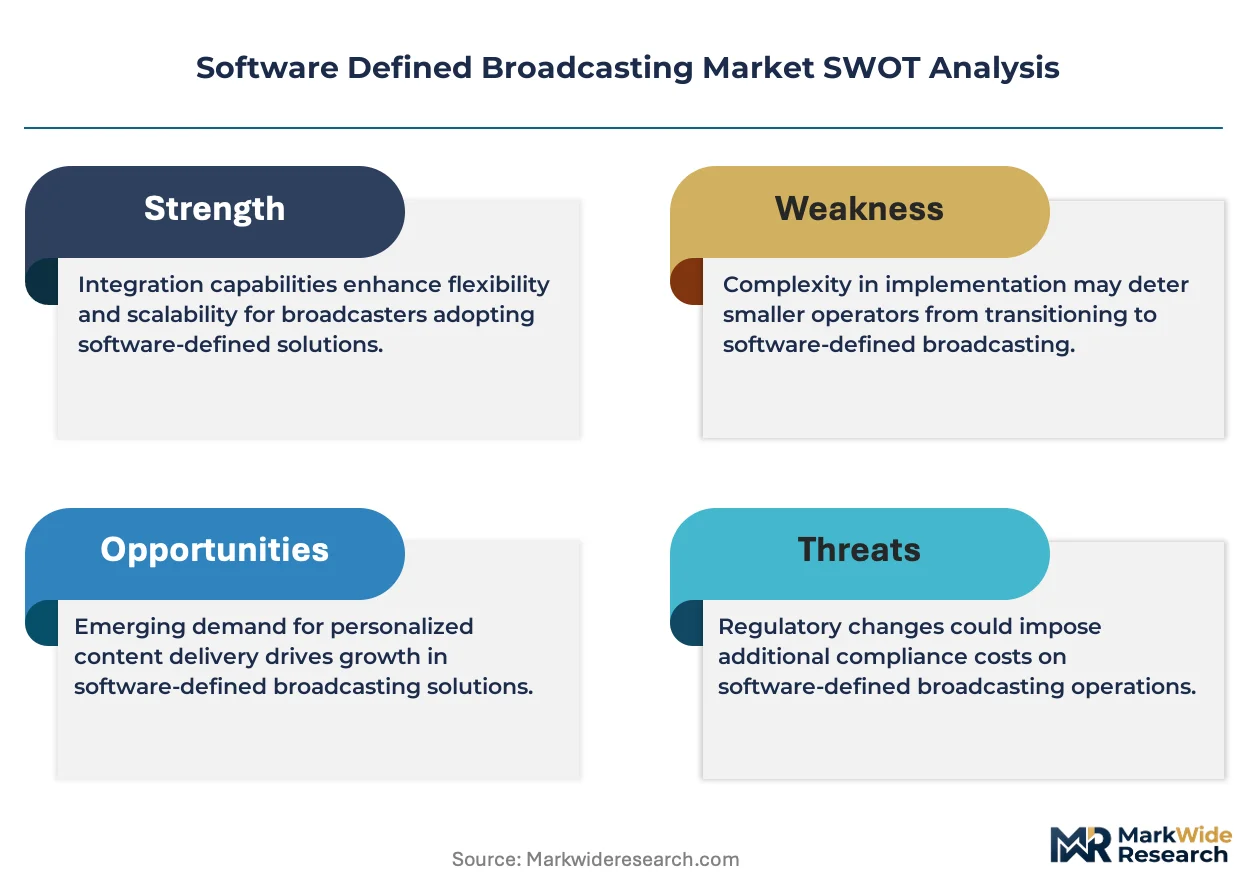
Software defined broadcasting denotes the virtualization of broadcast signal processing, modulation, and distribution functions that historically required dedicated RF and baseband equipment, now executed on x86 or ARM compute with GPU acceleration and real-time kernel scheduling for deterministic latency below 50 milliseconds. Its primary purpose is to enable broadcasters and network operators to spin transmission capacity up or down through API-driven orchestration rather than physical hardware swaps. Cloud-based solutions and adaptive bitrate streaming command expanding share as streaming platforms and media enterprises prioritize elasticity over fixed infrastructure, while on-premises deployment retains favor among national broadcasters with legacy satellite uplink commitments and strict local content custody rules. IP broadcast technology leads current installed value, though virtualized encoders represent the fastest structural expansion as CDN edge nodes absorb more origin functions.
The FCC mandates ATSC 3.0 next-generation broadcast standards, while the EBU coordinates spectrum policy across member states and the ITU-R sets international framework conditions for terrestrial and satellite broadcasting interoperability. These bodies shape demand by dictating transmission codec requirements, emission mask compliance, and cross-border signal carriage rules that determine whether software-defined implementations qualify for licensed spectrum access. Stakeholders must monitor spectrum reallocation proceedings and cloud egress pricing regimes as these twin forces determine whether centralized or edge-dense architectures deliver superior total cost of ownership.
Market Dynamics
Broadcast infrastructure virtualization is compressing capital cycles as telecommunication operators consolidate multicast and unicast traffic through centralized data centers, replacing dedicated RF chains with API-orchestrated compute pools.
Growth Catalysts
- ATSC 3.0 mandate:The FCC's next-generation broadcast standard compels terrestrial broadcasters to modernize transmission infrastructure, creating immediate demand for software-defined modulation and encoding stacks that satisfy emission mask compliance.
- 5G broadcast trials:German public broadcasters are deploying 3GPP Release 16 multicast-broadcast services over commercial mobile networks, validating software-defined core integration for mass-market media distribution.
- GPU acceleration:Real-time kernel scheduling on x86 architectures with NVIDIA and AMD silicon now delivers deterministic latency below 50 milliseconds for live production, eliminating the performance gap with dedicated baseband hardware.
Market Restraints
- Legacy satellite uplink commitments:National broadcasters with long-term transponder leases face stranded asset risk when migrating to IP-based distribution, slowing virtualization timelines.
- Cloud egress pricing volatility:Amazon Web Services and Microsoft Azure data transfer costs create unpredictable operating expenditure for centralized playout models versus fixed-cost on-premises deployments.
- RF engineer scarcity:The specialized workforce capable of bridging traditional transmission engineering with Kubernetes orchestration concentrates in Germany, the United Kingdom, and the United States, constraining rollout velocity elsewhere.
Strategic Opportunities
- DVB-I service layering:Hybrid broadcast-broadband specifications enable broadcasters to deliver streaming-grade user experiences over terrestrial infrastructure, opening addressable markets beyond traditional linear television.
- Edge node absorption:Content delivery networks are virtualizing origin server functions, allowing broadcasters to collapse encoding, packaging, and caching into single software instances at network peripheries.
- Ofcom framework consultation:The United Kingdom's IP transition timeline discussions are creating regulatory clarity that accelerates procurement decisions among commercial broadcasters and platform operators.
Industry Challenges
- Real-time operating system certification:Broadcast-critical applications require SIL-rated or equivalent deterministic scheduling guarantees that conflict with standard cloud virtualization layers, forcing custom kernel development.
- Interoperability fragmentation:Proprietary APIs from encoder vendors, orchestration platforms, and CDN operators create integration tax for multi-supplier deployments that span playout, distribution, and consumer device ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Software Defined Broadcasting Market |
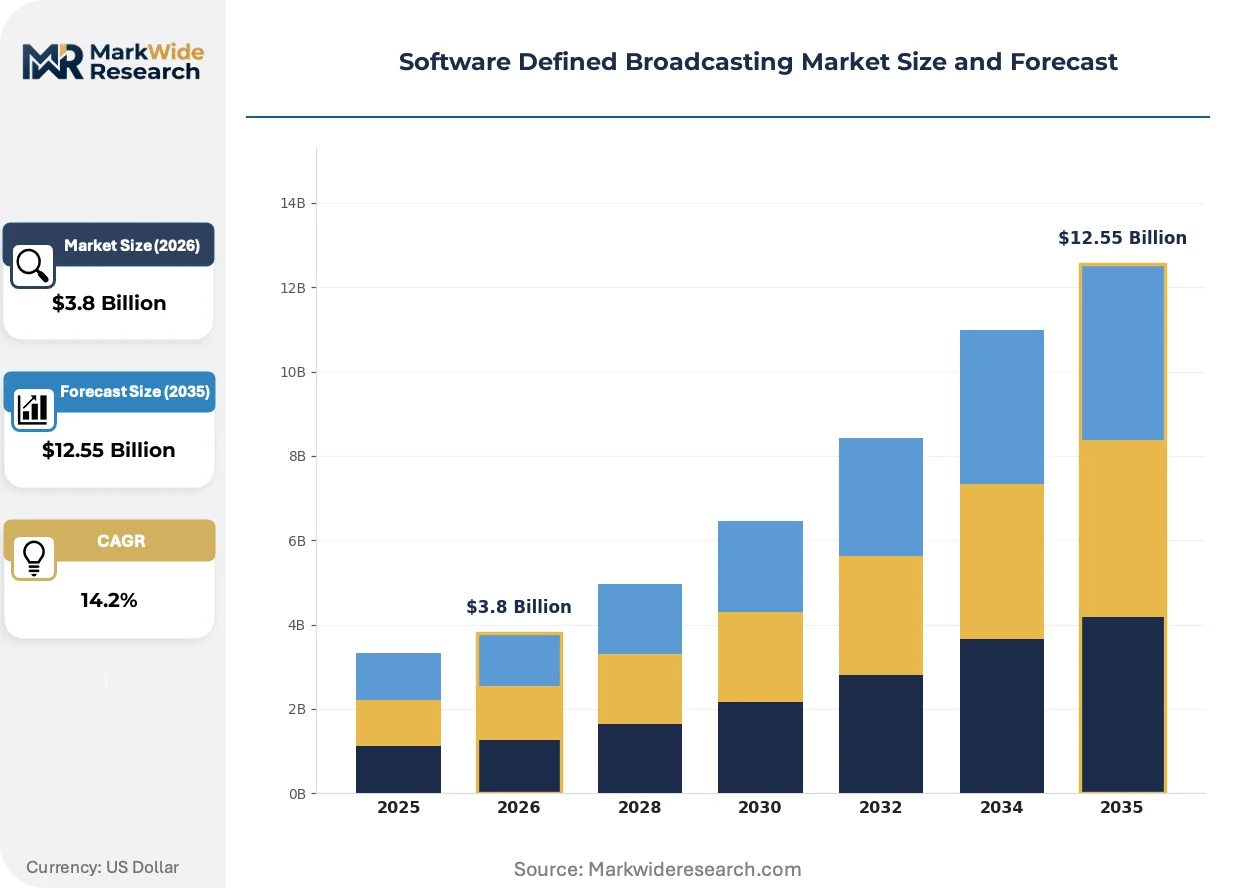
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IP Broadcast, Cloud-Based Solutions, Virtualized Encoders, Adaptive Bitrate Streaming Application: Content Delivery, Live Streaming, Video-on-Demand, Multimedia Distribution End User: Broadcasters, Streaming Platforms, Media Enterprises, Telecommunication Operators Deployment: On-Premises, Private Cloud, Public Cloud, Hybrid Cloud |
| Companies Covered | Harmonic Inc., Imagine Communications Corp., Ericsson AB, ARRIS International plc, Rohde & Schwarz GmbH & Co KG, Broadcast Electronics, Inc., Grass Valley, Evertz Microsystems Ltd., Avid Technology Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Software Defined Broadcasting Market Evolving Landscape
Virtualization architectures are dissolving the boundary between broadcast origination and internet distribution, compressing infrastructure tiers and enabling dynamic capacity allocation that responds to audience scale rather than fixed hardware provisioning.
Containerized playout software is hybridizing traditional master control room functions with cloud-native elasticity. Tier-one broadcasters in Germany and the United Kingdom are deploying Kubernetes-orchestrated channel origination that scales from single-channel disaster recovery to full primary playout during peak events. This hybridizing architecture collapses the distinction between broadcast and streaming operations, forcing vendor consolidation across historically separate supply bases.
The FCC's spectrum reallocation proceedings are tightening emission mask requirements for adjacent-channel protection in repacked UHF bands. Broadcasters must deploy software-defined exciters capable of real-time precorrection and adaptive modulation to maintain licensed spectrum access. Stations in congested metropolitan markets face capital refresh cycles compressed from decade-long hardware lifecycles to three-year software revision cycles.
Media enterprises are unbundling after-sales service from capital equipment procurement, demanding subscription-based encoder access with guaranteed availability SLAs rather than perpetual license ownership. This shift concentrates purchasing authority with CTO organizations and away from traditional broadcast engineering departments. The transformation is most visible among streaming-native platforms and multinational media conglomerates consolidating technical operations across multiple national markets.
Software Defined Broadcasting Market Segmentation
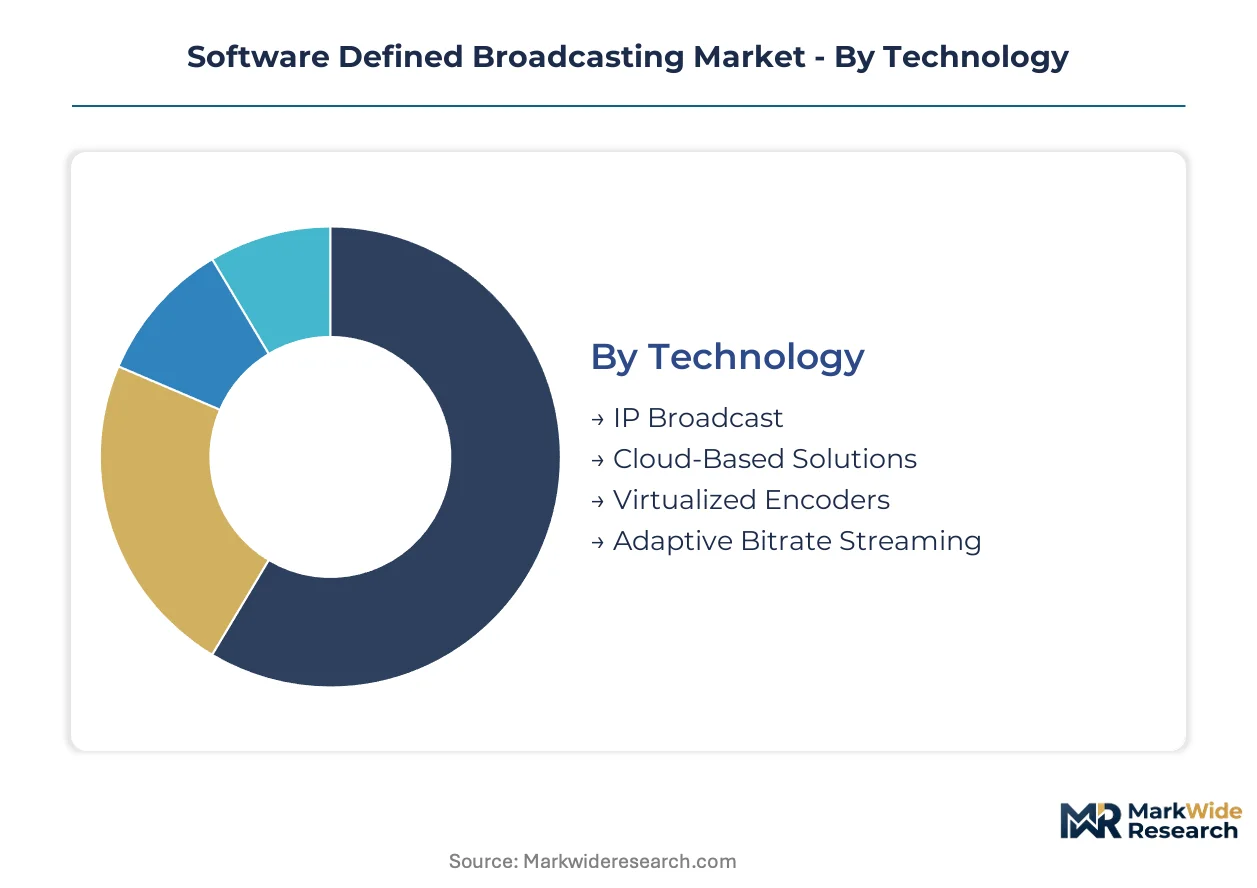
Software defined broadcasting segments reflect divergent infrastructure philosophies between legacy broadcasters guarding capital-intensive satellite commitments and streaming-native platforms prioritizing API-driven elasticity. Each dimension captures distinct procurement authority centers, technical specifications, and compliance obligations that reshape vendor competitive dynamics.
Technology:
Technical architecture determines latency tolerance, hardware substitution rates, and GPU acceleration requirements across transmission chains.
- IP Broadcast:Signal processing and modulation executed over packet-switched networks using commercial off-the-shelf switching fabric. German public broadcasters anchor installed demand as DVB-I trials validate hybrid broadcast-broadband service delivery over terrestrial infrastructure.
- Virtualized Encoders:Compression functions abstracted from dedicated ASIC hardware onto x86 or ARM compute with NVIDIA and AMD GPU scheduling. Streaming platforms and CDN edge nodes are absorbing origin server functions fastest, collapsing encoding and caching into single software instances.
- Cloud-Based Solutions:Fully managed encoding, packaging, and delivery orchestrated from hyperscaler data centers with API-driven capacity scaling.
- Adaptive Bitrate Streaming:Dynamic resolution and codec adjustment responding to last-mile network conditions and device capability.
IP Broadcast holds installed capacity. Virtualized Encoders is rotating up the share rankings.
Application:
Content format and consumption timing dictate orchestration complexity, storage economics, and real-time kernel certification requirements.
- Live Streaming:Deterministic sub-50 millisecond latency requirements enforced through real-time kernel scheduling on GPU-accelerated compute. United States broadcasters face compressed refresh cycles as FCC repacking tightens emission mask requirements for ATSC 3.0 compliance in congested metropolitan markets.
- Content Delivery:Multicast and unicast traffic consolidation through centralized data centers replacing dedicated RF distribution chains. Telecommunication operators in Germany and the United Kingdom are expanding software-defined infrastructure to manage hybrid broadcast-broadcast workloads.
- Video-on-Demand:File-based workflow optimization with asynchronous processing tolerating higher latency for storage efficiency gains.
- Multimedia Distribution:Converged audio, video, and data service bundling across heterogeneous consumer device ecosystems.
Content Delivery commands current infrastructure investment. Live Streaming is climbing the fastest as latency requirements harden.
End User:
Organizational type determines capital cycle length, compliance jurisdiction, and in-house versus outsourced technical operations.
- Telecommunication Operators:National-scale multicast infrastructure with 5G broadcast core integration and spectrum licensing obligations. German operators are validating 3GPP Release 16 multicast-broadcast services over commercial mobile networks, consolidating software-defined infrastructure procurement authority.
- Broadcasters:Licensed spectrum access with legacy satellite uplink commitments and strict local content custody rules constraining cloud migration velocity. United Kingdom commercial broadcasters are accelerating procurement decisions following Ofcom's IP transition timeline consultations.
- Streaming Platforms:Cloud-native operations with subscription-based encoder procurement and guaranteed availability SLAs replacing perpetual licenses.
- Media Enterprises:Multinational technical operation consolidation across national markets with CTO-led purchasing authority.
Broadcasters retain legacy infrastructure mass. Telecommunication Operators are gaining share fastest through 5G broadcast deployment.
Deployment:
Infrastructure location determines total cost of ownership predictability, data sovereignty compliance, and egress pricing exposure.
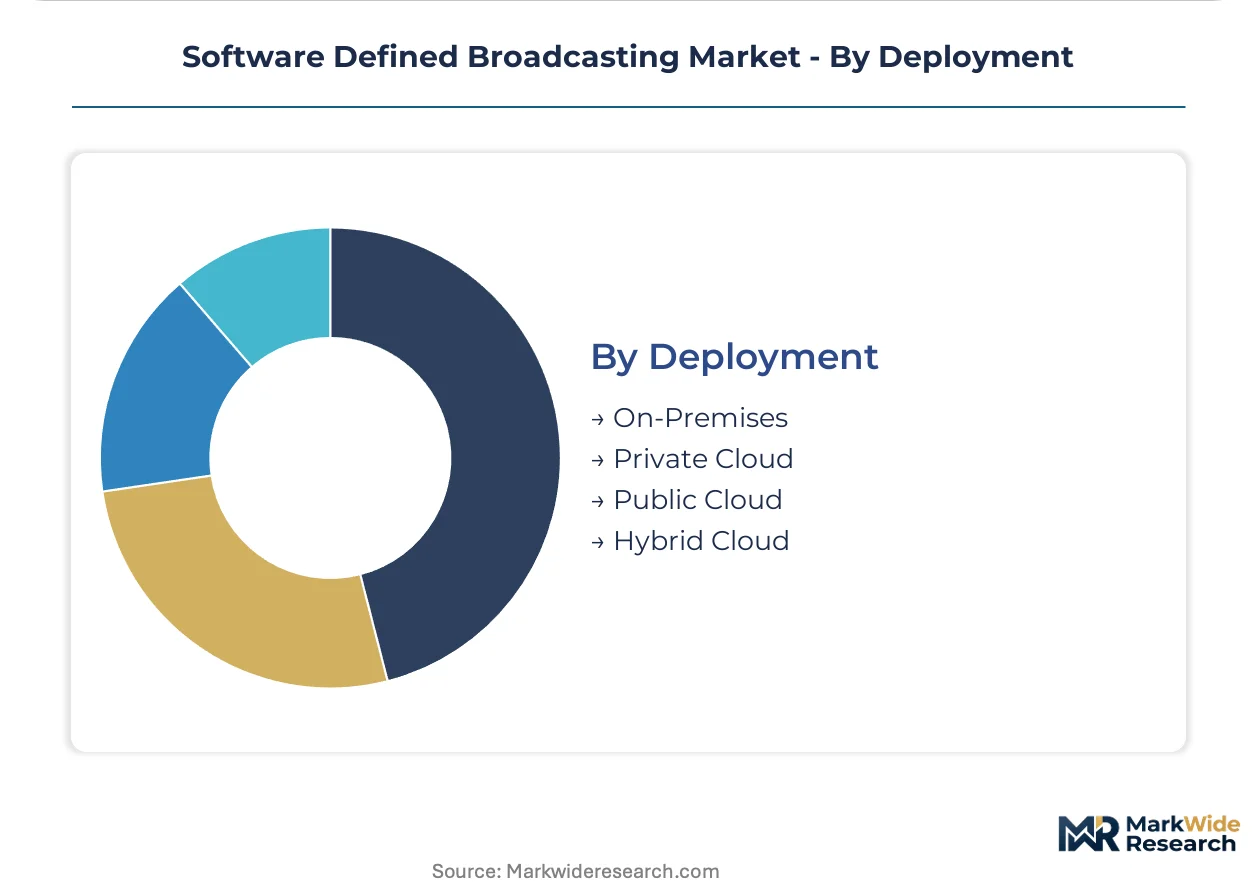
- On-Premises:Fixed-cost infrastructure with captive compute, storage, and networking assets under direct operational control. National broadcasters with long-term transponder leases favor this model to avoid stranded asset risk and cloud egress pricing volatility.
- Hybrid Cloud:Burst capacity orchestration across private data centers and hyperscaler pools with Kubernetes-native workload portability. Tier-one broadcasters in Germany and the United Kingdom deploy this architecture for disaster recovery scaling and peak event primary playout.
- Private Cloud:Dedicated tenant infrastructure with single-organization resource isolation and customized kernel scheduling.
- Public Cloud:Shared-tenant hyperscaler services with consumption-based pricing and managed service abstractions.
On-Premises retains favor among spectrum-licensed operators. Hybrid Cloud is expanding most quickly as orchestration maturity improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains dominant infrastructure position through its dense fiber backhaul interconnects and ATSC 3.0 deployment corridors, while Germany's broadcast manufacturing clusters and 5G testbeds anchor European capacity. Regulatory momentum across both markets is compressing procurement timelines for software-defined transmission equipment.
United States
The FCC's ATSC 3.0 mandate drives terrestrial broadcaster infrastructure refresh, particularly in congested metropolitan markets where emission mask compliance requires software-defined exciter deployment. The regulator's spectrum repacking proceedings have tightened adjacent-channel protection standards, forcing shorter capital cycles. New York and Los Angeles media clusters host the densest concentration of virtualization trials, with broadcasters consolidating master control operations through Kubernetes-orchestrated playout.
Germany
Public broadcasters ARD and ZDF anchor 3GPP Release 16 multicast-broadcast trials over commercial mobile networks, validating software-defined core integration for mass-market distribution. The country's national media regulator enforces local content custody rules that favor hybrid cloud architectures over full public cloud migration. Bavaria's manufacturing corridor around Munich hosts deep technical expertise in RF-to-IP transition engineering, with Rohde & Schwarz maintaining captive development facilities.
United Kingdom
Ofcom's IP transition timeline consultations are accelerating procurement decisions among commercial broadcasters and platform operators seeking regulatory clarity. The regulator's framework proceedings shape cross-border signal carriage rules that determine software-defined implementation eligibility. London's media technology cluster concentrates vendor integration expertise, while Manchester and Salford house major BBC technical operations undergoing virtualization migration.
Japan
METI coordinates national broadband infrastructure policy that underpins IP broadcast migration timelines for terrestrial and satellite operators. The ministry's spectrum efficiency directives push broadcasters toward software-defined modulation to maximize limited UHF allocation. Tokyo's Kanto region hosts concentrated R&D partnerships between broadcasters and telecommunications operators testing converged multicast-unicast architectures.
South Korea
The country's national spectrum authority drives 5G broadcast standardization aligned with 3GPP Release 16, creating immediate demand for virtualized core network functions. Local content regulations require domestic custody of broadcast streams, favoring private cloud deployment models over hyperscaler dependence. Seoul's media technology district houses concentrated expertise in real-time kernel scheduling for sub-50 millisecond live production latency.
Software Defined Broadcasting Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers: broadcast-native incumbents with RF heritage, telecommunications equipment vendors with 5G core expertise, and cloud-native software specialists with container orchestration platforms. Strategic archetypes include integrated transmission stack providers, modular component suppliers, and managed service operators. Dominant competitive moves center on API ecosystem partnerships with CDN operators and vertical integration into GPU-accelerated compute hardware.
Within the broadcast-native tier, Harmonic Inc. and Evertz Microsystems Ltd. occupy positions exemplifying divergent architectural philosophies, while Ericsson AB represents telecommunications vendor convergence on media workloads. Rohde & Schwarz GmbH & Co KG anchors European manufacturing depth with public sector procurement relationships. These named entities illustrate how vendor competitive positioning stratifies across RF-to-IP transition expertise, cloud-native software maturity, and 5G broadcast core integration capabilities.
| Leading Market Players |
|---|
| Harmonic Inc. |
| Imagine Communications Corp. |
| Ericsson AB |
| ARRIS International plc |
| Rohde & Schwarz GmbH & Co KG |
| Broadcast Electronics, Inc. |
| Grass Valley |
| Evertz Microsystems Ltd. |
| Avid Technology Inc. |
| Others |
Value Network & Pricing Analysis
Bavaria's manufacturing corridor around Munich concentrates RF-to-IP engineering capacity, with Rohde & Schwarz maintaining captive development facilities that anchor premium-tier pricing power for broadcast-native transmission stacks. This geographic concentration of specialized talent and vertical integration enables incumbent vendors to defend margin structures against commoditization pressures from cloud-native software specialists.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with premium tiers capturing GPU-accelerated real-time kernel scheduling and SIL-rated deterministic guarantees. Price differentiation rests on certification grade for emission mask compliance and after-sales service bundling with guaranteed availability SLAs. Pricing pressure stems from hyperscaler cloud egress volatility eroding centralized playout economics. Streaming platforms exhibit highest price sensitivity through subscription-based encoder procurement, while national broadcasters with spectrum licenses accept premium tiers for custody compliance.
Supply Chain Analysis
Contract manufacturing for commercial off-the-shelf servers concentrates with Foxconn, Wistron, and Jabil facilities in Taiwan and China, while GPU acceleration silicon flows from NVIDIA and AMD foundry partnerships in Taiwan and South Korea. Raw material dependencies include advanced packaging substrates, high-bandwidth memory modules, and precision RF components. Single-source vulnerability in GPU accelerator supply creates exposure to foundry allocation constraints. Distribution runs through direct vendor relationships with national broadcasters and telecommunication operators, supplemented by systems integrator channels for multinational media enterprises.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software defined broadcasting represents a service-attach opportunity where subscription-based encoder access with guaranteed availability SLAs expands faster than perpetual license hardware, concentrating purchasing authority with CTO organizations.
For Market Incumbents: Harden API ecosystem partnerships with CDN operators to defend against cloud-native software specialists disintermediating transmission stacks. Deepen backward integration into GPU-accelerated compute hardware to secure supply allocation and differentiate real-time performance guarantees. Lock in long-term procurement relationships with German and United Kingdom public broadcasters before Ofcom's IP transition timelines accelerate competitive tendering. For New Entrants and Emerging Players: Pursue edge node virtualization for CDN origin function absorption, where encoding-packaging-caching convergence creates white-space unclaimed by broadcast-native incumbents. Target South Korean private cloud deployment models constrained by local content custody regulations, using Kubernetes-native channel origination as the go-to-market wedge against legacy master control room vendors. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors telecommunications equipment vendors with 5G broadcast core expertise over pure-play broadcast hardware incumbents, as 3GPP Release 16 multicast-broadcast services validate software-defined core integration. Long-term viability hinges on API orchestration capabilities spanning RF-to-cloud workflows. Monitor spectrum reallocation proceedings and cloud egress pricing regime shifts as inflection indicators for centralized versus edge-dense architecture economics.| Strategic Initiative | Industry Significance |
|---|---|
| API Ecosystem Partnership | CDN operator integration collapses encoding-packaging-delivery tiers into single orchestration layers. |
| GPU-Accelerated Hardware Integration | NVIDIA and AMD silicon scheduling enables sub-50 millisecond deterministic latency for live production. |
| 5G Broadcast Core Certification | 3GPP Release 16 validation unlocks telecommunication operator procurement authority in Germany and South Korea. |
| Hybrid Cloud Orchestration Platform | Kubernetes-native workload portability addresses disaster recovery scaling for tier-one broadcasters. |
| Subscription-Based Encoder Access | Guaranteed availability SLAs align vendor incentives with streaming platform uptime requirements. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with broadcast engineering directors, telecommunication network planners, CTOs at streaming platforms, and procurement leads at national media regulators. Secondary validation drew from FCC spectrum proceeding filings, Ofcom framework consultation documents, EBU technical specifications, ITU-R broadcasting interoperability standards, and hyperscaler capex disclosures for cloud infrastructure expansion. Bottom-up segment sizing triangulated against top-down market construction across technology, application, end user, and deployment dimensions.
Calibration against historical infrastructure refresh cycles and regulatory mandate timelines shaped the analytical framework across the projection horizon. Segmentation modeled technology architecture, content format timing, organizational type capital cycles, and infrastructure location economics. CAGRs derived from elasticity coefficients linking software-defined capacity scaling to broadcast transmission volume growth, with cross-validation against GPU accelerator shipment trends and 5G broadcast trial deployment schedules.
Sensitivities concentrate around spectrum reallocation timing, cloud egress pricing volatility, and RF engineer availability constraints in non-core geographies. Forecasts reflect documented assumptions regarding ATSC 3.0 compliance deadlines and 3GPP Release 16 commercialization trajectories. Quarterly review of FCC and Ofcom proceeding dockets, hyperscaler data transfer pricing announcements, and German public broadcaster trial outcomes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Document Capture Software Market
Software & Services
Global Reference Check Software Market
Software & Services
Architectural Rendering Software Market
Software & Services
Australia HR Payroll Software Market
Software & Services
Collaboration Software Market
Software & Services
Mobile Backend As a Service (Mbaas) Market
Software & Services
Attendance Tracking Software Market
Software & Services
Global Political Campaign Software Market
Software & Services
Account-Based Advertising Software Market
Software & Services
Clustering Software Market
Software & Services
Construction Enterprise Resource Planning (ERP) Software Market
Software & Services
Debt Collection Software Market
Software & Services
Customer Self-Service Software Market
Software & Services
Global Disclosure Management Software Market
Software & Services
Workflow Automation and Optimization Software Market
Software & Services
North America Automotive Software Market