
 CRISPR Gene Editing Market | 2026-2036
CRISPR Gene Editing Market Size, Share, and Industry Trends Forecast 2026-2036
CRISPR Gene Editing Market Insights
A shift from single-source CRISPR reagent supply toward multi-source procurement is rebalancing vendor relationships across pharmaceutical and academic labs. Thermo Fisher Scientific leverages its scale to dominate plasmid and protein distribution networks. CRISPR Therapeutics AG anchors its position through therapeutic pipeline depth rather than tool sales. Intellia Therapeutics competes by specializing in in vivo gene editing platforms for rare diseases.
CRISPR gene editing employs RNA-guided Cas nucleases to introduce targeted double-strand breaks at specific genomic loci, enabling precise deletion, insertion, or modification of DNA sequences with single-base-pair resolution. The technology serves biomedical research, therapeutic development, and agricultural trait engineering by accelerating genotype-to-phenotype validation. Gene editing kits command the largest revenue share among product types due to recurring consumable demand from high-throughput screening workflows. Therapeutics represents the fastest-expanding application segment as multiple programs advance through Phase II trials. Academic institutions sustain steady volume demand for foundational research tools, though pharmaceutical companies generate higher per-account spending.
FDA gene therapy guidance and EMA's ATMP framework shape clinical trial design, manufacturing quality standards, and commercialization pathways for CRISPR-based therapeutics in the United States and Europe. China's NMPA biologics regulations and national dual carbon goals indirectly influence agricultural biotechnology applications by tightening environmental release protocols for gene-edited crops. Stakeholders must monitor evolving germline editing policy positions from WHO and national academies, as these declarations will constrain or enable future therapeutic expansion beyond somatic cell targets.
Market Dynamics
The CRISPR gene editing market pivots on the tension between therapeutic pipeline maturation and manufacturing scale constraints, as clinical-grade viral vector supply bottlenecks throttle Phase II trial expansion.
Growth Catalysts
- FDA Gene Therapy Guidance:The 2023 FDA guidance on long-term follow-up studies for gene therapies streamlines IND submission pathways, compressing pre-clinical-to-Phase-I timelines for oncology programs.
- Base Editing Platforms:Cytosine and adenine base editors enable precise single-nucleotide conversions without double-strand breaks, expanding addressable targets in hematopoietic stem cell applications.
- Boston-Cambridge Cluster:Concentrated biopharma R&D spending across Massachusetts and adjacent hubs sustains demand for high-complexity CRISPR reagents and specialized CRO services.
Market Restraints
- Plasmid DNA Supply Concentration:Three contract manufacturers control majority GMP plasmid capacity, creating queue delays for viral vector production essential for in vivo delivery.
- EMA ATMP Manufacturing Complexity:EMA's Advanced Therapy Medicinal Products framework imposes batch release testing requirements that extend cell therapy production cycles by 4-6 weeks.
- Off-Target Editing Detection:Current GUIDE-seq and CIRCLE-seq methods impose 8-12 week analytical timelines, constraining IND-enabling toxicology study throughput.
Strategic Opportunities
- Epigenome Editing Convergence:dCas9 fusion proteins with DNA methyltransferases and histone modifiers enable reversible gene regulation without permanent genomic alteration, opening chronic disease applications.
- India CDMO Expansion:India's PLI scheme for biopharmaceutical manufacturing attracts CRISPR reagent production investment, diversifying supply sources beyond US-EU-China concentration.
- Allogeneic Cell Therapy Standardization:Off-the-shelf CAR-T programs using CRISPR-mediated TRAC and B2M knockout reduce patient-to-patient manufacturing variability and per-dose cost structures.
Industry Challenges
- Gene Editing Workforce Scarcity:Shortage of GMP-grade cell culture specialists and analytical development scientists extends hiring cycles to 4-7 months for manufacturing scale-up teams.
- IP Licensing Thickets:Overlapping Broad Institute, UC Berkeley, and ToolGen patent estates force multi-party negotiation for commercial programs, inflating pre-clinical development budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CRISPR Gene Editing Market |
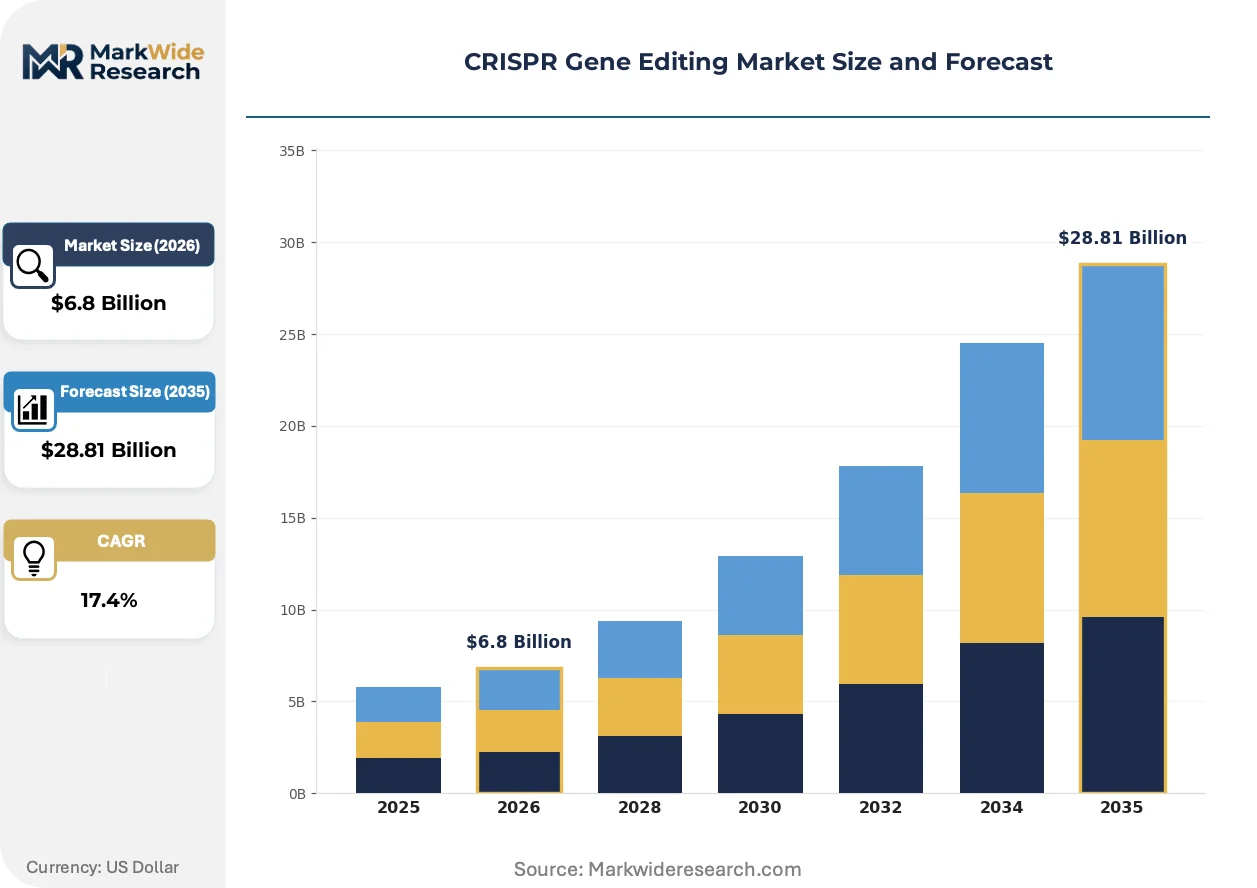
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $28.81 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plasmids, Cas Proteins, Guide RNA, Gene Editing Kits Application: Biomedical Research, Genetic Engineering, Agricultural Biotechnology, Therapeutics End User: Pharmaceutical Companies, Academic Institutions, Biotechnology Firms, Contract Research Organizations Technology: Gene Knockout, Gene Correction, Gene Replacement, Epigenetic Editing |
| Companies Covered | Thermo Fisher Scientific Inc., Merck KGaA, Lonza, QIAGEN, GenScript, Agilent Technologies Inc., CRISPR Therapeutics AG, Intellia Therapeutics Inc., Editas Medicine Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CRISPR Gene Editing Market Trends and Innovations
Machine learning-guided guide RNA design is compressing target validation timelines while regulatory frameworks crystallize around somatic versus germline editing boundaries.
Prime editing is converging with lipid nanoparticle delivery systems to enable direct liver-targeted correction of monogenic metabolic disorders. Biopharma companies including rare disease specialists are advancing prime editor programs through pre-clinical toxicology. This convergence is displacing earlier viral vector strategies for indications where transient editor expression suffices.
EMA's ATMP framework revision tightens comparability requirements for CRISPR-edited cell products manufactured across multiple sites. Sponsors must now demonstrate equivalent editing efficiency and product purity across manufacturing location changes. European oncology programs are responding by consolidating production at single GMP facilities rather than distributed networks.
Academic core facilities are consolidating CRISPR reagent purchasing through cooperative procurement consortia, displacing individual lab direct orders. University systems in California and Texas have established multi-institutional contracts with preferred distributors. This concentration is most visible in high-throughput screening applications where kit volumes justify negotiated pricing tiers.
CRISPR Gene Editing Market Segmentation
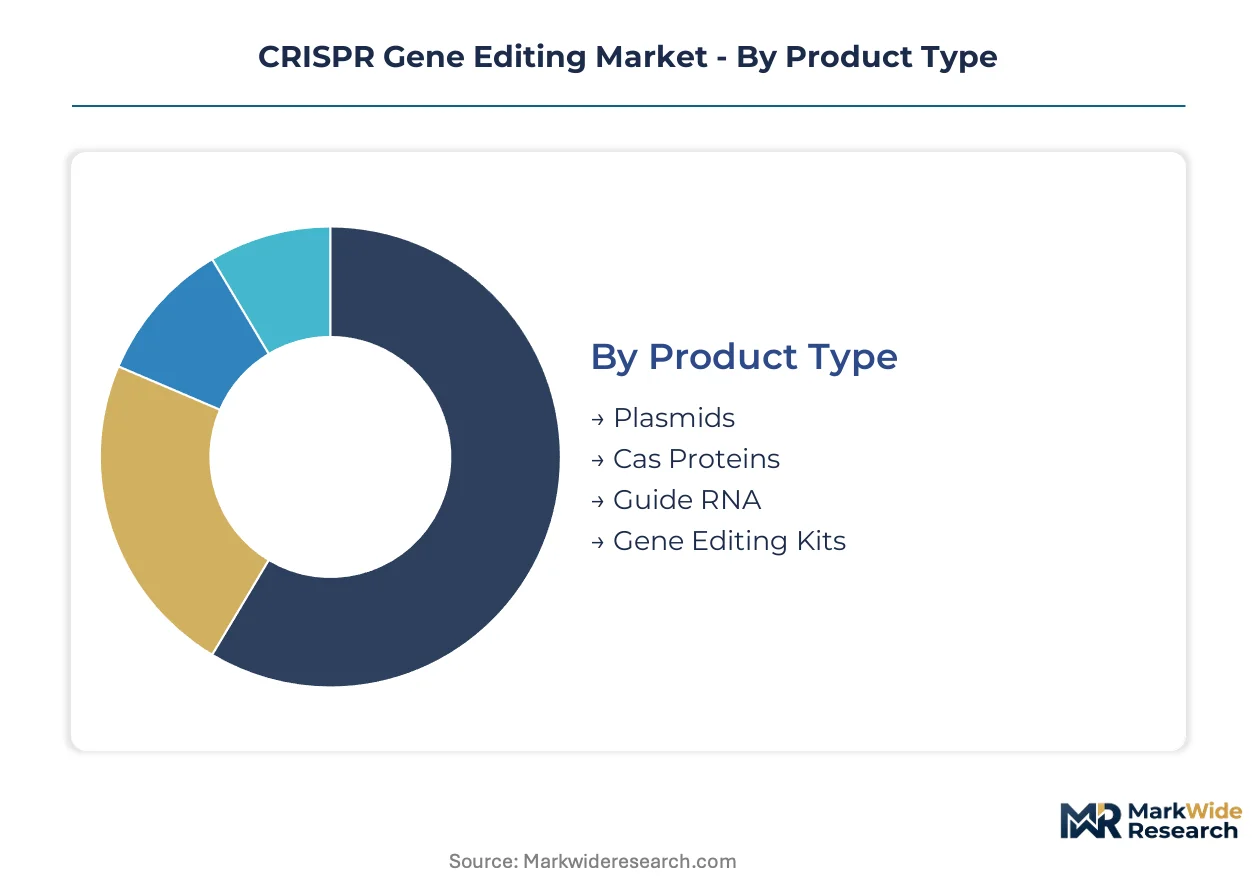
Segmentation in the CRISPR gene editing market reveals distinct capital allocation patterns across reagent supply, therapeutic development, and service delivery. Each dimension carries implications for margin structure, customer lifetime value, and regulatory pathway complexity.
Product Type:
Capital intensity concentrates in protein manufacturing and GMP-grade kit assembly, while plasmid production benefits from established fermentation infrastructure.
- Gene Editing Kits:Complete workflow solutions bundle Cas nucleases, guide RNA synthesis reagents, and delivery vectors into standardized protocols. Pharmaceutical companies in Massachusetts and Switzerland generate recurring high-volume orders for high-throughput screening campaigns.
- Cas Proteins:Recombinant nuclease production demands specialized bioreactor capacity and extensive purification validation. Supply bottlenecks at GMP-grade specifications create queue delays for therapeutic developers.
- Plasmids:Circular DNA vectors for guide RNA expression require less downstream processing than proteins.
- Guide RNA:Synthetic RNA oligonucleotides scale through solid-phase chemistry platforms.
Gene editing kits absorb the bulk of installed capacity; Cas proteins are expanding most quickly.
Application:
Margin profiles diverge sharply between consumable-driven research applications and capital-intensive therapeutic programs.
- Therapeutics:In vivo and ex vivo gene editing programs command the highest per-project spending as sponsors navigate IND-enabling studies and Phase I/II trials. FDA gene therapy guidance and EMA's ATMP framework shape clinical trial design and manufacturing quality standards in the United States and Germany.
- Biomedical Research:Academic core facilities and pharmaceutical discovery groups sustain steady demand for foundational validation tools. CRISPR knockout screens in oncology target identification represent the largest volume use case.
- Agricultural Biotechnology:Trait engineering in row crops and specialty produce faces environmental release protocol constraints.
- Genetic Engineering:Industrial microbiome modification and cell line development support bioproduction applications.
Therapeutics captures the steepest expansion trajectory; biomedical research maintains the broadest installed base.
End User:
Procurement sophistication and contract scale separate enterprise pharmaceutical buyers from fragmented academic purchasing.
- Pharmaceutical Companies:Integrated drug developers in the Boston-Cambridge cluster and Swiss biotech hubs negotiate multi-year supply agreements with volume-tiered pricing. Per-account spending far exceeds other customer categories due to therapeutic pipeline investment.
- Academic Institutions:University core facilities in California and Texas have consolidated purchasing through cooperative procurement consortia, displacing individual lab direct orders.
- Biotechnology Firms:Venture-backed gene editing specialists prioritize platform access over reagent ownership.
- Contract Research Organizations:Service providers in India and Germany absorb demand from sponsors lacking in-house editing infrastructure.
Pharmaceutical companies dominate absolute spending; biotechnology firms are gaining share fastest.
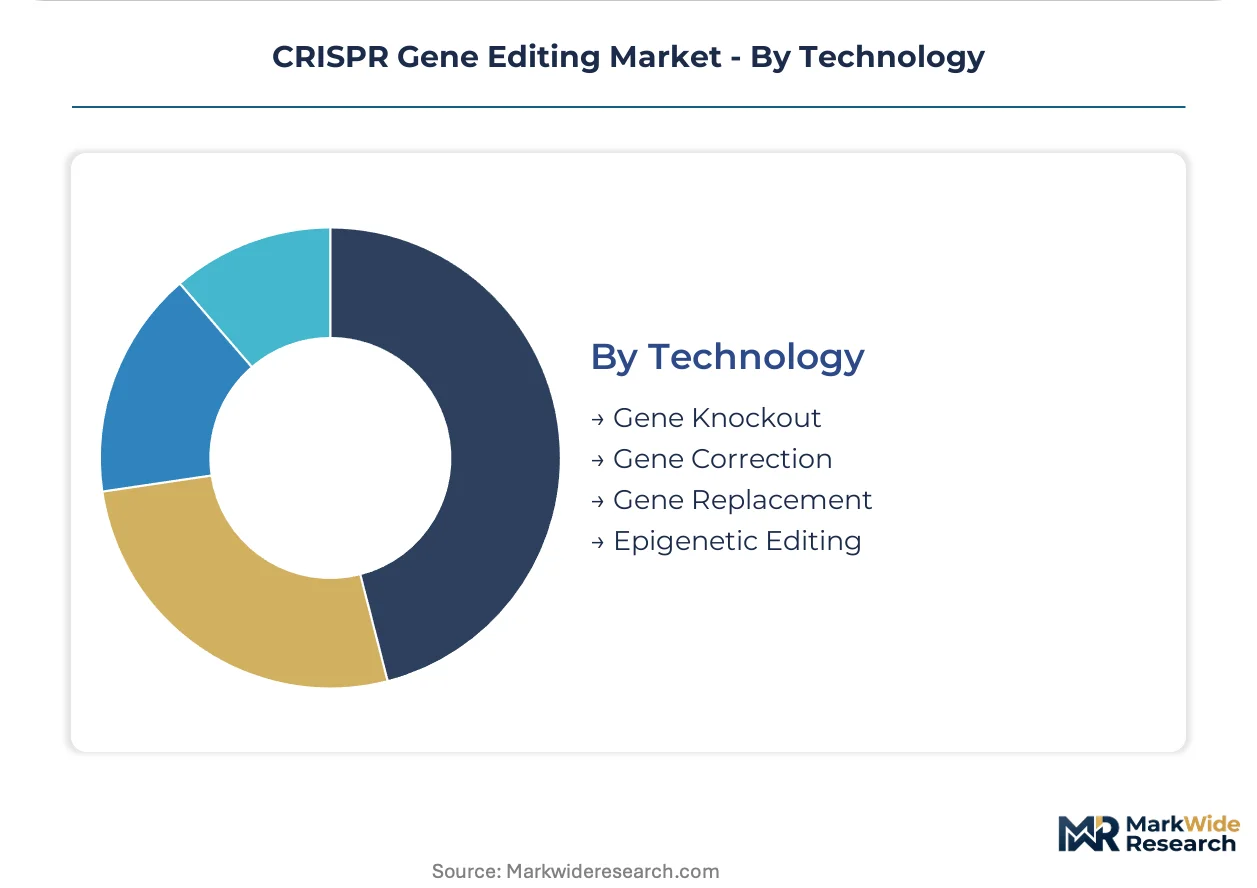
Technology:
Technical maturity and regulatory familiarity determine commercial readiness across editing modalities.
- Gene Knockout:Disruption of target loci through non-homologous end joining represents the most validated approach with extensive safety data. Academic screening applications and allogeneic CAR-T programs in the United States leverage this established methodology.
- Epigenetic Editing:dCas9 fusion proteins enable reversible gene regulation without permanent genomic alteration, opening chronic disease applications where transient intervention suffices.
- Gene Correction:HDR-mediated repair introduces precise sequence changes at target loci.
- Gene Replacement:Cassettes for functional gene insertion address null mutations.
Gene knockout commands the deepest clinical experience; epigenetic editing is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical pipeline investment concentrates in three national clusters where FDA, EMA, and NMPA frameworks govern clinical trial progression. Manufacturing capacity and research infrastructure align with these regulatory jurisdictions.
United States
Oncology programs and allogeneic cell therapies drive CRISPR therapeutic demand. FDA gene therapy guidance streamlines IND submissions for sponsors. The Boston-Cambridge cluster hosts concentrated biopharma R&D spending and specialized CRO services.
Germany
EMA's ATMP framework shapes manufacturing quality standards for European programs. Batch release testing extends production cycles. Heidelberg and Munich anchor cell therapy manufacturing infrastructure for continental distribution.
Switzerland
Swissmedic regulations align with EMA standards while offering streamlined pathways for innovative therapies. Basel and Zurich concentrate gene editing specialists serving pharmaceutical partners. Venture capital flows toward platform technology developers.
China
NMPA biologics regulations tighten environmental release protocols for agricultural applications. Dual carbon goals influence trait engineering priorities. Shanghai and Shenzhen biotech parks host expanding CRISPR reagent manufacturing capacity.
India
CDSCO oversight governs biopharmaceutical manufacturing standards. The PLI scheme attracts CRISPR reagent production investment. Hyderabad and Bengaluru CDMOs diversify supply sources beyond traditional US-EU-China concentration.
CRISPR Gene Editing Market Competitive Landscape
Capacity expansion dominates the current landscape as contract manufacturers race to relieve GMP plasmid bottlenecks. The vendor base separates into three tiers: integrated life science conglomerates, therapeutic platform specialists, and regional reagent suppliers. Two strategic archetypes predominate: scale-driven distributors leveraging logistics networks, and pipeline-depth players monetizing clinical progress rather than tool sales. M&A activity and strategic licensing partnerships represent the primary competitive vectors as patent thickets force multi-party negotiations.
Among integrated conglomerates, Thermo Fisher Scientific Inc. exemplifies scale-driven distribution dominance through plasmid and protein networks. Merck KGaA and Lonza occupy positions anchoring European manufacturing infrastructure for GMP-grade reagents. These three represent contrasting archetypes: one leverages consumable volume, another emphasizes chemical synthesis integration, and the third concentrates on cell therapy contract manufacturing capacity.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Lonza |
| QIAGEN |
| GenScript |
| Agilent Technologies Inc. |
| CRISPR Therapeutics AG |
| Intellia Therapeutics Inc. |
| Editas Medicine Inc. |
| Others |
Pricing and Supply Chain Analysis
GMP-grade cell culture specialists concentrated in Massachusetts and Switzerland command wage premiums that compress margins for GMP plasmid production while widening spreads between research-grade and clinical-grade pricing tiers.
Pricing Analysis
Service bundling separates validated GMP protocols with regulatory documentation from unbundled research-grade reagents lacking batch release support. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with pharmaceutical sponsors in the Boston-Cambridge cluster showing least price sensitivity. Cost compression in research-grade kits is intensifying because academic consortia negotiate collective procurement contracts. Biotechnology firms with platform licensing needs face highest price sensitivity due to cash runway constraints.
Supply Chain Analysis
India's PLI scheme for biopharmaceutical manufacturing is reshaping sourcing patterns by incentivizing domestic-content thresholds for CRISPR reagent production. Supply concentrates in the United States, Germany, and China for GMP-grade Cas proteins, plasmid DNA vectors, and synthetic guide RNA oligonucleotides. Raw material dependencies include recombinant E. coli fermentation stocks, solid-phase synthesis resins, and viral vector packaging cell lines. Single-source vulnerability for GMP plasmid capacity creates queue delays for therapeutic developers. Distribution runs through specialized life science distributors and direct pharmaceutical supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
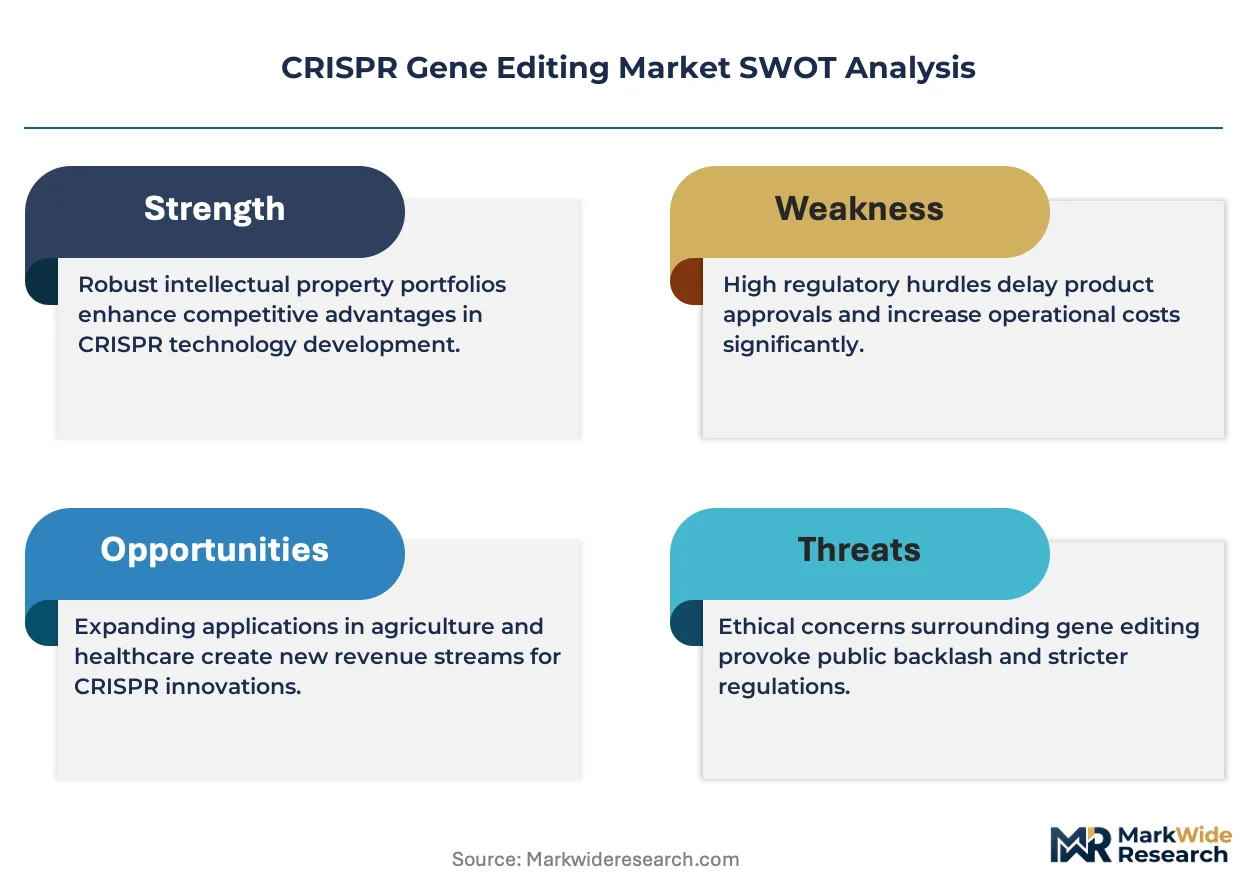
GMP plasmid manufacturing bottlenecks prop pricing power for contract manufacturers with validated capacity, making supply-constrained execution the defining competitive variable.
For Market Incumbents: Deepen backward integration into GMP-grade protein bioreactor capacity to offset queue delays threatening Phase II trial timelines. Lock in multi-year supply agreements with pharmaceutical sponsors before India's CDMO expansion matures. Patent thickets around Broad Institute and UC Berkeley estates require proactive licensing strategy to defend margin position against emerging platform specialists. For New Entrants and Emerging Players: Mid-tier biotechnology firms lacking in-house editing infrastructure represent the most penetrable buyer archetype for specialized CRO services. Target agricultural biotechnology applications in China where NMPA environmental release protocols create demand for compliant trait engineering support. A fee-for-service model with regulatory documentation packages offers lower barrier to entry than therapeutic platform development. For Investors and Strategic Acquirers: The window for entry favors CDMOs with GMP plasmid capacity expansion underway in India or Germany. Long-term viability hinges on manufacturing scale rather than tool innovation as clinical pipelines mature. Watch FDA gene therapy guidance revisions as the inflection signal for IND submission velocity and reagent demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Plasmid Capacity Expansion | Relieves viral vector production bottlenecks throttling Phase II oncology programs. |
| Base Editing Platform Licensing | Enables single-nucleotide corrections without double-strand break risks for hematopoietic applications. |
| Prime Editing-LNP Convergence | Displaces viral vectors for liver-targeted monogenic disorder correction. |
| Allogeneic CAR-T Standardization | Reduces patient-to-patient manufacturing variability through CRISPR-mediated knockout protocols. |
| Epigenome Editing Partnership | Opens chronic disease applications via reversible dCas9 fusion regulation without permanent alteration. |
Research Methodology
Independent corroboration across gene therapy development executives, regulatory affairs leads at EMA and FDA, GMP manufacturing specialists, and academic core facility directors underwrites the qualitative findings. Secondary validation draws from FDA gene therapy guidance documents, EMA ATMP framework revisions, ClinicalTrials.gov registry entries, and SEC filings of publicly traded CRISPR platform companies. Bottom-up demand modeling from reagent procurement volumes triangulates against top-down therapeutic pipeline investment flows.
Rate-of-change decomposition separates volume expansion in research applications from value concentration in therapeutic programs across the analysis window. Segmentation dimensions include product type, application, end user, and technology modality. CAGRs derive from fitted growth curves against historical procurement data and pipeline advancement timelines. Forecast inputs incorporate FDA IND submission velocity and EMA batch release testing cycle extensions.
Revisions become necessary when germline editing policy positions from WHO or national academies shift, or when GMP plasmid supply concentration resolves through capacity additions. Forecasts reflect assumptions about regulatory pathway stability and manufacturing scale-up execution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gene Editing & CRISPR
Global Recombinant DNA (Rdna) Technology Market
Gene Editing & CRISPR
Genetically Modified Animal Model Market
Gene Editing & CRISPR
CAS9 Technology Market
Gene Editing & CRISPR
Gene Editing Market
Gene Editing & CRISPR
Spain Gene Editing Market
Gene Editing & CRISPR
China Gene Editing Market
Gene Editing & CRISPR
DNA Modifying Agents Market
Gene Editing & CRISPR
Immunodeficient Mouse Models Market
Gene Editing & CRISPR
Brazil Gene Editing Market
Gene Editing & CRISPR
CRISPR Genomic Cure Market
Gene Editing & CRISPR
CRISPR Gene Detection and Diagnostic Market
Gene Editing & CRISPR
CRISPR Technology Market
Gene Editing & CRISPR
Global CRISPR and Cas Genes Market
Gene Editing & CRISPR
France Gene Editing Market
Gene Editing & CRISPR
Italy Gene Editing Market
Gene Editing & CRISPR
Cas9 Nuclease Market