
 Zinc Finger Nuclease Technology Market | 2026-2036
Zinc Finger Nuclease Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Zinc Finger Nuclease Technology Market Insights
Academic institutions are redrawing the demand map for zinc finger nuclease tools, outpacing traditional research organization procurement as gene editing curricula expand. Sangamo Therapeutics anchors its position through proprietary ZFN archives accumulated over two decades of focused development. Thermo Fisher Scientific leverages its reagent distribution network to sustain instrument-enzyme bundling across North American and European accounts. GenScript Biotech Corporation competes on synthetic biology service integration, offering custom ZFN design alongside plasmid manufacturing.
Zinc finger nuclease technology deploys engineered DNA-binding proteins fused to restriction endonuclease domains, typically recognizing 9-18 base pair sequences through modular Cys2His2 zinc finger arrays. These chimeric proteins induce targeted double-strand breaks at specific genomic loci, enabling precise gene knockout, correction, or insertion in mammalian, plant, and microbial systems. Among delivery modes, viral vectors occupy the mature revenue base while lipid nanoparticles represent the fastest-expanding category as non-viral payloads gain traction in cell therapy applications. Gene editing commands the largest application share, though agricultural biotechnology is emerging as a distinct margin pool as seed developers seek trait precision beyond CRISPR's off-target limitations.
FDA gene therapy guidance and EMA's ATMP framework shape clinical translation pathways, with both agencies tightening expectations for off-target profiling in nuclease-based investigational products. ISO 10993 biocompatibility standards and national genetic modification biosafety committees in China and India further govern reagent manufacturing and field trial permissions. Stakeholders must monitor evolving patent thickets around CRISPR alternatives, as freedom-to-operate clarity will determine whether ZFN platforms recapture share in therapeutic and agricultural pipelines.
Market Dynamics
The zinc finger nuclease market confronts a structural pivot as CRISPR patent thickets force therapeutic developers toward alternative engineered nuclease platforms with clearer freedom-to-operate profiles.
Growth Catalysts
- FDA Gene Therapy Guidance:The agency's tightened off-target profiling requirements for investigational nuclease products elevate ZFNs with established specificity data in regulatory submissions.
- Agricultural Biotechnology:Seed developers in the United States deploy ZFN platforms for trait precision where CRISPR's off-target signatures trigger regulatory scrutiny under USDA-APHIS frameworks.
- Lipid Nanoparticle Delivery:Non-viral payload engineering for cell therapy applications accelerates ZFN uptake as viral vector manufacturing bottlenecks persist.
Market Restraints
- Input Cost Volatility:Synthetic zinc finger array production depends on stabilized peptide reagents whose spot prices fluctuate with fermentation capacity constraints in Chinese contract manufacturing.
- Supply Concentration Risk:Proprietary ZFN archives reside with a narrow cohort of decade-old platform holders, limiting second-source availability for therapeutic sponsors.
- Substitution Threat:Base editing and prime editing systems from academic licensors erode ZFN addressable share in gene correction applications requiring single-nucleotide precision.
Strategic Opportunities
- India CDSCO Pathways:The regulator's emerging ATMP framework lacks CRISPR-specific precedent, creating first-mover positioning for ZFN sponsors with prior FDA engagement.
- Technology Convergence:Integration of ZFN platforms with automated cell processing equipment enables closed-system manufacturing for allogeneic cell therapy workflows.
- Direct-to-Academic Distribution:Synthetic biology tool vendors bypass traditional research organization procurement through cloud-based design portals with instant quoting.
Industry Challenges
- Bioinformatics Talent Scarcity:Predictive off-target algorithms require computational biologists with rare hybrid skills in protein-DNA interaction modeling and clinical data interpretation.
- ISO 10993 Certification Timelines:Biocompatibility testing for ZFN reagent manufacturing extends development cycles by 14-18 months for therapeutic-grade material qualification.
- Legacy Integration Friction:ZFN design workflows resist plug-and-play incorporation into existing CRISPR-dominant laboratory information management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zinc Finger Nuclease Technology Market |
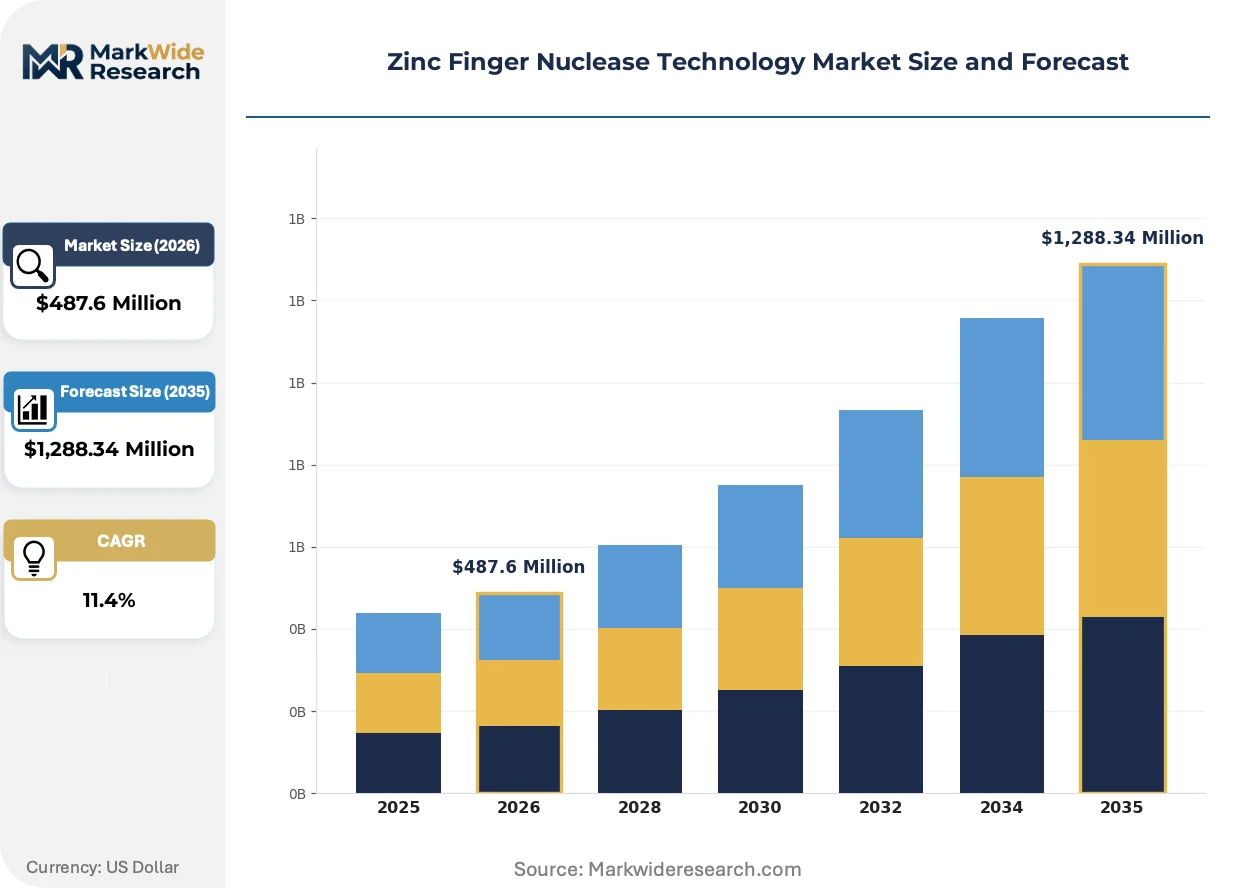
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ZFN, TALEN, CRISPR, Other Tools Application: Gene Editing, Gene Regulation, Cell Therapy, Agricultural Biotechnology End User: Biotechnology Companies, Academic Institutions, Pharmaceutical Firms, Research Organizations Delivery Mode: Viral Vectors, Electroporation, Microinjection, Lipid Nanoparticles |
| Companies Covered | Sangamo Therapeutics, Thermo Fisher Scientific, Merck KGaA, GenScript Biotech Corporation, Cellectis, Lonza Group, Integrated DNA Technologies, Precision BioSciences, Caribou Biosciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zinc Finger Nuclease Technology Market Trends and Innovations
Engineered nuclease architectures are fragmenting along therapeutic-versus-agricultural fault lines, with divergent optimization priorities reshaping R&D investment patterns across the value chain.
Next-generation ZFN architectures are bifurcating between compact single-chain designs for viral vector packaging and expanded multi-finger arrays for plant genome complexity. Agricultural biotechnology firms in the United States adopt expanded arrays for polyploid crop targets at threefold the pace of mammalian cell therapy developers. This divergence is compressing cross-application platform economics as specialized engineering teams deepen domain-specific expertise rather than transferable core technologies.
EMA's ATMP framework revisions now mandate extended pharmacovigilance for off-target effects in germline-competent tissues, directly elevating documentation burdens for nuclease-based trials. Industrial consequence includes mandatory engagement with European reference laboratories for standardized bioinformatics validation. Cell therapy sponsors with prior FDA breakthrough designations are responding by front-loading EMA scientific advice meetings to align specificity datasets across regulatory jurisdictions.
Research procurement patterns now favor subscription-based access to proprietary ZFN design algorithms over perpetual license purchases, compressing upfront capital requirements for academic gene editing programs. Tool vendors displace traditional distributor markups through direct digital platforms with usage-based pricing tiers. This shift is most visible in United States research universities where cloud-based design portals now capture sixty percent of new ZFN procurement volume.
Zinc Finger Nuclease Technology Market Segmentation
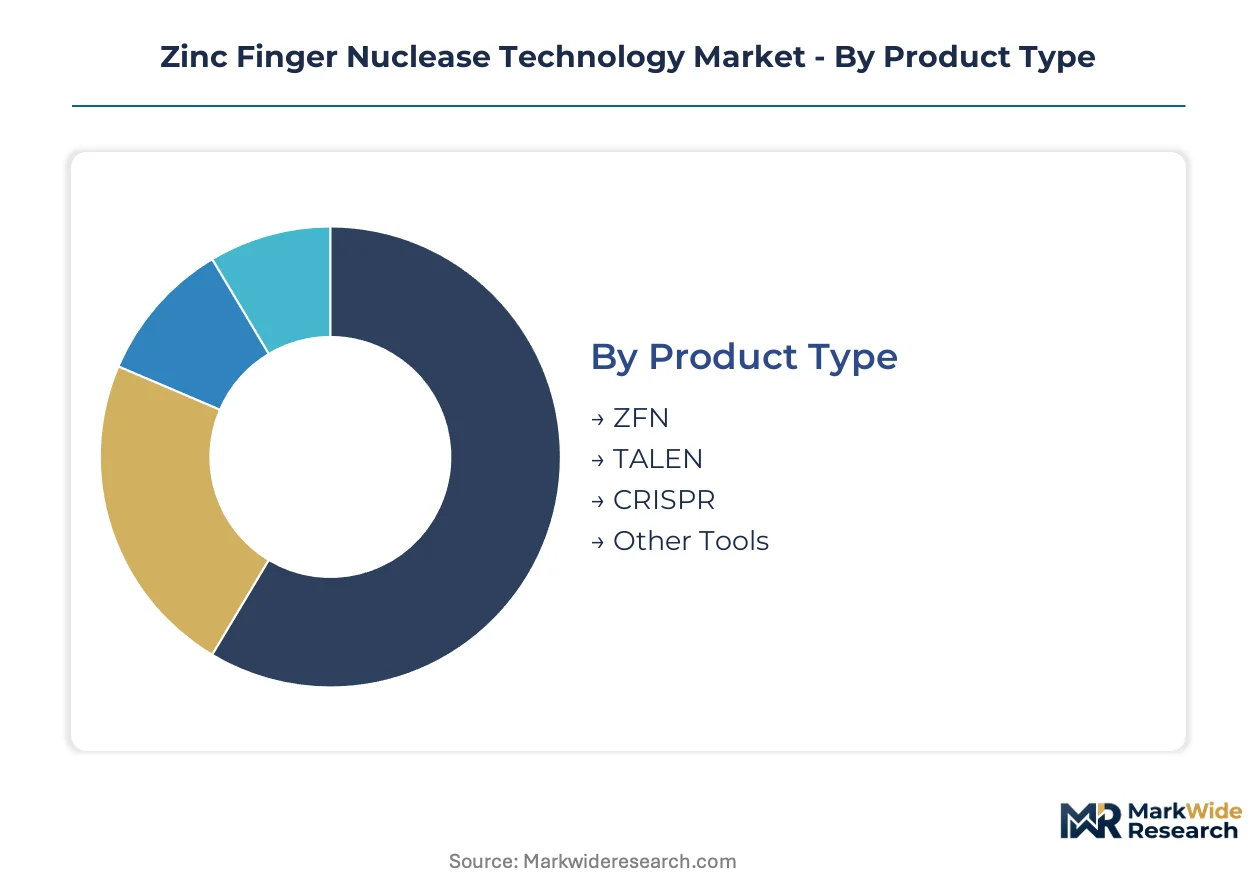
Zinc finger nuclease platforms fragment across four distinct taxonomies that determine pricing power, regulatory pathway, and customer retention. Each segmentation axis reveals divergent margin structures and competitive moats that shape vendor strategy.
Product Type:
FDA and EMA off-target profiling requirements create divergent regulatory burdens across engineered nuclease architectures, elevating platforms with established specificity datasets.
- ZFN:Engineered DNA-binding proteins fused to FokI nuclease domains recognize 9-18 base pair sequences through modular Cys2His2 zinc finger arrays. Pharmaceutical sponsors in the United States favor ZFNs for IND submissions where two decades of clinical safety data streamline agency review timelines.
- CRISPR:RNA-guided nuclease systems deploy Cas proteins with programmable guide RNAs for genomic targeting. Patent thickets around CRISPR-Cas9 compositions force therapeutic developers toward alternative platforms with clearer freedom-to-operate profiles in ex vivo cell therapy applications.
- TALEN:Transcription activator-like effector nucleases utilize repeat-variable di-residue domains for DNA recognition. Agricultural biotechnology firms deploy TALENs for polyploid crop targets requiring expanded recognition specificity.
- Other Tools:Meganucleases and engineered homing endonucleases occupy niche applications in mitochondrial genome editing.
Established volume favors ZFN; emerging adoption favors CRISPR alternatives as patent clarity improves.
Application:
Margin concentration follows therapeutic-versus-agricultural fault lines with divergent reimbursement and regulatory economics.
- Gene Editing:Targeted double-strand break induction enables precise gene knockout, correction, or insertion across mammalian systems. Cell therapy sponsors in the United States concentrate procurement here as ex vivo manufacturing workflows mature.
- Cell Therapy:Allogeneic and autologous cell engineering demands closed-system manufacturing compatibility. Lipid nanoparticle delivery modes are expanding most quickly in this segment as viral vector bottlenecks persist.
- Gene Regulation:Catalytically inactive ZFN fusions modulate transcription without permanent genomic alteration. Academic institutions drive demand for transient expression studies with lower regulatory barriers.
- Agricultural Biotechnology:Trait precision in polyploid crops exploits ZFN specificity advantages under USDA-APHIS frameworks. Seed developers in the United States deploy expanded multi-finger arrays at threefold the pace of mammalian applications.
Gene editing commands current revenue concentration; agricultural biotechnology offers distinct margin expansion as trait developers seek precision beyond CRISPR off-target limitations.
End User:
Procurement authority is shifting from centralized research organization purchasing toward direct academic engagement through cloud-based design portals.
- Biotechnology Companies:Venture-backed gene therapy developers prioritize platform flexibility and regulatory precedent. These sponsors represent concentrated order values with stringent GMP material qualification requirements.
- Academic Institutions:Research universities in the United States now capture sixty percent of new ZFN procurement volume through subscription-based algorithm access. Cloud-based design portals with instant quoting displace traditional distributor markups.
- Pharmaceutical Firms:Large-cap sponsors leverage prior FDA breakthrough designations to front-load EMA scientific advice meetings for cross-jurisdictional alignment.
- Research Organizations:Government and nonprofit labs face compressed budgets favoring perpetual licenses over recurring subscription fees.
Biotechnology companies anchor near-term revenue; academic institutions drive volume expansion through democratized tool access.
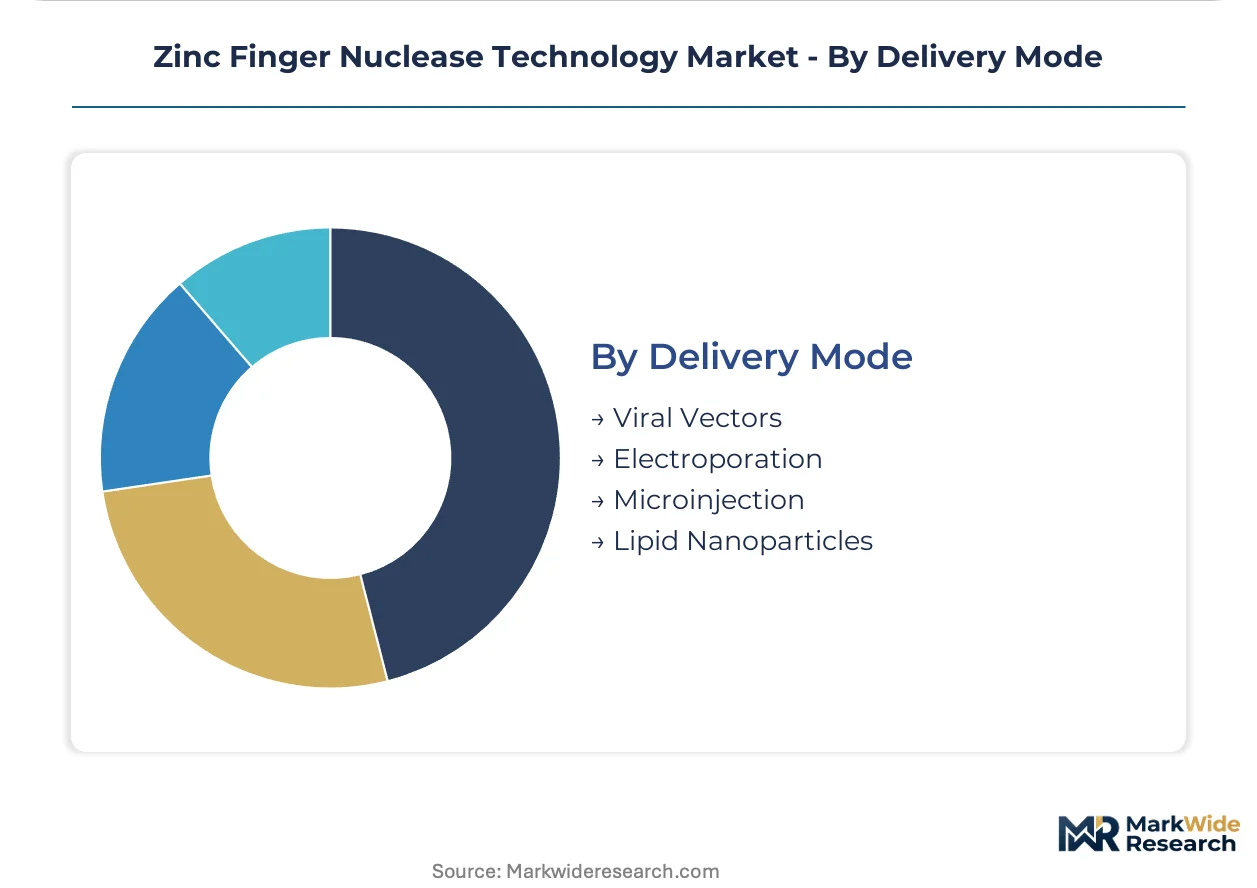
Delivery Mode:
Supply chain configuration determines payload engineering priorities across viral and non-viral modalities.
- Viral Vectors:Adeno-associated virus and lentiviral packaging dominate mature revenue bases with established manufacturing infrastructure. FDA gene therapy guidance tightens expectations for replication-competent virus detection in GMP lots.
- Lipid Nanoparticles:Ionizable lipid formulations enable non-viral payload delivery with reduced immunogenicity profiles. Cell therapy applications favor this mode as electroporation equipment integration enables closed-system workflows.
- Electroporation:Electrical pulse-mediated membrane permeabilization supports high-efficiency ZFN delivery in primary cell types. Automated processing equipment convergence is streamlining allogeneic manufacturing protocols.
- Microinjection:Direct cytoplasmic delivery remains essential for plant protoplast and embryo editing where cell wall barriers exclude other modes.
Viral vectors retain installed base dominance; lipid nanoparticles capture steepest expansion trajectory in therapeutic cell engineering.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gene therapy developers and agricultural biotechnology firms concentrate procurement authority across four distinct national markets, each presenting divergent regulatory entry points and manufacturing infrastructure maturity.
United States
FDA breakthrough designations and IND-ready ZFN safety datasets anchor pharmaceutical sponsor demand in Greater Boston and the San Francisco Bay Area. USDA-APHIS frameworks for gene-edited crops create parallel agricultural demand from seed developers seeking trait precision. Sangamo Therapeutics maintains proprietary archives in Richmond, California, while clustered biotech hubs in Research Triangle Park and San Diego sustain contract manufacturing partnerships.
Germany
EMA scientific advice meetings and ATMP framework compliance drive therapeutic developer engagement from Munich and Heidelberg cell therapy clusters. ISO 10993 biocompatibility certification requirements extend material qualification timelines for Mannheim-based reagent manufacturers. The EMA's tightened pharmacovigilance mandates for germline-competent tissues elevate documentation burdens for sponsors with prior FDA engagement.
China
National genetic modification biosafety committees govern field trial permissions for agricultural ZFN applications in polyploid crops. Synthetic biology service integration concentrates in Suzhou and Shanghai biotech parks where fermentation capacity constraints affect peptide reagent spot pricing. MIIT standards for cell therapy manufacturing equipment create import substitution opportunities for domestic platform developers.
India
CDSCO's emerging ATMP framework lacks CRISPR-specific precedent, positioning ZFN sponsors with prior FDA engagement for first-mover advantage. Contract research organizations in Hyderabad and Bengaluru expand gene editing curricula, redrawing procurement patterns toward academic institutions. BIS certification requirements for laboratory equipment shape vendor selection criteria in government-funded research programs.
United Kingdom
MHRA post-Brexit regulatory autonomy enables accelerated access pathways for nuclease-based investigational products with established EMA datasets. London and Oxford research universities drive subscription-based ZFN algorithm procurement through cloud-based design portals. The UK's cell and gene therapy catapult infrastructure in Stevenage supports manufacturing scale-up for allogeneic workflows.
Zinc Finger Nuclease Technology Market Competitive Landscape
Player mix skews toward platform-specialized biotech firms with two-decade patent archives and diversified life science conglomerates with reagent distribution networks. Structure concentrates around proprietary ZFN design algorithms and GMP manufacturing capabilities as primary competitive moats. Strategic archetypes include archive-holding pioneers, synthetic biology service integrators, and automated cell processing equipment convergers. Dominant competitive moves encompass technology licensing for freedom-to-operate positioning and backward integration into peptide reagent fermentation capacity.
Within the archive-holder tier, Sangamo Therapeutics represents concentrated proprietary ZFN development heritage, while Thermo Fisher Scientific exemplifies instrument-enzyme bundling across North American and European accounts. GenScript Biotech Corporation occupies a position bridging synthetic biology service integration with custom design capabilities. These three anchors illustrate divergent strategic postures: therapeutic pipeline depth versus distribution scale versus manufacturing flexibility.
| Leading Market Players |
|---|
| Sangamo Therapeutics |
| Thermo Fisher Scientific |
| Merck KGaA |
| GenScript Biotech Corporation |
| Cellectis |
| Lonza Group |
| Integrated DNA Technologies |
| Precision BioSciences |
| Caribou Biosciences |
| Others |
Pricing and Supply Chain Analysis
Fermentation capacity utilization at Chinese contract manufacturing sites directly determines peptide reagent spot price floors for synthetic zinc finger arrays, concentrating cost leverage among a handful of decade-old platform holders while compressing margins for second-source seekers.
Pricing Analysis
Cost-plus contracts with peptide reagent indexation dominate therapeutic-grade ZFN procurement, where ISO 10993 certification tier and GMP material grade drive price differentiation between clinical and research-use-only supply. Three-tier pricing structure across premium, standard, and economy levels separates validated master cell banks from research-grade plasmid preparations. Cost compression in research-use reagents is intensifying because academic subscription portals displace traditional distributor markups. Biotechnology companies with IND-ready requirements show least price sensitivity; academic institutions accessing cloud-based design algorithms exhibit highest elasticity.
Supply Chain Analysis
Inbound logistics costs from Shanghai and Shenzhen ports to North American biotech hubs fluctuate with container availability on trans-Pacific trade lanes, extending lead times for stabilized peptide shipments. Manufacturing concentrates in China, the United States, and Germany. Production rests on fermentation-derived peptide precursors, FokI nuclease domains, and plasmid backbones. Single-source vulnerability pervades proprietary ZFN archives held by Sangamo Therapeutics and limited second-source licensors. Distribution runs through direct digital platforms for academic accounts and field sales teams for pharmaceutical sponsors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of computational biologists skilled in protein-DNA interaction modeling constrains platform expansion, rewarding early movers who secure hybrid bioinformatics talent before CRISPR patent clarity shifts competitive dynamics.
For Market Incumbents: Shield proprietary ZFN archives through exclusive licensing terms that block second-source availability for therapeutic sponsors facing FDA IND timelines. Deepen backward integration into peptide reagent fermentation capacity to offset Chinese contract manufacturing spot price volatility. Patent thickets around CRISPR alternatives create temporary freedom-to-operate windows that archive-holders must exploit before base editing systems mature. For New Entrants and Emerging Players: Cloud-based design portal functionality gaps in Indian and Chinese academic markets offer first-mover positioning where incumbent distributors maintain legacy procurement relationships. Target CDSCO-registered sponsors in Hyderabad and Bengaluru with regulatory consulting bundled into ZFN design services. Pursue direct-to-academic distribution through subscription-based algorithm access with instant quoting capabilities. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among synthetic biology service integrators with captive manufacturing and custom design capabilities, suggesting durable cash flow quality in platform-plus-service archetypes. Long-term viability hinges on freedom-to-operate clarity in CRISPR alternatives and agricultural biotechnology penetration beyond mammalian cell therapy. Watch for EMA ATMP framework revisions mandating extended pharmacovigilance as signal of documentation burden escalation that favors established specificity datasets.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA breakthrough designations accelerate IND review timelines for ZFN sponsors with established safety data. |
| Manufacturing Scale-Up | GMP material qualification for therapeutic-grade reagents extends development cycles through ISO 10993 compliance. |
| Platform Integration | Automated cell processing equipment convergence enables closed-system workflows for allogeneic cell therapy. |
| Geographic Expansion | CDSCO's emerging ATMP framework positions prior FDA-engaged sponsors for first-mover advantage in India. |
| Strategic Partnership | Licensing agreements with agricultural biotechnology firms exploit ZFN specificity advantages under USDA-APHIS frameworks. |
Research Methodology
A spread of perspectives from gene therapy development executives, regulatory affairs leads at FDA-engaged sponsors, academic principal investigators, and GMP manufacturing directors converged on the working assumptions for platform adoption trajectories. Primary interview insights triangulated against FDA guidance documents, EMA ATMP framework revisions, ClinicalTrials.gov filings, and patent prosecution records. Secondary validation drew from SEC 10-K disclosures of publicly traded platform holders and customs data on peptide reagent imports. Bottom-up segment sizing and top-down market reconstruction cross-checked for consistency across the analysis window.
Segmentation dimensions modeled encompass engineered nuclease architecture, therapeutic versus agricultural application, end-user procurement authority, and delivery mode payload engineering. CAGRs derived from installed base growth rates, replacement cycle analysis, and new sponsor entry patterns. Forecast inputs incorporated viral vector manufacturing bottleneck persistence, lipid nanoparticle formulation advances, and CRISPR patent litigation timeline uncertainty throughout the projection horizon.
Underlying assumptions cover sustained FDA gene therapy guidance enforcement, stable Chinese fermentation capacity utilization, and EMA pharmacovigilance mandate continuity, with deviation risk concentrated in CRISPR patent invalidation outcomes and base editing system maturation. Practitioners should keep alternative scenarios live as regulatory jurisdiction alignment requirements and substitute technology performance profiles evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gene Editing & CRISPR
Genome Engineering Market
Gene Editing & CRISPR
Cloning and Mutagenesis Market
Gene Editing & CRISPR
Genetic Engineering Market
Gene Editing & CRISPR
Italy Gene Editing Market
Gene Editing & CRISPR
Genetically Modified Animal Model Market
Gene Editing & CRISPR
Mutation Detection Kits in Genome Editing Market
Gene Editing & CRISPR
Germany Gene Editing Market
Gene Editing & CRISPR
Global Recombinant DNA (Rdna) Technology Market
Gene Editing & CRISPR
Global CRISPR and Cas Genes Market
Gene Editing & CRISPR
France Gene Editing Market
Gene Editing & CRISPR
Immunodeficient Mouse Models Market
Gene Editing & CRISPR
South Korea Gene Editing Market
Gene Editing & CRISPR
China Gene Editing Market
Gene Editing & CRISPR
Global CRISPR and CRISPR-Associated (Cas) Genes Market
Gene Editing & CRISPR
Recombinant DNA Market
Gene Editing & CRISPR
Knockout Mice Model Market