
 Tenant Billing Software Market | 2026-2036
Tenant Billing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Tenant Billing Software Market Intelligence
North American software development capacity is hardening around property technology infrastructure. AppFolio leverages cloud-native architecture to sustain pricing power across mid-market property managers. Buildium anchors its position through deep accounting integration. TenantCloud competes aggressively on freemium user acquisition.
Tenant billing software automates utility allocation, rent invoicing, and lease charge computation through meter data integration and proration algorithms. The primary commercial purpose is to eliminate manual spreadsheet-based billing while ensuring regulatory compliance with local utility disclosure laws. Cloud-based deployment leads solution type adoption due to lower IT overhead for distributed property portfolios. Utility billing modules capture the fastest-growing margin pools as submetering hardware proliferates in Class A multifamily assets. Property managers represent the most concentrated customer type, though condominium boards expand fastest as self-managed associations digitize.
FCC guidelines on electronic billing communications intersect with state-level utility commission disclosure mandates to shape product requirements across US jurisdictions. GDPR and state privacy laws force data residency controls into platform architecture. Stakeholders must monitor evolving submetering regulations and payment rail interoperability standards to preserve competitive positioning.
Market Dynamics
Utility submetering hardware proliferation is compressing billing cycle times and forcing software platforms to absorb real-time meter data streams at scale, fundamentally reshaping vendor technical requirements.
Growth Catalysts
- State utility commission mandates:California and Texas now require granular utility disclosure to tenants, compelling property managers to automate allocation calculations rather than rely on manual estimation methods.
- Cloud infrastructure maturation:Distributed property portfolios increasingly demand zero on-premise maintenance, pushing mid-market firms toward SaaS billing platforms that consolidate multi-site operations.
- Class A multifamily asset densification:Institutional investors concentrating ownership in metropolitan corridors create concentrated demand for standardized billing across hundreds of units under single management.
Market Restraints
- Submetering hardware supply concentration:Metering device manufacturing clusters in East Asian industrial zones expose software vendors to component availability volatility and extended procurement timelines.
- State-by-state regulatory fragmentation:FCC electronic billing guidelines intersect inconsistently with local utility commission disclosure rules, forcing costly jurisdiction-specific compliance engineering.
- Legacy property management system entrenchment:Deep accounting integration in incumbent platforms creates switching friction that slows new vendor penetration in established portfolios.
Strategic Opportunities
- Self-managed condominium digitization:Condominium boards without professional property management represent an underpenetrated segment where simplified billing interfaces capture first-mover advantage.
- Payment rail interoperability expansion:Open banking APIs and real-time payment networks enable embedded rent-plus-utility collection, reducing friction for both managers and tenants.
- GDPR-aligned data residency architectures:Privacy-compliant platform designs built for European requirements transfer competitively to US state-level privacy law environments.
Industry Challenges
- Certified utility rate engine maintenance:Engineering teams must continuously validate proration algorithms against evolving municipal rate structures across thousands of jurisdictions.
- Legacy ERP integration complexity:Custom API development for entrenched accounting systems consumes disproportionate implementation resources and extends sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tenant Billing Software Market |
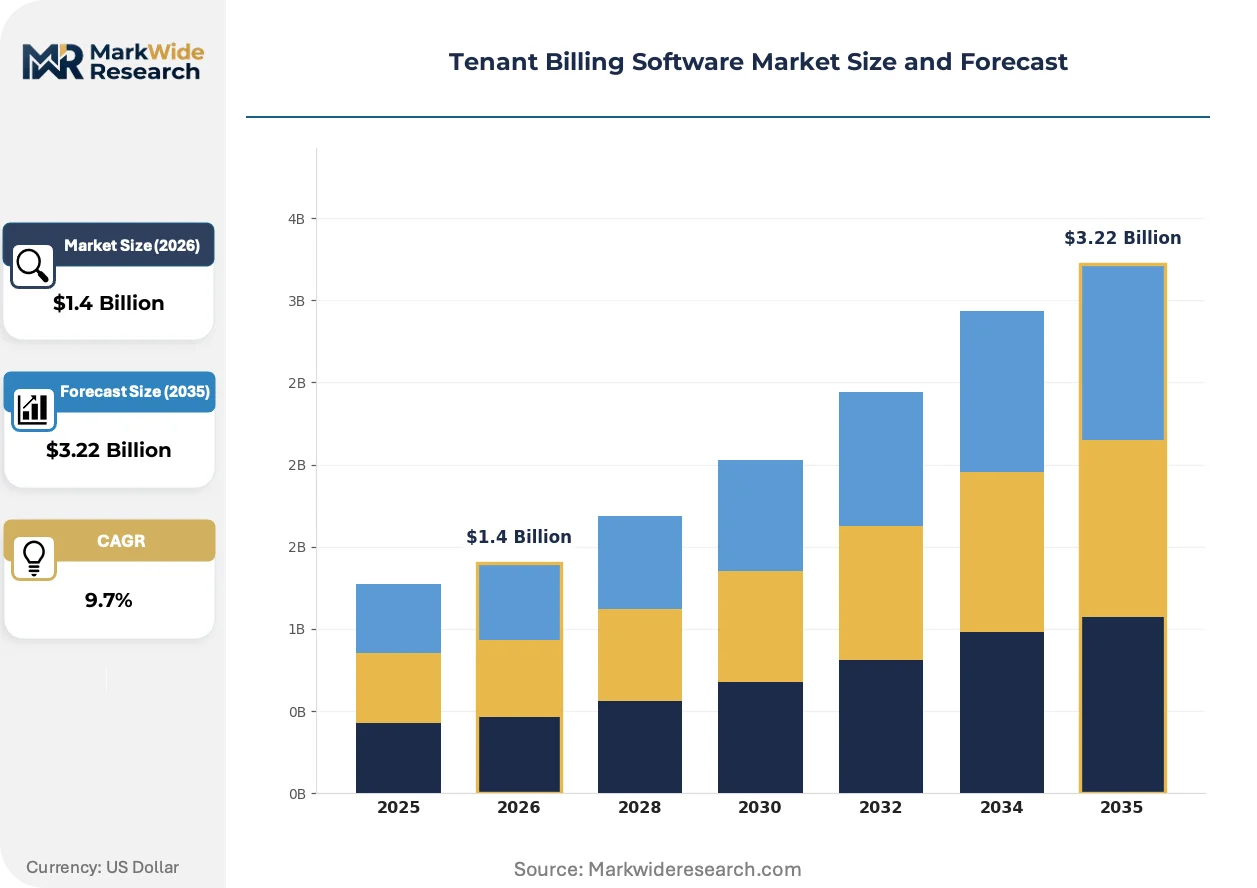
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $3.22 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Hosted Solution Type: Utility Billing, Rent Collection, Maintenance Charges, Lease Management, Payment Processing Customer Type: Property Managers, Real Estate Firms, Facility Managers, Condominium Boards, Cooperative Housing Integration Features: Accounting Software, CRM Systems, Payment Gateways, Reporting Tools, Notification Systems |
| Companies Covered | Avail, TenantCloud, Buildium, Propertyware, Nutiliti, AppFolio, Baselane, Rentec Direct, TurboTenant, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tenant Billing Software Market Strategic Shifts & Innovations
Real-time data infrastructure is displacing batch-processed billing architectures, enabling continuous rather than monthly tenant charge calculations. This shift demands fundamental platform redesigns.
Blockchain-based utility certificate tracking is decentralizing tenant-facing energy origin verification. Class A multifamily developers in coastal metropolitan markets adopt these tools to differentiate lease offerings. The technology is decentralizing what had been centralized utility disclosure, compressing the role of traditional billing intermediaries.
The FCC's electronic billing communication guidelines are tightening consent and accessibility requirements for digital rent statements. Property management software vendors must now engineer multi-channel delivery systems that satisfy both federal standards and state utility commission disclosure mandates. Mid-market platforms face the steepest compliance adaptation costs.
Subscription-based procurement of billing capabilities is displacing perpetual license purchases among smaller property management firms. Channel partners and industry associations increasingly bundle software access with hardware installation services. This pattern concentrates in Sun Belt metropolitan markets where new construction outpaces legacy system entrenchment.
Tenant Billing Software Market Segmentation
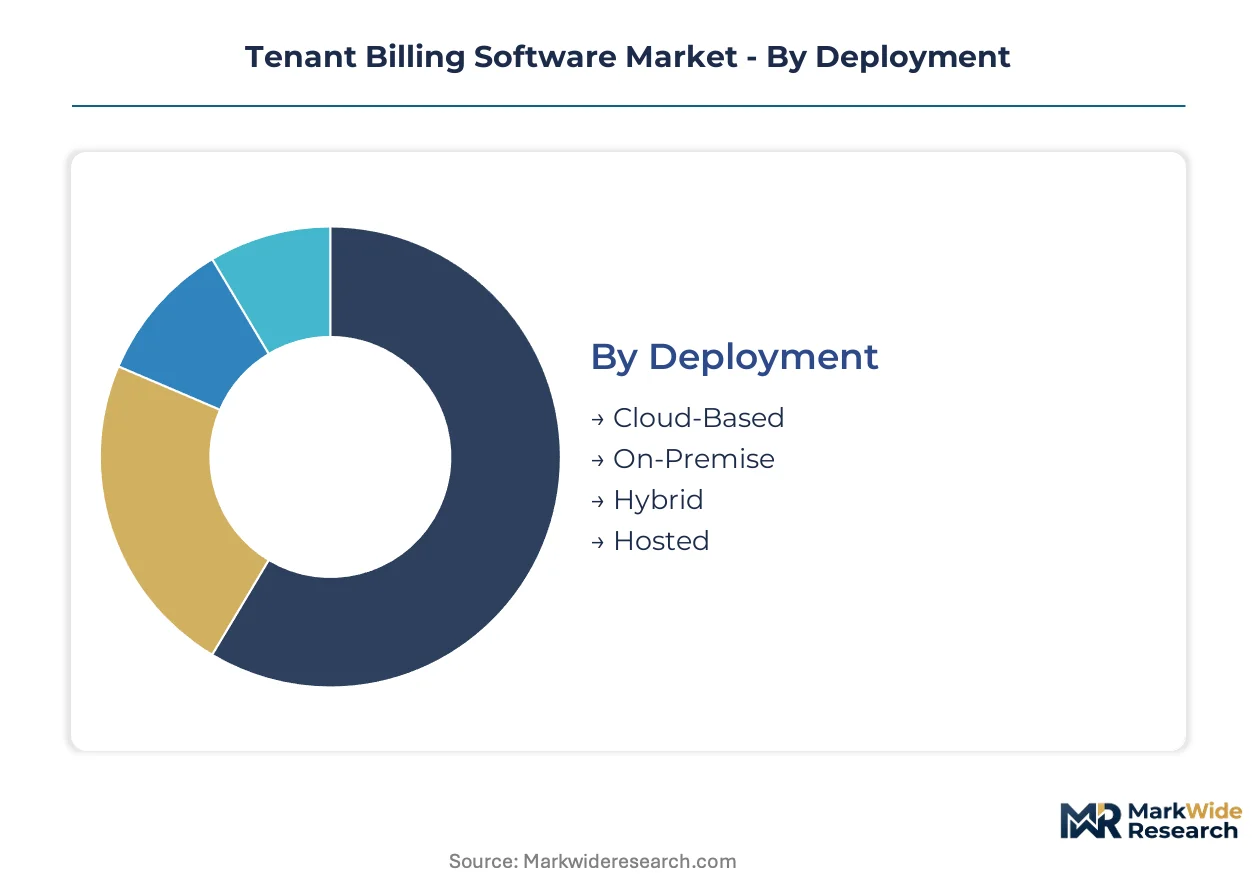
Tenant billing software vendors engineer certification pathways around deployment architecture and jurisdictional data residency mandates. Segmentation strategy determines which compliance burdens each product tier absorbs.
Deployment:
FCC electronic billing guidelines and GDPR data residency rules impose divergent architectural requirements across cloud, on-premise, and hybrid configurations.
- Cloud-Based:Multi-tenant SaaS architectures process meter data through regional cloud zones to satisfy state-level privacy laws. Property managers with distributed portfolios across California and Texas concentrate demand here as utility commission disclosure mandates tighten.
- On-Premise:Local server installations retain full data custody within facility boundaries. Financial institutions and government-leased properties specify this model to satisfy internal audit requirements and HIPAA-aligned data controls.
- Hybrid:Edge computing nodes handle real-time meter ingestion while cloud layers manage tenant-facing portals. This configuration spreads fastest among Class A multifamily developers seeking submetering responsiveness without surrendering operational data.
- Hosted:Single-tenant dedicated instances in vendor-managed data centers. Mid-market property managers without internal IT staff select this path to balance customization access against infrastructure responsibility.
Leading the category by volume: Cloud-Based. Expanding most quickly: Hybrid.
Solution Type:
Margin concentration follows regulatory complexity rather than transaction volume alone.
- Utility Billing:Proration engines calculate tenant-specific charges from submetered consumption data against municipal rate structures. California and Texas state utility commissions now mandate granular disclosure, accelerating automation demand in these jurisdictions.
- Rent Collection:Scheduled payment processing with late fee automation and lease-ledger reconciliation. This module anchors platform stickiness across mid-market property management firms.
- Maintenance Charges:Common area cost allocation across tenant pro-rata shares. Condominium boards digitizing self-managed operations represent the fastest-expanding customer pool for this capability.
- Lease Management:Charge schedule configuration tied to lease commencement and renewal dates. Integration depth with accounting systems determines competitive positioning.
- Payment Processing:Embedded rent-plus-utility collection through ACH, card networks, and emerging real-time payment rails. Open banking API adoption is reshaping vendor technical roadmaps.
Highest margin capture: Utility Billing. Steepest expansion trajectory: Payment Processing.
Customer Type:
Procurement authority and technical sophistication diverge sharply across buyer categories.
- Property Managers:Professional management firms operating multifamily assets at scale. Revenue concentration sits here due to portfolio-standardization requirements and recurring subscription volumes.
- Real Estate Firms:Owner-operators with mixed commercial-residential holdings. These buyers prioritize lease management integration across asset classes.
- Facility Managers:Corporate and institutional campus operators. Utility billing modules matter most for cost recovery in triple-net lease environments.
- Condominium Boards:Self-managed residential associations without professional management. Simplified interfaces and minimal training requirements unlock this underpenetrated segment.
- Cooperative Housing:Member-owned residential corporations with unique governance structures. Specialized allocation methodologies distinguish this niche.
Dominating procurement volume: Property Managers. Gaining share fastest: Condominium Boards.
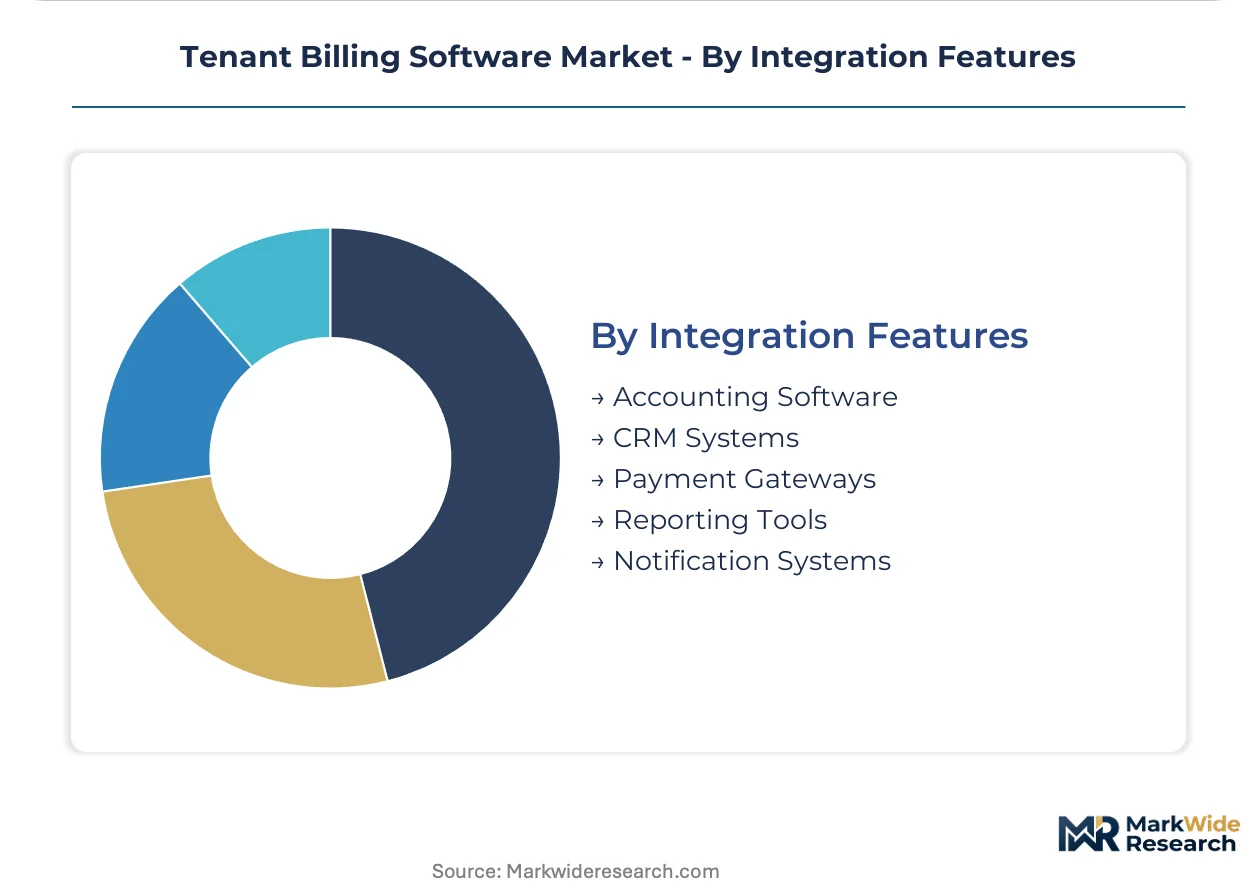
Integration Features:
API development burden and implementation timeline variance map directly to integration category.
- Accounting Software:General ledger synchronization with entrenched ERP systems. Custom integration development consumes disproportionate vendor engineering resources.
- CRM Systems:Tenant communication history and lease prospect tracking. Real estate firms with sales-led operations specify this capability.
- Payment Gateways:Processor-agnostic transaction routing with failover logic. PCI-DSS compliance scope expands with this integration depth.
- Reporting Tools:Business intelligence exports for institutional investor reporting. Class A multifamily assets with institutional ownership require standardized performance dashboards.
- Notification Systems:Multi-channel tenant alerts spanning email, SMS, and portal messaging. FCC electronic billing guidelines mandate accessibility-compliant delivery methods.
Widest deployment: Accounting Software. Climbing fastest: Notification Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure investments concentrate in metropolitan corridors where multifamily housing density supports platform economics. The United States anchors deployment volume as utility submetering regulations tighten across multiple states. Property technology clusters in Texas and California drive technical requirements for real-time meter data integration.
United States
California and Texas state utility commissions now mandate granular utility disclosure to tenants, compelling automation of allocation calculations. FCC electronic billing guidelines intersect with these state rules to shape multi-channel delivery requirements. Los Angeles and Dallas metropolitan corridors concentrate Class A multifamily development where institutional investors standardize billing across hundreds of units.
United Kingdom
GDPR data residency controls force regional cloud zone deployment for tenant data processing. The country's national property regulator aligns with EU Green Deal disclosure standards for energy efficiency reporting. London and Manchester multifamily developers adopt hybrid architectures to satisfy real-time submetering demands without surrendering operational data custody.
Germany
REACH compliance requirements influence chemical disclosure in utility billing for industrial-tenant properties. The federal network agency enforces strict metering accuracy standards that software platforms must integrate. Berlin and Munich property managers drive demand for certified utility rate engines that validate proration algorithms against municipal rate structures.
Japan
METI smart city initiatives accelerate submetering hardware deployment in Tokyo and Osaka metropolitan housing complexes. JIS standards govern meter data interoperability, forcing platform vendors to engineer specific ingestion protocols. Yokohama and Nagoya multifamily developers prioritize edge computing nodes for real-time consumption monitoring.
Australia
The national energy regulator mandates transparent utility cost allocation in strata-titled properties, digitizing self-managed condominium operations. TGA-aligned privacy frameworks shape tenant data handling requirements for billing platforms. Sydney and Melbourne property technology clusters concentrate cloud-native vendor development for Asia-Pacific market expansion.
Tenant Billing Software Market Key Industry Players
Global majors compete with regional champions across deployment architecture specialization and jurisdictional compliance depth. The vendor base stratifies between cloud-native SaaS platforms, legacy-integrated suite providers, and freemium user-acquisition specialists. Three archetypes dominate: vertically integrated property management suites, standalone utility billing specialists, and payment-rail-embedded fintech hybrids. Competitive moves concentrate on strategic partnerships with submetering hardware manufacturers and API-first accounting integrations that reduce switching friction.
Within the cloud-native tier, AppFolio and Buildium exemplify divergent positioning strategies. AppFolio occupies a position as the vertically integrated suite anchor for mid-market property managers, while Buildium represents the deep accounting integration archetype that slows competitive displacement in established portfolios. TenantCloud sits within the freemium acquisition specialist category, using simplified interfaces to penetrate underpenetrated self-managed segments before expanding feature depth.
| Leading Market Players |
|---|
| Avail |
| TenantCloud |
| Buildium |
| Propertyware |
| Nutiliti |
| AppFolio |
| Baselane |
| Rentec Direct |
| TurboTenant |
| Others |
Cost & Logistics Intelligence
Mid-market property managers' procurement consolidation around bundled SaaS tiers is compressing standalone billing module margins and forcing vendors to absorb submetering hardware costs into subscription pricing.
Pricing Analysis
Warranty and service bundling separates premium-tier deployments with certified utility rate engine maintenance from economy tiers that exclude algorithm validation. Pricing stratifies across premium, standard, and economy tiers based on integration depth with accounting systems and jurisdictional compliance coverage. Cost compression in the standard tier is intensifying because cloud infrastructure providers are passing through data residency engineering expenses. Self-managed condominium boards exhibit the highest price sensitivity, while institutional property managers with Class A multifamily portfolios demonstrate the least.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from institutional property managers, while value-added resellers serve fragmented mid-market accounts. Submetering hardware manufacturing concentrates in China, South Korea, and Taiwan. Software platform engineering draws from cloud compute services, API development labor pools, and certified utility rate databases. Single-source vulnerability in East Asian metering component supply creates procurement timeline risk. Distribution runs through property technology channel partners bundling hardware installation with SaaS access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
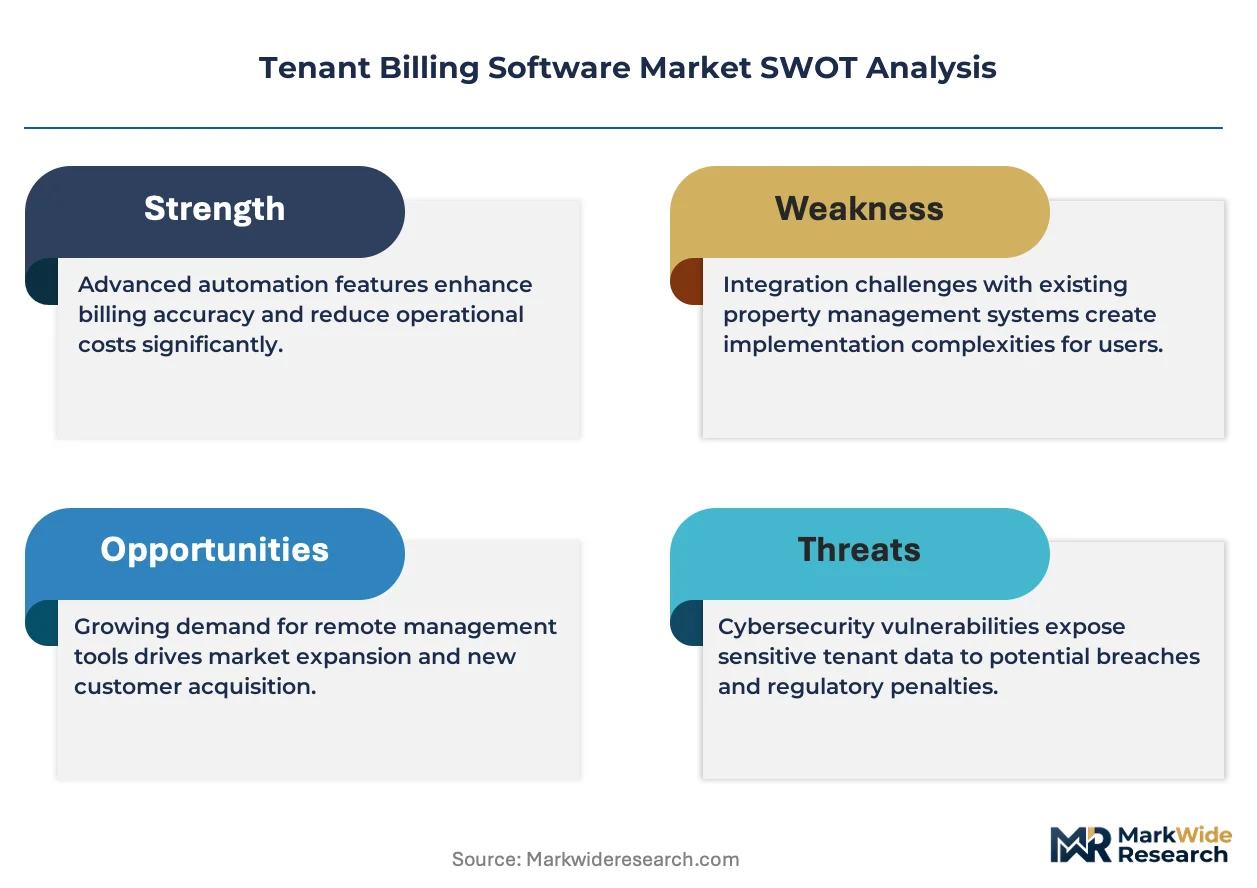
This market is consolidating as state-by-state regulatory fragmentation raises compliance engineering costs beyond smaller vendors' reach.
For Market Incumbents: Hedge against margin erosion by deepening API-first accounting integrations that increase switching friction in established portfolios. Acquire certified utility rate engine capabilities to defend against standalone billing specialists. Cloud infrastructure maturation threatens on-premise revenue streams. For New Entrants and Emerging Players: Begin with self-managed condominium boards in Sun Belt metropolitan markets where simplified interfaces unlock first-mover advantage before feature expansion. Payment rail interoperability expansion offers the most penetrable white-space target. Partner with submetering hardware installers for bundled go-to-market access. For Investors and Strategic Acquirers: The window for entry favors cloud-native platforms with GDPR-aligned data residency architectures transferable to US state privacy law environments. Long-term viability hinges on real-time meter data ingestion scale. Watch FCC electronic billing guideline enforcement intensity as inflection indicator for compliance-engineering cost spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep accounting API connections reduce customer switching friction in established portfolios. |
| Strategic Partnership | Submetering hardware manufacturer alliances bundle software access with installation services. |
| Acquisition of Specialist Firm | Certified utility rate engine capabilities compress development timelines for jurisdictional compliance. |
| Product Launch | Hybrid deployment architectures capture Class A multifamily demand for real-time responsiveness. |
| Geographic Expansion | GDPR-aligned data residency designs transfer competitively to California and Texas privacy mandates. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with property management executives, software platform engineers, submetering hardware procurement leads, and utility commission policy staff. FCC electronic billing guidelines, state utility commission disclosure mandates, and GDPR data residency frameworks provided regulatory boundary conditions. Bottom-up tenant billing software deployment estimates triangulated against top-down property technology spending forecasts.
Deployment architecture, customer type, and solution type were modeled at the segment level across the analysis window. Integration feature complexity and regional regulatory clusters provided additional granularity. CAGRs were derived from utility submetering hardware proliferation rates and SaaS subscription renewal patterns. Certified utility rate engine maintenance burdens and payment rail API adoption curves shaped growth trajectory assumptions.
Underlying measurement precision varies by segment; cloud-based deployment estimates carry tighter precision than hybrid configurations due to vendor disclosure consistency. Forecasts reflect assumptions about state utility commission mandate expansion pace and submetering hardware supply chain stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Software Licensing Market
Software & Services
Global Data Discovery Software Market
Software & Services
Audio Editing Software Market
Software & Services
Global Decision Making Software Market
Software & Services
SRM Software Market
Software & Services
Software Market
Software & Services
Global 360 Degree Feedback Software Market
Software & Services
Office Software Market
Software & Services
Global Qualitative Data Analysis Software Market
Software & Services
Middle East and Africa Digital Signage Software Market
Software & Services
Java Integrated Development Environment (IDE) Market
Software & Services
Air Cargo Software Market
Software & Services
Sales Performance Management (SPM) Software Market
Software & Services
Service Scheduling Software Market
Software & Services
B2B Gateway Software Market
Software & Services
Middle East and Africa Workforce Management Software Market