
 Newsroom Software Market | 2026-2036
Newsroom Software Market Size, Share, and Industry Trends Forecast 2026-2036
Newsroom Software Market Foresight
Market Context
Cloud-native architecture is tilting newsroom software away from monolithic on-premises suites toward modular, API-first platforms that integrate with social media and analytics stacks. Cision sustains its position through deep channel control across media monitoring and influencer databases. Prezly differentiates by specializing in boutique PR workflows with embedded newsroom publishing. Mynewsdesk anchors Nordic market presence through localized language support and regional media partnerships.
Technical Definition and Segment Structure
Newsroom software encompasses editorial systems that manage content creation, collaboration, distribution, and performance measurement across broadcast, digital, and print media operations, typically incorporating real-time workflow engines, multimedia asset management, and audience analytics dashboards. The primary commercial purpose is to compress editorial cycle times while maintaining compliance and multi-channel output consistency. Content Management and Automation Software command the largest installed bases, though Cloud-Based and SaaS deployment models are capturing the fastest expansion as publishers shed capital-intensive infrastructure. Workflow Management features embedded with Analytics represent the deepest margin pools, since data-driven editorial decision-making commands premium pricing from enterprise media buyers.
Regulatory Framework
The EU AI Act and GDPR shape product development trajectories, requiring algorithmic transparency in automated content curation and strict consent management for audience data processing. The FCC in the United States maintains ownership and content standards that influence broadcast media procurement specifications, while India's TRAI frameworks for digital media convergence create compliance thresholds for platform operators. Stakeholders must monitor how divergent AI disclosure mandates across Brussels, Washington, and New Delhi fragment product roadmaps and certification requirements.
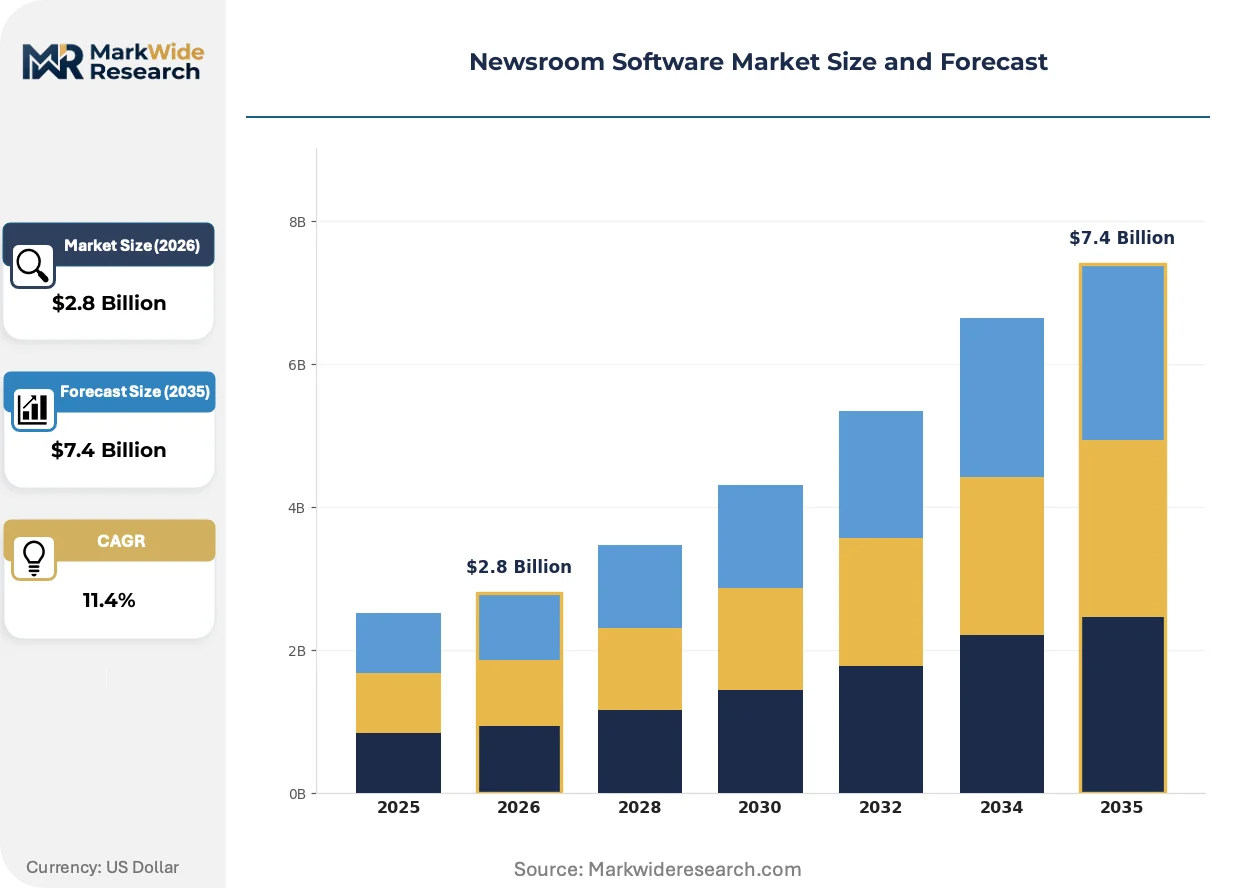
Market Dynamics
Cloud-native architecture is collapsing the traditional on-premises newsroom software stack as publishers shed capital-intensive infrastructure for modular, API-first platforms that integrate with social media and analytics ecosystems.
Growth Catalysts
- EU AI Act compliance mandates:Automated content governance tools are capturing investment as European publishers retrofit editorial workflows for algorithmic transparency requirements.
- Real-time multimedia asset management:Broadcast and digital news operations are compressing editorial cycle times through unified platforms that handle video, audio, and text in single pipelines.
- India TRAI digital convergence frameworks:Platform operators are modernizing infrastructure to meet compliance thresholds, accelerating procurement of cloud-based editorial systems.
Market Restraints
- GDPR consent management complexity:Strict audience data processing rules are fragmenting product roadmaps and extending certification timelines for vendors serving European publishers.
- Legacy system integration friction:Monolithic on-premises suites from the 2010s create technical debt that slows migration to SaaS deployment models.
- Specialized editorial talent scarcity:Newsrooms face hiring gaps for professionals who bridge traditional journalism with AI-assisted workflow engineering.
Strategic Opportunities
- Underpenetrated Nordic markets:Localized language support and regional media partnerships remain underserved by global vendors, creating entry points for specialized platforms.
- AI-assisted curation convergence:Machine learning and natural language processing are merging to enable predictive editorial planning that anticipates audience interest spikes.
- Subscription-driven procurement models:Publishers are unbundling capital expenditure into recurring operational budgets, opening SaaS channels previously blocked by procurement rules.
Industry Challenges
- Cross-border regulatory fragmentation:Divergent AI disclosure mandates across Brussels, Washington, and New Delhi are forcing vendors to maintain parallel product roadmaps and certification tracks.
- Workflow standardization delays:Lack of industry-wide interoperability protocols complicates integration between best-of-breed tools from different vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Newsroom Software Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Content Management, Collaboration Tools, Automation Software, Workflow Management End User: Broadcast Media, Digital News Platforms, Print Media, Online Publishers Deployment: On-Premises, Cloud-Based, Hybrid, SaaS Feature: Social Media Integration, Analytics, Multimedia Support, Multi-Channel Distribution |
| Companies Covered | Onclusive, PR.co, Prezly, Cision, ePressPack, Prowly, Mynewsdesk, Notified, Presspage, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Newsroom Software Market Shifts & Advancements
Generative AI and edge computing are actively reshaping how newsrooms produce and distribute content, compressing the gap between story conception and multi-platform publication.
Natural language generation is collapsing the boundary between raw data and publishable narrative as automated systems convert structured feeds into draft articles. Metro dailies and financial news services are adopting these tools fastest, using them to expand coverage volume without proportional headcount expansion. The structural consequence is collapsing traditional copy-editing hierarchies as machines handle first-pass production.
GDPR and the EU AI Act are mandating algorithmic transparency in automated content curation across European publishing operations. Vendors must now embed audit trails and explainability modules into editorial workflow software. Enterprise media buyers in Germany and France are prioritizing compliance-certified platforms, creating pricing premiums for vendors who invested early in governance architecture.
Newsroom procurement is fragmenting from suite-based purchases toward modular, best-of-breed tool selection. Publishers are unbundling content management from distribution analytics and audience measurement, selecting point solutions through pilot programs rather than enterprise commitments. This pattern is most visible in United States digital-native outlets and German regional publisher cooperatives, where technical teams favor API interoperability over single-vendor dependency.
Newsroom Software Market Segmentation
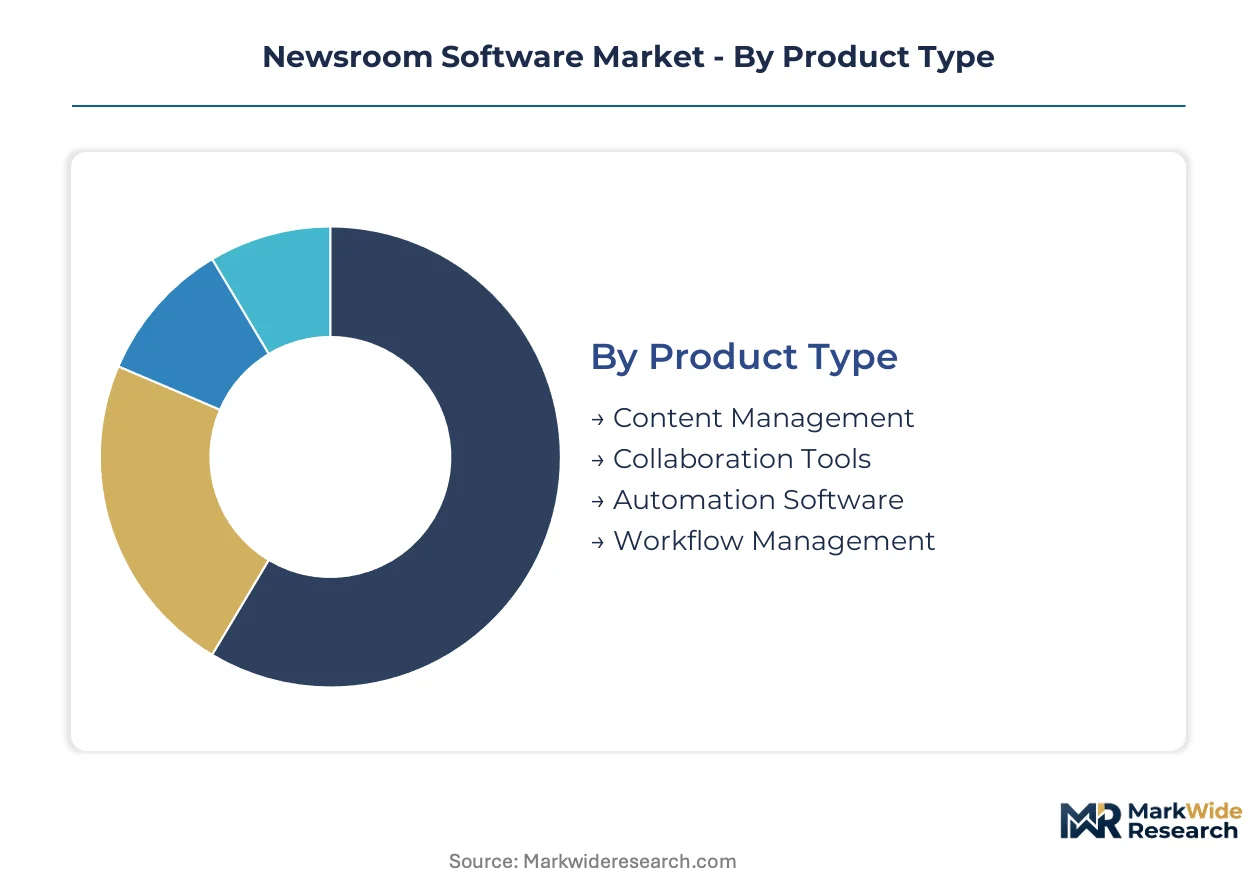
Newsroom software segmentation reveals how procurement cycles vary dramatically by infrastructure commitment. Publishers with quarterly budget cycles favor modular deployment models, while capital-intensive broadcast operations lock in five-year refresh timelines.
Product Type:
Content Management and Automation Software turn over every 18-24 months as publishers chase AI-assisted features, while Workflow Management suites endure 5-7 year cycles due to integration complexity.
- Content Management:Core editorial repositories handling text, image, and video assets with version control and archival retrieval. Digital news platforms in Germany and India are prioritizing these systems as they consolidate fragmented content silos ahead of EU AI Act transparency mandates.
- Automation Software:Machine learning pipelines that generate draft copy, tag content, and optimize headline performance against audience data. Financial news services and metro dailies in the United States are deploying these tools fastest to expand story volume without proportional headcount growth.
- Collaboration Tools:Real-time editing, annotation, and approval workflows connecting distributed editorial teams.
- Workflow Management:End-to-end process orchestration spanning assignment, production, compliance review, and multi-channel publication.
Content Management anchors the volume base while Automation Software gains share at the steepest rate.
End User:
Budget tiers separate broadcast incumbents with seven-figure capital allocations from digital-native outlets operating on annual SaaS contracts under six figures.
- Broadcast Media:Television and radio operations requiring frame-accurate video editing, live production switching, and FCC-compliant closed captioning workflows. These buyers in the United States maintain the longest procurement cycles due to capital budgeting constraints and regulatory certification requirements.
- Digital News Platforms:Online-first publishers prioritizing real-time analytics, social media integration, and mobile-optimized output pipelines. Outlets in India are modernizing fastest under TRAI digital convergence frameworks that mandate infrastructure upgrades.
- Print Media:Newspaper and magazine operations bridging legacy pagination systems with digital distribution requirements.
- Online Publishers:Pure-play digital content businesses including newsletters, podcasts, and vertical news sites.
Broadcast Media commands the deepest per-seat pricing while Digital News Platforms are expanding most quickly.
Deployment:
Technical debt burdens separate cloud-native entrants from organizations shackled to decade-old on-premises infrastructure requiring forklift replacement.
- Cloud-Based:Fully managed infrastructure with elastic compute scaling and zero local hardware footprint. Publishers in Germany are migrating fastest as GDPR compliance complexities favor vendors with certified European data residency.
- SaaS:Subscription software delivered through browsers and mobile applications with automatic feature updates. Regional publisher cooperatives in the United States favor this model to convert capital expenditure into operational budgets.
- On-Premises:Self-hosted systems requiring dedicated server infrastructure and internal IT maintenance.
- Hybrid:Mixed architectures preserving sensitive editorial workflows on local servers while pushing distribution through cloud endpoints.
On-Premises retains the largest installed base while Cloud-Based deployment climbs the fastest.
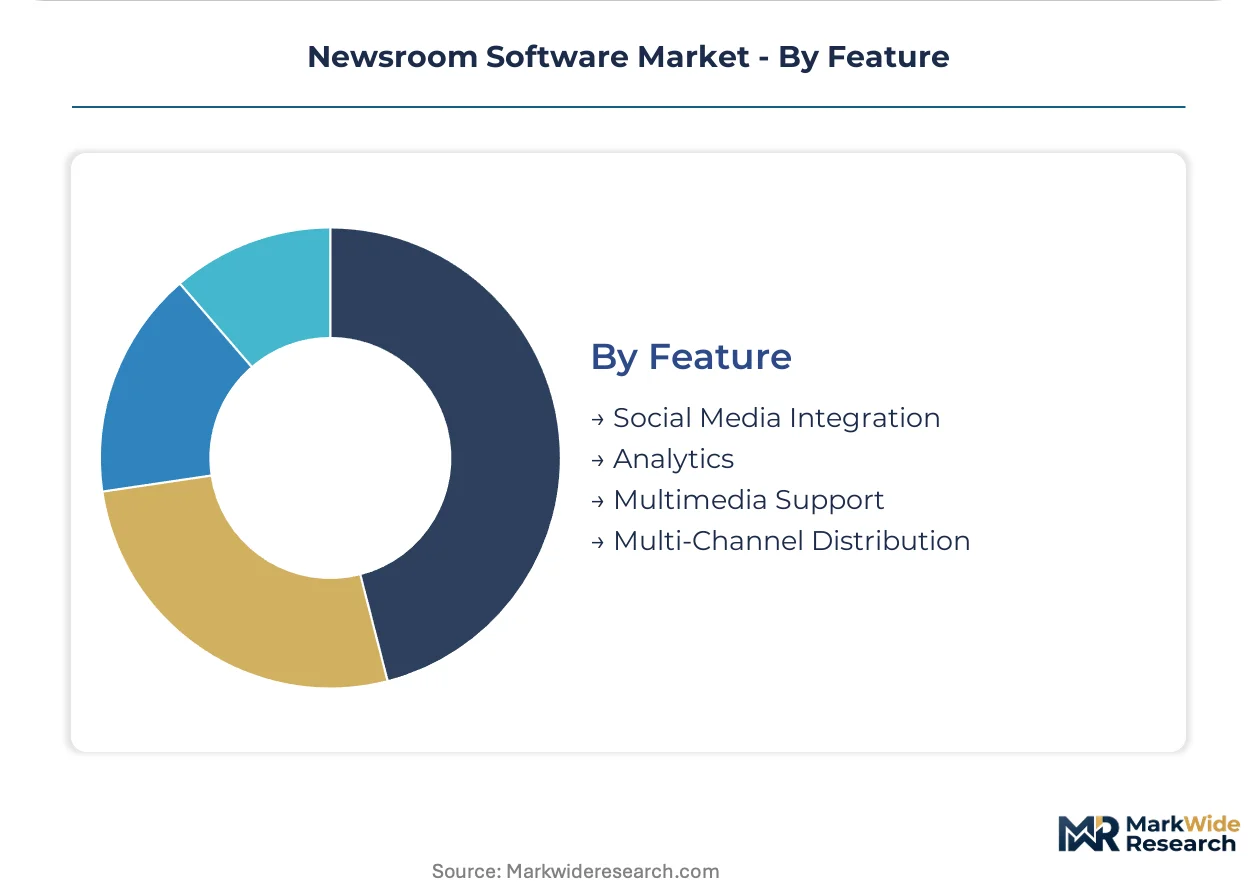
Feature:
Integration depth separates commodity modules from premium capabilities commanding pricing multiples based on data pipeline sophistication.
- Analytics:Audience behavior measurement, content performance scoring, and predictive trend identification. Enterprise media buyers in France and Germany are prioritizing compliance-certified platforms with embedded audit trails for EU AI Act algorithmic transparency requirements.
- Multi-Channel Distribution:Simultaneous publication orchestration across web, mobile, social, and syndication endpoints. Digital-native outlets in the United States are unbundling this capability from core content management to select best-of-breed point solutions.
- Social Media Integration:Direct publishing APIs, engagement monitoring, and influencer identification tools.
- Multimedia Support:Unified handling of video, audio, image, and interactive content within single editorial pipelines.
Analytics anchors enterprise pricing premiums while Multi-Channel Distribution shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Newsroom software procurement flows from United States and German vendors into Indian and Nordic media operations, with regulatory divergence fragmenting product certification requirements across these corridors.
United States
Digital-native outlets and broadcast networks drive demand for cloud-based editorial systems with real-time analytics integration. FCC ownership and content standards shape broadcast media procurement specifications, mandating closed captioning compliance and signal quality thresholds. New York and Los Angeles media clusters concentrate purchasing power, with metro dailies deploying automation tools to expand coverage volume without proportional headcount growth.
Germany
Enterprise media buyers prioritize compliance-certified platforms as EU AI Act algorithmic transparency mandates reshape editorial workflows. GDPR consent management complexities favor vendors with certified European data residency, accelerating migration from on-premises infrastructure. Berlin and Munich publisher cooperatives unbundle suite-based purchases, selecting modular point solutions through pilot programs rather than enterprise commitments.
India
Platform operators modernize infrastructure under TRAI digital convergence frameworks that mandate compliance thresholds for digital media operations. Cloud-based deployment models capture fastest expansion as publishers shed capital-intensive legacy systems. Bangalore and Mumbai media clusters anchor procurement activity, with online-first publishers prioritizing social media integration and mobile-optimized output pipelines.
United Kingdom
Newsroom procurement fragments toward best-of-breed tool selection as technical teams favor API interoperability over single-vendor dependency. Post-Brexit regulatory alignment questions complicate EU AI Act compliance strategies for publishers with cross-border operations. London digital media startups and regional newspaper groups drive SaaS adoption, converting capital expenditure into recurring operational budgets.
Sweden
Nordic markets remain underserved by global vendors, creating entry points for platforms with localized language support and regional media partnerships. GDPR implementation across Scandinavian publishing operations requires strict audience data processing controls. Stockholm anchors regional demand, with Mynewsdesk maintaining market presence through tailored workflow solutions for Nordic PR and communications teams.
Newsroom Software Market Competitive Landscape
On the supply side, the industry is moderately consolidated around specialized PR workflow platforms and broad media monitoring suites, with tiered competition separating global scale players from regional specialists and boutique SaaS providers. Three strategic archetypes dominate: channel-control platforms with deep media databases, boutique publishing specialists with embedded newsroom capabilities, and Nordic-focused regional players with localized partnerships. Competitive moves concentrate on API-first platform expansion and compliance-certified product roadmaps for European regulatory requirements.
Within the channel-control archetype, Cision anchors enterprise positioning through media monitoring and influencer database breadth. Prezly occupies the boutique specialist tier, representing PR workflow platforms with integrated newsroom publishing capabilities. Mynewsdesk exemplifies regional specialization, anchoring Nordic market presence through localized execution.
| Leading Market Players |
|---|
| Onclusive |
| PR.co |
| Prezly |
| Cision |
| ePressPack |
| Prowly |
| Mynewsdesk |
| Notified |
| Presspage |
| Others |
Supply & Pricing Matrix
Transatlantic data center connectivity corridors linking Frankfurt, London, and Virginia anchor cost dynamics for cloud-native newsroom software delivery, concentrating supply-side leverage among hyperscale infrastructure providers while forcing tiered pricing differentiation between enterprise broadcast buyers and digital-native SaaS subscribers.
Pricing Analysis
Legacy on-premises licensing, current-generation SaaS tiers, and emerging AI-augmented workflow suites stratify across premium, standard, and economy levels. Enterprise broadcast media in the United States absorb premium pricing for FCC-compliant closed captioning modules and frame-accurate video pipelines, while regional publisher cooperatives in Germany prioritize GDPR-certified mid-tier subscriptions. Cost compression in the standard tier intensifies because modular API-first platforms commodify core content management features. Digital-native outlets exhibit highest price sensitivity, unbundling suite purchases into best-of-breed point solutions.
Supply Chain Analysis
Upstream cloud infrastructure feeds from hyperscale data center concentrations in the United States, Ireland, and Germany, with compute and storage resources forming the primary input stack alongside natural language processing APIs and multimedia rendering engines. Single-source vulnerability concentrates around dominant cloud providers operating European sovereign data zones. Distribution runs through direct enterprise sales teams for broadcast incumbents, API marketplaces for developer-centric buyers, and regional value-added resellers serving Nordic publisher cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Newsroom software sits in early-cycle expansion as EU AI Act compliance mandates force retrofit investments across European publishing operations, accelerating replacement of legacy on-premises infrastructure.
For Market Incumbents: Insulate enterprise positioning by embedding algorithmic transparency audit trails ahead of divergent Brussels-Washington-New Delhi disclosure mandates, while deepening API interoperability partnerships to defend against modular point-solution encroachment. Channel control over media monitoring databases remains the critical lever for sustaining pricing power against boutique PR workflow specialists.
For New Entrants and Emerging Players: Nordic underpenetration offers the most accessible white-space entry, where localized language support and regional media partnerships remain underserved by global vendors. Target Sweden, Norway, and Denmark through GDPR-compliant SaaS offerings with embedded Scandinavian editorial workflow templates, leveraging pilot-to-scale procurement patterns visible in German regional cooperatives.
For Investors and Strategic Acquirers: Cloud-native workflow specialists with pre-built EU AI Act governance architecture represent the priority acquisition archetype for capturing compliance-premium pricing in enterprise media accounts. Monitor TRAI digital convergence framework implementation timelines in India as the inflection signal for infrastructure modernization procurement waves.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Enables modular unbundling of content management from distribution analytics for digital-native outlets. |
| EU AI Act Compliance Certification | Creates pricing premiums in German and French enterprise media buyer segments. |
| Acquisition of Nordic Workflow Specialist | Secures localized language capabilities and regional media partnership networks. |
| Edge Computing Deployment | Compresses editorial cycle times for real-time multimedia asset management in broadcast operations. |
| Strategic Partnership with Hyperscaler | Guarantees European data residency for GDPR-sensitive German publisher migrations. |
Research Methodology
Cross-validation between primary interviews with CTOs, editorial workflow engineers, and procurement officers at broadcast networks and digital publishers anchors the qualitative findings, while secondary validation draws from TRAI regulatory filings, EU AI Act implementation guidance, SEC software vendor disclosures, and hyperscaler capex announcements. Bottom-up segmentation modeling triangulates against top-down market sizing across deployment models, organization tiers, and regional adoption patterns.
Calibration against historical procurement cycle data and disclosed vendor revenue trajectories shapes the analytical framework across the projection horizon. Segmentation dimensions include product type, end-user category, deployment architecture, and feature integration depth, with CAGRs derived from elasticity modeling of cloud migration rates and AI feature adoption curves. Forecast inputs incorporate EU AI Act compliance investment schedules and TRAI digital convergence infrastructure mandates.
Practitioners should monitor regulatory divergence across Brussels, Washington, and New Delhi for early signals of fragmented certification requirements. Forecasts reflect assumptions around cloud migration velocity and AI governance investment timelines. Material shifts in EU AI Act enforcement stringency or TRAI framework implementation pace would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Anti-Plagiarism for the Education Sector Market
Software & Services
Augmented Reality Software Development Kit Market
Software & Services
Sales Training Software Market
Software & Services
Global Call Tracking Software Market
Software & Services
Global Student Information System Market
Software & Services
PLM and Engineering Software Market
Software & Services
Global Linux Operating System Market
Software & Services
North America Saas-Based Expense Management Market
Software & Services
Dynamic Slotting and Storage Optimization Software Market
Software & Services
Vacation Rental Software Market
Software & Services
Apache Spark Market
Software & Services
Global Nosql Database Market
Software & Services
Global Corporate Wellness Software Market
Software & Services
Business Rules Management System Market
Software & Services
Global Address Verification Software Market
Software & Services
Computer Engineering Market