
 MEP Software Market | 2026-2036
MEP Software Market Size, Share, and Industry Trends Forecast 2026-2036
MEP Software Market Analysis
Cloud-native BIM interoperability is reorganizing competitive tiers in MEP software as vendors race to unify mechanical, electrical, and plumbing data across project lifecycles. Autodesk leverages its Revit platform to anchor design-to-fabrication workflows for large infrastructure teams. Bentley Systems sustains deep penetration in water and energy infrastructure through advanced digital twin integration. Trimble differentiates by dominating field-to-office connectivity with hardware-software bundles for construction layout and MEP installation verification.
MEP software encompasses digital tools for modeling, calculating, and coordinating mechanical ventilation, electrical power distribution, and plumbing systems within building information models, typically operating with parametric object libraries that encode manufacturer-specific performance data such as duct friction coefficients or circuit breaker load curves. Its primary purpose is eliminating clashes between trades before construction begins while automating code compliance checks against regional building standards. BIM Integration commands the largest revenue share as owners mandate federated models for handover and facilities management, yet Cloud-Based deployment is expanding fastest as distributed engineering teams require real-time collaboration across time zones. Energy Analysis solutions carry premium pricing due to embedded physics engines that simulate thermal loads and carbon emissions against tightening jurisdictional thresholds.
Building codes from the International Code Council (ICC) in the United States, the EPBD framework administered by the European Commission, and model energy standards published by ASHRAE collectively dictate minimum performance thresholds that MEP software must automate to retain practitioner licenses. These regulatory layers shape product roadmaps by forcing vendors to update code databases annually and embed jurisdiction-specific compliance engines. Stakeholders must weigh whether to consolidate around full-stack platforms or preserve specialized point solutions as owner requirements fragment across energy modeling, prefabrication, and asset operations.
Market Dynamics
Cloud-native BIM interoperability is compressing vendor margins as engineering firms demand unified mechanical, electrical, and plumbing data layers across federated project models, forcing incumbents to rebuild architecture around open APIs rather than proprietary file formats.
Growth Catalysts
- EPBD Energy Mandates:The European Union's Energy Performance of Buildings Directive tightens efficiency thresholds for HVAC and electrical systems, compelling engineering teams to adopt automated compliance engines embedded in MEP platforms.
- Prefabrication Workflows:Offsite construction methods require millimeter-accurate MEP coordination, driving demand for design-to-fabrication software that exports directly to CNC cutting machines and robotic assembly lines.
- Germany's Digitalization Push:German construction contractors are accelerating cloud migration of mechanical and electrical workflows, creating concentrated demand for real-time collaboration tools across distributed engineering teams.
Market Restraints
- Legacy Data Silos:Decades of proprietary CAD file formats trap building system data in incompatible repositories, raising integration costs for owners seeking unified digital twins.
- Specialized Talent Scarcity:MEP engineers with dual competency in domain physics and computational scripting command premium wages, constraining software vendor implementation capacity.
- Input Cost Volatility:Cloud infrastructure pricing fluctuations from hyperscale providers directly compress SaaS margins for vendors serving mid-market mechanical contractors.
Strategic Opportunities
- India's Smart Cities Mission:Urban infrastructure digitization programs create white space for MEP platforms that automate water distribution and electrical load balancing across municipal portfolios.
- Digital Twin Convergence:Integration of IoT sensor streams with BIM geometry enables predictive maintenance contracts for commercial building operators, shifting revenue from perpetual licenses to recurring service fees.
- Retrofit Regulatory Tailwinds:ASHRAE 90.1 energy standard updates in the United States mandate deep energy retrofits of existing building stock, expanding addressable market beyond new construction.
Industry Challenges
- Interoperability Certification Delays:BuildingSMART International's openBIM compliance testing creates bottlenecks as vendors await certification for IFC 4.3 data exchange protocols.
- Computational Skill Gaps:Mid-career mechanical engineers lack training in parametric design scripting, slowing adoption of generative HVAC layout tools among established firms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MEP Software Market |
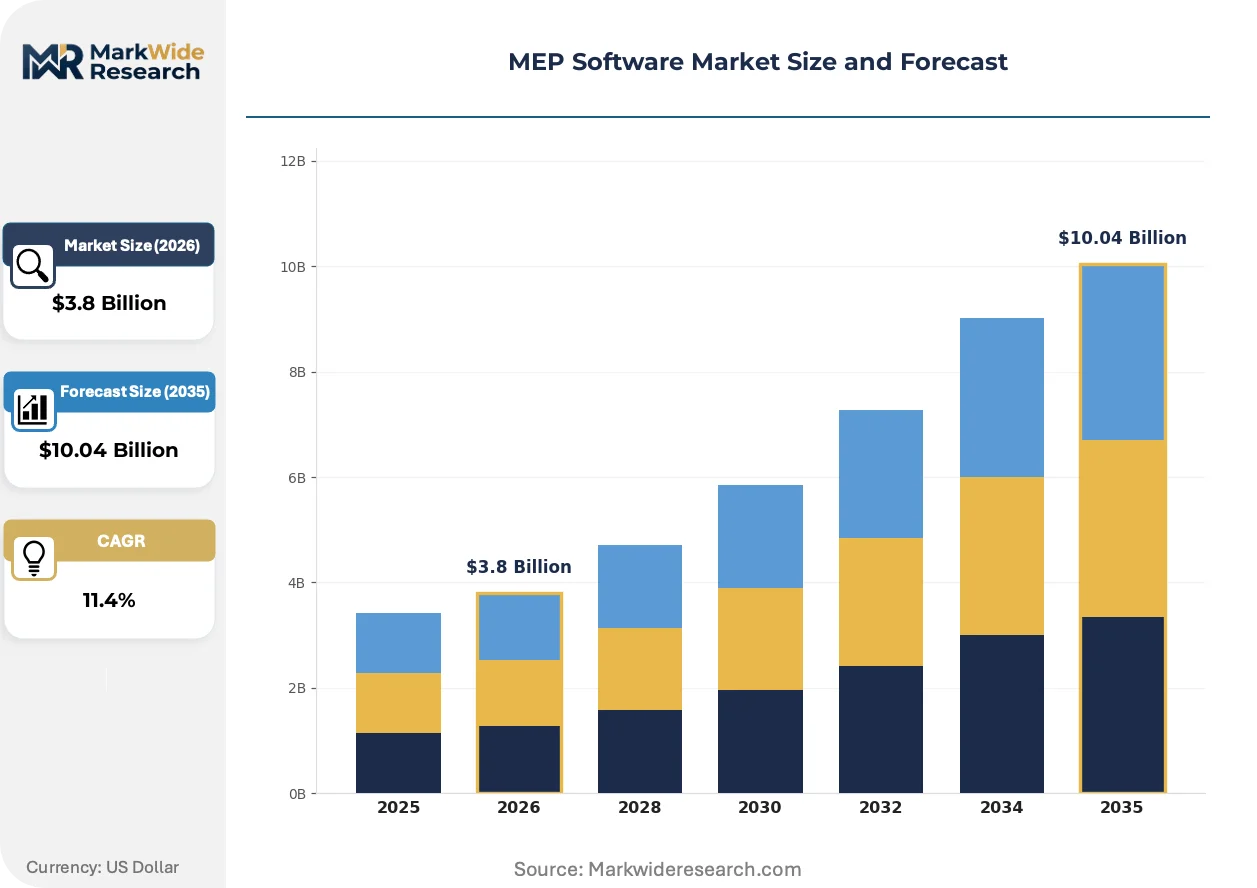
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Design Software, Estimation Software, Project Management Tools, BIM Integration End User: Contractors, Engineers, Architects, Facility Managers Deployment: On-Premise, Cloud-Based, Hybrid, Mobile Solution: Energy Analysis, Load Calculation, System Design, Code Compliance |
| Companies Covered | Bentley Systems, COINS Global, Autodesk, Witas, eVolve MEP, Trimble, MagiCAD, Exactal, Nemetschek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MEP Software Market Emerging Trajectories
Edge computing architectures are redistributing processing loads from centralized data centers to construction site trailers, enabling real-time clash detection without reliable internet connectivity. This infrastructure shift is compressing decision cycles for field teams.
Generative design algorithms for duct routing and electrical circuiting are miniaturizing the engineering labor required for schematic design phases, allowing mid-sized mechanical contractors to bid on complex institutional projects previously reserved for national firms. Early adopters in healthcare and laboratory verticals report 40% reduction in design iteration hours. The technology is miniaturizing traditional tier distinctions between regional and national MEP engineering practices.
The European Union's F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in commercial HVAC systems, forcing MEP software vendors to update embedded thermodynamic property databases and recalibrate load calculation engines. Equipment manufacturers in Germany and France are prioritizing platforms with native support for natural refrigerant performance curves. This regulatory compression is accelerating consolidation around vendors with dedicated sustainability modules.
Subscription pricing models are displacing perpetual licenses across the contractor segment, unbundling software access from hardware maintenance contracts that previously bundled field layout instruments. Distributors like Trimble's construction channel are pivoting toward usage-based billing for cloud-coordination seats. This shift is most visible in North American commercial construction, where general contractors now mandate SaaS delivery for all trade contractor software procurement.
MEP Software Market Segmentation
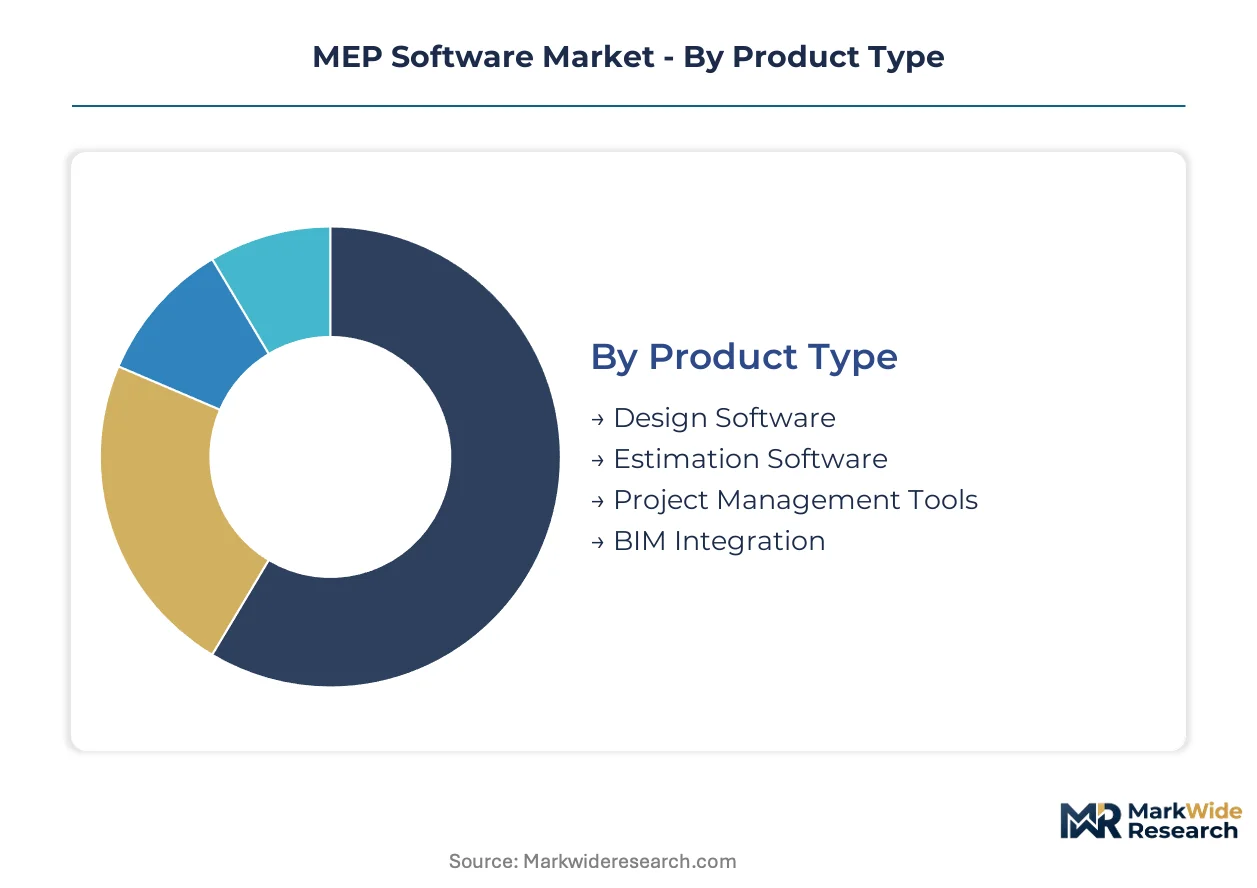
MEP software vendors organize product portfolios around distinct workflow stages and user competencies. Segmentation reveals where engineering firms consolidate spending versus where specialized point solutions retain pricing power.
Product Type:
Premium margins concentrate in modules that automate code compliance and fabrication-ready outputs, while commoditized design tools face pricing compression from open-source alternatives.
- Design Software:Core platforms for parametric modeling of ductwork, piping, and electrical raceways with manufacturer-specific component libraries. Demand clusters with German mechanical contractors modernizing HVAC workflows under EPBD efficiency mandates, where generative layout tools reduce engineering hours by 40 percent.
- BIM Integration:Federated model coordination engines that clash-detect across mechanical, electrical, and plumbing trades in real time. US commercial building owners now mandate BIM handover for facilities management, forcing mid-sized contractors to upgrade from 2D CAD.
- Estimation Software:Automated quantity takeoff and material costing tied to live supplier pricing databases.
- Project Management Tools:Schedule and resource coordination modules integrated with field progress tracking.
The dominant share belongs to BIM Integration, while Energy Analysis (under Solution) is closing the gap fastest.
End User:
Procurement authority varies sharply by stakeholder type, with contractors driving volume and architects controlling specification decisions early in project cycles.
- Contractors:Field-facing users requiring fabrication-grade accuracy and hardware-software bundles for layout verification. German MEP contractors are consolidating vendor relationships around cloud-native platforms that export directly to CNC machines.
- Engineers:Technical specifiers prioritizing physics-engine accuracy for load calculations and energy compliance. ASHRAE 90.1 updates in the US are forcing engineering consultants to upgrade thermal simulation capabilities.
- Architects:Early-stage design collaborators needing lightweight visualization tools for schematic coordination.
- Facility Managers:Post-handover operators leveraging digital twin data for predictive maintenance contracts.
Contractors command the largest seat count, though Facility Managers are expanding the fastest as owners shift to outcome-based service agreements.
Deployment:
Cloud infrastructure costs now determine SaaS margin structures more than feature differentiation, with hybrid architectures emerging as a compromise for security-conscious owners.
- Cloud-Based:Real-time collaboration platforms enabling distributed engineering teams across time zones. German construction firms are migrating mechanical and electrical workflows fastest, driven by federal digitalization incentives.
- On-Premise:Legacy installations retaining favor among defense and critical infrastructure projects with air-gapped security requirements.
- Hybrid:Split architectures keeping sensitive IP on local servers while enabling cloud coordination with external trades.
- Mobile:Field inspection and installation verification apps running on ruggedized tablets with offline sync capabilities.
Cloud-Based deployment holds the dominant position, while Hybrid models are gaining traction fastest among institutional clients with data sovereignty concerns.
Solution:
Regulatory complexity creates tiered pricing power, with solutions embedding jurisdictional code engines commanding 40-60 percent premiums over generic calculation tools.
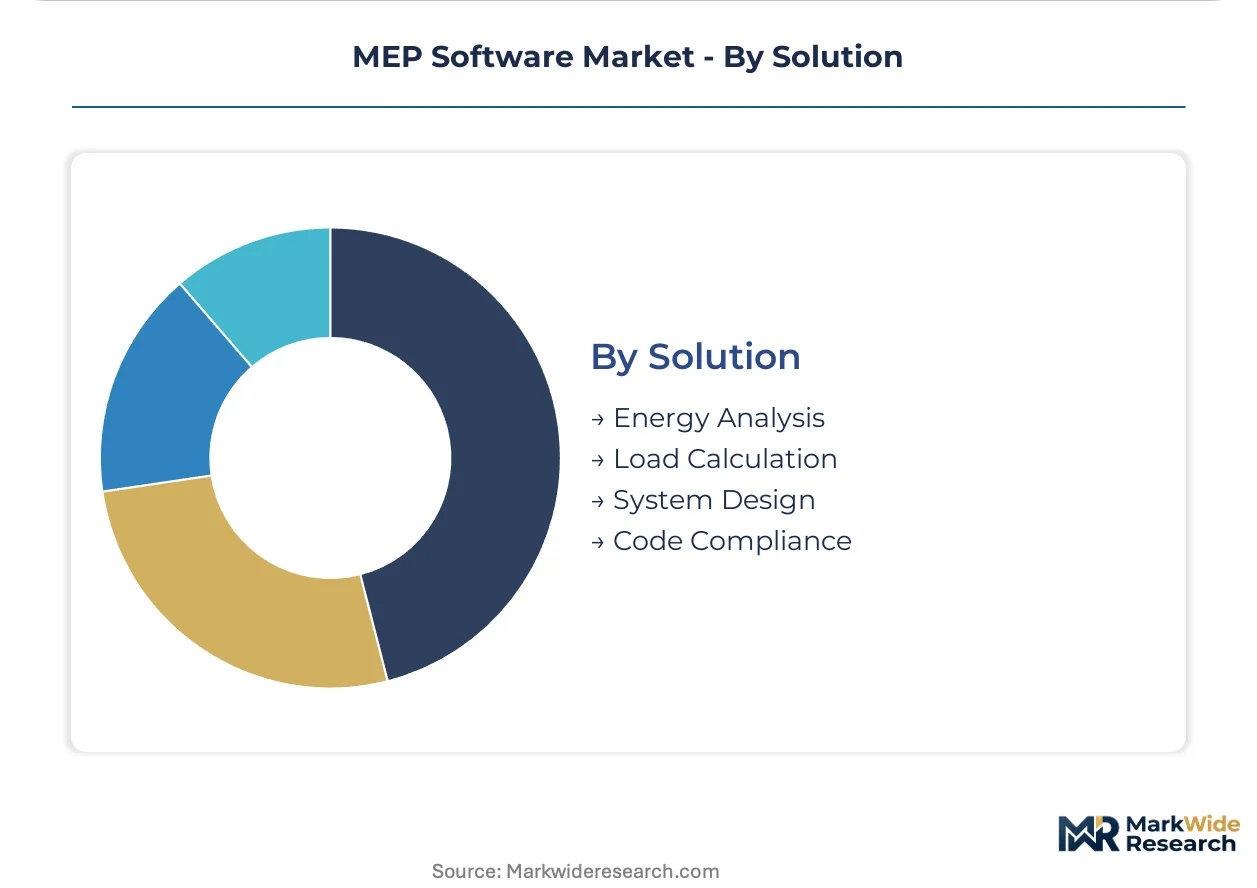
- Energy Analysis:Physics engines simulating thermal loads, carbon emissions, and refrigerant performance against tightening efficiency standards. The EU F-Gas Regulation is forcing updates to natural refrigerant property databases, favoring vendors with dedicated sustainability modules.
- Code Compliance:Automated checking engines against ICC, ASHRAE, and EPBD standards with annual database updates. Engineering firms in Germany and France prioritize platforms with native EPBD compliance to retain licensing.
- Load Calculation:HVAC and electrical demand sizing tools with climate-specific weather file integration.
- System Design:Equipment selection and sizing modules tied to manufacturer performance curves.
Energy Analysis generates the highest revenue per seat, while Code Compliance is expanding most quickly as jurisdictions tighten enforcement and audit frequency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates with established software vendors in North America and Western Europe, while demand expansion clusters in Germany, the United States, and India where construction digitization accelerates fastest. Cloud infrastructure investments and regulatory tightening on building energy performance are redrawing regional competitive positions.
Germany
Mechanical contractors in Bavaria and North Rhine-Westphalia are migrating HVAC workflows to cloud-native platforms under federal digitalization incentives. The EPBD implementation through the national Building Energy Act mandates automated compliance engines for energy performance certificates. Engineering clusters in Munich and Frankfurt concentrate demand for real-time BIM coordination tools that export directly to CNC fabrication equipment.
United States
Commercial building owners in Texas and California now mandate BIM handover protocols for facilities management, forcing mid-sized MEP contractors to abandon 2D CAD. ASHRAE 90.1 updates through state energy codes require thermal simulation capabilities that embed jurisdiction-specific compliance databases. The Southeast construction corridor from Atlanta to Miami shows fastest cloud adoption among regional mechanical contractors bidding on healthcare and laboratory projects.
India
Smart Cities Mission funding in Maharashtra and Karnataka is digitizing municipal water distribution and electrical load balancing systems. The Central Electricity Authority mandates automated demand forecasting for urban infrastructure portfolios. Engineering services clusters in Bangalore and Hyderabad are developing localized MEP platforms that integrate with indigenous equipment manufacturer databases for HVAC and electrical components.
United Kingdom
London-based engineering consultancies are consolidating vendor relationships around federated model coordination for complex commercial retrofits. The Building Safety Regulator's digital gateway requirements enforce structured data handover for high-risk building systems. Manchester and Birmingham contractor networks show concentrated adoption of mobile field verification apps running on ruggedized tablets with offline synchronization capabilities.
France
Paris-region engineering firms prioritize platforms with native EPBD compliance modules to retain professional licensing under tightened efficiency audits. The F-Gas Regulation implementation is accelerating updates to natural refrigerant property databases in HVAC design software. Lyon and Marseille industrial clusters demand energy analysis solutions with embedded carbon emissions simulation against national low-carbon building standards.
MEP Software Market Vendor Landscape
Concentration sits with full-stack platform providers that anchor design-to-fabrication workflows, while specialized point-solution vendors retain pricing power in code compliance and energy analysis modules. Three archetypes dominate: infrastructure-focused incumbents with deep digital twin integration, construction-technology bundlers combining hardware-software offerings, and cloud-native challengers attacking mid-market mechanical contractors. Competitive moves center on API openness for federated BIM data exchange and vertical integration into prefabrication output formats.
Within the infrastructure-platform tier, Bentley Systems and Autodesk exemplify contrasting geographic anchoring strategies, with the former sustaining penetration in water and energy utilities and the latter dominating commercial building design workflows. Trimble occupies a distinct position bridging field hardware with cloud coordination software for construction layout verification. Among European specialists, Nemetschek represents the architectural-software heritage segment expanding into MEP coordination, while MagiCAD exemplifies the HVAC-engineering-focused module approach. These five entities illustrate how vendor archetypes map to distinct buyer workflows across project lifecycles.
| Leading Market Players |
|---|
| Bentley Systems |
| COINS Global |
| Autodesk |
| Witas |
| eVolve MEP |
| Trimble |
| MagiCAD |
| Exactal |
| Nemetschek |
| Others |
Supply Flow & Price Mechanics
BuildingSMART International's openBIM certification regime gates both vendor qualification and price differentiation simultaneously, forcing suppliers to absorb compliance costs before accessing premium tiers while buyers pay premiums only for certified interoperability modules.
Pricing Analysis
ASHRAE 90.1 and EPBD compliance mandates dictate the pricing tier structure across MEP software, with code-embedded engines commanding 40-60 percent premiums over generic calculation tools. Three-tier pricing structure across premium, standard, and economy levels separates full-stack platforms with native BIM coordination from point solutions and open-source alternatives. Cost compression in the mid-market contractor segment is intensifying because cloud infrastructure pricing from hyperscale providers directly squeezes SaaS margins. Regional mechanical contractors in Germany and the American Southeast show highest price sensitivity, while institutional owners in healthcare and laboratory verticals demonstrate lowest sensitivity due to mandated compliance requirements.
Supply Chain Analysis
United States and Germany anchor core platform development for MEP software, with India emerging as the primary engineering services delivery hub for localization and implementation support. Cloud infrastructure draws from hyperscale data center networks concentrated in Northern Virginia, Frankfurt, and Mumbai, while specialized physics engines source from academic research partnerships in Switzerland and the Netherlands. Single-source vulnerability concentrates in BuildingSMART International's IFC certification pipeline, where testing bottlenecks delay product releases. Distribution runs through direct enterprise sales for large contractors, construction-technology distributors for mid-market hardware-software bundles, and regional systems integrators for localized deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in code compliance and energy analysis modules, as jurisdictional regulatory divergence creates defendable niches for specialized vendors against full-stack incumbents.
For Market Incumbents: Fortify API openness for federated BIM data exchange while accelerating backward integration into prefabrication output formats. Cloud-native challengers threaten mid-market mechanical contractor relationships in Germany and the American Southeast. Certification investment in BuildingSMART International's IFC 4.3 compliance represents the critical defensive lever. For New Entrants and Emerging Players: Lead with India's Smart Cities Mission urban infrastructure digitization programs, where localized MEP platforms integrating indigenous equipment manufacturer databases face minimal incumbent penetration. Municipal water distribution and electrical load balancing automation in Maharashtra and Karnataka offers the most penetrable white space. Channel partnerships with regional systems integrators provide the optimal go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed construction-technology bundlers combining field hardware with cloud coordination software. Long-term viability over a 5-10 year window hinges on recurring revenue transition from perpetual licenses to outcome-based service agreements. The signal to watch is owner mandate expansion for BIM handover protocols across commercial building portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies mechanical, electrical, and plumbing data layers across federated project models for large infrastructure teams. |
| Acquisition of Specialist Firm | Captures code compliance engines with embedded EPBD and ASHRAE databases for jurisdiction-specific automation. |
| Geographic Expansion | Establishes localized engineering services presence in Bangalore and Hyderabad for India's Smart Cities digitization. |
| Strategic Partnership | Links BIM geometry with IoT sensor streams for predictive maintenance contracts with commercial building operators. |
| Product Launch | Introduces generative design algorithms for duct routing that reduce engineering hours in healthcare and laboratory verticals. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through primary interviews with MEP engineering directors, construction technology procurement officers, BIM coordinators at general contractors, and facilities management executives at commercial building owners. Secondary validation drew from BuildingSMART International certification databases, ASHRAE standards publications, European Commission EPBD implementation reports, and hyperscaler cloud infrastructure capex disclosures. Bottom-up triangulation across project-level software procurement data combined with top-down market sizing across deployment models and end-user segments.
Across the analysis window, the forecasting framework modeled segmentation dimensions including deployment architecture, organization size tier, vertical application, integration complexity level, and regional adoption pattern. CAGRs were derived from growth rate convergence analysis across these segments. Key inputs included cloud infrastructure cost trajectories from hyperscale providers and regulatory enforcement intensity indices for building energy codes.
Forecasts assume regulatory continuity in EPBD implementation across European Union member states and ASHRAE 90.1 adoption patterns across American state energy codes; material policy shifts would require re-modeling. Specific risks that could revise projections include BuildingSMART International certification delays, hyperscale cloud pricing volatility, and refrigerant phase-down acceleration under F-Gas Regulation amendments. Recalibration cycles align with material shifts in jurisdictional code adoption and owner mandate expansion for digital handover protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
DevOps Market
Software & Services
Commissioning Software Market
Software & Services
Independent Software Vendors (Isvs) Market
Software & Services
Cloud Business Process Management (BPM) Software Market
Software & Services
Computer Assisted Coding Software Market
Software & Services
Global Third-Party Logistics Software Market
Software & Services
Board Portal Market
Software & Services
Embedded Hypervisor Market
Software & Services
Global Idea Management Software Market
Software & Services
Chromatography Data System (CDS) Software Market
Software & Services
Job Description Management Software Market
Software & Services
Global Meeting Room Booking System Software Market
Software & Services
Latin America Human Resource (HR) Technology Market
Software & Services
Lead-To-Account Matching and Routing Software Market
Software & Services
Global Reference Check Software Market
Software & Services
POS Software Market