
 Category Management Software Market | 2026-2036
Category Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Category Management Software Market Intelligence
GDPR is hardening the cost-of-entry calculus for vendors serving European retail chains. Oracle Corporation leverages its database infrastructure to anchor multi-tenant cloud deployments. SAP competes through deep ERP integration that sustains renewal rates among manufacturers. IBM differentiates via Watson-powered analytics modules that occupy the premium tier of enterprise contracts.
Category management software orchestrates assortment planning, shelf-space optimization, and supplier collaboration through algorithmic scoring of SKU profitability, typically processing point-of-sale feeds with sub-second refresh latency. Cloud-based deployments lead in new bookings as retailers abandon capital-intensive on-premises infrastructure. SaaS licensing models capture the fastest expansion among deployment modes by converting upfront license revenue into recurring streams. Analytics features command the deepest margin pools as AI-driven demand forecasting becomes non-negotiable for omnichannel inventory positioning.
The EU AI Act and GDPR jointly constrain automated decision-making in procurement workflows, forcing vendors to embed explainability layers. The US Federal Trade Commission scrutinizes algorithmic pricing for anti-competitive effects, elevating compliance engineering budgets. China's MIIT mandates data localization for cloud platforms, fragmenting architecture requirements across jurisdictions. Stakeholders must monitor regulatory divergence as a primary determinant of product roadmap prioritization and geographic expansion sequencing.
Market Dynamics
Cloud migration is compressing deployment cycles as retailers abandon capital-intensive on-premises infrastructure for SaaS licensing models that convert upfront license revenue into recurring streams. The EU AI Act and GDPR jointly constrain automated decision-making in procurement workflows, forcing vendors to embed explainability layers into algorithmic scoring systems.
Growth Catalysts
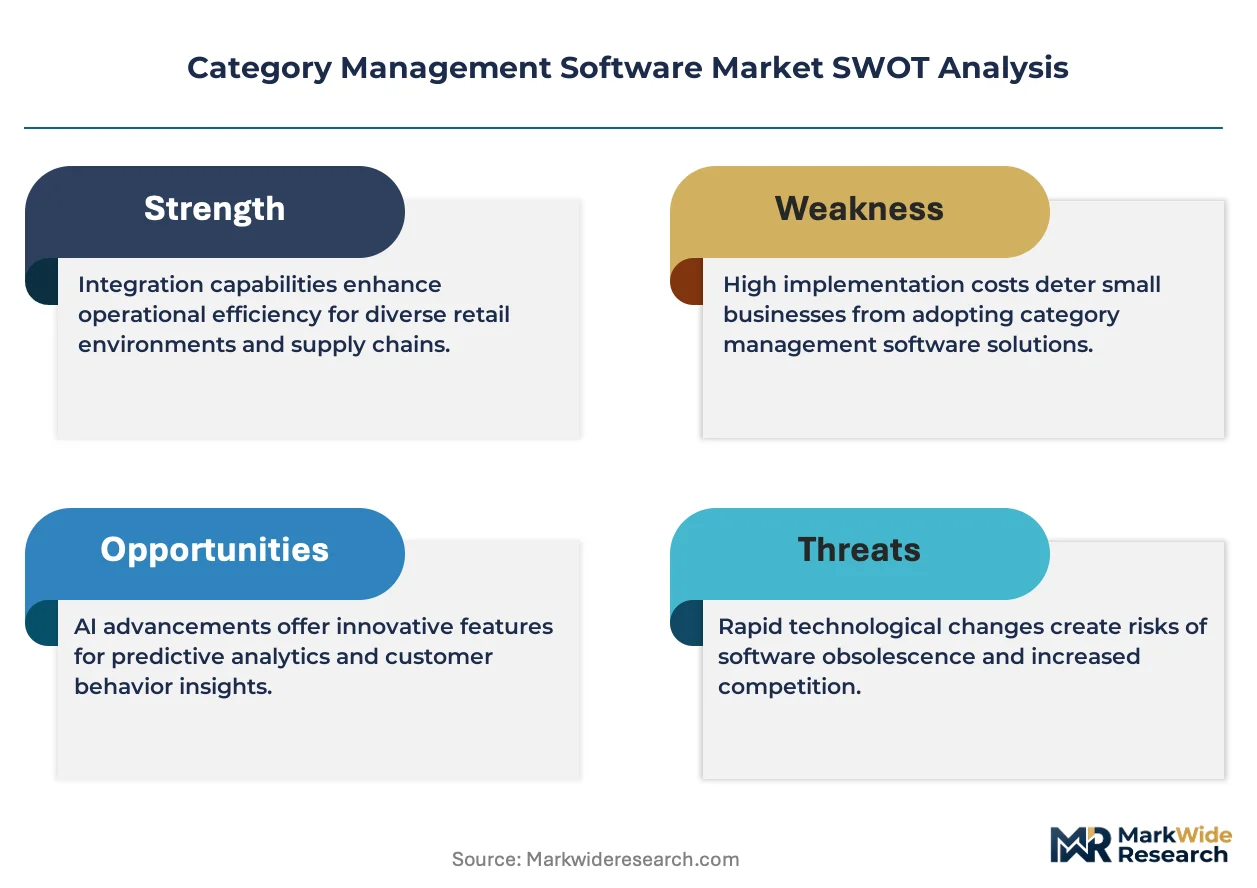
- EU AI Act compliance mandates:European retailers must upgrade legacy platforms to meet explainability requirements for automated procurement decisions, accelerating replacement cycles.
- Point-of-sale data velocity:Sub-second refresh latency demands from omnichannel inventory positioning are pulling retailers toward cloud-native architectures.
- China's MIIT data localization:Cloud platforms must architect region-specific deployments, fragmenting infrastructure requirements and expanding addressable vendor opportunities.
Market Restraints
- GDPR cost-of-entry calculus:European data residency and consent management requirements inflate engineering budgets for vendors without existing compliance infrastructure.
- US FTC algorithmic pricing scrutiny:Anti-competitive effect investigations elevate legal review costs for demand-forecasting modules that adjust pricing dynamically.
- Legacy ERP integration complexity:Deep SAP and Oracle system entrenchment among manufacturers creates switching friction that extends sales cycles.
Strategic Opportunities
- Underpenetrated mid-market retail chains:Tier-two grocers in Germany and France lack dedicated category management platforms, presenting greenfield SaaS expansion targets.
- Watson-powered analytics convergence:AI-driven demand forecasting modules are integrating natural language interfaces for supplier negotiation workflows.
- India's PLI scheme for retail tech:Domestic software development incentives create localized product development cost advantages for cloud platform providers.
Industry Challenges
- Explainability engineering talent scarcity:The intersection of machine learning and regulatory documentation expertise commands premium compensation in European hiring markets.
- Multi-jurisdiction certification timelines:Simultaneous GDPR, EU AI Act, and China's MIIT compliance reviews extend product launch windows by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Category Management Software Market |
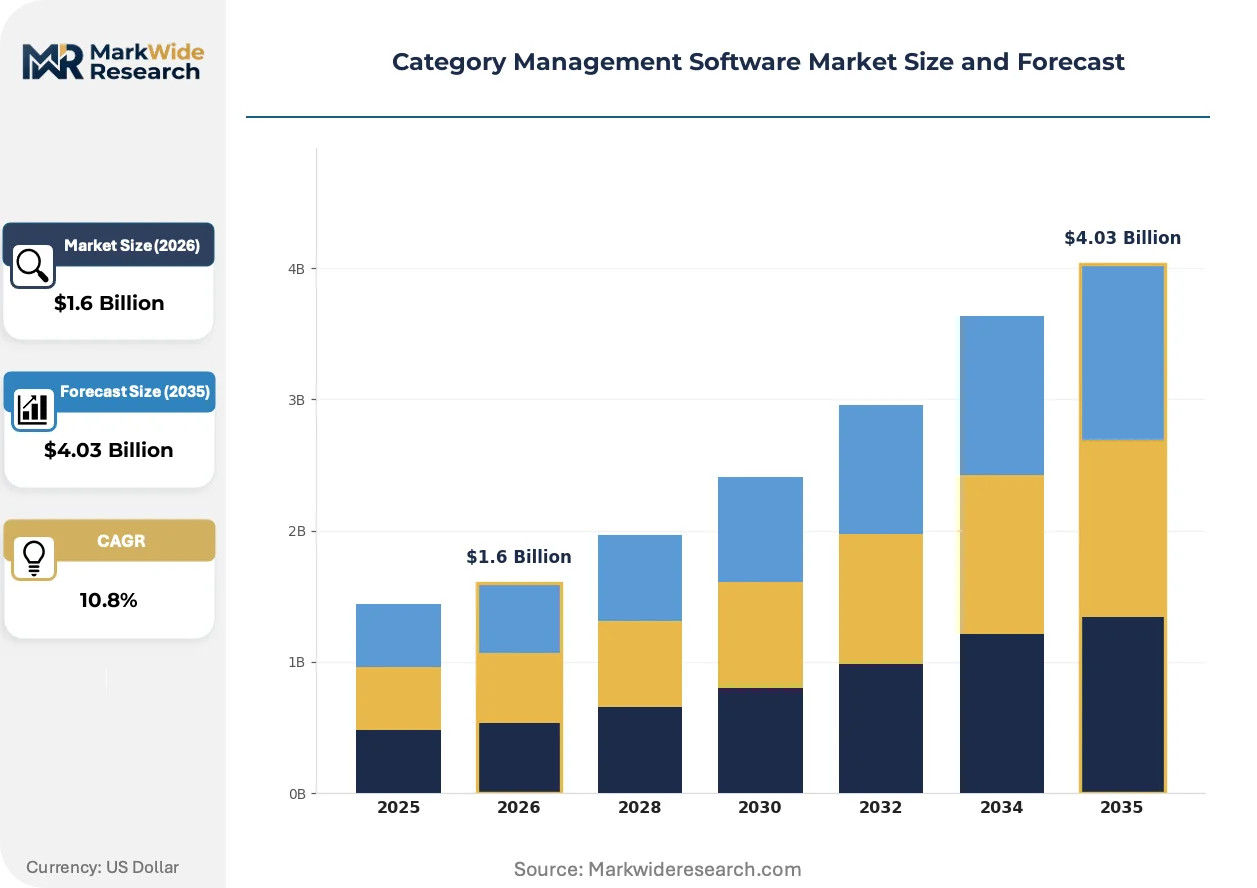
| Market Size in 2026 | $1.6 Billion |
| Market Size in 2035 | $4.03 Billion |
| CAGR (2026 – 2036) | 10.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based, On-premises, Hybrid, Mobile Solutions End User: Retailers, Distributors, Manufacturers, Wholesalers Deployment: Public Cloud, Private Cloud, SaaS, Software Licensing Feature: Analytics, Reporting, Collaboration, Inventory Management |
| Companies Covered | Oracle Corporation, Blue Yonder, SAP, Epicor Software Corporation, Aptos, Infor, IBM, Manhattan Associates, SAS Institute, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Category Management Software Market Strategic Shifts & Innovations
Algorithmic demand forecasting is displacing rule-based replenishment as the core value proposition, with vendors competing on prediction accuracy rather than workflow automation alone. Three interconnected developments are compressing competitive differentiation timelines.
Generative AI is integrating natural language interfaces into supplier collaboration modules, allowing category managers to query profitability scenarios through conversational prompts. Large retail chains in the United States are piloting these tools for assortment planning. The technology is integrating predictive and prescriptive analytics into unified workflows that compress decision latency from days to hours.
The EU AI Act's risk-based classification system is mandating human-in-the-loop checkpoints for high-risk procurement automation. European retailers must maintain audit trails for algorithmic shelf-space allocation decisions. Grocery chains in Germany and France are responding by embedding explainability dashboards that decompose SKU scoring into interpretable factor weights.
Subscription-based platform access is displacing perpetual license purchases as the dominant procurement model among mid-market retailers. Category managers now expect continuous feature deployment rather than annual version upgrades. This shift is most visible among regional grocery cooperatives in the United States, where capital constraints favor operating expenditure structures over upfront software investments.
Category Management Software Market Segmentation
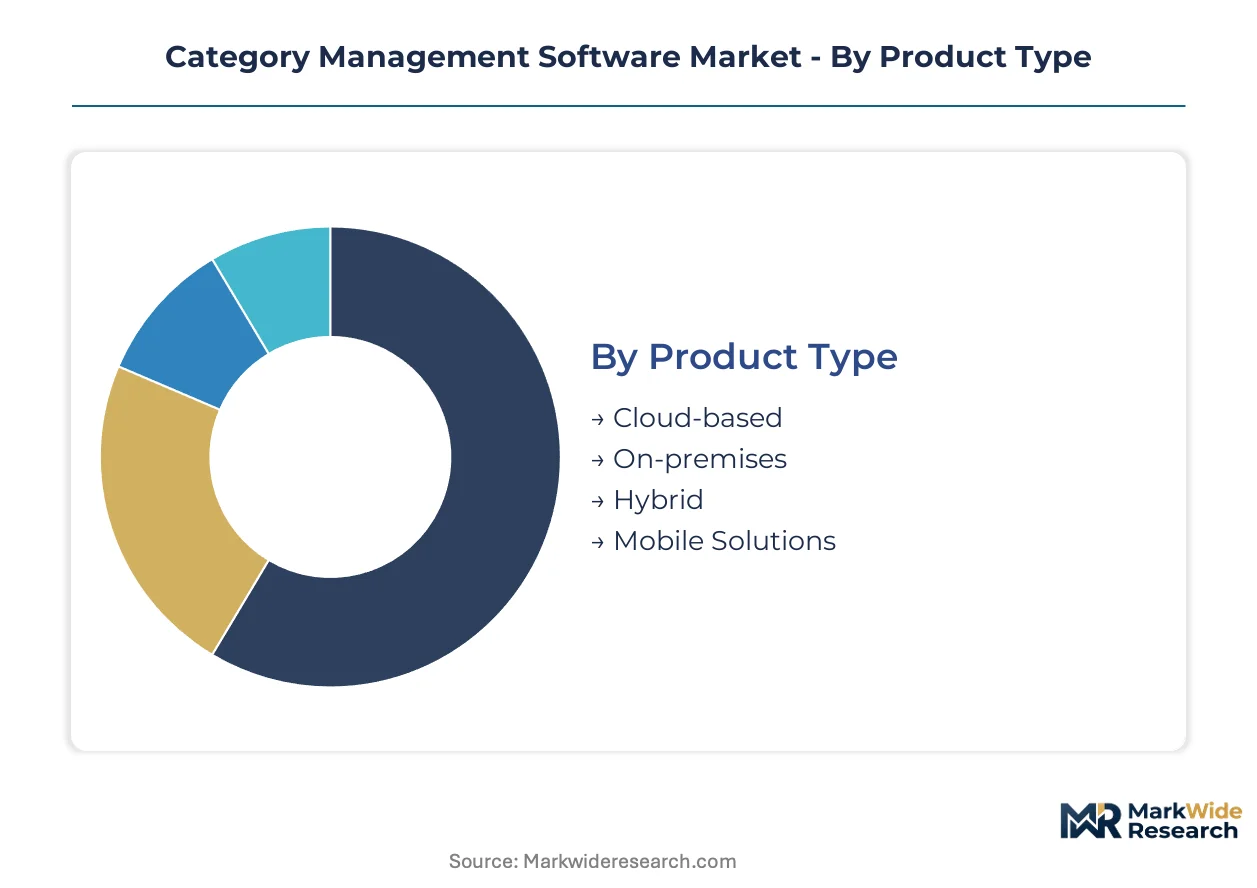
Segmentation in category management software reveals how procurement priorities diverge across infrastructure maturity and regulatory exposure. Retailers modernizing legacy ERP systems drive replacement cycles that favor specific deployment architectures over others.
Product Type:
Upgrade cycles accelerate where cloud infrastructure reduces capital expenditure burdens and compliance automation becomes mandatory.
- Cloud-based:Multi-tenant architectures process point-of-sale feeds with sub-second latency while embedding GDPR consent management and EU AI Act explainability layers. German grocery cooperatives and US regional chains prioritize these platforms to escape on-premises maintenance overhead.
- On-premises:Single-tenant installations persist among manufacturers with deep SAP or Oracle ERP entrenchment, where data residency requirements and legacy integration complexity extend replacement timelines. China's MIIT localization mandates sustain demand for captive infrastructure among domestic retail conglomerates.
- Hybrid:Split architectures isolate sensitive procurement data on local servers while pushing analytics workloads to public cloud nodes.
- Mobile Solutions:Native iOS and Android applications enable floor-level shelf-space audits and real-time supplier communication.
Volume placements concentrate in Cloud-based; the faster expansion belongs to Hybrid.
End User:
Customer type determines feature depth requirements and pricing tolerance across the procurement workflow stack.
- Retailers:Omnichannel grocers and big-box operators demand algorithmic assortment planning with AI-driven demand forecasting modules. French and German chains embed explainability dashboards to satisfy EU AI Act audit trail requirements for automated shelf-space decisions.
- Manufacturers:Consumer packaged goods producers prioritize supplier collaboration portals with natural language negotiation interfaces. Watson-powered analytics modules occupy premium contract tiers among multinational producers seeking predictive inventory positioning.
- Distributors:Mid-tier logistics operators adopt SaaS licensing to convert upfront software investments into operating expenditures.
- Wholesalers:Regional cooperatives favor subscription-based platform access with continuous feature deployment over annual version upgrades.
Retailers dominate current bookings; manufacturers are gaining share fastest through ERP-integrated replacement cycles.
Deployment:
Infrastructure choice reflects jurisdictional data sovereignty pressures and internal IT capability depth.
- Public Cloud:Shared infrastructure delivers elastic compute for seasonal demand spikes without capital commitment. US mid-market chains abandon owned data centers for AWS and Azure deployments that embed FTC-compliant algorithmic pricing documentation.
- SaaS:Recurring revenue models capture the steepest expansion trajectory by converting perpetual license customers to subscription structures. Regional grocery cooperatives in the United States favor operating expenditure structures over upfront software investments.
- Private Cloud:Dedicated tenant isolation serves retailers with segmented brand portfolios requiring data firewalls.
- Software Licensing:Perpetual purchase agreements persist among capital-constrained municipalities and institutional buyers with multi-year depreciation schedules.
Public Cloud anchors installed base; SaaS licensing climbs the fastest among new bookings.
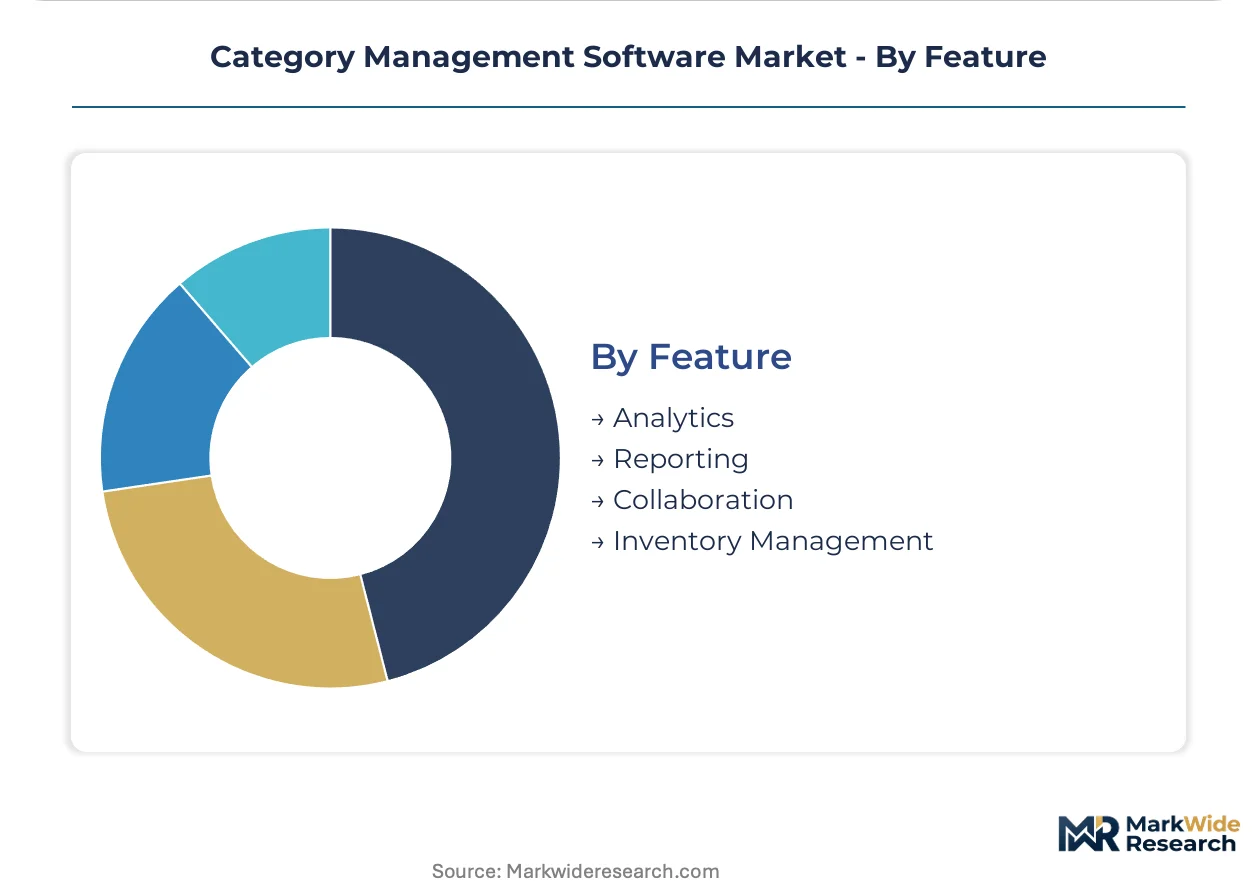
Feature:
Capability prioritization separates premium contract tiers from standard workflow automation offerings.
- Analytics:AI-driven demand forecasting modules command the deepest margin pools as prediction accuracy becomes the primary competitive differentiator. Generative AI integration enables natural language queries that compress decision latency from days to hours.
- Collaboration:Supplier negotiation portals with conversational interfaces attract premium pricing among multinational retail chains piloting generative AI tools.
- Reporting:Automated compliance documentation for GDPR and EU AI Act audit trails reduces legal review overhead.
- Inventory Management:Real-time omnichannel positioning algorithms prevent stockouts across physical and digital storefronts.
Analytics modules capture premium pricing; Collaboration features are expanding most quickly through AI interface investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for category management software concentrates in the United States, Germany, and China as retailers modernize legacy systems and accelerate cloud migration timelines.
United States
Regional grocery cooperatives and omnichannel retailers drive SaaS adoption to escape on-premises maintenance overhead. The FTC scrutinizes algorithmic pricing for anti-competitive effects, elevating compliance engineering budgets. Chicago and Dallas-Fort Worth anchor pilot deployments of generative AI tools for assortment planning.
Germany
Grocery cooperatives prioritize cloud-native platforms with embedded explainability dashboards. The EU AI Act mandates human-in-the-loop checkpoints for automated shelf-space decisions. Berlin and Munich host engineering centers developing interpretable factor weighting systems for SKU scoring algorithms.
China
Domestic retail conglomerates sustain demand for captive infrastructure alongside public cloud deployments. MIIT data localization mandates fragment architecture requirements across jurisdictions. Shanghai and Shenzhen anchor region-specific cloud platform development for compliance with data sovereignty rules.
France
French chains embed explainability layers to satisfy GDPR audit trail requirements for automated procurement workflows. The EU AI Act risk-based classification system constrains algorithmic decision-making velocity. Paris and Lyon concentrate vendor development of compliance documentation automation tools.
India
Domestic software development incentives create localized product development cost advantages for cloud platform providers. The PLI scheme for retail tech attracts engineering investment. Bangalore and Hyderabad anchor delivery centers serving European and North American retail chains.
Category Management Software Market Key Industry Players
United States-based technology conglomerates anchor the premium tier; German and European specialists hold positions in ERP-integrated workflows. The vendor base organizes around three strategic archetypes: database infrastructure providers leveraging multi-tenant cloud deployments, ERP-integrated suite vendors sustaining renewal rates through deep system entrenchment, and AI-powered analytics specialists occupying premium contract tiers. Competitive moves concentrate on M&A for cloud-native capabilities and strategic partnerships for regulatory compliance automation.
Within the database infrastructure tier, Oracle Corporation exemplifies multi-tenant cloud anchoring. SAP occupies a position among ERP-integrated suite vendors with deep manufacturing system entrenchment. IBM represents the AI-powered analytics archetype through Watson-powered modules.
| Leading Market Players |
|---|
| Oracle Corporation |
| Blue Yonder |
| SAP |
| Epicor Software Corporation |
| Aptos |
| Infor |
| IBM |
| Manhattan Associates |
| SAS Institute |
| Others |
Cost & Logistics Intelligence
Mid-market grocery cooperatives in the United States and Germany concentrate procurement authority, anchoring subscription-based SaaS pricing as the dominant commercial model across the category management software landscape.
Pricing Analysis
Short lead-time deployment demands command premium SaaS tiers, while extended implementation cycles access discounted annual commitments. Pricing stratifies across premium, standard, and economy tiers differentiated by AI module depth and GDPR compliance automation bundled into base licensing. Cost compression in the standard tier is intensifying because hyperscaler infrastructure commoditizes core compute resources. Regional grocery cooperatives exhibit highest price sensitivity; multinational retail chains with ERP-integrated workflows demonstrate lowest elasticity.
Supply Chain Analysis
Cloud infrastructure supply rests on hyperscaler data center networks concentrated in the United States, Germany, and China, with regional availability zones fragmenting under MIIT localization mandates. Engineering talent pipelines feed from Indian delivery centers in Bangalore and Hyderabad, while compliance documentation expertise clusters in Berlin and Paris. Single-source vulnerability concentrates in explainability engineering talent pools constrained by EU AI Act implementation timelines. Distribution runs through direct enterprise sales teams supplemented by systems integrator partnerships for SAP and Oracle ecosystem penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The category management software market functions as a cost-of-compliance story, with the EU AI Act erecting barrier-to-entry moats that favor vendors with pre-built explainability infrastructure and documented audit trail capabilities.
For Market Incumbents: Lock in renewal rates among SAP-entrenched manufacturers by deepening ERP integration modules that extend switching friction. Acquire cloud-native specialist firms to compress feature deployment cycles and neutralize emerging SaaS-native competitors targeting mid-market displacement.
For New Entrants and Emerging Players: Cloud-native distribution channels open direct access to tier-two grocery cooperatives in Germany and France lacking dedicated category management platforms. Target underpenetrated mid-market retail chains with freemium analytics tiers that convert to paid subscriptions upon EU AI Act compliance deadlines.
For Investors and Strategic Acquirers: The window for entry favors vertical SaaS specialists with embedded regulatory automation and existing GDPR certification infrastructure. Watch explainability engineering hiring velocity in Berlin and Munich as an inflection indicator for platform upgrade cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep SAP and Oracle ERP anchoring sustains renewal rates among manufacturers. |
| Acquisition of Specialist Firm | Cloud-native capability gaps close through targeted buys of compliance automation vendors. |
| Strategic Partnership | Systems integrator alliances accelerate enterprise sales cycles for hybrid deployment architectures. |
| Geographic Expansion | MIIT-compliant data centers in Shanghai and Shenzhen unlock Chinese retail conglomerate access. |
| Product Launch | Generative AI natural language interfaces differentiate supplier collaboration modules for premium pricing. |
Research Approach
SEC filings, hyperscaler capex disclosures, and EU regulatory documentation formed the secondary backbone, supplemented by primary interviews with category management directors, IT procurement officers at retail chains, platform engineers, and systems integration specialists. Bottom-up and top-down triangulation validated segment-level assumptions across deployment models and end-user verticals.
Bottom-up modeling anchored volume projections in point-of-sale data velocity requirements and cloud migration timelines, while top-down checks applied macro retail technology spending patterns across the projection horizon. Segmentation dimensions spanned deployment architecture, organization size, integration complexity, and regional regulatory adoption patterns. CAGRs were derived from replacement cycle compression rates and compliance-driven upgrade elasticity.
Inputs from vendor revenue disclosures and retail chain procurement databases were available through the study window; gaps in private mid-market retailer technology spending introduce uncertainty bands around SaaS adoption velocity assumptions. A small set of named triggers—including EU AI Act enforcement timing and MIIT data localization expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Application Virtualization Market
Software & Services
Customer Revenue Optimization Software Market
Software & Services
OCR Scanning Software Market
Software & Services
Global Bug Tracking Software Market
Software & Services
Automotive Digital Retailing Software Market
Software & Services
AI Powered Software Testing Tool Market
Software & Services
Pharmacy Billing Software Market
Software & Services
Configure Price and Quote (CPQ) Market
Software & Services
Global Electronic Design Automation Tools (EDA) Market
Software & Services
Global Knowledge Management Software Market
Software & Services
HR Management Software (Personnel and Organization) Market
Software & Services
Productivity Software Publishing Market
Software & Services
Enterprise Backup and Recovery Software Market
Software & Services
Global Time Tracking Software Market
Software & Services
Over the Air (OTA) Updates Market
Software & Services
Telecom Billing Software Market