
 3D CAD Software Market | 2026-2036
3D CAD Software Market Size, Share, and Industry Trends Forecast 2026-2036
3D CAD Software Market Intelligence
The EU Green Deal is hardening compliance requirements for digital product passports across European manufacturing supply chains. Siemens leverages its industrial software stack to anchor simulation-to-production workflows for automotive OEMs. Autodesk competes through cloud-native architectural design tools that sustain recurring revenue in building information modeling.
3D CAD software constitutes computer-aided design applications that generate, modify, and analyze three-dimensional digital models using parametric geometry kernels and NURBS surface mathematics, serving primarily to shorten product development cycles and reduce physical prototyping costs. Mechanical design platforms dominate license revenue among product type categories, while cloud-based deployment represents the fastest-expanding delivery mode as industrial machinery buyers shift capital expenditure to operational expenditure models. Simulation application modules command premium pricing due to integrated finite element analysis capabilities that eliminate separate solver purchases.
The EU AI Act and CE marking requirements under the EU Green Deal are reshaping how software vendors validate algorithmic design assistants for safety-critical aerospace applications. Germany's KBA enforces functional safety standards that filter which platforms qualify for automotive supplier networks. Stakeholders must monitor whether emerging EU software liability directives will shift compliance burdens from end users to platform developers.
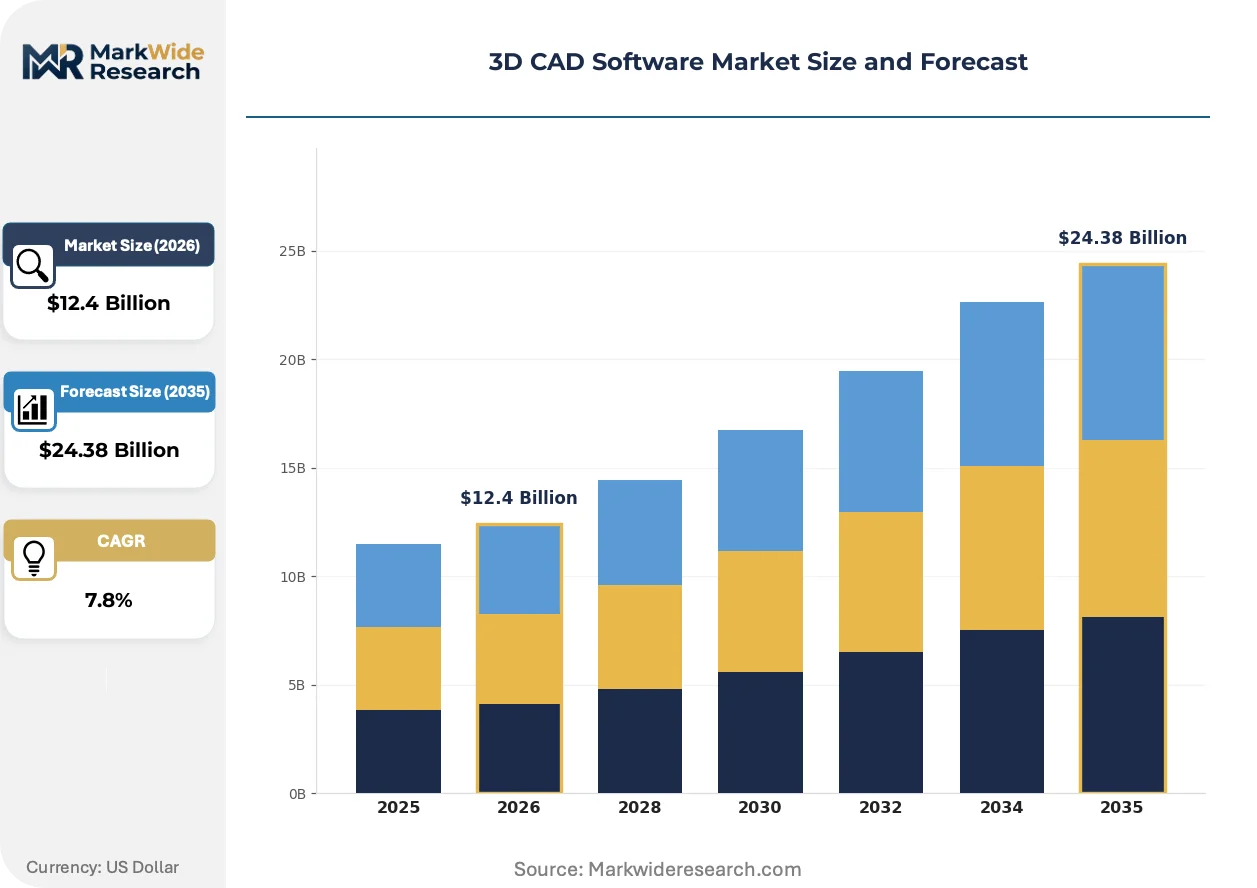
Market Dynamics
The EU Green Deal's digital product passport mandates are forcing aerospace and automotive manufacturers to upgrade legacy design platforms toward simulation-integrated compliance architectures, compressing vendor evaluation cycles and elevating algorithmic traceability requirements.
Growth Catalysts
- EU Green Deal digital product passport requirements:European manufacturers must embed lifecycle data into design files, accelerating replacement of standalone CAD licenses with integrated compliance suites.
- Aerospace simulation-ready design platforms:Boeing and Airbus suppliers now require finite element analysis kernels embedded within parametric modeling environments to eliminate solver handoffs.
- Germany's industrial automation corridor:Machine tool builders in Stuttgart and Munich are consolidating vendor relationships around platforms that bridge CAD data directly into production line controllers.
Market Restraints
- Specialized geometry kernel supply concentration:Parasolid and ACIS kernels control foundational solid modeling mathematics, creating single-source vulnerability for mid-tier platform developers.
- EU AI Act validation costs:Safety-critical aerospace applications now require documented algorithmic transparency for generative design assistants, extending compliance timelines by 18-24 months.
- Subscription pricing resistance among capital equipment buyers:Heavy machinery manufacturers prefer perpetual licenses that align with depreciation schedules, slowing cloud transition in industrial segments.
Strategic Opportunities
- India's PLI scheme for automotive tooling:Domestic component manufacturers qualify for production-linked incentives when adopting certified design-to-manufacture software stacks.
- Convergence of additive manufacturing and topology optimization:Lattice generation algorithms embedded within CAD kernels enable direct-to-print workflows for medical implant producers.
- Japan's METI digital twin infrastructure grants:Factory automation projects receive public co-funding when integrating real-time sensor feedback with parametric design environments.
Industry Challenges
- Generative design prompt engineering talent scarcity:Aerospace and automotive firms compete for specialists who can translate performance constraints into algorithmic objectives for AI-assisted topology tools.
- Legacy PLM-CAD integration complexity:Siemens Teamcenter and Dassault ENOVIA environments require custom middleware to synchronize cloud-native CAD data with on-premise revision control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D CAD Software Market |
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $24.38 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: General-Purpose, Mechanical Design, Electrical Design, Architectural Design End User: Automotive OEMs, Aerospace Manufacturers, Consumer Electronics, Industrial Machinery Deployment: On-Premise, Cloud-Based, Hybrid, Desktop Application: Prototyping, Simulation, Visualization, Mechanical Engineering |
| Companies Covered | Siemens, Hexagon, Autodesk, Bentley Systems, Ansys, Dassault Systèmes, SolidWorks, Bricsys, PTC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D CAD Software Market Strategic Shifts & Innovations
Real-time rendering engines and neural geometry compression are collapsing the boundary between design visualization and manufacturing simulation, enabling instantaneous design validation that previously required overnight solver batches.
Cloud-native GPU acceleration is expanding into mechanical design workflows previously restricted to workstation-class hardware. Mid-sized automotive suppliers in Michigan and Bavaria now access RTX-powered virtual workstations through browser interfaces, eliminating capital expenditure on dedicated visualization clusters. This shift is expanding into safety-critical applications as ISO 26262-certified cloud instances become available for functional safety documentation.
The EU AI Act's risk classification framework is mandating algorithmic audit trails for generative design tools deployed in aerospace applications. EASA certification timelines now require documented training data provenance and bias testing for machine learning-assisted topology optimization. German KBA enforcement of these standards is filtering which platforms qualify for automotive supplier networks, creating regulatory moats around established compliance architectures.
Buyer concentration among tier-one aerospace OEMs is compressing vendor switching cycles from five-year enterprise agreements to annual platform evaluations. Procurement teams at Airbus and Safran now pilot competing kernels on identical component datasets before renewal decisions. This pattern is most visible in Toulouse and Hamburg, where engineering directors negotiate direct platform access for preferred supplier tiers rather than delegating to IT procurement functions.
3D CAD Software Market Segmentation
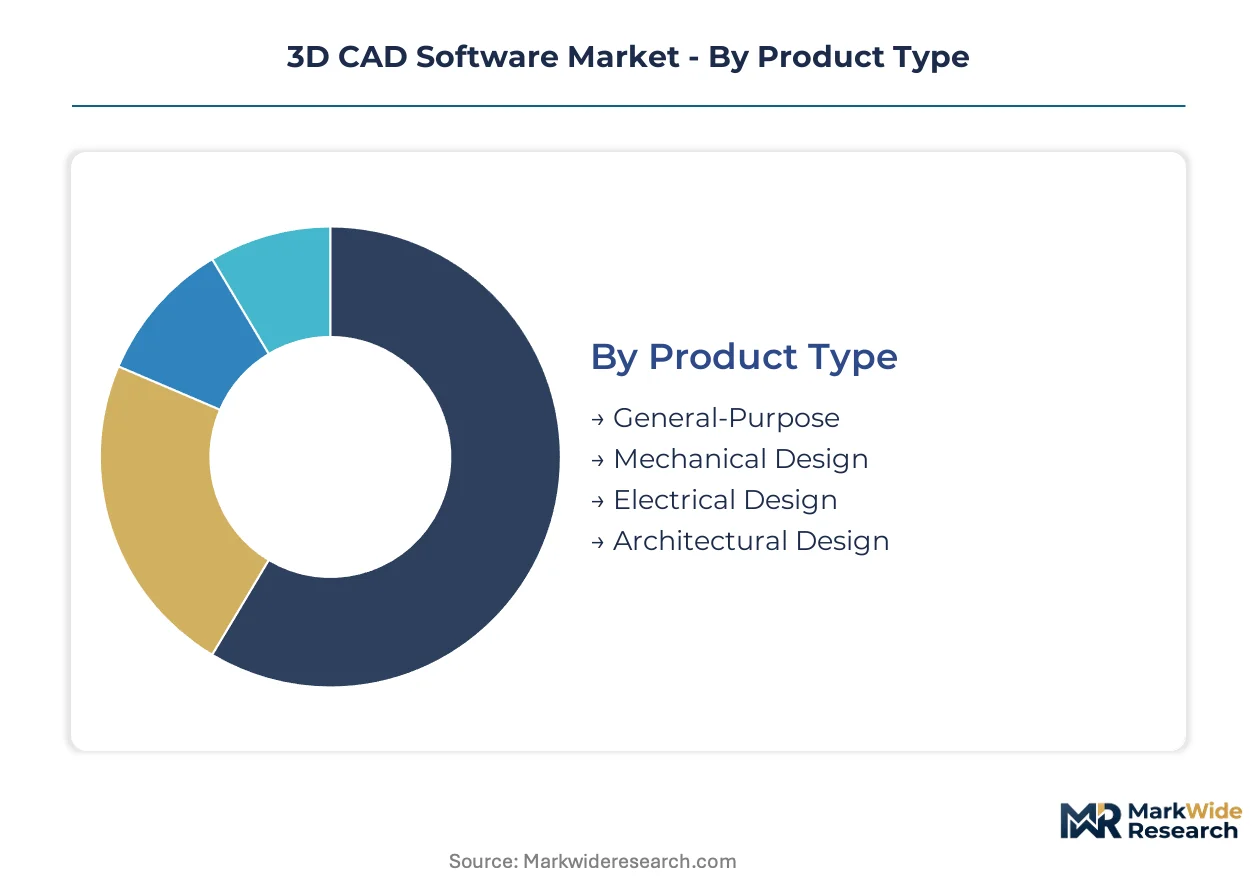
3D CAD software segmentation reflects how engineering organizations prioritize capital allocation across design workflows. License structures, deployment preferences, and application integration requirements vary sharply between aerospace certification environments and consumer electronics rapid-iteration cycles.
Product Type:
Platform replacement cycles concentrate where embedded simulation kernels eliminate separate solver procurement and compliance documentation overhead.
- Mechanical Design:Parametric solid modeling environments with NURBS surface mathematics and assembly constraint management dominate license revenue. Stuttgart machine tool builders and Munich automotive suppliers consolidate procurement around platforms that bridge directly into production line controllers, compressing vendor evaluation timelines.
- General-Purpose:Versatile geometry kernels serve cross-functional engineering teams requiring part modeling, assembly design, and basic rendering without specialized vertical modules. Mid-tier manufacturers in India's PLI-qualified automotive tooling sector favor these platforms for cost-controlled design-to-manufacture certification.
- Architectural Design:Building information modeling platforms with clash detection and quantity takeoff capabilities serve construction documentation workflows.
- Electrical Design:Schematic capture and PCB layout tools with 3D mechanical integration address electromechanical product development.
Mechanical Design sits at the top of the volume ranking, with General-Purpose climbing the fastest among cost-conscious supplier tiers.
End User:
Customer concentration patterns reveal how procurement authority has shifted from IT departments toward engineering directors with direct platform evaluation mandates.
- Aerospace Manufacturers:EASA certification requirements and EU AI Act algorithmic audit trails for generative design tools mandate documented training data provenance. Airbus and Boeing suppliers now require finite element analysis kernels embedded within parametric environments to eliminate solver handoffs, extending compliance timelines substantially.
- Automotive OEMs:German KBA functional safety standards filter platform qualification for supplier networks. Cloud-native GPU acceleration through ISO 26262-certified instances now supports safety-critical documentation workflows previously restricted to on-premise workstation clusters.
- Industrial Machinery:Heavy equipment manufacturers in capital-intensive segments show persistent preference for perpetual licenses aligning with depreciation schedules.
- Consumer Electronics:Rapid product cycles drive demand for subscription-based platforms with frequent feature updates and collaborative cloud workspaces.
Automotive OEMs anchor procurement volume, while Aerospace Manufacturers impose the steepest compliance-driven upgrade trajectory.
Deployment:
Delivery mode selection tracks how engineering organizations balance capital expenditure constraints against data sovereignty requirements and latency-sensitive visualization workloads.
- Cloud-Based:Browser-accessible virtual workstations with RTX-powered GPU acceleration eliminate dedicated visualization cluster procurement. Michigan and Bavaria mid-sized suppliers access mechanical design workflows previously restricted to workstation-class hardware, though safety-critical applications await broader ISO 26262-certified instance availability.
- Hybrid:Split architectures maintain sensitive intellectual property on-premise while leveraging cloud rendering and collaboration for non-critical workflows. Japan's METI digital twin infrastructure grants favor these configurations when integrating real-time sensor feedback with parametric design environments.
- On-Premise:Perpetual license models with local data retention persist in defense-adjacent and regulated manufacturing segments.
- Desktop:Traditional workstation-installed software maintains presence where internet connectivity remains unreliable or security policies prohibit cloud data transmission.
Cloud-Based deployment is gaining share fastest among mid-market suppliers, with Hybrid configurations dominating aerospace and defense-adjacent installations.
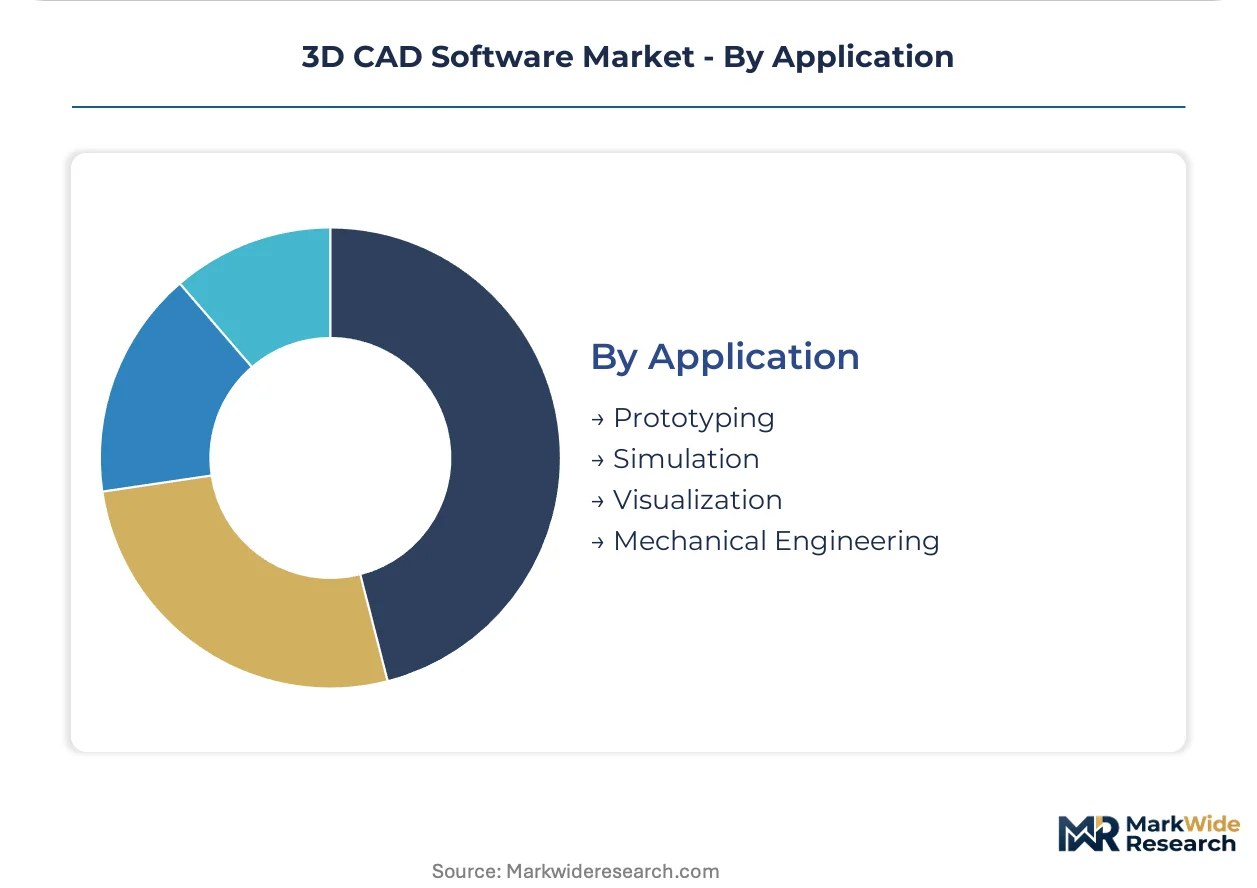
Application:
Module integration depth determines platform stickiness as engineering organizations seek to collapse handoffs between design visualization and manufacturing simulation.
- Simulation:Integrated finite element analysis and computational fluid dynamics kernels command premium pricing by eliminating separate solver purchases. Real-time rendering engines and neural geometry compression enable instantaneous design validation that previously required overnight batch processing.
- Prototyping:Direct-to-print workflows with lattice generation algorithms support additive manufacturing integration for medical implant producers and aerospace lightweighting applications.
- Mechanical Engineering:Core parametric modeling and assembly design functions constitute the foundational license tier across all end-user segments.
- Visualization:Real-time rendering and virtual reality presentation capabilities serve design review and stakeholder communication workflows.
Simulation modules command the highest pricing tier, with Prototyping applications expanding most quickly through additive manufacturing convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software engineering talent clusters in Stuttgart, Bangalore, and Boston anchor regional platform development. Aerospace certification specialists concentrate around Toulouse and Hamburg. Industrial automation corridors in Bavaria and Michigan drive procurement authority shifts toward engineering directors.
United States
Michigan automotive suppliers and Seattle-area aerospace clusters propel demand for ISO 26262-certified cloud instances. FAA certification requirements for algorithmic design tools extend compliance timelines for generative AI applications. Detroit engineering directors now negotiate direct platform access rather than delegating to IT procurement functions.
Germany
Stuttgart machine tool builders and Munich automotive OEMs consolidate vendor relationships around production-line-integrated platforms. KBA functional safety standards filter which CAD platforms qualify for supplier networks. Bavaria's industrial automation corridor compresses vendor evaluation cycles as engineering teams demand bridge-to-controller capabilities.
France
Toulouse aerospace engineering pools and Paris-region software development centers anchor EASA certification workflows. EU AI Act risk classification mandates algorithmic audit trails for generative design tools deployed at Airbus and Safran. Hamburg procurement teams pilot competing geometry kernels on identical component datasets before renewal decisions.
India
Pune and Chennai automotive component manufacturers leverage PLI scheme incentives for certified design-to-manufacture software stacks. BIS standards alignment accelerates domestic tooling sector upgrades. Karnataka's engineering services corridor supplies prompt engineering talent for AI-assisted topology optimization tools.
Japan
Nagoya automotive suppliers and Tokyo digital twin infrastructure projects access METI grants for real-time sensor integration with parametric environments. JIS standards govern geometry data exchange in multi-tier supplier networks. Osaka medical device clusters adopt lattice generation algorithms for direct-to-print implant workflows.
3D CAD Software Market Key Industry Players
Capital-heavy producers compete with asset-light designers as the market structures around three tiers. Kernel developers with captive geometry mathematics anchor the foundational layer. Platform integrators bundle compliance modules and simulation solvers for aerospace and automotive verticals. Cloud-native challengers displace workstation-installed software through browser-accessible GPU acceleration. Dominant competitive moves include strategic partnerships bridging CAD-to-production workflows and portfolio diversification into additive manufacturing preparation tools.
Within the integrated industrial software tier, Siemens and Dassault Systèmes exemplify platform consolidation strategies that embed simulation kernels within parametric environments. Autodesk occupies a position representing cloud-native architectural and mechanical design tools that sustain recurring revenue through subscription models. These three anchors reflect divergent paths: European industrial conglomerates leveraging manufacturing equipment relationships, versus American software specialists betting on browser-based delivery and building information modeling dominance.
| Leading Market Players |
|---|
| Siemens |
| Hexagon |
| Autodesk |
| Bentley Systems |
| Ansys |
| Dassault Systèmes |
| SolidWorks |
| Bricsys |
| PTC |
| Others |
Cost & Logistics Intelligence
Cloud-native GPU acceleration and browser-accessible virtual workstations are compressing cost economics for mid-sized suppliers while concentrating procurement authority among kernel developers who control foundational geometry mathematics. This technology transition simultaneously erodes perpetual license premiums and elevates subscription-tier pricing power for platforms embedding simulation-ready compliance modules.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and embedded simulation depth. Premium tiers command substantial markups for EASA-compliant algorithmic audit trails and ISO 26262-certified cloud instances. Cost compression in standard tiers intensifies because mid-tier vendors license Parasolid and ACIS kernels from single-source suppliers. Capital equipment buyers in industrial machinery show greatest price sensitivity, preferring perpetual licenses aligned with depreciation schedules.
Supply Chain Analysis
Returns and refurbishment flows for legacy workstation hardware are minimal in this software-dominant market, though license reallocation and subscription downgrades create revenue leakage patterns. Kernel development concentrates in Germany, France, and the United States, with geometry mathematics sourcing from captive R&D or licensed IP. Supply chain risk centers on single-source vulnerability for Parasolid and ACIS foundational kernels. Distribution runs through direct enterprise sales teams and authorized reseller networks serving aerospace and automotive verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's digital product passport mandates function as a regulatory compounder, forcing compliance-oriented software upgrades across European manufacturing supply chains and accelerating platform replacement cycles.
For Market Incumbents: Deploy embedded simulation kernels to deepen platform stickiness. Siemens and Dassault Systèmes should accelerate finite element analysis integration to eliminate separate solver procurement. Kernel licensing revenue from mid-tier vendors provides defensive cash flow against cloud-native challengers.
For New Entrants and Emerging Players: Mid-sized automotive suppliers in India's PLI-qualified tooling sector represent an underserved buyer archetype seeking cost-controlled design-to-manufacture certification. Browser-accessible GPU acceleration with ISO 26262-compliant instances opens safety-critical workflows previously restricted to incumbents.
For Investors and Strategic Acquirers: Valuations sit cheapest among geometry kernel specialists with captive mathematics and established aerospace certification relationships. Long-term viability hinges on regulatory moats around EU AI Act compliance architectures. Monitor EASA certification timeline compression as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding finite element analysis kernels within parametric environments eliminates solver handoffs for Airbus suppliers. |
| Strategic Partnership | Bridge-to-controller capabilities with Stuttgart machine tool builders compress vendor evaluation cycles. |
| Acquisition of Specialist Firm | Lattice generation algorithm providers enable direct-to-print workflows for Osaka medical implant clusters. |
| Geographic Expansion | METI digital twin infrastructure grants in Japan favor hybrid cloud configurations with real-time sensor integration. |
| Product Launch | ISO 26262-certified cloud instances unlock safety-critical documentation workflows for Michigan automotive suppliers. |
Research Approach
Multiple input streams — primary interviews with platform engineering directors, IT procurement officers, and aerospace certification specialists, alongside secondary validation through SEC filings, hyperscaler capex disclosures, and EASA regulatory databases — were reconciled using bottom-up license volume modeling and top-down market sizing triangulation.
Segmentation dimensions across the analysis window encompassed deployment model, organization size, vertical application, and integration complexity, with CAGRs derived from regression analysis of historical replacement cycles and forward projection of EU regulatory compliance deadlines. Cloud transition velocity and additive manufacturing convergence served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; cloud-based deployment and consumer electronics end-use carry tighter precision than on-premise installations in defense-adjacent segments. Forecasts reflect assumptions around regulatory timeline adherence and kernel licensing continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Tenant Billing System Market
Software & Services
Global App Design Software Market
Software & Services
Global ERP Software Market
Software & Services
Global UIUX Software Market
Software & Services
Equipment Management Software Market
Software & Services
Embedded Hypervisor Market
Software & Services
Global Application Development Software Market
Software & Services
Global Gym Software Market
Software & Services
Supply Chain Visibility (SCV) Software Market
Software & Services
Global User Research and User Testing Software Market
Software & Services
SRM Software Market
Software & Services
Enterprise Mobility Software Market
Software & Services
MEP Software Market
Software & Services
Team Collaboration Tools Market
Software & Services
Automation Test Software Market
Software & Services
Programmable Automation Controller (PAC) Programming Software Market