
 Enterprise Backup and Recovery Software Market | 2026-2036
Enterprise Backup and Recovery Software Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Backup and Recovery Software Market Foresight
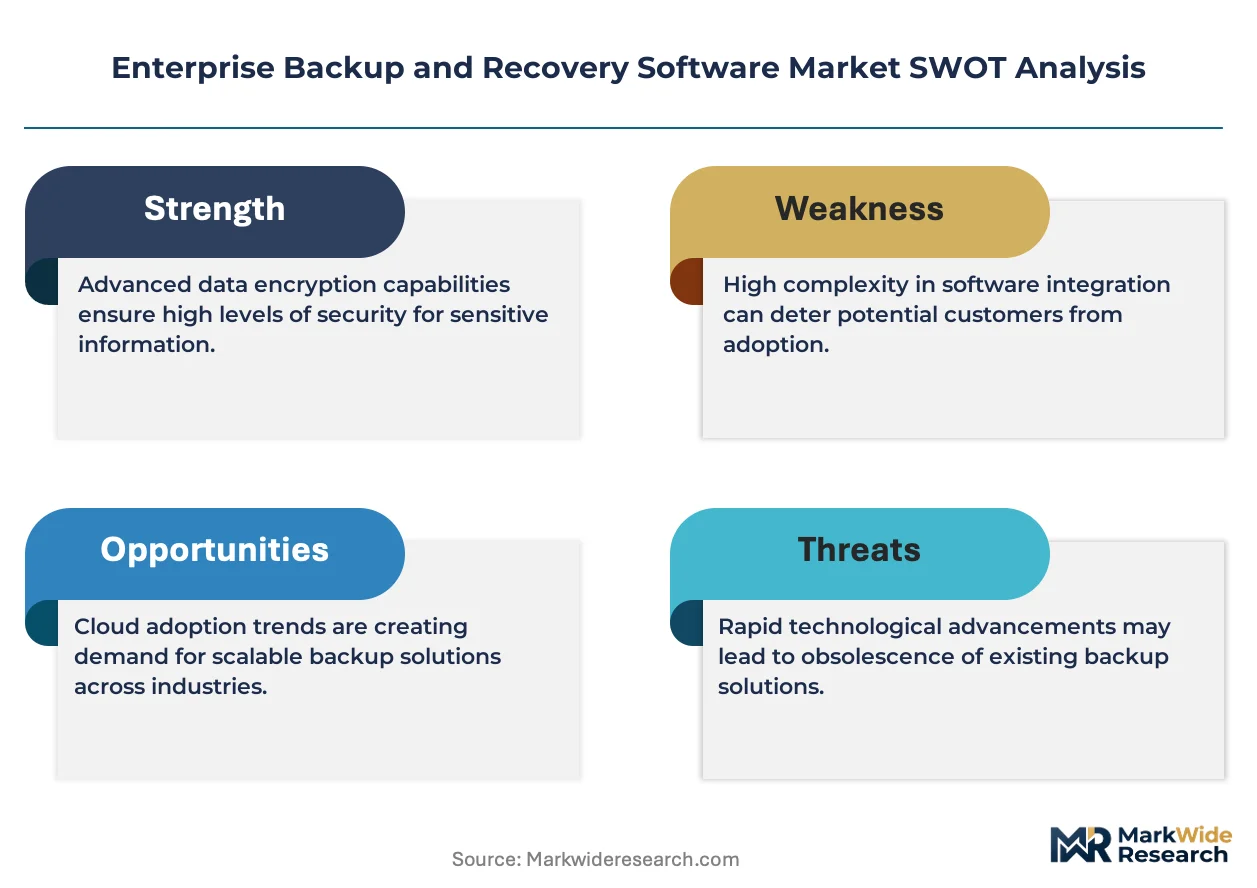
Object storage is hardening as the default substrate for enterprise backup repositories, displacing traditional tape and deduplicated disk arrays at the core of long-term retention economics. Dell anchors its competitive posture through captive supply of integrated hardware-software appliances that compress total cost of ownership for on-premises workloads. Veeam differentiates through deep ecosystem integration with VMware and Microsoft platforms, sustaining renewal rates among virtualized infrastructure customers. Rubrik positions around immutable file systems and policy-driven automation, navigating the shift from backup-centric to cyber-resilience-centric buying criteria.
Enterprise backup and recovery software encompasses applications, platforms, and services engineered to create redundant copies of organizational data, validate restoration integrity through automated testing, and orchestrate failover to secondary infrastructure with recovery time objectives typically measured in minutes to hours. The primary commercial purpose centers on operational continuity, regulatory defensibility, and forensic recovery following data corruption, deletion, or encryption events. Cloud backup deployment leads absolute spending as CIOs retire tape libraries and colocation contracts, though hybrid architectures capture the fastest expansion by reconciling latency-sensitive primary restore requirements with elastic cold-tier economics. Disaster recovery services command premium pricing relative to basic archiving due to the engineering intensity of runbook automation and cross-region replication orchestration.
FDA 21 CFR Part 11 imposes audit trail and electronic record integrity requirements on pharmaceutical and medical device manufacturers, directly shaping backup retention policies and immutable storage specifications in regulated verticals. The SEC's cybersecurity disclosure rules mandate public companies document incident response and recovery capabilities, elevating board-level scrutiny of backup architecture resilience. NIST SP 800-53 controls and FedRAMP authorization frameworks further constrain vendor selection for federal contractors. Stakeholders must monitor the divergence between EU operational resilience directives and US sector-specific mandates, as compliance fragmentation threatens to bifurcate product roadmaps and channel investments.
Market Dynamics
Immutable backup architectures are hardening as the non-negotiable baseline for enterprise procurement, with ransomware recovery capabilities now outweighing traditional cost-per-gigabyte metrics in vendor selection criteria. This shift compresses legacy tape-dependent business models while elevating cyber-resilience engineering to core product differentiation.
Growth Catalysts
- FedRAMP Authorization:Federal contractors face mandatory cloud backup vendor certification, steering procurement toward domestic providers with established authority-to-operate credentials.
- Healthcare Ransomware Exposure:Hospital systems and pharmaceutical manufacturers accelerate immutable storage deployment to satisfy HIPAA contingency planning mandates and FDA 21 CFR Part 11 audit trail requirements.
- Object Storage Economics:S3-compatible cloud repositories undercut tape library total cost of ownership for seven-year retention horizons, eliminating mechanical media handling and offsite vaulting logistics.
Market Restraints
- Skilled Cyber-Resilience Engineering:Shortage of architects capable of designing air-gapped, write-once-read-many architectures limits enterprise implementation velocity and extends professional services dependency.
- Cross-Border Data Sovereignty:Conflicting national localization mandates fragment backup infrastructure design, forcing redundant in-country deployments that erode cloud elasticity economics.
- Legacy Tape Infrastructure Sunk Costs:Decades of magnetic media investment and operationalized vaulting contracts create organizational inertia against all-flash and object storage migration.
Strategic Opportunities
- EU NIS2 Directive Compliance:Critical infrastructure operators across energy, transport, and digital services face hardened backup and recovery obligations, opening managed service provider penetration.
- AI-Driven Recovery Orchestration:Machine learning models predicting failure patterns and automating runbook execution converge with immutable snapshots to compress mean-time-to-recovery.
- Edge-to-Cloud Continuity:Manufacturing and retail distributed footprints create demand for lightweight backup agents synchronizing to centralized repositories without WAN bandwidth saturation.
Industry Challenges
- FedRAMP ATO Timeline Compression:Authorization pathways stretching 12-18 months delay federal market entry for emerging vendors with superior technical architectures.
- Multi-Cloud Recovery Consistency:Enterprises operating across AWS, Azure, and Google Cloud struggle with API heterogeneity and inconsistent snapshot immutability guarantees.
- Insider Threat Vector Hardening:Administrative credential compromise can override logical immutability controls, requiring hardware-rooted trust mechanisms that complicate software-only deployment models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Backup and Recovery Software Market |
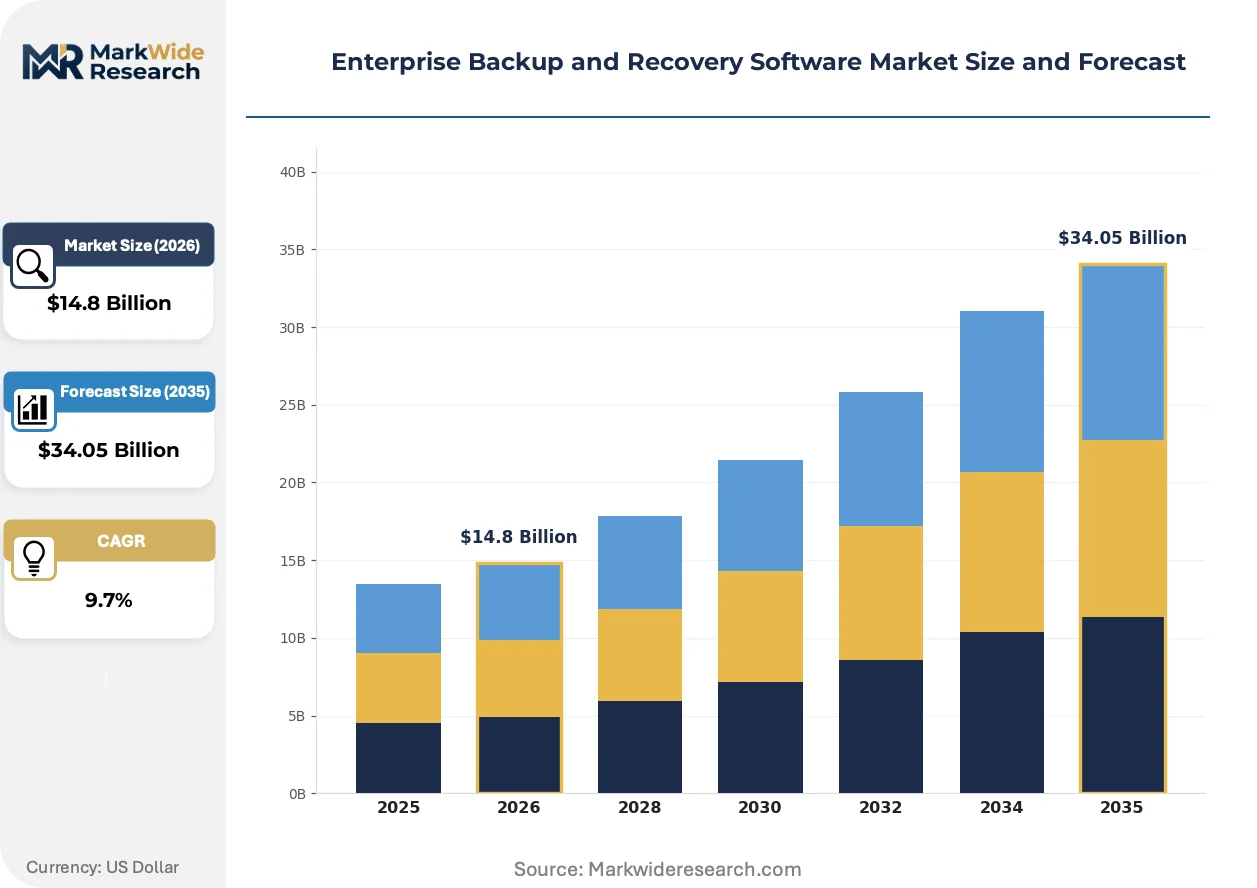
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $34.05 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud Backup, Local Backup, Hybrid Backup, Offsite Backup Deployment: On-Premises, Cloud-Based, Hybrid, Managed Service End User: SMEs, Large Enterprises, Government Agencies, Educational Institutions Service Type: Disaster Recovery, Data Archiving, Continuous Data Protection, Remote Backup |
| Companies Covered | Cohesity, AWS, Veeam, Arcserve, Rubrik, Commvault, Dell, Clumio, Acronis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Backup and Recovery Software Market Shifts & Advancements
Backup infrastructure is rewriting its value proposition from data protection to operational resilience, with automated recovery testing and cyber-recovery runbooks displacing passive archival as the primary buyer evaluation criteria. This redefinition elevates software intelligence over storage hardware in procurement decisions.
Immutable file systems with hardware-rooted cryptographic verification are rewriting long-term retention economics for regulated industries. Pharmaceutical manufacturers under FDA 21 CFR Part 11 and financial services firms facing SEC cybersecurity disclosure rules deploy these architectures to satisfy audit defensibility requirements. The technology compresses legal hold and e-discovery preparation timelines from weeks to hours.
The EU NIS2 Directive mandates operational resilience testing and incident recovery capabilities for critical infrastructure operators across member states. Energy utilities and healthcare providers must document backup restoration procedures and exercise them annually, creating compliance-driven demand for managed disaster recovery services. German and French operators lead implementation due to national regulator enforcement precedents.
Subscription consumption models for backup-as-a-service are displacing perpetual license and capital-intensive appliance procurement in mid-market accounts. Managed service providers in the United States bundle immutable cloud repositories with ransomware response retainers, capturing annual recurring revenue streams that hardware vendors struggle to replicate. This shift concentrates buyer relationships with channel partners rather than primary vendors.
Enterprise Backup and Recovery Software Market Segmentation
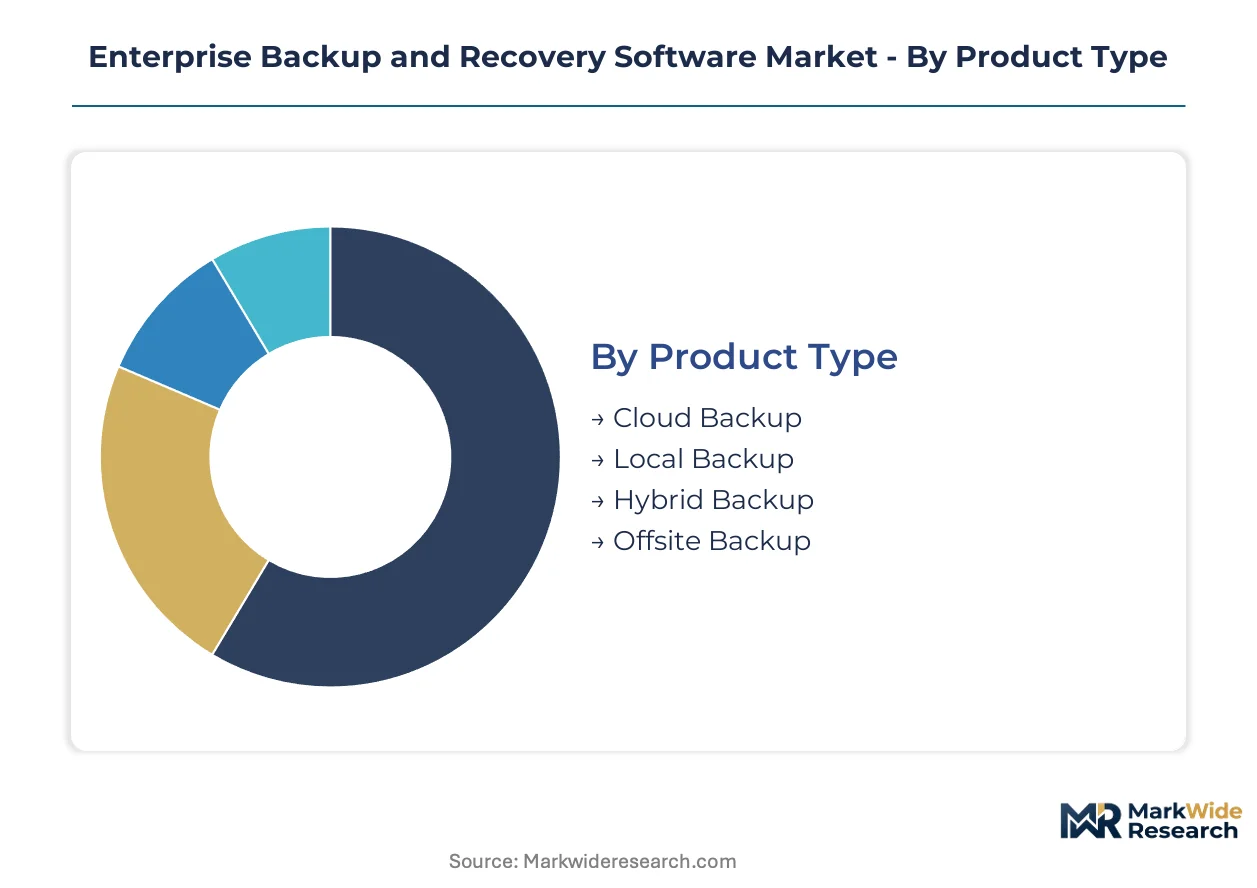
Enterprise backup procurement diverges sharply by infrastructure maturity, regulatory exposure, and operational scale. Buyers select architectures based on recovery time objectives, data sovereignty constraints, and cyber-resilience postures rather than storage economics alone.
Product Type:
Standardization dominates cloud and hybrid offerings, while local and offsite configurations retain customization for air-gapped compliance requirements.
- Cloud Backup:S3-compatible object repositories with immutable versioning and cross-region replication. Demand concentrates among US federal contractors navigating FedRAMP authorization mandates and HIPAA-covered entities requiring geographic redundancy.
- Hybrid Backup:Tiered architectures synchronizing on-premises flash tiers with cloud cold storage. Financial services firms in Frankfurt and London deploy these configurations to satisfy EU NIS2 operational resilience testing requirements while maintaining sub-hour recovery capabilities.
- Local Backup:All-flash or deduplicated disk arrays for latency-sensitive primary restoration.
- Offsite Backup:Vaulted tape and secondary site replication for long-term retention compliance.
Leading the category by volume: Cloud Backup. Expanding most quickly: Hybrid Backup.
Deployment:
Cost tier stratification separates capital-intensive on-premises builds from operational expenditure models favored by mid-market accounts.
- Cloud-Based:Consumption-priced object storage with API-driven policy automation. US healthcare providers accelerating immutable storage deployment to counter ransomware exposure represent the fastest-expanding customer cohort.
- Managed Service:Third-party operated backup-as-a-service with bundled ransomware response retainers. German energy utilities under EU NIS2 enforcement precedents drive compliance-driven adoption across critical infrastructure verticals.
- On-Premises:Customer-operated hardware-software appliances with captive support contracts.
- Hybrid:Split control planes across owned infrastructure and managed cloud tiers.
Dominant by revenue scale: Cloud-Based. Steepest expansion trajectory: Managed Service.
End User:
Application criticality separates always-on enterprise requirements from scheduled-protection patterns in smaller organizations.
- Large Enterprises:Multi-petabyte environments with sub-15-minute recovery point objectives and automated cyber-recovery runbooks. Pharmaceutical manufacturers under FDA 21 CFR Part 11 audit trail mandates anchor demand for immutable file systems with hardware-rooted verification.
- Government Agencies:Classified and unclassified workloads with FedRAMP High authorization requirements. US federal procurement steers toward domestic cloud backup vendors with established authority-to-operate credentials.
- SMEs:Subscription-based backup-as-a-service with standardized retention policies.
- Educational Institutions:Semester-aligned backup windows with research data protection priorities.
Highest absolute spending: Large Enterprises. Gaining share fastest: Government Agencies.
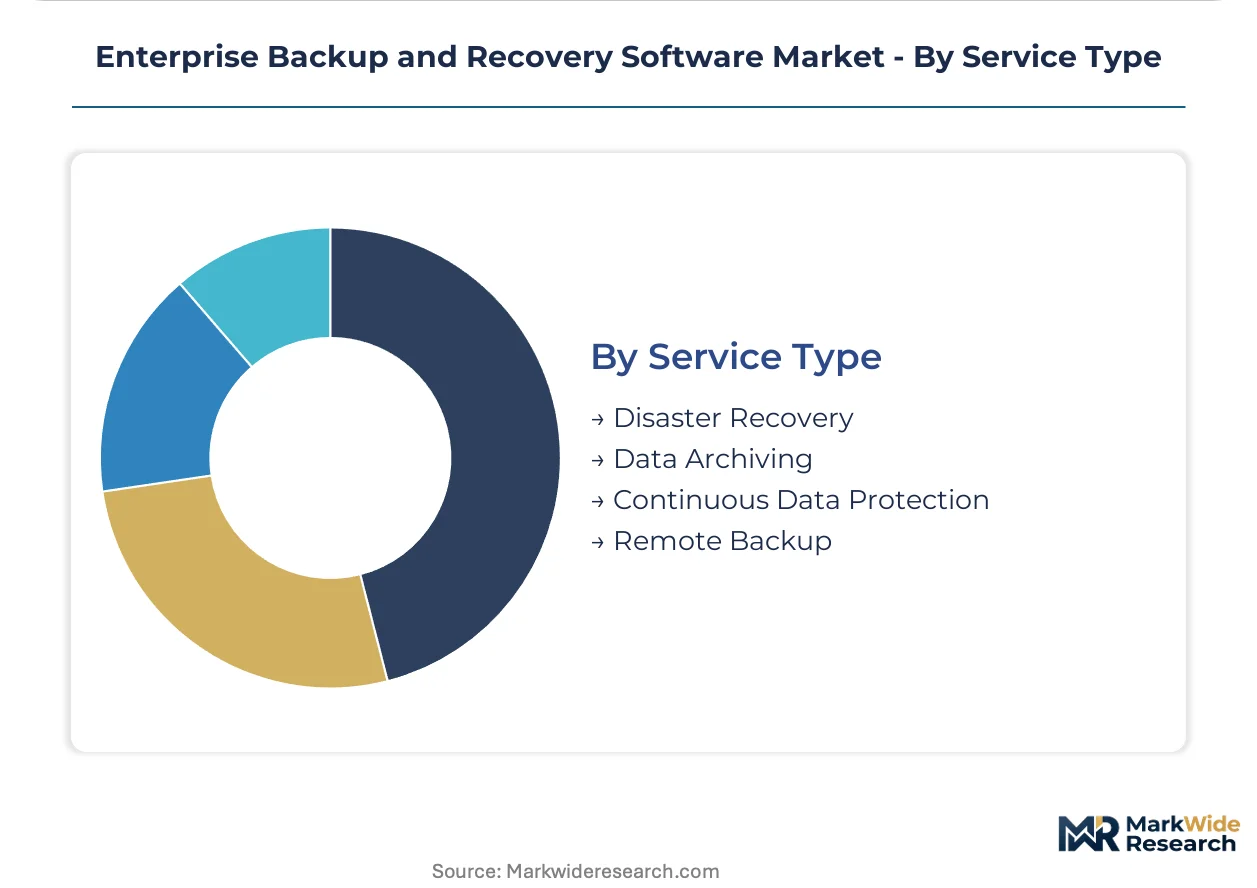
Service Type:
Margin structure differentiates engineering-intensive disaster recovery orchestration from passive archival storage.
- Disaster Recovery:Automated failover with cross-region replication and runbook execution. French healthcare providers conducting annual EU NIS2-mandated restoration exercises drive managed service penetration for critical infrastructure operators.
- Continuous Data Protection:Journal-based replication capturing every write operation for near-zero recovery point objectives. High-frequency trading firms and electronic health record systems require these capabilities to satisfy SEC cybersecurity disclosure rules and HIPAA contingency planning mandates.
- Data Archiving:Immutable long-term retention for legal hold and e-discovery preparation.
- Remote Backup:Edge-synchronized agents for distributed retail and manufacturing footprints.
Premium pricing concentration: Disaster Recovery. Climbing the fastest: Continuous Data Protection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise backup procurement concentrates in jurisdictions with stringent data sovereignty mandates and critical infrastructure protection frameworks. Regulatory divergence between FedRAMP-authorized US federal contractors and EU NIS2-bound operators fragments vendor selection criteria across major economies.
United States
Federal contractors drive immutable cloud repository demand through FedRAMP High authorization requirements. The SEC's cybersecurity disclosure rules elevate board-level scrutiny of recovery capabilities for public companies. Healthcare clusters in Boston and the Research Triangle accelerate air-gapped storage deployment to satisfy HIPAA contingency mandates.
Germany
Energy utilities and automotive manufacturers anchor EU NIS2 compliance-driven procurement for operational resilience testing. The national IT security act enforces critical infrastructure backup obligations with annual restoration exercises. Industrial operators in Bavaria and North Rhine-Westphalia deploy hybrid architectures reconciling sub-hour recovery with cold-tier economics.
United Kingdom
Financial services firms in the City of London navigate post-Brexit divergence from EU operational resilience frameworks. The Financial Conduct Authority mandates recovery time objective documentation for systemic institutions. NHS trusts across England expand managed backup-as-a-service to counter ransomware exposure in patient record systems.
Japan
Manufacturing conglomerates and financial institutions drive demand for continuous data protection with near-zero recovery point objectives. METI guidelines on critical infrastructure protection shape vendor selection for energy and telecommunications operators. Tokyo-Osaka corridor enterprises prioritize hardware-rooted immutability for electronic record integrity.
India
IT services exporters and pharmaceutical manufacturers expand hybrid backup footprints to satisfy client audit requirements in regulated verticals. The Digital Personal Data Protection Act introduces data localization considerations for cross-border repository design. Bengaluru and Hyderabad technology clusters anchor managed service provider growth for mid-market accounts.
Enterprise Backup and Recovery Software Market Competitive Landscape
Branded specialists and infrastructure-integrated OEMs split share differently across deployment segments, with cloud-native entrants capturing mid-market subscription revenue while appliance vendors defend on-premises workloads. Market structure tilts toward consolidation at the platform layer and fragmentation among point-solution specialists. Three archetypes dominate: integrated hardware-software appliance providers, cloud-native immutable storage platforms, and managed service aggregators bundling response capabilities. Competitive intensity centers on FedRAMP authorization velocity and cyber-resilience engineering differentiation rather than storage economics alone.
Within the integrated appliance tier, Dell anchors positions through captive supply of converged infrastructure. Veeam and Rubrik exemplify divergent strategic postures among software-centric platforms—Veeam through deep ecosystem integration with virtualization leaders, Rubrik through policy-driven automation and immutable file system architecture. These three occupy positions spanning traditional data protection evolution and cyber-resilience repositioning.
| Leading Market Players |
|---|
| Cohesity |
| AWS |
| Veeam |
| Arcserve |
| Rubrik |
| Commvault |
| Dell |
| Clumio |
| Acronis |
| Others |
Supply & Pricing Matrix
FedRAMP authorization requirements for federal contractors gate qualified supply to domestic cloud backup vendors with established authority-to-operate credentials, compressing vendor pools and sustaining premium-tier pricing for compliant providers. This regulatory filter concentrates procurement leverage among authorized vendors while elevating cyber-resilience engineering as a price-defensible differentiator.
Pricing Analysis
Volume concentrates in subscription SaaS tiers while margins accrue to managed service bundles with ransomware response retainers. Three-tier pricing structure across premium, standard, and economy levels separates FedRAMP-authorized providers from uncertified competitors and self-managed on-premises deployments. Cost compression in mid-market SaaS tiers intensifies because hyperscaler storage commoditization erodes per-gigabyte rates. Government agencies exhibit the lowest price sensitivity due to mandatory compliance requirements, while educational institutions anchor the economy tier with semester-aligned procurement cycles.
Supply Chain Analysis
Dual-sourcing requirements for critical infrastructure operators mandate multi-supplier qualification across primary and disaster recovery sites, fragmenting vendor concentration. Supply concentrates in the United States for FedRAMP-authorized cloud repositories, Germany for EU NIS2-compliant hybrid architectures, and Japan for hardware-rooted immutability components. Component dependencies include S3-compatible object storage, cryptographic verification modules, and air-gapped tape libraries. Single-source vulnerability runs through hyperscaler API heterogeneity. Distribution runs through managed service providers bundling response capabilities rather than direct vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise backup infrastructure is transitioning from passive archival to active cyber-resilience platforms, with immutable object storage displacing tape-dependent legacy architectures. This technology transition redefines procurement criteria toward automated recovery orchestration and policy-driven immutability.
For Market Incumbents: Deepen vertical integration into hardware-rooted cryptographic verification to defend against cloud-native entrants with superior automation layers. Prioritize FedRAMP authorization velocity as a channel control lever, compressing 12-18 month timelines to capture federal contractor procurement windows. Invest in AI-driven recovery runbook development to offset margin pressure from storage commoditization.
For New Entrants and Emerging Players: Enter via EU NIS2 compliance services for German and French critical infrastructure operators, where enforcement precedents create immediate managed service demand. Target mid-market healthcare providers in the US Research Triangle with immutable backup-as-a-service bundles, leveraging ransomware response retainers to establish annual recurring revenue before expanding to enterprise accounts.
For Investors and Strategic Acquirers: FedRAMP authorization timeline compression is the leading indicator that technical differentiation is converting to procurement advantage faster than sales cycles can capture. Position acquisition targets around cloud-native platforms with existing authority-to-operate credentials and established channel partner networks. Deviation in hyperscaler snapshot immutability guarantees would shift the outlook materially.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep VMware and Microsoft ecosystem ties sustain renewal rates among virtualized infrastructure customers. |
| Geographic Expansion | EU NIS2 compliance capabilities unlock German energy utility and French healthcare procurement channels. |
| Acquisition of Specialist Firm | AI-driven recovery orchestration targets compress mean-time-to-recovery for high-frequency trading firms. |
| Strategic Partnership | Managed service provider alliances concentrate buyer relationships and capture ransomware response retainers. |
| Product Launch | Hardware-rooted immutable file systems satisfy FDA 21 CFR Part 11 audit trail mandates for pharmaceutical manufacturers. |
Research Methodology
SEC filings, hyperscaler capex disclosures, and FedRAMP authorization databases formed the secondary backbone for vendor positioning and procurement trend validation. Primary interviews with CTOs, IT procurement officers at healthcare systems, channel partners, and integration specialists combined with secondary sources through bottom-up and top-down triangulation. This approach anchored segmentation across deployment model, organization size, vertical regulatory exposure, and regional adoption pattern.
Historical trendline analysis tracked immutable storage adoption velocity and ransomware recovery capability prioritization across the analysis window. The modeling framework segmented by product type, deployment mode, end-user scale, and service tier complexity, with CAGRs derived from regression against infrastructure refresh cycles and compliance mandate enforcement timelines. Forecast inputs included FedRAMP authorization pipeline data and EU NIS2 implementation schedules for critical infrastructure verticals.
Revisions become necessary when hyperscaler immutability guarantee changes, cross-border data sovereignty mandate divergence, or insider threat vector breakthroughs materialize. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and cloud storage cost trajectories. Deviation in FedRAMP authorization velocity or EU NIS2 penalty structures would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Quantum Computing Software Market
Software & Services
Global Content Management Systems (CMS) Market
Software & Services
Global Online Community Management Software Market
Software & Services
Deck Design Software Market
Software & Services
Nonconformance Management Software Market
Software & Services
Global Customer Experience Software Market
Software & Services
Global Employee Engagement Software Market
Software & Services
Client Virtualization Software Market
Software & Services
Global Board Management Software Market
Software & Services
Global Web Scraper Software Market
Software & Services
Contract Abstraction Software Market
Software & Services
Embedded Operating Systems Market
Software & Services
Latin America Human Resource (HR) Technology Market
Software & Services
Global Disk Imaging Software Market
Software & Services
AI Powered Software Testing Tool Market
Software & Services
Content Curation Software Market