
 Sofrito Market | 2026-2036
Sofrito Market Size, Share, and Industry Trends Forecast 2026-2036
Sofrito Market Analytics
Consolidation among restaurant chains and contract food service operators is realigning procurement volumes toward fewer, larger buyers with specification power. Goya Foods leverages its vertically integrated supply chain from Latin American agricultural zones to dominate shelf-stable sofrito distribution in North American retail. Herdez Del Fuerte anchors its position through deep regional manufacturing presence in Mexico, while McCormick & Company competes by extending its spice expertise into blended sofrito seasoning formats for industrial kitchens.
Sofrito denotes a blended aromatic base of tomatoes, peppers, onions, garlic, and cilantro or culantro, traditionally prepared fresh but now manufactured through thermal processing, aseptic filling, or flash-freezing to achieve shelf stability and flavor consistency. The product serves as a foundational flavor component across Latin American, Caribbean, and Mediterranean cuisines, reducing kitchen labor while delivering standardized taste profiles. Fresh sofrito retains premium positioning in specialty stores and food service channels where authenticity commands price separation, while canned variants occupy mainstream retail with longer shelf life and lower per-unit cost. The sauces sub-category within product type captures expanding demand from home cooks seeking pourable convenience formats.
FDA nutrition labeling requirements and EFSA sodium reduction frameworks pressure manufacturers to reformulate traditional recipes without compromising sensory identity. The EU Green Deal agricultural standards and US FDA Food Safety Modernization Act traceability rules add compliance costs that favor scaled producers with quality management infrastructure. Stakeholders must monitor evolving clean-label certification criteria and regional procurement consolidation patterns to anticipate which production formats and packaging configurations will capture disproportionate margin pools.
Market Dynamics
Restaurant chain consolidation and clean-label regulatory mandates are compressing supplier margins while rewarding scaled manufacturers with reformulation capabilities and traceable agricultural sourcing.
Growth Catalysts
- US FDA Food Safety Modernization Act:Traceability mandates favor large producers with digitized supply chain infrastructure, accelerating procurement consolidation toward qualified suppliers.
- Flash-freezing technology:Industrial kitchens adopt cryogenic freezing to preserve volatile aromatic compounds, extending sofrito shelf life without thermal degradation of flavor.
- Puerto Rico:Per-capita sofrito consumption remains the highest globally, with food service operators standardizing procurement specifications across island-wide chain locations.
Market Restraints
- Tomato input volatility:Climate-driven harvest variability in California and Andalusia creates raw material cost instability for sauce-base formulations.
- Fresh segment supply concentration:Small-batch producers in Santo Domingo and San Juan control premium fresh sofrito distribution, limiting scalable sourcing options.
- EFSA sodium reduction frameworks:Mandatory reformulation timelines compress product development cycles while risking sensory profile drift from traditional recipes.
Strategic Opportunities
- Eastern Spain:Underpenetrated industrial food service channels in Valencia and Barcelona present expansion vectors for aseptic pouch formats.
- EU Green Deal agricultural standards:Incentives for sustainable farming practices create cost advantages for certified organic sofrito ingredient sourcing.
- E-commerce direct-to-consumer:Subscription models for specialty sofrito variants bypass traditional retail slotting fees and capture margin compression.
Industry Challenges
- Culantro cultivation expertise:Skilled agricultural labor for this critical aromatic herb concentrates in Caribbean growing regions, creating talent bottlenecks for geographic expansion.
- Clean-label certification timelines:Third-party organic and non-GMO verification processes extend product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sofrito Market |
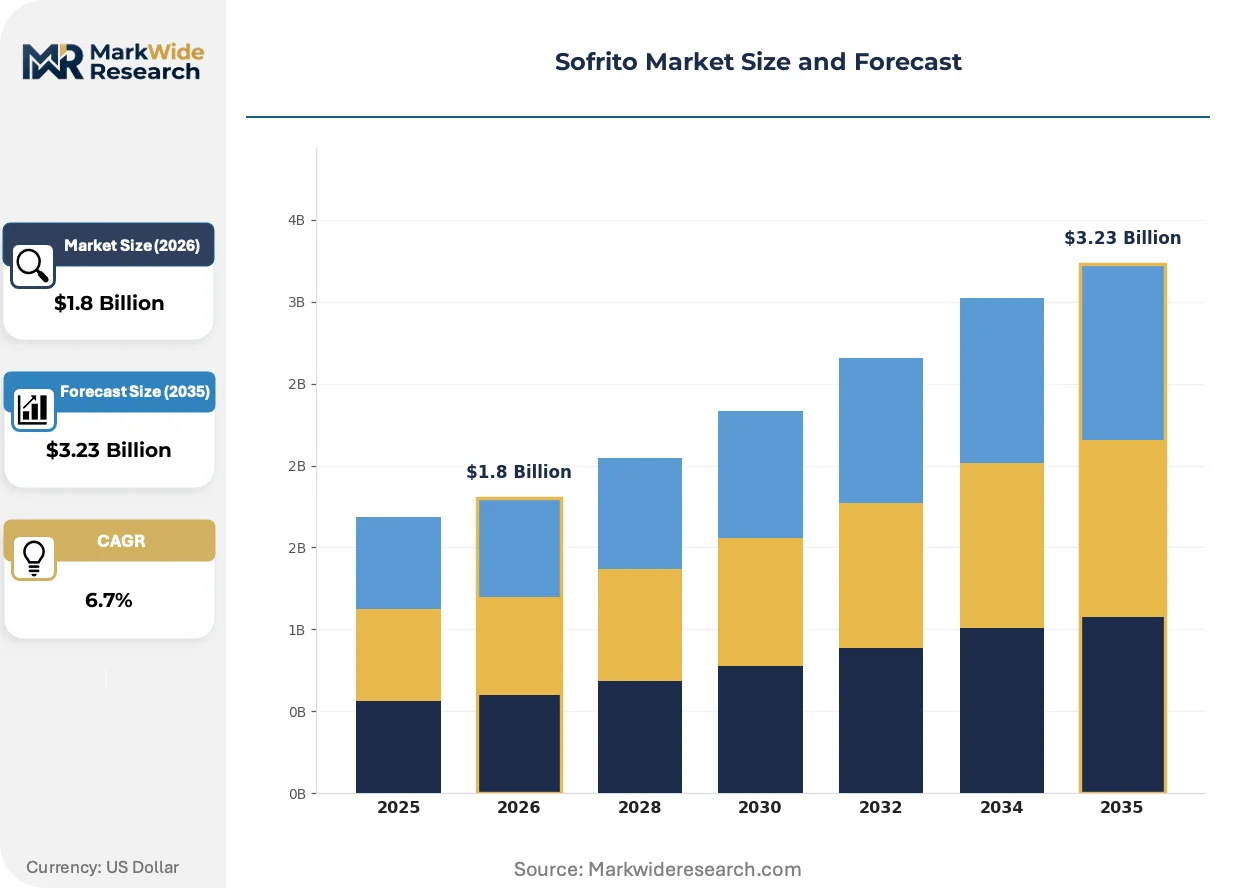
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh, Canned, Frozen, Sauces Ingredient Type: Vegetables, Spices, Herbs, Oils Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Food Service Packaging Type: Bottles, Jars, Packs, Cans |
| Companies Covered | Goya Foods, Herdez Del Fuerte, La Morena, McCormick & Company, La Costeña, Iberia Foods, Figueroa Produce, Goya Santo Domingo, Tainos Sofrito & Mojo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sofrito Market Evolving Landscape
Processing technology convergence and regulatory transparency mandates are restructuring how sofrito is manufactured, labeled, and distributed across retail and food service channels.
Aseptic cold-fill processing is overtaking traditional retort canning for premium sofrito lines. Flash-pasteurization followed by nitrogen-flushed pouch filling preserves volatile sulfur compounds from garlic and recirculating aldehydes from cilantro. Food service distributors in Miami and New York City are converting cold-chain infrastructure to accommodate these shorter-shelf-life, higher-margin formats.
EU Green Deal agricultural standards are reshaping ingredient sourcing protocols for exporters serving European markets. The framework mandates deforestation-free supply chain certification for tomato and pepper inputs, with compliance documentation required at port of entry. Dominican Republic and Puerto Rico-based manufacturers are investing in satellite-verified farm mapping to maintain market access.
Home cook purchasing behavior is fragmenting across convenience-oriented formats. Pourable sauce sub-categories are capturing volume from traditional jarred sofrito as meal-kit providers and recipe platforms specify pre-blended, measured bases. This shift concentrates most visibly in US Northeast metropolitan markets where dual-income households prioritize cooking time reduction over per-unit cost optimization.
Sofrito Market Segmentation
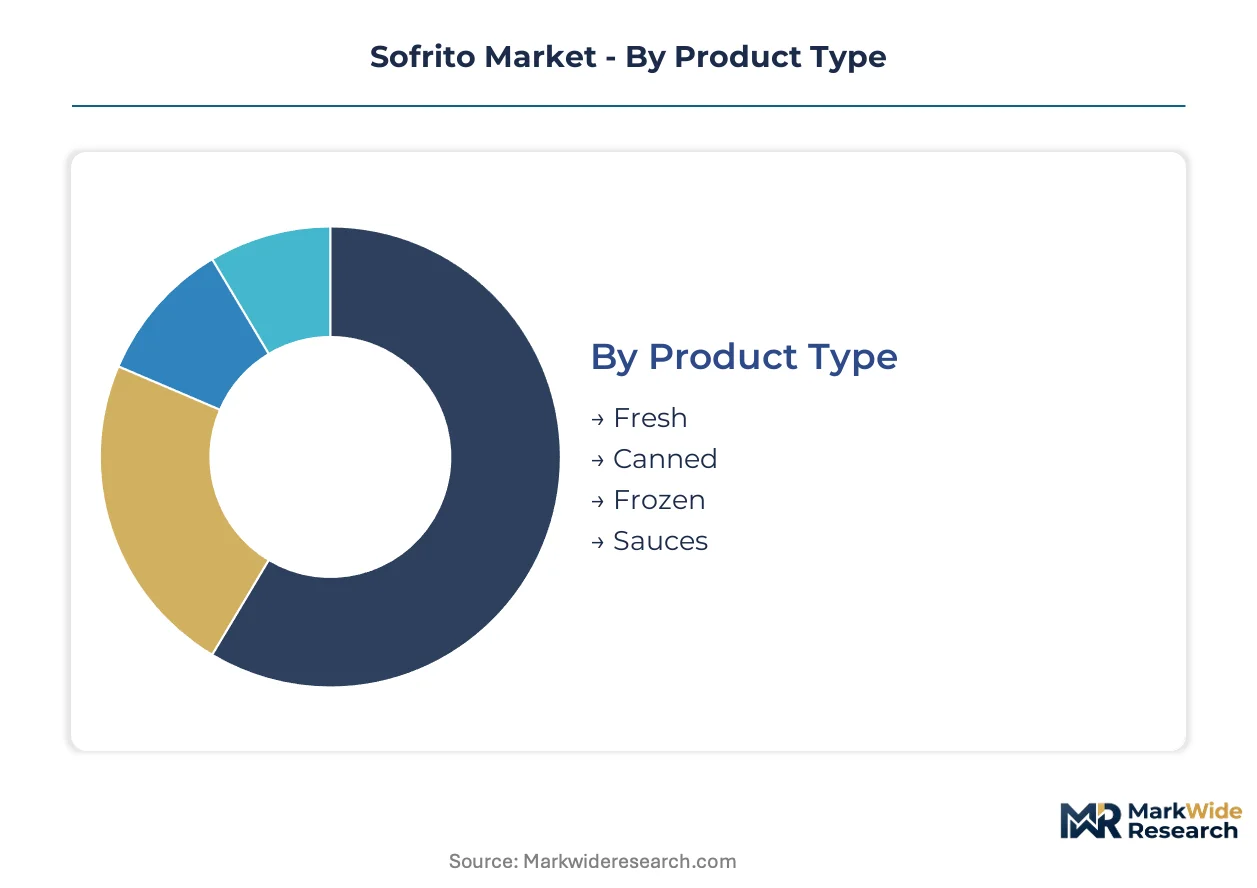
Sofrito manufacturers compete across distinct technical and commercial boundaries that determine margin capture and procurement access. Product format, ingredient sourcing, channel presence, and packaging configuration each create separate competitive arenas with divergent capital requirements and customer loyalty patterns.
Product Type:
Supply concentration among flash-freezing equipment providers and aseptic filling specialists is tilting competitive advantage toward producers with capital-intensive processing capabilities.
- Fresh:Unpasteurized blends of tomatoes, peppers, onions, garlic, and cilantro or culantro deliver maximum volatile aromatic retention. Puerto Rican food service chains and Dominican specialty retailers anchor demand, though cold-chain requirements constrain distribution radius and shelf life limits procurement flexibility.
- Frozen:Cryogenic freezing preserves sulfur compounds and aldehyde profiles that thermal processing degrades. Industrial kitchens in Miami and New York City are converting cold-chain infrastructure to accommodate these formats, driving adoption among restaurant groups seeking labor reduction without flavor compromise.
- Canned:Retort processing dominates mainstream retail through extended shelf stability and lower per-unit cost. Goya Foods leverages Latin American agricultural sourcing to maintain cost position in North American mass-market channels.
- Sauces:Pourable convenience formats capture volume from meal-kit providers and recipe platforms specifying pre-blended, measured bases. US Northeast metropolitan markets show strongest penetration where dual-income households prioritize cooking time reduction.
Today's leader: Canned. Tomorrow's challenger: Frozen.
Ingredient Type:
Cost tier stratification across ingredient categories is reshaping procurement strategies as EFSA sodium reduction mandates and clean-label certification requirements add compliance complexity.
- Vegetables:Tomatoes, peppers, and onions constitute the volumetric base of all sofrito formulations. California and Andalusia growing regions supply processing-grade tomatoes, though climate-driven harvest variability creates raw material cost instability that squeezes margin at the economy tier.
- Herbs:Cilantro and culantro deliver signature aromatic identity that distinguishes regional variants. Skilled agricultural labor for culantro cultivation concentrates in Caribbean growing regions, creating talent bottlenecks for geographic expansion and premium pricing power for established suppliers.
- Spices:Blended seasoning formats extend McCormick's industrial kitchen penetration through standardized flavor profiles that reduce kitchen labor and variation.
- Oils:Olive and vegetable oil carriers influence flavor delivery and shelf stability, with EU Green Deal deforestation-free certification requirements adding documentation burdens for exporters serving European markets.
Vegetables anchor volume economics. Herbs command premium separation.
Distribution Channel:
Customer type fragmentation is forcing parallel channel strategies as home cooks and food service operators diverge in specification priorities and purchasing cadence.
- Food Service:Restaurant chain consolidation is realigning procurement volumes toward fewer, larger buyers with specification power and reformulation requirements. Contract operators across Latin America and the Caribbean are standardizing regional menu offerings through centralized sofrito procurement.
- Supermarkets:Mass retail shelf placement demands slotting fee tolerance and promotional funding capacity that favors scaled producers with vertically integrated supply chains.
- Online Retail:Subscription models for specialty variants bypass traditional retail slotting fees and capture margin compression through direct-to-consumer relationships.
- Specialty Stores:Authenticity positioning commands price separation for small-batch producers in Santo Domingo and San Juan, though supply concentration limits scalable sourcing options.
Food Service concentrates buying power. Online Retail offers margin escape.
Packaging Type:
Maturity gradients across packaging technologies are creating investment timing decisions as aseptic cold-fill processing overtakes traditional retort canning for premium lines.
- Jars:Glass containment dominates fresh and refrigerated sofrito segments where transparency signals quality and supports premium positioning in specialty retail channels.
- Packs:Aseptic pouches with nitrogen flushing preserve volatile compounds for shorter-shelf-life, higher-margin formats. Eastern Spain industrial food service channels in Valencia and Barcelona present expansion vectors for this configuration.
- Bottles:Pourable convenience for sauce sub-categories aligns with meal-kit provider specifications and home cook time-reduction priorities.
- Cans:Metal containment retains economy-tier dominance through established filling infrastructure and consumer familiarity, though thermal degradation limits flavor fidelity.
Jars hold premium position. Packs are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Puerto Rico outpaces the Dominican Republic in per-capita sofrito consumption, while Spain's eastern provinces present the most underdeveloped industrial food service penetration among mature markets.
United States
Puerto Rican diaspora communities in Florida and New York Metro drive concentrated demand for authentic sofrito formats. FDA Food Safety Modernization Act traceability mandates favor large producers with digitized supply chains. Miami-Dade County food service distributors are converting cold-chain infrastructure to accommodate flash-frozen sofrito formats for restaurant groups.
Dominican Republic
Santo Domingo-based small-batch producers control premium fresh sofrito distribution with limited scalable sourcing. The country's agricultural ministry supports culantro cultivation programs to preserve skilled labor pools. San Juan de la Maguana growing clusters supply processing-grade peppers to regional manufacturers.
Puerto Rico
Island-wide restaurant chain standardization creates centralized procurement specifications with reformulation requirements. Local environmental regulations govern agricultural runoff from intensive tomato cultivation. Guaynabo industrial zones host aseptic processing facilities serving Caribbean export markets.
Spain
Valencia and Barcelona industrial food service channels show underpenetration for aseptic pouch sofrito formats. EFSA sodium reduction frameworks compress product development timelines for traditional recipes. Andalusia's Almería greenhouse complexes supply tomatoes despite climate-driven harvest variability.
Mexico
Herdez Del Fuerte leverages deep regional manufacturing presence to anchor distribution across Latin American export corridors. Mexican agricultural standards enforcement shapes pepper and tomato input quality specifications. Nuevo León processing clusters concentrate flash-freezing capacity for North American food service supply.
Sofrito Market Competitive Landscape
Caribbean producers anchor the fresh and premium tier; Mexican and US-based specialists hold scale positions in processed formats. The market structure tilts toward consolidation as restaurant chain procurement concentrates volumes among fewer qualified suppliers. Three archetypes dominate: vertically integrated agricultural processors, regional brand houses with manufacturing depth, and spice specialists extending into blended seasoning formats. Dominant competitive moves include backward integration into Latin American agricultural zones and aseptic processing technology licensing for premium line extensions.
Among Caribbean-origin producers, Goya Foods and Goya Santo Domingo exemplify the vertically integrated archetype with agricultural sourcing control, while Herdez Del Fuerte represents regional manufacturing depth in Mexican production clusters. McCormick & Company occupies a position as the spice specialist extending expertise into industrial kitchen formats. These three named entities illustrate how competitive positioning stratifies across supply chain control, geographic manufacturing presence, and flavor technology specialization rather than product-level differentiation alone.
| Leading Market Players |
|---|
| Goya Foods |
| Herdez Del Fuerte |
| La Morena |
| McCormick & Company |
| La Costeña |
| Iberia Foods |
| Figueroa Produce |
| Goya Santo Domingo |
| Tainos Sofrito & Mojo |
| Others |
Value Network & Pricing Analysis
Aseptic cold-fill processing adoption simultaneously compresses production costs for scaled manufacturers while concentrating procurement power among equipment-capable suppliers. This technology shift rewards flash-freezing operators with price-setting leverage in premium tiers while thermal processors defend volume positions through Latin American agricultural sourcing economies.
Pricing Analysis
Capacity additions in Nuevo León are reshaping price floors for frozen sofrito formats as Mexican processors expand cryogenic infrastructure. Three-tier pricing structure across premium, standard, and economy levels separates flash-frozen aseptic pouches from canned mass-market lines. Price differentiation hinges on cold-chain certification and EFSA compliance documentation. Cost compression in the economy tier intensifies because California tomato harvest variability squeezes margin. Food service chains show lowest price sensitivity; home cooks in specialty retail channels exhibit highest.
Supply Chain Analysis
Dual-sourcing qualification requirements from restaurant chain consolidators mandate redundant supplier relationships across Dominican Republic and Puerto Rico growing clusters. Raw material flows draw from California processing tomatoes, Andalusia greenhouse peppers, and Caribbean culantro cultivation zones. Supply chain risk centers on single-source vulnerability for skilled agricultural labor in Santo Domingo and San Juan. Distribution runs through Miami-Dade cold-chain hubs for North American food service penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory complexity as FDA Food Safety Modernization Act traceability mandates reshape supplier qualification requirements and procurement consolidation patterns.
For Market Incumbents: Anticipate margin compression from clean-label reformulation timelines by accelerating backward integration into satellite-verified Latin American agricultural zones. Invest in aseptic processing licensing to defend premium positioning against flash-freezing entrants. Culantro cultivation talent bottlenecks in Caribbean regions represent the critical supply constraint threatening geographic expansion. For New Entrants and Emerging Players: Launch via subscription direct-to-consumer models to bypass supermarket slotting fee barriers and capture margin compression in US Northeast metropolitan markets. Target underpenetrated industrial food service channels in Valencia and Barcelona with nitrogen-flushed pouch formats. E-commerce specialty variants offer the most penetrable white-space given authenticity positioning commands price separation. For Investors and Strategic Acquirers: Valuations sit cheapest among small-batch fresh sofrito producers in Santo Domingo and San Juan facing scalable sourcing limitations. Five-to-ten year viability favors manufacturers with digitized supply chain infrastructure and EFSA pre-certification. Monitor clean-label certification timeline compression as the inflection signal indicating which production formats will capture disproportionate margin pools.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Processing Technology Licensing | Flash-pasteurization preserves volatile sulfur compounds from garlic for premium food service contracts. |
| Satellite-Verified Agricultural Sourcing | EU Green Deal deforestation-free certification maintains European port-of-entry access for Dominican exporters. |
| Flash-Freezing Capacity Expansion | Cryogenic infrastructure in Miami-Dade accommodates restaurant group procurement standardization requirements. |
| Direct-to-Consumer Subscription Launch | Specialty variant bypass of retail slotting fees captures margin compression in dual-income Northeast households. |
| Culantro Cultivation Program Investment | Caribbean agricultural labor preservation defends premium fresh sofrito supply concentration against geographic expansion. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to capture procurement pattern shifts and regulatory compliance cost structures. Primary discussions engaged food service procurement directors, agricultural supply planners, aseptic processing equipment specialists, and clean-label certification consultants. Secondary validation drew from FDA Food Safety Modernization Act guidance documents, EFSA sodium reduction framework publications, EU Green Deal agricultural standards, and customs trade data on tomato and pepper input flows. Bottom-up volume modeling triangulated against top-down category spend estimates.
Historical reference periods anchored projections across the analysis window with segment-level CAGRs derived from trend extrapolation and driver elasticity assessment. Modeled dimensions span product format, ingredient sourcing tier, distribution channel, and packaging configuration. Forecast inputs incorporated restaurant chain consolidation velocity, clean-label certification penetration curves, and cold-chain infrastructure conversion rates in target metropolitan markets.
Forecast precision tightens around the base case; tail outcomes carry wider variance under climate-driven harvest volatility and regulatory timeline acceleration scenarios. Deviation in FDA traceability enforcement intensity or EFSA sodium mandate implementation pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Maple Syrup Market
Specialty Foods
Liquid Mushroom Market
Specialty Foods
Mexico Guacamole Market
Specialty Foods
Healthy Low-Fat Desserts Market
Specialty Foods
Acacia Honey Market
Specialty Foods
Low Calorie Diet Meal Plan Market
Specialty Foods
Medicinal Herbs Market
Specialty Foods
Global Sauerkrauts Market
Specialty Foods
Global Guilt-Free Desserts Market
Specialty Foods
Super Foods Market
Specialty Foods
Moringa Products Market
Specialty Foods
Cannabis Infused Drinks Market
Specialty Foods
Hot and Sour Noodles Market
Specialty Foods
Goldenseal Market
Specialty Foods
North America Alcohol-Infused Ice Cream Market
Specialty Foods
Kosher Food Market