
 Global Printing Software Market | 2026-2036
Global Printing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Printing Software Market Foresight
Subscription-based SaaS licensing is narrowing the capital barrier for mid-sized print service providers seeking enterprise-grade workflow tools. HP Inc. leverages its installed base of hardware endpoints to bundle software contracts at the point of device refresh. Canon Inc. anchors its competitive stance through deep integration between its imagePRESS controllers and proprietary color management algorithms. Xerox Corporation sustains relevance via managed print services contracts that embed software usage into per-page pricing structures.
Global Printing Software comprises applications that govern raster image processing, job queuing, color profile management, and device fleet orchestration across digital and offset production environments. These systems translate design files into machine-ready instructions while enforcing ink coverage limits, substrate calibration curves, and finishing parameters to minimize waste and rework. Cloud-based deployment leads in new contract value as print shops retire on-premises servers to reduce IT overhead and enable remote job submission. Workflow automation solutions capture expanding margin pools as labor shortages in prepress departments push shops toward touchless job onboarding and automatic imposition. Document security modules are gaining traction among government offices and financial publishers facing stricter audit requirements for print audit trails.
The EU AI Act and GDPR shape product roadmaps for European publishers by mandating automated decision logging and data residency controls in software that handles variable data printing. The US FDA enforces 21 CFR Part 11 compliance for printed labeling in pharmaceutical packaging, driving validation-ready software configurations. ISO 12647 color standards govern contract proofing accuracy, creating specification barriers for vendors lacking certified output modules. Stakeholders must weigh the pace of edge computing adoption against centralized cloud architectures as print volumes fragment across distributed production sites.
Market Dynamics
Cloud-native print management architectures are compressing the traditional on-premises software refresh cycle, forcing vendors to restructure perpetual license revenue into consumption-based metering models.
Growth Catalysts
- EU AI Act compliance mandates:Automated decision logging requirements for variable data printing systems are accelerating procurement of audit-ready workflow platforms across German and French publishing houses.
- Touchless job onboarding:Prepress labor shortages in North American commercial print shops are forcing adoption of AI-driven imposition and color correction modules that eliminate manual file preparation.
- Industrial print clusters:Concentrated demand from manufacturing hubs in Germany is pulling enterprise-grade fleet orchestration tools into mid-market service bureaus through volume discount structures.
Market Restraints
- Substrate calibration complexity:Proprietary color profile formats from dominant hardware vendors create switching friction that locks print shops into single-source ecosystems.
- GDPR data residency costs:Strict localization requirements for print audit trails force European operators to maintain redundant cloud regions, elevating total cost of ownership versus North American counterparts.
- Legacy controller obsolescence:Embedded RIP firmware in aging digital presses lacks API compatibility with modern workflow automation, stranding capital equipment before full depreciation.
Strategic Opportunities
- Edge computing convergence:Distributed production sites in India and Brazil are piloting hybrid architectures that process sensitive jobs locally while pushing non-critical rendering to centralized cloud nodes.
- 21 CFR Part 11 validation services:FDA-mandated electronic record compliance for pharmaceutical label printing creates a premium consulting attach market for software vendors with pre-validated configurations.
- Finishing parameter automation:Integration between imposition software and robotic bindery systems opens margin expansion in photobook and direct mail segments where manual handoff currently dominates.
Industry Challenges
- Color science expertise scarcity:Retirement of prepress specialists trained in ISO 12647 contract proofing standards is degrading quality consistency at independent print service providers.
- Multi-vendor integration complexity:Heterogeneous fleets mixing HP, Canon, and Xerox controllers require custom middleware development that extends deployment timelines and inflates professional services costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Printing Software Market |
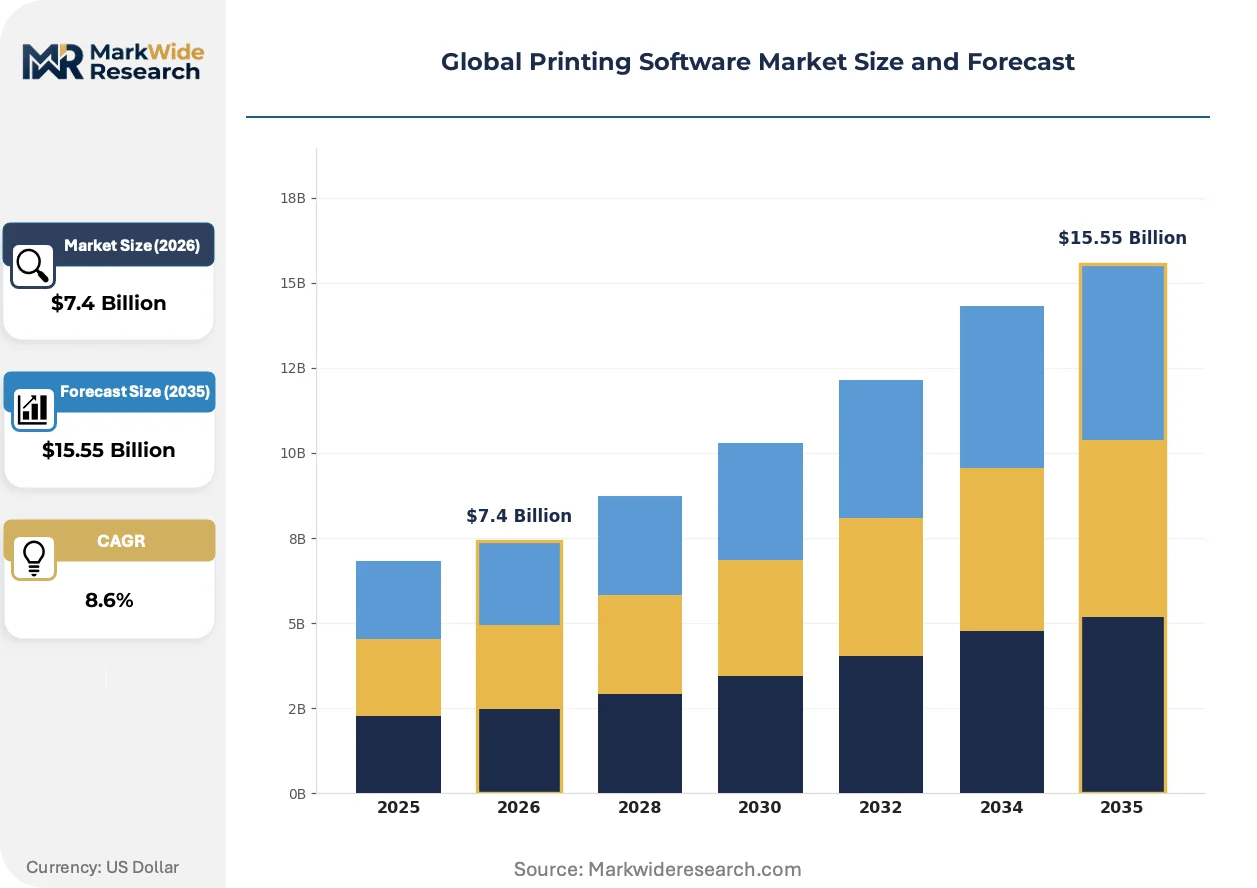
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $15.55 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Edge, Containerized Solution Type: Print Management, Workflow Automation, Document Security, Asset Tracking, Analytics End User: Publishing Houses, Advertising Agencies, Educational Institutions, Government Offices, Graphic Designers Application: Color Proofing, Variable Data Printing, Print Scheduling, Digital Asset Management, Remote Printing |
| Companies Covered | PaperCut Software International, Xerox Corporation, Canon Inc., HP Inc., Seiko Epson Corporation, Nuance Communications, PrinterLogic, Ringdale UK Ltd., ePaper Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Printing Software Market Shifts & Advancements
Native cloud RIP engines are collapsing the distinction between design file preparation and production execution, enabling real-time job routing that responds to press availability rather than batch schedules.
Serverless raster image processing is rendering obsolete the traditional model of dedicated on-premises RIP farms for high-volume production environments. Large format and signage printers in the United States are adopting pay-per-page cloud rendering for variable data jobs that previously required capital-intensive hardware clusters. This shift compresses job turnaround from hours to minutes while eliminating the three-to-five-year controller refresh cycle.
The EU AI Act's automated decision logging requirements are forcing workflow vendors to embed immutable audit trails into every color correction and variable data merge operation. German financial publishers now reject software lacking certified decision provenance modules, creating specification barriers for vendors without European development presence. Compliance investments are concentrating procurement decisions among vendors with dedicated GDPR engineering teams.
Subscription-based per-seat licensing is displacing perpetual ownership models across mid-sized print service providers in Japan and South Korea. Channel partners in these markets now lead with SaaS trials rather than on-premises pilots, compressing sales cycles from quarters to weeks. The shift favors vendors with mature API ecosystems that integrate cleanly with existing MIS and accounting systems without custom deployment.
Global Printing Software Market Segmentation
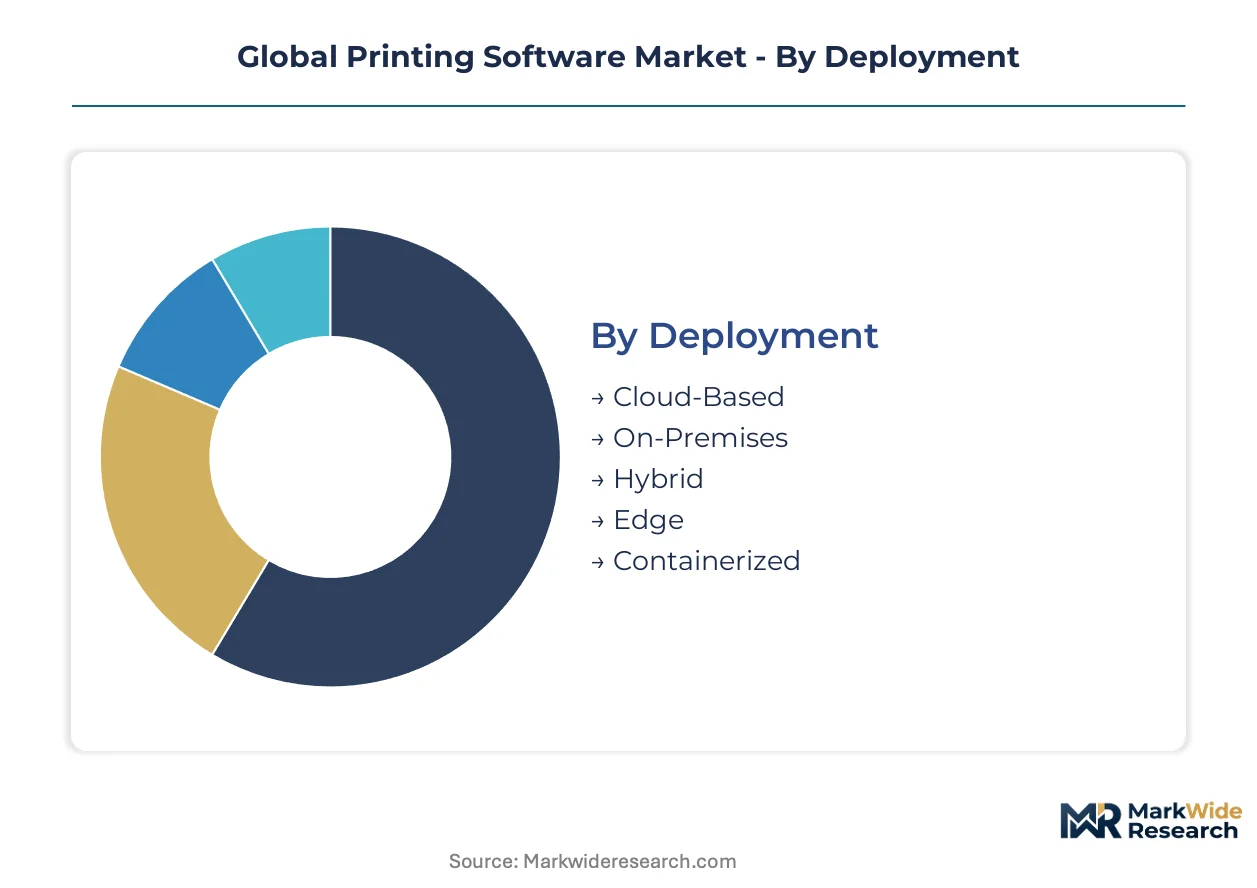
Printing software vendors structure product portfolios around deployment architectures and operational workflows that dictate recurring revenue intensity. Segmentation reveals where subscription attach rates diverge and which customer profiles justify dedicated professional services investment.
Deployment:
After-sales service intensity varies sharply across deployment modes, with cloud-native architectures demanding continuous platform engineering while edge deployments require localized field support networks.
- Cloud-Based:Multi-tenant SaaS architectures centralize raster image processing and color profile management on vendor-operated infrastructure. German commercial print shops are migrating legacy on-premises RIP farms to cloud-native stacks to satisfy GDPR data residency requirements through EU-region hosting.
- On-Premises:Perpetual-licensed software running on customer-managed servers retains dominance in high-security government facilities and defense contractors where air-gapped networks are mandatory. Japanese publishing houses maintain on-premises color proofing workstations to preserve ISO 12647 certification chains without external data exposure.
- Hybrid:Split architectures process sensitive job metadata locally while pushing non-critical rendering to cloud nodes. Indian mid-market print service providers pilot hybrid configurations to balance data sovereignty concerns against capital expenditure reduction.
- Edge:Distributed computing nodes at production sites enable sub-second job routing decisions without round-trip latency to centralized data centers. Brazilian large-format signage printers deploy edge RIP engines to support real-time variable data merges for event marketing campaigns.
- Containerized:Kubernetes-orchestrated microservices enable elastic scaling of print management workloads across heterogeneous infrastructure. South Korean packaging converters adopt containerized workflows to harmonize software versions across geographically dispersed production facilities.
Cloud-Based holds the largest share; momentum sits with Containerized as DevOps practices penetrate industrial print operations.
Solution Type:
Margin structures diverge across solution categories based on integration depth with hardware controllers and regulatory compliance burdens.
- Print Management:Core platforms governing device fleet orchestration, job queuing, and consumables monitoring across mixed-vendor environments. French financial publishers mandate print management suites with embedded EU AI Act decision logging for variable document personalization.
- Workflow Automation:AI-driven modules eliminating manual prepress tasks through automatic imposition, color correction, and file normalization. North American commercial print shops facing prepress labor shortages are expanding automation deployments to maintain throughput without headcount expansion.
- Document Security:Audit trail modules enforcing access controls, watermarking, and print job encryption for sensitive materials. German government offices require certified security stacks meeting BSI technical guidelines for classified document handling.
- Asset Tracking:Real-time location and utilization monitoring for mobile print fleets and distributed production equipment. Australian educational institutions deploy asset tracking to optimize shared printer allocations across multi-campus networks.
- Analytics:Consumables forecasting, press utilization optimization, and predictive maintenance algorithms. Japanese packaging converters leverage analytics to minimize substrate waste through ink coverage prediction and job batching optimization.
Print Management commands the revenue base; Workflow Automation is expanding most quickly as labor constraints intensify.
End User:
Customer archetypes determine pricing elasticity and implementation complexity based on internal IT sophistication and compliance exposure.
- Publishing Houses:High-volume book, magazine, and catalog producers requiring color-accurate contract proofing and tight integration with editorial content management systems. German publishing clusters drive demand for ISO 12647-certified output modules with automated quality verification.
- Advertising Agencies:Creative services firms producing campaign materials across print and digital channels with compressed turnaround requirements. Brazilian agencies prioritize cloud-based remote printing to coordinate production across decentralized creative teams.
- Educational Institutions:Universities and school districts managing high-volume transactional printing with severe budget constraints. Indian educational technology initiatives are subsidizing print management software adoption to reduce per-page costs across public university systems.
- Government Offices:Administrative bodies with stringent document security mandates and multi-year procurement cycles. French public sector tenders now embed EU AI Act compliance requirements as mandatory evaluation criteria.
- Graphic Designers:Freelance and boutique studio operators seeking professional color management without enterprise infrastructure investment. South Korean independent designers favor subscription-based proofing tools with pay-per-use cloud rendering.
Publishing Houses represent the deepest account penetration; Government Offices are gaining share fastest on security-driven procurement.
Application:
Use case specialization determines technical specification requirements and integration touchpoints with adjacent design and production systems.
- Color Proofing:Contract-grade output verification against ISO 12647 standards with delta-E measurement and substrate simulation. Japanese commercial printers maintain proofing investments despite digital transition to preserve high-value packaging contract relationships.
- Variable Data Printing:Personalized document composition merging database records with template designs for direct mail and transactional applications. German financial services firms drive demand for audit-traceable variable printing under GDPR Article 5 accountability requirements.
- Print Scheduling:Dynamic job sequencing optimizing press utilization across mixed digital and offset equipment fleets. Indian packaging converters implement advanced scheduling to minimize changeover times on short-run flexible packaging orders.
- Digital Asset Management:Centralized repository systems governing version control, rights management, and automated distribution of design files. Australian marketing services firms integrate DAM with print workflows to accelerate campaign localization across regional markets.
- Remote Printing:Cloud-enabled job submission and proofing approval without physical presence at production facilities. Brazilian event marketing agencies rely on remote printing to execute last-minute signage updates across dispersed venue networks.
Color Proofing retains the value concentration; Variable Data Printing shows the steepest expansion trajectory on personalization demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports more printing software engineering services than it imports, while the United States runs a structural deficit in specialized workflow automation modules. Trade imbalances concentrate procurement power in manufacturing clusters with deep prepress expertise.
United States
Large-format signage printers in California and Texas are adopting serverless cloud RIP engines to eliminate capital-intensive hardware refresh cycles. FDA 21 CFR Part 11 compliance mandates for pharmaceutical label printing drive validation-ready software configurations. The Pacific Northwest hosts independent software vendors developing Kubernetes-orchestrated containerized workflows for packaging converters.
Germany
Industrial print clusters in Bavaria and Baden-Württemberg pull enterprise-grade fleet orchestration tools into mid-market service bureaus through volume discount structures. EU AI Act automated decision logging requirements accelerate procurement of audit-ready workflow platforms across Frankfurt and Munich publishing houses. Stuttgart-area packaging converters demand ISO 12647-certified output modules with embedded quality verification.
Japan
Publishing houses in Tokyo and Osaka maintain on-premises color proofing workstations to preserve certification chains without external data exposure. Subscription-based per-seat licensing displaces perpetual ownership models across mid-sized print service providers in Kansai. METI industrial digitization programs subsidize cloud migration for prepress departments facing specialist retirements.
India
Mid-market print service providers in Maharashtra and Karnataka pilot hybrid configurations to balance data sovereignty concerns against capital expenditure reduction. Educational technology initiatives subsidize print management software adoption across public university systems in Delhi-NCR. Mumbai packaging converters implement advanced scheduling algorithms to minimize changeover times on short-run flexible packaging orders.
Brazil
Event marketing agencies in São Paulo rely on remote printing to execute last-minute signage updates across dispersed venue networks. Large-format printers deploy edge RIP engines to support real-time variable data merges for campaign materials. ANVISA pharmaceutical labeling regulations create demand for audit-traceable document security modules in Rio de Janeiro packaging hubs.
Global Printing Software Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in color science and security modules. The vendor base organizes around three functional layers: hardware-anchored suites bundling device controllers with workflow tools, pure-play SaaS vendors offering cloud-native RIP and fleet management, and niche specialists delivering compliance-certified security or proofing modules. Competitive moves concentrate on API ecosystem expansion and consumption-based metering transitions that convert perpetual license customers to recurring revenue streams.
Among hardware-anchored platform vendors, HP Inc., Canon Inc., and Xerox Corporation exemplify distinct strategic postures. HP leverages its installed base of hardware endpoints to bundle software contracts at the point of device refresh. Canon anchors its competitive stance through deep integration between imagePRESS controllers and proprietary color management systems. Xerox sustains relevance via managed print services contracts that embed software usage into per-page pricing structures, representing the service-integration archetype.
| Leading Market Players |
|---|
| PaperCut Software International |
| Xerox Corporation |
| Canon Inc. |
| HP Inc. |
| Seiko Epson Corporation |
| Nuance Communications |
| PrinterLogic |
| Ringdale UK Ltd. |
| ePaper Ltd. |
| Others |
Supply & Pricing Matrix
Bavarian software engineering clusters in Germany concentrate R&D capacity for color management algorithms, translating upstream talent scarcity into premium pricing power for ISO 12647-certified output modules. This geographic concentration of prepress expertise allows dominant vendors to maintain subscription pricing tiers that compress margins for mid-market print service providers in peripheral markets.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels, with differentiation driven by GDPR compliance certification depth and after-sales service bundling intensity. Pricing pressure stems from subscription fatigue among Japanese mid-sized print shops migrating from perpetual licenses. Government offices in France show least price sensitivity due to EU AI Act compliance mandates that override cost considerations.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for hardware-anchored software vendors sourcing controller firmware components. Manufacturing concentration rests on Germany, Japan, and South Korea for precision color calibration hardware. Raw material dependencies include specialized ASICs for raster image processing, high-resolution sensor arrays, and substrate simulation substrates. Distribution runs through authorized channel partners with embedded professional services capabilities rather than direct digital marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Printing Software Market functions as a service-attach opportunity where managed print services contracts expand recurring revenue faster than hardware refresh cycles. Workflow automation modules represent the fastest-growing attach layer as labor shortages force touchless job onboarding adoption.
For Market Incumbents: Insulate installed base relationships by embedding API ecosystems that lock print shops into proprietary color profile formats, creating switching friction against pure-play SaaS challengers. Canon and HP should deepen controller-software integration to strand competitors lacking hardware endpoints. Invest in GDPR engineering teams to capture French and German public sector tenders where compliance specifications act as procurement filters. For New Entrants and Emerging Players: Mid-market commercial print shops in India and Brazil represent the most penetrable entry point, where hybrid cloud-edge architectures address data sovereignty concerns without requiring full enterprise sales cycles. Target workflow automation modules for North American prepress departments facing specialist retirements. Lead with SaaS trials rather than on-premises pilots to compress sales cycles from quarters to weeks. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-software play because regulatory burden intensity across EU AI Act, GDPR, and FDA 21 CFR Part 11 creates durable specification barriers. Acquisition targets should exhibit pre-validated configurations for pharmaceutical label printing and dedicated European development presence. Watch ANVISA regulatory expansion in Brazil as signal for emerging market compliance premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep API ecosystems lock print shops into proprietary color profile formats against competitors. |
| Geographic Expansion | EU-region cloud hosting satisfies GDPR data residency requirements for German publishing clusters. |
| Acquisition of Specialist Firm | Pre-validated FDA 21 CFR Part 11 configurations capture pharmaceutical label printing premiums. |
| Product Launch | Serverless cloud RIP engines eliminate capital-intensive hardware refresh cycles for signage printers. |
| Strategic Partnership | Robotic bindery system integrations open margin expansion in photobook and direct mail segments. |
Research Methodology
The analysis maps cloud-native RIP engines, workflow automation modules, and document security platforms, each validated through primary interviews with CTOs at commercial print shops, prepress department heads, IT procurement officers, and channel integration specialists. Secondary sources include SEC filings from HP and Canon, EU AI Act compliance documentation, FDA 21 CFR Part 11 guidance, and ISO 12647 certification registries. Bottom-up triangulation across vendor revenue disclosures and top-down macroeconomic sizing ensures cross-validation.
Assumptions held fixed include sustained EU AI Act enforcement intensity, continued prepress labor shortage severity in North America, and stable cloud infrastructure cost curves across the projection horizon. Segmentation dimensions modeled span deployment architecture, solution type, end-user vertical, and application use case. CAGRs derive from regression analysis against historical software licensing transitions and hardware refresh cycle compression patterns, with sensitivity testing against edge computing adoption velocity and containerized workflow penetration rates.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting print shop capital expenditure cycles or escalation in US-China technology trade restrictions would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement continuity and cloud migration pace. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Project Software Market
Software & Services
MES Software Market
Software & Services
Global Online Community Management Software Market
Software & Services
Global Online Assessment Software Market
Software & Services
Tenant Billing Software Market
Software & Services
Meditation Management Apps Market
Software & Services
Global Budgeting Software Market
Software & Services
Pay-Per-Click (PPC) Software Market
Software & Services
Global Applicant Tracking Software Market
Software & Services
Job Description Management Software Market
Software & Services
IT Professional Services Market
Software & Services
Global Virtualization Software Market
Software & Services
Executive Search (Headhunting) Software Market
Software & Services
Attendance Management Software Market
Software & Services
Air Cargo Software Market
Software & Services
Automotive Customization Software Market