
 Content Curation Software Market | 2026-2036
Content Curation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Content Curation Software Market Outlook
Enterprise-grade feature sets is rotating toward the center of procurement decisions as buyers prioritize governance controls and API reliability over basic aggregation. Curata sustains its position through deep workflow automation for B2B marketing teams. BuzzSumo competes on discovery algorithms and influencer identification capabilities. UpContent differentiates by embedding native distribution hooks for social channels.
Content curation software encompasses platforms that algorithmically aggregate, filter, and organize third-party digital assets against user-defined parameters such as keyword relevance, sentiment thresholds, and publication authority scores. These systems serve commercial and institutional users by reducing manual research burden while maintaining editorial governance over externally sourced material. Cloud-based deployments capture the dominant share of new implementations as IT departments favor elastic scaling and reduced infrastructure overhead. Among end users, marketing agencies represent the most active procurement segment due to recurring campaign volume and multi-account management needs. Feature sets anchored in automation command premium pricing relative to baseline collaboration modules.
The EU AI Act and GDPR impose algorithmic transparency and data processing constraints on European deployments, compelling vendors to build explainability dashboards and consent audit trails. The FCC's oversight of digital platform practices in the United States shapes how curation tools handle copyrighted material and attribution chains. ISO 27001 certification has become a baseline threshold for enterprise procurement evaluations, particularly in financial services and healthcare adjacent use cases. Stakeholders must weigh regulatory divergence against platform standardization when selecting deployment architectures for multi-jurisdictional operations.
Market Dynamics
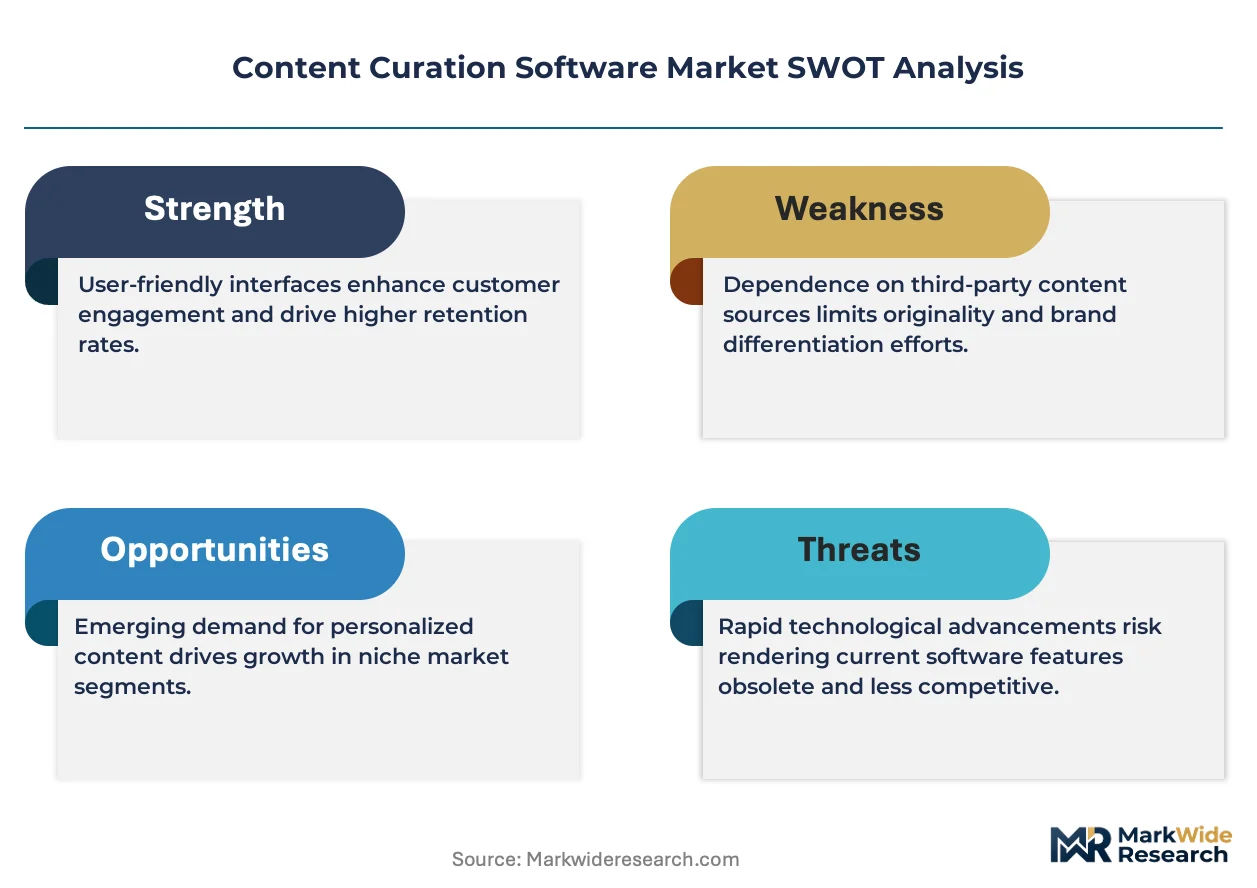
Marketing agencies now dominate procurement flows for content curation platforms, compressing vendor sales cycles while elevating demands for multi-tenant governance and API reliability over basic aggregation features.
Growth Catalysts
- EU AI Act compliance mandates:Automated transparency requirements across European deployments are accelerating vendor investment in explainability dashboards and consent audit trails.
- Cloud-native infrastructure preference:IT departments favor elastic scaling and reduced infrastructure overhead, driving replacement of on-premise legacy systems.
- Marketing agency procurement concentration:Recurring campaign volume and multi-account management needs create sustained demand for workflow automation capabilities.
Market Restraints
- Algorithmic bias liability exposure:GDPR data processing constraints and EU AI Act transparency requirements impose compliance costs that disadvantage smaller vendors.
- Attribution chain complexity:FCC oversight of digital platform practices in the United States creates friction around copyrighted material handling and source verification.
- ISO 27001 certification threshold:Enterprise procurement evaluations in financial services and healthcare adjacent use cases exclude uncertified vendors from consideration.
Strategic Opportunities
- Underpenetrated mid-market segment:Small and medium enterprises outside major metropolitan clusters represent unserved demand for scaled-down governance modules.
- Native social distribution integration:Embedding direct publishing hooks for LinkedIn, X, and Instagram creates differentiation against API-dependent competitors.
- Influencer identification convergence:Combining discovery algorithms with creator economy platforms opens adjacent revenue streams beyond core curation licensing.
Industry Challenges
- Multijurisdictional compliance architecture:Vendors must maintain divergent codebases to satisfy GDPR, EU AI Act, and FCC requirements simultaneously.
- API reliability engineering:Marketing agencies demand sub-second response times for real-time campaign adjustments, straining infrastructure investment cycles.
- Editorial governance automation:Balancing algorithmic efficiency with human oversight workflows creates product design tension that slows feature release velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Content Curation Software Market |
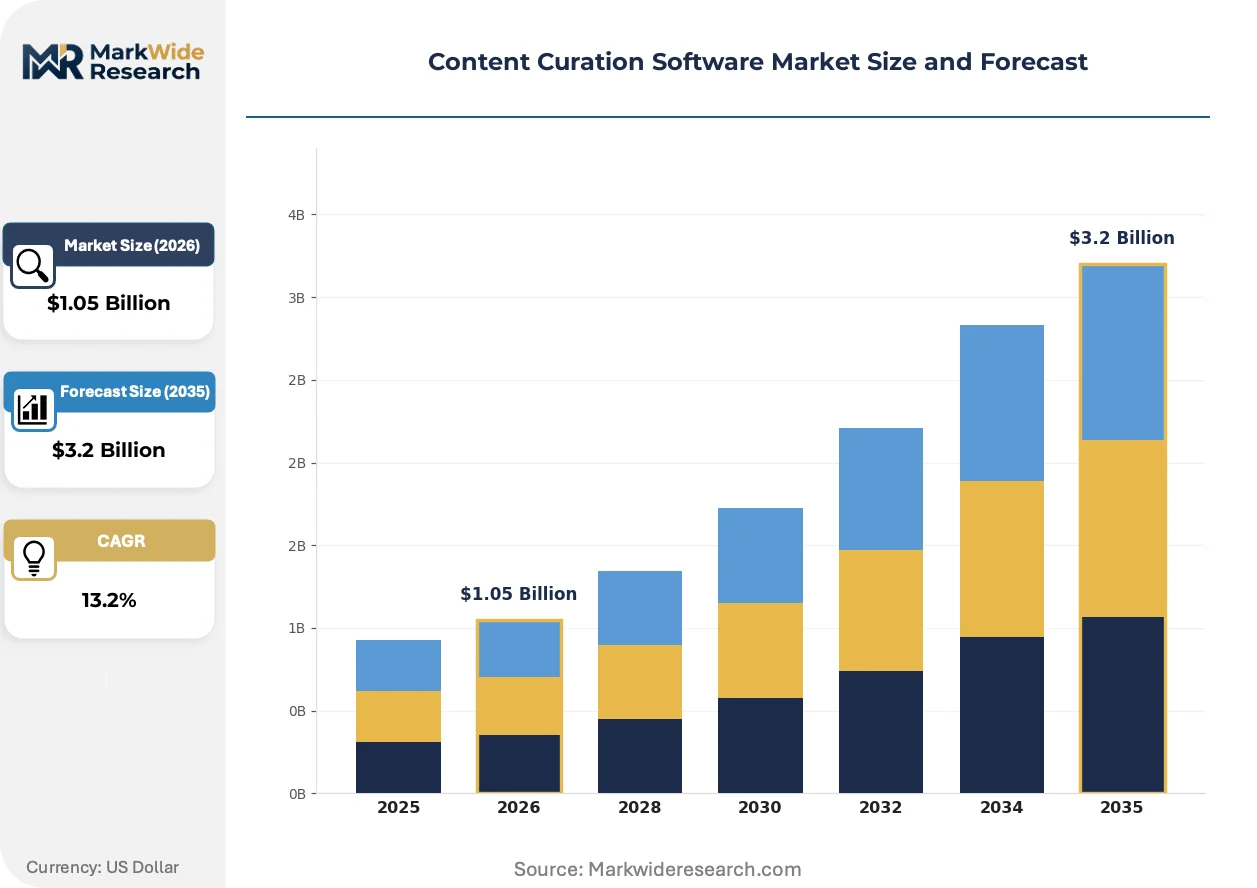
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Cloud-based, On-premises, Hybrid, SaaS End User: Marketing Agencies, Educational Institutions, Media Companies, Corporate Enterprises Feature Set: Automation, Analytics, Collaboration, Customization Content Type: Images, Articles, Videos, Podcasts |
| Companies Covered | Curata, UpContent, Planable, Groupiest, ContentStudio, BuzzSumo, Scoop.it, DrumUp, Quuu, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Content Curation Software Market Strategic Shifts
Natural language processing capabilities are decomposing traditional keyword-matching architectures, enabling semantic understanding that reduces false-positive content retrieval while compressing manual review overhead.
Generative AI summarization engines are decomposing the role of human editorial teams in B2B marketing agencies, with early adopters in technology and professional services verticals deploying auto-generated briefing documents at scale. This compression of labor-intensive curation workflows is forcing incumbent vendors to rearchitect core product roadmaps around synthesis capabilities rather than aggregation alone.
The EU AI Act's algorithmic transparency mandates are reshaping European deployment requirements, compelling vendors to build explainability dashboards that surface scoring weights and source authority calculations. Financial services and healthcare adjacent use cases face the steepest compliance burdens, with procurement teams now requiring documented consent audit trails as standard evaluation criteria.
Subscription fatigue among mid-market buyers is fragmenting procurement patterns, with marketing agencies unbundling all-in-one suites to purchase specialized discovery, governance, and distribution modules from separate vendors. This disaggregation is most visible in the United States, where procurement teams prioritize best-of-breed API interoperability over single-vendor consolidation.
Content Curation Software Market Segmentation
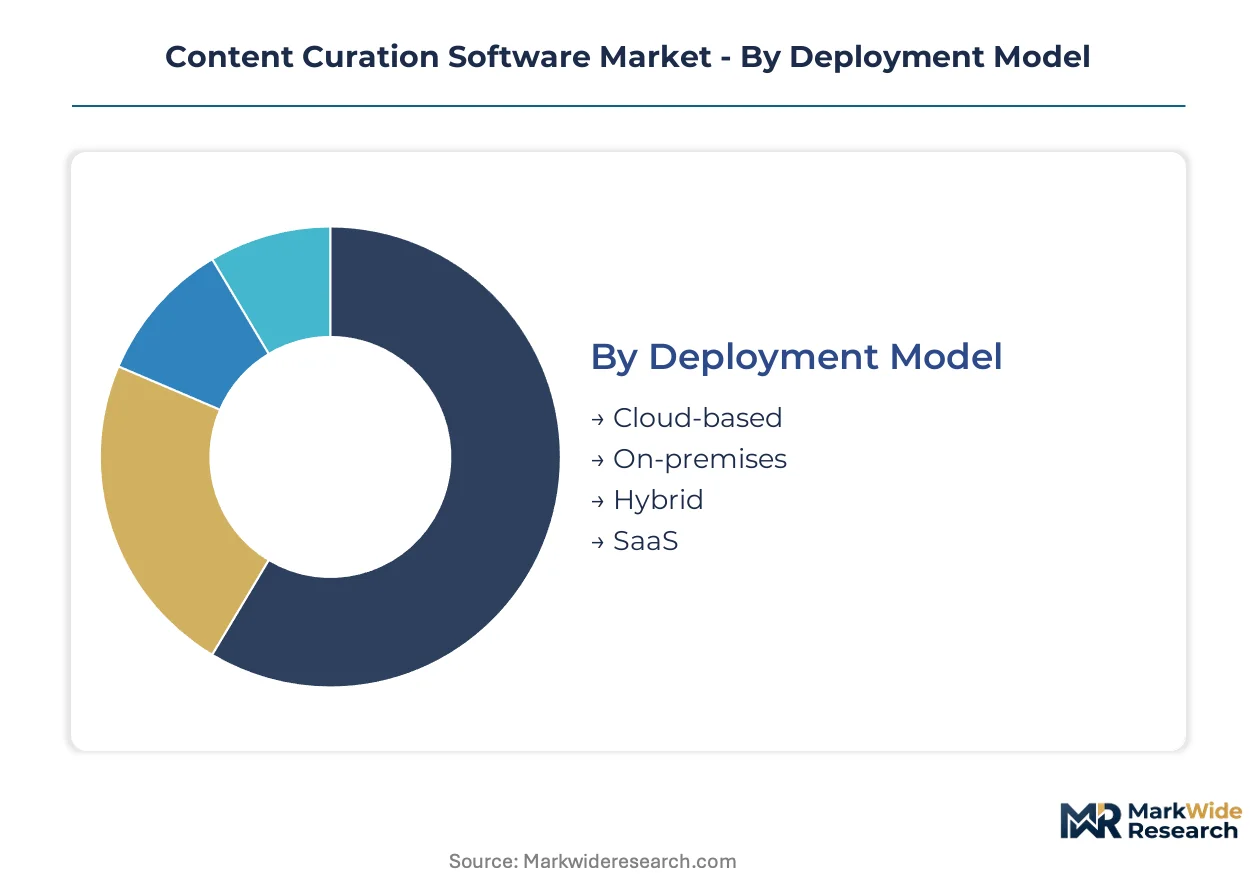
Segmentation in content curation software reveals how procurement patterns cluster around governance requirements and workflow integration depth. Buyers prioritize deployment flexibility and feature modularity over monolithic suites as regulatory complexity escalates.
Deployment Model:
Channel mix varies sharply by deployment type, with cloud-native platforms flowing through direct vendor sales and hybrid solutions requiring systems integrator intermediation.
- Cloud-based:Elastic infrastructure supports real-time scaling for marketing agencies managing volatile campaign volumes. Demand concentrates in the United States where IT departments prioritize reduced data center overhead. FCC oversight of cross-border data flows creates compliance friction for multi-jurisdictional deployments.
- SaaS:Subscription licensing with API-first architecture enables rapid integration into existing marketing stacks. Procurement runs through digital marketplaces and direct self-service channels, with mid-market buyers favoring monthly billing cycles over annual commitments.
- On-premises:Air-gapped installations serve financial services and healthcare adjacent use cases with strict data residency mandates.
- Hybrid:Split processing between edge and cloud accommodates GDPR data localization requirements while preserving analytics scalability.
Cloud-based deployments dominate installed base. SaaS is where expansion concentrates.
End User:
Cost tier stratification separates enterprise procurement with dedicated compliance officers from self-serve mid-market adoption with minimal governance overhead.
- Marketing Agencies:Multi-tenant workflow automation supports concurrent campaign management across dozens of client accounts. Demand clusters in major metropolitan markets with dense creative services ecosystems. Recurring content volume drives premium pricing tolerance for governance controls.
- Corporate Enterprises:Internal communications and brand safety protocols require explainability dashboards and documented source authority chains. Procurement evaluations mandate ISO 27001 certification as a baseline threshold.
- Educational Institutions:Library science and journalism programs deploy curation tools for curriculum development and research methodology training.
- Media Companies:Editorial teams leverage discovery algorithms to monitor competitor coverage and identify emerging story angles.
Marketing Agencies anchor current revenue. Corporate Enterprises are climbing the fastest.
Feature Set:
Application maturity separates established collaboration modules from emerging automation capabilities commanding development investment.
- Automation:Algorithmic aggregation with sentiment filtering and authority scoring reduces manual research burden by orders of magnitude. Marketing agencies in technology verticals deploy auto-generated briefing documents at scale, compressing editorial team headcount.
- Analytics:Engagement metrics and source performance tracking enable data-driven curation decisions with measurable ROI attribution.
- Collaboration:Shared workspaces and approval workflows remain standard in bundled suites despite unbundling pressure from specialized vendors.
- Customization:White-label interfaces and configurable scoring weights accommodate brand-specific governance requirements.
Automation commands premium pricing. Analytics is gaining share fastest.
Content Type:
Volume concentration in short-form assets contrasts with margin expansion in multimedia processing requiring transcoding and rights management infrastructure.
- Articles:Text-based curation with NLP-powered semantic matching dominates B2B marketing use cases. GDPR and EU AI Act transparency mandates compel explainability dashboards surfacing keyword relevance algorithms.
- Videos:Automated transcription and thumbnail generation support social distribution at scale. Media companies and corporate communications teams drive demand for native publishing hooks to LinkedIn and Instagram.
- Images:Visual search and metadata extraction serve design-heavy workflows in creative agencies.
- Podcasts:Audio segmentation and speaker identification remain niche, concentrated in media monitoring and competitive intelligence applications.
Articles dominate installed base. Videos represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States demonstrate the lowest price elasticity as enterprises prioritize governance controls and API reliability, while mid-market segments in emerging markets remain highly sensitive to subscription costs and seek modular, pay-as-you-scale alternatives.
United States
Enterprise procurement concentrates around marketing agencies in New York and San Francisco demanding sub-second API response times for real-time campaign adjustments. FCC oversight of digital platform practices shapes attribution chain requirements for copyrighted material handling. The Northeast corridor hosts the densest ecosystem of B2B marketing technology buyers, with Boston-based financial services firms mandating ISO 27001 certification as a baseline procurement threshold.
Germany
Industrial marketing teams in automotive and machinery verticals drive demand for explainability dashboards surfacing algorithmic scoring weights. The EU AI Act imposes mandatory transparency requirements on automated content curation tools deployed across European operations. Baden-Württemberg's manufacturing hub generates concentrated procurement from Mittelstand firms seeking hybrid cloud deployments that satisfy GDPR data localization mandates.
United Kingdom
London's creative services cluster sustains premium pricing tolerance for multi-tenant workflow automation supporting concurrent client account management. The Information Commissioner's Office enforces GDPR compliance through documented consent audit trails for algorithmic processing. Fintech marketing teams in the Square Mile deploy curation tools for competitive intelligence and regulatory content monitoring at scale.
India
Digital marketing agencies in Bangalore and Mumbai represent the fastest-expanding mid-market segment for SaaS-based curation platforms with monthly billing preferences. The country's data protection authority is developing localization requirements that influence cloud deployment architecture decisions. Hyderabad's IT services corridor hosts emerging demand from outsourcing firms building white-label content solutions for North American and European clients.
Japan
Corporate communications teams in Tokyo prioritize brand safety protocols and documented source authority chains for externally curated content. METI guidelines on AI governance shape vendor selection criteria for explainability and human oversight integration. Osaka's manufacturing marketing departments show rising interest in automated briefing document generation for B2B verticals.
Content Curation Software Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with workflow automation specialists commanding premium pricing while API-first aggregators compete on accessibility and integration speed. The vendor base organizes into three tiers: enterprise-grade governance platforms, mid-market SaaS tools, and specialized discovery engines. Consolidation pressure is accelerating as marketing agencies unbundle suites and demand best-of-breed interoperability. Dominant competitive moves include native social distribution integration and generative AI summarization capabilities that compress editorial labor.
Within the workflow automation tier, Curata exemplifies deep B2B marketing integration, while UpContent represents the distribution-native archetype with embedded social publishing hooks. BuzzSumo occupies a position on the discovery-specialist vector, competing through algorithmic content identification and influencer mapping capabilities. These three anchors illustrate how differentiation is fragmenting across automation depth, distribution breadth, and discovery sophistication rather than consolidating around monolithic platforms.
| Leading Market Players |
|---|
| Curata |
| UpContent |
| Planable |
| Groupiest |
| ContentStudio |
| BuzzSumo |
| Scoop.it |
| DrumUp |
| Quuu |
| Others |
Value Chain & Pricing Dynamics
Cloud infrastructure spend substituting for on-premise data center capital is redrawing vendor cost structures and customer procurement economics simultaneously. This shift concentrates supplier power with hyperscaler platforms while compressing margins for independent software vendors unable to negotiate enterprise-scale compute commitments.
Pricing Analysis
Annual support and professional services tiers now drive lifetime value capture, with vendors bundling implementation consulting and ongoing governance advisory into multi-year contracts. Subscription pricing stratifies across enterprise, growth, and starter tiers differentiated by API call volume and explainability dashboard depth. Cost compression in the mid-market segment is intensifying because marketing agencies unbundle suites and demand modular, best-of-breed pricing. Corporate enterprises show the lowest price sensitivity, prioritizing ISO 27001-certified governance controls over per-seat cost optimization.
Supply Chain Analysis
Inventory-light development cycles characterize the sector, with zero physical warehousing and near-instantaneous software delivery compressing traditional lead-time considerations to API latency benchmarks. Engineering talent concentrates in the United States, India, and Germany, with Bangalore and Berlin emerging as secondary hubs for NLP and machine learning specialization. The supply chain draws from cloud compute providers, open-source algorithm libraries, and third-party data licensing agreements rather than physical inputs. Single-source vulnerability rests on hyperscaler concentration for infrastructure-as-a-service. Distribution runs through direct vendor sales, digital marketplaces, and systems integrator channels for hybrid deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now favor interoperability over consolidation, with marketing agencies forcing vendors toward open API architectures that enable best-of-breed stacking rather than monolithic suite lock-in.
For Market Incumbents: Fortify workflow automation depth against generative AI-native entrants by embedding native summarization engines and explainability dashboards that satisfy EU AI Act mandates. Invest in ISO 27001 certification maintenance and GDPR-compliant consent audit trail infrastructure to defend enterprise procurement evaluation thresholds. Prioritize API reliability engineering to meet sub-second response time demands from high-volume marketing agency clients. For New Entrants and Emerging Players: Anchor in the underpenetrated mid-market segment outside major metropolitan clusters, where small and medium enterprises seek scaled-down governance modules with monthly billing flexibility. Target India and Southeast Asia for SaaS-based expansion, where digital marketing agencies favor pay-as-you-scale alternatives. Pursue a vertical-specialist go-to-market angle, positioning against horizontal incumbents with industry-specific authority scoring algorithms for healthcare or financial services use cases. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed workflow automation specialists holding concentrated B2B marketing agency relationships but lacking generative AI capabilities. Long-term viability hinges on synthesis feature roadmaps that compress editorial labor rather than aggregation alone. Watch for API interoperability consolidation plays as the inflection signal, where vendors with superior integration depth become acquisition targets for platform giants seeking curation layer expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Generative AI Summarization Integration | Auto-generated briefing documents compress editorial headcount in B2B marketing agencies. |
| Native Social Distribution Hooks | Direct publishing to LinkedIn and Instagram differentiates against API-dependent competitors. |
| EU AI Act Compliance Architecture | Explainability dashboards and consent audit trails unlock European enterprise procurement. |
| Mid-Market Modular Unbundling | Specialized discovery and governance modules capture subscription-fatigue-driven demand fragmentation. |
| Influencer Identification Convergence | Creator economy platform integration opens adjacent revenue beyond core curation licensing. |
Study Parameters
A spread of perspectives from chief technology officers, marketing agency operations directors, IT procurement officers, and platform integration specialists converged on the working assumptions underlying demand projections. Primary fieldwork combined structured interviews with secondary validation against SEC filings, hyperscaler capex disclosures, App Annie mobile platform data, and EU regulatory submission databases. Bottom-up sizing of vendor-reported customer counts and average contract values triangulated against top-down addressable market calculations from IT spend benchmarks.
Segmentation dimensions modeled include deployment architecture, organization size tier, vertical industry, feature module complexity, and regional regulatory cluster. Growth trajectories across the analysis window derived from cohort-based adoption curves and replacement cycle timing for legacy on-premise systems. NLP capability maturity and API reliability benchmarks served as technology-specific forecast inputs alongside marketing agency headcount expansion rates.
Decision-makers should treat outputs as directional under assumptions of sustained cloud infrastructure cost curves and stable GDPR enforcement intensity; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Fixed Asset Management Software Market
Software & Services
United States Contract Lifecycle Management Software Market
Software & Services
Runtime Software Market
Software & Services
Sports League Management Software Market
Software & Services
Lighting Control Software Market
Software & Services
Software-Defined Anything Market
Software & Services
Server Virtualization Software Market
Software & Services
Global Internal Communications Software Market
Software & Services
Japan Qualitative Data Analysis Software Market
Software & Services
Computational Medicine and Drug Discovery Software Market
Software & Services
Global Java Web Frameworks Software Market
Software & Services
Service Scheduling Software Market
Software & Services
Integration Brokerage Software Market
Software & Services
Mobile Application Development Platform (MADP) Market
Software & Services
Global Reporting Software Market
Software & Services
United States IT Services Market