
 Waterway Transportation Software Solutions Market | 2026-2036
Waterway Transportation Software Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Waterway Transportation Software Solutions Market Analytics
Cloud-to-edge integration is narrowing the gap between vessel telemetry and shore-based decision systems. SAP SE leverages its ERP backbone to anchor fleet management workflows across integrated logistics networks. Oracle Corporation sustains competitive positioning through specialized database architectures that handle real-time maritime data streams. Veson Nautical Corporation dominates chartering and voyage management with purpose-built maritime software that controls pricing and scheduling workflows.
Waterway transportation software solutions encompass platforms that manage vessel routing, cargo visibility, port scheduling, and regulatory reporting through modular architectures processing AIS, radar, and sensor feeds. These systems execute voyage optimization, berth allocation, and customs documentation to synchronize inland waterway movements with intermodal supply chains. Fleet management and route optimization segments lead current deployment volumes as operators prioritize fuel efficiency and transit-time reduction. AI-driven analytics represents the fastest-expanding technology category, with cloud-based solutions capturing the majority of new implementations due to lower infrastructure overhead and faster update cycles.
The European Maritime Safety Agency enforces digital reporting standards under the European Maritime Single Window environment, while the International Maritime Organization mandates data exchange protocols through its Electronic Data Interchange framework. The US Coast Guard administers vessel compliance through its Automated Mutual-Assistance Vessel Rescue system and port state control databases. Stakeholders must evaluate regulatory divergence between EU and US reporting standards when selecting platform architectures that support multi-jurisdictional operations.
Market Dynamics
Container shipping lines are consolidating procurement authority to optimize fleet utilization and reduce idle time across inland waterway networks. This demand concentration is reshaping vendor relationships and platform architecture requirements.
Growth Catalysts
- EU Green Deal:The European Commission's emissions reporting mandates are forcing Rhine corridor operators to deploy integrated fuel monitoring systems. Digital voyage documentation is now compulsory for all EU-flagged vessels.
- Cloud-to-edge telemetry:Real-time AIS and sensor data processing is enabling predictive maintenance workflows that cut unplanned downtime. Port authorities in Germany are prioritizing berth allocation algorithms.
- Charter market volatility:Spot rate fluctuations are driving demand for dynamic voyage optimization tools. Operators require software that adjusts routing in response to fuel price movements and canal congestion.
Market Restraints
- Legacy system integration costs:Proprietary terminal operating systems at major European ports resist API connectivity. Middleware development consumes disproportionate implementation budgets.
- Cybersecurity compliance fragmentation:The International Maritime Organization's guidelines lack enforcement mechanisms. National regulators impose conflicting data localization requirements.
- Skilled maritime-IT labor scarcity:Specialized expertise combining nautical operations with software engineering concentrates in Hamburg and Rotterdam. Recruitment timelines extend platform deployment cycles.
Strategic Opportunities
- AI-driven predictive analytics:Machine learning models trained on historical voyage data are identifying optimal speed-fuel tradeoffs. Early adopters report measurable bunker cost reductions.
- Danube corridor expansion:Infrastructure investments linking Central European manufacturing hubs to Black Sea ports are creating demand for multi-modal visibility platforms.
- Electronic Data Interchange standardization:The International Maritime Organization's unified reporting protocols will simplify cross-border documentation. Vendors aligning early capture regulatory advisory revenue.
Industry Challenges
- Interoperability certification delays:Vessel equipment manufacturers and software vendors dispute liability for integration failures. Type approval processes for combined hardware-software systems lack precedent.
- Change management resistance:Master mariners with decades of experience distrust automated routing recommendations. Training programs must demonstrate safety equivalence before adoption accelerates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waterway Transportation Software Solutions Market |
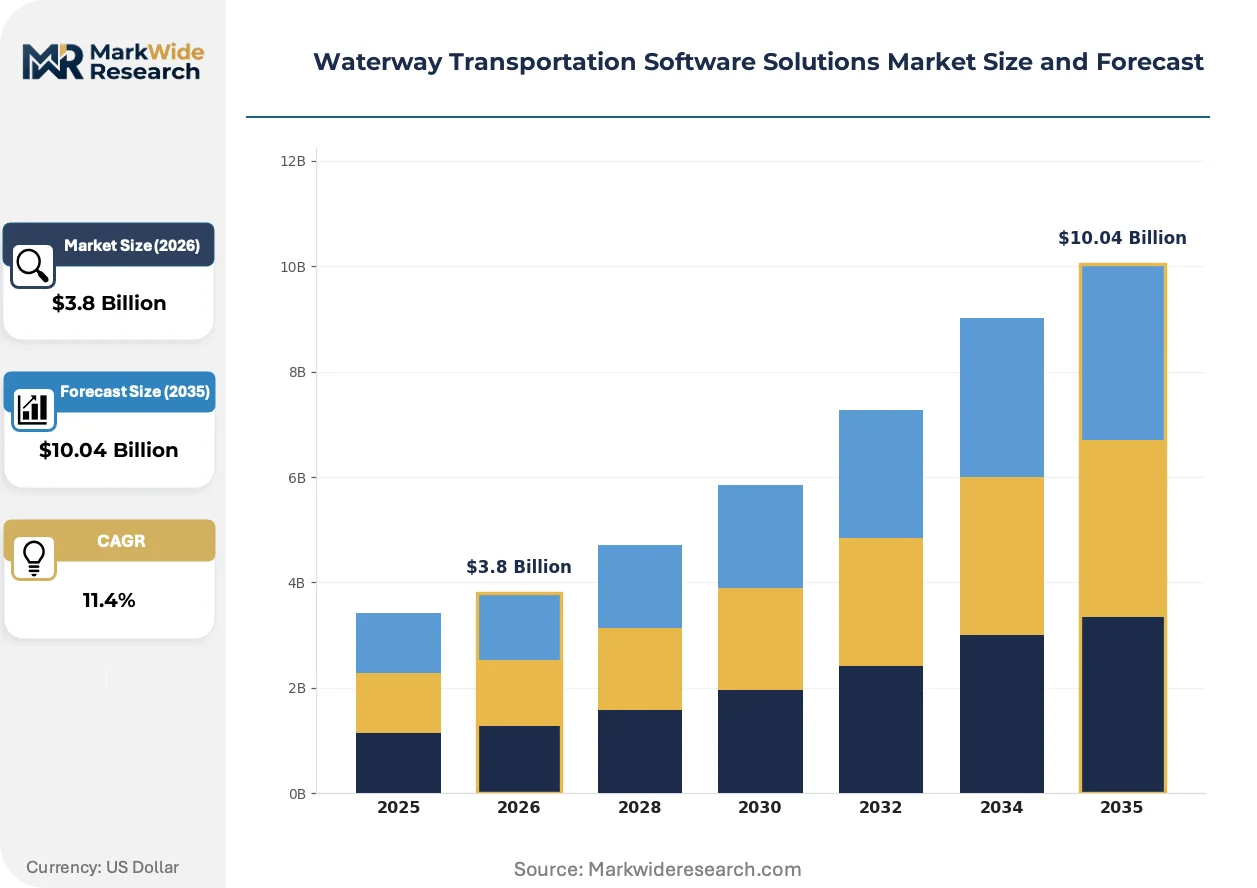
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fleet Management, Route Optimization, Cargo Tracking, Regulatory Compliance End User: Shipping Companies, Port Authorities, Freight Forwarders, Logistic Operators Technology: Cloud-Based Solutions, On-Premise Software, IoT Integration, AI-Driven Analytics Service Type: Consulting, System Integration, Support & Maintenance, Training |
| Companies Covered | SAP SE, Oracle Corporation, Accenture plc, Cognizant Technology Solutions Corporation, Veson Nautical Corporation, ABS Wavesight, Descartes Systems Group Inc., Bass Software Ltd., DNV GL AS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waterway Transportation Software Solutions Market Evolving Landscape
Maritime software architectures are pivoting from on-premise installations to distributed cloud-native systems. This shift is compressing update cycles and enabling continuous regulatory compliance.
Digital twin technology is virtualizing vessel performance simulation before physical deployment. Shipowners in the Rhine corridor are adopting these platforms to model engine retrofit impacts on fuel consumption. The technology is virtualizing capital allocation decisions by replacing sea trials with synthetic environment testing.
The European Maritime Safety Agency is enforcing harmonized reporting through its Single Window environment. This policy is eliminating redundant port documentation submissions. Container lines operating EU-registered fleets are restructuring back-office functions to consolidate compliance workflows under unified data architectures.
Charterers are consolidating software vendor relationships to capture volume pricing and integration efficiencies. Long-term framework agreements are displacing transactional procurement for voyage management modules. This concentration is most visible among German chemical shippers coordinating tanker movements across the Rhine-Main-Danube network.
Waterway Transportation Software Solutions Market Segmentation
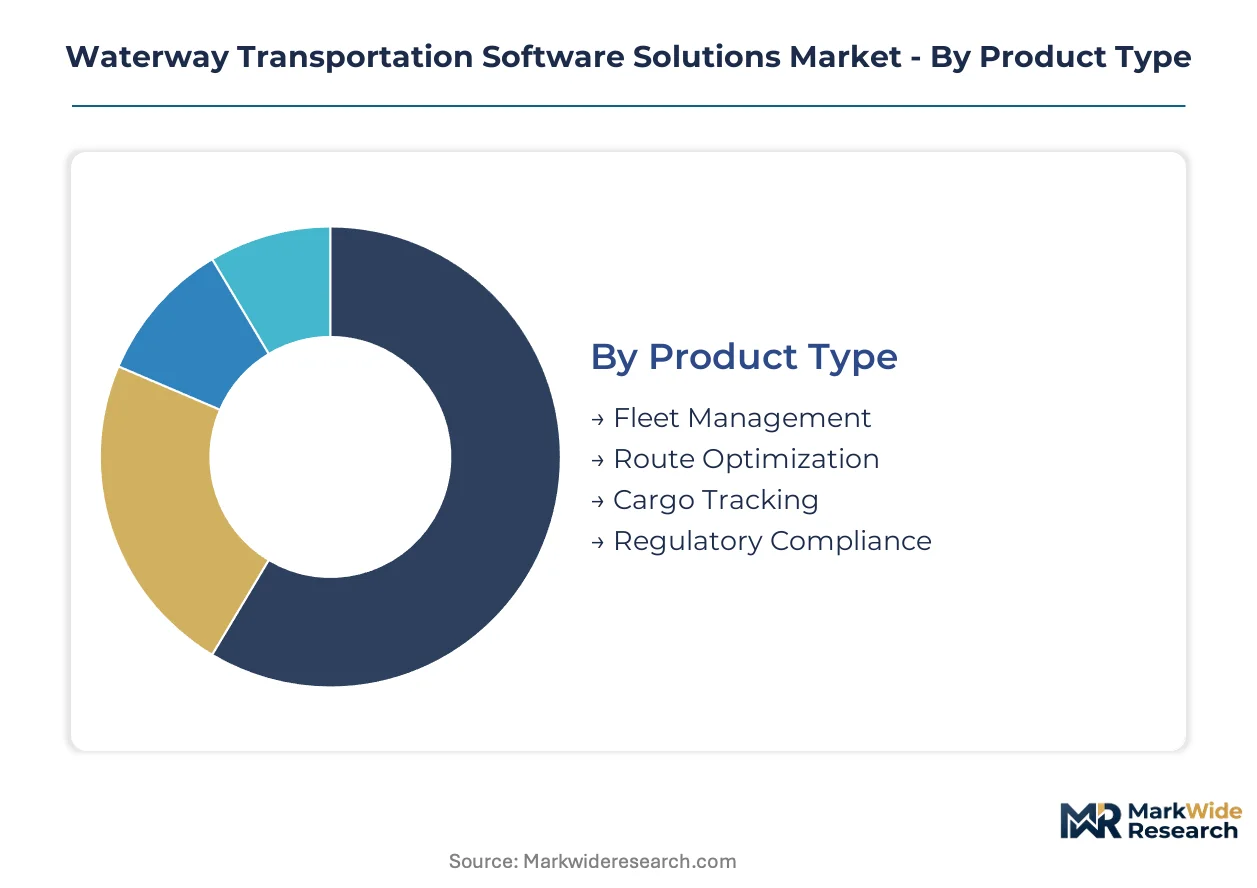
Waterway transportation software solutions fragment across four critical dimensions that determine procurement priorities and platform architecture. Product type configurations dictate whether operators prioritize real-time fleet visibility or back-office compliance automation. Technology deployment models and service relationships further stratify vendor selection criteria across maritime supply chains.
Product Type:
Application focus determines whether platforms optimize vessel movements, cargo flows, or regulatory submissions. The Rhine corridor and Danube basin operators exhibit divergent priorities based on fleet composition and trade lane characteristics.
- Fleet Management:Platforms monitor vessel position, engine performance, and maintenance schedules through integrated AIS and sensor telemetry. Rhine chemical shippers in Germany deploy these systems to coordinate tanker rotations across multiple loading terminals. EU Green Deal fuel reporting mandates are accelerating replacement of spreadsheet-based tracking.
- Route Optimization:Algorithms calculate speed-fuel tradeoffs, canal transit timing, and berth queue positions to minimize voyage cost. German container lines prioritize these modules to navigate Rhine water level fluctuations and lock congestion. Charter market volatility demands dynamic recalculation capabilities.
- Cargo Tracking:Visibility platforms synchronize inland waterway movements with intermodal handoffs at Rotterdam and Antwerp. Real-time container location data reduces demurrage exposure for freight forwarders.
- Regulatory Compliance:Automated documentation engines generate EU Maritime Single Window submissions and IMO Electronic Data Interchange protocols. Port authorities mandate these systems for vessel clearance.
Fleet Management commands the established base. The steepest expansion runs through Route Optimization.
End User:
Customer type shapes platform complexity requirements and integration depth with existing terminal operating systems. Procurement authority concentration varies significantly across stakeholder categories.
- Shipping Companies:Carriers require end-to-end voyage management spanning chartering, operations, and post-voyage analysis. German container lines consolidate software spend to capture volume pricing across integrated fleet networks. Master mariner training programs determine adoption velocity.
- Port Authorities:Public entities prioritize berth allocation algorithms and customs integration over commercial optimization. Rotterdam and Hamburg port operators lead deployment of predictive queue management.
- Freight Forwarders:Intermediaries demand multi-modal visibility platforms connecting barge, rail, and truck movements. These users prioritize API connectivity over proprietary system depth.
- Logistic Operators:Third-party providers coordinate chemical and bulk movements across Rhine-Main-Danube corridors. Their software investments concentrate on cargo tracking and regulatory documentation modules.
Shipping Companies anchor procurement volumes. Logistic Operators are climbing the fastest as chemical supply chains digitize.
Technology:
Deployment architecture determines update frequency, cybersecurity exposure, and total cost of ownership. Infrastructure choices reflect operator IT maturity and regulatory data localization requirements.
- Cloud-Based Solutions:SaaS platforms deliver continuous regulatory compliance updates and elastic compute for voyage optimization algorithms. Lower infrastructure overhead attracts mid-size Rhine operators lacking dedicated maritime-IT teams.
- On-Premise Software:Local installations persist where national data localization requirements conflict with cross-border cloud architectures. German federal procurement guidelines influence this segment.
- IoT Integration:Edge processing of engine sensors and fuel flow meters enables predictive maintenance workflows. Shipowners model retrofit ROI through digital twin simulations before physical deployment.
- AI-Driven Analytics:Machine learning models trained on historical voyage data identify optimal speed-fuel tradeoffs. Early adopters report measurable bunker cost reductions across container and tanker fleets.
On-Premise Software retains legacy commitments. AI-Driven Analytics represents the fastest-growing trajectory as charterers demand predictive capabilities.
Service Type:
Commercial relationships surrounding software deployment determine implementation success and long-term platform value. Service intensity varies with customer IT sophistication and change management requirements.
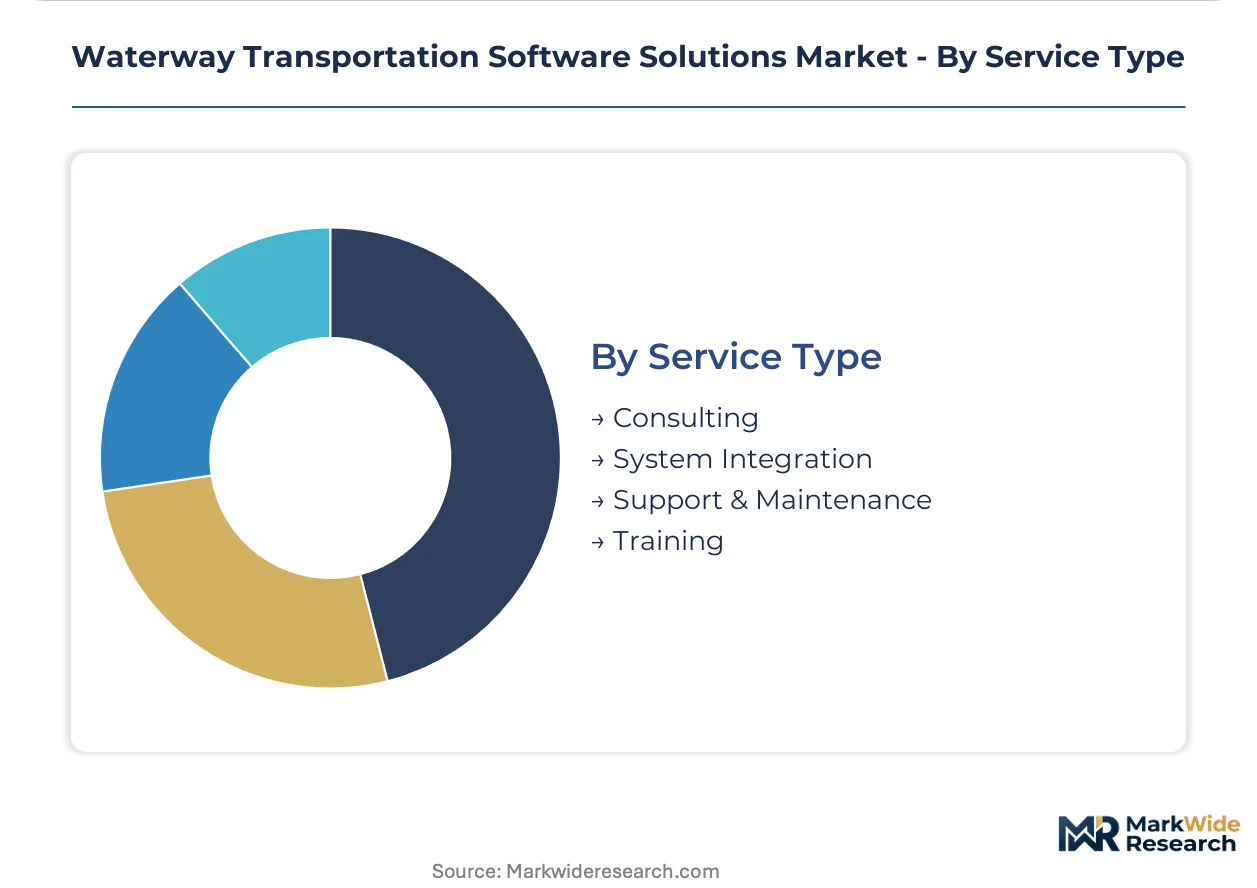
- Consulting:Advisory engagements address regulatory divergence between EU and US reporting standards. Vendors capture recurring revenue through compliance workflow restructuring.
- System Integration:Middleware development connects proprietary terminal operating systems to modern voyage management platforms. Port authorities in Antwerp and Rotterdam drive demand for API connectivity layers.
- Support & Maintenance:Continuous technical assistance ensures uptime for mission-critical berth allocation and cargo tracking functions. Long-term contracts displace transactional procurement.
- Training:Change management programs address master mariner distrust of automated routing recommendations. Safety equivalence demonstration accelerates adoption curves.
Support & Maintenance commands recurring revenue bases. Consulting is expanding most quickly as regulatory complexity intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rhine corridor operators concentrate procurement authority for integrated logistics platforms. German chemical shippers and container lines anchor regional software spend. EU emissions mandates reshape deployment priorities across inland waterway networks.
Germany
Rhine-Main-Danube operators deploy fleet management systems to coordinate tanker rotations across multiple loading terminals. The EU Green Deal mandates digital fuel reporting for all EU-flagged vessels. Hamburg port authorities prioritize berth allocation algorithms to reduce vessel idle time.
Netherlands
Rotterdam-Antwerp freight forwarders demand multi-modal visibility connecting barge movements to intermodal handoffs. The European Maritime Single Window environment eliminates redundant port documentation submissions. Chemical supply chains digitizing across the Rhine delta drive cargo tracking module adoption.
United States
Inland waterway operators on the Mississippi-Ohio system invest in voyage optimization for lock transit timing. The US Coast Guard administers vessel compliance through Automated Mutual-Assistance Vessel Rescue systems. Port authorities along the Gulf Intracoastal Waterway deploy predictive queue management.
China
Yangtze River Delta container lines expand software procurement to optimize fleet utilization across dense inland networks. National data localization requirements influence on-premise deployment decisions. Shanghai-Ningbo port clusters lead adoption of cloud-to-edge telemetry for real-time cargo visibility.
Belgium
Antwerp logistic operators coordinate chemical and bulk movements through integrated port-to-port platforms. REACH compliance workflows require automated documentation engines for cross-border shipments. Flemish chemical shippers consolidate vendor relationships to capture volume pricing on voyage management modules.
Waterway Transportation Software Solutions Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Enterprise software conglomerates anchor integrated logistics networks through ERP backbone extensions. Maritime-focused developers dominate chartering and voyage management with purpose-built workflows. Systems integrators capture implementation revenue connecting proprietary terminal operating systems to modern platforms. Competitive moves concentrate on strategic partnerships with port authorities and technology licensing for predictive analytics modules.
Within the maritime-specialist tier, Veson Nautical Corporation and Bass Software Ltd. exemplify purpose-built platform developers. SAP SE and Oracle Corporation occupy positions as ERP-anchored conglomerates extending fleet management workflows. DNV GL AS represents the certification-body archetype leveraging maritime expertise for compliance software. These three archetypes—specialist developers, enterprise extenders, and certification-derived vendors—structure competitive positioning across procurement decisions.
| Leading Market Players |
|---|
| SAP SE |
| Oracle Corporation |
| Accenture plc |
| Cognizant Technology Solutions Corporation |
| Veson Nautical Corporation |
| ABS Wavesight |
| Descartes Systems Group Inc. |
| Bass Software Ltd. |
| DNV GL AS |
| Others |
Value Network & Pricing Analysis
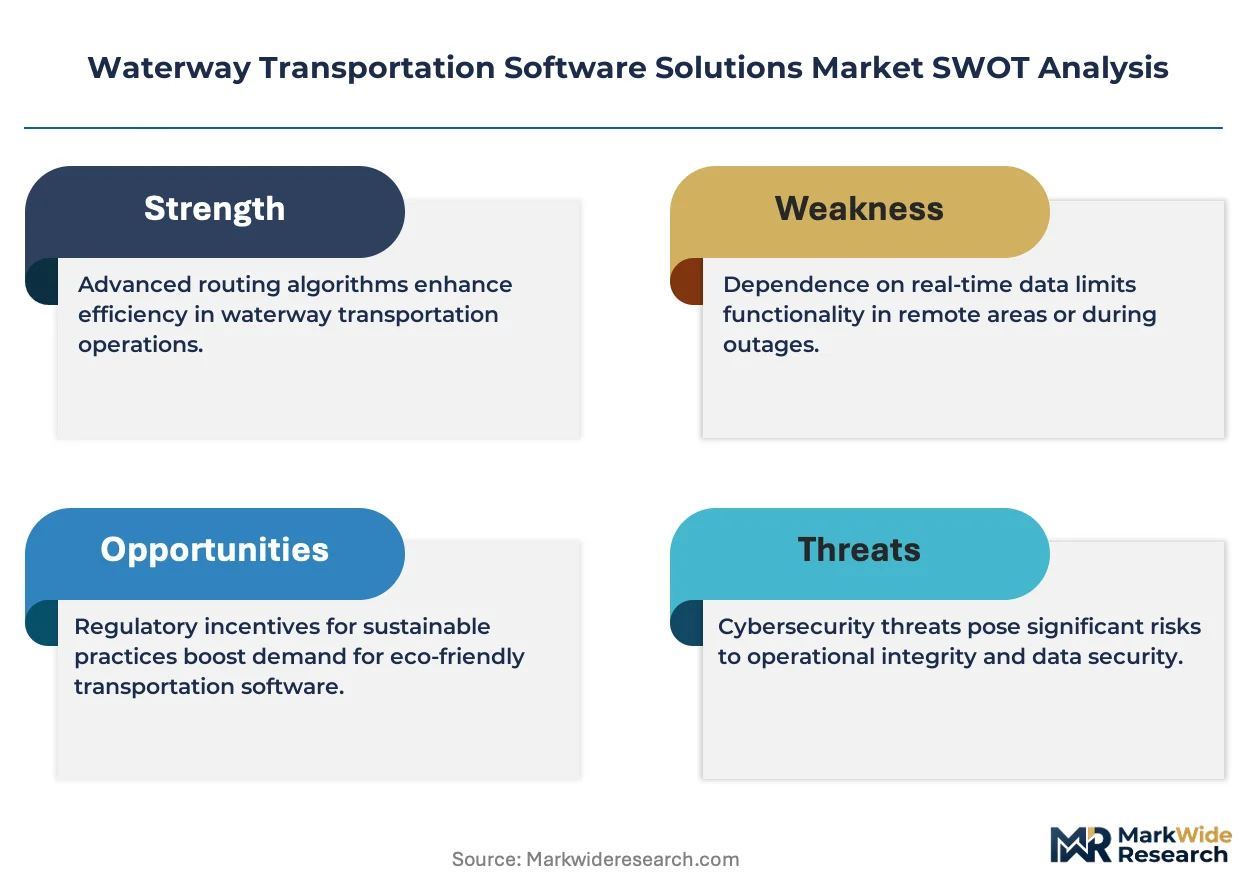
Single-source dependency on Hamburg and Rotterdam maritime-IT labor pools compresses both pricing tier spreads and supply chain configuration. EU Green Deal reporting mandates force Rhine operators toward premium SaaS tiers, while mid-size fleets absorb cost compression through standardized cloud modules.
Pricing Analysis
Cost-plus contracts indexed to maritime-IT salary benchmarks dominate enterprise deployments. Three-tier pricing structure across premium, standard, and economy levels separates SAP-anchored ERP integrations from modular SaaS subscriptions and basic compliance-only packages. Price differentiation rests on ISO 27001 cybersecurity certification and API connectivity depth. Pricing pressure stems from mid-size Rhine operators consolidating vendor relationships for volume discounts. Freight forwarders exhibit highest price sensitivity due to thin margins on intermodal coordination services.
Supply Chain Analysis
Contract-manufacturing concentration among Accenture and Cognizant technology service centers holds capacity for systems integration and middleware development. Software development draws from India, Poland, and Germany. Cloud infrastructure rests on hyperscaler data centers in Frankfurt, Amsterdam, and Dublin. Supply chain risk centers on single-source vulnerability for specialized maritime-IT talent combining nautical operations with software engineering. Distribution runs through direct vendor-to-shipping-company sales channels and systems integrator partnerships with port authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across regulatory reporting standards creates niche opportunities for compliance-specialist vendors. The divergence between EU Maritime Single Window and US Coast Guard data protocols generates demand for multi-jurisdictional platform architectures.
For Market Incumbents: Build switching-cost moats through deep ERP integration into SAP backbone environments. Incumbents should consolidate chartering workflow data to capture voyage optimization feedback loops. Threat from maritime-focused developers like Veson Nautical demands defensive patent positioning around predictive berth allocation algorithms. Vertical integration into edge sensor hardware tightens telemetry control. For New Entrants and Emerging Players: Danube corridor chemical shippers lacking dedicated maritime-IT teams represent the most penetrable entry point for lightweight SaaS compliance modules. New entrants should target US inland waterway operators on the Mississippi-Ohio system underserved by European-centric platform architectures. Go-to-market through port authority pilot programs reduces customer acquisition friction. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialist developers with proven IMO Electronic Data Interchange certification. Long-term viability hinges on regulatory advisory revenue streams extending beyond software licensing. Acquisition targets should demonstrate embedded port authority relationships. Watch for EU Green Deal enforcement intensity as inflection signal for compliance module demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep SAP ERP backbone anchoring captures Rhine-Main-Danube fleet management workflows. |
| Strategic Partnership | Port authority alliances in Hamburg and Rotterdam lock in berth allocation algorithm deployments. |
| Acquisition of Specialist Firm | Maritime-IT talent concentration in Hamburg commands premium valuation for capability access. |
| Geographic Expansion | Danube corridor infrastructure investments create demand for multi-modal visibility platforms. |
| Product Launch | AI-driven predictive analytics modules trained on historical voyage data differentiate bunker cost optimization. |
Research Methodology
Operator-level perspectives from fleet managers, port authority IT directors, chartering executives, and maritime compliance officers anchored the qualitative base. Primary interviews combined with secondary validation from EU Maritime Safety Agency regulatory filings, SEC 10-K disclosures from listed software vendors, IMO Electronic Data Interchange protocol documentation, and Rhine corridor customs data. Bottom-up vessel deployment counts triangulated against top-down software spend estimates from shipping company procurement leads.
Scenario-bracketing across regulatory enforcement intensity and cloud adoption velocity framed the analytical approach. Segmentation dimensions modeled include deployment architecture, fleet size tier, cargo type specialization, and regional regulatory cluster. CAGRs derived from logistic curve fitting to historical software procurement patterns. Forecast inputs incorporated EU Green Deal implementation timelines and charter market volatility indices.
Stress conditions across maritime-IT salary inflation, cybersecurity compliance fragmentation, and legacy system API resistance were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory harmonization progress. Quarterly review of EU Green Deal enforcement actions and IMO guideline adoption rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Mobile Application Development Market
Software & Services
Observability Platform Market
Software & Services
Team Collaboration Tools Market
Software & Services
Anti-Plagiarism for the Education Sector Market
Software & Services
Poland IT Software and Service Market
Software & Services
Global Mobile User Interface Services Market
Software & Services
Tenant Billing System Market
Software & Services
Global Virtualization Software Market
Software & Services
Global Legal Case Management Software Market
Software & Services
PAC Programming Software Market
Software & Services
Contract Lifecycle Management (CLM) Solution Market
Software & Services
Global Cloud-Based Call Center Software Market
Software & Services
On-Demand Wellness Software Market
Software & Services
Landing Page Creation Software Market
Software & Services
Proxy Services and Software Market
Software & Services
Service Scheduling Software Market