
 Projector Software Market | 2026-2036
Projector Software Market Size, Share, and Industry Trends Forecast 2026-2036
Projector Software Market Insights
ISO 21118 lumens certification is reorganizing competitive tiers among projector software vendors. Barco leverages its dominance in large-venue calibration protocols to sustain premium positioning. Epson anchors the education segment through integrated whiteboard compatibility. Panasonic competes on enterprise-grade security certifications across North American and European deployments.
Projector software encompasses applications that manage, calibrate, and distribute visual content across projection hardware, typically supporting resolutions from XGA through 4K with color gamut management and edge-blending algorithms. The technology serves commercial, educational, and entertainment environments where synchronized multi-display output replaces static presentation methods. Cloud-Based deployment leads in new installations as IT departments prioritize centralized license management and over-the-air firmware synchronization. Projection Mapping Software represents the fastest-expanding product type as experiential marketing budgets shift toward immersive architectural displays. On-Premises installations retain stronghold status in defense and classified government facilities where air-gapped networks remain mandatory.
FCC Part 15 rules govern wireless transmission protocols in US projector software stacks, while CE marking requirements under EU Radio Equipment Directive shape product configurations for European distribution. Japan's TELEC certification adds a third compliance layer for vendors targeting METI-backed smart building initiatives. Procurement teams must evaluate whether their preferred platforms maintain concurrent certification across all three jurisdictions before committing to multi-national rollouts.
Market Dynamics
Hybrid work permanence is fragmenting projector software demand between enterprise AV refresh cycles and sporadic educational procurement, while FCC Part 15 certification requirements concentrate vendor participation in wireless-capable segments.
Growth Catalysts
- ISO 21118 lumens standardization:Unified brightness measurement protocols reduce procurement friction across German corporate campuses and Japanese smart building deployments.
- Experiential marketing budgets:Retail and hospitality verticals in the United States allocate capital toward architectural projection mapping for immersive brand activations.
- Cloud-based license management:IT departments prioritize centralized firmware synchronization and subscription models over perpetual on-premises installations.
Market Restraints
- Input cost volatility:Semiconductor shortages and optical component pricing pressure margin structures for edge-blending hardware-software bundles.
- Regulatory friction:Concurrent FCC, CE marking, and TELEC certification requirements extend product launch timelines by 8-14 months for multi-jurisdictional vendors.
- Substitution threat:Direct-view LED walls displace projection systems in high-ambient-light corporate environments above 200-inch display requirements.
Strategic Opportunities
- Defense and classified facilities:Air-gapped network mandates in United States government installations sustain demand for non-cloud on-premises deployment models.
- Convergence of AI-driven calibration:Machine learning algorithms for automated keystone correction and color matching integrate with existing enterprise AV management platforms.
- Indian smart classroom initiatives:Central and state education technology procurement programs create volume demand for integrated whiteboard-compatible software stacks.
Industry Challenges
- Specialized firmware engineering talent:Shortage of engineers proficient in real-time video processing and multi-display synchronization limits vendor R&D velocity.
- Legacy AV infrastructure integration:Enterprise buyers require backward compatibility with decade-old control protocols, complicating software architecture decisions.
- Cross-certification timeline compression:Simultaneous pursuit of FCC Part 15, EU Radio Equipment Directive, and TELEC approvals strains regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Projector Software Market |
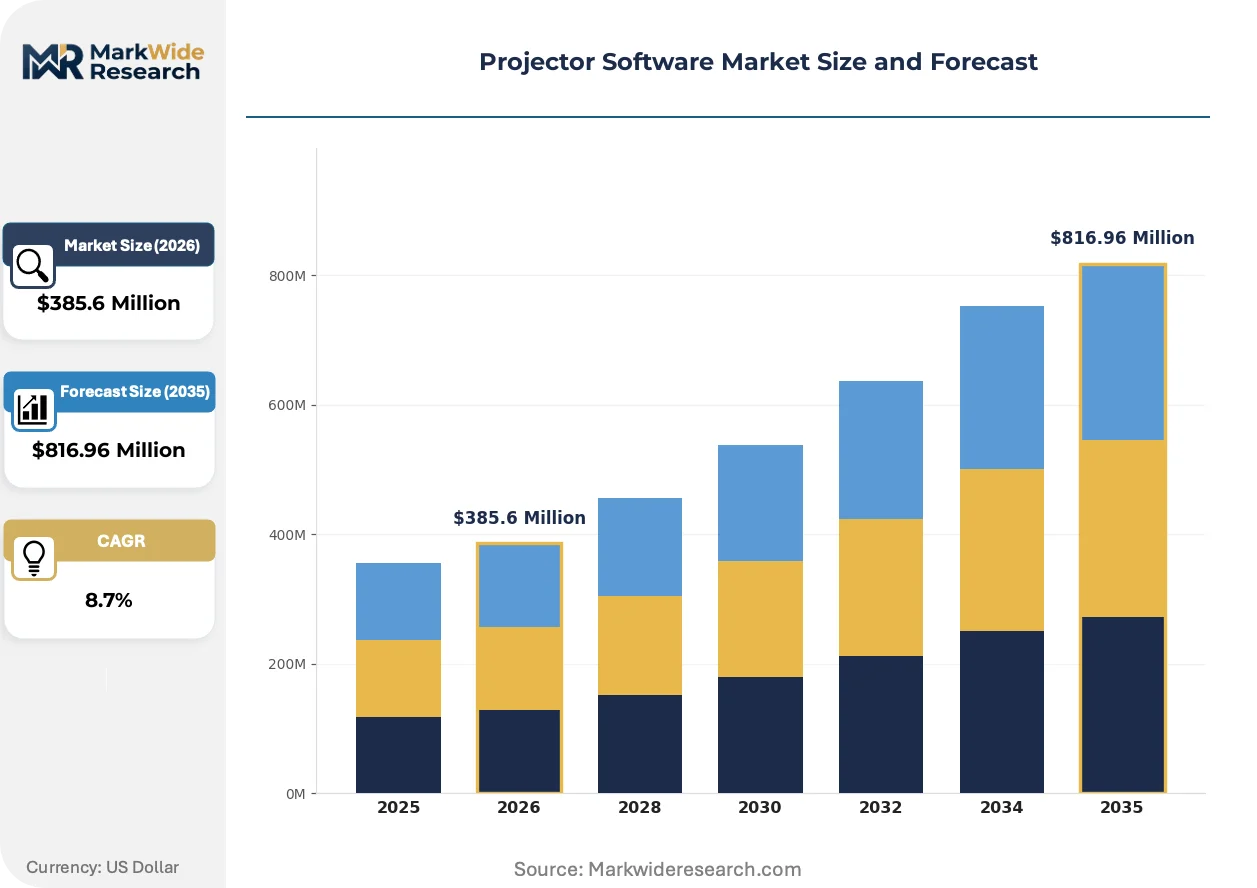
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $816.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Presentation Software, Remote Control Software, Projection Mapping Software, Lecture Capture Software Deployment Model: Cloud-Based, On-Premises, Hybrid, SaaS End User: Corporate, Education, Entertainment, Healthcare Functionality: Screen Sharing, Collaboration Tools, Scheduling, Content Management |
| Companies Covered | Barco, Epson, BenQ, Panasonic, Sharp NEC, Digital Projection, Sony Corporation, Christie Digital Systems, HeavyM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Projector Software Market Trends and Innovations
Software-defined projection control is unbundling hardware-software bundles and enabling subscription monetization, while regulatory convergence around wireless transmission standards is reshaping vendor certification strategies across major economies.
Edge-computing architectures for real-time warping and blending is decomposing the traditional division between source devices and display processors. Large-venue operators in Germany and Japan deploy GPU-accelerated software stacks that eliminate dedicated hardware scalers. This compression of the signal chain is decomposing established tiering between premium and mid-market hardware offerings.
EU Radio Equipment Directive harmonization is consolidating previously fragmented national approval processes for wireless projection systems. CE marking requirements now cover both 2.4 GHz and 60 GHz transmission protocols under unified electromagnetic compatibility standards. European enterprise procurement teams increasingly specify RED-certified stacks, filtering vendor participation in cross-border tenders.
Outcome-based AV service contracts are displacing capital-intensive hardware purchases in United States corporate real estate portfolios. Facility managers contract for guaranteed uptime and brightness performance rather than owning depreciating projector assets. This preference shift concentrates purchasing authority with managed service providers and compresses direct vendor relationships.
Projector Software Market Segmentation
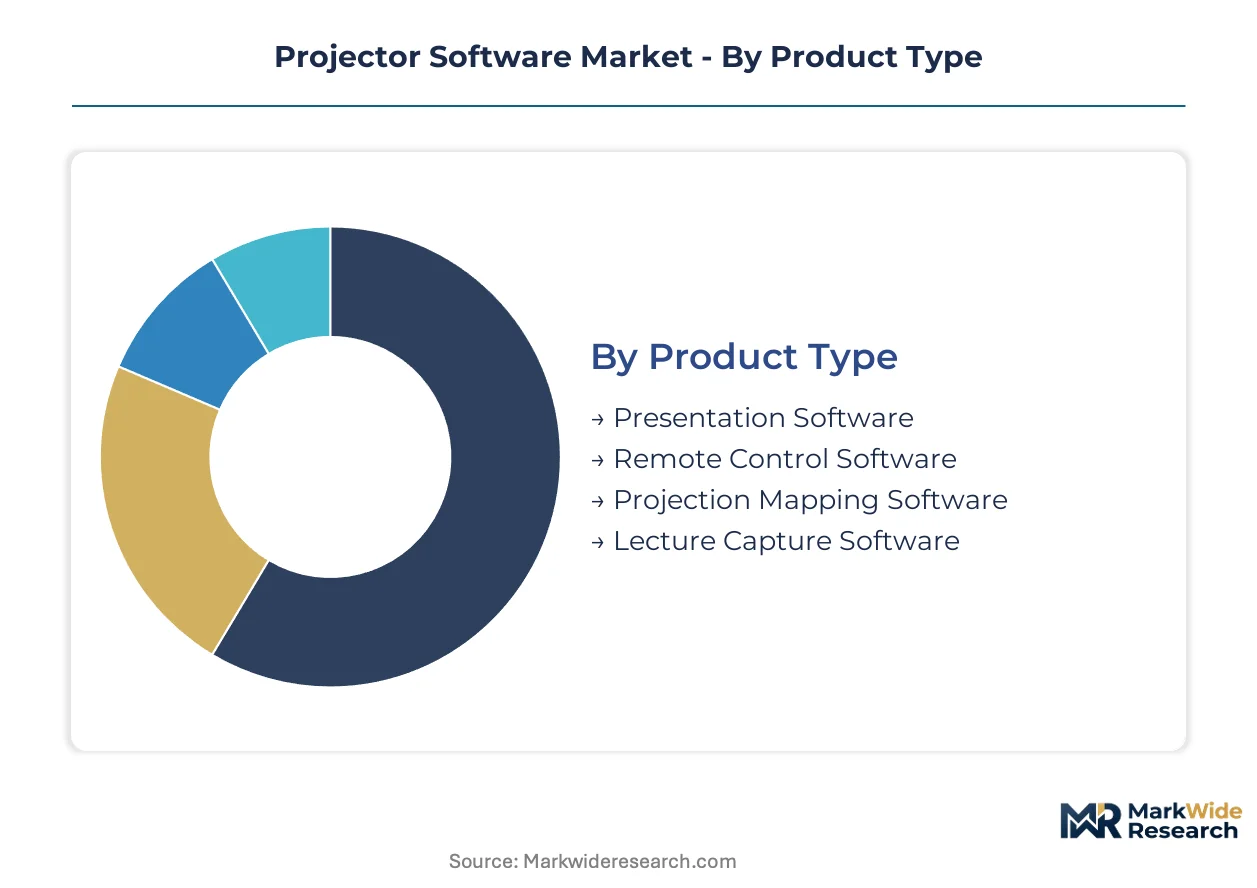
Projector software vendors calibrate feature depth and compliance certification differently across each segment. Procurement teams evaluate segments against FCC Part 15, CE marking, and TELEC requirements depending on their deployment geography and security posture.
Product Type:
FCC Part 15 certification requirements diverge sharply between wireless-enabled projection mapping stacks and hardwired presentation tools, filtering vendor participation by transmission protocol complexity.
- Presentation Software:Core slide management and source-switching functionality dominates corporate boardroom refreshes in the United States and Germany. Hybrid work permanence sustains demand for multi-source aggregation as facility managers prioritize interoperability with legacy AV infrastructure.
- Projection Mapping Software:Real-time warping engines and edge-blending algorithms enable immersive architectural displays on irregular surfaces. Experiential marketing budgets in the United States retail and hospitality verticals drive the steepest expansion trajectory as brands compete for physical attention.
- Remote Control Software:Networked device management protocols support centralized monitoring across distributed enterprise campuses.
- Lecture Capture Software:Integrated recording and streaming modules serve institutional learning management systems in Japanese and Indian education procurement.
Presentation Software handles the majority of throughput; Projection Mapping Software is the fastest mover on share.
Deployment Model:
Cost tier differentiation separates subscription-driven cloud stacks from capital-intensive perpetual licenses, with hybrid architectures emerging as a compromise for regulated industries.
- Cloud-Based:Centralized license management and over-the-air firmware synchronization reduce IT operational burden. United States enterprise AV departments prioritize this model for multi-site standardization despite ongoing FCC Part 15 compliance verification for wireless transmission modules.
- On-Premises:Air-gapped network operation satisfies defense and classified government facility mandates in the United States. TELEC certification becomes irrelevant for these deployments while procurement teams absorb higher upfront capital costs.
- Hybrid:Split architectures retain sensitive processing locally while pushing analytics to cloud endpoints.
- SaaS:Pure subscription monetization aligns with outcome-based AV service contracts displacing hardware ownership in corporate real estate portfolios.
Cloud-Based deployments command the largest installed base; SaaS is climbing the fastest as managed service providers consolidate purchasing authority.
End User:
Application maturity varies by vertical, with corporate and education segments driving divergent certification priorities across ISO 21118 lumens standardization and security hardening.
- Corporate:Enterprise-grade security certifications and multi-tenant management dominate procurement specifications in North American and European deployments. FCC Part 15 and CE marking concurrency filters vendor shortlists for wireless-capable conference room systems.
- Education:Integrated whiteboard compatibility and lecture capture integration anchor demand in Japanese smart building initiatives and Indian state procurement programs. Budget constraints favor perpetual licenses over subscription models in public institutional buying.
- Entertainment:High-refresh-rate synchronization and low-latency streaming support live event production.
- Healthcare:HIPAA-aligned audit trails and patient data isolation govern surgical suite and telemedicine applications.
Corporate segment carries the highest revenue concentration; Education is expanding most quickly on government technology procurement.
Functionality:
Customer type differentiation separates basic screen mirroring from advanced workflow orchestration, with collaboration tools commanding premium pricing in distributed team environments.
- Screen Sharing:Fundamental wireless display protocols serve as table stakes across all price tiers. German corporate campuses prioritize ISO 21118-certified brightness management alongside basic mirroring to ensure procurement standardization.
- Collaboration Tools:Multi-user annotation, real-time editing, and persistent session storage support hybrid meeting workflows. United States enterprise buyers specify these features as non-negotiable in post-pandemic AV refresh cycles.
- Scheduling:Room booking integration and calendar synchronization reduce facility management friction.
- Content Management:Centralized asset libraries and version control support brand consistency across large venue networks.
Screen Sharing remains the functional baseline; Collaboration Tools is gaining share fastest as meeting modality shifts persist.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global projector software market depends on fiber-optic and satellite interconnects that link enterprise AV hubs across major economies. These digital infrastructure assets determine where cloud-based deployment models achieve lowest-latency performance for real-time collaboration tools.
United States
Enterprise AV refresh cycles in corporate real estate portfolios sustain demand for FCC Part 15-certified wireless projection systems. Defense and classified government facilities mandate air-gapped on-premises deployments under federal procurement guidelines. Dallas-Fort Worth and Northern Virginia data center corridors concentrate managed service provider operations for outcome-based AV contracts.
Germany
ISO 21118 lumens standardization drives procurement standardization across corporate campuses in Bavaria and North Rhine-Westphalia. CE marking under EU Radio Equipment Directive filters vendor participation in cross-border enterprise tenders. Stuttgart's automotive engineering clusters deploy edge-blending software for immersive design review environments.
Japan
METI-backed smart building initiatives anchor demand for integrated whiteboard-compatible software stacks in Kanto and Kansai metropolitan areas. TELEC certification requirements add compliance layers for wireless transmission modules targeting institutional buyers. Tokyo's dense commercial real estate market accelerates subscription-based AV service contract adoption.
India
Central and state education technology procurement programs generate volume demand for lecture capture software in smart classroom deployments. BIS certification standards shape product configurations for domestic distribution networks. Bengaluru's technology corridor and Hyderabad's IT clusters drive corporate adoption of cloud-based license management platforms.
United Kingdom
GDPR-aligned data governance requirements influence hybrid deployment architectures for enterprise AV systems in London and Southeast England financial services sectors. Post-Brexit regulatory divergence creates parallel certification tracks for vendors serving UK and EU markets. Manchester's media production hubs sustain demand for projection mapping software in experiential marketing applications.
Projector Software Market Competitive Landscape
Listed leaders compete with private specialists across certification breadth and deployment model flexibility. The vendor base stratifies between hardware-integrated incumbents and pure-play software developers. Three archetypes dominate: diversified electronics conglomerates with captive projection divisions, AV-focused specialists with deep calibration expertise, and cloud-native entrants prioritizing subscription monetization. Competitive moves concentrate on strategic partnerships for wireless protocol licensing and portfolio diversification into adjacent collaboration software categories.
Within the diversified electronics tier, Barco, Epson, and Panasonic occupy positions that exemplify contrasting strategic anchors. Barco represents the large-venue calibration specialist archetype with roots in professional visualization. Epson exemplifies the hardware-integrated model where projection software serves as a differentiation layer for optical engine sales. Panasonic sits within the enterprise security certification vector, leveraging long-standing government and corporate relationships across North American and European deployments. These three entities collectively illustrate how certification depth, geographic footprint, and deployment model flexibility separate competitive tiers in procurement evaluations.
| Leading Market Players |
|---|
| Barco |
| Epson |
| BenQ |
| Panasonic |
| Sharp NEC |
| Digital Projection |
| Sony Corporation |
| Christie Digital Systems |
| HeavyM |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at cloud infrastructure providers concentrates bargaining power among hyperscaler partners, compressing margin structures for independent software vendors while elevating price floors for on-premises perpetual licenses in air-gapped defense installations.
Pricing Analysis
Volume-discount tiering separates enterprise multi-site deployments from single-location educational procurements. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 21118 certification grade and FCC Part 15 wireless protocol complexity. Pricing pressure stems from semiconductor input cost volatility and optical component shortages pressuring edge-blending hardware-software bundles. Education procurement teams exhibit highest price sensitivity, while defense and classified facilities absorb premium pricing for air-gapped compliance.
Supply Chain Analysis
Strategic stockpiling of optical engines and wireless transmission modules dominates vendor inventory strategies, buffering against foundry allocation constraints for specialized video processing chipsets. Manufacturing concentrates in Taiwan for semiconductor fabrication, Japan for precision optical components, and China for assembly integration. Raw material dependencies span rare-earth phosphors for laser light sources, high-purity glass substrates, and GPU accelerators for real-time warping algorithms. Single-source vulnerability in Taiwan semiconductor foundries poses structural risk. Distribution runs through AV systems integrators and managed service providers rather than direct enterprise sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-based deployment models and AI-driven calibration algorithms are disrupting procurement patterns across corporate AV refresh cycles, with FCC Part 15 certification requirements creating regulatory moats that concentrate vendor participation.
For Market Incumbents: Shield premium positioning through concurrent FCC, CE marking, and TELEC certification maintenance, which filters competitor entry in multi-jurisdictional enterprise tenders. Deepen backward integration into optical engine supply to buffer semiconductor shortage exposure. Prioritize R&D velocity in machine learning calibration algorithms to defend against cloud-native entrants.
For New Entrants and Emerging Players: Managed service provider aggregation gaps in outcome-based AV contracts offer white-space entry points where incumbents under-serve facility management outsourcing demand. Indian smart classroom initiatives present the most penetrable geography given volume procurement scale and whiteboard compatibility requirements. Pursue SaaS-native architectures with centralized license management as the primary go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native software vendors with managed service provider channel relationships, positioning these archetypes for superior cash-flow quality. Long-term viability over the projection horizon favors acquisition targets with ISO 21118 certification depth and defense-sector on-premises deployment capability. Monitor TELEC certification timeline compression as the signal indicating regulatory affairs capacity constraints among mid-tier vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Concurrent Certification Investment | FCC Part 15, CE marking, and TELEC concurrency filters vendor participation in cross-border enterprise tenders. |
| AI-Driven Calibration Development | Machine learning algorithms for automated keystone correction integrate with existing enterprise AV management platforms. |
| Managed Service Provider Partnership | Outcome-based AV service contracts displace direct vendor relationships and concentrate purchasing authority. |
| Backward Integration into Optical Engines | In-house production of laser light sources buffers margin structures against rare-earth phosphor cost volatility. |
| Hybrid Deployment Architecture Launch | Split cloud-local processing satisfies GDPR-aligned data governance in UK financial services sectors. |
Research Methodology
A spread of perspectives from AV systems integrators, IT procurement officers, facility management directors, and regulatory affairs specialists converged on the working assumptions underlying demand forecasts. Primary interviews with enterprise AV managers and secondary validation against FCC certification databases, EU Radio Equipment Directive filings, and METI smart building procurement records anchored the analysis. Bottom-up triangulation across deployment model adoption curves and top-down cross-checks against optical component trade flows ensured methodological rigor.
Segmentation dimensions modeled span product type, deployment architecture, end-user vertical, and geographic regulatory cluster across the analysis window. CAGRs derive from fitted growth curves calibrated to ISO 21118 standardization adoption rates and experiential marketing budget allocation patterns. Industry-specific forecast inputs include wireless protocol certification timelines and GPU-accelerated software stack penetration in large-venue applications.
Underlying assumptions cover sustained hybrid work permanence and semiconductor supply normalization, with deviation risk concentrated in direct-view LED wall substitution acceleration and concurrent regulatory timeline compression. Revision becomes warranted when TELEC certification backlogs exceed eighteen-month thresholds or when defense procurement guidelines shift cloud-adoption mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Intellectual Property Software Market
Software & Services
Hypervisor Market
Software & Services
Global Email Management Software Market
Software & Services
Lead Management Software Market
Software & Services
Application Performance Management (APM) Software Market
Software & Services
US Digital Marketing Software Market
Software & Services
Global Big Data Software Market
Software & Services
Email Optimization Software Market
Software & Services
MEP Software Market
Software & Services
Auto Software Market
Software & Services
Global Testing Software Market
Software & Services
Supplier Quality Management Applications Market
Software & Services
SMS Marketing Software Market
Software & Services
Design Engineering Software Market
Software & Services
United Arab Emirates (UAE) Cloud Accounting Software Market
Software & Services
Global Molecular Modeling Software for Chemistry Market